
 Global Pseudocumene Market | 2026-2036
Global Pseudocumene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pseudocumene Market Outlook
REACH is restructuring the cost-of-entry calculus for pseudocumene suppliers seeking European market access, with compliance costs now filtering smaller participants from certification pipelines. Sinopec Limited leverages its integrated refinery-aromatics complex to sustain feedstock cost advantages across solvent and intermediate grades. ExxonMobil Corporation anchors North American supply reliability through its Gulf Coast manufacturing footprint and pipeline-linked distribution network.
Pseudocumene, or 1,2,4-trimethylbenzene, is a C9 aromatic hydrocarbon with a boiling point of approximately 169 degrees Celsius, produced primarily through catalytic reforming of naphtha or disproportionation of xylene streams; it serves as a critical precursor for trimellitic anhydride and high-solvency industrial formulations. The solvent segment dominates volume consumption in paint and coating applications, where pseudocumene's evaporation rate and solvency power support premium formulation performance. The intermediate segment leads value generation, as chemical-grade pseudocumene feeds into specialized polymer additives and engineering plastic precursors that command tighter specification premiums.
EPA regulations in the United States and REACH in Europe are converging on volatile organic compound thresholds and workplace exposure limits, forcing reformulation investments across coating and adhesive applications. China's MEE enforces emission controls at aromatics complexes that affect export-grade production economics. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance fragmentation threatens to segment product specifications and complicate cross-border inventory management.
Market Dynamics
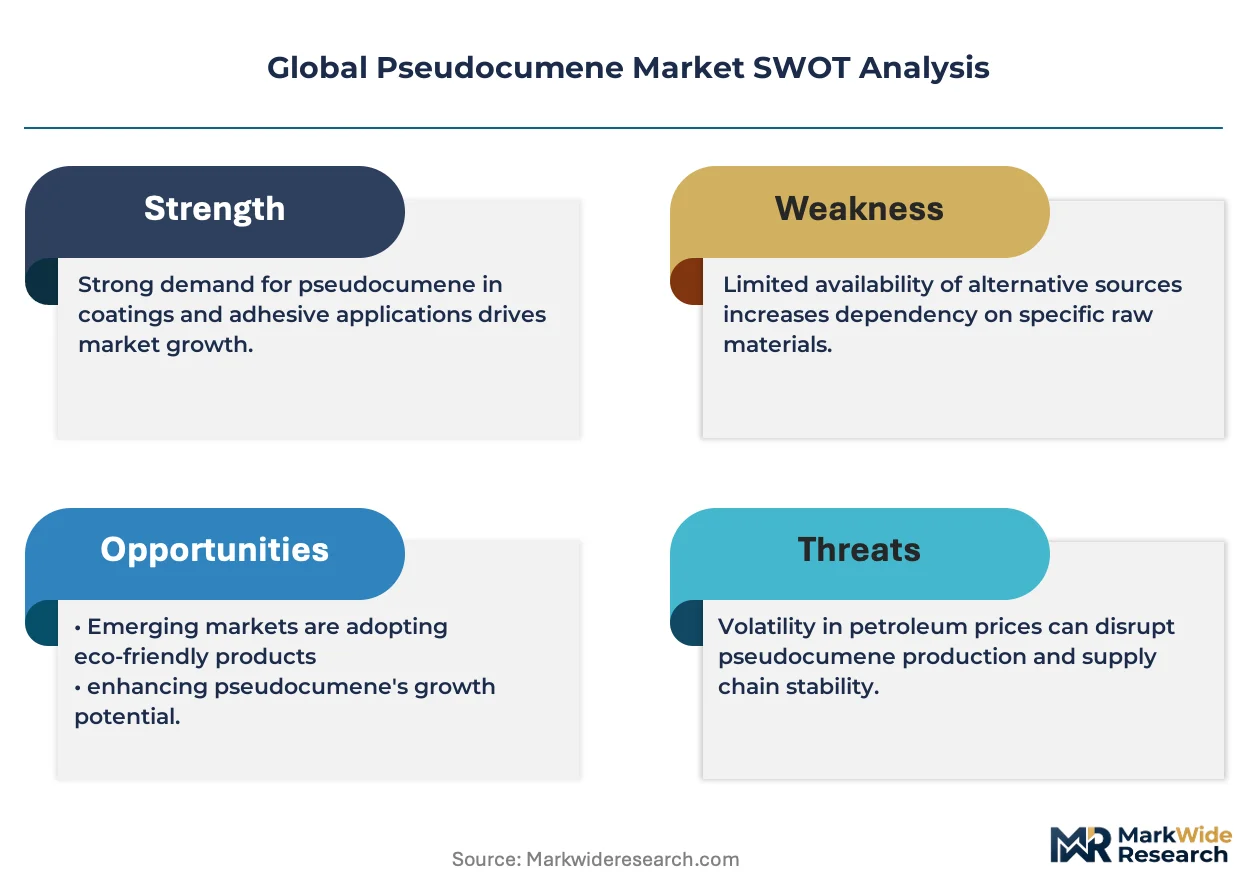
REACH compliance costs and EPA purity benchmarks are bifurcating the pseudocumene supplier base, concentrating volume among integrated aromatics producers while disqualifying smaller traders from European and North American certification pipelines.
Growth Catalysts
- Automotive coating demand:High-performance solvent formulations for electric vehicle battery enclosures and lightweight body panels are absorbing chemical-grade pseudocumene at accelerated rates.
- REACH registration thresholds:European chemicals regulation is consolidating qualified supply onto certified producers, reducing price competition and stabilizing margins for compliant participants.
- Catalytic reforming yield improvements:Advanced naphtha processing configurations at integrated refineries are expanding pseudocumene output without proportional feedstock cost increases.
Market Restraints
- Naphtha feedstock volatility:Crude-linked aromatic feedstock costs transmit directly to pseudocumene production economics, compressing margin predictability for non-integrated processors.
- China supply concentration:State-backed petrochemical capacity expansions in Shandong and Jiangsu provinces are capturing downstream derivative production, limiting export availability for third-party traders.
- Trimellitic anhydride substitution:Bio-based plasticizer precursors and alternative aromatic anhydrides are displacing pseudocumene-derived intermediates in flexible PVC applications.
Strategic Opportunities
- India specialty chemical manufacturing:PLI scheme incentives for domestic aromatic intermediate production are attracting joint venture investments from established pseudocumene suppliers seeking tariff-advantaged supply positions.
- Semiconductor-grade solvent purification:Ultra-high purity pseudocumene for photoresist formulations represents an emerging specification tier with 40-60% price premiums over industrial grades.
- EU Green Deal carbon border adjustments:Embedded emissions accounting for imported aromatics is creating competitive openings for European producers with verified low-carbon process configurations.
Industry Challenges
- Process safety engineering scarcity:Qualified specialists for high-temperature aromatic unit operations are concentrated among retiring cohorts at legacy refineries, constraining operational expansion timelines.
- REACH dossier maintenance:Substance evaluation updates and extended safety data requirements demand sustained regulatory affairs investment that smaller market participants struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pseudocumene Market |
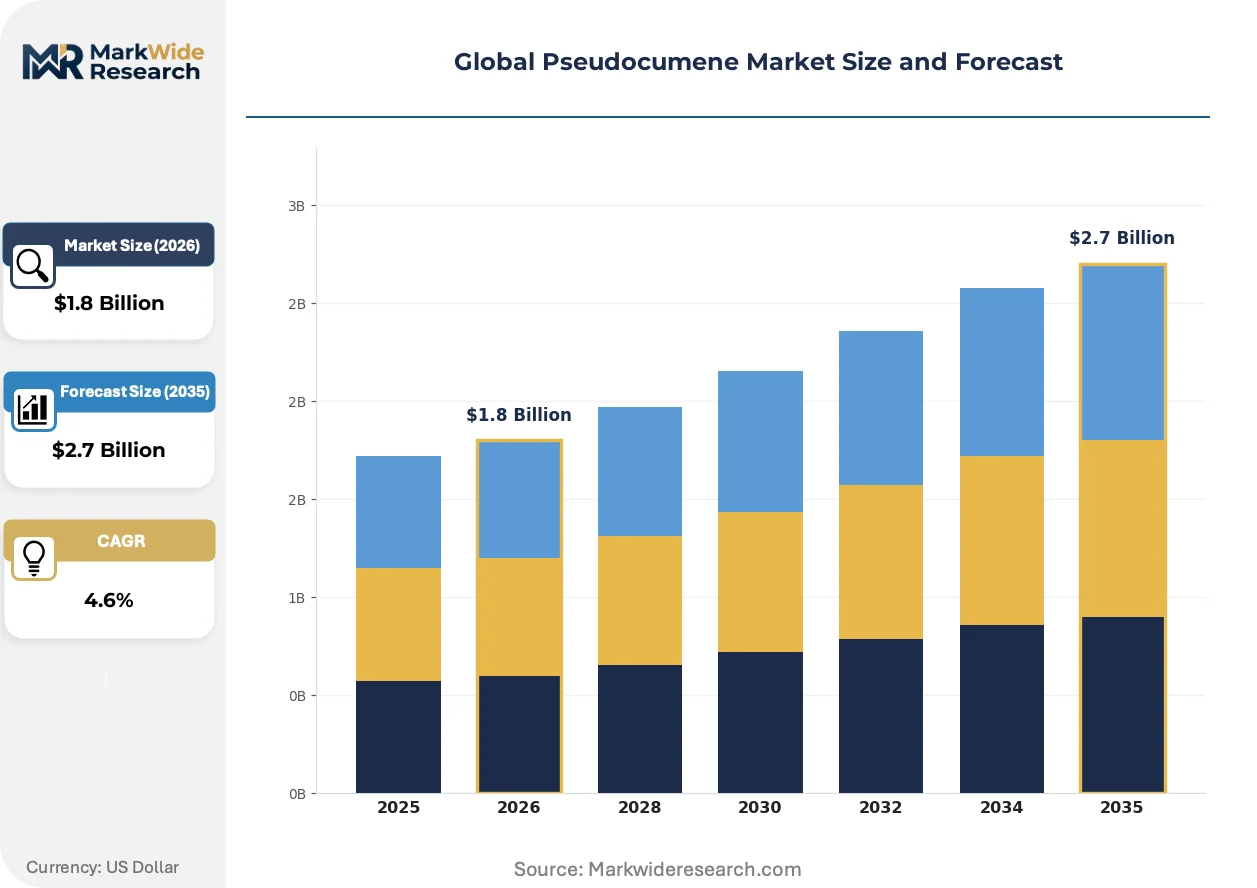
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Intermediate, Additive, Chemical Application: Paint, Coating, Adhesive, Plastic End User: Manufacturing, Automotive, Consumer Goods, Construction Grade: Industrial, Commercial, Laboratory, Others |
| Companies Covered | Sinopec Limited, LyondellBasell Industries N.V., ExxonMobil Corporation, Dow Chemical Company, BASF SE, Chevron Phillips Chemical Company LLC, China National Petroleum Corporation, Flint Hills Resources, INEOS Group Holdings S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pseudocumene Market Strategic Shifts
Modular process intensification and regulatory emissions tracking are compressing batch cycle times while fragmenting product specifications across jurisdiction-specific purity grades.
Continuous catalytic reforming with integrated solvent recovery loops is modularizing pseudocumene production economics. Paint and coating formulators in Germany and the Netherlands are adopting these streamlined supply configurations. The technology is modularizing capital deployment decisions, enabling mid-scale entrants to achieve unit cost parity with legacy integrated producers.
EPA Method 24 volatile organic compound testing protocols are tightening evaporation rate specifications for industrial coatings. Formulators serving the US automotive OEM supply chain are reformulating high-solvency systems to meet composite vapor pressure thresholds. The solvent segment is responding by segmenting product lines into EPA-compliant and legacy formulations with diverging price structures.
Direct refinery-to-formulator procurement contracts are displacing traditional distributor intermediaries in high-volume coating applications. Large automotive paint manufacturers in China are negotiating captive offtake arrangements with Sinopec aromatics complexes. This channel compression is most visible in Shandong province, where integrated supply chains are eliminating three-layer distribution markups.
Global Pseudocumene Market Segmentation
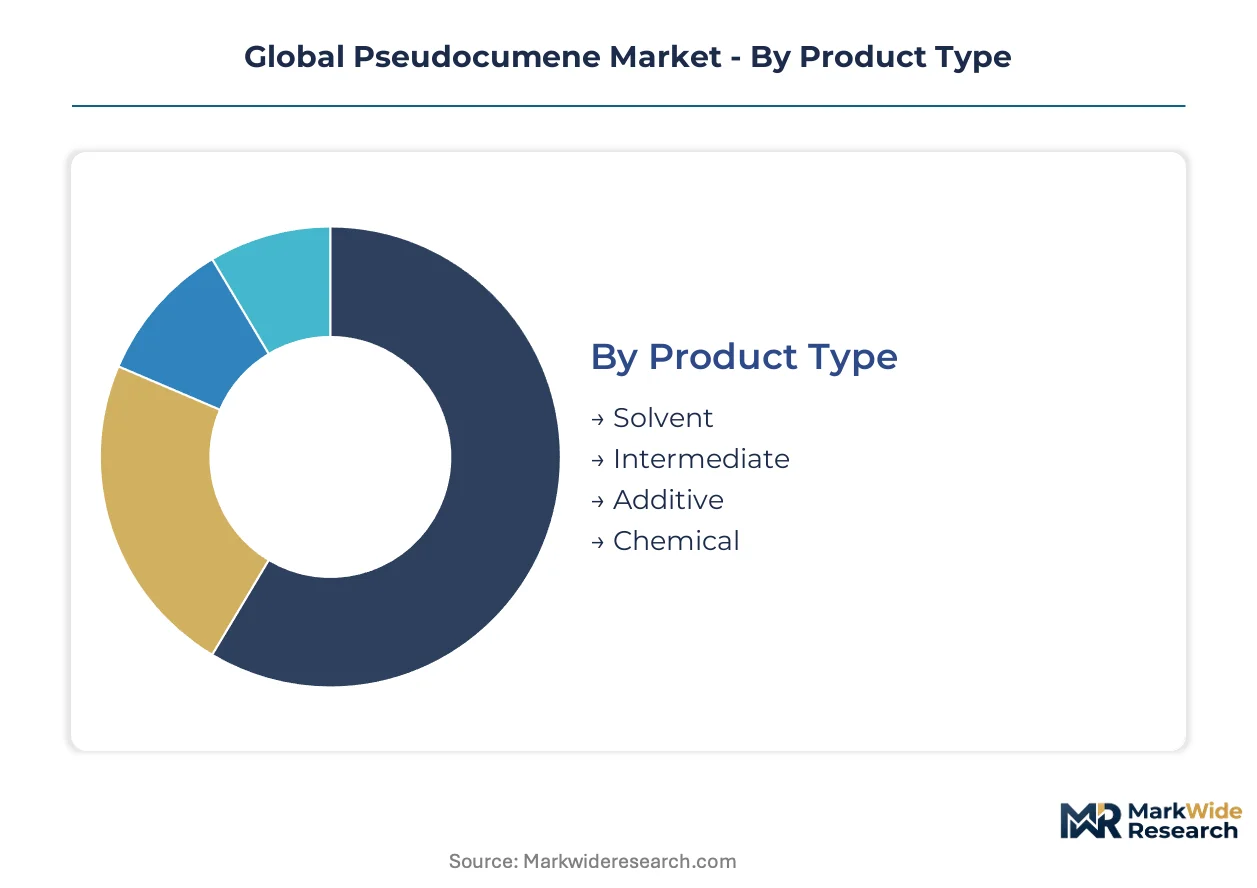
Pseudocumene's commercial value bifurcates sharply between commodity solvent volumes and specification-critical intermediate grades. Segmentation discipline separates margin-accretive specialty applications from price-pressured industrial offtake.
Product Type:
The volume-premium split runs deepest here, with solvent grades moving in bulk tonnage while intermediates capture specification premiums through purity thresholds.
- Solvent:Technical-grade pseudocumene with 95-99% purity serves paint formulation and industrial cleaning applications where evaporation rate control matters more than trace impurity limits. Demand concentrates in automotive OEM coating supply chains across Germany, the United States, and Japan, where EPA Method 24 and REACH VOC thresholds are forcing reformulation investments that favor compliant solvent grades.
- Intermediate:Chemical-grade material at 99.5%+ purity feeds trimellitic anhydride production for plasticizers and engineering polymer precursors. China's Shandong and Jiangsu aromatics complexes are capturing downstream derivative production, limiting export availability for third-party traders serving specialty chemical manufacturers.
- Additive:Functionalized pseudocumene derivatives enhance fuel stability and lubricant performance in aviation and marine applications.
- Chemical:General-purpose reagent grades support laboratory synthesis and small-batch specialty manufacturing.
Today's leader: Solvent. Tomorrow's challenger: Intermediate.
Application:
Application segmentation tracks the divergence between regulated industrial coatings and specification-critical polymer systems.
- Paint:Architectural and protective coatings absorb the largest solvent volumes, with formulation houses in the Netherlands and Germany driving demand for low-VOC compliant grades. REACH registration requirements are consolidating qualified supply onto certified producers, reducing price competition.
- Coating:Industrial finishes for automotive and aerospace applications require tighter evaporation control and higher solvency power. Electric vehicle battery enclosure coatings are absorbing chemical-grade pseudocumene at accelerated rates as lightweighting mandates expand substrate complexity.
- Adhesive:Pressure-sensitive and structural adhesive formulations use pseudocumene as a co-solvent for tackifier resins.
- Plastic:Polymer additive applications leverage pseudocumene-derived intermediates for plasticizer and stabilizer synthesis.
Paint dominates current volumes. Coating applications are climbing the fastest on EV-driven specification upgrades.
End User:
End-user segmentation reveals how automotive specification pressure cascades through tiered supply chains.
- Automotive:OEM paint shops and battery enclosure manufacturers drive the most demanding purity requirements. Direct refinery-to-formulator procurement contracts are displacing traditional distributor intermediaries in high-volume coating applications, compressing channel margins.
- Manufacturing:General industrial production consumes solvent grades for equipment cleaning and process applications.
- Consumer Goods:Packaging and household product applications use lower-specification grades with less regulatory scrutiny.
- Construction:Protective coatings and sealants represent cyclical demand tied to infrastructure investment cycles.
Automotive sets the specification ceiling. Manufacturing provides the volume floor.
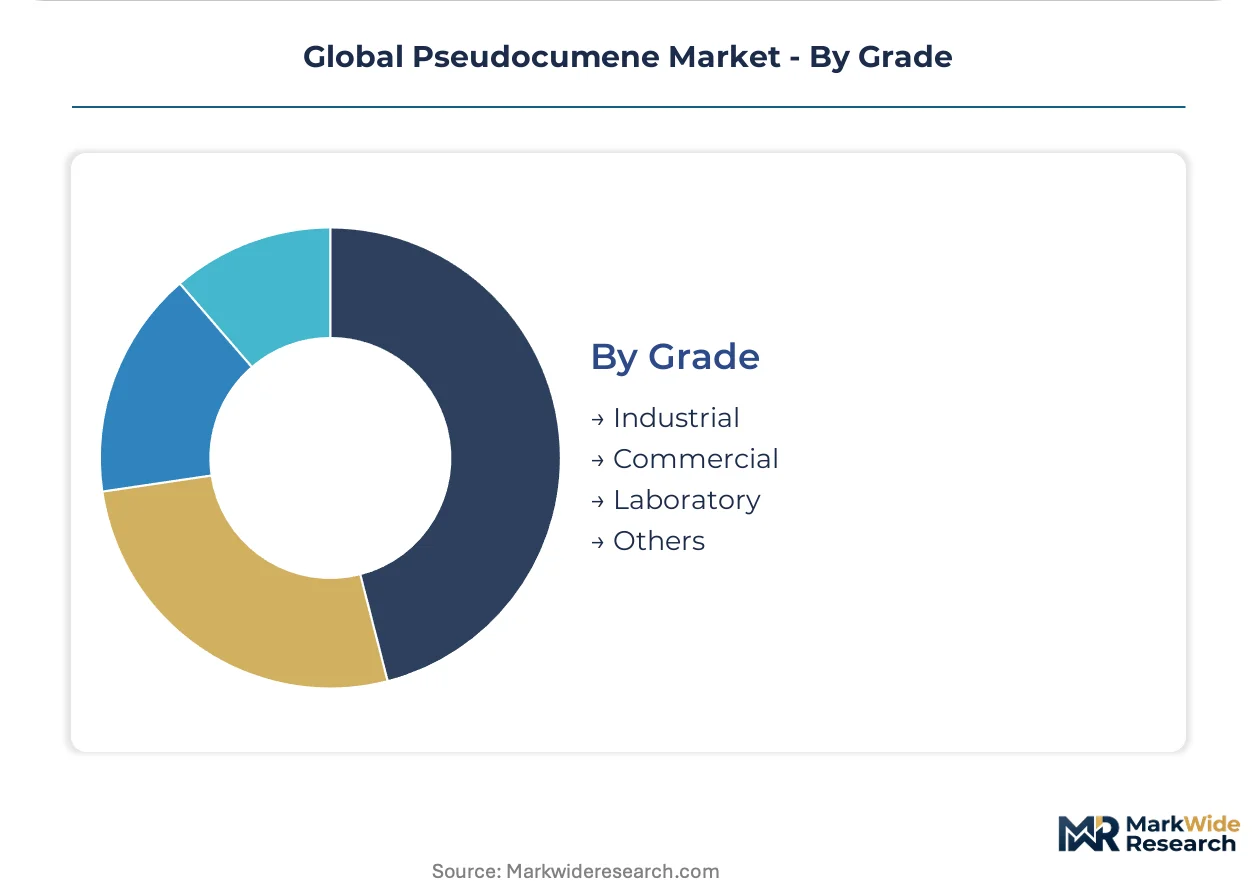
Grade:
Grade stratification reflects the cost of compliance across jurisdictional purity benchmarks.
- Industrial:Standard purity for bulk solvent applications where trace aromatics tolerance is functionally acceptable.
- Commercial:Mid-tier grades balance cost and performance for formulated product manufacturers.
- Laboratory:Ultra-high purity specifications for analytical and research applications command 40-60% price premiums over industrial grades.
- Others:Custom-blended and specification-modified grades for niche applications.
Industrial grade anchors volume. Laboratory grade captures margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized process engineers for high-temperature aromatic unit operations concentrate disproportionately in legacy refining corridors across China, Germany, and the United States, anchoring regional production capacity.
China
State-backed petrochemical expansions in Shandong and Jiangsu provinces are capturing downstream trimellitic anhydride production. MEE emission controls at aromatics complexes tighten export-grade production economics. Direct refinery-to-formulator contracts in Shandong province are eliminating traditional distribution intermediaries from coating supply chains.
Germany
Automotive OEM paint shops in Bavaria and Baden-Württemberg drive specification-critical solvent demand for battery enclosure coatings. REACH registration thresholds filter uncertified suppliers from European certification pipelines. The Ludwigshafen chemical cluster anchors integrated aromatics-to-derivatives production with pipeline-linked distribution.
United States
Gulf Coast refineries leverage naphtha feedstock access and pipeline infrastructure for North American supply reliability. EPA Method 24 VOC testing protocols force reformulation investments across automotive coating applications. Texas and Louisiana host the dominant concentration of catalytic reforming capacity serving industrial solvent markets.
Japan
Precision coating formulators in the Kansai and Chubu regions absorb high-purity pseudocumene for electronics and automotive finishes. METI industrial standards enforce trace impurity limits that exceed generic export specifications. The Nagoya industrial corridor integrates solvent production with downstream adhesive and sealant manufacturing.
India
Specialty chemical manufacturers in Gujarat and Maharashtra are expanding aromatic intermediate capacity under PLI scheme incentives. BIS quality benchmarks for industrial solvents are tightening import substitution requirements. The Dahej and Mundra chemical zones attract joint venture investments from established pseudocumene suppliers seeking tariff-advantaged positions.
Global Pseudocumene Market Competitive Environment
The competitive structure tilts toward integrated aromatics producers with captive naphtha supply and pipeline distribution networks. REACH compliance costs and EPA purity benchmarks bifurcate the supplier base, concentrating volume among certified integrated producers while disqualifying smaller traders. Three archetypes dominate: state-backed petrochemical conglomerates with refinery integration, multinational chemical majors with global distribution networks, and regional specialists serving specification-critical coating applications. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with direct refinery-to-formulator procurement contracts displacing traditional distributor channels.
Among integrated state-backed producers, Sinopec Limited occupies a position exemplifying refinery-aromatics complex integration with captive feedstock advantages. ExxonMobil Corporation anchors North American supply reliability through Gulf Coast manufacturing infrastructure. BASF SE represents the European integrated chemical major archetype with REACH-certified production serving specification-critical automotive coating supply chains.
| Leading Market Players |
|---|
| Sinopec Limited |
| LyondellBasell Industries N.V. |
| ExxonMobil Corporation |
| Dow Chemical Company |
| BASF SE |
| Chevron Phillips Chemical Company LLC |
| China National Petroleum Corporation |
| Flint Hills Resources |
| INEOS Group Holdings S.A. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between REACH-registered and uncertified pseudocumene suppliers manifests simultaneously in 15-25% price spreads and in supply chain exclusion of non-compliant traders from European and North American procurement pipelines. This bifurcation concentrates volume among integrated aromatics producers with captive naphtha supply while fragmenting distribution channels for specification-critical grades.
Pricing Analysis
Bundled long-term offtake contracts with integrated refinery operators dominate high-volume solvent procurement, while unbundled spot transactions persist for specialty intermediate grades with divergent purity specifications. Price differentiation rests on REACH certification status and naphtha feedstock integration depth, with certified producers commanding sustained premiums. Cost compression in industrial solvent tiers intensifies as Chinese state-backed capacity expansions transmit volume pressure through export channels. Automotive OEM formulators exhibit lowest price sensitivity due to specification-locked supply agreements, while general industrial manufacturers drive aggressive spot-market negotiation.
Supply Chain Analysis
Naphtha feedstock supply rests on Gulf Coast refineries in the United States, integrated aromatics complexes in China's Shandong and Jiangsu provinces, and pipeline-linked production clusters in Germany's Ludwigshafen chemical corridor. Catalytic reforming catalysts, specialized process equipment, and qualified high-temperature unit operators constitute critical input dependencies. Single-source vulnerability concentrates in Chinese state-controlled petrochemical conglomerates capturing downstream derivative production. Distribution runs through direct refinery-to-formulator contracts displacing traditional three-layer distributor networks in high-volume coating applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pseudocumene markets offer margin expansion through semiconductor-grade purification investments and carbon-border-advantaged European production positioning, as regulatory compliance costs filter sub-scale competitors from premium-tier certification pipelines.
For Market Incumbents: Cement REACH dossier maintenance capabilities and captive naphtha integration as defensive moats against bio-based plasticizer substitution threats threatening trimellitic anhydride demand. Prioritize backward integration into catalytic reforming capacity at Gulf Coast and Ludwigshafen manufacturing footprints to sustain feedstock cost parity with state-backed Chinese producers. For New Entrants and Emerging Players: Specialty chemical manufacturers in India's Gujarat and Maharashtra chemical zones represent the most penetrable buyer archetype for tariff-advantaged supply positioning under PLI scheme incentives. Target semiconductor-grade solvent purification as a specification tier with 40-60% price premiums over industrial grades, leveraging modular process intensification configurations to achieve unit cost parity without legacy refinery infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with European producers with verified low-carbon process configurations positioned for EU Green Deal carbon border adjustment advantages. Acquisition targets should demonstrate integrated aromatics-to-derivatives production with pipeline-linked distribution and REACH-certified intermediate-grade capacity. Watch MEE emission control tightening at Chinese aromatics complexes as an inflection indicator for export-grade availability constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalytic Reforming | Captive naphtha supply at Gulf Coast refineries eliminates feedstock cost volatility exposure. |
| Semiconductor-Grade Purification Investment | Ultra-high purity photoresist solvents command 40-60% premiums over industrial specifications. |
| REACH Dossier Maintenance Expansion | Sustained regulatory affairs investment filters smaller competitors from European certification pipelines. |
| Joint Venture in India PLI Zones | Dahej and Mundra chemical corridors offer tariff-advantaged positions for aromatic intermediate production. |
| Carbon Border Adjustment Preparation | Verified low-carbon process configurations at European plants create competitive openings under EU Green Deal. |
Study Parameters
Bottom-up solvent and intermediate consumption modeling reconciled against top-down refinery output and trade flow tracking forms the analytical core of this study. Primary interviews with catalytic reforming unit managers, procurement leads at automotive OEM coating formulators, distribution channel partners in specialty chemicals, and technical R&D directors at trimellitic anhydride producers combined with secondary validation from customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA regulatory disclosure databases. Triangulation across these sources validates volume and value estimates.
Historical trendline analysis of naphtha-crack spreads, catalytic reforming yield improvements, and regulatory compliance cost trajectories informed projection frameworks across the analysis window. Segmentation dimensions modeled include purity grade tier, end-use application, and regional production hub configuration. CAGRs derived from elasticity-adjusted demand curves incorporating automotive coating specification upgrades and bio-based substitution threats in flexible PVC applications.
Underlying measurement precision varies by segment; semiconductor-grade and laboratory-grade specifications carry tighter precision than commodity solvent volumes due to concentrated supplier bases. Forecasts reflect assumptions regarding MEE enforcement consistency, REACH evaluation timelines, and naphtha price volatility transmission. Regulatory divergence between EPA Method 24 and evolving VOC thresholds, alongside Chinese export policy shifts, warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Organocatalyst Market
Organic Chemicals
North America Biphenyl Market
Organic Chemicals
Acrylonitrile Market
Organic Chemicals
Humic Acid Market
Organic Chemicals
US Humate Market
Organic Chemicals
Organic Hydrosols Market
Organic Chemicals
N-Hexanol Market
Organic Chemicals
Acetic Acid Market
Organic Chemicals
Alanine Market
Organic Chemicals
Europe Organic Acid Market
Organic Chemicals
Gamma-Butyrolactone (GBL) Market
Organic Chemicals
Global Metal-Organic Framework Market
Organic Chemicals
Organic Polysulfide Market
Organic Chemicals
Dimethylformamide (DMF) Market
Organic Chemicals
Nonylphenol Market
Organic Chemicals
Cyclohexanone Market