
 North America Organic Acid Market | 2026-2036
North America Organic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
North America Organic Acid Market Analytics
Food-grade specification upgrades are reorganizing competitive dynamics across the North America organic acid landscape. Cargill, Incorporated leverages its captive corn-milling infrastructure to secure feedstock cost advantages for fermentation-based acids. BASF SE anchors its position through integrated petrochemical and biotechnology pathways, serving both commodity and specialty grades. Eastman Chemical Company differentiates via acetic acid derivatives tailored for pharmaceutical and coatings applications.
Organic acids comprise carboxylic compounds containing one or more –COOH functional groups, typically produced through petrochemical oxidation or microbial fermentation with purity thresholds ranging from technical grade to food-grade and pharmaceutical-grade specifications; these acids function as chemical intermediates, preservatives, pH modifiers, and chelating agents across industrial processes. Acetic acid dominates volume flows due to its role in vinyl acetate monomer and purified terephthalic acid production, while lactic acid captures expanding margin pools as polylactic acid bioplastics gain traction. Citric acid maintains mature demand arcs in beverage acidification, though formic acid is gaining share in animal nutrition and silage preservation.
The US FDA governs food-contact and pharmaceutical-grade acid purity through 21 CFR specifications, while EPA regulations under the Toxic Substances Control Act shape manufacturing discharge and chemical handling protocols; Canada's PMRA and Health Canada impose parallel residue and safety standards affecting agricultural acid applications. The US Department of Agriculture bio-preferred program and emerging state-level carbon intensity scoring are redirecting procurement toward fermentation-derived supply chains. Stakeholders must track evolving biogenic carbon accounting methodologies and their impact on capital allocation between petrochemical and bio-based production platforms.
Market Dynamics
Fermentation-derived production platforms are displacing petrochemical oxidation routes across the North America organic acid landscape as corn-processing clusters in the US Midwest achieve scale economies and regulatory frameworks increasingly weight biogenic carbon intensity in procurement decisions.
Growth Catalysts
- US EPA Safer Choice Program:Tightening specifications for bio-based acid inputs are redirecting formulation chemistry toward fermentation-derived supply chains in household and industrial cleaning products.
- Polylactic acid bioplastics:Expanding capacity for PLA resins is pulling lactic acid demand upward as food packaging and textile fiber applications commercialize at scale.
- Corn-processing clusters:Concentrated feedstock infrastructure across Iowa, Illinois, and Nebraska is lowering delivered costs for dextrose and starch hydrolysates used in microbial fermentation.
Market Restraints
- Natural gas price volatility:Petrochemical oxidation routes for acetic acid and formic acid remain exposed to Henry Hub fluctuations that compress margins during upstream energy spikes.
- Pharmaceutical-grade certification timelines:US FDA 21 CFR compliance for injectable-grade acids requires 18-24 month validation cycles that delay market entry for new fermentation facilities.
- Citric acid substitution:Glucono-delta-lactone and malic acid blends are capturing share in dry-mix beverage applications where clean-label positioning outweighs cost premiums.
Strategic Opportunities
- US Department of Agriculture BioPreferred Program:Federal procurement mandates for biobased content are creating preferential purchasing channels for fermentation-derived acids in institutional cleaning and lubricant applications.
- Canada prairie provinces:Underdeveloped fermentation infrastructure in Saskatchewan and Manitoba offers greenfield sites with access to wheat and canola feedstock streams distinct from US corn dominance.
- Animal nutrition formic acid:Silage preservation and feed acidification in dairy and swine operations represent a margin-accretive application where petrochemical supply chains maintain limited presence.
Industry Challenges
- Metabolic engineering talent scarcity:Strain development for high-titer organic acid production requires specialized synthetic biology expertise concentrated in limited academic and corporate research centers.
- Downstream separation capex:Crystallization and chromatographic purification systems for food-grade and pharmaceutical-grade specifications demand capital intensity that constrains mid-scale facility economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Organic Acid Market |
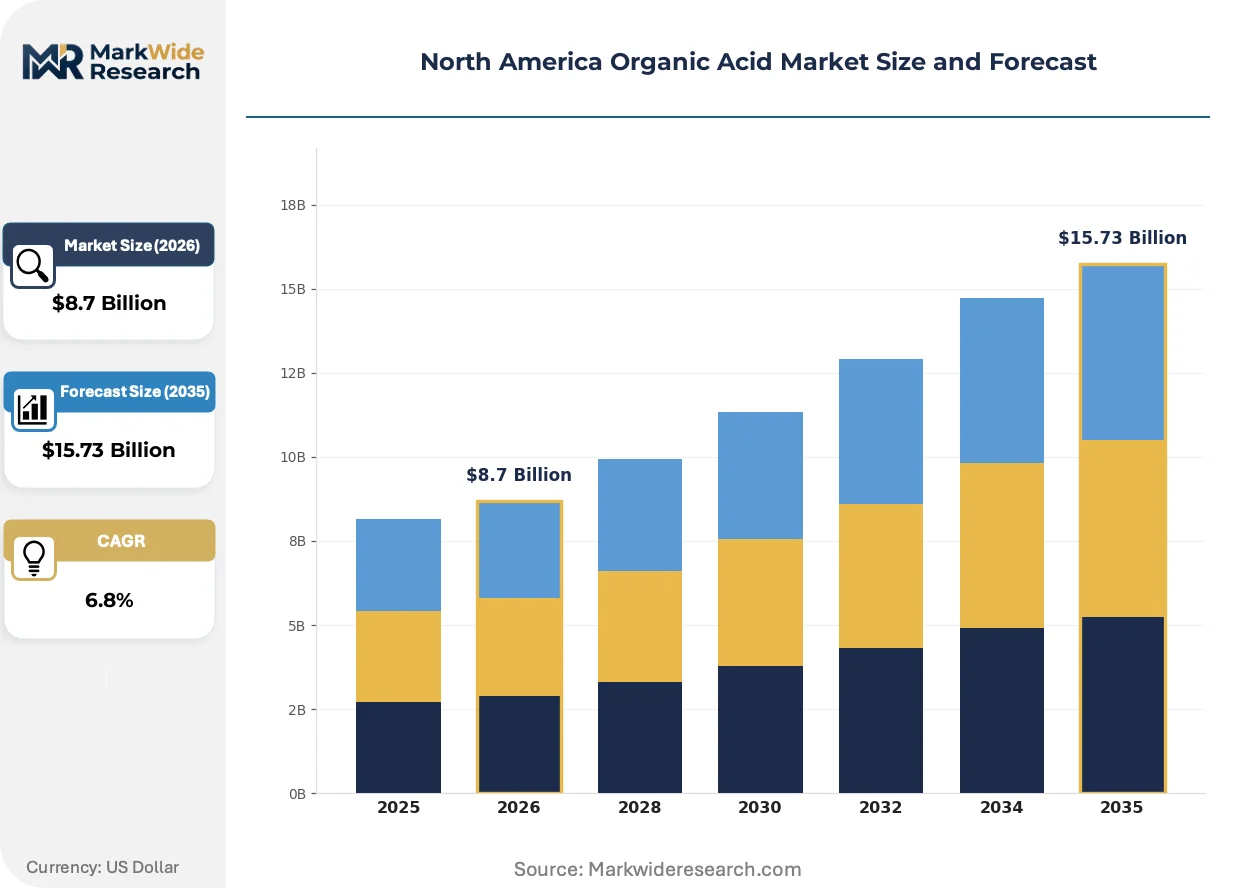
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetic Acid, Citric Acid, Lactic Acid, Formic Acid End Use Industry: Food & Beverage, Pharmaceuticals, Agriculture, Chemicals Application: Preservatives, Flavoring Agents, pH Regulators, Solvents Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Cargill, Incorporated, BASF SE, Archer Daniels Midland Company, Eastman Chemical Company, Tate & Lyle PLC, DuPont, Corbion N.V., Koninklijke DSM N.V., Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Organic Acid Market Evolving Landscape
Continuous fermentation systems and cell-free enzymatic synthesis are compressing unit economics for biobased acids while regulatory carbon accounting methodologies reshape competitive positioning between production platforms.
Cell-free enzymatic cascades are displacing whole-cell fermentation for C3-C6 organic acid synthesis by eliminating biomass formation overhead and achieving higher carbon yields per substrate input. Specialty chemical manufacturers are piloting these systems for pyruvic acid and succinic acid derivatives where titer sensitivity justifies premium enzyme costs. The technology is compressing facility footprints and enabling distributed production models that reduce feedstock transportation requirements.
Canada's Chemicals Management Plan and parallel US EPA TSCA Section 5 premanufacture notification requirements are tightening data requirements for new acid derivatives entering industrial and consumer applications. Biobased acid producers must now submit comprehensive aquatic toxicity and biodegradation dossiers that extend registration timelines by 12-18 months. Food-contact applications face the most stringent scrutiny as Health Canada and US FDA harmonize migration testing protocols for acidulant additives.
Direct contracting between fermentation facilities and downstream compounders is consolidating purchasing relationships that previously ran through regional distributors. Large animal nutrition and food ingredient formulators are establishing multi-year offtake agreements with named production facilities to secure supply continuity and lock in carbon intensity credentials. This pattern is most visible in US Midwest logistics corridors where rail-served corn processors can deliver bulk acids to compounders within 500-mile radiuses.
North America Organic Acid Market Segmentation
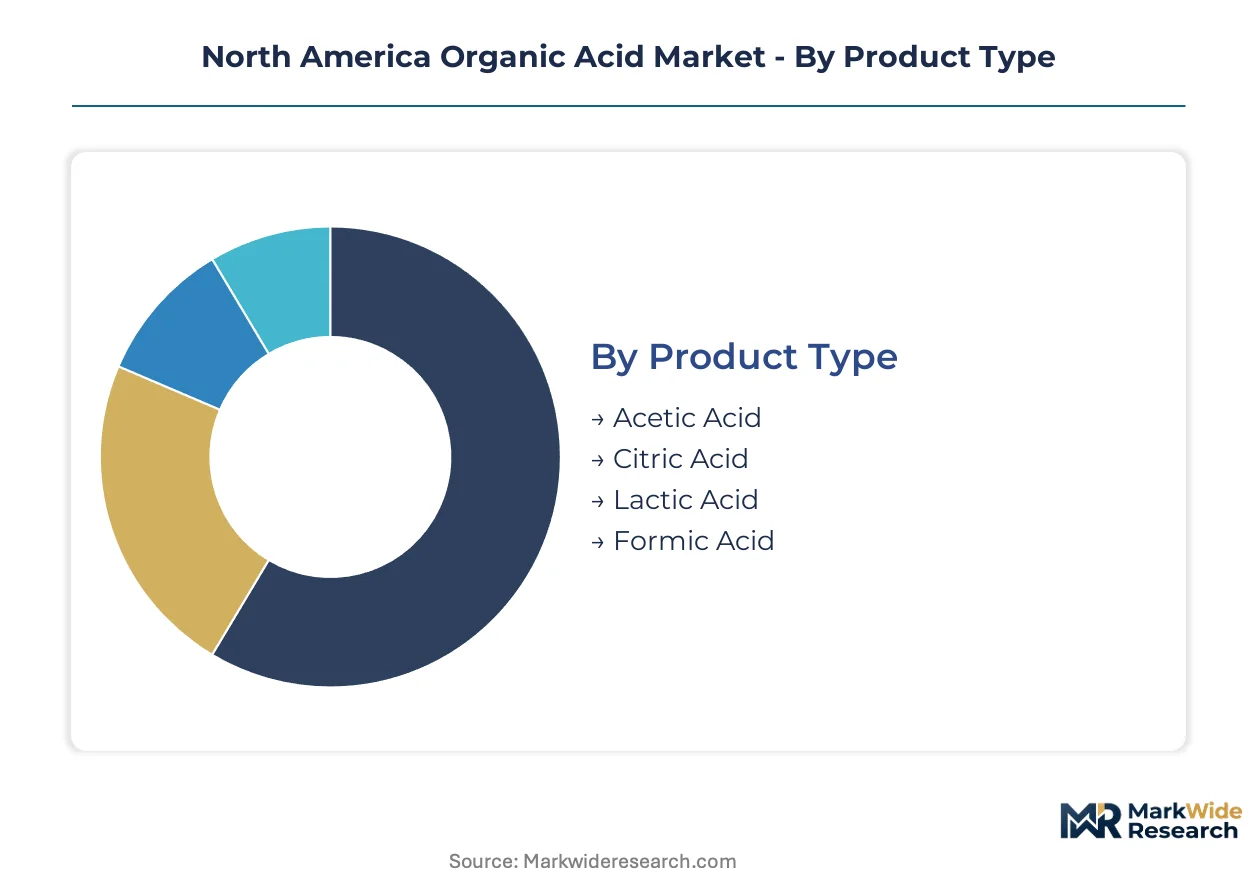
Segmentation in the North America organic acid market reveals how production platform economics, regulatory thresholds, and end-use purity requirements fragment purchasing behavior across distinct supply channels. Understanding these divides exposes where fermentation-derived supply chains command premium positioning versus where petrochemical oxidation routes retain cost advantages.
Product Type:
Channel-mix patterns diverge sharply across acid chemistries, with commodity-grade volumes flowing through distributor networks while pharmaceutical and food-grade specifications demand direct mill-to-compounder relationships.
- Acetic Acid:This C2 carboxylic acid serves as the primary feedstock for vinyl acetate monomer and purified terephthalic acid synthesis, with US Gulf Coast petrochemical complexes dominating technical-grade supply. Demand concentrates in Texas and Louisiana chemical corridors where pipeline networks deliver bulk quantities to polymer producers, though fermentation-derived food-grade material bypasses distributors entirely through captive contracts with vinegar and condiment manufacturers.
- Lactic Acid:Chiral hydroxy acid produced via Lactobacillus fermentation of Midwest corn dextrose, commanding specification premiums for polylactic acid bioplastic polymerization. Iowa and Illinois processing clusters are pulling volume upward as NatureWorks and TotalEnergies Corbion expand PLA resin capacity, with direct rail shipments replacing traditional distributor intermediaries.
- Citric Acid:Tricarboxylic acid from Aspergillus niger fermentation, mature demand arcs in beverage acidification and pharmaceutical buffering.
- Formic Acid:Simplest carboxylic acid with expanding silage preservation and feed acidification applications in Wisconsin and Ontario dairy operations.
By volume, acetic acid leads. By expansion trajectory, lactic acid is climbing the fastest.
End Use Industry:
Cost tier stratification separates pharmaceutical-grade certification investments from technical-grade commodity plays, with margin structures inverting across these boundaries.
- Food & Beverage:Acidulants, preservatives, and pH modifiers governed by FDA 21 CFR and Health Canada food additive regulations. Clean-label fermentation credentials are reorganizing procurement in California and New York natural product formulating hubs, where USDA BioPreferred certification unlocks institutional purchasing.
- Pharmaceuticals:USP-grade acids for injectable formulations and active pharmaceutical ingredient synthesis, with 18-24 month FDA validation cycles creating supply stickiness. New Jersey and Massachusetts compounding facilities are locking in multi-year offtake agreements with named fermentation plants to secure supply continuity.
- Agriculture:Feed acidification, silage preservation, and crop protection adjuvants across US Midwest and Canadian prairie operations.
- Chemicals:Intermediate demand for esters, solvents, and specialty derivatives in Texas and Ontario industrial corridors.
Pharmaceutical-grade specifications capture highest unit margins. Food and beverage applications are expanding most quickly.
Application:
Volume concentration in preservatives reflects their irreplaceable functional role, while pH regulators face substitution pressure from mineral acid alternatives.
- Preservatives:Antimicrobial organic acids inhibiting bacterial and fungal spoilage in processed foods, beverages, and animal feed. Demand clusters in Illinois meat processing and California plant-based food manufacturing, where propionic acid and sorbic acid blends are displacing synthetic alternatives.
- pH Regulators:Buffering systems maintaining stability in pharmaceuticals, cosmetics, and industrial formulations. Citric acid and lactic acid dominate this functional category, with Midwest fermentation facilities supplying Great Lakes region chemical compounders through direct tanker arrangements.
- Flavoring Agents:Acidulants providing tartness profiles in beverages and confectionery, with malic acid and tartaric acid gaining share in clean-label positioning.
- Solvents:Ester derivatives for coatings, adhesives, and extraction applications in Ohio and Ontario manufacturing belts.
Preservatives anchor volume flows. Flavoring agents are gaining share fastest on clean-label momentum.
Distribution Channel:
Customer-type stratification separates bulk industrial purchasers from formulation-scale buyers, with channel economics favoring direct relationships at scale and digital platforms at fragmentation.
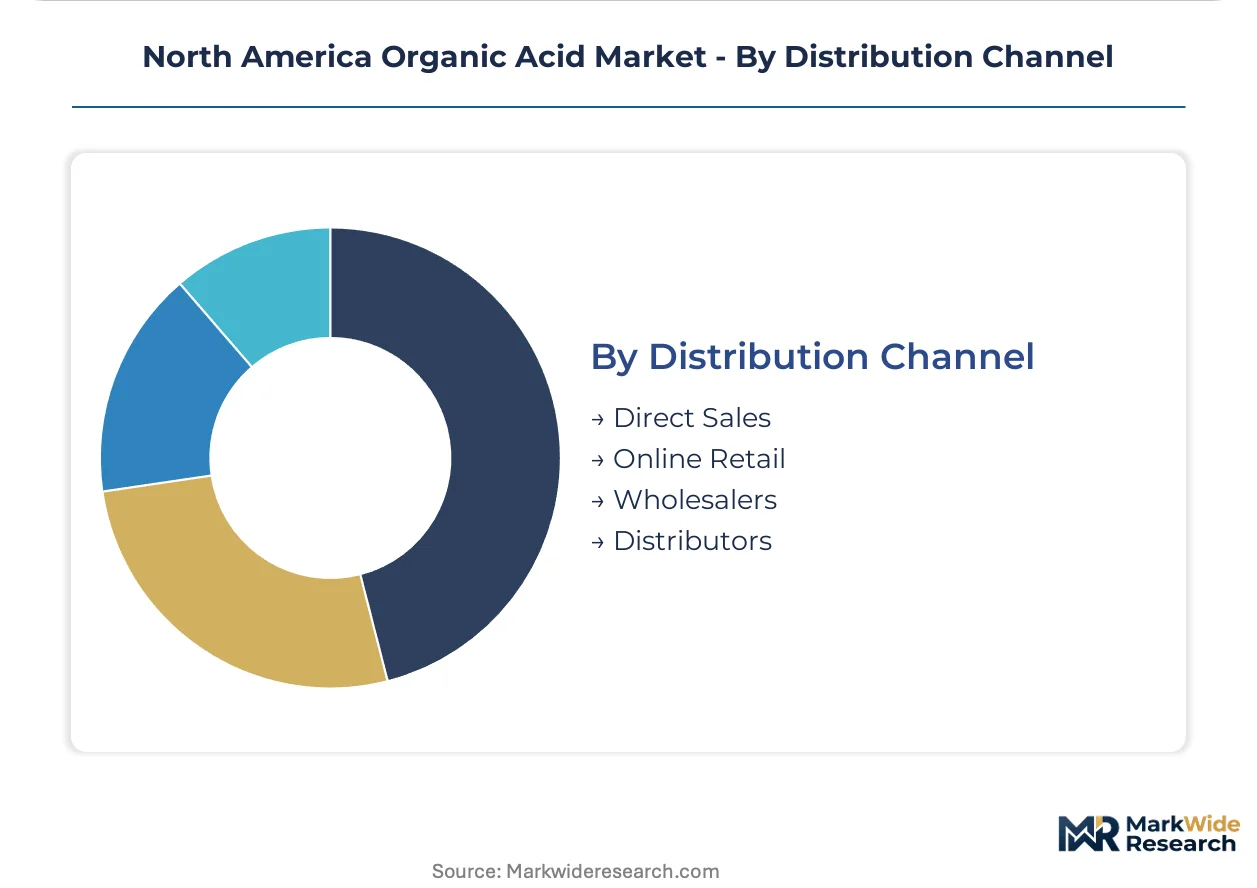
- Direct Sales:Mill-to-compounder contracts for bulk acids exceeding railcar quantities, predominant in US Midwest corn-processing corridors where Cargill and ADM fermentation facilities serve named animal nutrition and food ingredient formulators. These arrangements eliminate distributor markups and enable carbon intensity credentialing for institutional procurement.
- Distributors:Regional chemical distributors holding inventory for mid-scale compounders and blenders, surviving on technical service and formulation support. Their relevance concentrates in fragmented end-use segments where order sizes fall below direct-shipment minimums.
- Wholesalers:Volume aggregators serving smaller food processors and agricultural operations across secondary markets.
- Online Retail:E-procurement platforms capturing laboratory-scale and specialty chemical demand, with fastest penetration in research institutions and startup formulators.
Direct sales dominate value capture. Online retail is expanding most quickly at the long tail of demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North American organic acid trade flows reflect a net export position in fermentation-derived materials balanced against import dependency for select petrochemical grades, with cross-border supply chains integrating US Midwest corn-processing infrastructure and Canadian prairie feedstock development.
United States
Iowa and Illinois corn-processing clusters supply dextrose feedstock for lactic acid and citric acid fermentation at scale. The EPA's Safer Choice program tightens bio-based input specifications for institutional cleaning products. NatureWorks operates PLA resin capacity in Blair, Nebraska, pulling fermentation-derived acid demand upward through direct rail linkages.
Canada
Saskatchewan and Manitoba wheat and canola streams offer alternative carbohydrate feedstocks distinct from US corn dominance. Health Canada's Chemicals Management Plan extends registration timelines for new acid derivatives through aquatic toxicity dossier requirements. Ontario dairy operations in Wellington County drive formic acid uptake for silage preservation and feed acidification.
Mexico
Beverage acidification demand concentrates in Mexico City and Monterrey metropolitan manufacturing zones. COFEPRIS food additive regulations align with US FDA 21 CFR specifications to facilitate cross-border ingredient trade. Jalisco's tequila and beer production corridors source citric acid and lactic acid through Lázaro Cárdenas port logistics.
North America Organic Acid Market Competitive Landscape
Concentration sits with integrated agribusiness conglomerates that command captive corn-milling infrastructure and fermentation capacity. The market structure tiers between commodity-grade volume producers and specialty-grade purity specialists. Strategic archetypes include Midwest-based feedstock-integrated fermenters, European-headquartered diversified chemical multinationals with North American acid platforms, and precision fermentation startups targeting pharmaceutical-grade certification. Dominant competitive moves encompass backward integration into dextrose supply and multi-year offtake contracting with downstream compounders.
Within the feedstock-integrated tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify archetypes that leverage Iowa and Illinois corn-processing clusters to secure delivered cost advantages for fermentation-derived acids. BASF SE and Eastman Chemical Company anchor positions spanning both petrochemical oxidation and biotechnology pathways, serving differentiated specification grades across industrial and specialty applications.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| BASF SE |
| Archer Daniels Midland Company |
| Eastman Chemical Company |
| Tate & Lyle PLC |
| DuPont |
| Corbion N.V. |
| Koninklijke DSM N.V. |
| Celanese Corporation |
| Others |
Value Network & Pricing Analysis
Multi-year offtake agreements between Iowa corn processors and Great Lakes compounders lock in both supply access and price visibility for fermentation-derived acids, insulating buyers from Henry Hub volatility while securing USDA BioPreferred certification pathways for institutional procurement.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the North America organic acid landscape. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade specifications captures margin differentiation tied to FDA 21 CFR certification timelines and downstream purification capex. Cost compression in technical-grade acetic acid is intensifying because Gulf Coast petrochemical complexes maintain spare oxidation capacity. Animal nutrition formulators exhibit highest price sensitivity due to thin feed margins, while pharmaceutical compounders accept premiums for USP-grade supply continuity.
Supply Chain Analysis
Strategic stockpile preferences dominate pharmaceutical-grade acid procurement as New Jersey and Massachusetts compounders maintain 90-day buffers against FDA validation cycle disruptions. Fermentation supply concentrates in the United States, Canada, and Mexico, with Iowa and Illinois corn dextrose streams feeding Midwest bioreactors. Raw material dependencies center on yellow dent corn, wheat starch hydrolysates, and canola-derived carbohydrates. Single-source vulnerability runs through rail-served corn-processing clusters where Cargill and ADM control dextrose supply. Distribution runs through direct mill-to-compounder tanker arrangements for bulk volumes, with regional distributors serving fragmented beverage and agricultural blenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
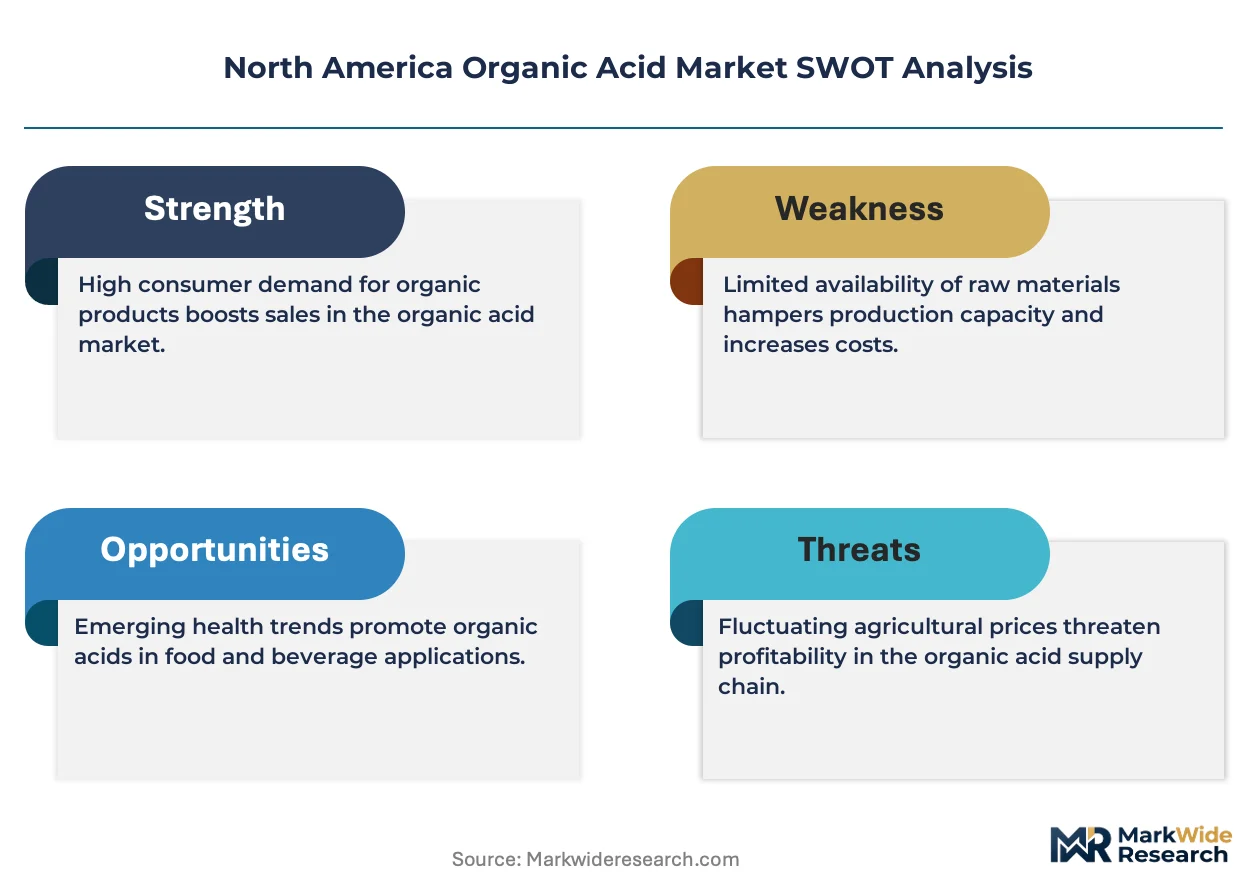
Fragmentation opportunity exists as clean-label demand splits procurement between fermentation-derived and petrochemical oxidation platforms, creating tiered supply niches that reward specialized certification investments over commodity scale.
For Market Incumbents: Compound feedstock-advantaged positions by securing captive dextrose supply from Nebraska and Iowa corn-milling infrastructure. Deepen strain development capabilities through synthetic biology partnerships to defend against cell-free enzymatic synthesis startups targeting pyruvic acid and succinic acid derivatives. Prioritize USP-grade certification investments to lock in pharmaceutical compounder relationships before 18-24 month FDA validation cycles create supply stickiness. For New Entrants and Emerging Players: Custom fermentation services for precision organic acid derivatives represent a service-layer gap where incumbents under-serve mid-scale specialty chemical formulators. Target Saskatchewan and Manitoba greenfield sites with wheat and canola feedstock access distinct from US corn dominance. Pursue toll manufacturing arrangements with existing bioreactor capacity to bypass crystallization capex barriers while building customer relationships. For Investors and Strategic Acquirers: Capital is best deployed toward fermentation facilities with named pharmaceutical-grade offtake agreements and rail-served Midwest locations. Long-term viability hinges on biogenic carbon accounting methodology alignment that privileges fermentation platforms in federal and state procurement. Watch for USDA BioPreferred program expansion into lubricant and cleaning product categories as inflection indicator for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dextrose Supply | Cargill and ADM leverage Iowa corn-milling infrastructure to secure fermentation feedstock cost advantages. |
| Pharmaceutical-Grade Certification Investment | FDA 21 CFR compliance for injectable-grade acids creates 18-24 month supply stickiness with compounders. |
| Cell-Free Enzymatic Synthesis Piloting | Specialty manufacturers achieve higher carbon yields per substrate input for C3-C6 acid derivatives. |
| Multi-Year Offtake Contracting | Direct mill-to-compounder arrangements eliminate distributor markups and enable carbon intensity credentialing. |
| Prairie Province Greenfield Development | Saskatchewan and Manitoba wheat and canola streams offer feedstock diversification from US corn dominance. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA Safer Choice program documentation, FDA 21 CFR regulatory filings, USDA BioPreferred procurement databases, and ACC industry reports. Plant managers at Midwest fermentation facilities, procurement leads at animal nutrition compounders, distribution channel partners serving food ingredient formulators, and technical R&D directors at specialty chemical manufacturers provided operational perspective. Bottom-up volume modeling triangulated against top-down market sizing from trade flow analysis.
Segmentation dimensions modeled include acid chemistry, grade tier, end-use industry, application function, and distribution channel across the projection horizon. CAGRs were derived from production capacity buildout schedules, PLA resin demand pull-through coefficients, and regulatory procurement mandate adoption curves. Forecast inputs incorporated corn dextrose price trajectories, natural gas oxidation economics, and biogenic carbon accounting methodology evolution.
Forecasts assume regulatory continuity in US EPA TSCA and Canada Chemicals Management Plan regimes; material policy shifts would require re-modeling. Forecasts reflect assumptions regarding fermentation technology yield improvements and petrochemical feedstock price stability. Revision becomes warranted when cell-free enzymatic synthesis cost curves cross whole-cell fermentation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Diethyl Ketone Market
Organic Chemicals
Global Benzoic Acid Market
Organic Chemicals
Dimethylformamide (DMF) Market
Organic Chemicals
Benzethonium Chloride Market
Organic Chemicals
Dioctyl Phthalate Market
Organic Chemicals
Oryzenin Market
Organic Chemicals
Para-Tert-Octylphenol (POTP) Market
Organic Chemicals
Anisole Derivatives Market
Organic Chemicals
Synthetic and Bio-Based Aniline Market
Organic Chemicals
Global Metal-Organic Framework Market
Organic Chemicals
2-Iodophenol Market
Organic Chemicals
Long-Chain Dicarboxylic Acid Market
Organic Chemicals
Organic Polysulfide Market
Organic Chemicals
1,3-Dioxolane Market
Organic Chemicals
Cyclopentanone Market
Organic Chemicals
Europe Lactic Acid Market