
 Synthetic and Bio-Based Aniline Market | 2026-2036
Synthetic and Bio-Based Aniline Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic and Bio-Based Aniline Market Analysis
Buyer concentration in the rubber and automotive supply chain is decoupling from traditional petrochemical offtake patterns as specialty polymer compounders and bio-based material developers fragment procurement across smaller, sustainability-screened suppliers. BASF SE leverages its integrated Ludwigshafen complex to sustain cost-advantaged polymer-grade aniline output for European tire manufacturers. Covestro AG anchors its position through captive consumption in methylene diphenyl diisocyanate chains, while Wanhua Chemical Group dominates Asian merchant supply with backward integration into nitrobenzene feedstock.
Synthetic and bio-based aniline denotes aromatic amine compounds produced via nitrobenzene hydrogenation or emerging biomass-derived pathways, typically exhibiting 99.5% minimum purity for polymer applications and serving as essential precursors for polyurethane foams, rubber chemicals, and pharmaceutical intermediates. Polymer grade aniline commands the dominant value share due to its irreplaceable role in MDI synthesis for construction and refrigeration insulation. Eco-friendly process methods are gaining fastest traction as REACH restrictions and carbon border adjustments elevate the cost structure of conventional nitration routes, while technical grade segments retain volume leadership in commodity dye and agrochemical applications.
The European Chemicals Agency enforces REACH registration and authorization protocols that constrain conventional aniline production economics, while China's Ministry of Ecology and Environment applies dual carbon goals to tighten nitrobenzene plant emissions permits. The EPA in the United States monitors benzene exposure limits under OSHA standards, shaping workplace controls and capital allocation for domestic producers. Stakeholders must monitor feedstock volatility in benzene and renewable carbohydrate streams alongside regulatory tightening in major manufacturing jurisdictions to align capacity investments with evolving compliance thresholds.
Market Dynamics
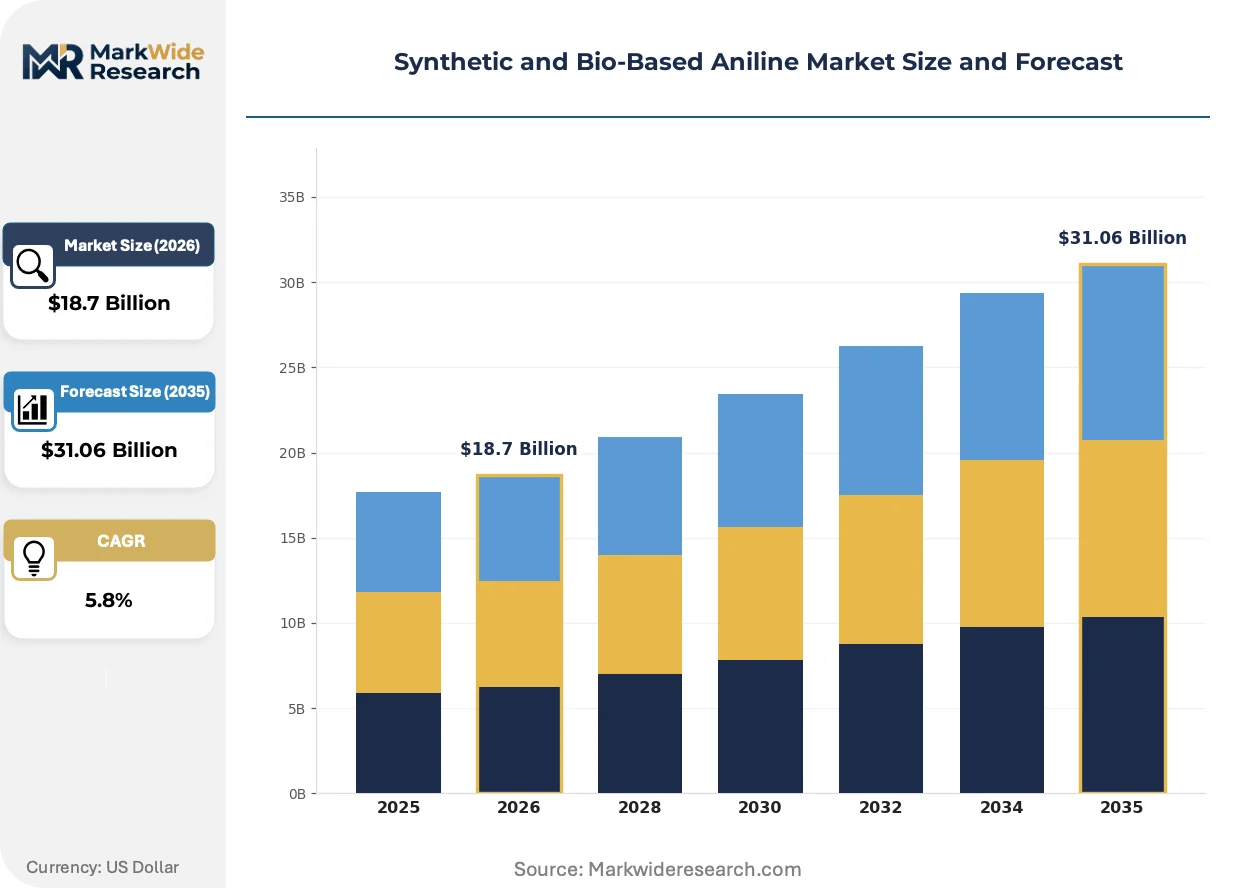
The Synthetic and Bio-Based Aniline Market is undergoing structural recalibration as REACH authorization protocols and EU Green Deal carbon border adjustments force European producers toward catalytic hydrogenation retrofits and biomass-derived feedstock trials, while Asian capacity expansion concentrates merchant supply power in nitrobenzene-integrated complexes.
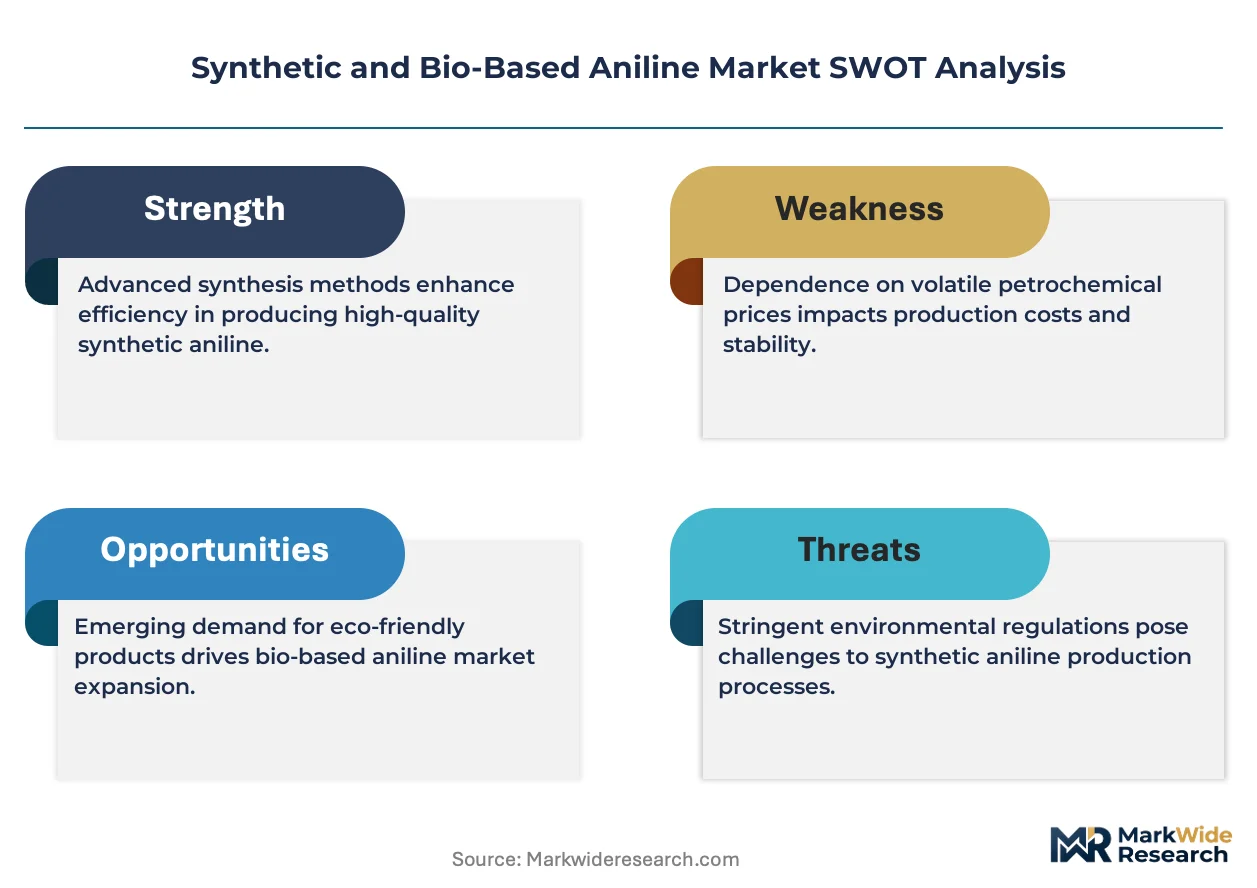
Growth Catalysts
- REACH Compliance Deadlines:The European Chemicals Agency's authorization requirements for conventional nitration routes are accelerating capital deployment into catalytic synthesis retrofits among Ludwigshafen and Antwerp corridor producers.
- Polyurethane Construction Demand:Methylene diphenyl diisocyanate consumption for refrigeration insulation and building panels is pulling polymer-grade aniline volumes upward across Germany, China, and India.
- Rubber Processing Expansion:Asia-Pacific tire manufacturing clusters are absorbing incremental aniline derivative capacity for accelerator chemicals and antidegradant formulations.
Market Restraints
- Benzene Feedstock Volatility:Crude oil price oscillations transmit directly to nitrobenzene production economics, compressing margin visibility for non-integrated merchant suppliers.
- Chinese Supply Concentration:Wanhua Chemical Group and state-affiliated nitrobenzene complexes control the majority of Asian merchant export volumes, creating offtake dependency risk for European compounders.
- Technical Purity Thresholds:Pharmaceutical and electronic-grade applications demand sub-50 ppm impurity profiles that conventional hydrogenation trains struggle to achieve without distillation column expansion.
Strategic Opportunities
- Indian Domestic Capacity Gap:Substantial MDI and rubber chemical demand growth is outpacing local nitrobenzene-aniline integration, creating import substitution potential for producers with benzene pipeline access.
- Biomass-Derived Pathways:Lignin and carbohydrate fermentation routes to aniline are attracting pilot-scale investment as the EU Green Deal carbon border adjustment mechanism elevates conventional route costs.
- Specialty Agrochemical Intermediates:Technical-grade aniline derivatives for fungicide and herbicide synthesis represent underserved volume pockets outside the polyurethane concentration zones.
Industry Challenges
- Catalytic Process Engineering Talent:The shift from conventional acid nitration to vapor-phase hydrogenation and emerging biochemical routes has created scarcity in reactor design and catalyst selection expertise.
- REACH Authorization Timelines:The European Chemicals Agency's substance evaluation and authorization protocols extend 18-36 months, freezing formulation decisions for downstream compounders awaiting regulatory certainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic and Bio-Based Aniline Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aniline Oil, Aniline Hydrochloride, Polymer Grade Aniline, Industrial Aniline End Use Industry: Textiles, Paints, Rubber, Pharmaceuticals Production Method: Chemical Synthesis, Eco-Friendly Process, Catalytic Process, Biochemical Synthesis Market Segment: Technical Grade, Food Grade, Specialty Grade, Others |
| Companies Covered | Lanxess AG, Sumitomo Chemical Co., Ltd., BASF SE, Shandong Jinling Group, Bondalti Chemicals, Covestro AG, Huntsman International LLC, Sinopec Group, Wanhua Chemical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic and Bio-Based Aniline Market Emerging Trajectories
Process intensification and feedstock diversification are fragmenting the traditional nitrobenzene hydrogenation monopoly, as regulatory pressure and carbon accounting requirements open competitive space for novel synthesis architectures.
Continuous flow hydrogenation reactor technology is modularizing aniline production economics by enabling distributed, smaller-scale units that reduce benzene inventory exposure and permit rapid feedstock switching. Specialty chemical producers in the Netherlands and Belgium are piloting skid-mounted systems for pharmaceutical-grade output. This distributed architecture is compressing the minimum efficient scale for competitive entry, challenging the historical dominance of Ludwigshafen-scale integrated complexes.
The EU Green Deal's carbon border adjustment mechanism is tightening emissions accounting for imported aniline and MDI derivatives, forcing non-European exporters to document process carbon intensity or face tariff escalation. German automotive and construction buyers are now screening suppliers for Scope 3 disclosure compliance. Asian merchant exporters without verified low-carbon production routes are experiencing tender exclusion from premium European offtake contracts.
Compounders in the tire and construction insulation sectors are consolidating supplier relationships around dual-source frameworks that split volumes between established petrochemical-grade suppliers and emerging bio-based certification holders. This bifurcation is fragmenting procurement departments into sustainability-screened and cost-optimized buying cells. The segmentation is most pronounced in Germany and France, where automotive OEMs have mandated renewable content thresholds in polyurethane component specifications.
Synthetic and Bio-Based Aniline Market Segmentation
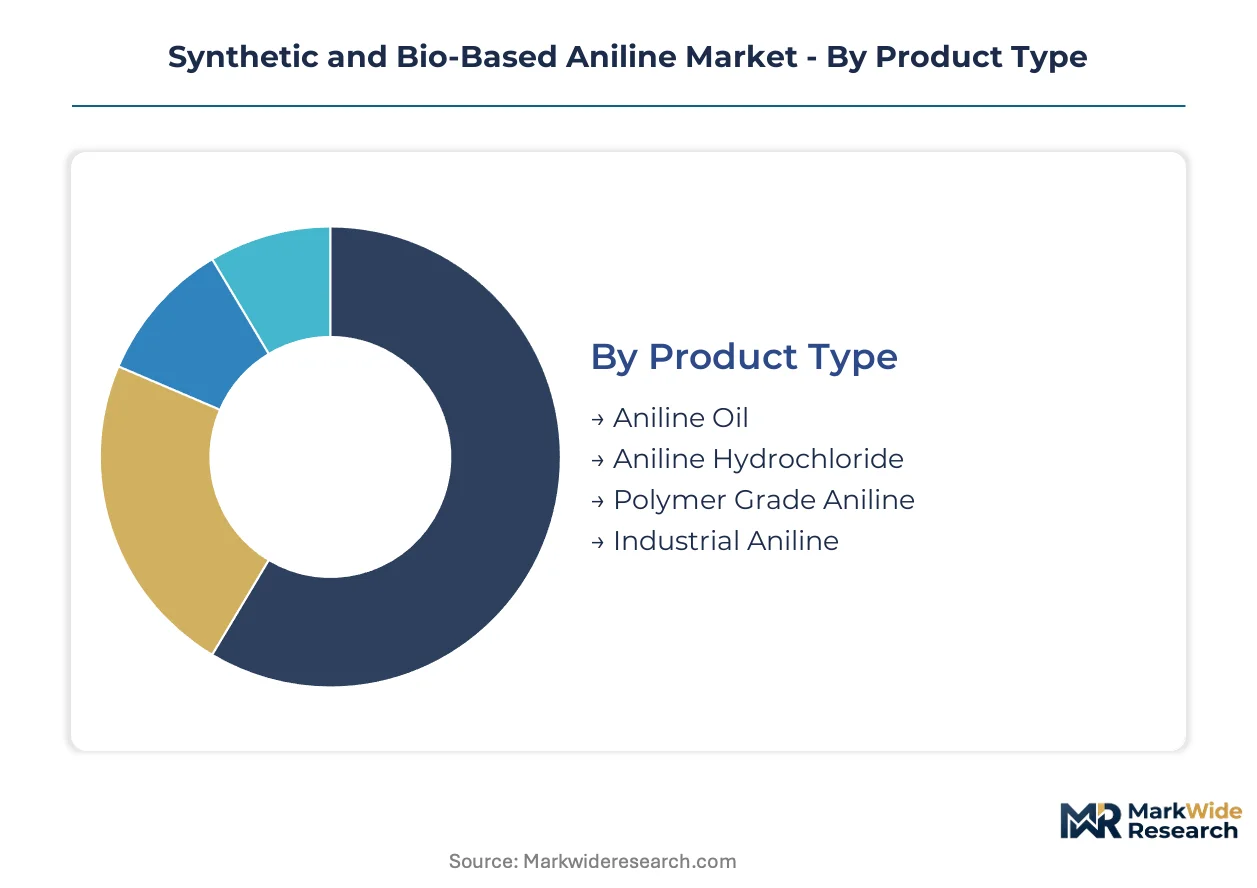
Aniline segmentation determines pricing power and compliance burden across distinct purity thresholds and synthesis pathways. Buyers in MDI chains and rubber processing demand polymer-grade specifications, while agrochemical formulators absorb technical-grade volumes at compressed margins.
Product Type:
Upgrade cycles in polyurethane insulation and automotive rubber are elevating purity requirements across all product categories.
- Polymer Grade Aniline:Specifications demand 99.5% minimum purity with sub-50 ppm impurity profiles for methylene diphenyl diisocyanate synthesis. German construction insulation manufacturers and Chinese refrigerator panel producers anchor demand concentration, though distillation column expansion requirements constrain new entrants.
- Aniline Oil:The standard liquid formulation serves commodity dye intermediates and agrochemical synthesis where purity tolerances remain broader. Indian rubber chemical compounders and Brazilian fungicide manufacturers represent the primary offtake concentration zones.
- Aniline Hydrochloride:Salt-form variant for pharmaceutical intermediate synthesis and specific diazotization reactions in dye manufacture.
- Industrial Aniline:Lower-purity grade capturing volume in metal finishing and general chemical synthesis applications.
Volume placements concentrate in Polymer Grade Aniline; the faster expansion belongs to Aniline Oil.
End Use Industry:
Cost tier differentiation separates specification-intensive pharmaceutical offtake from commodity rubber and textile absorption.
- Rubber:Tire manufacturing clusters in India, Thailand, and Germany consume aniline derivatives for accelerator chemicals and antidegradant formulations. REACH authorization protocols for conventional nitration routes are forcing compounders toward certified low-carbon supplier lists.
- Pharmaceuticals:Sub-50 ppm impurity thresholds for active pharmaceutical ingredient precursors command substantial purity premiums. CDSCO registration requirements in India and FDA oversight in the United States extend qualification timelines.
- Textiles:Dye intermediate synthesis absorbs technical-grade volumes with cyclical demand tied to apparel production cycles.
- Paints:Pigment and coating additive applications represent fragmented, price-sensitive offtake.
Margin capture peaks in Pharmaceuticals; Rubber retains volume leadership.
Production Method:
Application requirements dictate method selection, with carbon accounting now filtering tender eligibility for European offtake.
- Chemical Synthesis:Conventional nitrobenzene hydrogenation dominates installed capacity. BASF's Ludwigshafen complex and Wanhua's Ningbo facilities exemplify benzene-backward integrated economics.
- Eco-Friendly Process:Lignin and carbohydrate fermentation routes attract pilot-scale investment as EU Green Deal carbon border adjustments elevate conventional route costs. Dutch specialty chemical producers are trialing skid-mounted distributed units.
- Catalytic Process:Vapor-phase hydrogenation retrofits reduce benzene inventory exposure and emissions intensity.
- Biochemical Synthesis:Enzymatic reduction pathways remain pre-commercial but draw venture funding for pharmaceutical-grade applications.
Capacity concentration remains in Chemical Synthesis; Eco-Friendly Process is climbing the fastest.
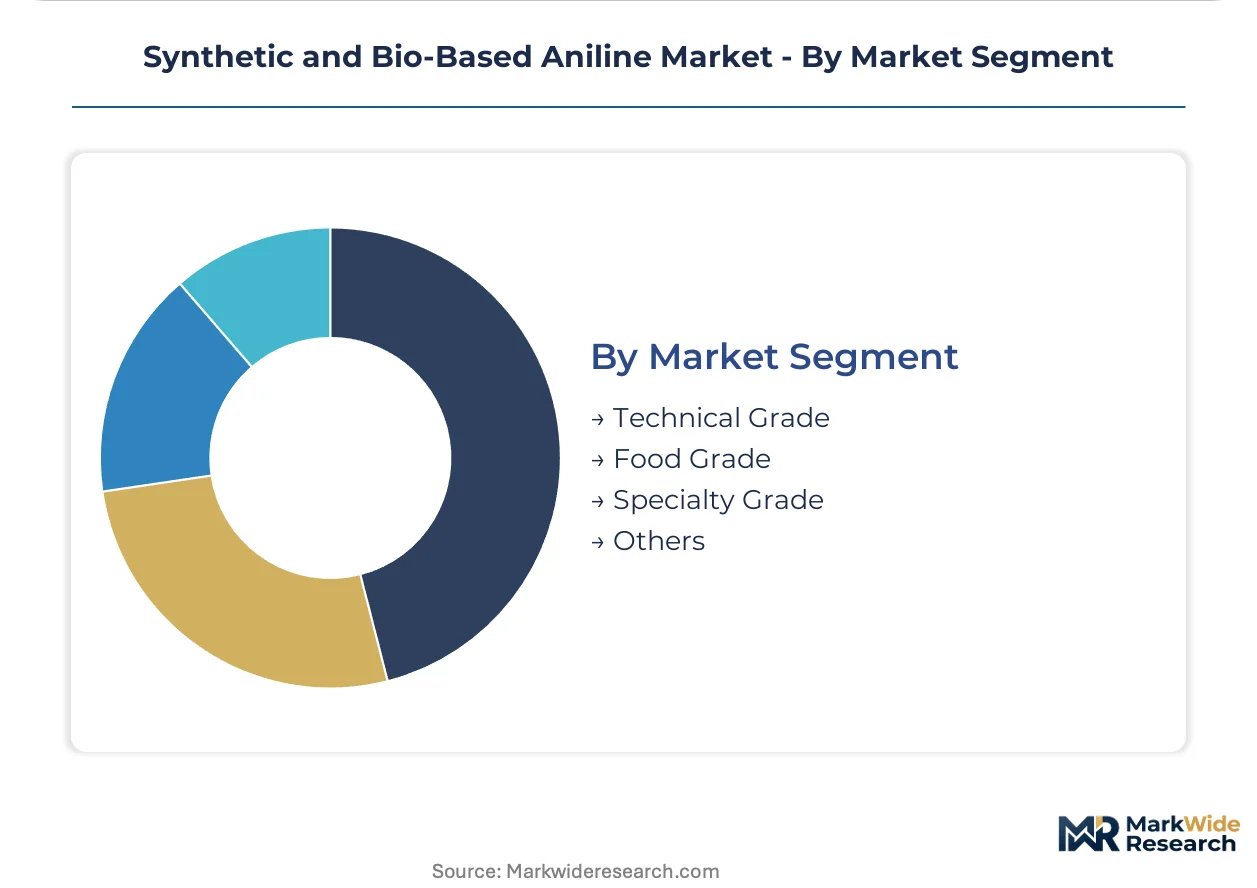
Market Segment:
Customer type bifurcation splits procurement between specification-intensive compounders and price-optimized commodity buyers.
- Technical Grade:Broad impurity tolerances serve agrochemical intermediates, general dyes, and metal finishing. Chinese state-affiliated complexes and Indian merchant exporters compete on delivered cost.
- Specialty Grade:Electronic and pharmaceutical applications demand documented batch consistency and traceability. German automotive OEMs now mandate renewable content thresholds in polyurethane component specifications.
- Food Grade:Limited applications in approved food contact materials and specific additive synthesis.
- Others:Captures emerging certification categories and custom synthesis contracts.
Supply concentration sits with Technical Grade; Specialty Grade is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China, Germany, and India concentrate the majority of polymer-grade aniline demand, driven by MDI consumption for construction insulation and rubber processing chemicals. Regulatory divergence between REACH-authorized European production and emission-tightened Asian manufacturing is fragmenting procurement patterns across these three demand poles.
China
MDI production for refrigerator panel and construction foam applications absorbs the largest polymer-grade volumes globally. The Ministry of Ecology and Environment applies dual carbon goals to tighten nitrobenzene plant emissions permits, favoring integrated producers with captive benzene supply. The Ningbo petrochemical cluster hosts backward-integrated aniline-nitrobenzene complexes serving both domestic polyurethane manufacturers and export markets.
Germany
Automotive OEMs and construction insulation manufacturers anchor European polymer-grade consumption, with tire compounders demanding REACH-compliant accelerator derivatives. The EU Green Deal carbon border adjustment mechanism elevates process emissions scrutiny for imported material. The Ludwigshafen chemical complex sustains cost-advantaged output through benzene pipeline integration and catalytic hydrogenation retrofits.
India
Rubber chemical and emerging MDI demand is outpacing domestic nitrobenzene-aniline integration capacity, creating sustained import dependency. CDSCO registration requirements for pharmaceutical-grade applications extend qualification timelines for specialty compounders. The Gujarat chemical belt and Maharashtra industrial corridors concentrate rubber processing and agrochemical intermediate manufacturing.
United States
Polyurethane foam producers for construction and refrigeration represent the primary offtake channel, with specialty agrochemical intermediate demand providing secondary volume. The EPA monitors benzene exposure limits under OSHA standards, shaping workplace controls and capital allocation decisions. The Gulf Coast petrochemical corridor maintains nitrobenzene-integrated supply positions serving domestic MDI chains.
Japan
Electronic-grade and pharmaceutical intermediate applications command premium pricing for ultra-high-purity specifications. METI industrial policy encourages process efficiency investments and carbon intensity reduction in chemical manufacturing. The Chubu/Nagoya industrial zone concentrates specialty chemical production serving semiconductor and automotive supply chains.
Synthetic and Bio-Based Aniline Market Vendor Landscape
German producers anchor one tier; Chinese specialists hold merchant supply dominance. The market structure bifurcates between benzene-backward integrated complexes achieving scale economies and regional compounders serving technical-grade niches. Three archetypes define competitive positioning: nitrobenzene-integrated multinational chemical groups, state-affiliated Asian merchant suppliers, and European specialty producers with REACH-authorized catalytic routes. Capacity expansion and feedstock integration represent the dominant competitive moves, with secondary emphasis on sustainability certification for European offtake eligibility.
Within the integrated multinational tier, BASF SE and Covestro AG exemplify the European archetype of benzene-pipeline-integrated production with captive MDI consumption. Wanhua Chemical Group occupies the dominant position among Asian merchant suppliers with nitrobenzene backward integration. These three entities represent the structural poles around which procurement patterns in tire manufacturing, construction insulation, and pharmaceutical intermediate supply chains currently organize.
| Leading Market Players |
|---|
| Lanxess AG |
| Sumitomo Chemical Co., Ltd. |
| BASF SE |
| Shandong Jinling Group |
| Bondalti Chemicals |
| Covestro AG |
| Huntsman International LLC |
| Sinopec Group |
| Wanhua Chemical Group |
| Others |
Supply Flow & Price Mechanics
Benzene-backward integration into nitrobenzene-aniline complexes anchors pricing power for Ludwigshafen and Ningbo corridor producers, while non-integrated merchant suppliers absorb margin compression from feedstock volatility and REACH compliance cost escalation. This structural asymmetry fragments procurement negotiations across polymer-grade specification tiers.
Pricing Analysis
Volume placements in technical-grade aniline oil for agrochemical intermediates compress margins against polymer-grade premiums commanded by MDI chain suppliers. Three-tier pricing structure across polymer, technical, and industrial grades reflects purity thresholds and certification burden rather than brand differentiation. Cost compression in technical-grade segments is intensifying because Chinese state-affiliated complexes flood export markets with nitrobenzene-integrated supply. Rubber compounders in India and Thailand exhibit highest price sensitivity; pharmaceutical API precursor buyers accept substantial premiums for sub-50 ppm impurity documentation.
Supply Chain Analysis
Direct-to-MDI-plant pipeline networks handle captive consumption volumes for BASF and Covestro, while merchant spot markets absorb residual technical-grade flows. Supply concentrates in China, Germany, and India as primary manufacturing poles, with feedstock draws from benzene crackers and catalytic reformers. Raw material dependencies center on benzene feedstock, hydrogen supply, and nitrobenzene intermediate streams. Single-source vulnerability from Wanhua Chemical Group's dominance in Asian merchant export volumes creates offtake dependency risk for European compounders lacking dual-source frameworks. Distribution runs through integrated chemical complexes, regional distribution terminals, and specialty chemical distributors serving pharmaceutical and electronic-grade niches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vapor-phase hydrogenation retrofits and lignin-derived biochemical pathways are displacing conventional acid nitration routes, forcing capital reallocation across the installed base. This technology-transition phase rewards early movers with REACH-authorized catalytic processes and verified carbon intensity documentation.
For Market Incumbents: Extend catalytic hydrogenation retrofit programs across Ludwigshafen and Antwerp corridor assets to preempt REACH authorization cost escalation. Lock in long-term benzene pipeline contracts and dual-source supplier frameworks to defend margin position against Wanhua Chemical Group's merchant supply dominance. Prioritize Scope 3 disclosure compliance to maintain European automotive OEM tender eligibility.
For New Entrants and Emerging Players: The premium-to-economy price gap in pharmaceutical-grade aniline hydrochloride offers white-space entry for fermentation-derived pathways with CDSCO and FDA registration support. Target Indian domestic capacity gaps in MDI and rubber chemical supply chains where import dependency outpaces local nitrobenzene-aniline integration. Pursue skid-mounted distributed production architectures to compress minimum efficient scale and enable rapid feedstock switching.
For Investors and Strategic Acquirers: Exit pathways concentrate in benzene-backward integrated mid-cap specialists with REACH-authorized production routes and established pharmaceutical customer qualifications. Long-term viability hinges on carbon intensity positioning as EU Green Deal carbon border adjustments escalate conventional route costs. Watch for inflection in EU carbon border adjustment enforcement timelines that would accelerate tender exclusion for non-compliant Asian exporters.
| Strategic Initiative | Industry Significance |
|---|---|
| Catalytic Hydrogenation Retrofit | REACH authorization protocols force acid nitration replacement to preserve European market access. |
| Backward Integration into Nitrobenzene | Benzene pipeline integration secures cost advantage against merchant feedstock volatility. |
| Biomass-Derived Pathway Pilot | Lignin fermentation routes attract venture funding for EU Green Deal compliance positioning. |
| Dual-Source Supplier Framework | Rubber compounders split volumes between petrochemical and bio-based certification holders. |
| Pharmaceutical Grade Qualification | CDSCO and FDA registration extends qualification timelines but commands substantial purity premiums. |
Methodological Framework
Multi-period observation of nitrobenzene plant emissions permits, REACH authorization timelines, and MDI capacity utilization anchored the trend analysis, supplemented by interviews with plant managers at integrated chemical complexes, procurement leads at tire manufacturers, distribution channel partners in specialty chemical networks, and technical R&D directors in catalytic process engineering. Secondary validation drew from ECHA substance registration databases, customs and trade flow data, SEC 10-K filings of listed chemical groups, and Cefic industry reports. Bottom-up capacity and consumption modeling triangulated against top-down macroeconomic demand drivers.
Input-output matrices mapped benzene feedstock costs, hydrogen supply economics, and regulatory compliance burden across production method segments and grade tiers throughout the forecast period. Segmentation dimensions spanned product type, end-use industry, production method, and market grade. CAGRs were derived from regression analysis of historical capacity expansion patterns against downstream polyurethane and rubber chemical demand trajectories. Forecast inputs incorporated dual carbon goal enforcement intensity from China's Ministry of Ecology and Environment and EU carbon border adjustment mechanism implementation pace.
Inputs from ECHA registration databases and Chinese provincial emissions permit disclosures were available through the study window; gaps in verified process carbon intensity data for Asian merchant exporters introduce uncertainty bands around European offtake share projections. Forecasts reflect assumptions regarding REACH authorization timeline adherence and carbon border adjustment tariff escalation schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Phenolic Board Market
Organic Chemicals
Organic Chemicals Market
Organic Chemicals
DMDM Hydantoin Market
Organic Chemicals
Azelaic Acid Market
Organic Chemicals
Cyclopentanone Market
Organic Chemicals
Organic Polysulfide Market
Organic Chemicals
Anisole Derivatives Market
Organic Chemicals
Behenyl Alcohol Market
Organic Chemicals
Dioctyl Maleate (DOM) Market
Organic Chemicals
2-Fluorobenzotrifluoride Market
Organic Chemicals
North America Humic Acid Market
Organic Chemicals
Asia-Pacific Synthetic Camphor Market
Organic Chemicals
Alanine Market
Organic Chemicals
Phenol Market
Organic Chemicals
Synthetic Antioxidants Market
Organic Chemicals
Oryzenin Market