
 US Humate Market | 2026-2036
US Humate Market Size, Share, and Industry Trends Forecast 2026-2036
US Humate Market Intelligence
The displacement of synthetic chelating agents by natural humic substances is consolidating the value proposition for organic soil amendments. The Andersons Inc. leverages its vast distribution network to supply humate products to large-scale agricultural producers across the US. Bio Huma Netics Inc. specializes in its proprietary Micro Carbon Technology to enhance nutrient efficiency for various crops. Actagro LLC competes through its portfolio of scientifically formulated humic-based soil and plant health solutions.
Humates are salts derived from humic acid, a primary organic component of soil and geologic deposits like leonardite. These substances function commercially to improve soil structure, boost nutrient uptake by plants, and increase water holding capacity. Among product types, potassium humate commands the largest share, valued for its solubility and compatibility with common fertilizers. Granular and liquid concentrate forms are prevalent in agriculture, designed for efficient application with existing farm machinery.
The USDA's National Organic Program (NOP) provides a critical framework, allowing certified humate products to access the high-value organic farming market. Concurrently, EPA guidelines for soil amendments ensure product safety and environmental compliance, which builds confidence among conventional crop producers. Future supplier success will depend on demonstrating quantifiable improvements in soil carbon sequestration and water use efficiency to align with evolving agricultural policy goals.
Market Dynamics
The primary force shaping the US humate market is the institutionalization of soil health within federal agricultural policy. USDA incentives for climate-smart practices are elevating humic substances from niche amendments to critical components of mainstream production, particularly for large-scale row crop operations.
Growth Catalysts
- Climate-Smart Agriculture Policy:USDA programs promoting soil carbon sequestration and reduced fertilizer runoff provide direct financial and operational incentives for farmers in the Midwest to adopt humate products.
- Synthetic Agent Displacement:In large-scale row crop production, humates are increasingly substituted for synthetic chelating agents due to their comparable efficacy and alignment with sustainable farming principles.
- Water Scarcity Concerns:In arid and semi-arid farming regions, the documented ability of humates to improve soil water holding capacity is a powerful value proposition for agricultural producers.
Market Restraints
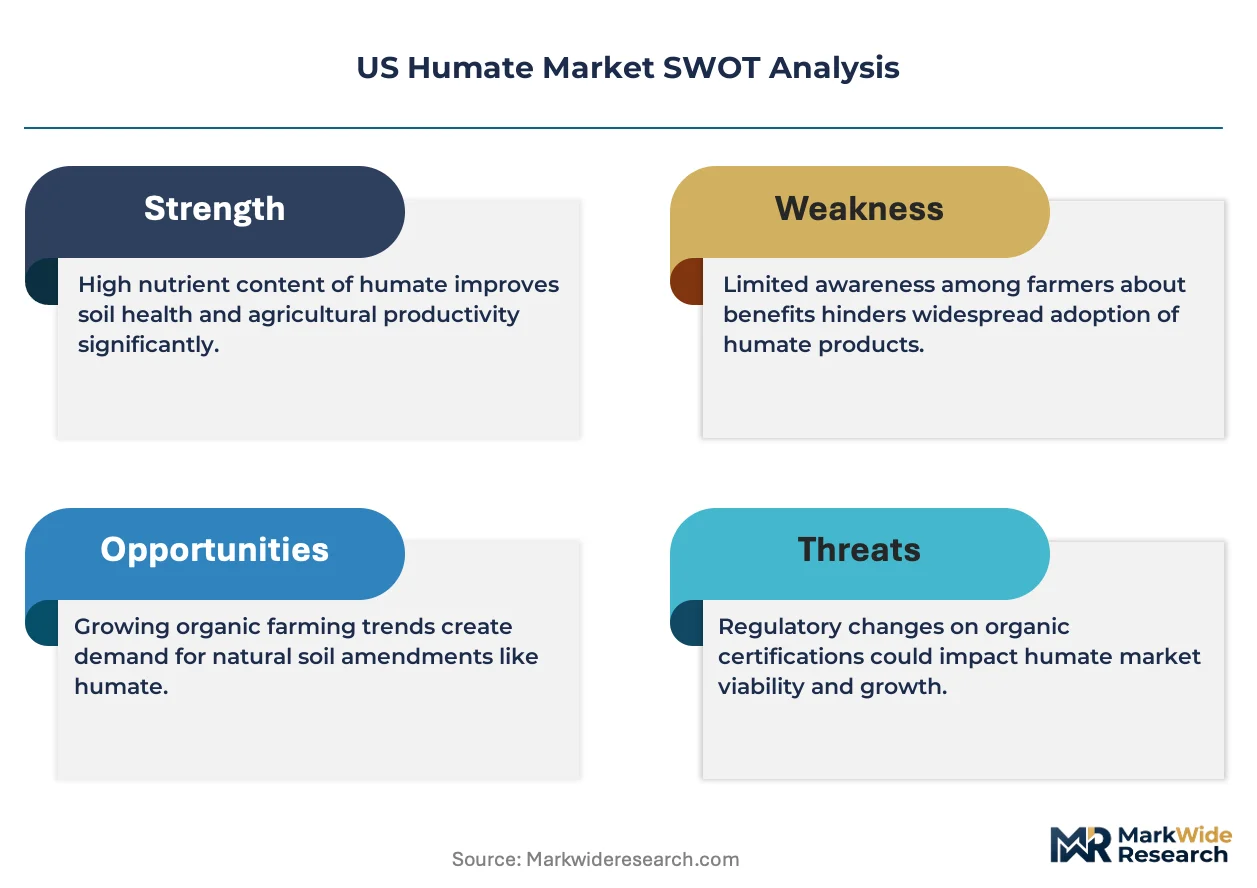
- Source Material Concentration:The reliance on leonardite, a finite resource mined from specific geologic deposits, creates potential supply chain vulnerabilities and price volatility tied to extraction costs and logistics.
- Product Inconsistency:Natural variations in the composition of raw humic substances present a technical hurdle for creating standardized products with predictable performance, complicating farmer adoption.
- Competition from Biosolids:Municipal and industrial biosolids, often available at a lower cost, compete as a soil amendment, particularly for non-food chain crops, constraining humate market penetration.
Strategic Opportunities
- Carbon Market Integration:Developing methodologies to quantify and verify the carbon sequestration benefits of humate application offers a pathway to participate in emerging agricultural carbon credit markets.
- Specialty Crop Penetration:Targeting high-value specialty crop markets in states like California and Florida with formulations tailored for horticulture and viticulture represents a significant growth vector.
- Enhanced NOP Certification:Expanding the portfolio of products certified under the USDA's National Organic Program can unlock premium pricing and access to a dedicated, high-growth agricultural segment.
Industry Challenges
- Agronomic Education Gap:Overcoming farmer skepticism and inertia requires significant investment in field trials, demonstration plots, and educational outreach to prove ROI against conventional synthetic inputs.
- Standardization and Efficacy Proof:Establishing industry-wide standards for measuring humic and fulvic acid content is a critical challenge for ensuring product quality and enabling reliable performance comparisons for buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Humate Market |
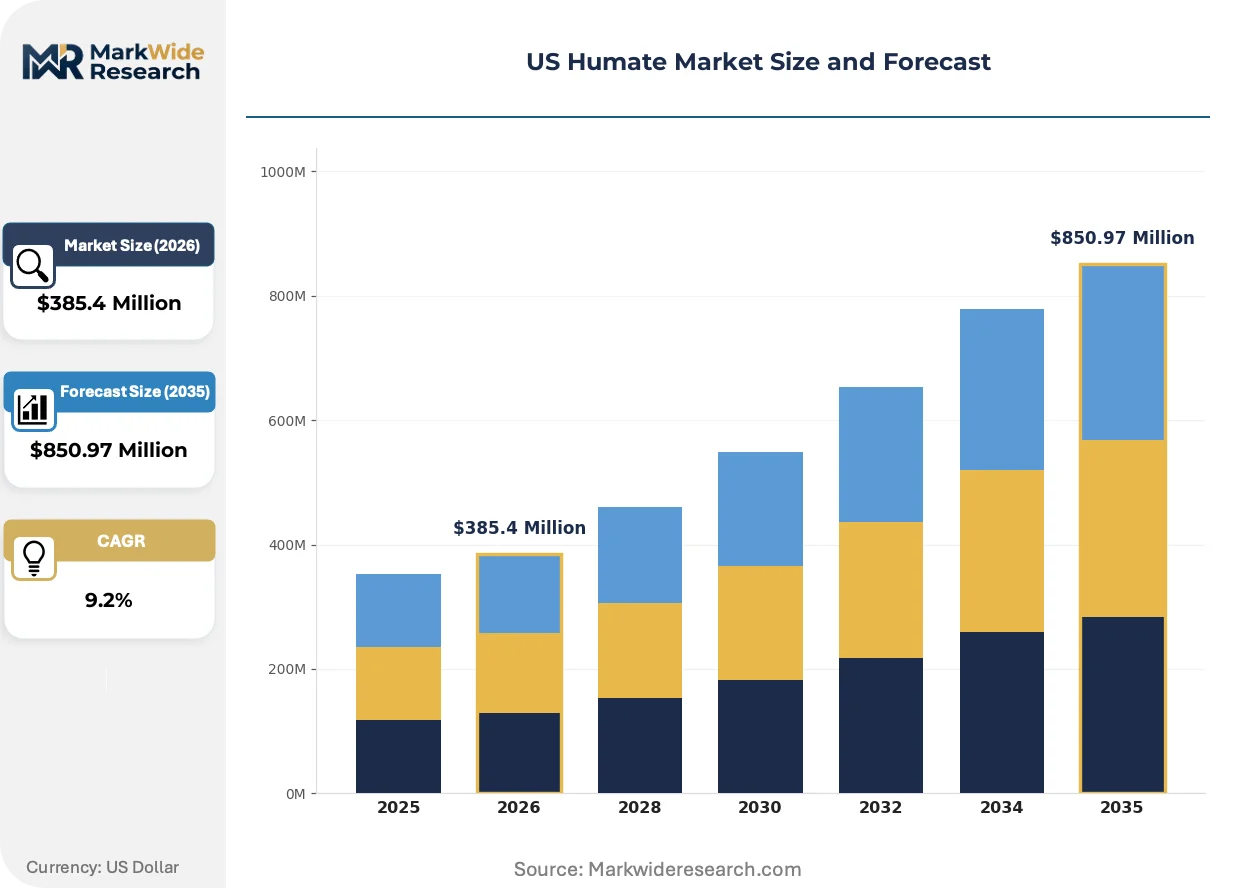
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $850.97 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potassium Humate, Sodium Humate, Ammonium Humate, Calcium Humate Application: Agriculture, Horticulture, Animal Feed, Water Treatment, Soil Remediation Form: Powder, Granules, Liquid Concentrate, Pellets End User: Crop Producers, Fertilizer Manufacturers, Feed Manufacturers, Environmental Agencies, Research Institutes |
| Companies Covered | Faust Bio-Agricultural Services, HGS BioScience Inc., Humic Growth Solutions, Humintech GmbH, Black Earth Humic LP, Actagro LLC, The Andersons Inc., Bio Huma Netics Inc., Italpollina USA Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Humate Market Strategic Shifts & Innovations
A fundamental shift is underway as humates transition from soil conditioners to precision tools for nutrient management. This evolution is driven by advanced formulation science and a new emphasis on verifiable performance metrics in US agriculture, aligning with both economic and environmental goals.
Advanced humate formulations combine humic substances with specific micronutrients. Large-scale agricultural producers adopt these complex products to improve nutrient uptake and plant resilience. This trend is decentralizing crop nutrition programs from bulk fertilizer application toward targeted, data-informed soil and foliar treatments.
The USDA's focus on climate-smart agriculture provides a powerful tailwind. This policy encourages practices that build soil carbon, directly benefiting products like humates. Suppliers serving the Midwest farm belt are most affected, reformulating R&D to align with quantifiable goals for water efficiency and carbon sequestration.
Farmer purchasing criteria are evolving beyond cost-per-gallon to focus on demonstrated improvements in crop yield. This shift favors suppliers providing robust field trial data over distributors competing on price. This behavior is most prominent in water-stressed regions like the Southwest and in high-input corn production zones.
US Humate Market Segmentation
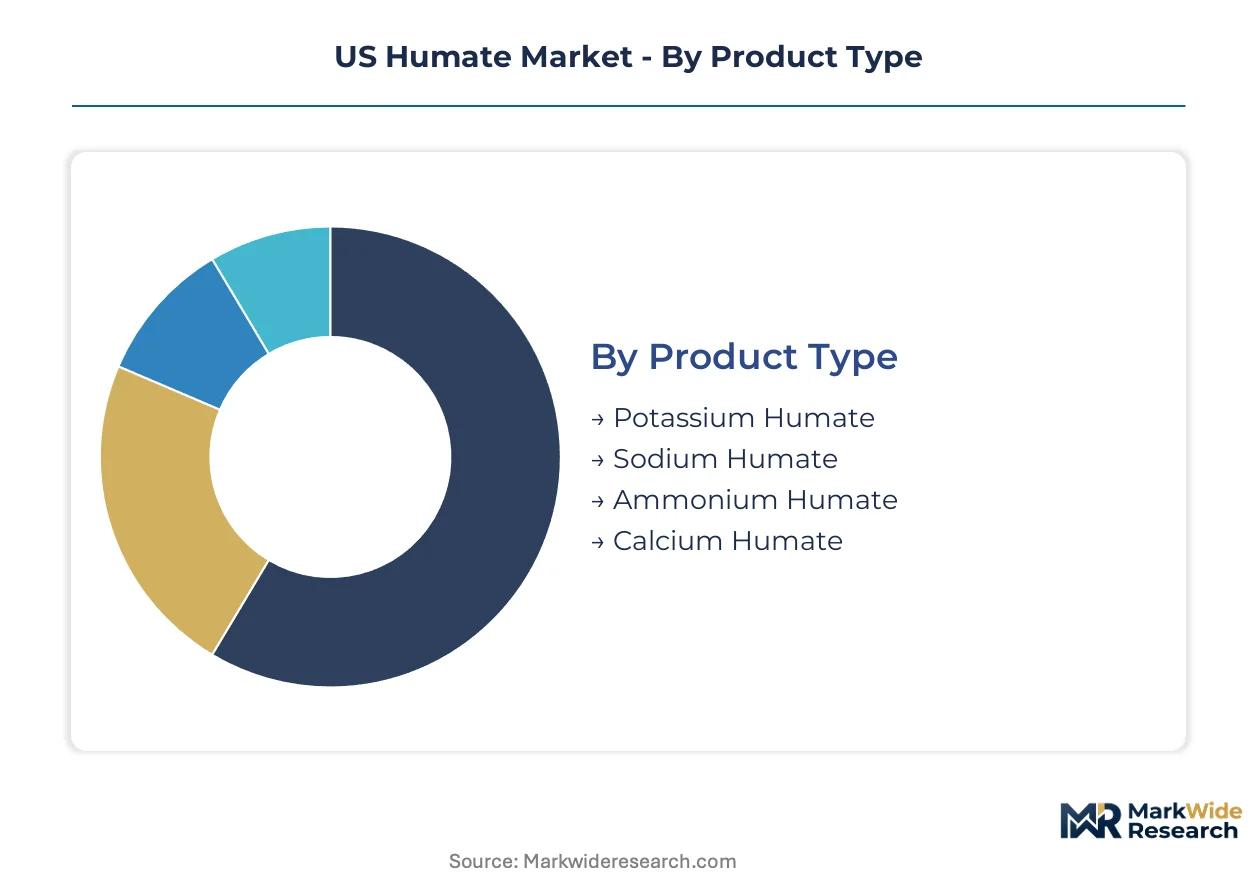
The US humate market demonstrates distinct segments driven by product composition, application versatility, physical form, and diverse end-user requirements. Understanding these segmentations provides critical insights into specific demand drivers and strategic opportunities for manufacturers and distributors.
Product Type:
Humate product types differentiate based on the specific cation bound to the humic acid, influencing solubility and plant availability for various agricultural and industrial uses.
- Potassium Humate:This highly soluble salt of humic acid is favored for its compatibility with most liquid fertilizers and ease of application in large-scale row crop production. Demand concentrates in the Midwest, where farmers integrate it into existing nutrient management programs for enhanced efficiency.
- Sodium Humate:Primarily used in animal feed supplements and some industrial applications, sodium humate offers good solubility and serves as a detoxifying agent in livestock diets.
- Ammonium Humate:Valued for its dual role as a humic substance and a source of plant-available nitrogen, ammonium humate is increasingly adopted in soil amendment programs. Its application is growing in regions focused on improving nutrient uptake and reducing synthetic fertilizer reliance.
- Calcium Humate:This product type is less soluble than potassium or sodium humates but provides both calcium and humic acid benefits, often used for soil conditioning in areas with calcium deficiencies.
Potassium Humate leads on scale; Ammonium Humate leads on momentum.
Application:
The utility of humate products extends across diverse sectors, driven by their inherent soil and biological conditioning properties and specific functional benefits.
- Agriculture:Humates are widely applied in large-scale farming to improve soil structure, enhance nutrient uptake, and increase water holding capacity, particularly for corn, soybean, and wheat cultivation. This application segment dominates demand across the US, especially in the Midwest.
- Horticulture:Used in specialty crops, nurseries, and greenhouses, humates boost plant vigor, root development, and transplant success in high-value ornamental and fruit production. This segment sees significant adoption in California and Florida for premium crop cultivation.
- Animal Feed:Humic substances are incorporated into animal feed formulations to improve nutrient absorption, support gut health, and bind mycotoxins in livestock and poultry.
- Water Treatment:Humates serve as natural chelating agents and flocculants in industrial and municipal water treatment processes, aiding in the removal of heavy metals and organic pollutants.
- Soil Remediation:In environmental applications, humates are deployed to stabilize heavy metals and organic contaminants in polluted soils, facilitating land recovery and ecological restoration.
Agricultural applications drive the largest volume, while horticulture presents significant value expansion.
Form:
Humate forms are tailored to optimize handling, storage, and application methods for different end-users and existing farm machinery.
- Powder:Powdered humates offer high concentration and can be easily dissolved for liquid applications or blended into dry formulations, requiring careful handling to prevent dust.
- Granules:Granular humates provide ease of uniform application with standard spreading equipment, reducing dust and improving flowability for large-scale agricultural operations. This form is particularly prevalent in the Midwest for broadacre field applications.
- Liquid Concentrate:Liquid concentrates offer convenience and precision for foliar sprays or fertigation systems, allowing for targeted nutrient delivery and integration into existing irrigation infrastructure. Demand for liquid concentrates is strong in regions like the Southwest due to water efficiency needs.
- Pellets:Pelleted humates are typically used for slow-release applications or in specific soil conditioning contexts, offering controlled dissolution and reduced dust.
Liquid Concentrate forms show significant growth, aligning with modern farm machinery.
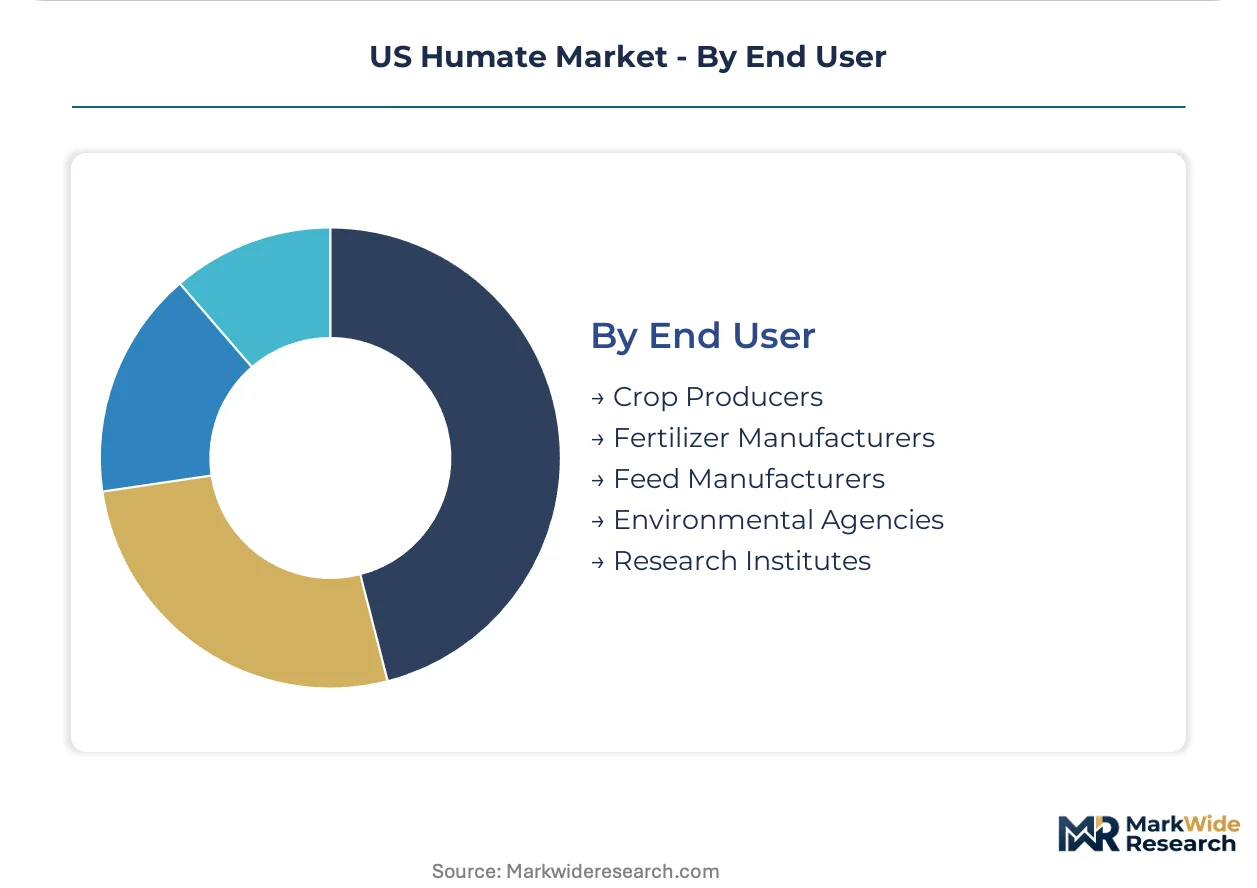
End User:
End-user segments reflect the diverse adoption points for humate products within the US agricultural and industrial ecosystem, each with unique purchasing criteria.
- Crop Producers:Direct consumers of humate products, crop producers apply these amendments to improve soil health, enhance crop yields, and meet sustainable agriculture mandates. This segment represents the largest direct market for humate suppliers.
- Fertilizer Manufacturers:These manufacturers integrate humates into blended fertilizers and specialty nutrient products, enhancing the efficacy and value proposition of their core offerings. This integration allows for broader market penetration through established distribution channels.
- Feed Manufacturers:Companies producing animal feed incorporate humic substances to formulate health-promoting and performance-enhancing supplements for livestock.
- Environmental Agencies:Government and private environmental organizations utilize humates for large-scale land reclamation, pollution control, and ecological restoration projects.
- Research Institutes:Academic and commercial research bodies use humates in studies focused on soil science, plant physiology, and environmental remediation, driving innovation in product development.
Crop Producers represent the core demand base, with Fertilizer Manufacturers integrating humates into broader product lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Midwest farm belt drives a substantial portion of US humate demand, primarily for large-scale row crop production. USDA incentives for climate-smart agriculture practices further elevate the role of humic substances across this region. These policies foster increased adoption of soil amendment products for improved soil health and carbon sequestration.
Midwest
Large-scale row crop production in the Midwest generates significant demand for humate products to enhance soil structure and nutrient uptake. USDA incentives for climate-smart agriculture directly encourage farmers in states like Iowa and Illinois to integrate humates. These products are crucial for improving soil carbon sequestration and water use efficiency in the Corn Belt.
California
California's high-value specialty crop markets, including horticulture and viticulture, drive demand for tailored humate formulations. State-level water conservation mandates and organic farming certifications influence product selection among growers. The Central Valley exemplifies the adoption of humates for boosting plant vigor and root development in fruit and vegetable cultivation.
Florida
Florida's extensive ornamental and fruit production sectors utilize humates to improve soil conditioning and transplant success. State environmental protection initiatives encourage the use of sustainable soil amendments to safeguard water quality. Southern Florida's nurseries and citrus groves frequently incorporate humic substances for enhanced plant resilience.
Southwest
Water scarcity concerns in the Southwest make humates valuable for their ability to improve soil water holding capacity in arid farming regions. EPA guidelines for soil amendments ensure product safety and environmental compliance for agricultural producers. Arizona and Texas agricultural zones increasingly adopt liquid humate concentrates for precision irrigation systems.
US Humate Market Key Industry Players
Global majors compete with regional champions across distribution networks and product specialization within the US humate market. The industry structure shows a mix of large-scale distributors and specialized technology providers. Strategic archetypes include companies focused on broad agricultural supply, those emphasizing proprietary formulations, and niche players targeting organic markets. Portfolio diversification and strategic partnerships represent dominant competitive moves among these entities.
Specialists in advanced soil and plant health solutions include Actagro LLC, which occupies a position through its scientifically formulated humic-based offerings. The Andersons Inc. exemplifies a large-scale distributor, leveraging its vast network to supply agricultural producers nationwide. Bio Huma Netics Inc. represents a technology-driven archetype, focusing on its proprietary Micro Carbon Technology to enhance nutrient efficiency across various crops. These companies collectively demonstrate the varied approaches to market penetration and value creation within the humate sector.
| Leading Market Players |
|---|
| Faust Bio-Agricultural Services |
| HGS BioScience Inc. |
| Humic Growth Solutions |
| Humintech GmbH |
| Black Earth Humic LP |
| Actagro LLC |
| The Andersons Inc. |
| Bio Huma Netics Inc. |
| Italpollina USA Inc. |
| Others |
Cost & Logistics Intelligence
USDA incentives for climate-smart agriculture practices are intensifying farmer demand for verifiable performance data, which forces humate suppliers to invest in advanced formulations and justify premium pricing.
Pricing Analysis
Raw material costs, particularly for leonardite extraction, directly influence humate product pricing. The market primarily operates on a per-unit transactional pricing model. Price differentiation stems from product solubility and NOP certification status. Pricing softness reflects competition from lower-cost biosolids. Large-scale row crop producers exhibit high price sensitivity, while specialty crop growers prioritize efficacy over cost.
Supply Chain Analysis
NOP certification requirements gate access to high-value organic markets, influencing humate supply chain configurations. Humate raw material supply concentrates in specific geologic deposits within the US, drawing from states like New Mexico and North Dakota. The industry relies on leonardite and specific processing chemicals. Single-source vulnerability for leonardite represents a structural supply chain risk. Distribution runs through large agricultural co-operatives and specialized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US humate market functions as a regulatory compounder, with USDA incentives for climate-smart agriculture practices driving increased adoption. This policy framework elevates humates from niche products to mainstream soil amendments.
For Market Incumbents: Hedge against product inconsistency by investing in advanced formulation R&D and quality control for raw humic substances. Incumbents should consolidate distribution channels to counter emerging competition from biosolids. Margin pressure from generic product offerings necessitates a focus on scientifically validated performance metrics. Expanding NOP certification for a broader product portfolio serves as a key lever.
For New Entrants and Emerging Players: Proprietary Micro Carbon Technology offers a technology-first wedge for new entrants to penetrate high-value specialty crop markets. Targeting horticulture and viticulture in California provides a penetrable segment for premium formulations. Focus on demonstrating quantifiable improvements in nutrient efficiency and water use. A direct-to-farm educational outreach model can build trust and accelerate adoption.
For Investors and Strategic Acquirers: Asymmetric upside sits with technology-driven specialists possessing strong intellectual property in humate formulation science. The market demonstrates long-term viability, driven by sustained agricultural policy support for soil health over the next decade. Acquisition targets should be mid-cap companies with robust field trial data and established distribution networks in the Midwest. The signal to watch is the expansion of carbon credit markets for agricultural practices.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Formulation R&D | Drives product differentiation and addresses inconsistency challenges for humate suppliers. |
| Carbon Credit Methodology Development | Unlocks new revenue streams by quantifying and verifying humate-driven carbon sequestration. |
| Distribution Network Expansion | Increases market penetration, particularly for large-scale row crop producers in the Midwest. |
| NOP Certification Portfolio Growth | Accesses premium pricing and expands reach within the high-value organic farming segment. |
| Field Trial and Demonstration Programs | Overcomes farmer skepticism by providing verifiable ROI against conventional agricultural inputs. |
Research Approach
Coverage spans the US, with primary inputs from each key agricultural region including the Midwest, California, and the Southwest. This involved combining primary interviews with industry stakeholders, including farm managers, fertilizer manufacturers, and agricultural chemical distributors, with secondary validation. Secondary sources included USDA reports, EPA guidelines, and company financial filings. Bottom-up data aggregation and top-down market sizing triangulated the findings.
Rate-of-change decomposition informed the forecast framework, projecting market evolution across the analysis window. The model segmented by product type, application, physical form, and end-user, alongside regional agricultural output. Compound annual growth rates were derived from historical data trends and projected policy impacts. Key inputs included USDA climate-smart agriculture program budgets and crop acreage forecasts.
The model holds under current agricultural policy and raw material availability; deviation in federal farm bill provisions or leonardite extraction costs would shift projections. Forecasts reflect assumptions regarding farmer adoption rates and technological advancements in humate formulations. A model refresh is warranted upon material change in USDA incentive structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
North America Cycloalkanes Market
Organic Chemicals
1,3-Dichloroacetone Market
Organic Chemicals
Chloroethylene Market
Organic Chemicals
Cyclohexanone Market
Organic Chemicals
Alanine Market
Organic Chemicals
North America Biphenyl Market
Organic Chemicals
Acrylonitrile Market
Organic Chemicals
Chloroacetyl Chloride Market
Organic Chemicals
Acetaldehyde Market
Organic Chemicals
Organocatalyst Market
Organic Chemicals
Chlorocyclopentane Market
Organic Chemicals
Dioxolane Market
Organic Chemicals
Triethylene Glycol Market
Organic Chemicals
DMDM Hydantoin Market
Organic Chemicals
Gamma-Butyrolactone (GBL) Market
Organic Chemicals
Acetylacetone Market