
 Cyclopentanone Market | 2026-2036
Cyclopentanone Market Size, Share, and Industry Trends Forecast 2026-2036
Cyclopentanone Market Analysis
Pharmaceutical intermediate demand is expanding faster than conventional solvent applications, redrawing the end-use vertical mix for cyclopentanone suppliers. BASF leverages its integrated aromatics and ketone chemistry platforms to serve European pharmaceutical contract manufacturers. Zhejiang NHU Co., Ltd. anchors Asia-Pacific supply through captive adipic acid derivative capacity and backward integration into cyclopentane feedstock. Solvay S.A. differentiates via specialty-grade purification protocols that meet FDA and EMA impurity thresholds for drug-substance intermediates.
Cyclopentanone is a cyclic ketone with formula C5H8O, boiling point 130.6°C, manufactured primarily through adipic acid pyrolysis or cyclopentane oxidation, serving as a versatile building block for pharmaceuticals, agrochemicals, and fragrance molecules. Pharmaceutical-grade cyclopentanone commands the strongest margin pool due to stringent residual solvent limits under ICH Q3C and USP <467> guidelines. Industrial-grade supply dominates volume throughput but faces compression as chemical manufacturing customers migrate toward higher-purity specifications for downstream regulatory compliance.
EPA hazardous air pollutant standards and REACH Annex XVII restrictions on volatile organic compounds are tightening permissible emission profiles for cyclopentanone handling and storage facilities. FDA Current Good Manufacturing Practice inspections for active pharmaceutical ingredient starting materials extend regulatory reach upstream to ketone intermediate producers. Stakeholders must monitor evolving solvent substitution dynamics as bio-based pentanone alternatives advance through pilot-scale validation.
Market Dynamics
Pharmaceutical-grade purity specifications are compressing industrial-grade margins as ICH Q3C residual solvent limits propagate upstream through ketone supply chains, forcing adipic acid pyrolysis operators to retool for impurity control.
Growth Catalysts
- API synthesis expansion:Drug developers in China and India are scaling cyclopentanone procurement for antiviral and cardiovascular intermediate production, tightening regional supply-demand balances.
- REACH Annex XVII VOC restrictions:Tighter emission thresholds for volatile organic compounds in Europe are disqualifying conventional solvents and redirecting formulation demand toward cyclopentanone's favorable toxicological profile.
- Adipic acid derivative integration:Backward integration into cyclopentane feedstock by major Asian chemical conglomerates is securing cost-competitive ketone output for export markets.
Market Restraints
- Crude oil-adipic acid price linkage:Cyclopentanone production economics remain tethered to naphtha-derived adipic acid volatility, compressing margin visibility for non-integrated producers.
- China supply concentration:Over sixty percent of merchant-grade capacity sits with three domestic chemical groups, creating geographic risk exposure for European and North American formulators.
- Bio-based pentanone substitution:Fermentation-derived C5 ketone alternatives from lignocellulosic feedstocks are advancing through pilot validation, threatening long-term petrochemical ketone positioning.
Strategic Opportunities
- Indian pharmaceutical contract manufacturing:CDMO expansion under India's PLI scheme for active pharmaceutical ingredients is opening dedicated cyclopentanone supply contracts with purity guarantees.
- Fragrance molecule diversification:High-value jasmine lactone and civetone synthesis from cyclopentanone precursors is expanding addressable market beyond pharmaceutical intermediates.
- EPA hazardous air pollutant compliance services:Technical advisory and emission-control equipment bundling with ketone supply creates defensible positioning against commodity competitors.
Industry Challenges
- Analytical chemistry talent scarcity:Gas chromatography-mass spectrometry specialists capable of validating residual solvent profiles to USP <467> thresholds command premium compensation and extended recruitment cycles.
- Multi-jurisdiction certification timelines:Simultaneous FDA, EMA, and NMPA starting material qualification requires eighteen-to-twenty-four month documentation cycles, delaying revenue recognition for new production assets.
- Legacy batch reactor retrofit costs:Continuous flow adipic acid pyrolysis systems demand capital outlays that strain mid-scale producers' balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyclopentanone Market |
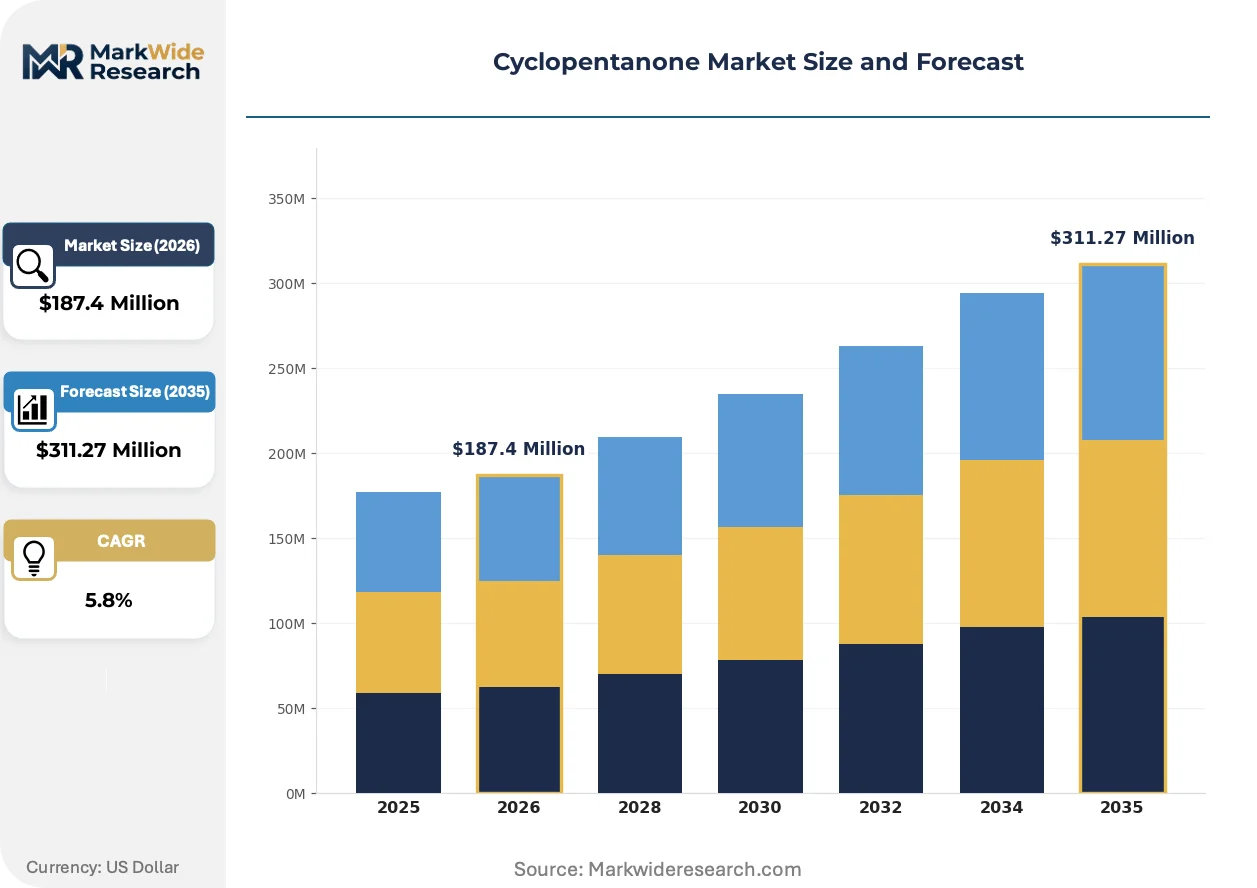
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthesis Grade, Analytical Grade, Industrial Grade, Pharmaceutical Grade End User: Chemical Manufacturing, Pharmaceuticals, Agriculture, Cosmetic Industry Application: Solvent, Intermediate, Flavoring Agent, Fragrance Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Caffaro Industrie S.p.A., JUNSEI CHEMICAL CO., LTD., Solvay S.A., Matrix Fine Chemicals GmbH, Shanghai Pearlk Chemical Co., Ltd., BASF, Zhejiang NHU Co., Ltd., Kanto Chemical Co., Inc., Zeon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyclopentanone Market Emerging Trajectories
Continuous manufacturing protocols and bio-based feedstock validation are rewriting process economics for cyclic ketone production, while regulatory harmonization pressures are compressing regional quality variance.
Membrane-based purification is consolidating quality differentiation between pharmaceutical and industrial cyclopentanone grades. Nanofiltration and pervaporation systems installed by European and Japanese producers are achieving residual impurity levels below ten parts per million without energy-intensive distillation sequences. Specialty chemical divisions at major aromatics houses are adopting these units to defend margin pools against commodity importers.
EPA Method 8260D volatile organic compound monitoring requirements are extending to ketone storage and handling facilities across the United States. Revised hazardous air pollutant thresholds mandate vapor recovery systems and leak detection repairs at loading terminals, adding operational complexity for distributors serving pharmaceutical manufacturing clusters in New Jersey and Puerto Rico.
Formulators are consolidating purchase volumes through qualified supplier programs rather than spot-market procurement. Large pharmaceutical manufacturers in Germany and Switzerland are reducing approved vendor lists to three cyclopentanone sources per region, demanding dedicated inventory buffers and audit transparency in exchange for multi-year contracts. This concentration pattern favors integrated producers with captive feedstock positions over merchant traders.
Cyclopentanone Market Segmentation
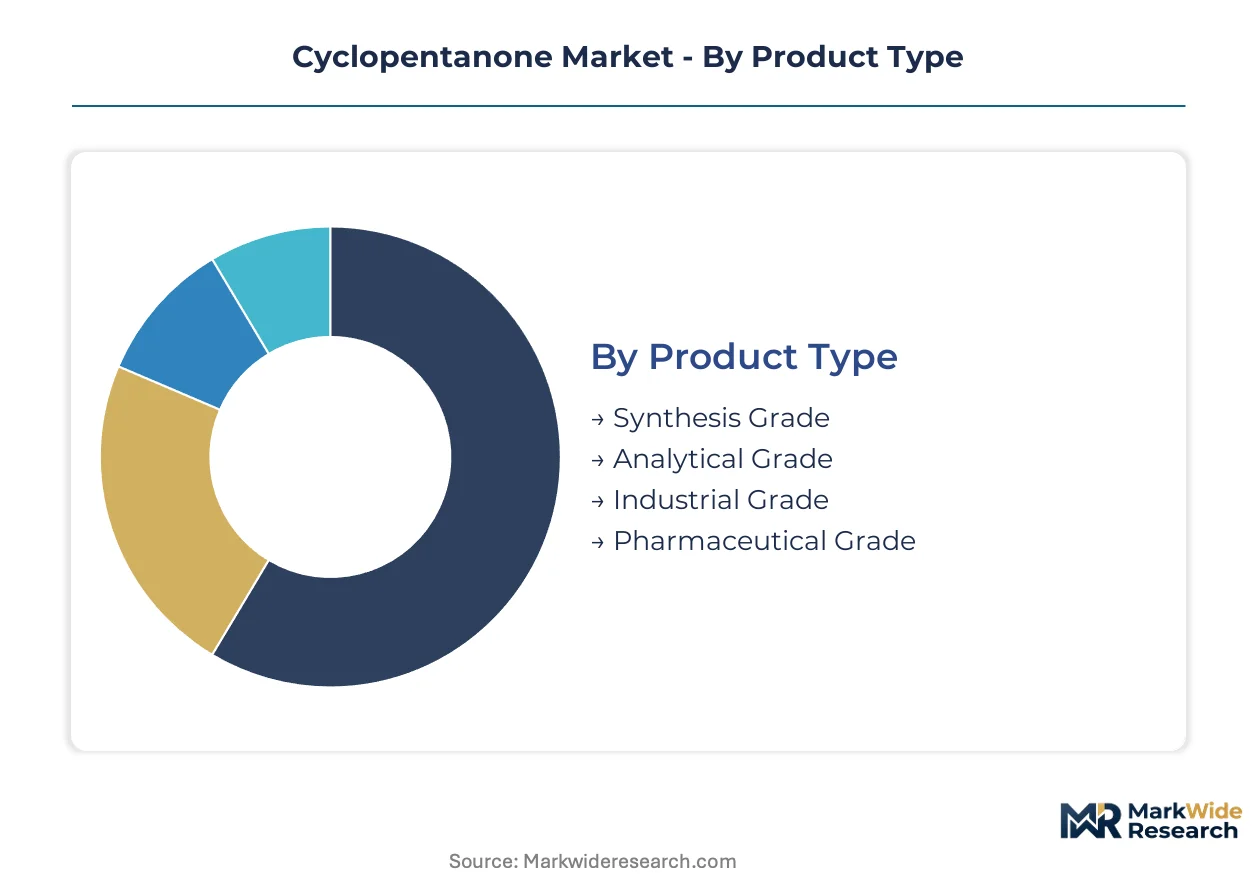
Cyclopentanone suppliers face divergent margin structures across purity tiers and end-use verticals. Pharmaceutical-grade specifications command premium positioning while industrial-grade volumes anchor capacity utilization.
Product Type:
Supply concentration in pharmaceutical-grade output is tightening as adipic acid pyrolysis operators retool for impurity control under ICH Q3C propagation.
- Pharmaceutical Grade:Residual solvent specifications under USP <467> and ICH Q3C mandate gas chromatography-mass spectrometry validation to ten parts per million thresholds. Demand concentrates in Swiss and German API contract manufacturers seeking multi-year qualified supplier contracts with dedicated inventory buffers.
- Industrial Grade:Standard purity specifications serve chemical manufacturing and agrochemical formulation with less stringent analytical overhead. Chinese domestic chemical groups dominate merchant capacity, creating geographic risk exposure for European and North American formulators.
- Synthesis Grade:Moderate purity tier for research-scale organic synthesis and academic procurement.
- Analytical Grade:Reference standard specifications for chromatographic calibration and quality control laboratories.
Industrial grade absorbs the bulk of installed capacity; pharmaceutical grade is expanding most quickly.
End User:
Application-driven cost tiers separate commodity chemical buyers from regulated pharmaceutical procurement with divergent qualification timelines.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and intermediate production drive the highest purity requirements. CDMO expansion under India's PLI scheme is opening dedicated supply contracts with eighteen-to-twenty-four month documentation cycles for FDA, EMA, and NMPA starting material qualification.
- Chemical Manufacturing:Solvent applications and downstream ketone derivative production constitute volume demand. EPA hazardous air pollutant standards and REACH Annex XVII VOC restrictions are redirecting formulation demand toward cyclopentanone's favorable toxicological profile.
- Agriculture:Agrochemical intermediate synthesis for pesticide and herbicide active ingredients.
- Cosmetic Industry:Fragrance precursor applications including jasmine lactone and civetone synthesis.
Chemical manufacturing anchors current volume throughput; pharmaceuticals climbs the fastest on regulatory tailwinds.
Application:
Customer type concentration favors direct procurement relationships over spot-market engagement for regulated applications.
- Intermediate:Building block function for antiviral, cardiovascular, and CNS drug synthesis with strict impurity profiling. Drug developers in China and India are scaling procurement, tightening regional supply-demand balances.
- Solvent:Dissolution and reaction medium applications across organic synthesis with emission-control compliance requirements. EPA Method 8260D monitoring extends to storage facilities in New Jersey and Puerto Rico pharmaceutical clusters.
- Fragrance:High-value specialty molecule synthesis from cyclopentanone precursors.
- Flavoring Agent:Food-grade applications with FEMA GRAS specifications.
Intermediate applications command priority capacity allocation; fragrance synthesis gains share fastest on premium pricing.
Distribution Channel:
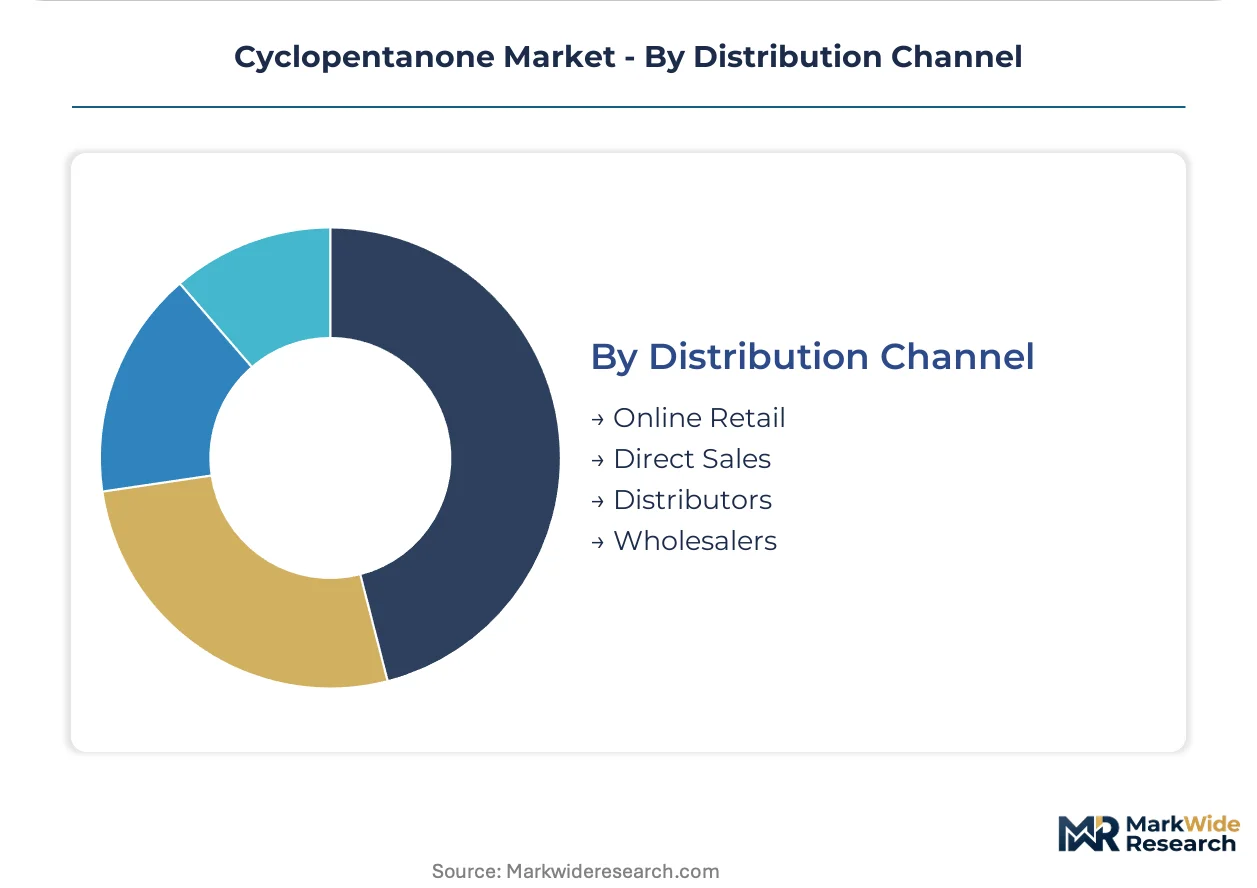
Volume scale separates bulk direct procurement from fragmented spot-market transactions with divergent service requirements.
- Direct Sales:Multi-year contracts with integrated inventory buffers and audit transparency for qualified supplier programs. Large pharmaceutical manufacturers in Germany and Switzerland are reducing approved vendor lists to three sources per region.
- Distributors:Regional stocking and technical advisory bundling for mid-scale chemical manufacturers. Vapor recovery system mandates under revised EPA hazardous air pollutant thresholds add operational complexity at loading terminals.
- Online Retail:Research-scale and academic procurement with credit-card transaction efficiency.
- Wholesalers:Commodity-grade volume aggregation for industrial solvent applications.
Direct sales captures the majority of pharmaceutical-grade revenue; distributor relationships deepen fastest on compliance service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical parks in Zhejiang and Jiangsu provinces drive cyclopentanone production concentration through integrated adipic acid derivative complexes and preferential tax treatment for pharmaceutical intermediate exports.
China
Domestic chemical manufacturers scale pharmaceutical intermediate production for antiviral and cardiovascular API synthesis under NMPA starting material guidelines. The country's dual carbon goals tighten emission controls at cyclopentane oxidation facilities in the Yangtze River Delta. Zhejiang NHU anchors supply through captive feedstock integration at its Xinchang production base.
United States
Pharmaceutical contract manufacturers in New Jersey and Puerto Rico tighten cyclopentanone procurement under FDA Current Good Manufacturing Practice inspections for API starting materials. EPA Method 8260D volatile organic compound monitoring extends to ketone storage terminals serving the Northeast pharmaceutical corridor. Vapor recovery system mandates add operational complexity at loading facilities in the New Jersey chemical cluster.
Germany
Swiss and German API manufacturers reduce approved vendor lists to three cyclopentanone sources per region under REACH Annex XVII volatile organic compound restrictions. BASF leverages integrated aromatics platforms to serve European pharmaceutical contract manufacturers from its Ludwigshafen complex. The EMA impurity threshold propagation through ketone supply chains compresses industrial-grade margin pools.
India
CDMO expansion under the PLI scheme for active pharmaceutical ingredients opens dedicated cyclopentanone supply contracts with eighteen-to-twenty-four month documentation cycles. CDSCO starting material qualification timelines delay revenue recognition for new ketone production assets. Hyderabad and Ahmedabad pharmaceutical clusters drive regional demand concentration for high-purity grades.
Japan
Membrane-based purification adopters achieve residual impurity levels below ten parts per million through nanofiltration systems at pharmaceutical-grade facilities. METI chemical manufacturing standards propagate stringent analytical validation requirements downstream to ketone intermediate producers. The Kanto region's specialty chemical divisions defend margin pools against commodity importers through pervaporation technology deployment.
Cyclopentanone Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated aromatics houses commanding pharmaceutical-grade premiums and merchant traders absorbing industrial-volume compression. The vendor base stratifies into three tiers: captive adipic acid derivative producers with backward feedstock control, specialty-grade purification operators with FDA and EMA qualification capabilities, and regional distributors bundling compliance services. Dominant competitive moves include capacity expansion at Asian chemical parks and strategic partnerships linking European pharmaceutical manufacturers to qualified Asian suppliers.
Within the integrated producer tier, Zhejiang NHU Co., Ltd. and BASF exemplify divergent geographic anchoring strategies—Chinese captive feedstock integration versus European aromatics platform leverage. Solvay S.A. occupies a position representing specialty-grade purification archetypes, with S.p.A. and GmbH suffixes indicating Italian and German structural forms among European participants. Shanghai Pearlk Chemical Co., Ltd. and Kanto Chemical Co., Inc. represent Asia-Pacific merchant distribution models, while JUNSEI CHEMICAL CO., LTD. and Zeon Corporation exemplify Japanese precision chemical positioning. Matrix Fine Chemicals GmbH anchors Central European fine chemical specialization.
| Leading Market Players |
|---|
| Caffaro Industrie S.p.A. |
| JUNSEI CHEMICAL CO., LTD. |
| Solvay S.A. |
| Matrix Fine Chemicals GmbH |
| Shanghai Pearlk Chemical Co., Ltd. |
| BASF |
| Zhejiang NHU Co., Ltd. |
| Kanto Chemical Co., Inc. |
| Zeon Corporation |
| Others |
Supply Flow & Price Mechanics
Gas chromatography-mass spectrometry specialists in the Yangtze River Delta command premium compensation that widens spreads between pharmaceutical and industrial cyclopentanone tiers. Labor-cost differentials between analytical-chemistry hubs in China and commodity chemical regions compress margins for non-integrated producers while sustaining premium capture at FDA-qualified facilities.
Pricing Analysis
Short lead-time premiums distinguish qualified supplier contracts from spot-market transactions in cyclopentanone procurement. Contract-based long-term offtake dominates pharmaceutical-grade supply, with price differentiation resting on USP <467> certification tier and dedicated inventory buffers. Cost compression in industrial-grade supply is intensifying because Chinese domestic chemical groups scale merchant capacity. Large pharmaceutical manufacturers in Germany exhibit lowest price sensitivity; mid-scale chemical manufacturers in spot markets show highest elasticity.
Supply Chain Analysis
Direct-to-API-manufacturer channels handle qualified pharmaceutical demand while distributor networks serve industrial solvent buyers. Supply concentrates in China, Germany, and India for pharmaceutical-grade output; industrial-grade merchant capacity clusters in Zhejiang and Jiangsu provinces. Raw material dependencies center on naphtha-derived adipic acid, cyclopentane feedstock, and specialized membrane purification equipment. Single-source vulnerability from three Chinese chemical groups controlling sixty percent of merchant-grade capacity exposes European and North American formulators. Distribution runs through regional stocking points with vapor recovery system mandates at New Jersey and Puerto Rico loading terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cyclopentanone production is transitioning from batch adipic acid pyrolysis to continuous flow systems and membrane-based purification, displacing legacy energy-intensive distillation sequences. This technology shift rewrites capital deployment priorities and qualification timelines across the supplier base.
For Market Incumbents: Acquire continuous flow reactor assets and membrane purification units to defend pharmaceutical-grade margin pools against commodity importers. Backward integration into cyclopentane feedstock secures cost visibility as naphtha volatility compresses non-integrated producers. Investment in FDA and EMA starting material documentation capabilities extends competitive moats beyond eighteen-month qualification cycles. For New Entrants and Emerging Players: Indian pharmaceutical contract manufacturing organizations under the PLI scheme represent an underserved buyer archetype seeking dedicated supply contracts with purity guarantees. Fragrance molecule synthesis for jasmine lactone and civetone production offers penetrable white-space beyond pharmaceutical intermediates. Technical advisory bundling with emission-control compliance services creates differentiated positioning against commodity distributors. For Investors and Strategic Acquirers: Re-rating potential sits with specialty-grade purification operators given EMA impurity threshold propagation through ketone supply chains. Five-to-ten year viability favors FDA and NMPA-qualified producers with captive feedstock positions over merchant traders. Monitor bio-based pentanone pilot-scale validation progress as inflection indicator for long-term petrochemical ketone displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cyclopentane Feedstock | Zhejiang NHU anchors supply security through captive production at Xinchang. |
| Membrane Purification Technology Deployment | Solvay achieves sub-ten ppm impurity levels without energy-intensive distillation. |
| Continuous Flow Reactor Conversion | European producers reduce batch-to-batch variance under ICH Q3C propagation. |
| Multi-Jurisdiction Qualification Investment | BASF leverages Ludwigshafen aromatics platforms for simultaneous FDA and EMA compliance. |
| Compliance Service Bundling | Distributors add EPA Method 8260D advisory to defend against commodity competitors. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this cyclopentanone market assessment. Primary interviews with plant managers at adipic acid pyrolysis facilities, procurement leads at pharmaceutical CDMOs, distribution channel partners, and technical R&D directors at specialty chemical divisions combined with secondary validation from FDA 483 inspection observations, EMA starting material guidelines, NMPA pharmaceutical intermediate regulations, and Cefic solvent market reports. Bottom-up capacity modeling and top-down demand estimation triangulated volume and value outputs.
Segment-level modeling disaggregated pharmaceutical-grade, industrial-grade, synthesis-grade, and analytical-grade tiers across end-use verticals including API synthesis, chemical manufacturing, agrochemicals, and fragrance production. Regional production clusters in China, the United States, Germany, India, and Japan were modeled separately with grade-specific demand elasticities. CAGRs were derived from regression analysis against pharmaceutical intermediate procurement trends and regulatory compliance investment cycles. Forecast inputs included adipic acid price volatility indices, CDSCO and NMPA qualification pipeline data, and EPA hazardous air pollutant enforcement patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to bio-based pentanone substitution advances, REACH Annex XVII VOC restriction tightening, and China dual carbon policy implementation at cyclopentane oxidation facilities. Forecasts reflect assumptions regarding sustained pharmaceutical-grade premium capture and continuous manufacturing adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
2-Methylbutanoic Acid Market
Organic Chemicals
Dioctyl Maleate (DOM) Market
Organic Chemicals
North America Cycloalkanes Market
Organic Chemicals
North America Biphenyl Market
Organic Chemicals
Aliphatic Amines Market
Organic Chemicals
Acetaldehyde Market
Organic Chemicals
Gamma-Butyrolactone (GBL) Market
Organic Chemicals
4-Tert-Amylphenol Market
Organic Chemicals
Chloroacetyl Chloride Market
Organic Chemicals
Global Benzoic Acid Market
Organic Chemicals
Oryzenin Market
Organic Chemicals
N-Hexanol Market
Organic Chemicals
Pyridine Derivatives Market
Organic Chemicals
Humic Acid Market
Organic Chemicals
Aminophenol Market
Organic Chemicals
Global Pseudocumene Market