
 Organic Matting Agent Market | 2026-2036
Organic Matting Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Matting Agent Market Outlook
Modular additive packages is broadening buyer choice across coating formulators seeking tailored gloss control without full system overhauls. Evonik Industries leverages its silica technology leadership to anchor premium matting solutions for automotive clearcoats. Wacker Chemie AG sustains competitive positioning through silicone-based organic matting agents that differentiate on thermal stability. PPG Industries controls integrated supply advantages by combining resin and additive expertise in-house.
An organic matting agent is a finely dispersed particulate or wax-based additive, typically composed of precipitated silica, micronized polyolefin wax, or modified biopolymer matrices, that scatters incident light at coating surfaces to reduce specular reflection and produce uniform low-gloss finishes. These agents function by creating micro-roughness at the film-air interface, with particle sizes generally ranging from 2 to 15 micrometers and oil absorption values dictating compatibility with waterborne, solventborne, and UV-curable systems. Silica dominates product type volumes due to its established performance in industrial wood and coil coatings, though wax-based alternatives are gaining traction in plastics where surface feel and scratch resistance carry premium value. Coatings application leads absolute consumption, while inks represent a concentrated margin pool driven by narrow specification tolerances in food-contact packaging.
REACH registration requirements and ECHA substance evaluation protocols constrain raw material selection for European formulators, pushing investment toward bio-based and recycled-content matting technologies. EPA VOC emission standards under 40 CFR 59 shape product development priorities for US architectural and industrial coating producers, particularly in California where CARB SCM 2007 limits drive waterborne system conversion. China's MEE environmental inspections and GB standards for industrial coatings are tightening particulate emission controls at manufacturing facilities. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation investments and ensure cross-border product registration compliance.
Market Dynamics
Automotive OEMs are aggressively expanding matte-finish interior applications, forcing coating formulators to reconfigure additive packages around bio-based silica alternatives that satisfy REACH and EU Green Deal compliance without sacrificing optical performance.
Growth Catalysts
- REACH substance evaluation protocols:ECHA's tightening registration requirements redirect European formulator investment toward precipitated silica and modified biopolymer matrices with verified eco-toxicology profiles.
- Automotive interior matte finishes:OEM design studios in Germany and the US are specifying low-gloss clearcoats for dashboard and trim applications, concentrating demand among tier-one coating suppliers.
- Waterborne system conversion:CARB SCM 2007 limits in California and parallel EPA VOC standards under 40 CFR 59 are accelerating solventborne displacement by compatible organic matting agents with low oil absorption values.
Market Restraints
- Precipitated silica supply concentration:Production of high-purity silica for premium matting applications clusters among a limited set of European and Asian chemical specialists, creating input vulnerability.
- Wax-based alternative performance ceiling:Micronized polyolefin waxes face thermal stability limitations above 120°C, constraining deployment in automotive under-hood and coil coating segments.
- Cross-border registration friction:Divergent substance notification requirements between EPA, ECHA, and China's MEE force redundant toxicology testing and extend product launch timelines.
Strategic Opportunities
- India industrial coatings expansion:BIS certification mandates and DGFT import substitution policies create opening for domestic formulation of bio-based matting agents serving wood and plastics processors.
- UV-curable inkjet integration:Narrow specification tolerances in food-contact packaging are absorbing modified biopolymer matrices that scatter light without compromising cure speed or adhesion.
- Recycled-content silica recovery:EU Green Deal circular economy incentives and EMAS environmental management standards reward post-industrial silica reclamation from coating manufacturing waste streams.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in particle size distribution optimization for waterborne-solventborne-UV system compatibility remains concentrated among retiring technical service professionals.
- Legacy coating line retrofit costs:Integrating low-gloss additive packages into established automotive OEM supply contracts requires capital-intensive dispersion equipment upgrades and revalidated process parameters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Matting Agent Market |
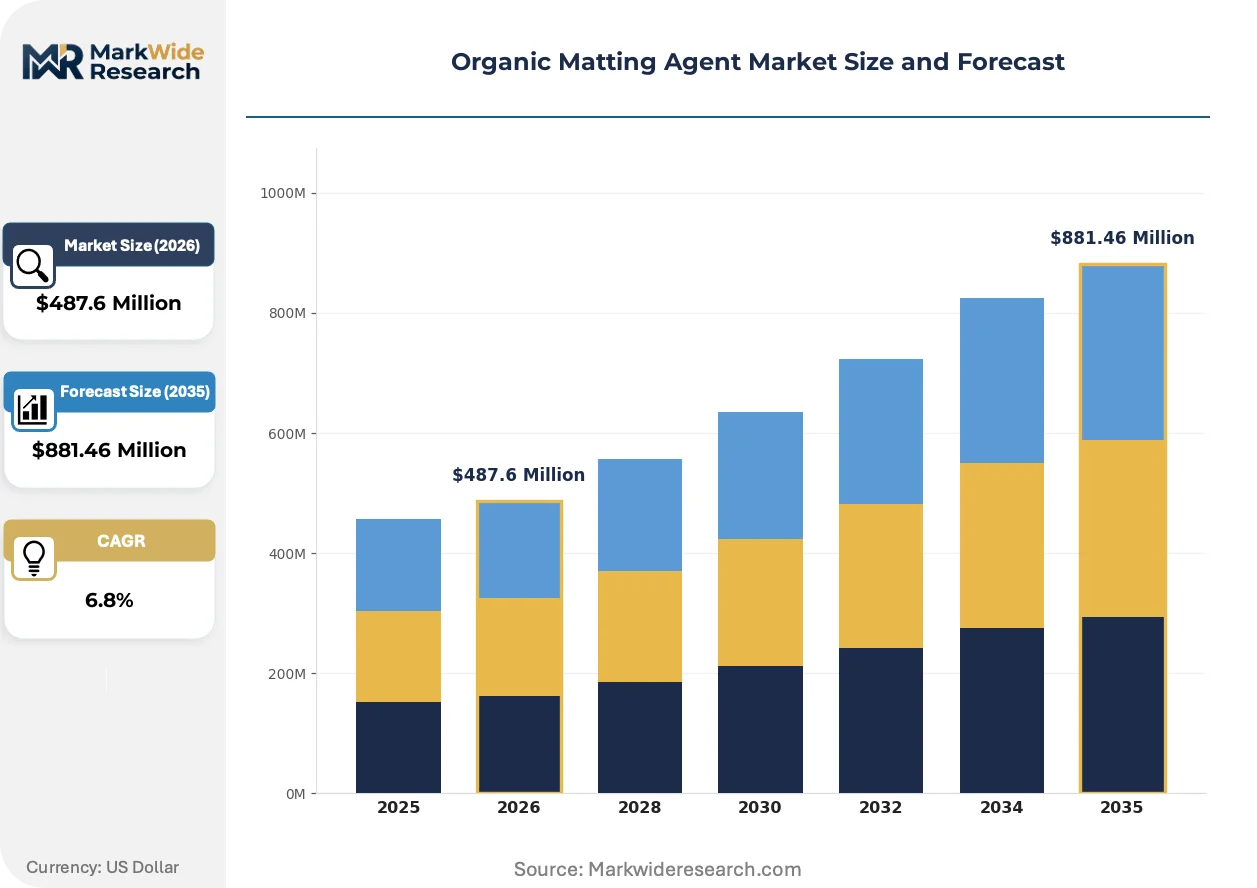
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica, Talc, Barytes, Others Application: Coatings, Inks, Plastics, Adhesives End User: Automotive, Construction, Packaging, Household Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Evonik Industries, Wacker Chemie AG, PPG Industries, Baltimore Innovations, W. R. Grace & Co.-Conn., Imerys, PQ Corporation, Huber Engineered Materials, Huntsman International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Matting Agent Market Strategic Shifts
Coating chemistry is pivoting toward modular additive architectures that decouple gloss control from base resin systems, enabling faster formulation iteration without full reformulation cycles.
Modified biopolymer matrices derived from cellulose and chitin sources are absorbing market attention as precipitated silica alternatives. Automotive interior trim suppliers in Germany and Japan are piloting these materials for dashboard applications where surface feel and scratch resistance carry premium value. The technology is absorbing R&D investment from formulators seeking to preempt REACH authorization bottlenecks for conventional silica grades.
EU Green Deal carbon border adjustment mechanisms and F-Gas Regulation phase-down schedules are redirecting coating facility investment toward low-emission manufacturing. Industrial wood and coil coating producers face compressed compliance timelines for demonstrating recycled-content verification across additive supply chains. German automotive coating clusters are responding fastest, integrating EMAS-certified silica recovery into captive additive production.
Specification-driven procurement is consolidating buyer power among multinational coating formulators with in-house dispersion capabilities. Regional distributors serving mid-tier plastics processors are losing share to direct technical service relationships with Evonik and Wacker Chemie AG specialists. This pattern concentrates most visibly in Bavaria's automotive supply corridor, where OEMs mandate single-source additive qualification for matte-finish interior programs.
Organic Matting Agent Market Segmentation
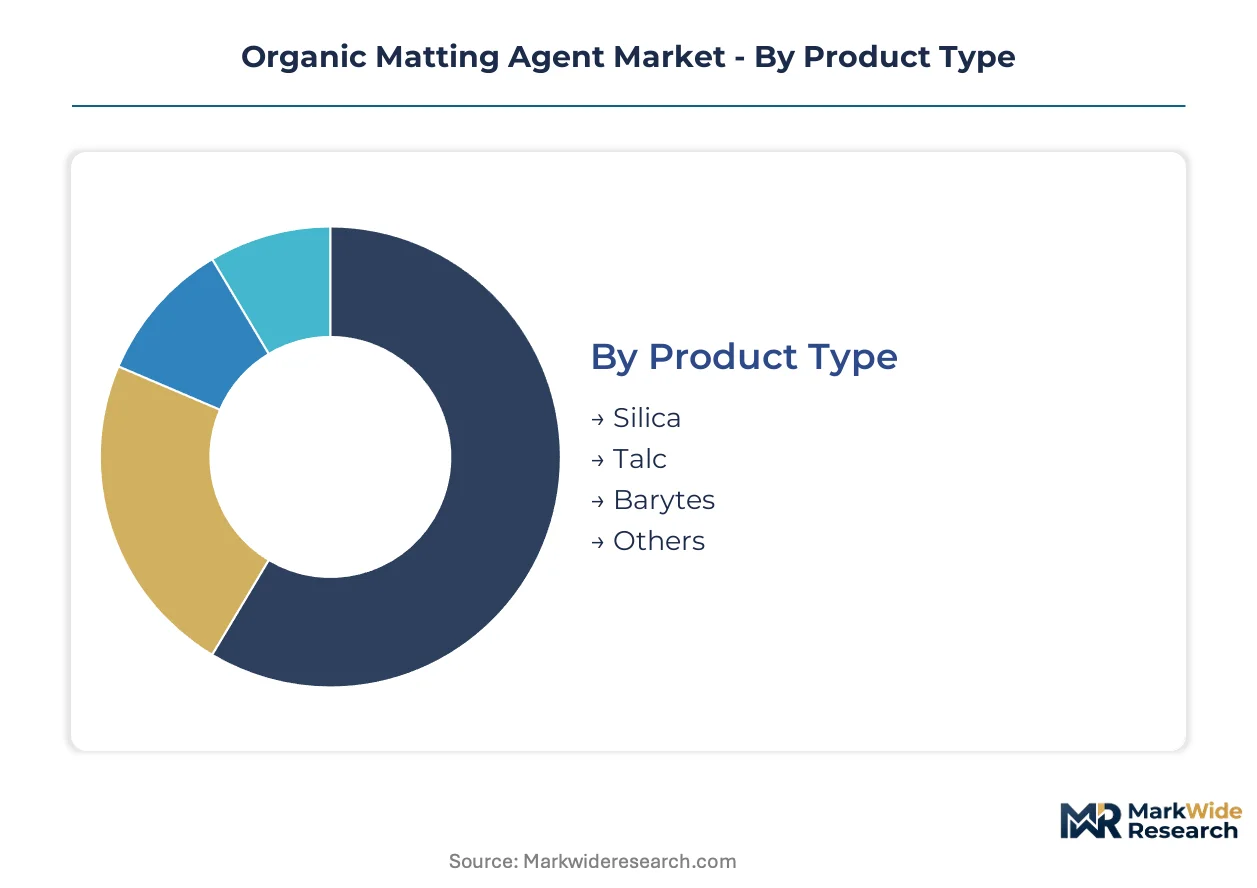
Organic matting agents serve divergent performance requirements across coating chemistries, substrate types, and regulatory environments. Segmentation reveals where formulation complexity concentrates and which additive specifications command premium positioning.
Product Type:
Precipitated silica dominates formulation portfolios due to its tunable particle architecture and established regulatory dossiers.
- Silica:Precipitated and fumed variants with controlled pore volumes scatter incident light through micro-roughness generation. Demand concentrates in German automotive OEM clearcoats where REACH-compliant grades with verified eco-toxicology profiles are mandatory for interior matte programs.
- Talc:Lamellar magnesium silicate structures provide cost-efficient matting in industrial primers where gloss reduction requirements are moderate. Construction coating formulators in Italy and Spain specify platy talc grades for exterior masonry finishes facing cost pressure from waterborne system conversion.
- Barytes:Barium sulfate delivers chemical inertness and density-driven sag resistance in high-build marine and protective coatings.
- Others:Modified biopolymer matrices from cellulose and chitin sources are piloting in Japanese automotive interior trim where surface feel differentiates specification.
Mature deployment sits with silica. Newer deployment is concentrated in modified biopolymer alternatives.
Application:
Coatings absorb the majority of volume, though inks generate concentrated margin pools through narrow specification windows.
- Coatings:Architectural, industrial, and automotive clearcoats utilize silica and wax dispersions for gloss control across waterborne, solventborne, and UV-curable platforms. German automotive coating clusters in Bavaria specify low-gloss interior finishes that demand single-source additive qualification.
- Inks:Food-contact packaging applications require modified biopolymer matrices that satisfy migration limits while maintaining cure speed in UV inkjet systems. European converters face compressed compliance timelines under EU Green Deal circular economy verification.
- Plastics:Micronized waxes enhance surface feel and scratch resistance in interior automotive trim and consumer electronics housings.
- Adhesives:Specialty construction adhesives incorporate matting agents for aesthetic matching in visible joint applications.
Volume leadership belongs to coatings. Margin concentration sits with inks.
End User:
Automotive OEMs are driving specification intensity through matte-finish interior design strategies.
- Automotive:Dashboard, trim, and clearcoat applications specify precipitated silica with thermal stability above 120°C and haze consistency across batch lots. German OEM design studios mandate REACH-registered grades with recycled-content verification under EMAS environmental management standards.
- Construction:Exterior masonry and wood coatings utilize talc and silica blends where cost efficiency competes with performance in waterborne system conversion.
- Packaging:Food-contact and luxury cosmetic packaging demand modified biopolymers with migration compliance and premium surface aesthetics.
- Household:Furniture and appliance coatings balance scratch resistance with cost in mid-tier formulation.
Specification intensity peaks in automotive. Cost pressure concentrates in construction.
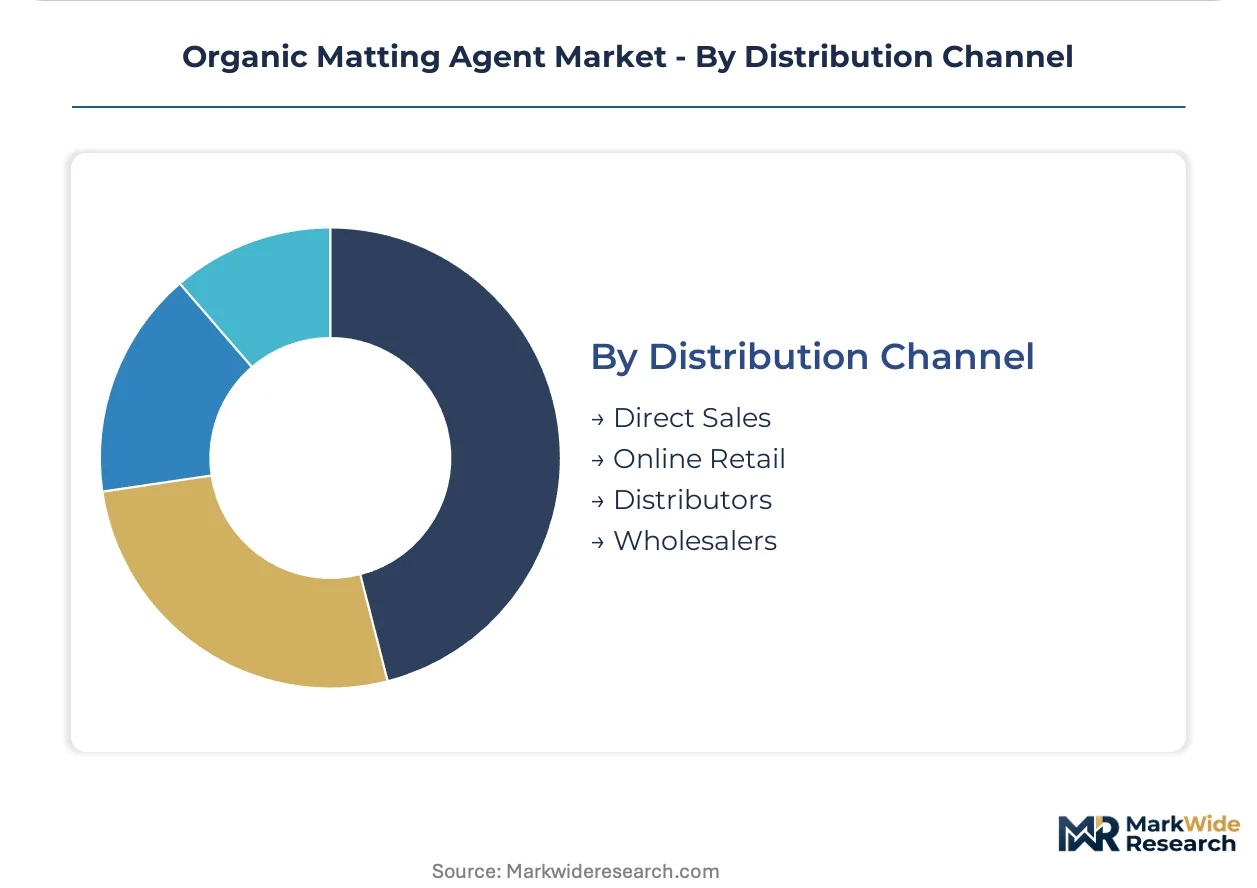
Distribution Channel:
Technical service requirements are reshaping channel structure toward direct engagement.
- Direct Sales:Evonik and Wacker Chemie AG specialists maintain technical service relationships with multinational formulators for dispersion optimization and particle size distribution tuning. Bavarian automotive supply corridors increasingly mandate single-source qualification through direct channels.
- Distributors:Regional chemical distributors serve mid-tier plastics processors and smaller coating formulators lacking in-house dispersion capabilities.
- Online Retail:Standardized silica and talc grades for research and small-batch formulation are migrating to digital procurement platforms.
- Wholesalers:Construction coating raw materials in Southern Europe move through traditional wholesale networks serving local applicators.
Relationship value concentrates in direct sales. Transaction efficiency dominates online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's automotive coating corridor concentrates European organic matting agent demand through OEM matte-finish mandates and REACH-registered silica qualification requirements.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify low-gloss interior clearcoats for dashboard and trim applications. ECHA substance evaluation protocols under REACH redirect formulator investment toward bio-based silica alternatives with verified eco-toxicology profiles. Stuttgart's tier-one coating suppliers consolidate single-source additive qualification through direct technical relationships.
United States
California's CARB SCM 2007 limits accelerate waterborne system conversion among architectural and industrial coating producers. EPA VOC emission standards under 40 CFR 59 shape product development priorities across solventborne displacement. Detroit's automotive OEM design studios expand matte-finish interior specifications, concentrating demand among Michigan-based formulators.
China
Industrial wood and coil coating processors absorb silica and wax-based matting agents for waterborne platform expansion. MEE environmental inspections and GB standards tighten particulate emission controls at manufacturing facilities. The Yangtze River Delta coating cluster responds with captive additive dispersion capabilities serving export-oriented automotive suppliers.
Japan
Automotive interior trim suppliers pilot modified biopolymer matrices from cellulose and chitin sources for dashboard applications where surface feel differentiates specification. METI industrial standards guide migration compliance for food-contact packaging ink applications. Nagoya's automotive supply corridor integrates UV-curable inkjet systems with narrow-specification biopolymer matting technologies.
India
BIS certification mandates and DGFT import substitution policies create openings for domestic formulation of bio-based matting agents. Industrial wood and plastics processors in Maharashtra and Gujarat absorb precipitated silica and micronized wax grades for cost-competitive coating production. Mumbai-Pune chemical corridor attracts regional distributor investment serving mid-tier formulators lacking in-house dispersion capabilities.
Organic Matting Agent Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, with market structure consolidating around technical service capabilities and regulatory dossier depth. Three archetypes dominate: integrated resin-additive houses with captive supply advantages, silica technology leaders with REACH-registered premium grades, and silicone-based specialists differentiating on thermal stability. Competitive moves concentrate on strategic partnerships for dispersion optimization and portfolio diversification into bio-based alternatives.
Within the technology-leader tier, Evonik Industries and Wacker Chemie AG exemplify divergent specialization strategies. Evonik's German GmbH structure anchors silica technology leadership for automotive clearcoat applications. Wacker Chemie AG occupies a parallel position through silicone-based organic matting agents. PPG Industries represents the integrated conglomerate archetype, combining resin and additive expertise in-house for OEM supply contract control.
| Leading Market Players |
|---|
| Evonik Industries |
| Wacker Chemie AG |
| PPG Industries |
| Baltimore Innovations |
| W. R. Grace & Co.-Conn. |
| Imerys |
| PQ Corporation |
| Huber Engineered Materials |
| Huntsman International LLC |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal circular economy verification gates qualified supply access and props premium-tier pricing power for REACH-registered silica grades serving Bavarian automotive OEMs. Formulators lacking EMAS-certified additive sources face exclusion from single-source qualification programs, compressing procurement options for interior matte-finish specifications.
Pricing Analysis
Margin tightening in standard-grade silica reflects precipitated silica supply concentration among European and Asian chemical specialists. Three-tier pricing structure across premium REACH-registered, standard industrial, and economy talc-replacement grades separates automotive OEM qualification tiers from construction coating cost pressures. Pricing pressure stems from CARB SCM 2007 compliance investments in waterborne system conversion. Tier-one automotive formulators exhibit lowest price sensitivity; mid-tier plastics processors face acute cost compression.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke patterns for specialty silica and wax dispersions. Production gravity centers on Germany, China, and Japan for high-purity precipitated silica, micronized polyolefin waxes, and modified biopolymer matrices respectively. Raw material flows draw from sodium silicate feedstocks, petroleum-derived wax fractions, and cellulose/chitin biopolymer sources. Single-source vulnerability concentrates in automotive OEM additive qualification where dispersion optimization expertise is captive to Evonik and Wacker Chemie AG technical service relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precipitated silica production capacity bottlenecks among REACH-registered European specialists prop pricing power and sustain supply-constrained market dynamics through the analysis window.
For Market Incumbents: Cement silica technology leadership by deepening backward integration into sodium silicate feedstocks and expanding EMAS-certified recovery capabilities. Lock in single-source qualification status with Bavarian automotive OEMs through dedicated technical service relationships that preempt modified biopolymer substitution threats.
For New Entrants and Emerging Players: Begin with domestic formulation partnerships in Maharashtra and Gujarat serving Indian industrial wood processors under BIS certification mandates. Target UV-curable inkjet packaging converters in Nagoya's automotive supply corridor with modified biopolymer matrices that satisfy METI migration compliance. Pursue direct technical collaboration with regional distributors lacking dispersion capabilities.
For Investors and Strategic Acquirers: EMAS environmental management certification adoption among German automotive coating clusters is the leading indicator that recycled-content verification will become a mandatory supplier qualification threshold. Position for consolidation of mid-tier silica recovery specialists with captive coating waste stream access. Monitor DGFT import substitution policy enforcement as the inflection signal for Indian domestic capacity buildout viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Silicate Feedstocks | Secures raw material supply for REACH-registered precipitated silica production serving Bavarian OEMs. |
| EMAS-Certified Silica Recovery Program | Captures post-industrial coating waste streams to satisfy EU Green Deal circular economy verification requirements. |
| Direct Technical Service Expansion | Locks in single-source additive qualification with tier-one automotive formulators in Stuttgart's coating cluster. |
| Modified Biopolymer Matrix R&D Partnership | Preempts REACH authorization bottlenecks for conventional silica grades in Japanese automotive interior applications. |
| Regional Distribution Hub Establishment | Reduces logistics friction for mid-tier plastics processors in Mumbai-Pune chemical corridor. |
Study Parameters
Multi-period observation of REACH registration timelines, EMAS certification adoption rates, and automotive OEM matte-finish specification releases anchored the trend analysis, supplemented by interviews with coating formulator R&D directors, automotive tier-one procurement managers, specialty chemical distribution partners, and ECHA regulatory affairs specialists. Secondary validation drew from ECHA substance evaluation protocols, EU Green Deal policy documentation, SEC 10-K filings of listed chemical conglomerates, and German automotive production registration data. Bottom-up formulation demand modeling triangulated against top-down coating industry consumption estimates.
Input-output matrices mapped silica grade tier, end-use industry, coating chemistry platform, and regional regulatory cluster across the projection horizon. CAGRs were derived from segmented demand elasticity modeling and capacity expansion announcements. Forecast inputs incorporated automotive OEM interior design cycle timing, waterborne system conversion compliance deadlines, and biopolymer matrix pilot program scalability.
Underlying measurement precision varies by segment; automotive OEM qualification data carries tighter precision than mid-tier plastics processor estimates. Forecasts reflect documented assumptions regarding REACH authorization timelines and EMAS certification adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Synthetic Antioxidants Market
Organic Chemicals
Triethylene Glycol Market
Organic Chemicals
Global Ketones Market
Organic Chemicals
Europe Lactic Acid Market
Organic Chemicals
US Humate Market
Organic Chemicals
Acetic Acid Market
Organic Chemicals
Cyclic Ketones Market
Organic Chemicals
Dioctyl Phthalate Market
Organic Chemicals
Organic Coating Market
Organic Chemicals
Acetaldehyde Market
Organic Chemicals
Soy Chemicals Market
Organic Chemicals
2-Iodophenol Market
Organic Chemicals
Acrylic Acid Market
Organic Chemicals
2-Methylbutanoic Acid Market
Organic Chemicals
Global Carboxylic Acid Market
Organic Chemicals
Synthetic Camphor Market