
 Organic Polysulfide Market | 2026-2036
Organic Polysulfide Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Polysulfide Market Outlook
Project finance for specialty chemical capacity is fragmenting competitive access, allowing mid-scale entrants to lease rather than build dedicated polysulfide plants. Arkema leverages its European manufacturing network to sustain feedstock integration across sulfur-based chemistries. Dow Inc. anchors North American supply through backward integration into chlorinated intermediate production. Toray Fine Chemicals competes in Asia-Pacific through high-purity grades for electronics and display applications.
Organic polysulfides comprise sulfur-rich oligomers with disulfide and polysulfide linkages, typically synthesized via condensation of sodium polysulfide with organic dihalides; these materials cure through oxidative crosslinking to form elastomeric networks with exceptional chemical resistance and gas impermeability, serving primarily as sealants, adhesives, and binders in demanding structural and environmental barrier applications. Polysulfide sealants occupy the largest value share due to entrenched specification in aircraft fuel tank sealing and marine caulking where replacement cycles are long and certification barriers are steep. Polysulfide elastomers represent the fastest-expanding category, driven by electric vehicle battery module gaskets requiring thermal stability and electrolyte resistance.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based formulation practices, pushing manufacturers toward waterborne or 100-percent-solids polysulfide systems. REACH registration requirements and the EU Green Deal's chemical sustainability criteria are reshaping raw material sourcing decisions across European supply chains. Stakeholders must monitor evolving flammability and smoke-toxicity standards from FAA and EASA as next-generation aircraft architectures redefine sealant performance thresholds.
Market Dynamics
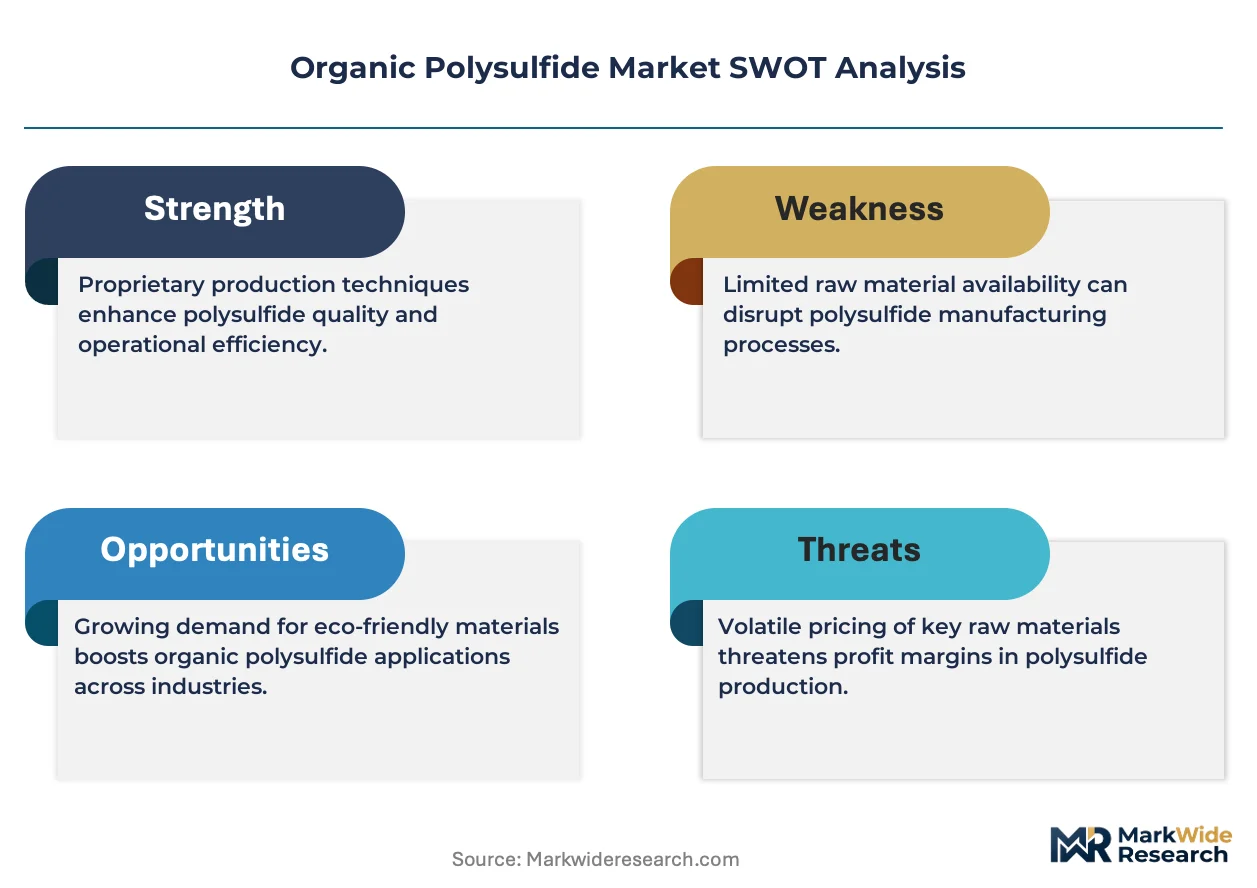
REACH registration deadlines and EPA National Emission Standards for Hazardous Air Pollutants are forcing manufacturers to abandon solvent-based polysulfide formulations, accelerating capital redeployment toward waterborne curing systems and 100-percent-solids chemistry platforms.
Growth Catalysts
- FAA airworthiness directives:Aging aircraft fleets require fuel tank resealing cycles that specify polysulfide sealants exclusively, locking in replacement demand across North American and European maintenance networks.
- German automotive OEM battery programs:Electric vehicle manufacturers in Stuttgart and Munich specify polysulfide elastomer gaskets for thermal management and electrolyte containment in high-voltage enclosures.
- Marine classification society rules:Lloyd's Register and DNV mandates for hull sealing integrity in commercial shipping sustain polysulfide caulk demand through 25-year vessel inspection cycles.
Market Restraints
- Sulfur feedstock concentration:Refinery-derived sulfur supply clusters in the US Gulf Coast and Middle Eastern petrochemical corridors expose processors to regional production disruptions and freight cost volatility.
- REACH authorization timelines:ECHA's substance evaluation protocols for thiol-terminated intermediates extend new product registration cycles to 18-24 months, freezing formulation innovation pipelines.
- Silicone sealant substitution:Room-temperature-vulcanizing silicone systems penetrate aircraft interior sealing applications where FAA fuel tank specifications do not apply, eroding addressable volume in secondary aerospace markets.
Strategic Opportunities
- South Korean battery supply chain:LG Energy Solution and Samsung SDI expansion in Gwangju and Ulsan creates demand for high-purity polysulfide binders in solid-state electrolyte research programs.
- EU Green Deal chemical sustainability criteria:Bio-based sulfur sourcing requirements open procurement advantages for European manufacturers with circular feedstock certifications.
- Hybrid waterborne-UV curing convergence:Combination systems reduce solvent content below EPA thresholds while accelerating production line speeds for automotive tier-one adhesive applicators.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in thiol-epoxy hybrid chemistry and oxidative crosslinking kinetics concentrates at legacy sealant manufacturers, constraining talent mobility.
- FAA/EASA dual certification timelines:Aircraft fuel tank sealant approvals require 36-48 month qualification protocols including fuel immersion and thermal cycling validation, freezing product iteration cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Polysulfide Market |
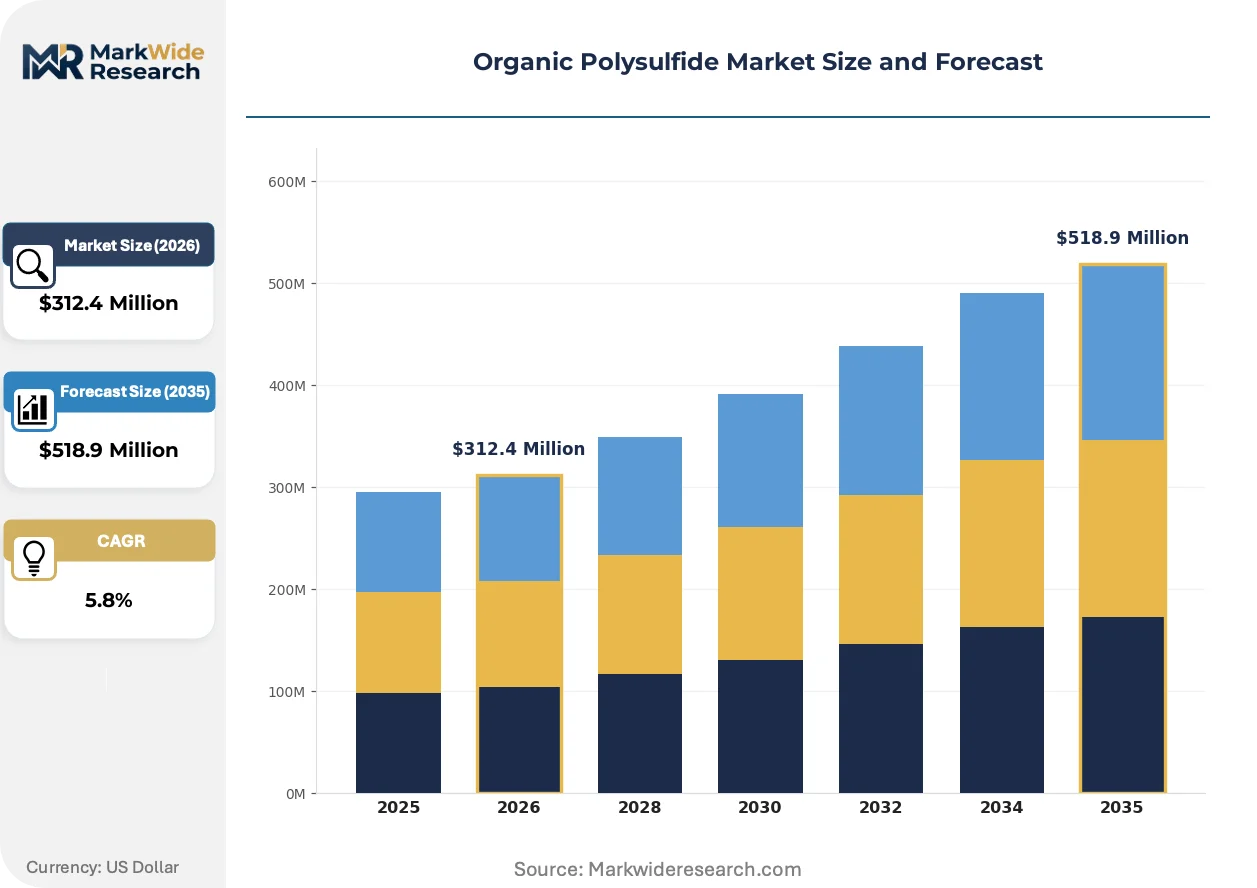
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polysulfide Sealants, Polysulfide Elastomers, Polysulfide Resins, Polysulfide Adhesives Application: Construction, Automotive, Aerospace, Marine End User: Contractors, Manufacturers, Distributors, OEMs Distribution Channel: Online Retail, Wholesale, Direct Sales, Retail Outlets |
| Companies Covered | BASF SE, Arkema, Dow Inc., PPG Industries, Inc., Toray Fine Chemicals, Nouryon, 3M Company, Sika AG, Kazan Synthetic Rubber Plant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Polysulfide Market Strategic Shifts
Digital process control systems and predictive curing analytics are compressing quality assurance timelines while regulatory chemistry restrictions force raw material substitution strategies across formulation laboratories.
Advanced rheology monitoring with embedded spectroscopic sensors is digitizing real-time viscosity tracking during polysulfide sealant mixing operations. Automotive adhesive applicators in Detroit and Wolfsburg deploy these systems to eliminate batch-to-batch variation. The technology is digitizing quality control documentation chains that previously required manual laboratory verification.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants tightens permissible solvent content in formulated products to 250 grams per liter. Manufacturers respond by converting continuous production lines to waterborne polysulfide dispersions with modified amine curing agents. Aerospace sealant producers in California and Texas face the steepest compliance costs due to state-level overlay regulations.
Specification-driven procurement now dominates electric vehicle battery enclosure sourcing, with OEM technical teams embedding material scientists at tier-one adhesive suppliers. Long-term supply agreements with performance guarantees replace spot purchasing for polysulfide gasket materials. This pattern concentrates most visibly in German and South Korean automotive supply chains where battery platform standardization accelerates.
Organic Polysulfide Market Segmentation
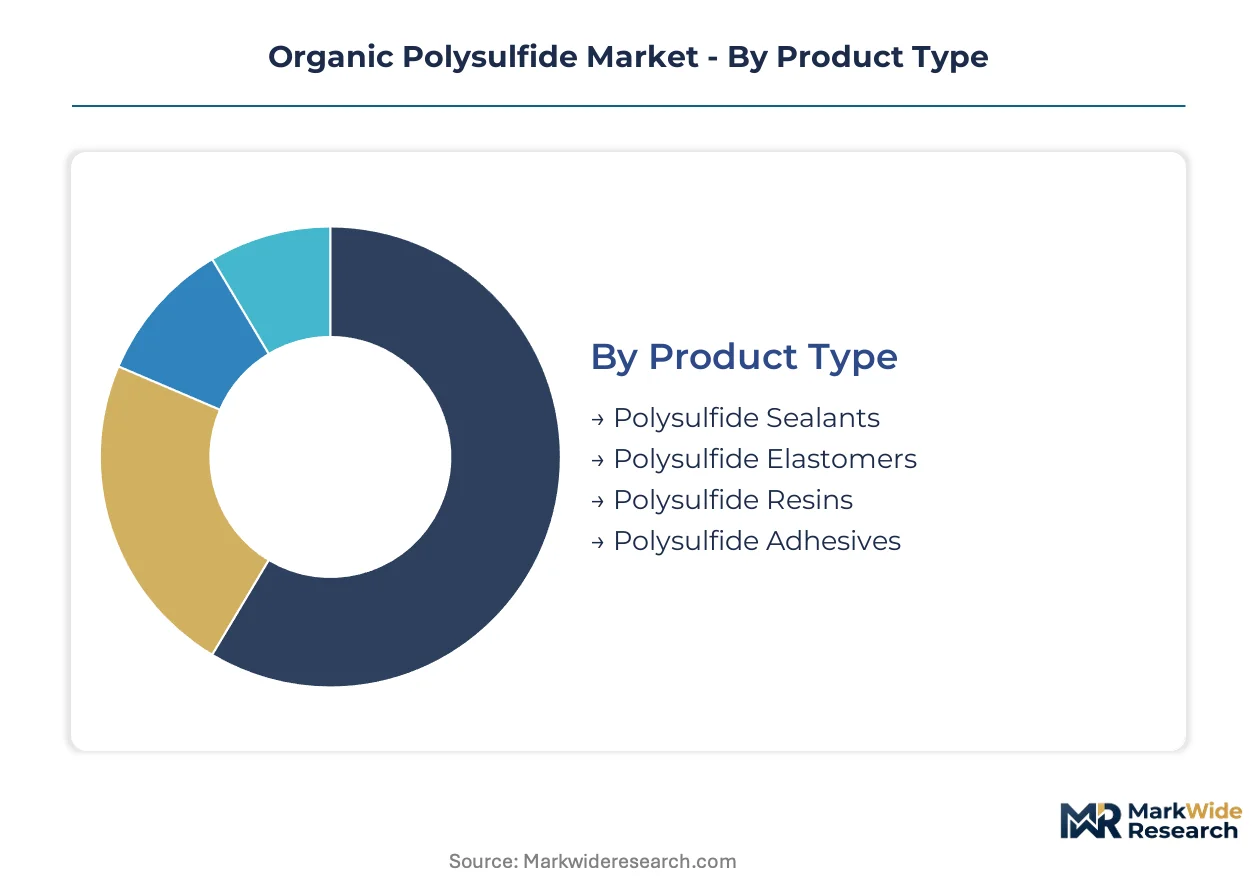
Segmentation in organic polysulfides reveals how specification-grade chemistry separates from commodity formulations. Product architecture, application severity, and procurement channel each create distinct margin tiers and competitive barriers.
Product Type:
Mature sealant formulations dominate commercial throughput while emerging elastomer grades capture specification-driven premiums.
- Polysulfide Sealants:Thiol-terminated liquid polymers cure through oxidative crosslinking to form fuel-impermeable elastomeric films. Aircraft fuel tank sealing at Boeing and Airbus assembly plants in Charleston and Hamburg sustains demand through mandatory resealing cycles driven by FAA airworthiness directives.
- Polysulfide Elastomers:Solid rubber compounds deliver thermal stability and electrolyte resistance for electric vehicle battery module gaskets. German automotive OEMs in Stuttgart specify these materials for high-voltage enclosure sealing as battery platform standardization accelerates.
- Polysulfide Resins:Low-viscosity oligomers serve as reactive diluents and toughening agents in epoxy hybrid systems for marine coatings.
- Polysulfide Adhesives:Structural bonding formulations bond dissimilar substrates in construction expansion joints and curtain wall assemblies.
Polysulfide sealants handle the majority of throughput; polysulfide elastomers are the fastest mover on share.
Application:
Cost tier separation runs from specification-critical aerospace down to price-sensitive construction bulk purchasing.
- Construction:Expansion joint sealants and glazing compounds for commercial building envelopes. Municipal infrastructure projects in Texas and Florida specify polysulfide for bridge deck waterproofing where movement accommodation exceeds silicone capabilities.
- Automotive:Battery enclosure gaskets and direct glazing adhesives. OEM technical teams embed material scientists at tier-one suppliers in Wolfsburg and Detroit to lock in performance-guaranteed supply agreements.
- Aerospace:Fuel tank sealing and fuselage seam compounds. FAA certification requirements freeze product iteration cycles at 36-48 months, protecting incumbent formulations from displacement.
- Marine:Hull caulking and deck sealing for commercial shipping. Lloyd's Register and DNV inspection mandates sustain demand through 25-year vessel maintenance cycles.
Aerospace commands the highest unit margins; automotive is expanding most quickly as electric vehicle production scales.
End User:
Customer type determines specification authority and procurement complexity across the value chain.
- Contractors:Construction applicators purchasing bulk sealants through distribution. Regional glazing contractors in California face EPA state-level overlay regulations on solvent content.
- Manufacturers:Tier-one adhesive formulators and automotive parts suppliers. These entities maintain captive laboratories for thiol-epoxy hybrid chemistry development.
- Distributors:Industrial chemical wholesalers stocking multiple grades. Inventory concentration in the US Gulf Coast exposes these intermediaries to sulfur feedstock disruption risk.
- OEMs:Original equipment manufacturers with direct material science teams. German and South Korean battery producers increasingly bypass distribution to secure long-term polysulfide supply.
Manufacturers retain the deepest formulation expertise; OEMs are gaining share fastest through direct procurement.
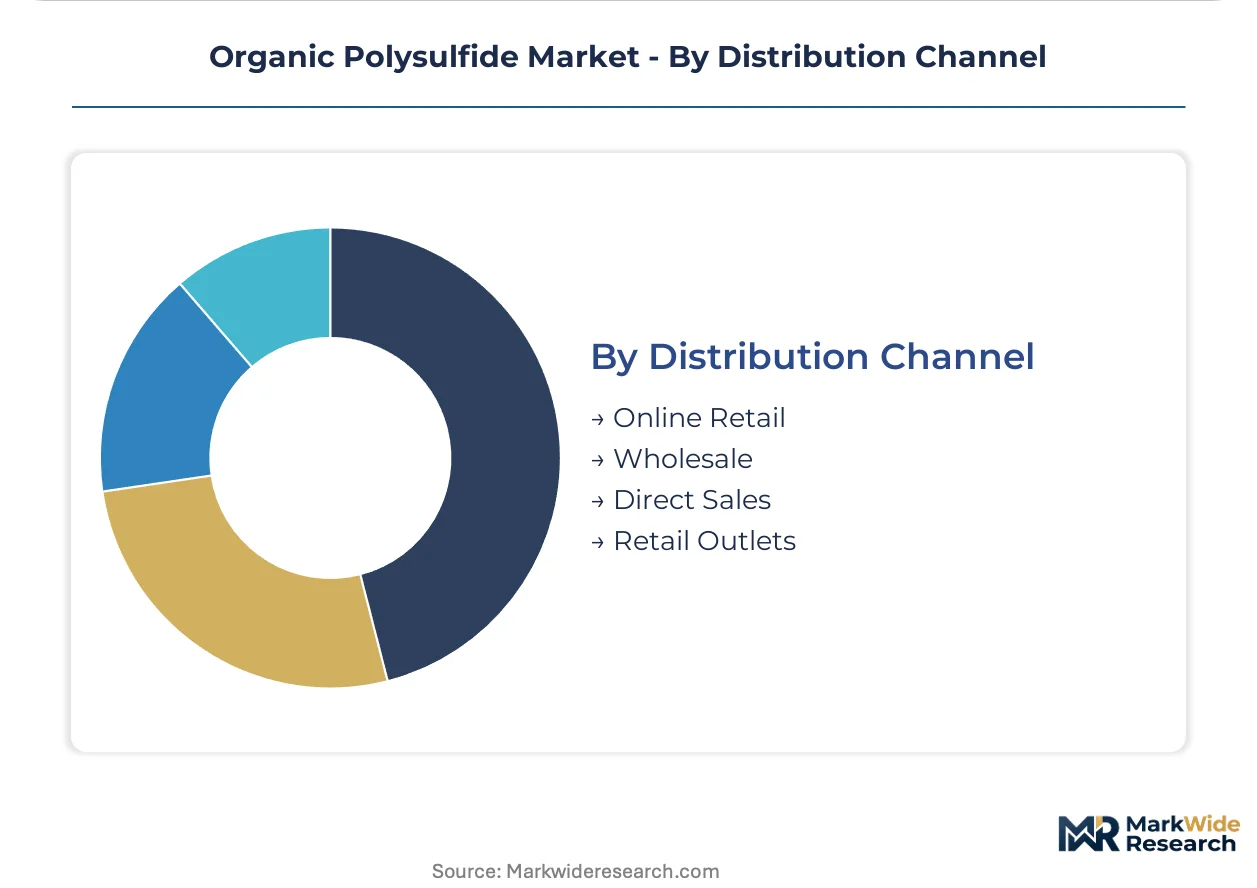
Distribution Channel:
Volume concentration favors wholesale bulk while margin capture shifts toward direct technical sales.
- Online Retail:Small-package sealants for maintenance and repair operations. Limited penetration due to hazardous material shipping restrictions on solvent-containing formulations.
- Wholesale:Bulk drum and tote shipments to construction and marine contractors. Texas and Louisiana distributors maintain regional sulfur-based chemical inventories.
- Direct Sales:Technical service agreements with automotive and aerospace OEMs. Specification-driven procurement embeds supplier scientists at customer R&D facilities.
- Retail Outlets:Consumer-grade caulks and sealants for marine and architectural applications. Shelf space competition from silicone and polyurethane alternatives constrains placement.
Wholesale channels handle the majority of volume; direct sales is climbing the fastest as OEM technical engagement deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in organic polysulfides tilt toward import dependency in Asia-Pacific battery hubs while North American and European markets maintain tighter supply-demand balances through captive production. Export volumes concentrate in sulfur-rich petrochemical corridors. Import demand clusters where electric vehicle assembly scales fastest.
United States
Aerospace sealant demand at Boeing's Charleston facility and Tesla's battery enclosure programs in Texas drive consumption. EPA National Emission Standards for Hazardous Air Pollutants constrain solvent-based formulation practices in California and Texas production sites. The US Gulf Coast sulfur cluster near Houston anchors domestic feedstock supply for polysulfide intermediates.
Germany
Automotive OEMs in Stuttgart and Munich specify polysulfide elastomer gaskets for electric vehicle battery thermal management systems. REACH registration requirements and EU Green Deal chemical sustainability criteria reshape raw material sourcing decisions across Bavarian and Baden-Württemberg supply chains. BASF's Ludwigshafen complex maintains integrated sulfur-based chemistry production.
China
Shipbuilding at Dalian and Guangzhou yards sustains marine caulking demand while battery manufacturers in Shenzhen trial solid-state electrolyte binders. The country's national chemical safety regulator enforces volatile organic compound thresholds in formulated products. Yangtze River Delta chemical parks concentrate polysulfide resin capacity for epoxy hybrid systems.
South Korea
LG Energy Solution and Samsung SDI expansion in Gwangju and Ulsan creates demand for high-purity polysulfide grades in battery research programs. The national chemical regulatory framework aligns with REACH-equivalent substance evaluation protocols. Seoul Capital Area technical teams embed material scientists at tier-one adhesive suppliers for specification-driven procurement.
Japan
Electronics display manufacturers in Osaka and Nagoya procure high-purity polysulfide resins for specialty coating applications. METI industrial standards govern chemical substance handling in manufacturing processes. Toray Fine Chemicals' Chubu region facilities serve Asia-Pacific electronics supply chains with specification-grade materials.
Organic Polysulfide Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream where thiol-terminated chemistry expertise concentrates. The vendor base separates into three distinct tiers: multinational chemical conglomerates with sulfur-based integration, mid-scale regional formulators serving construction and marine markets, and specialty electronics-grade producers. Consolidation pressures intensify as REACH compliance costs and FAA certification timelines favor incumbents with captive regulatory affairs capabilities. Strategic moves center on backward integration into sulfur feedstock and hybrid waterborne-UV curing technology licensing.
Among European-based chemical conglomerates, BASF SE and Arkema exemplify integrated platform operators with sulfur-based chemistry networks spanning multiple industrial applications. Dow Inc. anchors North American supply through in-house production of chlorinated intermediates. Toray Fine Chemicals occupies a position within the Asia-Pacific specialty tier, representing high-purity grade capabilities for electronics and display applications where specification barriers protect margin structures.
| Leading Market Players |
|---|
| BASF SE |
| Arkema |
| Dow Inc. |
| PPG Industries, Inc. |
| Toray Fine Chemicals |
| Nouryon |
| 3M Company |
| Sika AG |
| Kazan Synthetic Rubber Plant |
| Others |
Value Chain & Pricing Dynamics
US Gulf Coast sulfur clusters feed captive chlorinated intermediate production at Dow's Texas operations, anchoring margin capture downstream where specification-grade sealants command premiums over commodity construction formulations. Pricing power concentrates with manufacturers holding backward integration into sulfur-based feedstocks, while non-integrated formulators absorb volatility through long-term offtake contracts.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where aerospace fuel tank sealants trade at certification-grade premiums above construction bulk grades. Price differentiation separates FAA-certified formulations from uncertified marine caulks, with volume scale and after-sales technical service bundling as secondary tiering factors. Cost compression in construction-grade segments is intensifying as silicone substitutes erode polysulfide share in non-critical glazing applications. Municipal contractors purchasing bridge deck sealants exhibit highest price sensitivity, while German automotive OEMs prioritize performance guarantees over unit cost.
Supply Chain Analysis
Export-control restrictions on dual-use chemical processing equipment constrain capacity expansion in certain jurisdictions, fragmenting global supply availability. Manufacturing concentrates in the United States, Germany, and China, with raw material flows drawing from refinery-derived sulfur clusters, chlorinated organic intermediates, and thiol-terminated polymer feedstocks. Single-source vulnerability runs through Middle Eastern sulfur supply corridors exposed to regional production disruptions. Distribution runs through wholesale bulk channels for construction and marine contractors, while direct technical sales dominate automotive and aerospace procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards service-attach strategies where formulation technical support and qualification assistance generate recurring revenue streams expanding faster than base polymer sales. After-sales regulatory compliance consulting and certification maintenance programs deepen customer captivity beyond product transactions.
For Market Incumbents: Insulate specification-grade positions by accelerating captive sulfur feedstock integration and embedding technical teams at German and South Korean battery OEMs. Counter silicone substitution threats through hybrid waterborne-UV curing technology licensing that preserves polysulfide chemistry advantages while meeting EPA emission thresholds. Prioritize FAA/EASA dual certification pipeline investment to extend incumbent protection against formulation challengers.
For New Entrants and Emerging Players: Establish a beachhead in South Korean solid-state battery research programs where LG Energy Solution and Samsung SDI trial high-purity polysulfide binders lacking established supply relationships. Target marine classification society-approved hull caulking for regional shipbuilders in Dalian and Guangzhou where incumbent presence remains thinner. Pursue technical partnership routes with automotive tier-one adhesive suppliers rather than direct OEM confrontation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional formulators holding REACH registration portfolios but lacking sulfur integration. Long-term viability hinges on regulatory compliance capability rather than scale alone. Watch for ECHA substance evaluation acceleration on thiol-terminated intermediates as an inflection signal that would favor acquirers with captive regulatory affairs infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Feedstock | Captive supply from US Gulf Coast refinery clusters secures margin protection against freight volatility. |
| Hybrid Waterborne-UV Curing Technology Licensing | Combination systems enable California and Texas producers to meet EPA National Emission Standards thresholds. |
| Long-term Supply Agreement with Performance Guarantees | German automotive OEMs embed material scientists at tier-one suppliers, locking out spot-market competitors. |
| Green Manufacturing Transition | EU Green Deal bio-based sulfur sourcing requirements open procurement advantages for circular-certified producers. |
| Joint Venture in Asia-Pacific Battery Hubs | Gwangju and Ulsan expansion by LG Energy Solution and Samsung SDI creates demand for high-purity grades. |
Study Parameters
The analysis maps polysulfide sealants, elastomers, resins, and adhesives, each validated through formulation chemists at legacy manufacturers, procurement leads at German automotive OEMs, distribution channel partners in Texas and Louisiana, and technical R&D directors at aerospace sealant producers. Secondary sources include customs and trade flow data, ACC and Cefic chemical industry reports, SEC 10-K filings from listed chemical conglomerates, and REACH registration databases. Bottom-up segment sizing triangulates against top-down chemical consumption estimates.
Assumptions held fixed include current EPA National Emission Standards enforcement levels and ECHA substance evaluation timelines, while variables included electric vehicle battery platform standardization rates and solid-state electrolyte commercialization trajectories. The projection framework models grade tier, end-use industry, packaging format, and regional production hub dimensions throughout the forecast period. CAGRs derive from segment-level volume build-ups incorporating aerospace resealing cycle frequencies, automotive battery enclosure content per vehicle, and marine vessel inspection mandates.
Sensitivities concentrate around REACH authorization timeline compression, FAA airworthiness directive acceleration, and sulfur feedstock disruption events. Forecasts reflect these assumptions without claiming predictive certainty. Material shifts in ECHA regulatory stringency or solid-state battery chemistry transitions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Bromobenzene Market
Organic Chemicals
Behenyl Alcohol Market
Organic Chemicals
Europe Organic Acid Market
Organic Chemicals
Chlorinated Methane Market
Organic Chemicals
Dioxolane Market
Organic Chemicals
DMDM Hydantoin Market
Organic Chemicals
Global Ketones Market
Organic Chemicals
North America Humic Acid Market
Organic Chemicals
N-Pentane Market
Organic Chemicals
Long-Chain Dicarboxylic Acid Market
Organic Chemicals
Synthetic Camphor Market
Organic Chemicals
Humic Acid Market
Organic Chemicals
Crotonic Acid Market
Organic Chemicals
Synthetic Antioxidants Market
Organic Chemicals
Global Glycolic Acid Market
Organic Chemicals
2-Iodophenol Market