
 Global Biphenyl Market | 2026-2036
Global Biphenyl Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biphenyl Market Analysis
East Asian aromatic chemical capacity is hardening as the dominant supply benchmark for biphenyl derivatives. Eastman Chemical Company leverages its integrated coal-tar distillation network to sustain cost-competitive feedstock access. BASF SE anchors European pharmaceutical-grade output through dedicated high-purity trains. Jiangsu Zhongneng Chemical Technology Co., Ltd. dominates domestic Chinese supply with backward integration into crude biphenyl refining.
Biphenyl consists of two phenyl rings joined by a single carbon-carbon bond, exhibiting a melting point near 69°C and serving primarily as a precursor for polychlorinated biphenyl alternatives, heat transfer media, and pharmaceutical intermediates. Industrial grade material occupies the largest volume share in chemical manufacturing applications where thermal stability requirements are moderate. Reagent grade commands premium positioning in electronics verticals where trace metal specifications determine material acceptance.
EPA guidelines in the United States and REACH registration requirements in Europe constrain chlorinated biphenyl residuals while China's MEE enforces emission thresholds around aromatic chemical production. These frameworks elevate compliance costs for smaller producers and redirect procurement toward certified bulk supply channels. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate specification fragmentation in cross-border trade.
Market Dynamics
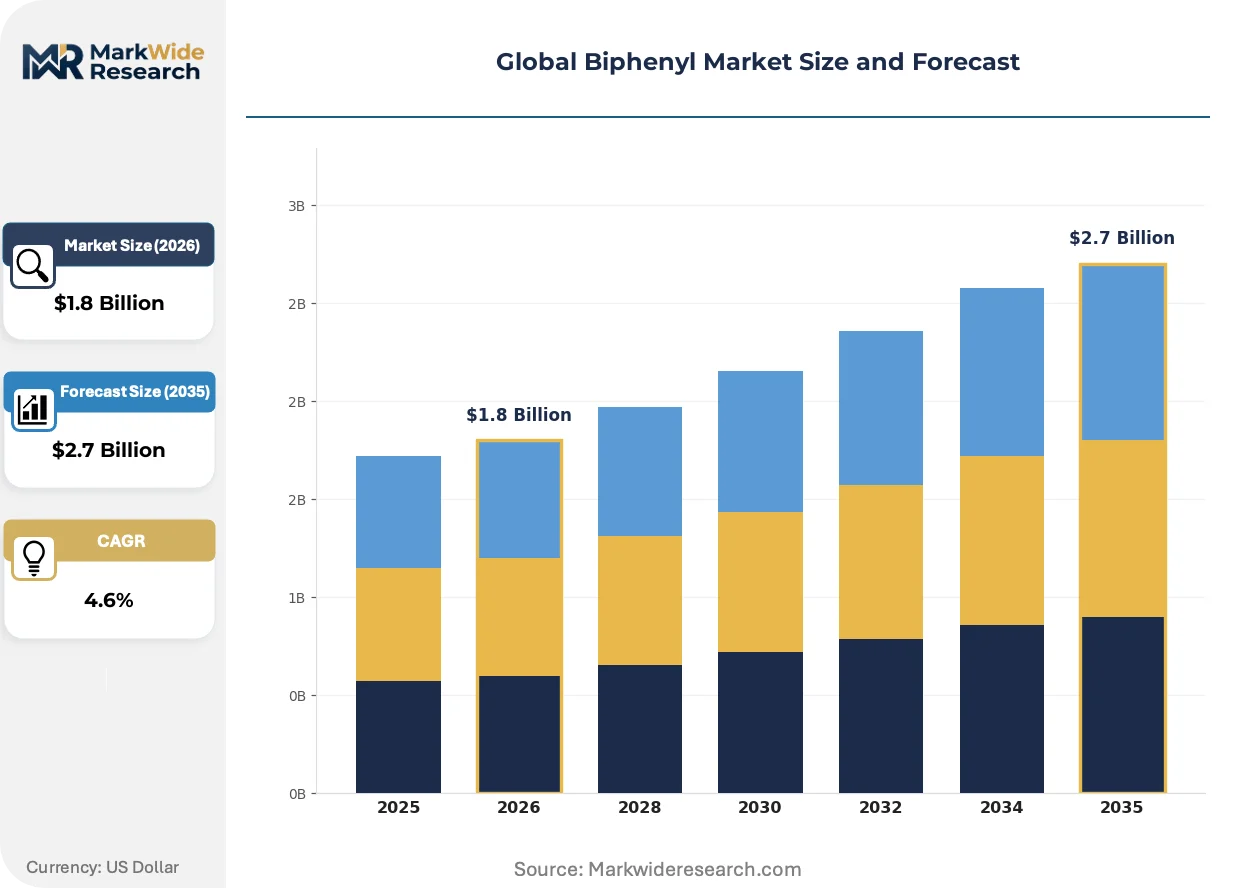
The Global Biphenyl Market pivots on REACH-driven purity escalation and China's polyphenyl capacity buildout, which together compress legacy chlorinated feedstock channels and redirect procurement toward certified high-purity supply chains.
Growth Catalysts
- Heat transfer fluid demand:Chemical processing plants in Germany and Japan are expanding biphenyl-based thermal media installations to replace mineral oils in high-temperature loops. This end-use vertical absorbs industrial-grade volumes at scale.
- EPA residual limits:The United States Environmental Protection Agency's tightened chlorinated biphenyl thresholds are forcing reformulation across electrical insulation applications. Compliance-driven material replacement pulls pharmaceutical-grade supply.
- China's dual carbon goals:Beijing's emission intensity mandates are accelerating closures of small-scale coal-tar distillers. Concentration of refining capacity in Shandong and Jiangsu provinces secures feedstock access for integrated producers.
Market Restraints
- Crude coal-tar volatility:Input costs for biphenyl refining swing with coking economics and steel production cycles in China. Margin compression hits non-integrated processors without captive tar supply.
- MEE emission enforcement:China's Ministry of Ecology and Environment is tightening aromatic volatile organic compound limits. Smaller Jiangsu and Zhejiang refiners face capital-intensive scrubber retrofits or exit.
- Isopropylbiphenyl substitution:Partially hydrogenated alternatives are displacing biphenyl in low-temperature heat transfer applications. Substitution pressure concentrates in European food-processing equipment.
Strategic Opportunities
- India specialty chemical buildout:The country's PLI scheme for chemical manufacturing is attracting greenfield investment in Gujarat and Maharashtra. Early entrants can establish pharmaceutical-grade supply relationships before domestic capacity saturates.
- Electronics-grade purification:Semiconductor fabs in South Korea and Taiwan are specifying sub-ppb metal content for biphenyl derivatives used in photoresist solvents. Premium positioning opens for certified producers.
- EU Green Deal chemistry:The European Union's sustainable chemistry transition is incentivizing bio-based biphenyl route development. Research funding and offtake commitments are concentrating in Dutch and German consortia.
Industry Challenges
- High-purity train commissioning:Pharmaceutical-grade production requires 18-24 month validation cycles for REACH dossier completeness. Delayed certification blocks revenue recognition for new entrants.
- Analytical chemistry talent scarcity:Trace-level chlorinated residual testing demands GC-MS specialists familiar with EPA Method 1668. Recruitment friction slows quality control expansion in North American facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biphenyl Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Reagent Grade, Purity Grade, Specialty Chemicals Application: Chemical Manufacturing, Phosphor Production, Heat Transfer Fluids, Solvent Industry Vertical: Pharmaceuticals, Electronics, Agriculture, Textiles Delivery Mode: Bulk Supply, Packaged Supply, Online Distribution, Direct Shipping |
| Companies Covered | Eastman Chemical Company, BASF SE, Dow Inc., Mitsubishi Chemical Corporation, Jiangsu Zhongneng Chemical Technology Co., Ltd., LANXESS AG, Merck KGaA, Huntsman Corporation, Solvay S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biphenyl Market Emerging Trajectories
Process intensification and regulatory convergence are compressing the viable supply base while opening premium tiers for certified purity grades. Technology adoption patterns diverge sharply between commodity heat-transfer applications and precision electronics verticals.
Membrane-based purification is unifying the separation of biphenyl isomers and residual polynuclear aromatics in a single continuous operation. Japanese electronics material suppliers are adopting this technology fastest, with two major South Korean chemical groups following within 18 months. The process is unifying what previously required multiple crystallization and distillation stages, collapsing capital intensity for entrants targeting semiconductor-grade specifications.
REACH Article 33 disclosure obligations are extending downstream through European electrical equipment supply chains. Manufacturers of transformers and capacitors must now document biphenyl-derived fluid composition to demonstrate chlorinated residual compliance. German and French OEMs are consolidating procurement onto pre-certified bulk suppliers to eliminate batch-level testing overhead.
Long-term offtake contracting is displacing spot market purchasing among Asian chemical processors. Buyers in Singapore and Thailand are locking in 24-36 month biphenyl supply agreements with fixed purity bands and indexed pricing. This behavior is most visible in polyphenyl derivative production, where feedstock security determines operating rates for continuous polymerization trains.
Global Biphenyl Market Segmentation
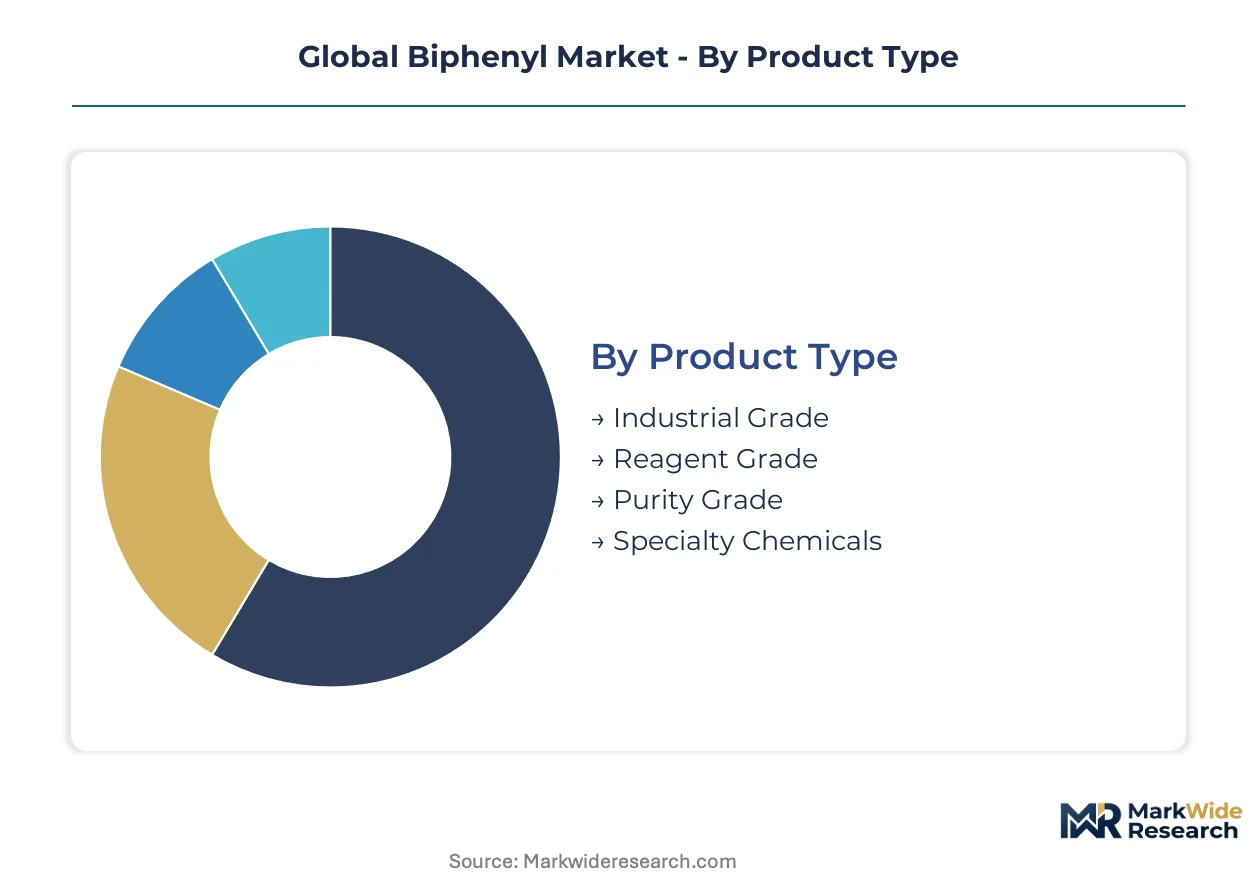
Biphenyl market segmentation reveals how purity specifications and delivery logistics split procurement behavior across chemical processing, electronics, and pharmaceutical verticals. Supply chain configuration varies sharply between bulk industrial consumers and precision-grade electronics buyers.
Product Type:
Supply concentration in Shandong and Jiangsu provinces directly shapes which purity grades achieve cost-competitive scale.
- Industrial Grade:Material with 95-98% purity serves heat transfer fluid formulation and chemical synthesis where thermal stability exceeds trace contamination concerns. Chemical processing plants in Germany and Japan absorb volumes through long-term offtake contracts indexed to coal-tar feedstock costs.
- Reagent Grade:99%+ purity specifications with sub-ppm metal content enable pharmaceutical intermediate synthesis and analytical chemistry applications. REACH dossier requirements for residual polynuclear aromatic documentation concentrate European procurement onto certified producers with validated quality systems.
- Purity Grade:Ultra-high purification for electronics verticals demands sub-ppb metal content verified by ICP-MS protocols. South Korean semiconductor fabs specify this tier for photoresist solvent applications.
- Specialty Chemicals:Derivatized biphenyls including halogenated and alkylated variants serve custom synthesis contracts.
Today's leader: Industrial Grade. Tomorrow's challenger: Reagent Grade.
Application:
End-use differentiation tracks temperature requirements and regulatory exposure intensity across processing industries.
- Chemical Manufacturing:Biphenyl serves as a precursor for polyphenyl polymers and dye intermediates in continuous production trains. China's dual carbon goals are accelerating closures of small-scale coal-tar distillers, concentrating feedstock access for integrated producers.
- Phosphor Production:High-purity biphenyl derivatives function as host matrices for LED phosphor systems. Japanese electronics material suppliers dominate specification-setting for this application tier.
- Heat Transfer Fluids:Eutectic mixtures with diphenyl oxide achieve thermal stability above 300°C in chemical processing loops. German and Japanese plants are expanding installations to replace mineral oils in high-temperature applications.
- Solvent:Biphenyl dissolves polar and non-polar compounds across reaction chemistry and extraction processes.
Heat Transfer Fluids capture current volume leadership. Phosphor Production shows the steepest expansion trajectory as LED manufacturing scales.
Industry Vertical:
Margin structure diverges dramatically between specification-driven electronics procurement and price-sensitive agricultural applications.
- Pharmaceuticals:API synthesis and drug formulation demand validated supply chains with complete batch documentation. EPA residual limits on chlorinated biphenyls are forcing reformulation across North American pharmaceutical manufacturing.
- Electronics:Semiconductor and display manufacturing specify sub-ppb metal content for photoresist and cleaning solvent applications. South Korean and Taiwanese fabs are consolidating procurement onto pre-certified bulk suppliers.
- Agriculture:Pesticide intermediate production consumes industrial-grade volumes with moderate purity requirements.
- Textiles:Dye carrier applications in polyester processing use biphenyl derivatives for color fastness enhancement.
Electronics commands premium positioning. Pharmaceuticals is gaining share fastest as oncology API pipelines expand.
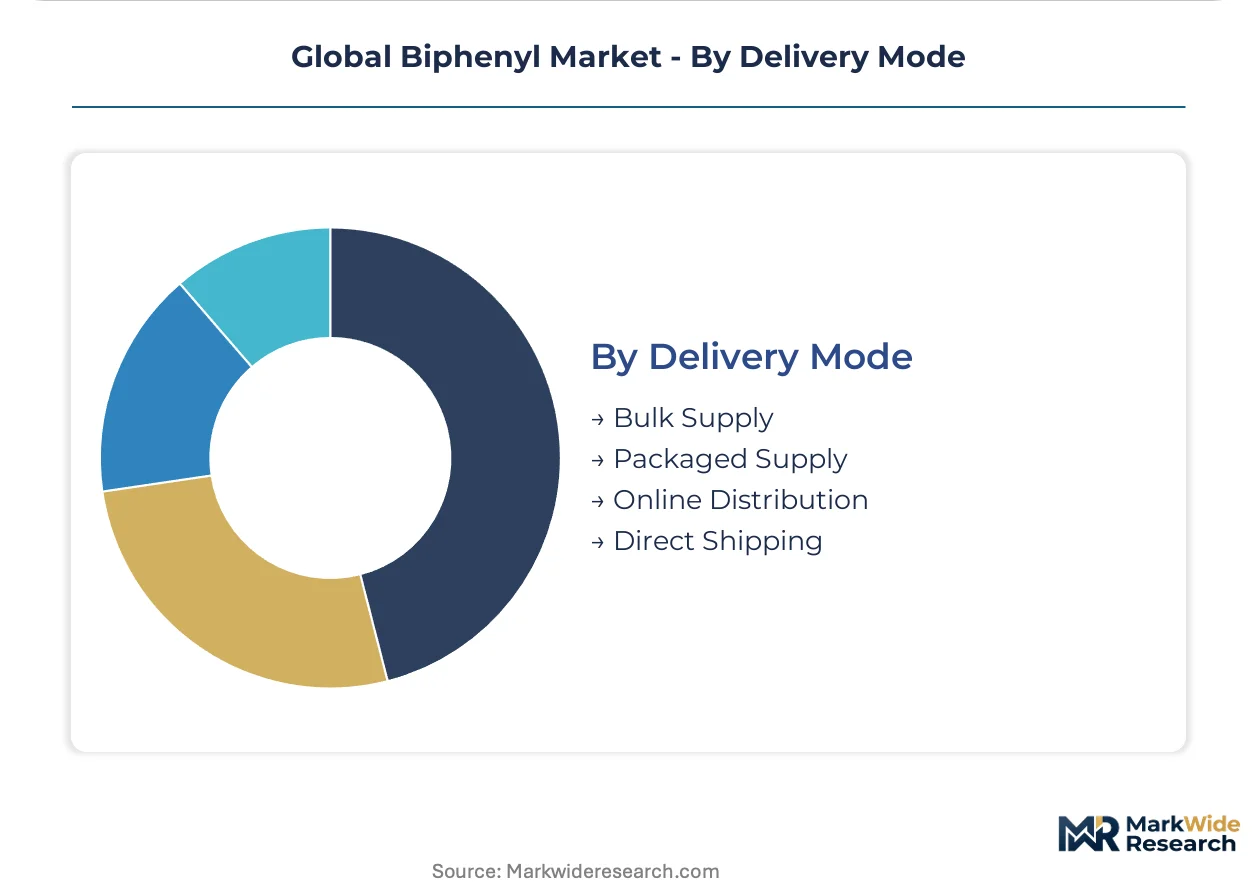
Delivery Mode:
Logistics configuration reflects buyer scale, inventory carrying cost tolerance, and geographic concentration of demand clusters.
- Bulk Supply:Tanker and railcar delivery of molten biphenyl serves chemical processors with continuous consumption rates above 500 metric tons annually. Singapore and Thai buyers are locking in 24-36 month supply agreements with fixed purity bands.
- Packaged Supply:Drummed solid material in 200kg containers enables pharmaceutical and electronics manufacturers with batch-oriented consumption patterns. REACH Article 33 disclosure obligations are extending downstream through European electrical equipment supply chains.
- Online Distribution:E-procurement platforms serve research laboratories and small-scale synthesis operations with credit-card purchasing and rapid fulfillment.
- Direct Shipping:Producer-to-consumer logistics eliminate distributor margin for large-volume contracts with dedicated freight arrangements.
Bulk Supply anchors industrial procurement. Packaged Supply is expanding most quickly as electronics-grade demand fragments across multiple consuming sites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting biphenyl production toward jurisdictions with lower compliance-cost burdens. Producers in China and India capture cost advantages from streamlined environmental permitting, while European and North American facilities absorb REACH and EPA compliance premiums.
China
Shandong and Jiangsu provinces concentrate domestic refining capacity for industrial-grade biphenyl supply. MEE emission thresholds are forcing small-scale coal-tar distillers to retrofit scrubbers or exit, consolidating feedstock access for integrated producers. Qingdao chemical clusters are expanding high-purity train capacity to serve semiconductor-grade demand from South Korean fabs.
Germany
Leverkusen and Ludwigshafen chemical corridors anchor European pharmaceutical-grade biphenyl output. REACH Article 33 disclosure obligations extend downstream through transformer and capacitor supply chains, consolidating procurement onto pre-certified bulk suppliers. BASF SE maintains dedicated high-purity trains validated for residual polynuclear aromatic documentation.
United States
Gulf Coast petrochemical complexes in Texas and Louisiana process biphenyl for heat transfer fluid formulation. EPA Method 1668 residual limits on chlorinated biphenyls are forcing reformulation across electrical insulation applications. Houston-area processors are locking in long-term offtake contracts with indexed pricing to manage crude coal-tar volatility.
Japan
Kanto and Kansai industrial belts sustain demand for LED phosphor host matrices and electronics-grade derivatives. METI industrial standards shape specification-setting for semiconductor material purity. Osaka chemical groups are adopting membrane-based purification technology fastest, collapsing capital intensity for sub-ppb metal content verification.
South Korea
Giheung and Pyeongtaek semiconductor clusters specify sub-ppb metal content for photoresist solvent applications. MFDS pharmaceutical regulations intersect with electronics material standards for dual-use chemical certification. Samsung and SK Hynix supplier qualification programs are consolidating procurement onto pre-certified bulk channels with 24-36 month contract structures.
Global Biphenyl Market Vendor Landscape
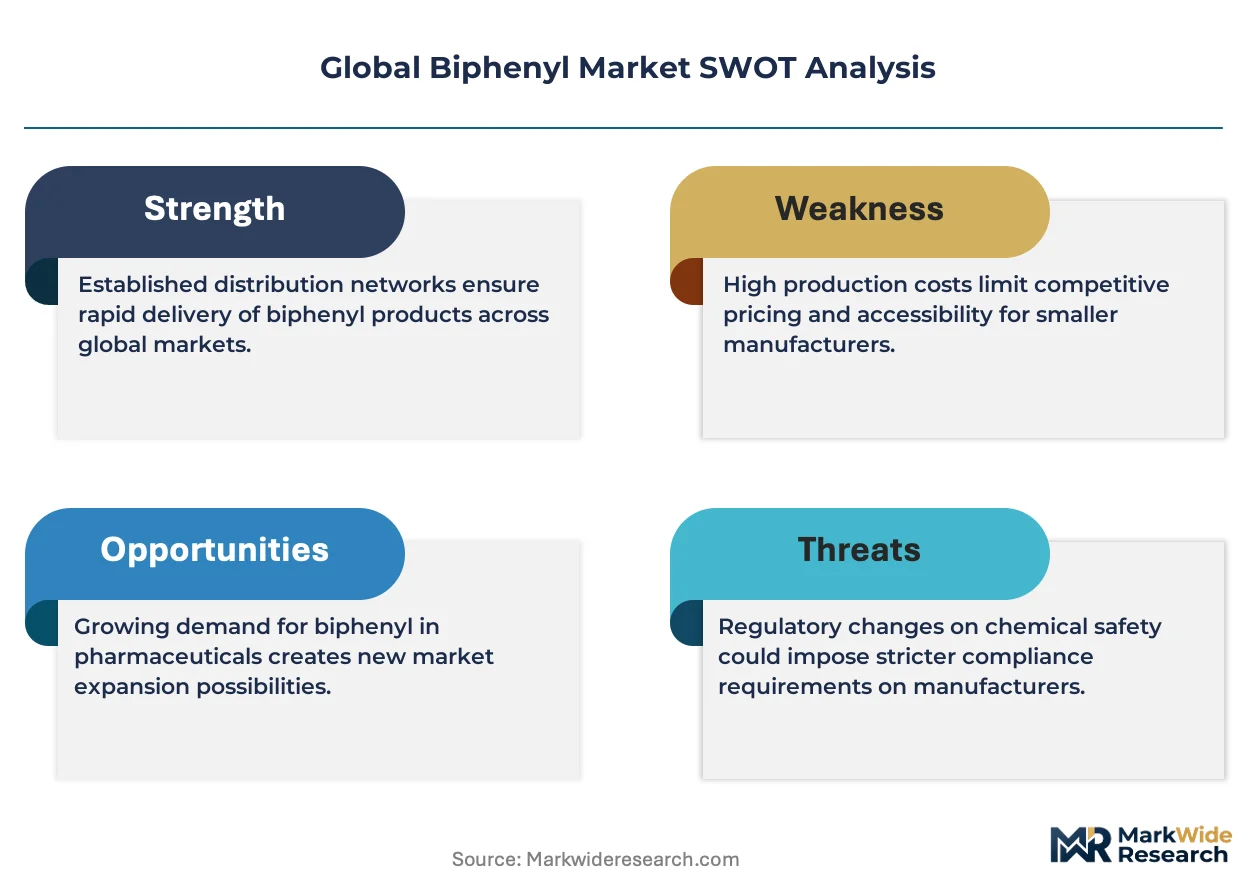
Established producers occupy the standard tier; emerging entrants pursue electronics-grade purification and bio-based route development. The vendor base stratifies between integrated coal-tar refiners with captive feedstock and specialty chemical houses with validated quality systems. Three archetypes dominate: backward-integrated Chinese refiners, European pharmaceutical-grade specialists, and Japanese electronics material suppliers. Capacity expansion and long-term offtake contracting represent the dominant competitive moves.
Within the integrated refiner tier, Jiangsu Zhongneng Chemical Technology Co., Ltd. exemplifies backward integration into crude biphenyl refining. Among European specialists, BASF SE and LANXESS AG occupy positions defined by REACH dossier completeness and pharmaceutical-grade validation. Eastman Chemical Company represents the North American archetype of coal-tar distillation network leverage. These three anchors illustrate how geographic feedstock access and regulatory compliance capabilities determine competitive positioning across purity grades.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| BASF SE |
| Dow Inc. |
| Mitsubishi Chemical Corporation |
| Jiangsu Zhongneng Chemical Technology Co., Ltd. |
| LANXESS AG |
| Merck KGaA |
| Huntsman Corporation |
| Solvay S.A. |
| Others |
Supply Flow & Price Mechanics
China's dual carbon goals and MEE emission thresholds gate qualified supply and premium-tier pricing access, concentrating cost-competitive industrial-grade production in Shandong and Jiangsu while forcing smaller refiners toward scrubber retrofits or exit. Buyers seeking pharmaceutical-grade or electronics-grade material face narrower certified supplier pools with validated REACH dossiers and ICP-MS protocols, compressing procurement options and sustaining tiered price premiums.
Pricing Analysis
Distributor margin layers separate industrial-grade bulk contracts from packaged pharmaceutical and electronics deliveries. Pricing stratifies across premium, standard, and economy tiers based on purity certification and volume scale, with South Korean semiconductor fabs paying substantial premiums for sub-ppb metal content verified by ICP-MS. Cost compression in industrial-grade tiers is intensifying because crude coal-tar volatility swings with coking economics. Chemical processing plants exhibit highest price sensitivity through indexed long-term offtake contracts, while electronics manufacturers show least sensitivity due to specification-locked supplier qualification programs.
Supply Chain Analysis
Single-source vulnerability sits with China's concentrated coal-tar refining base in Shandong and Jiangsu provinces. Feedstock supply draws from captive coking operations and steel production cycles, with merchant tar availability tightening as dual carbon mandates accelerate small-distiller closures. Logistics chokepoint risk concentrates in Qingdao port capacity for electronics-grade exports to South Korean fabs. Distribution runs through bulk tanker and railcar for chemical processors above 500 metric tons annually, with drummed solid material serving batch-oriented pharmaceutical and electronics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Biphenyl Market functions as a stable compounder anchored by heat transfer fluid replacement cycles in chemical processing plants, where thermal stability requirements above 300°C sustain predictable demand renewal.
For Market Incumbents: Anticipate isopropylbiphenyl substitution pressure in European food-processing equipment by deepening backward integration into crude coal-tar refining and locking 24-36 month offtake contracts with Singapore and Thai polyphenyl producers. Prioritize membrane-based purification technology adoption to collapse capital intensity for semiconductor-grade certification and defend margin position against Japanese electronics material suppliers. For New Entrants and Emerging Players: Enter via India's PLI scheme for chemical manufacturing in Gujarat and Maharashtra, where pharmaceutical-grade supply relationships remain uncommitted before domestic capacity saturates. Target electronics-grade purification for South Korean and Taiwanese semiconductor fabs, leveraging membrane-based isomer separation to bypass multi-stage crystallization capital requirements. Position through direct supplier qualification programs at Samsung and SK Hynix rather than distributor channels. For Investors and Strategic Acquirers: Valuations sit cheapest among non-integrated Chinese refiners facing MEE scrubber retrofit costs or forced exit, creating distressed acquisition opportunities with embedded coal-tar feedstock access. Long-term viability over a 5-10 year window favors integrated producers with validated REACH dossiers and semiconductor-grade certification pipelines. Watch for inflection in South Korean fab capacity expansion announcements as the signal for electronics-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coal-Tar Refining | Captive feedstock access insulates margin from coking cycle volatility in China. |
| Membrane-Based Purification Technology Adoption | Japanese electronics material suppliers collapse capital intensity for sub-ppb metal verification fastest. |
| Long-Term Supply Agreement Structuring | Singapore and Thai buyers lock 24-36 month contracts with fixed purity bands and indexed pricing. |
| Semiconductor-Grade Certification Investment | South Korean MFDS regulations intersect with electronics standards for dual-use chemical qualification. |
| Green Manufacturing Transition | Dutch and German consortia concentrate EU Green Deal research funding for bio-based biphenyl routes. |
Methodological Framework
Direct dialogue with plant managers at chemical processing facilities, procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors at electronics material suppliers grounded qualitative assessment. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA Method 1668 regulatory documentation. Bottom-up and top-down triangulation cross-checked volume estimates against coal-tar distillation capacity and end-use consumption patterns.
Bottom-up modeling built from grade-tier, end-use industry, packaging format, and regional production hub segmentation across the analysis window. Top-down cross-checks validated aggregate market size against aromatic chemical production indices and heat transfer fluid formulation volumes. CAGRs were derived from regression analysis of historical purity-grade pricing trends and capacity expansion announcements. Forecast inputs incorporated MEE enforcement timelines and South Korean semiconductor fab buildout pipelines.
Inputs from regulatory filing databases and industry association reports were available through the study window; gaps in small-scale Chinese refiner financial disclosures introduce uncertainty bands around consolidation speed assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Global Pseudocumene Market
Organic Chemicals
Dimethyl Carbonate Market
Organic Chemicals
Isophthalic Acid Market
Organic Chemicals
Dimethylformamide (DMF) Market
Organic Chemicals
Global Carboxylic Acid Market
Organic Chemicals
Phenol Market
Organic Chemicals
US Humate Market
Organic Chemicals
Dioxolane Market
Organic Chemicals
Global Metal-Organic Framework Market
Organic Chemicals
Europe Organic Acid Market
Organic Chemicals
Mercaptopropionic Acid Market
Organic Chemicals
Benzyl Cyanide Market
Organic Chemicals
2,6-Dichloro Aniline Market
Organic Chemicals
Aspartic Acid Market
Organic Chemicals
Acrylonitrile Market
Organic Chemicals
Cyclic Ketones Market