
 Dioxolane Market | 2026-2036
Dioxolane Market Size, Share, and Industry Trends Forecast 2026-2036
Dioxolane Market Analysis
Green solvent substitution in pharmaceutical and electronics manufacturing is reshaping procurement priorities for cyclic acetal alternatives. BASF Chemical Intermediates leverages its integrated C1 chemistry platform to sustain cost-advantaged supply of high-purity grades. Merck KGaA anchors its position through pharmaceutical-grade certification and stringent quality protocols for GMP-compliant applications. Hefei TNJ Chemical Industry Co. Ltd. dominates regional supply to Asian battery electrolyte producers with scaled 1,3-dioxolane output.
Dioxolane refers to a five-membered cyclic acetal containing two oxygen atoms adjacent to a methylene bridge, typically existing as 1,3-dioxolane with a boiling point near 75°C and miscibility with water and most organic solvents; industrially it functions primarily as a polar aprotic solvent, chemical intermediate, and electrolyte co-solvent. The solvent application segment leads volume consumption due to its role in lithium-ion battery electrolyte formulations and pharmaceutical reaction media, while the intermediate segment registers the fastest structural growth as agrochemical and polymer manufacturers expand downstream acetal chemistry. Dimethoxy variants command premium positioning in electronics-grade specifications, whereas methyl ether derivatives occupy broader industrial solvent markets with thinner margin profiles.
EPA industrial solvent emission regulations and REACH substance restriction frameworks constrain volatile organic compound content in formulated products, compelling producers to document purity thresholds and supply chain transparency. China's SAMR national chemical standards and the EU's CLP classification requirements further segment market access between technical-grade and battery-grade specifications. Stakeholders must monitor evolving electrolyte solvent specifications from battery manufacturers and anticipate regulatory tightening on acetal impurities in pharmaceutical applications.
Market Dynamics
Electrolyte solvent specifications from lithium-ion battery manufacturers are compressing purity tolerances and forcing acetal producers to reconfigure distillation infrastructure around water-content thresholds below 50 ppm.
Growth Catalysts
- REACH substance restriction frameworks:European ECHA mandates on volatile organic compound content are disqualifying traditional ether solvents from pharmaceutical formulation contracts, redirecting procurement toward cyclic acetals with documented impurity profiles.
- Lithium battery electrolyte formulations:Chinese cell manufacturers are scaling cylindrical and prismatic battery output, consuming dioxolane as a co-solvent with ethylene carbonate to depress freezing points and enhance ionic conductivity at sub-zero temperatures.
- Agrochemical intermediate demand:Brazilian and Indian crop protection manufacturers are expanding acetal chemistry downstream into pyrethroid synthesis and herbicide active ingredients, pulling technical-grade dioxolane through regional distribution networks.
Market Restraints
- Formaldehyde input cost volatility:The C1 feedstock underpinning dioxolane production fluctuates with methanol pricing and natural gas differentials, compressing margin visibility for non-integrated producers lacking captive formaldehyde supply.
- Supply concentration in Shandong and Jiangsu provinces:Chinese chemical producers control approximately two-thirds of global 1,3-dioxolane nameplate capacity, creating single-source vulnerability for European and North American battery electrolyte blenders.
- Tetrahydrofuran substitution in pharmaceutical applications:THF retains incumbent status in Grignard reactions and organometallic synthesis despite higher hygroscopicity, slowing dioxolane penetration in conservative GMP environments.
Strategic Opportunities
- US Inflation Reduction Act domestic content incentives:Battery cell and electrolyte producers qualifying for IRA tax credits are requalifying North American dioxolane supply chains to meet localized content thresholds for electric vehicle tax credit eligibility.
- Solid-state battery electrolyte precursor applications:Polymer and sulfide-based solid electrolyte developers are evaluating dioxolane derivatives as plasticizers and interface modifiers in prototype manufacturing lines.
- EU Green Deal sustainable chemistry procurement mandates:Public pharmaceutical tenders across Germany, France, and the Netherlands are incorporating lifecycle assessment scoring that favors bio-based acetal routes over petrochemical alternatives.
Industry Challenges
- Pharmaceutical-grade certification timelines:EMA and FDA drug master file submissions for novel solvent sources require 18-36 month validation cycles, freezing supplier switches until regulatory packages achieve active status.
- Electronics-grade moisture specification compliance:Battery electrolyte blenders demand Karl Fischer titration certificates traceable to national metrology institutes, forcing producers to invest in inert-atmosphere packaging and dedicated analytical laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dioxolane Market |
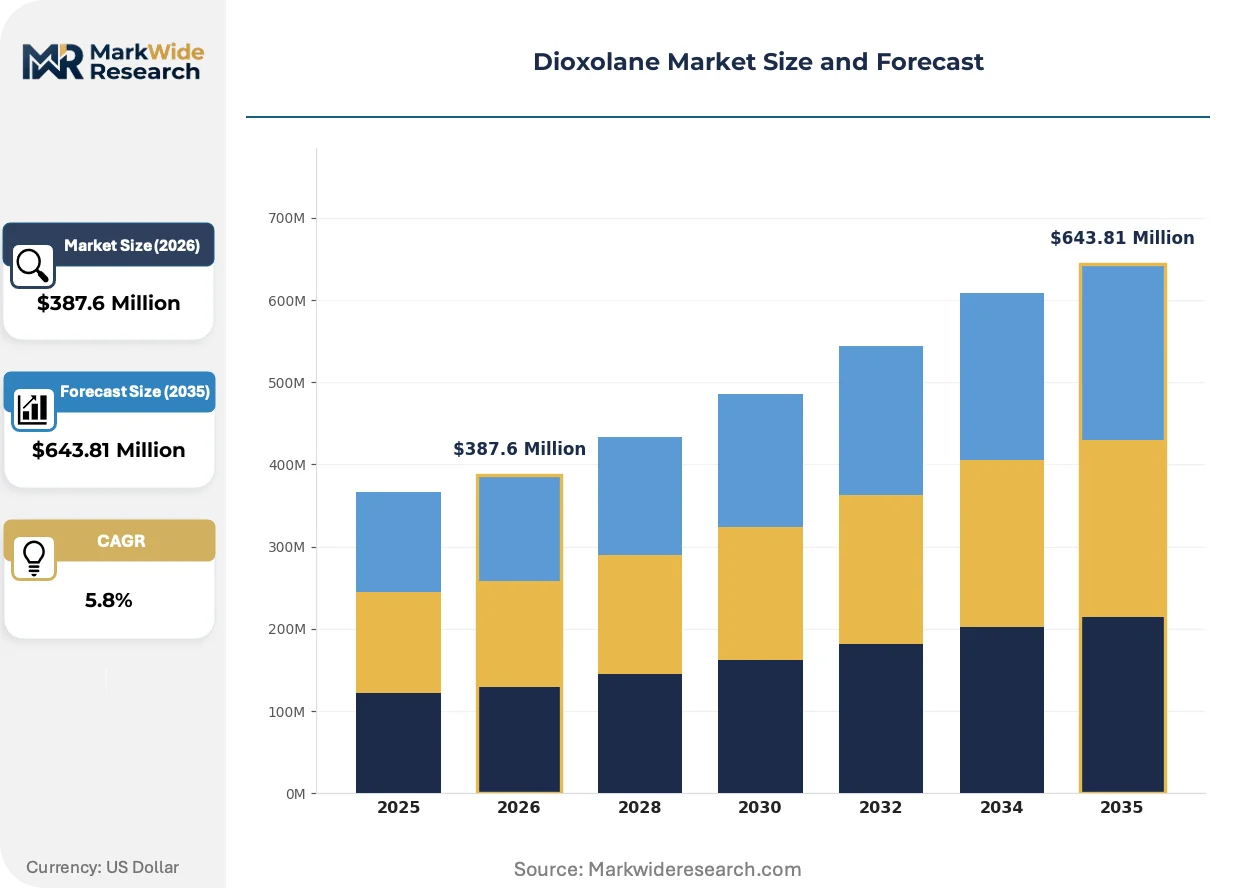
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dimethoxy, Dihydroxy, Ethyl Ether, Methyl Ether Application: Solvent, Reagent, Intermediate, Extractant End User: Pharmaceuticals, Agrochemicals, Electronics, Petrochemicals Form: Liquid, Powder, Concentrate, Emulsion |
| Companies Covered | BASF Chemical Intermediates, Lambiotte & Cie S.A, Merck KGaA, Honeywell, Kairav Chemofarbe Industries Ltd., TCI Chemicals Pvt. Ltd., Chemdyes Corporation, Hefei TNJ Chemical Industry Co. Ltd., Henan DaKen Chemical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dioxolane Market Emerging Trajectories
Process intensification in cyclic acetal manufacturing is collapsing batch cycle times while membrane separation technologies are displacing conventional azeotropic distillation for water removal.
Membrane pervaporation modules incorporating hydrophilic polymeric selective layers are collapsing energy requirements for dioxolane dehydration from 8-12 kWh per kilogram to below 3 kWh. German and Japanese specialty chemical producers are piloting these systems at demonstration scale. The technology is compressing capital intensity for battery-grade capacity expansions and eroding the cost advantage of legacy producers with sunk investment in extractive distillation trains.
EPA industrial solvent emission regulations under the National Emission Standards for Hazardous Air Pollutants are tightening methylene chloride and perchloroethylene phase-out timelines. Formulators serving aerospace and metal finishing sectors are substituting dioxolane-based cleaning blends to maintain degreasing performance while achieving compliance. Midwestern US coating manufacturers are accelerating solvent qualification programs to preempt 2025-2026 enforcement windows.
Electrolyte procurement from battery original equipment manufacturers is consolidating toward direct long-term offtake agreements with qualified solvent producers, bypassing traditional chemical distributors. Korean and Chinese cell manufacturers are negotiating five-year supply contracts with fixed-volume minimums and indexed pricing. The shift is visible most acutely in the Yangtze River Delta and Great Lakes manufacturing corridors where gigafactory concentration enables dedicated logistics infrastructure.
Dioxolane Market Segmentation
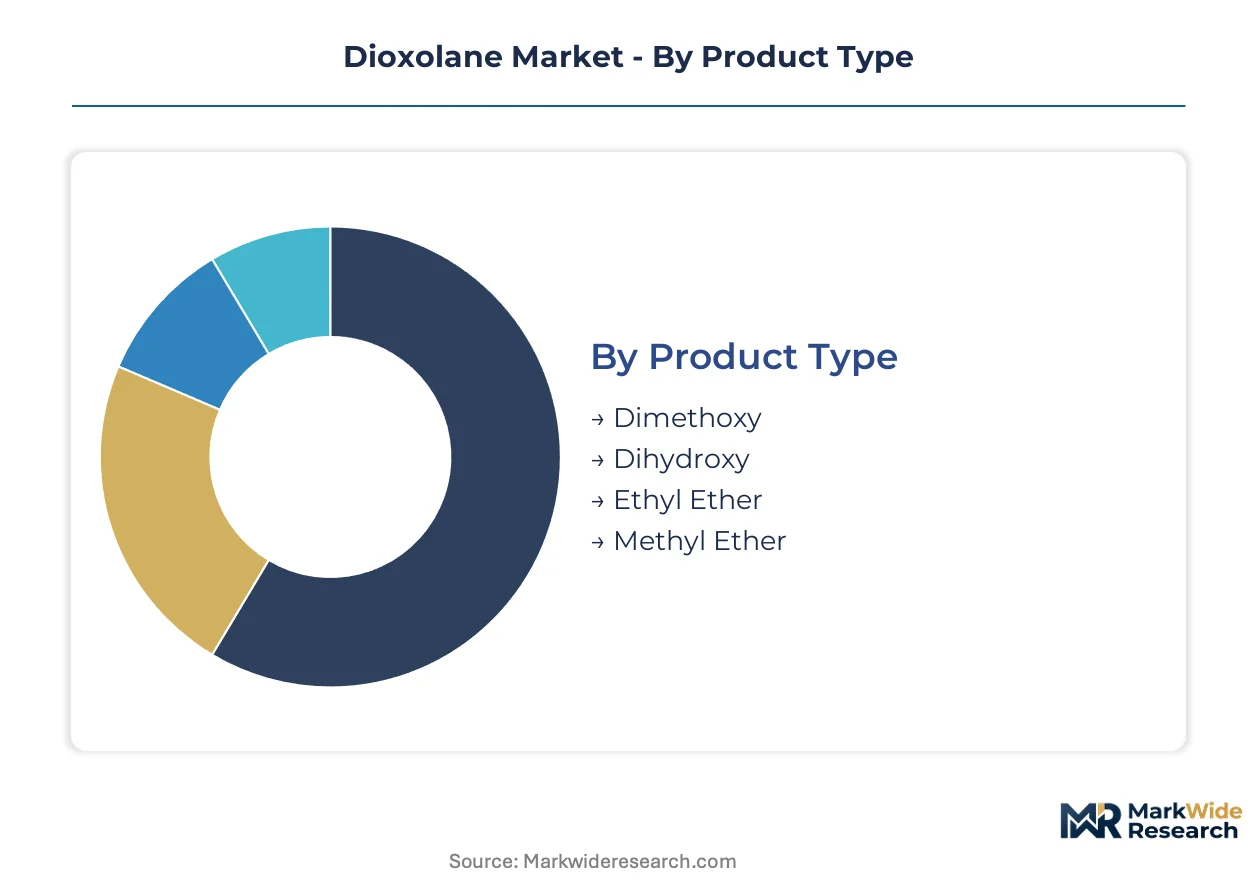
Dioxolane segmentation reveals how purity gradients and end-use specifications fragment supply chains. Battery electrolyte blenders, pharmaceutical formulators, and agrochemical manufacturers each impose distinct certification burdens that reshape producer economics across product tiers.
Product Type:
Cost tier differentiation separates electronics-grade specifications from commodity solvent markets, with purity thresholds determining margin capture.
- Dimethoxy:This variant carries dual methoxy substituents on the dioxolane ring, delivering superior hydrophobicity and thermal stability for lithium-ion battery electrolyte co-solvents. Korean and Chinese cell manufacturers specify sub-50 ppm moisture content for cylindrical battery formulations, compressing supplier qualification timelines.
- Methyl Ether:Single ether substitution produces a cost-optimized solvent for agrochemical intermediate synthesis and industrial cleaning applications. Brazilian crop protection manufacturers absorb technical-grade volumes through regional distribution hubs serving pyrethroid production lines.
- Dihydroxy:Hydroxyl-functionalized variants serve polymer plasticizer and crosslinker chemistry with reactive site availability.
- Ethyl Ether:Extended alkyl chain modification targets specialty fragrance and flavor intermediate markets with controlled volatility profiles.
Dimethoxy commands the established base. The steepest expansion runs through Methyl Ether.
Application:
Application segmentation tracks how functional role determines regulatory exposure and customer stickiness across downstream industries.
- Solvent:Polar aprotic characteristics enable dioxolane to dissolve ionic salts and organic substrates across battery electrolyte and pharmaceutical reaction media. EPA National Emission Standards for Hazardous Air Pollutants are accelerating substitution away from methylene chloride in metal finishing degreasing operations, pulling technical-grade volumes through Midwestern US coating supply chains.
- Intermediate:Acetal chemistry downstream into herbicide actives and polymer modifiers registers structural expansion as Brazilian and Indian crop protection manufacturers scale pyrethroid synthesis capacity.
- Reagent:Grignard reaction media and organometallic synthesis applications compete with incumbent tetrahydrofuran in conservative GMP environments.
- Extractant:Selective separation applications in natural product isolation and purification processes leverage dioxolane's water miscibility and tunable polarity.
Solvent anchors volume consumption. Intermediate is climbing the fastest.
End User:
End user concentration exposes producers to divergent certification cycles and procurement power structures across regulated industries.
- Electronics:Lithium battery electrolyte blenders impose the most stringent purity protocols, with Karl Fischer titration certificates traceable to national metrology institutes required for qualification. Chinese gigafactory concentration in the Yangtze River Delta enables direct long-term offtake agreements that bypass traditional chemical distribution.
- Pharmaceuticals:GMP-compliant solvent specifications demand EMA and FDA drug master file submissions with 18-36 month validation timelines, freezing supplier switches until regulatory packages achieve active status.
- Agrochemicals:Technical-grade consumption flows through regional distributors serving Brazilian and Indian crop protection manufacturing.
- Petrochemicals:Process solvent and extraction applications in refinery and downstream chemical operations absorb commodity-tier volumes.
Electronics commands premium positioning. Pharmaceuticals is expanding most quickly.
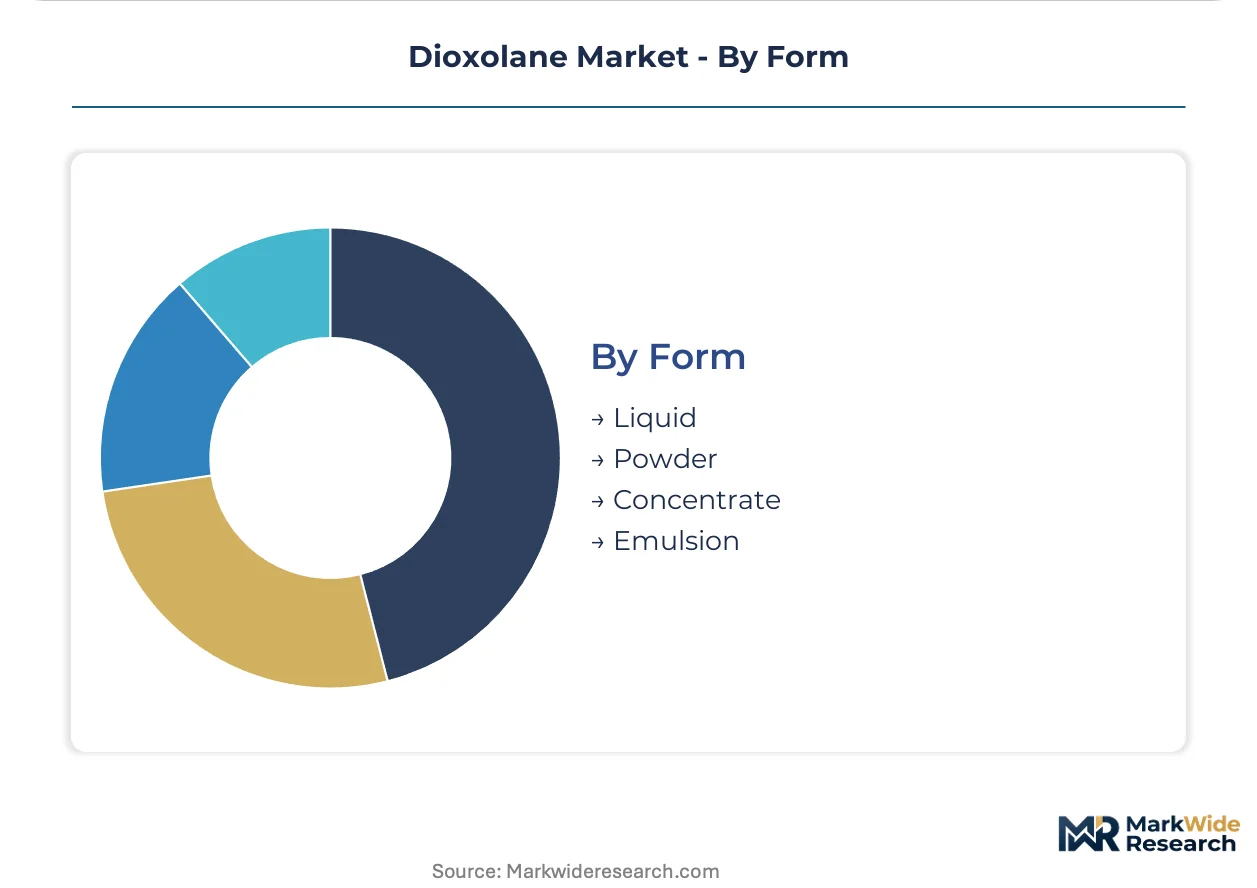
Form:
Physical state segmentation reflects logistics economics and downstream handling requirements across concentrated and diluted supply modes.
- Liquid:Standard bulk delivery format for solvent and reagent applications with established tanker and drum logistics infrastructure.
- Concentrate:Reduced water content formulations minimize shipping costs for battery electrolyte blenders with in-house dilution capability.
- Powder:Solid-state handling for specialized polymer additive and pharmaceutical formulation applications requiring precise dosing control.
- Emulsion:Aqueous dispersion formats for controlled-release agrochemical and coating applications with compatibility requirements.
Liquid commands the established base. Concentrate is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Chinese chemical producers dominate international dioxolane trade, while import-dependent battery electrolyte blenders in Europe and North America scramble to requalify supply chains. The regional map reveals stark asymmetries between production concentration and consumption dispersion.
China
Lithium battery electrolyte manufacturers in the Yangtze River Delta absorb the majority of domestic 1,3-dioxolane output for cylindrical and prismatic cell formulations. SAMR national chemical standards enforce purity thresholds that separate battery-grade from technical-grade specifications. Shandong and Jiangsu provinces host approximately two-thirds of global nameplate capacity, with producers scaling membrane pervaporation investments to compress dehydration energy costs.
Germany
Pharmaceutical formulators in the Rhine-Ruhr corridor source high-purity grades for GMP-compliant reaction media under EMA drug master file protocols. REACH substance restriction frameworks disqualify traditional ether solvents from formulation contracts, redirecting procurement toward cyclic acetals with documented impurity profiles. BASF Chemical Intermediates leverages its integrated C1 chemistry platform in Ludwigshafen to sustain cost-advantaged regional supply.
United States
Midwestern coating manufacturers accelerate solvent qualification programs to preempt EPA National Emission Standards for Hazardous Air Pollutants enforcement windows in 2025-2026. The Inflation Reduction Act's domestic content incentives drive battery cell and electrolyte producers to requalify North American dioxolane supply chains for electric vehicle tax credit eligibility. Ohio and Michigan gigafactory concentration enables dedicated logistics infrastructure for direct long-term offtake agreements.
South Korea
Battery original equipment manufacturers negotiate five-year supply contracts with fixed-volume minimums and indexed pricing, bypassing traditional chemical distributors. Korean cell producers impose Karl Fischer titration certificates traceable to national metrology institutes for electrolyte solvent qualification. The Busan-Ulsan industrial corridor concentrates demand from cylindrical battery output scaling.
Brazil
Crop protection manufacturers expand acetal chemistry downstream into pyrethroid synthesis and herbicide active ingredients, pulling technical-grade dioxolane through regional distribution networks. ANVISA agrochemical registration requirements shape import specifications for formulated intermediates. São Paulo state anchors demand concentration for agrochemical intermediate applications.
Dioxolane Market Vendor Landscape
On the supply side, the industry is bifurcated between integrated petrochemical majors with captive formaldehyde supply and specialized acetal producers dependent on merchant feedstock markets. Three archetypes dominate competitive positioning: integrated C1 chemistry platforms, pharmaceutical-grade certification specialists, and scaled Asian commodity producers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with membrane pervaporation technology licensing emerging as a secondary vector for technology differentiation.
Within the integrated chemistry tier, BASF Chemical Intermediates and Merck KGaA exemplify divergent strategic positions—BASF anchoring cost-advantaged supply through backward integration into methanol and formaldehyde, Merck occupying the pharmaceutical-grade certification niche through stringent quality protocols. Hefei TNJ Chemical Industry Co. Ltd. represents the scaled Asian commodity archetype, dominating regional supply to battery electrolyte producers with concentrated 1,3-dioxolane output from Jiangsu province.
| Leading Market Players |
|---|
| BASF Chemical Intermediates |
| Lambiotte & Cie S.A |
| Merck KGaA |
| Honeywell |
| Kairav Chemofarbe Industries Ltd. |
| TCI Chemicals Pvt. Ltd. |
| Chemdyes Corporation |
| Hefei TNJ Chemical Industry Co. Ltd. |
| Henan DaKen Chemical Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Shandong and Jiangsu province producers control roughly two-thirds of global 1,3-dioxolane nameplate capacity, anchoring margin capture in battery-grade specifications where Korean and Chinese electrolyte blenders absorb premiums for sub-50 ppm moisture certification.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing, with Korean cell manufacturers negotiating five-year agreements carrying fixed-volume minimums and indexed pricing tied to formaldehyde feedstock costs. Three-tier pricing structure across battery-grade, pharmaceutical-grade, and technical-grade levels separates electronics specifications certified to Karl Fischer titration standards from commodity solvent tiers. Cost compression in technical-grade methyl ether derivatives is intensifying because Brazilian agrochemical distributors consolidate procurement volumes. Battery electrolyte blenders show least price sensitivity given qualification timelines spanning 18-36 months, while Midwestern US coating manufacturers exhibit highest sensitivity as they substitute dioxolane for phased-out methylene chloride.
Supply Chain Analysis
Extended payment terms from Chinese producers to merchant formaldehyde suppliers are compressing working capital cycles for non-integrated acetal manufacturers. Manufacturing concentrates in China, Germany, and the United States, with feedstock supply resting on methanol pricing differentials and natural gas cost structures in each production cluster. Raw material dependencies span formaldehyde, ethylene glycol, and membrane pervaporation module components for dehydration infrastructure. Single-source vulnerability runs through Shandong-Jiangsu production corridors, where export licensing and shipping bottlenecks threaten European and North American electrolyte blenders. Distribution runs through direct long-term offtake agreements with battery OEMs, bypassing traditional chemical distributors in the Yangtze River Delta and Great Lakes manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dioxolane sits in early-cycle expansion as solid-state battery electrolyte developers evaluate acetal derivatives for interface modification, extending addressable demand beyond conventional lithium-ion formulations.
For Market Incumbents: Harden membrane pervaporation technology positions through exclusive licensing arrangements with German and Japanese specialty engineering firms, blocking competitor access to sub-3 kWh dehydration economics. Secure captive formaldehyde supply through backward integration into methanol or long-term feedstock offtakes, insulating margin structures from C1 volatility that compresses non-integrated producers. For New Entrants and Emerging Players: North American battery electrolyte qualification represents the most penetrable entry point, where IRA domestic content incentives are forcing requalification of supply chains previously dependent on Chinese imports. Target Ohio and Michigan gigafactory corridors with dedicated logistics infrastructure and Karl Fischer certification packages traceable to NIST metrology standards, bypassing the 18-36 month FDA/EMA validation timelines that freeze pharmaceutical-grade switches. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Chinese commodity producers in Jiangsu province lacking pharmaceutical-grade certification infrastructure but holding scaled 1,3-dioxolane output. Five-to-ten year viability hinges on solid-state battery commercialization timelines and acetal derivative adoption in polymer electrolyte interfaces. Signal to monitor: Korean OEM electrolyte specification releases for dioxolane co-solvent inclusion in cylindrical cell formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Pervaporation Licensing | Collapses dehydration energy costs from 8-12 kWh to below 3 kWh for battery-grade output. |
| Backward Integration into Formaldehyde | Captive C1 feedstock supply insulates margin structures from methanol price volatility. |
| Pharmaceutical-Grade Certification Investment | FDA drug master file submissions unlock 18-36 month GMP-compliant solvent procurement cycles. |
| North American Supply Chain Requalification | IRA domestic content thresholds redirect battery electrolyte procurement from Chinese imports. |
| Long-Term Offtake Agreement Structuring | Korean and Chinese cell manufacturers negotiate five-year contracts with fixed-volume minimums. |
Methodological Framework
Initial hypotheses were tested against primary input from plant managers at Shandong and Jiangsu production facilities, procurement leads at Korean battery OEMs, and technical R&D directors at electrolyte formulation houses, then refined against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated chemical majors, and SAMR national chemical standards documentation. Bottom-up capacity and consumption estimates were triangulated with top-down market sizing derived from downstream application demand modeling.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by grade tier, end-use industry, packaging format, and regional production hub, with CAGRs derived from electrolyte solvent specification evolution and agrochemical intermediate pull-through in Brazilian and Indian markets. Forecast inputs incorporated membrane pervaporation adoption curves, IRA domestic content incentive implementation, and REACH substance restriction phase-out timelines.
Macroeconomic conditions sit as an overlay; deviation in methanol pricing spreads, natural gas cost differentials, or lithium-ion battery capacity buildout schedules would shift the trajectory. Forecasts reflect documented assumptions on solid-state battery commercialization timelines and regulatory enforcement windows. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Acrylonitrile Market
Organic Chemicals
US Humate Market
Organic Chemicals
N-Pentane Market
Organic Chemicals
Global Carboxylic Acid Market
Organic Chemicals
Aliphatic Amines Market
Organic Chemicals
Pyridine Derivatives Market
Organic Chemicals
Organic Peroxide Market
Organic Chemicals
Chloroacetyl Chloride Market
Organic Chemicals
Cyclic Ketones Market
Organic Chemicals
Europe Cycloalkanes Market
Organic Chemicals
Anisole Derivatives Market
Organic Chemicals
Oryzenin Market
Organic Chemicals
North America Phenol Market
Organic Chemicals
4-Tert-Amylphenol Market
Organic Chemicals
Europe Lactic Acid Market
Organic Chemicals
2,6-Dichloro Aniline Market