
 Rubber Tapes Market | 2026-2036
Rubber Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Tapes Market Outlook
Self-fusing silicone rubber formulations is reconfiguring how high-voltage electrical insulation systems are assembled across industrial and transportation applications. 3M Company leverages its polymer science infrastructure to sustain patent-protected tape architectures for extreme temperature environments. Nitto Denko Corporation anchors its competitive position through backward integration into specialty rubber compounding operations in Japan and Southeast Asia.
Rubber tapes are pressure-sensitive adhesive strips manufactured from synthetic or natural rubber elastomers, typically calendered to thicknesses between 0.1 mm and 2.0 mm and engineered for electrical insulation, sealing, or surface protection duties. Electrical-grade rubber tapes must meet dielectric strength specifications exceeding 10 kV/mm for medium-voltage cable jointing applications. The electrical product type commands the dominant margin pool due to certification requirements and specification-driven procurement, while double-sided rubber tapes represent the fastest-expanding category as automotive lightweighting demands structural bonding without mechanical fasteners. Masking tapes compete primarily on price and regional logistics efficiency, with limited differentiation beyond temperature resistance ratings.
FDA regulations govern rubber tape compositions used in food processing equipment and packaging machinery, restricting extractable substances in adhesive layers. EPA oversight of solvent emissions from tape coating operations shapes manufacturing location decisions and capital expenditure planning for domestic production. OSHA workplace exposure limits for volatile organic compounds influence plant design and automation investments. Stakeholders must monitor evolving flammability standards from UL and IEC as electrification expands rubber tape deployment into battery thermal management and charging infrastructure systems.
Market Dynamics
Automotive electrification is compressing specification cycles for high-voltage insulation materials, forcing rubber tape suppliers to synchronize R&D roadmaps with battery platform development timelines at OEM engineering centers.
Growth Catalysts
- EV Battery Thermal Management:Electric vehicle manufacturers are specifying multi-layer rubber tape laminates for cell-to-cell insulation and pack-level fire barriers, creating specification-locked demand pools.
- REACH Chemical Restrictions:European ECHA substance evaluations are accelerating reformulation investments toward solvent-free adhesive systems, advantaging early movers with compliant product lines.
- Grid Modernization Infrastructure:Utility investments in medium-voltage cable networks across China, Germany, and the United States are expanding procurement volumes for electrical-grade splicing tapes.
Market Restraints
- Natural Rubber Price Volatility:Thai and Indonesian latex supply disruptions transmit directly to compounding cost structures, compressing margins for non-integrated manufacturers.
- Specialty Silicone Feedstock Concentration:Dow and Wacker Chemie control dominant shares of medical-grade silicone monomer supply, creating bottleneck risks for high-performance tape formulations.
- Acrylic Adhesive Substitution:UV-cured acrylic tapes are capturing share in low-temperature electrical applications where rubber's pliability advantage diminishes.
Strategic Opportunities
- India Industrial Electrification:BIS certification requirements for electrical insulation materials are creating localized supply gaps that imported specialty tapes can fill.
- Solid-State Battery Assembly:Dry electrode manufacturing processes require pressure-sensitive tapes compatible with ceramic-coated separators and sulfide electrolytes.
- US Inflation Reduction Act:Domestic content bonuses for EV and battery manufacturing are incentivizing tape production localization near Ohio, Michigan, and South Carolina assembly plants.
Industry Challenges
- Polymer Compounding Expertise Scarcity:Formulation chemists capable of balancing dielectric performance, flame retardancy, and processability command premium compensation and extended recruitment cycles.
- Multi-Jurisdiction Certification Overlap:UL 510, IEC 60454, and GB/T 20631 testing protocols impose redundant validation costs for products serving transnational OEM supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Tapes Market |
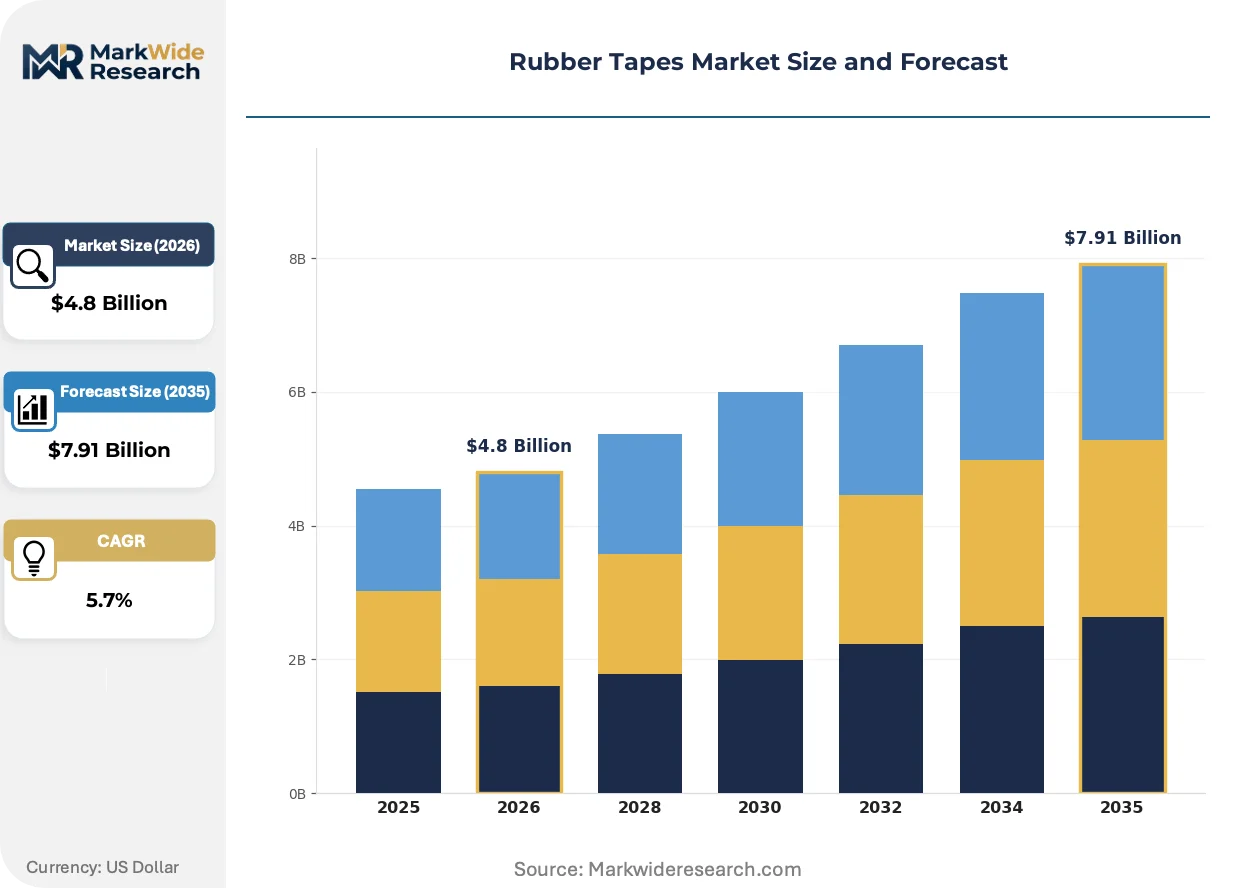
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrical, Masking, Duct, Double-Sided Application: Construction, Automotive, Electronics, Packaging Adhesive Type: Rubber-Based, Acrylic-Based, Silicone-Based, Hot Melt End User: Manufacturers, Contractors, Retailers, Consumers |
| Companies Covered | Scapa Group plc, tesa SE, Intertape Polymer Group Inc., Berry Global Inc., HellermannTyton Company, 3M Company, Nitto Denko Corporation, Lintec Corporation, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Tapes Market Strategic Shifts
Material science advances and regulatory chemistry constraints are converging to redefine performance benchmarks across electrical, automotive, and industrial rubber tape applications.
Self-fusing silicone formulations are eliminating the need for heat-shrink or resin-based sealing in medium-voltage cable joints. Utility contractors in Germany and the United States are specifying these tapes for live-line working conditions. Heat-activated bonding chemistry is rendering obsolete mechanical clamping systems in underground distribution networks.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons are compelling reformulation of traditional rubber-resin adhesives. Tape manufacturers serving European automotive OEMs must validate extractable substance profiles below 0.001% thresholds. Medical device and food equipment segments face parallel constraints under EFSA migration limits, driving solvent-free coating line investments.
Specification-driven procurement is consolidating vendor pools at tier-one automotive and energy accounts. Buyers are unbundling material supply from application engineering services, pressuring mid-size tape converters to develop in-house technical support capabilities. This pattern is most pronounced in China, where State Grid Corporation and CATL have reduced qualified supplier lists by half since 2022.
Rubber Tapes Market Segmentation
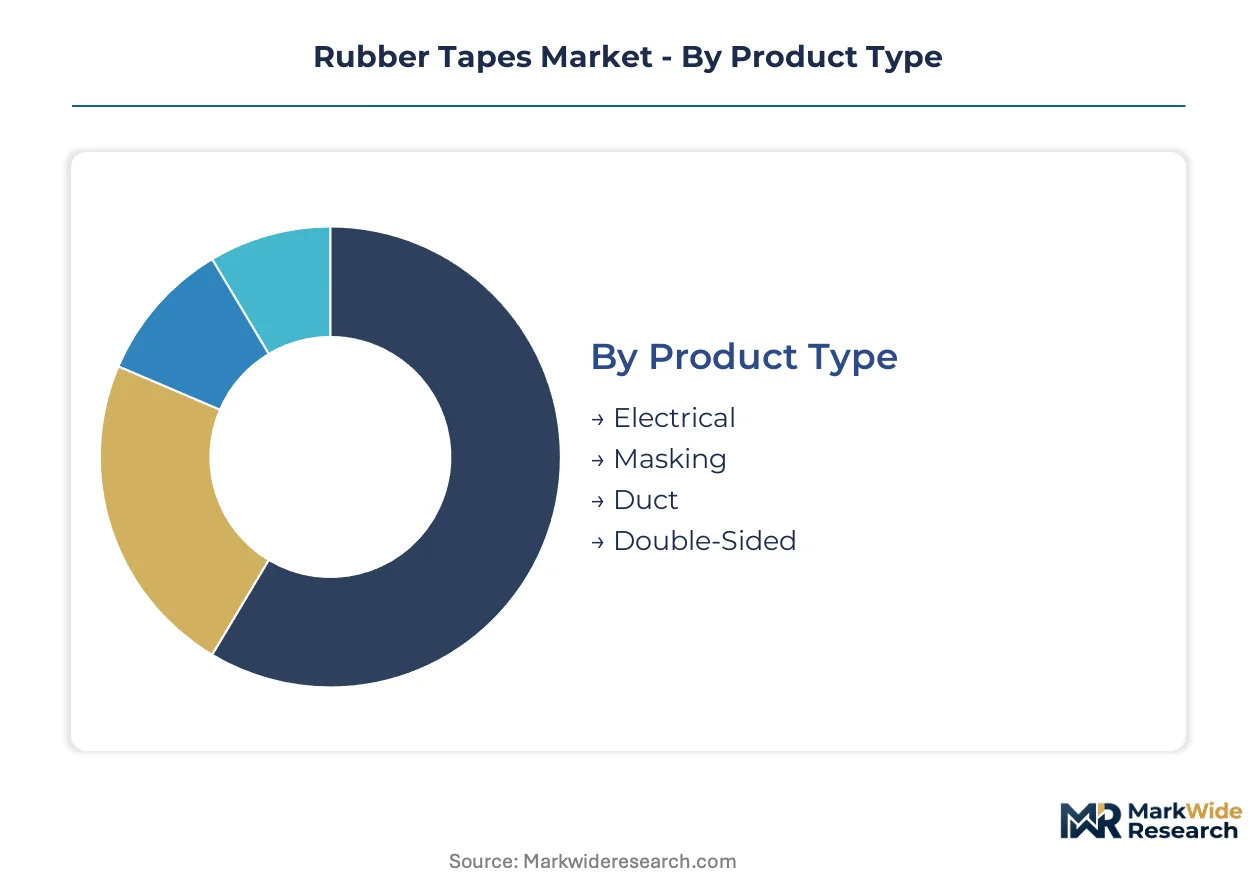
Rubber tape segmentation reveals how formulation chemistry and procurement channels create distinct margin profiles across the value chain. Specification intensity varies dramatically between electrical infrastructure and consumer retail channels, forcing suppliers to maintain parallel product architectures.
Product Type:
Mature electrical-grade formulations coexist with emerging structural bonding categories as electrification reshapes demand composition.
- Electrical:Calendered synthetic rubber laminates meeting dielectric strength thresholds above 10 kV/mm for medium-voltage cable jointing. State Grid Corporation procurement in China and utility modernization programs in Germany concentrate demand for certified splicing tapes, with UL 510 and IEC 60454 validation creating specification-locked supply relationships.
- Double-Sided:Pressure-sensitive adhesive constructions enabling structural bonding without mechanical fasteners in automotive lightweighting. Cell-to-cell insulation and pack-level fire barriers for electric vehicle batteries at CATL and BYD manufacturing facilities in China represent the steepest demand expansion trajectory.
- Masking:Temperature-resistant formulations for surface protection during industrial coating and painting operations.
- Duct:Heavy-duty polyethylene-laminated constructions for HVAC sealing and general repair applications.
Electrical-grade products handle the majority of throughput; double-sided configurations are climbing the fastest on share.
Application:
Cost tier differentiation separates specification-driven industrial procurement from price-sensitive consumer channels.
- Automotive:Multi-layer rubber tape laminates for battery thermal management, wiring harness bundling, and interior trim attachment. OEM engineering centers in Stuttgart, Detroit, and Shanghai are compressing qualification cycles as platform electrification accelerates.
- Construction:Weatherproof sealing and temporary protection for building envelopes, HVAC ductwork, and underground utilities. Infrastructure stimulus programs in the United States and Germany are expanding procurement volumes for contractor-grade products.
- Electronics:Precision die-cut tapes for component mounting, EMI shielding, and thermal interface management.
- Packaging:General-purpose carton sealing and reinforcement with limited performance differentiation.
Automotive applications command premium pricing tiers; construction represents the highest absolute volume channel.
Adhesive Type:
Supply concentration in specialty feedstocks constrains formulation flexibility for high-performance segments.
- Silicone-Based:Self-fusing formulations eliminating heat-shrink requirements in medium-voltage cable joints. Dow and Wacker Chemie control dominant shares of medical-grade silicone monomer supply, creating feedstock bottleneck risks for tape manufacturers serving live-line working conditions in German and US utility markets.
- Rubber-Based:Traditional solvent-borne natural and synthetic rubber adhesives facing REACH Annex XVII reformulation pressure. ECHA substance evaluations on polycyclic aromatic hydrocarbons are accelerating capital investment in solvent-free coating lines.
- Acrylic-Based:UV-cured systems capturing share in low-temperature electrical applications where rubber pliability advantages diminish.
- Hot Melt:Thermoplastic formulations for high-speed packaging and disposable product assembly.
Silicone-based chemistry anchors the premium tier; rubber-based formulations retain volume leadership despite regulatory headwinds.
End User:
Customer type determines service intensity, with specification engineering separating industrial accounts from transactional retail.
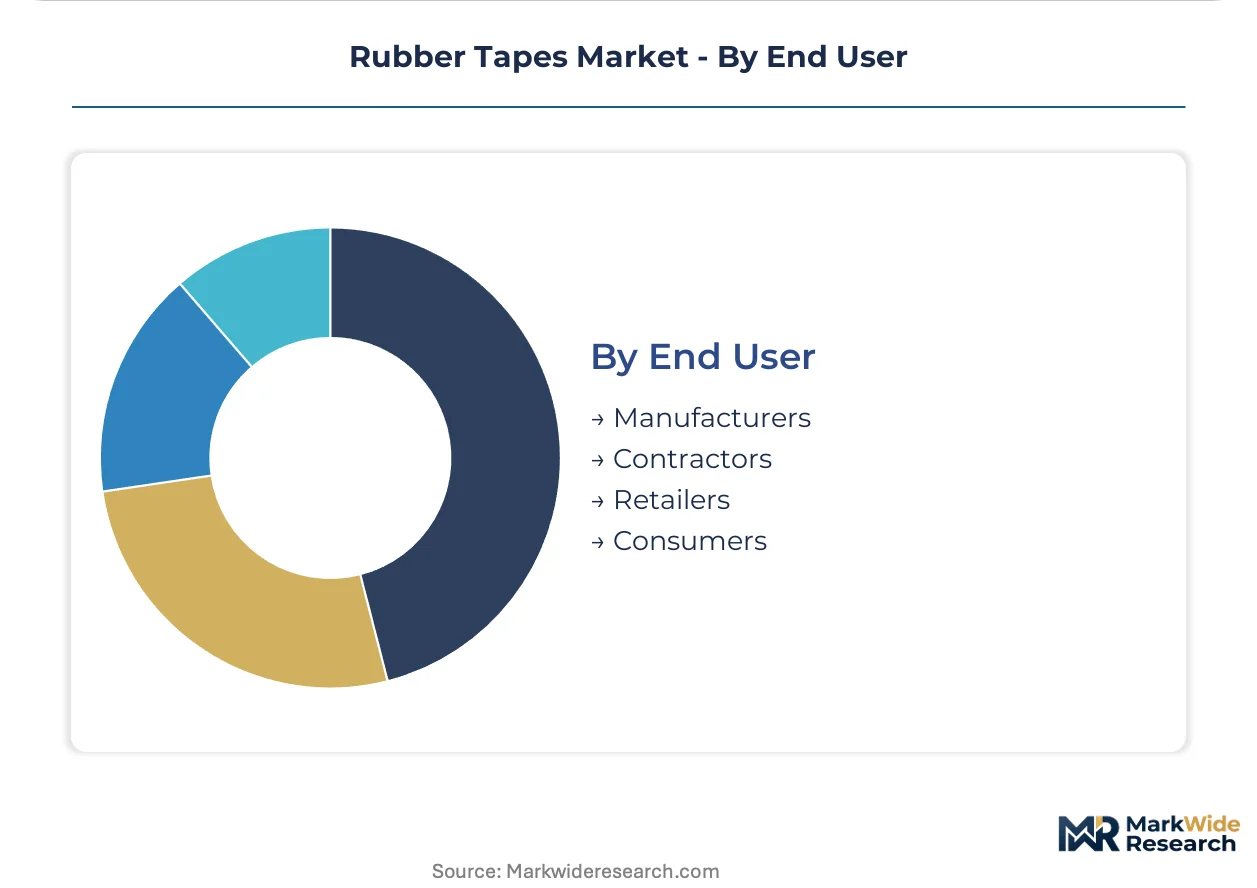
- Manufacturers:Tier-one automotive and energy OEMs unbundling material supply from application engineering services. CATL and State Grid Corporation have reduced qualified supplier lists by half since 2022, consolidating procurement around vendors with in-house technical support capabilities.
- Contractors:Utility and construction trades sourcing through distributor networks with regional logistics efficiency as the primary selection criterion.
- Retailers:Big-box and specialty channels serving DIY and maintenance-repair-operations demand with limited product differentiation.
- Consumers:Household repair and craft applications representing the most price-elastic demand segment.
Manufacturers generate the dominant margin pool; contractors represent the fastest-expanding service requirement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in rubber tape formulations are reshaping regional manufacturing footprints, with net-importing markets accelerating localization incentives and feedstock-rich jurisdictions consolidating compounding capacity.
China
CATL and BYD battery manufacturing complexes in Fujian and Guangdong provinces are absorbing multi-layer rubber tape laminates for cell-to-cell insulation at unprecedented scale. MIIT industrial standards for electrical insulation materials are tightening certification requirements for domestic suppliers. The Yangtze River Delta cluster around Shanghai hosts the densest concentration of tape converting operations serving State Grid Corporation procurement.
Germany
Automotive OEM engineering centers in Stuttgart and Munich are compressing qualification cycles for high-voltage insulation materials as platform electrification accelerates. ECHA REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons are compelling solvent-free adhesive system investments. The Ruhr industrial corridor maintains specialized compounding capacity for utility-grade splicing tapes serving live-line working conditions.
United States
IRA domestic content bonuses for EV and battery manufacturing are incentivizing tape production localization near Ohio, Michigan, and South Carolina assembly plants. EPA oversight of solvent emissions from coating operations shapes capital expenditure planning for domestic production. The Texas Gulf Coast petrochemical corridor supplies synthetic rubber feedstocks to regional tape manufacturers.
Japan
Specialty rubber compounding operations in Osaka and Kobe prefectures anchor backward integration strategies for high-performance tape formulations. METI industrial policy supports domestic production of electrical-grade materials for grid modernization. The Chubu region around Nagoya concentrates precision die-cutting capabilities for electronics applications.
India
BIS certification requirements for electrical insulation materials are creating localized supply gaps that imported specialty tapes can fill. CEA grid expansion programs are expanding procurement volumes for medium-voltage cable jointing products. The Maharashtra-Gujarat industrial corridor is emerging as a conversion hub for contractor-grade construction tapes.
Rubber Tapes Market Competitive Environment
On the supply side, the industry is tiered between integrated polymer science conglomerates, specialized tape converters, and regional fabricators serving price-sensitive channels. Three strategic archetypes dominate: patent-protected formulation leaders with captive R&D infrastructure, backward-integrated compounders controlling specialty elastomer supply, and distributor-aligned converters competing on logistics efficiency. Capacity expansion near automotive battery clusters and strategic partnerships with utility procurement entities represent the dominant competitive moves.
Within the integrated conglomerate tier, 3M Company and Nitto Denko Corporation exemplify archetypes built on polymer science infrastructure and backward integration into specialty compounding respectively. Among diversified materials groups, Berry Global Inc. and Avery Dennison Corporation occupy positions spanning multiple adhesive tape categories. The specialist tier includes Scapa Group plc and HellermannTyton Company, representing focused positioning in electrical and industrial binding applications.
| Leading Market Players |
|---|
| Scapa Group plc |
| tesa SE |
| Intertape Polymer Group Inc. |
| Berry Global Inc. |
| HellermannTyton Company |
| 3M Company |
| Nitto Denko Corporation |
| Lintec Corporation |
| Avery Dennison Corporation |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta cluster around Shanghai concentrates converting capacity for electrical-grade tapes, with State Grid Corporation procurement volumes translating directly into pricing leverage for qualified domestic suppliers serving medium-voltage cable jointing applications.
Pricing Analysis
Current-generation solvent-borne rubber adhesives command premium positioning against next-generation solvent-free formulations still scaling production, while legacy natural rubber compounds face price erosion from acrylic substitution in low-temperature applications. Three-tier pricing structure across UL 510 certified premium, standard industrial-grade, and economy masking tiers reflects certification investment recovery and dielectric performance differentiation. Cost compression in standard electrical grades is intensifying because Thai latex supply volatility transmits directly to non-integrated compounders. Retail DIY channels exhibit highest price sensitivity; specification-locked automotive OEM procurement demonstrates lowest elasticity due to platform qualification requirements.
Supply Chain Analysis
Extended payment terms from tier-one automotive and utility buyers now stretch 90-120 days, forcing mid-size converters toward supply-chain finance facilities anchored by distributor credit lines. Raw material sourcing concentrates in Thailand and Indonesia for natural rubber latex, China for synthetic rubber feedstocks, and Germany for medical-grade silicone monomers. Specialty silicone monomer supply rests on Dow and Wacker Chemie production, creating single-source vulnerability for high-performance self-fusing formulations. Distribution runs through authorized distributor networks for electrical and automotive specification grades, with big-box retail capturing consumer masking and duct tape volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat opportunity where regulatory entrenchment through multi-jurisdiction certification creates switching costs that lock out unqualified competitors from tier-one OEM and utility procurement.
For Market Incumbents: Entrench specification-locked relationships by accelerating solvent-free coating line investments ahead of REACH Annex XVII enforcement timelines, while defending margin position through captive compounding capacity additions near CATL and BYD battery manufacturing complexes to compress logistics costs and qualification cycles for cell-to-cell insulation laminates. For New Entrants and Emerging Players: Establish a beachhead in India's BIS-certified electrical insulation gap by importing specialty splicing tapes for CEA grid expansion programs, targeting contractor-grade construction applications in the Maharashtra-Gujarat corridor where localized supply shortages create procurement urgency without requiring immediate OEM platform qualification. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors backward-integrated compounders with captive silicone rubber formulation capabilities, as solid-state battery assembly requirements for ceramic-compatible pressure-sensitive tapes extend the viable investment window. Acquisition targets should demonstrate UL 510 and IEC 60454 certification infrastructure with technical service capabilities. The signal to watch is OEM unbundling of material supply from application engineering, which will consolidate procurement around vendors with in-house support capabilities and eliminate pure-play converters.| Strategic Initiative | Industry Significance |
|---|---|
| Solvent-Free Coating Line Investment | REACH Annex XVII compliance secures European automotive OEM qualification for rubber-resin adhesive tapes. |
| Backward Integration into Specialty Compounding | Captive silicone rubber production hedges Dow and Wacker Chemie monomer supply concentration risks. |
| Localization Near Battery Manufacturing Clusters | Proximity to CATL and BYD facilities in Fujian and Guangdong compresses logistics costs and platform qualification cycles. |
| Multi-Jurisdiction Certification Investment | UL 510, IEC 60454, and GB/T 20631 validation opens specification-locked procurement at State Grid Corporation and tier-one automotive accounts. |
| Technical Service Capability Buildout | In-house application engineering addresses OEM unbundling trends and defends margin position against pure-play converters. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with tape formulation chemists, OEM platform engineers at Stuttgart and Detroit engineering centers, utility procurement officers at State Grid Corporation, and distributor channel managers; combined with secondary validation against customs and trade data, SEC 10-K filings from diversified materials groups, MIIT industrial standards documentation, and ECHA substance evaluation databases. Bottom-up demand modeling from end-use application volumes and top-down supply-side capacity assessments were triangulated to converge on market size estimates.
Forecast inputs considered product type segmentation across electrical, double-sided, masking, and duct configurations; adhesive chemistry differentiation between silicone, rubber, acrylic, and hot-melt systems; and end-user channel structure spanning manufacturers, contractors, retailers, and consumers. CAGRs were derived from elasticity-adjusted demand projections across the projection horizon, incorporating EV battery thermal management adoption curves, grid modernization infrastructure spend trajectories, and REACH regulatory compliance timelines as industry-specific forecast inputs.
Sensitivities concentrate around natural rubber latex supply disruption scenarios, acrylic adhesive substitution acceleration in low-temperature electrical applications, and solid-state battery manufacturing process standardization timelines. Forecasts reflect assumptions about regulatory enforcement consistency, OEM platform electrification roadmaps, and feedstock supply concentration stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Styrene Butadiene Rubber (E-SBR and S-SBR) Market
Rubber
Rubber Bulb Seals Market
Rubber
Medical Rubber and Balloon Products Market
Rubber
Cellular Rubber Market
Rubber
Europe Neoprene Market
Rubber
Rubber Sheets Market
Rubber
Chloro-Sulfonated Polyethylene Market
Rubber
Styrene Butadiene (SB) Latex Market
Rubber
Global Crumb Rubber Market
Rubber
Rubber Wear Liners Market
Rubber
EMEA and Asia Pacific Electrical Insulating Rubber Gloves Market
Rubber
Synthetic Polyisoprene Rubber Market
Rubber
Rubber Choppers Market
Rubber
Sterile Rubber Stopper Market
Rubber
Rubber Flooring Market
Rubber
Rubber Splicing Tape Market