
 Fast Curing Nitrile Butadiene Rubber (NBR) Market | 2026-2036
Fast Curing Nitrile Butadiene Rubber (NBR) Market Size, Share, and Industry Trends Forecast 2026-2036
Fast Curing Nitrile Butadiene Rubber (NBR) Market Foresight
Project finance for specialty chemical capacity is fragmenting competitive access across the Fast Curing NBR value chain. ARLANXEO leverages its integrated butadiene feedstock position to sustain margin stability in European automotive seal supply. KUMHO PETROCHEMICAL anchors Northeast Asian demand through dedicated elastomer complexes serving industrial hose makers. Zeon Corporation specializes in high-ACN grades that differentiate its portfolio for oil-resistant gasket applications.
Fast Curing Nitrile Butadiene Rubber denotes a sulfur-vulcanizable elastomer containing 18-50% acrylonitrile by mass, formulated with accelerated cure systems that reduce press cycle times to under three minutes at 160-180°C. The material delivers fuel, oil, and abrasion resistance for dynamic seals, hoses, and precision-molded components in powertrain and fluid-handling systems. Sheet stock dominates volume flows for gasket converters serving maintenance-repair operations, while molded goods capture premium positioning through tight-tolerance automotive seal contracts. Adhesive solutions represent the fastest-expanding product type as manufacturers bond NBR substrates to metal housings in thermal management assemblies.
EPA emission standards and REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons are elevating formulation costs for cure package modifications across North American and European supply chains. China's GB standards for rubber product volatile organic compound content are forcing domestic compounders toward low-fogging accelerator systems. FDA 21 CFR 177.2600 compliance requirements for repeated-use rubber articles are reshaping medical device segment qualification protocols. Stakeholders must monitor regulatory divergence between jurisdictions to determine where localized compounding investments yield sustainable access.
Market Dynamics
Vehicle electrification is compressing cure-cycle requirements as thermal management assemblies multiply per platform, forcing compounders to reformulate accelerator packages for sub-three-minute press times without sacrificing oil resistance.
Growth Catalysts
- EPA emission standards:Tightening limits on volatile organic compounds from rubber processing are compelling seal manufacturers to adopt low-fogging fast-cure systems for underhood applications.
- Industrial hose fabricators:Maintenance-repair-operations demand for sheet stock is accelerating as energy infrastructure expansion in China drives localized compounding investments.
- Metal-to-rubber bonding:Thermal management module assembly is displacing mechanical fastening with adhesive-bonded NBR-to-aluminum interfaces in battery pack sealing.
Market Restraints
- Butadiene feedstock volatility:Crude-linked monomer pricing swings compress compounder margins during periods of petrochemical oversupply in Northeast Asia.
- REACH Annex XVII PAH limits:Polycyclic aromatic hydrocarbon restrictions on cure package components force reformulation investments that smaller European compounders cannot absorb.
- Fluorocarbon elastomer substitution:Perfluoroelastomer grades are displacing high-ACN NBR in extreme-temperature fuel cell sealing where service temperatures exceed 150°C.
Strategic Opportunities
- India automotive seal localization:PLI scheme incentives for advanced chemistry cell manufacturing are creating captive demand for fast-cure compounds in battery module gasketing.
- GB standards compliance:China's volatile organic compound content mandates for rubber products are forcing domestic compounders toward low-fogging systems that favor established fast-cure formulations.
- Digital compound matching:AI-driven rheology prediction is converging with cloud-based formulation databases to compress new grade qualification timelines for tier-two seal suppliers.
Industry Challenges
- Accelerated aging certification:FDA 21 CFR 177.2600 repeated-use rubber qualification protocols for medical device applications extend approval timelines beyond eighteen months.
- Legacy press fleet incompatibility:Temperature uniformity limitations in older compression molding equipment prevent adoption of 180°C cure profiles required for fastest cycle times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fast Curing Nitrile Butadiene Rubber (NBR) Market |
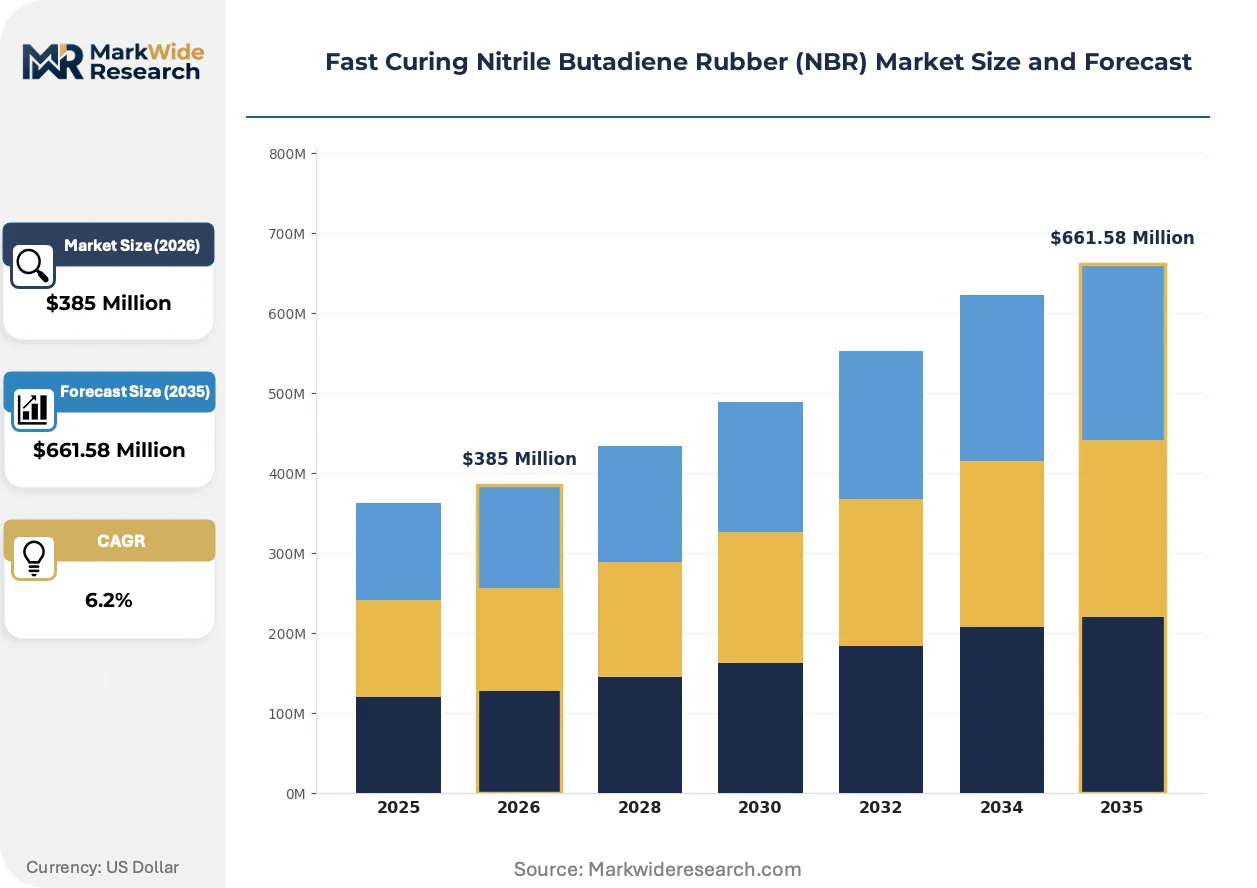
| Market Size in 2026 | $385 Million |
| Market Size in 2035 | $661.58 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Automotive Seals, Industrial Hoses, Gaskets, Medical Devices Product Type: Sheet Stock, Extruded Shapes, Molded Goods, Adhesive Solutions Delivery Mode: Bulk Supply, Custom Orders, Standard Inventory, Emergency Stock End User: Manufacturers, Retailers, OEMs, Distributors |
| Companies Covered | JSR Corporation, ARLANXEO, LANXESS AG, China Petroleum & Chemical Corporation, BASF SE, Zeon Corporation, KUMHO PETROCHEMICAL, Trinseo, LG Chem Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fast Curing Nitrile Butadiene Rubber (NBR) Market Shifts & Advancements
Digital formulation tools and regulatory chemistry restrictions are simultaneously compressing development cycles and expanding performance verification requirements across the fast-cure NBR value chain.
Ultra-fast sulfur-donor cure systems incorporating thiuram and dithiocarbamate hybrids are virtualizing traditional peroxide cure platforms in high-volume automotive seal production. Tier-one suppliers in Germany and Japan are adopting these systems for electric vehicle battery pack gaskets where metal adhesion and oil resistance must coexist. The technology is virtualizing the trade-off between cure speed and compression set resistance that previously segmented premium from standard grades.
REACH restrictions on N-nitrosamine-generating accelerators are forcing European compounders toward zinc-based cure system alternatives with higher raw material costs. The industrial consequence is margin compression for sheet stock producers serving maintenance-repair channels where price elasticity is highest. gasket fabricators in Italy and Poland are responding by consolidating purchase volumes to secure tiered pricing from integrated elastomer suppliers.
Specification-driven procurement is consolidating buyer power as automotive OEMs reduce their approved compounder lists from twelve to four suppliers per platform. Direct sourcing agreements between seal manufacturers and petrochemical producers are displacing distributor intermediaries in high-volume hose and belt applications. This concentration is most visible in China where domestic petrochemical capacity supports captive supply relationships with industrial rubber converters in Shandong and Jiangsu provinces.
Fast Curing Nitrile Butadiene Rubber (NBR) Market Segmentation
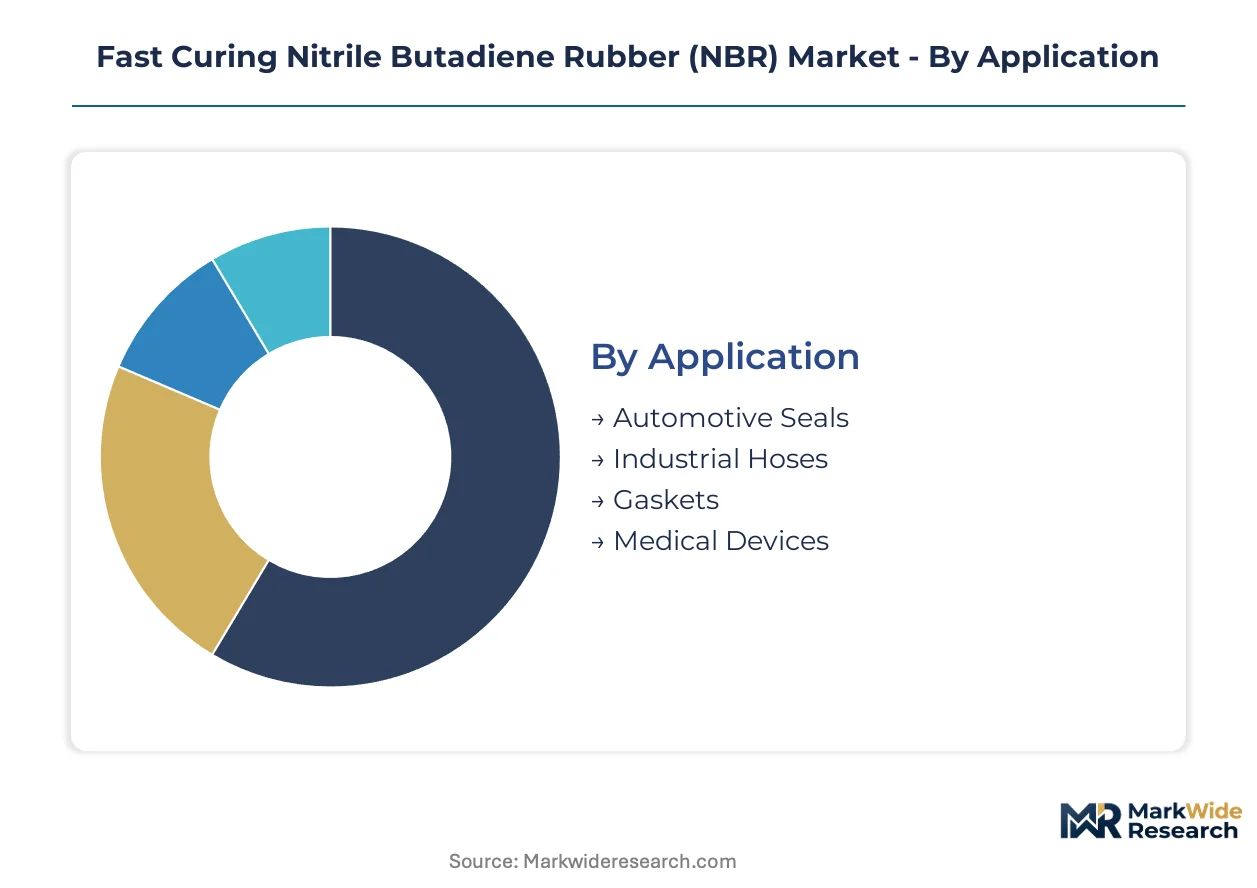
Segmentation in fast-curing NBR reveals how cure-speed specifications, delivery pressures, and regulatory compliance requirements fragment demand across incompatible supply chain configurations. Each dimension captures a distinct tension between compounder capability and buyer procurement priorities.
Application:
Application segmentation tracks where accelerated cure cycles translate into measurable throughput gains versus where oil resistance dominates specification requirements.
- Automotive Seals:Dynamic seals for powertrain and thermal management assemblies require sub-three-minute cure cycles at 160-180°C to match electrification-driven volume ramps. Tier-one suppliers in Germany and Japan prioritize metal-to-rubber adhesion properties for battery pack gasketing.
- Industrial Hoses:Reinforced hose constructions for fluid-handling systems balance abrasion resistance against extrusion throughput. Energy infrastructure expansion in China concentrates demand among Shandong and Jiangsu fabricators serving maintenance-repair channels.
- Gaskets:Sheet stock converters value consistency in compression set across batch lots for flange sealing applications.
- Medical Devices:FDA 21 CFR 177.2600 compliance requirements for repeated-use rubber articles extend qualification timelines for tubing and diaphragm producers.
Automotive Seals holds installed capacity. Medical Devices is rotating up the share rankings.
Product Type:
Product type segmentation reflects how manufacturing process constraints—press cycle time, extrusion speed, adhesive bonding—separate premium formulations from commodity grades.
- Sheet Stock:Calendered slabs for gasket fabricators dominate volume flows through maintenance-repair channels where price elasticity is highest. Italian and Polish converters consolidate purchase volumes to offset REACH-driven cure package cost inflation.
- Adhesive Solutions:Solvent-based and waterborne systems for NBR-to-metal bonding are gaining share fastest as thermal management modules displace mechanical fastening in electric vehicle assembly.
- Extruded Shapes:Continuous profiles for hose reinforcement and sealing beads serve industrial OEMs with long-run production schedules.
- Molded Goods:Precision-molded components for tight-tolerance automotive contracts capture premium positioning through direct sourcing agreements.
Sheet Stock commands the volume base. Adhesive Solutions is climbing the fastest.
Delivery Mode:
Delivery mode segmentation captures how inventory risk, customization depth, and supply security trade off across buyer procurement strategies.
- Custom Orders:Formulation-to-spec contracts for automotive OEMs involve co-development of accelerator packages and metal adhesion promoters. Direct agreements between seal manufacturers and petrochemical producers are displacing distributor intermediaries in high-volume applications.
- Emergency Stock:Rapid-response inventory for unplanned maintenance events commands 40-60% price premiums over standard lead-time supply.
- Bulk Supply:Tank-wagon and railcar deliveries to integrated compounders minimize per-kilogram logistics costs for high-throughput operations.
- Standard Inventory:Warehoused grades with published specifications serve tier-two fabricators with predictable demand patterns.
Custom Orders anchors strategic relationships. Emergency Stock is expanding most quickly in energy sector procurement.
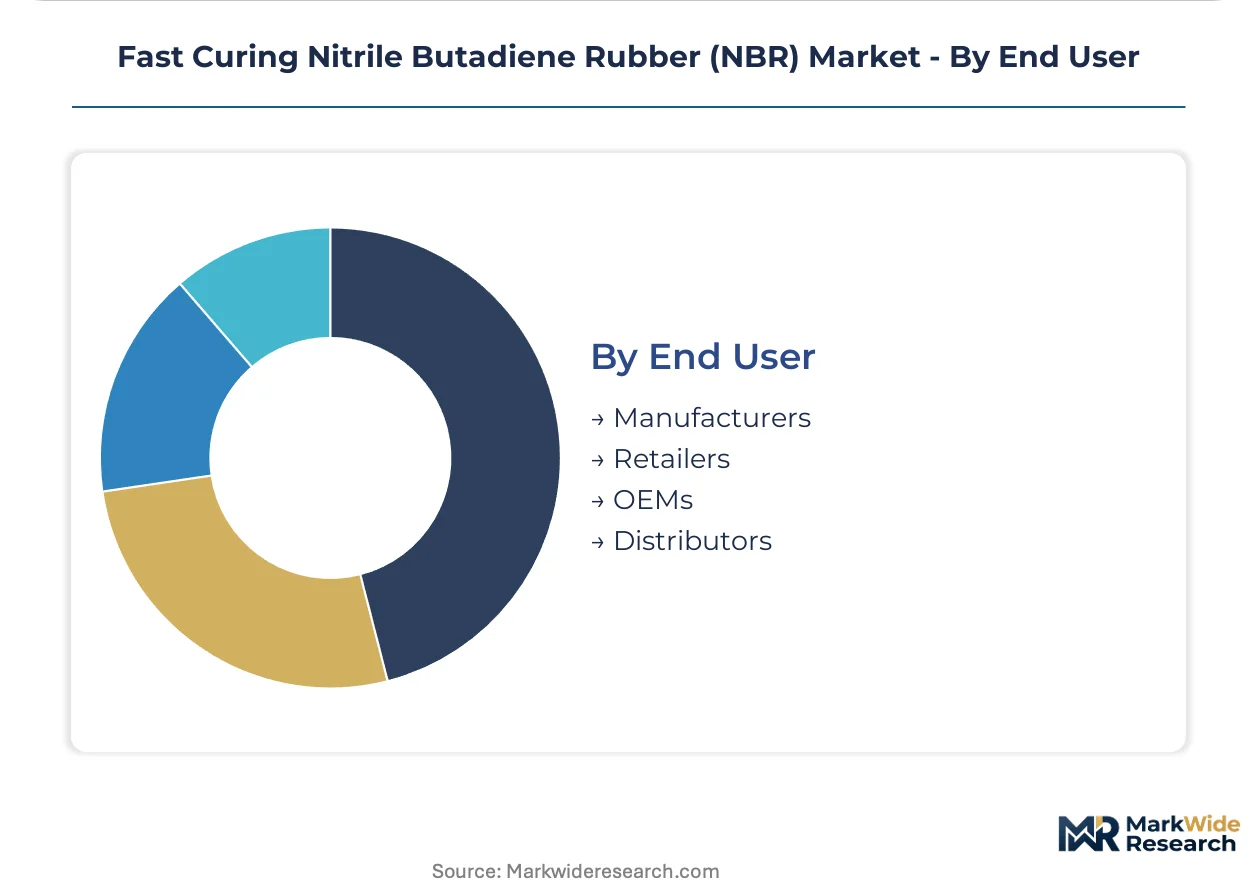
End User:
End user segmentation distinguishes how specification authority, volume scale, and technical integration requirements concentrate buying power across the value chain.
- OEMs:Automotive and industrial original equipment manufacturers wield consolidated approved-supplier lists, reducing compounder counts from twelve to four per platform. Specification-driven procurement compresses margins for non-preferred suppliers.
- Manufacturers:Tier-one seal and hose producers with captive compounding capabilities backward-integrate into elastomer blending for margin control.
- Distributors:Regional stocking intermediaries serve fragmented maintenance-repair demand where lot sizes and formulation variety outstrip direct supplier economics.
- Retailers:Small-format packaging for aftermarket channels carries higher per-unit logistics costs that compounders offset through minimum order thresholds.
OEMs concentrate specification authority. Manufacturers are deepening upstream integration fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for advanced chemistry cell manufacturing is generating captive demand for fast-cure NBR compounds in battery module gasketing, redirecting investment flows across Asia-Pacific supply chains.
United States
Automotive electrification is compressing cure-cycle specifications for thermal management seals as Detroit-based OEMs consolidate approved compounder lists. EPA emission standards on volatile organic compounds from rubber processing compel underhood seal manufacturers toward low-fogging accelerator systems. Gulf Coast petrochemical corridors in Texas and Louisiana anchor butadiene feedstock availability for domestic elastomer blending operations.
Germany
Tier-one automotive seal suppliers prioritize metal-to-rubber adhesion properties for electric vehicle battery pack gasketing in high-volume production contracts. ECHA REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons force reformulation investments across cure package supply chains. The Ruhr industrial cluster concentrates compounding capacity serving OEM specification-driven procurement with direct petrochemical producer agreements.
China
Domestic petrochemical capacity supports localized supply chains for industrial hose and gasket fabricators serving energy infrastructure expansion. GB standards for rubber product volatile organic compound content mandate low-fogging accelerator systems that favor established fast-cure formulations. Shandong and Jiangsu provinces host captive supply relationships between elastomer producers and rubber converters.
Japan
Specialists in high-ACN grades differentiate portfolios for oil-resistant gasket applications in precision-molded automotive components. METI industrial standards shape qualification protocols for repeated-use rubber articles in medical device segments. The Nagoya-Tokyo manufacturing corridor concentrates tier-one seal production with integrated rheology testing capabilities.
Fast Curing Nitrile Butadiene Rubber (NBR) Market Competitive Landscape
On the supply side, the industry is consolidating around integrated petrochemical producers with captive butadiene positions and specialty elastomer compounders with formulation IP. The competitive terrain separates feedstock-integrated multinationals, regional scale players with dedicated elastomer complexes, and niche specialists in high-performance grades. Capacity expansion and strategic partnerships dominate competitive moves as participants secure backward integration into monomer supply and forward linkages to automotive OEM specification lists.
Within the integrated petrochemical tier, ARLANXEO and KUMHO PETROCHEMICAL exemplify archetypes leveraging feedstock control to sustain margin stability across automotive seal supply chains. Zeon Corporation occupies a specialist position in high-ACN grade portfolios differentiated for oil-resistant applications. These three anchors illustrate how competitive positioning stratifies between feedstock security, regional scale advantages, and technical specialization in cure system formulation.
| Leading Market Players |
|---|
| JSR Corporation |
| ARLANXEO |
| LANXESS AG |
| China Petroleum & Chemical Corporation |
| BASF SE |
| Zeon Corporation |
| KUMHO PETROCHEMICAL |
| Trinseo |
| LG Chem Ltd. |
| Others |
Supply & Pricing Matrix
Northeast Asian butadiene capacity concentration in China, South Korea, and Japan anchors feedstock cost structures that cascade through elastomer blending margins into automotive seal pricing. Compounders with captive monomer positions capture margin pools that independent blenders forfeit during crude-linked pricing swings.
Pricing Analysis
Certification level creates the primary spread across fast-cure NBR tiers, with FDA 21 CFR 177.2600-compliant medical grades commanding substantial premiums over industrial sheet stock. Three-tier pricing structure across premium, standard, and economy levels reflects REACH-compliant formulations, automotive OEM direct contracts, and maintenance-repair channel supply respectively. Cost compression in standard grades intensifies because Chinese domestic petrochemical capacity floods regional spot markets. Maintenance-repair channel buyers exhibit highest price sensitivity, while battery pack gasketing contracts for electric vehicle platforms show lowest elasticity due to qualification lock-in.
Supply Chain Analysis
Extended payment terms from integrated petrochemical producers to tier-one seal manufacturers compress working capital cycles for independent compounders. Supply concentrates in China, South Korea, and Germany, with Shandong province hosting captive relationships between elastomer producers and rubber converters. Feedstock draws from crude-linked butadiene, acrylonitrile, and sulfur-donor accelerator packages. Single-source vulnerability runs through Northeast Asian monomer corridors exposed to petrochemical oversupply cycles. Distribution runs through direct petrochemical-to-OEM agreements displacing distributor intermediaries in high-volume hose and belt applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vehicle electrification represents a high-growth disruption as thermal management assembly multiplication per platform compounds fast-cure NBR demand. EPA emission standards and REACH Annex XVII restrictions simultaneously expand addressable market for compliant formulations while compressing non-compliant supplier margins.
For Market Incumbents: Build formulation IP moats around ultra-fast sulfur-donor cure systems incorporating thiuram and dithiocarbamate hybrids. Perfluoroelastomer substitution in fuel cell sealing above 150°C threatens high-ACN NBR positioning; counter through backward integration into butadiene feedstock to sustain margin stability during monomer price volatility. Secure automotive OEM specification lists before platform consolidation reduces approved compounder counts from twelve to four. For New Entrants and Emerging Players: Mid-market adhesive solution formulations for NBR-to-aluminum bonding in battery pack assembly represent the most penetrable entry point. India's PLI scheme for advanced chemistry cell manufacturing generates captive demand for localized fast-cure compound supply. Target digital compound matching services as go-to-market angle, converging AI-driven rheology prediction with cloud-based formulation databases to compress qualification timelines for tier-two seal suppliers. For Investors and Strategic Acquirers: Capital is best deployed toward specialty elastomer compounders with REACH-compliant cure system portfolios and established automotive OEM relationships. Long-term viability over the projection horizon hinges on regulatory chemistry adaptation capability rather than commodity scale. Watch for ECHA restrictions on N-nitrosamine-generating accelerators as inflection indicator forcing zinc-based system migrations that favor formulated-IP holders over commodity blenders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butadiene Feedstock | Captive monomer supply insulates ARLANXEO and KUMHO PETROCHEMICAL from crude-linked pricing volatility. |
| REACH-Compliant Cure System Reformulation | Zinc-based accelerator alternatives command premium positioning as ECHA Annex XVII restrictions tighten. |
| Digital Compound Matching Platform | AI-driven rheology prediction compresses new grade qualification timelines for tier-two seal suppliers. |
| Direct Petrochemical-to-OEM Agreements | Long-term supply contracts displace distributor intermediaries in high-volume automotive seal applications. |
| Medical Device Certification Investment | FDA 21 CFR 177.2600 compliance extends addressable market into repeated-use rubber article segments. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this study. Plant managers at Northeast Asian elastomer complexes, procurement leads at German tier-one seal manufacturers, distribution channel partners serving Italian and Polish gasket fabricators, and technical R&D directors specializing in cure system formulation provided operational perspectives. Secondary sources include ECHA REACH Annex XVII regulatory updates, EPA emission standard filings, customs and trade data from China and South Korea, and SEC 10-K disclosures from listed petrochemical producers. Bottom-up volume modeling triangulates against top-down demand aggregation from automotive production databases.
Calibration against historical price elasticities and capacity utilization rates shapes the projection framework across the analysis window. Segmentation dimensions modeled include application type, product form, delivery mode, and end-user procurement structure. CAGRs derive from elasticity-adjusted demand curves and supply-side capacity expansion schedules. Industry-specific forecast inputs incorporate electric vehicle platform ramp timelines and thermal management module content-per-vehicle trajectories.
Stress conditions across butadiene feedstock volatility, REACH regulatory stringency, and fluorocarbon substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about electrification penetration and compliance cost pass-through. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Flooring Market
Rubber
Rubber Foam Market
Rubber
Butyl Reclaimed Rubber Market
Rubber
Oil Saver Rubber Market
Rubber
Chloro-Sulfonated Polyethylene Market
Rubber
Rubber Choppers Market
Rubber
Tire and Rubber Lubricants Market
Rubber
Europe Rubber Derived Unrefined Pyrolysis Oil Market
Rubber
Cellular Rubber Market
Rubber
Ethylene Propylene Rubber Cable Market
Rubber
Rubber Ropes Market
Rubber
Rubber Coatings Market
Rubber
Global Crumb Rubber Market
Rubber
Global Tire Material Market
Rubber
Rubber Sand Market
Rubber
Polyisoprene Market