
 Ultra-Thin Electronic PI Film Market | 2026-2036
Ultra-Thin Electronic PI Film Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra-Thin Electronic PI Film Market Insights
Roll-to-roll sputtering and atomic layer deposition integration is reshaping how ultra-thin PI films achieve sub-micron metal cladding for flexible circuit applications. DuPont leverages its Kapton heritage and captive resin synthesis to sustain pricing power in aerospace-grade specifications. PI Advanced Materials anchors supply to Samsung Display and LG Display through dedicated cleanroom coating lines in South Korea. Kaneka Corporation dominates high-heat automotive segments with proprietary low-CTE formulations that compete against liquid crystal polymer alternatives.
Ultra-thin electronic PI film refers to polyimide substrates below 25 micrometers thickness, synthesized from pyromellitic dianhydride and oxydianiline monomers through two-step imidization, serving as dielectric substrates for flexible printed circuits and display backplanes. Flexible film occupies the largest volume share due to foldable OLED penetration in consumer devices, while adhesive film represents the fastest-growing category as chip-on-flex bonding requirements multiply in telecommunications hardware. High-temperature resistance technology leads the specification mix because automotive under-hood electronics and aerospace avionics demand continuous operation above 200°C without thermal degradation.
FDA oversight of medical device flexible circuits and EPA restrictions on solvent-based casting processes constrain manufacturing choices for suppliers targeting North American healthcare and industrial markets. REACH substance restrictions and EU Green Deal carbon-border adjustments compel European buyers to audit supply chain chemistry and energy intensity. Stakeholders must monitor how China's GB standards for electronic materials and MIIT domestic substitution policies redirect procurement flows for display panel manufacturers.
Market Dynamics
Foldable OLED display procurement by smartphone OEMs is compressing substrate thickness requirements below 12 micrometers while simultaneously tightening thermal cycling specifications, forcing resin formulators and coating equipment suppliers to synchronize process windows.
Growth Catalysts
- REACH Substance Restrictions:ECHA's tightening purity mandates for halogenated compounds in electronic-grade films are accelerating solvent-free casting process investments across European coating facilities.
- Automotive Under-Hood Electronics:EV power inverter modules and battery management systems require continuous operation above 200°C, pulling high-heat PI formulations into volume automotive supply chains.
- Seoul-Pyeongtaek Corridor:Samsung Display and LG Display have concentrated flexible substrate procurement within a 80-kilometer radius, creating localized demand density that supports dedicated cleanroom coating infrastructure.
Market Restraints
- Pyromellitic Dianhydride Supply Concentration:Three Asian chemical producers control over 75% of electronic-grade PMDA monomer output, exposing film manufacturers to input cost volatility and allocation risk.
- Liquid Crystal Polymer Substitution:LCP films from Celanese and Polyplastics are capturing high-frequency RF antenna substrate share where dimensional stability above 150°C is required but extreme thermal endurance is not.
- RoHS Compliance Friction:EU enforcement of restricted substance thresholds in imported electronic components creates certification delays for non-European film suppliers seeking European flexible circuit OEM qualification.
Strategic Opportunities
- Medical Device Flexible Circuits:FDA's evolving oversight of implantable and wearable diagnostic electronics creates demand for biocompatible PI substrates with validated sterilization resistance.
- India Display Manufacturing:PLI scheme incentives for domestic panel production under India's Ministry of Electronics and Information Technology are attracting substrate qualification programs from Korean and Japanese film suppliers.
- Atomic Layer Deposition Convergence:ALD barrier coating integration with roll-to-roll PI processing is enabling hermetic encapsulation for flexible microLED backplanes without thermal damage to underlying polymer structures.
Industry Challenges
- Cleanroom Coating Technician Scarcity:South Korea's display cluster faces acute shortages of process engineers capable of maintaining sub-micron thickness uniformity across 1500-millimeter web widths.
- Automotive Qualification Timelines:AEC-Q200 stress testing and PPAP documentation requirements extend new film grade approval cycles to 24-36 months, freezing formulation innovation in pipeline.
- Two-Step Imidization IP Complexity:DuPont's historical patent estate around controlled thermal cyclization creates licensing friction for new entrants developing alternative imidization chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra-Thin Electronic PI Film Market |
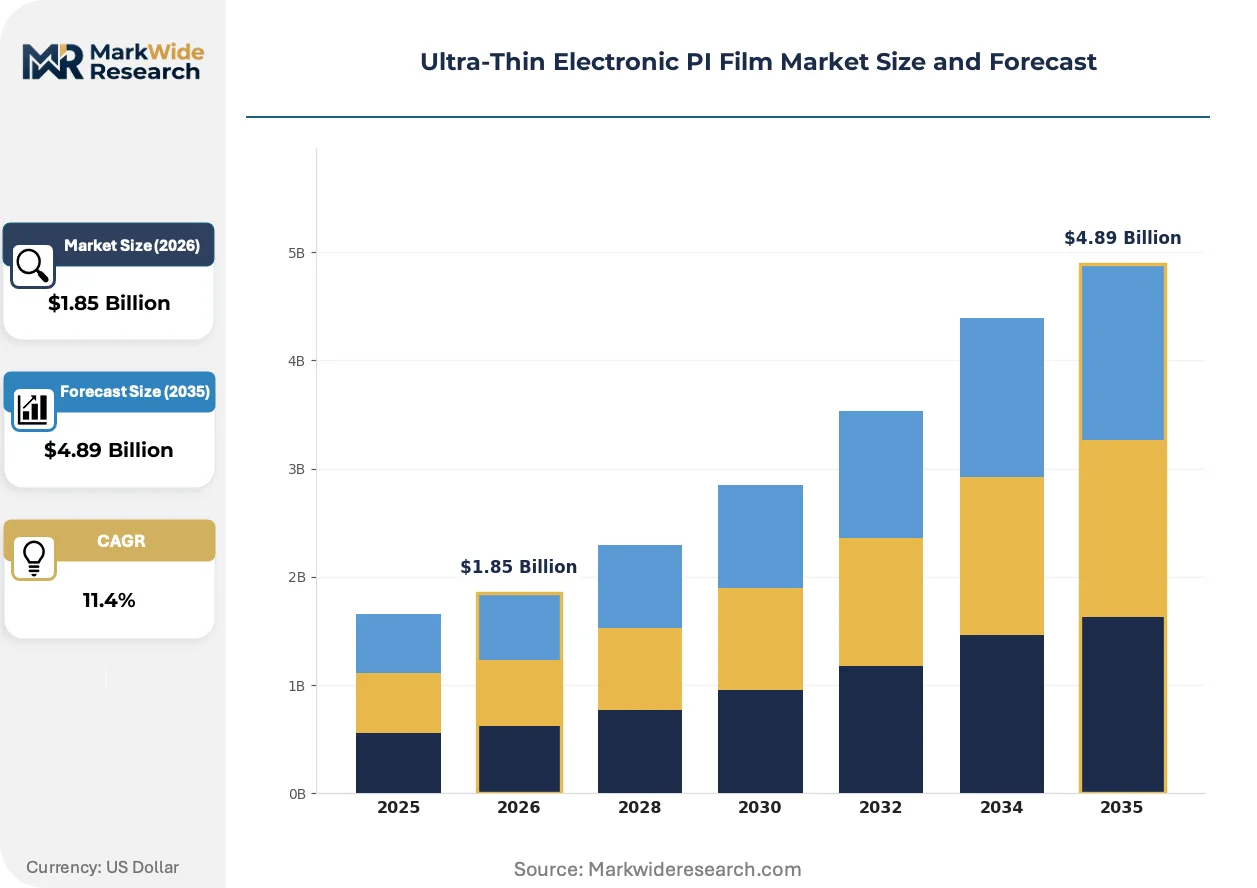
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Film, Rigid Film, Adhesive Film, Composite Film Application: Display Panels, Wearable Devices, Automotive Displays, Consumer Electronics End User: Electronics Manufacturers, Aerospace, Telecommunications, Defense Technology: High-Temperature Resistance, Low Dielectric Constant, Low Thermal Conductivity, High Humidity Resistance |
| Companies Covered | DuPont, PI Advanced Materials, Kaneka Corporation, Toray Industries, UBE Industries, SKC Kolon PI, Taimide Tech, Saint-Gobain Performance Plastics, Mitsubishi Gas Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra-Thin Electronic PI Film Market Trends and Innovations
Metal cladding deposition methods and environmental compliance frameworks are simultaneously evolving, reshaping how ultra-thin PI films achieve electrical functionality while satisfying chemical substance restrictions across multiple jurisdictions.
Solvent-based casting technology is migrating from standard industrial practice to regulated legacy process status as aqueous and melt-processable polyimide alternatives achieve thickness uniformity below 15 micrometers. European coating houses under ECHA pressure are retrofitting drying ovens and solvent recovery systems at accelerated capital deployment rates. This transition is compressing incumbent equipment suppliers' service revenue while opening qualification pathways for resin formulators with waterborne chemistry expertise.
EU Green Deal carbon-border adjustment mechanisms are restructuring procurement audits for electronic-grade films entering European flexible circuit supply chains. Buyers now require documented energy intensity and renewable power share across monomer synthesis, resin production, and coating operations. Korean suppliers serving LG Display and Samsung Display have invested in photovoltaic-powered coating lines to maintain European OEM qualification status.
Specification consolidation among foldable smartphone OEMs is compressing substrate qualification cycles from 18 months toward 9-month windows. Tier-1 flexible circuit manufacturers are pre-qualifying multiple PI film sources simultaneously rather than sequential single-source validation. This pattern is most visible in South Korea's Ansan and Gumi manufacturing zones where Samsung Electronics and LG Electronics procurement teams co-locate supplier technical review functions.
Ultra-Thin Electronic PI Film Market Segmentation
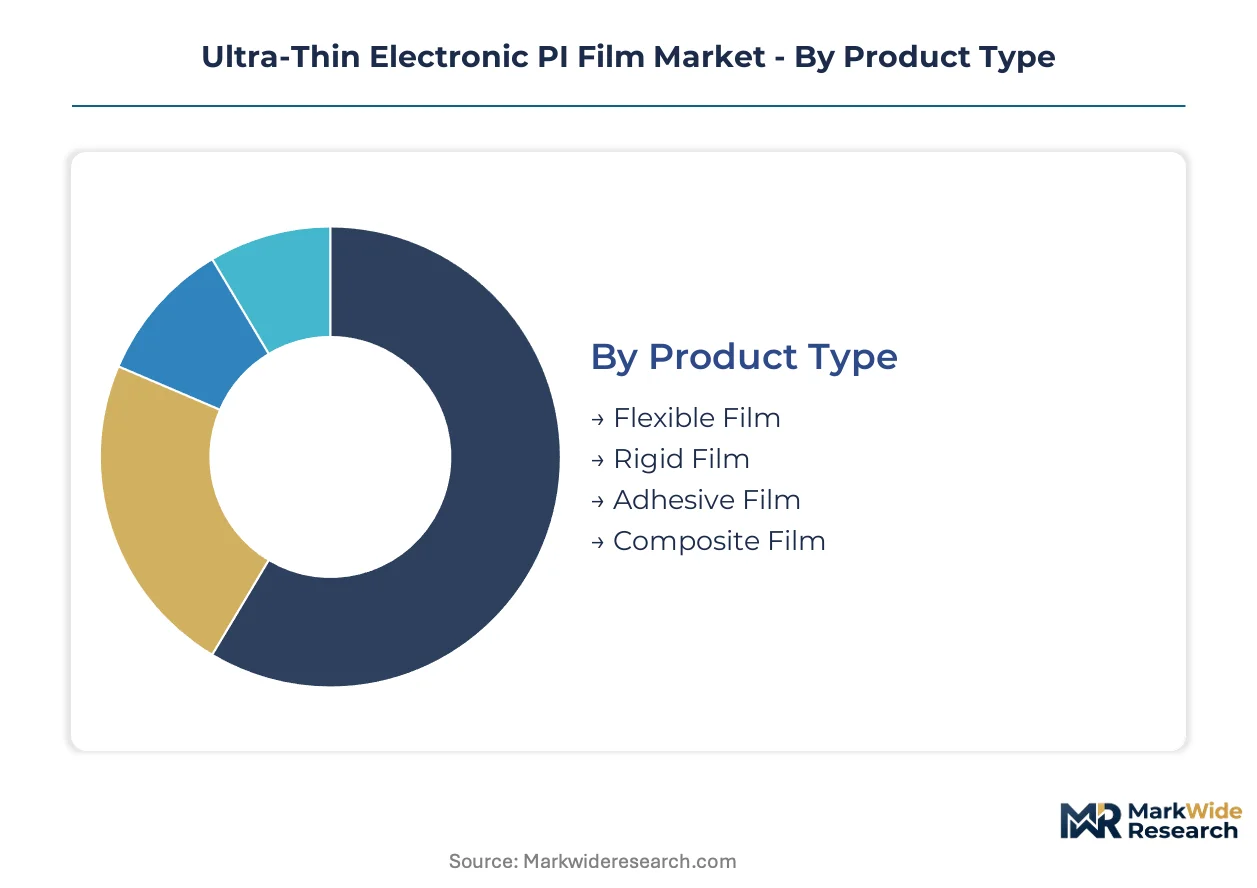
Ultra-thin electronic PI film specifications diverge sharply across end-use thermal profiles and dimensional constraints. Substrate thickness, dielectric constant, and imidization chemistry must align precisely with downstream fabrication processes.
Product Type:
Cost tier differentiation separates commodity-grade substrates from precision-engineered variants with captive resin synthesis.
- Flexible Film:Polyimide substrates below 25 micrometers enable dynamic bending radii under 3 millimeters for foldable OLED backplanes. Samsung Display and LG Display procurement in South Korea's Seoul-Pyeongtaek corridor concentrates demand for sub-12 micrometer specifications.
- Adhesive Film:Pressure-sensitive and thermosetting adhesive layers facilitate chip-on-flex bonding in telecommunications hardware. Fastest volume expansion tracks 5G infrastructure buildouts requiring hermetic component attachment without solder reflow thermal damage.
- Rigid Film:Glass-reinforced or ceramic-filled formulations provide dimensional stability for rigid-flex transition zones in aerospace avionics.
- Composite Film:Multi-layer laminates combining PI with fluoropolymer or metal foil barriers serve specialized EMI shielding applications.
Flexible film commands the established base. The steepest expansion runs through adhesive film.
Application:
Customer type segmentation reveals divergent qualification timelines and specification stringency across device categories.
- Display Panels:Foldable OLED and microLED backplanes demand sub-15 micrometer thickness with thermal cycling endurance exceeding 200,000 bend cycles. South Korean panel manufacturers drive specification convergence through consolidated procurement.
- Automotive Displays:Center stack and instrument cluster integration requires continuous operation from -40°C to 125°C ambient with AEC-Q200 stress validation. 24-36 month qualification cycles freeze formulation selection.
- Wearable Devices:Skin-contact biocompatibility requirements from FDA-regulated medical wearables constrain plasticizer and residual solvent content.
- Consumer Electronics:Tablet and laptop hinge mechanisms prioritize cost-optimized 25-50 micrometer substrates with standard IPC-4202 compliance.
Display panels command the established base. The steepest expansion runs through automotive displays.
End User:
Supply concentration patterns align with regulatory jurisdiction and certification infrastructure density.
- Electronics Manufacturers:Flexible printed circuit board fabricators in South Korea, Japan, and Taiwan consume volume substrates for smartphone and computing device integration. REACH and RoHS compliance audits from European OEMs redirect procurement toward ECHA-registered coating facilities.
- Aerospace:FAA and EASA certification requirements for flame resistance and outgassing control sustain DuPont Kapton heritage formulations despite premium pricing.
- Telecommunications:5G base station and antenna module producers source low-loss dielectric substrates for millimeter-wave frequency operation.
- Defense:ITAR-controlled supply chains and MIL-PRF-38534 validation restrict qualified film sources to domestic producers in US and European NATO member states.
Electronics manufacturers command the established base. The steepest expansion runs through telecommunications.
Technology:
Performance specification tiers separate thermal endurance leaders from dielectric-optimized formulations for high-frequency signal integrity.
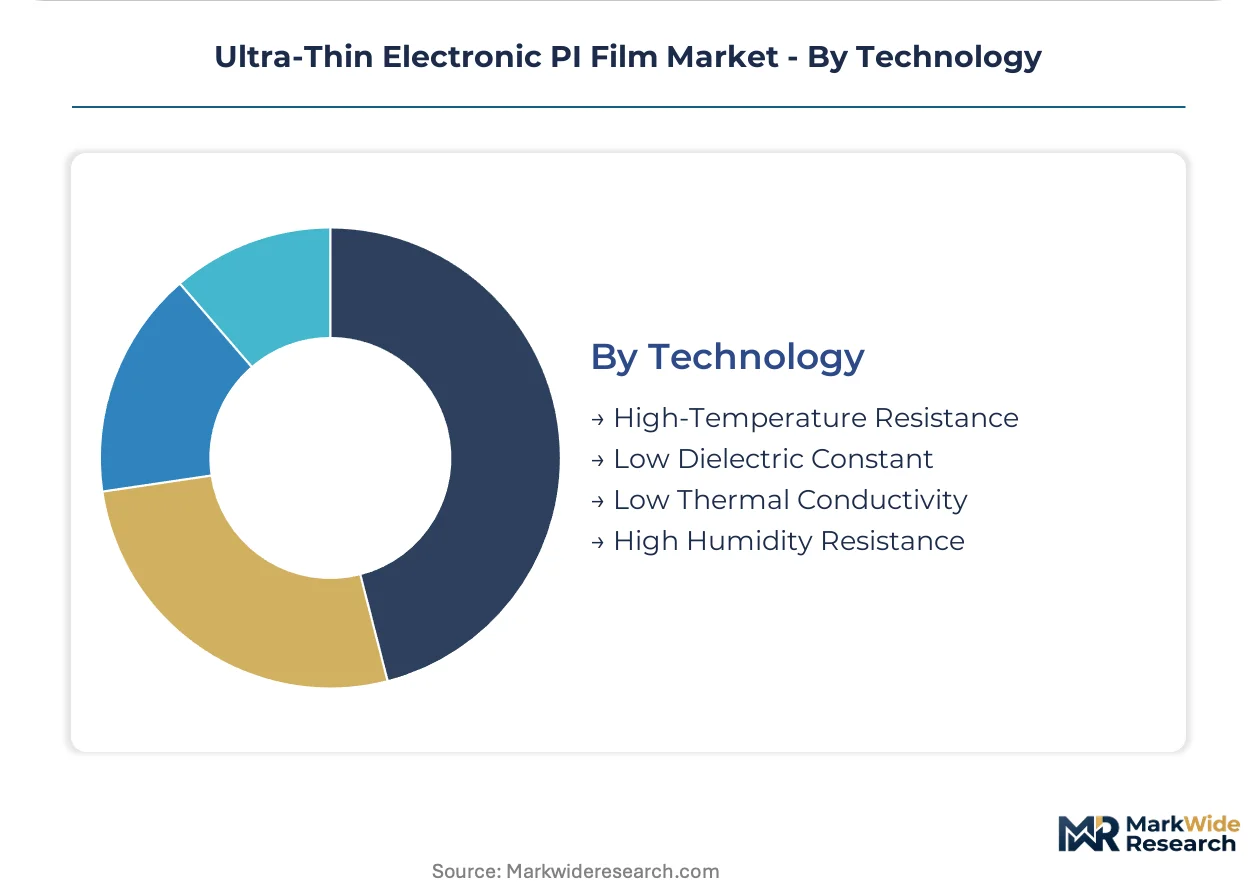
- High-Temperature Resistance:Continuous service above 200°C without mechanical degradation requires controlled thermal cyclization during two-step imidization. EV power inverter modules and aerospace engine compartment sensors pull these formulations into automotive and defense supply chains.
- Low Dielectric Constant:Fluorinated monomer incorporation and nanoporous structures reduce Dk below 3.0 for 5G mmWave and satellite communication substrates. Fastest technology expansion tracks RF antenna-in-package integration where signal loss minimization outweighs thermal budget constraints.
- Low Thermal Conductivity:Engineered porosity and filler exclusion limit heat spreading in thermal barrier applications for battery pack insulation.
- High Humidity Resistance:Hydrophobic surface modification and fluoropolymer overcoating prevent moisture ingress in tropical climate outdoor electronics.
High-temperature resistance commands the established base. The steepest expansion runs through low dielectric constant.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flexible circuit board fabricators cluster near display and semiconductor manufacturing hubs, creating localized procurement gravity that concentrates resin formulation and coating capacity in three countries.
South Korea
Samsung Display and LG Display drive sub-12 micrometer substrate procurement for foldable OLED panels. MFDS medical device regulations constrain biocompatible film qualifications for wearable diagnostics. Seoul's Ansan district and Pyeongtaek's packaging corridor host dedicated cleanroom coating lines serving these panel makers.
China
MIIT domestic substitution policies redirect procurement flows for display panel manufacturers toward local resin synthesis. GB standards for electronic materials tighten purity specifications for halogenated compounds. Yangtze River Delta coating facilities near Shanghai expand aqueous casting capacity under MEE environmental enforcement.
Japan
Automotive under-hood electronics and 5G telecommunications hardware pull high-heat and low-Dk formulations into volume supply chains. METI technology roadmaps prioritize low-loss dielectric development for mmWave applications. Chubu region chemical producers near Nagoya maintain captive PMDA monomer synthesis for film manufacturing.
United States
FAA and FDA oversight of aerospace avionics and implantable medical devices sustains premium-grade film demand with extended qualification cycles. EPA restrictions on solvent-based casting constrain manufacturing choices for healthcare market entrants. California's Bay Area hosts flexible circuit design centers sourcing validated substrate grades.
Germany
REACH substance restrictions and EU Green Deal carbon-border adjustments compel supply chain audits of energy intensity and renewable power share. ECHA enforcement of halogenated compound thresholds accelerates solvent-free process investments. Baden-Württemberg automotive suppliers qualify PI substrates for EV power inverter modules under KBA type approval frameworks.
Ultra-Thin Electronic PI Film Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. The structure concentrates around resin synthesis capabilities and captive monomer supply, with heritage chemical conglomerates occupying premium positions and regional coaters serving cost-sensitive segments. Two strategic archetypes dominate: vertically integrated resin-to-film producers and specialized coating houses dependent on merchant resin supply. Competitive moves center on cleanroom capacity expansion near display clusters and technology licensing agreements for aqueous casting processes.
Within the heritage chemical tier, DuPont exemplifies premium positioning through decades of aerospace-grade formulation development. Japanese conglomerates Toray Industries and UBE Industries occupy positions spanning resin synthesis through precision coating, representing the integrated archetype that controls input costs and specification granularity. Korean specialists PI Advanced Materials and SKC Kolon PI sit within the regional champion category, anchoring supply relationships with Seoul-Pyeongtaek display manufacturers through proximity-driven service models.
| Leading Market Players |
|---|
| DuPont |
| PI Advanced Materials |
| Kaneka Corporation |
| Toray Industries |
| UBE Industries |
| SKC Kolon PI |
| Taimide Tech |
| Saint-Gobain Performance Plastics |
| Mitsubishi Gas Chemical Company |
| Others |
Pricing and Supply Chain Analysis
The Incheon-Pyeongtaek maritime corridor's freight cost dynamics amplify supply concentration effects, as resin formulators near Seoul's display cluster leverage proximity to command premium pricing while distant coaters absorb logistics penalties that compress their margins into standard-grade tiers.
Pricing Analysis
Cost-plus contracts with pyromellitic dianhydride indexation dominate long-term supply agreements between film manufacturers and display panel OEMs. Three-tier pricing structure across aerospace-grade, electronic-grade, and industrial-grade specifications reflects certification intensity and captive resin synthesis control. Cost compression in standard electronic-grade substrates is intensifying because merchant resin suppliers compete for volume share. Automotive OEMs exhibit lowest price sensitivity due to AEC-Q200 validation requirements, while consumer electronics contract manufacturers negotiate aggressively on per-square-meter basis.
Supply Chain Analysis
Upstream feedstock concentration in China, Japan, and South Korea shapes raw material access patterns for coating facilities worldwide. Electronic-grade PMDA monomer, oxydianiline precursor chemicals, and high-purity solvents constitute critical input dependencies. Single-source vulnerability runs through the three Asian chemical producers controlling majority monomer output. Distribution runs through direct mill relationships with flexible circuit fabricators in South Korea's Ansan district and Japan's Chubu region, bypassing merchant distributors for qualified grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultra-thin electronic PI film sits in early-cycle expansion as foldable OLED penetration accelerates substrate procurement for dynamic bending applications.
For Market Incumbents: Build captive resin synthesis moats through backward integration into PMDA monomer production or exclusive offtake agreements with Japanese chemical producers. Secure cleanroom coating capacity within 50 kilometers of Seoul-Pyeongtaek display corridor before liquid crystal polymer alternatives capture additional RF substrate share. Prioritize AEC-Q200 pre-validation investments to lock automotive qualification timelines before EV platform standardization freezes supplier selection. For New Entrants and Emerging Players: Build out aqueous casting process capabilities to serve European flexible circuit OEMs facing ECHA solvent restriction enforcement. India's PLI-subsidized display manufacturing zones offer the most penetrable geography for substrate qualification programs. Target medical device flexible circuit segment through FDA biocompatibility pre-submission pathways, where incumbent certification density remains lowest. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with undermonetized PI film divisions lacking display corridor proximity. Five-to-ten year viability hinges on resin-to-film integration depth rather than coating-only scale. Monitor Samsung Display and LG Display dual-sourcing announcements as inflection signal for qualification cycle compression and margin pressure release.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Synthesis | Captive PMDA supply insulates Korean coaters from allocation risk during pyromellitic dianhydride supply shocks. |
| Cleanroom Capacity Expansion Near Seoul | Proximity to Samsung Display and LG Display procurement teams accelerates sub-12 micrometer qualification cycles. |
| Aqueous Casting Process Migration | ECHA solvent restriction compliance opens European flexible circuit OEM qualification pathways for waterborne chemistry specialists. |
| AEC-Q200 Pre-Validation Investment | Automotive grade approval locks 24-36 month supplier selection windows before EV power inverter module platform freezes. |
| Medical Device Biocompatibility Certification | FDA implantable electronics oversight creates defensible premium tier for sterilization-resistant substrate formulations. |
Research Methodology
Operator-level perspectives from resin synthesis plant managers, flexible circuit procurement leads at Korean display manufacturers, coating equipment technical directors, and ECHA regulatory compliance officers anchored the qualitative base. Secondary validation drew from MIIT domestic substitution policy filings, REACH substance restriction updates, SEC 10-K disclosures from heritage chemical conglomerates, and Korean customs trade data for polyimide film imports. Bottom-up volume builds across substrate thickness tiers and top-down demand validation from foldable OLED panel production forecasts were triangulated to constrain estimate variance.
Scenario-bracketing around foldable smartphone adoption curves and EV power electronics thermal management requirements framed the analytical envelope across the projection horizon. Segmentation dimensions modeled included product type tier, application thermal profile, end-user regulatory jurisdiction, and technology specification cluster. CAGRs were derived from S-curve penetration analysis against addressable substrate area in display and automotive modules. Industry-specific forecast inputs incorporated Samsung Display and LG Display capital expenditure plans for flexible OLED capacity, plus AEC-Q200 stress testing timeline assumptions from Tier 1 automotive suppliers.
Stress conditions across PMDA monomer supply disruption, ECHA solvent restriction acceleration, and liquid crystal polymer substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding imidization chemistry yield improvements and cleanroom coating throughput scaling. Cross-checking against Korean display equipment supplier order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Miniature Ball Bearing Market
Passive And Interconnecting Electronic Components
Elastomeric Connectors Market
Passive And Interconnecting Electronic Components
Thick Film Resistor Market
Passive And Interconnecting Electronic Components
Wirewound Resistor Market
Passive And Interconnecting Electronic Components
Galvanic Isolators Market
Passive And Interconnecting Electronic Components
Plastic Film Capacitors Market
Passive And Interconnecting Electronic Components
United Kingdom MLCC Market
Passive And Interconnecting Electronic Components
Molded Interconnect Devices (MID) Market
Passive And Interconnecting Electronic Components
Germany MLCC Market
Passive And Interconnecting Electronic Components
Through Hole Resistor Market
Passive And Interconnecting Electronic Components
Hybrid Capacitor Market
Passive And Interconnecting Electronic Components
Anti-Sulfur Chip Resistors Market
Passive And Interconnecting Electronic Components
Passive and Interconnecting Electronic Components Market
Passive And Interconnecting Electronic Components
Power and Utilities MLCC Market
Passive And Interconnecting Electronic Components
Lead-Free Solder Paste Market
Passive And Interconnecting Electronic Components
Chip Capacitor Market