
 Respiratory Gating Market | 2026-2036
Respiratory Gating Market Size, Share, and Industry Trends Forecast 2026-2036
Respiratory Gating Market Insights
Software-defined motion tracking is realigning what respiratory gating vendors bundle into long-term service contracts. Varian Medical Systems leverages its installed base of linear accelerators to attach recurring software subscription revenue. Siemens Healthineers anchors its gating portfolio to MR-linac workflows, creating tighter integration between diagnostic and therapeutic platforms. Philips Healthcare differentiates through hybrid deployment architectures that let clinics shift processing between on-premises servers and cloud analytics.
Respiratory gating encompasses real-time patient motion detection and beam-interruption systems that synchronize radiation delivery to specific phases of the breathing cycle, typically achieving spatial tracking precision within one to two millimeters to spare healthy tissue during thoracic and upper-abdominal treatment. The technology layer spans infrared, electromagnetic, and optical tracking modalities, with electromagnetic systems dominating current installations due to their compatibility with existing linac rooms while optical tracking captures the fastest expansion as camera-based systems eliminate wearable markers. Application demand clusters in radiation therapy and diagnostic imaging, with radiation therapy representing the mature margin pool where reimbursement is established and diagnostic imaging emerging as the faster-growing segment as CT and PET protocols adopt respiratory synchronization for cardiac and pulmonary scans.
FDA 510(k) clearance requirements shape hardware-software bundle submissions for the US market, while the EU Medical Device Regulation imposes stricter clinical evidence standards for electromagnetic and optical tracking systems sold in Europe. Japan's PMDA maintains distinct software-as-medical-device classification rules that delay cloud-based deployment approvals relative to on-premises installations. Stakeholders must monitor how regulatory divergence between FDA, EMA, and PMDA pathways affects product roadmap prioritization and geographic launch sequencing.
Market Dynamics
Software-defined motion tracking is compressing hardware margins and elongating service contract durations across respiratory gating installations. Vendors now bundle real-time analytics subscriptions with electromagnetic and optical tracking hardware, shifting revenue recognition from upfront capital sales to recurring software streams.
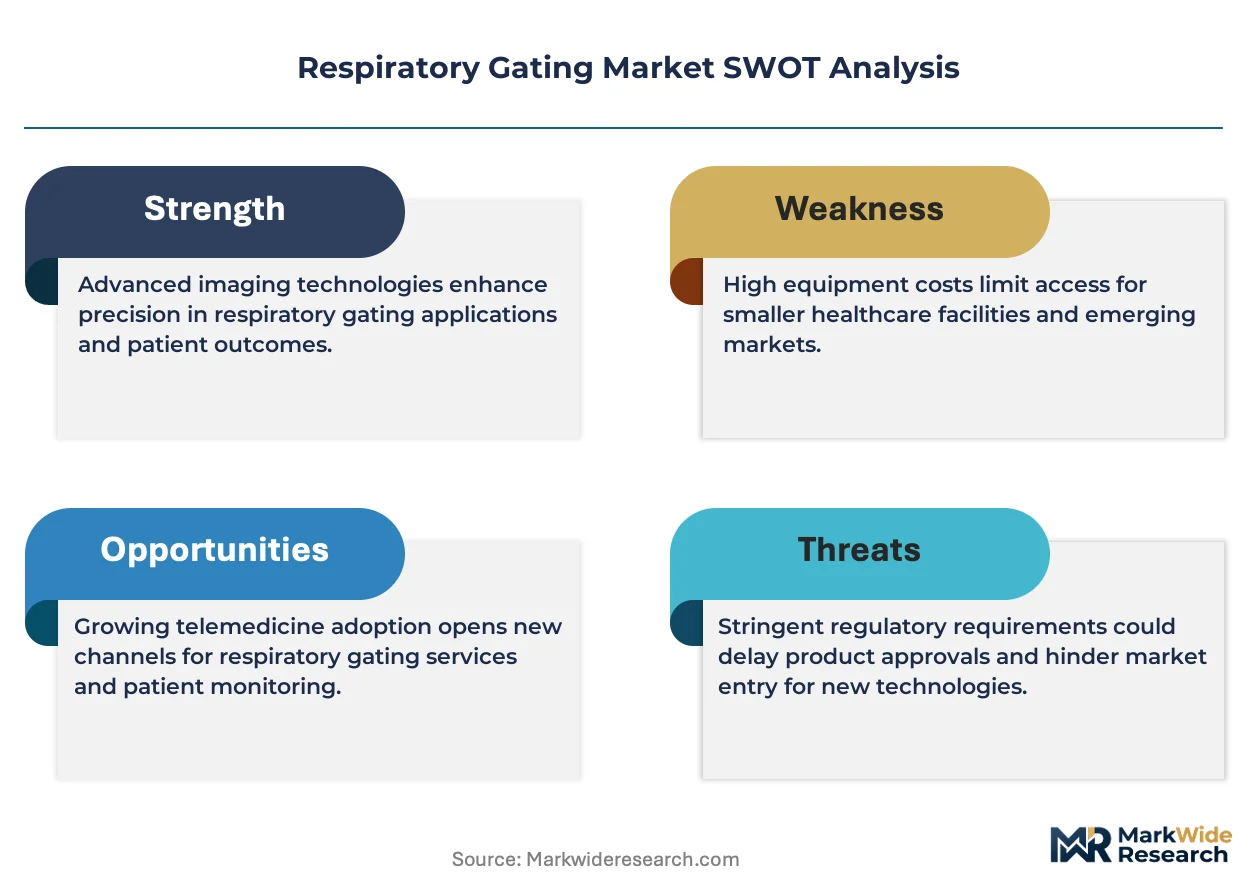
Growth Catalysts
- Proton therapy infrastructure:United States oncology centers are installing motion management systems alongside new proton facilities to protect healthy tissue during thoracic radiation delivery.
- EU Medical Device Regulation:Stricter clinical evidence standards for electromagnetic tracking systems are accelerating consolidation among vendors capable of funding extensive trials.
- Hybrid cloud architectures:Processing flexibility between on-premises servers and cloud analytics is expanding addressable clinic sizes beyond academic medical centers.
Market Restraints
- Electromagnetic component concentration:Sensor manufacturing concentrates among German and Japanese precision electronics suppliers, creating input vulnerability.
- PMDA software-as-medical-device classification:Japan's distinct cloud-deployment approval delays compress near-term addressable market for SaaS-heavy entrants.
- Optical tracking substitution:Marker-free camera systems threaten electromagnetic installed base renewal cycles in greenfield linac rooms.
Strategic Opportunities
- Diagnostic imaging synchronization:CT and PET protocols adopting respiratory gating for cardiac and pulmonary scans represent faster-growing application white space.
- Germany MR-linac penetration:Siemens Healthineers' integrated workflows create reference-site effects for motion management attachment.
- FDA 510(k) pathway compression:Streamlined clearance for real-time tracking software bundles accelerates time-to-market for algorithmic improvements.
Industry Challenges
- Multi-modal integration complexity:Clinics struggle to synchronize infrared, electromagnetic, and optical data streams within existing linac control systems.
- Clinical physics talent scarcity:Radiation therapy departments face recruitment gaps for specialists trained in respiratory motion modeling and adaptive planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respiratory Gating Market |
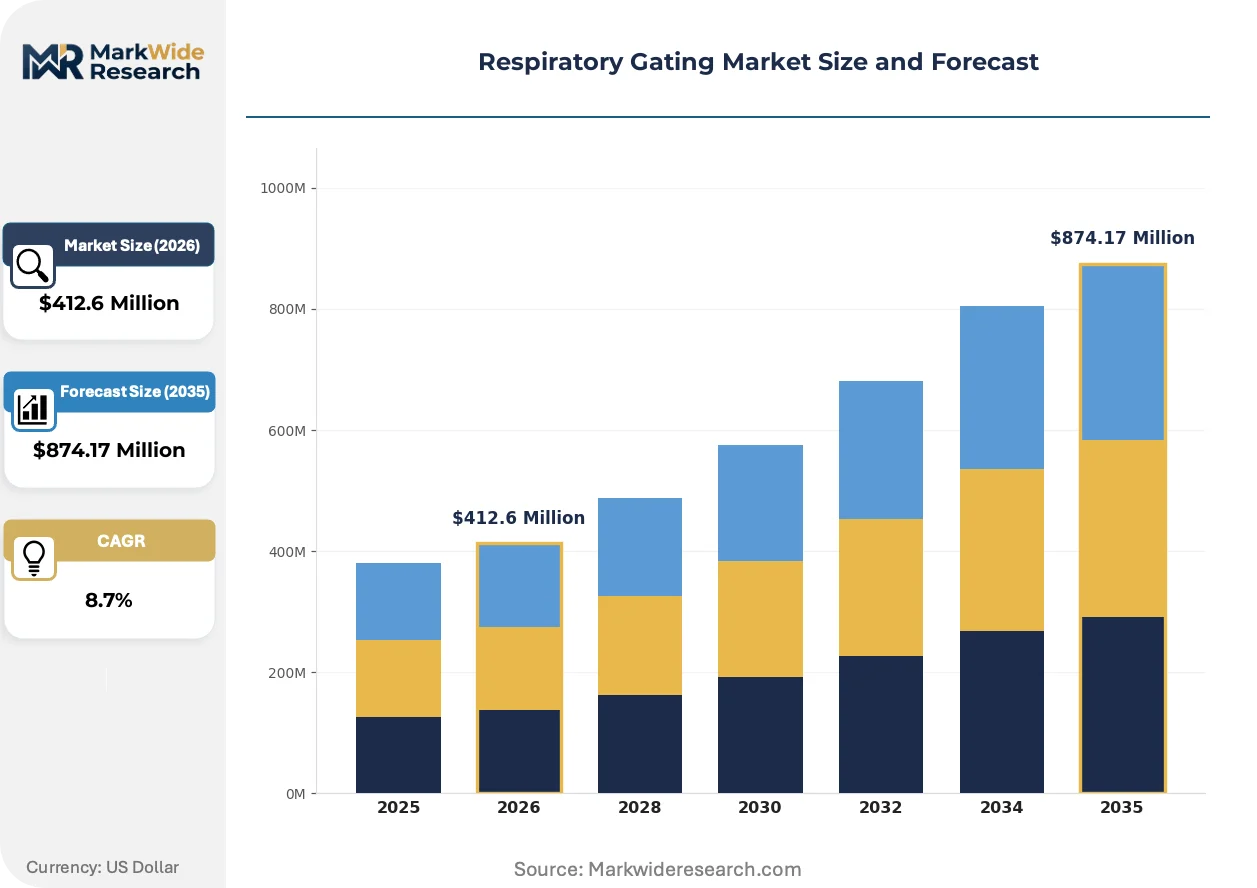
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Infrared, Ultrasound, Electromagnetic, Optical Tracking, Spirometry Application: Radiation Therapy, Diagnostic Imaging, Cardiac Monitoring, Pulmonary Function Assessment, Motion Management End User: Oncology Centers, Diagnostic Clinics, Cardiology Units, Research Laboratories, Academic Institutions Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Solutions |
| Companies Covered | Varian Medical Systems, Siemens Healthineers, Philips Healthcare, GE HealthCare, Canon Medical Systems, Fujifilm, Brainlab, Elekta, C-RAD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respiratory Gating Market Trends and Innovations
Real-time patient motion detection is migrating from hardware-centric to algorithm-centric competitive differentiation. Vendors now compete on predictive analytics accuracy and integration depth rather than sensor precision alone.
Markerless optical tracking is absorbing the fastest expansion trajectory across respiratory gating modalities. Camera-based surface imaging eliminates patient-worn electromagnetic markers, reducing setup time and skin irritation complaints. Academic medical centers in the United States are piloting these systems for lung SBRT protocols. The technology is absorbing market share from electromagnetic installations in greenfield proton therapy suites where room configuration flexibility matters.
Japan's PMDA maintains distinct software-as-medical-device classification rules that delay cloud-based deployment approvals relative to on-premises installations. This regulatory friction fragments vendor product roadmaps, forcing parallel development tracks for Japanese and Western markets. Electromagnetic tracking vendors with established on-premises architectures retain advantage in Tokyo and Osaka metropolitan hospital clusters.
Service contract unbundling is compressing traditional multi-year hardware-software bundles into modular subscriptions. Radiation therapy departments now separately procure tracking hardware, motion management software, and predictive analytics tiers. This pattern is most visible in United States community oncology centers seeking operational flexibility amid reimbursement uncertainty. Vendors respond with usage-based pricing for software modules tied to patient treatment volumes.
Respiratory Gating Market Segmentation
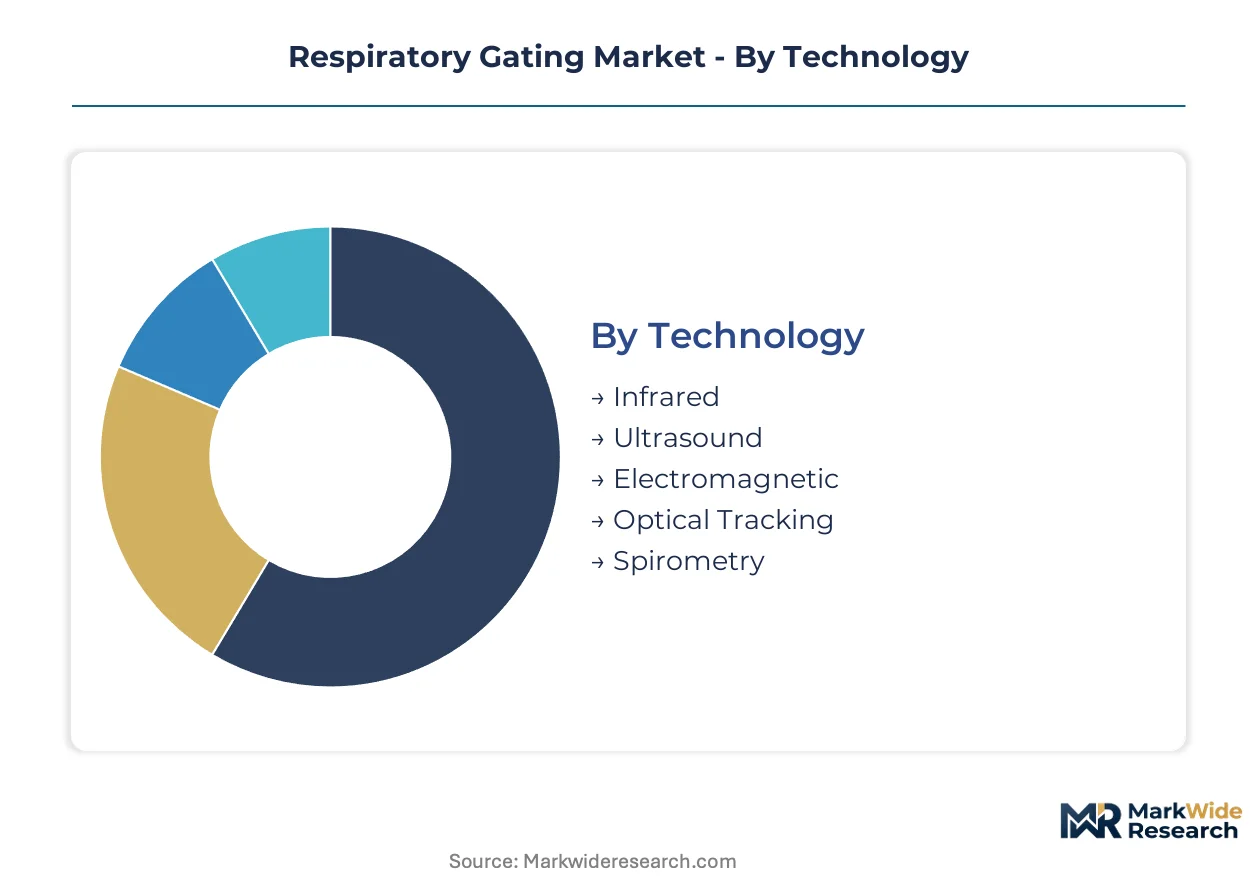
Respiratory gating vendors structure pricing and service contracts around technology modality, clinical application, and infrastructure requirements. Understanding these segment boundaries clarifies where capital deployment concentrates versus where operational expenditure models are displacing upfront hardware sales.
Technology:
Capital intensity varies sharply across tracking modalities, with electromagnetic and optical systems demanding the heaviest upfront investment in sensor arrays and calibration infrastructure.
- Electromagnetic:Requires implantable or surface-mounted fiducial markers coupled with electromagnetic field generators. United States proton therapy centers anchor demand here due to established reimbursement pathways and physics staff familiarity with marker-based workflows.
- Optical Tracking:Deploys camera-based surface imaging without patient-worn markers, cutting setup time and eliminating skin irritation risks. Greenfield linac installations in Germany and Japan are absorbing this technology fastest as room configuration flexibility becomes decisive.
- Infrared:Uses reflective marker triangulation for position tracking. Academic medical centers with legacy linac fleets maintain installed bases.
- Ultrasound:Employs acoustic imaging for real-time organ boundary detection. Research laboratories pilot this for cardiac motion assessment.
- Spirometry:Measures airflow patterns to infer respiratory phase. Pulmonary function assessment suites deploy this as a low-cost entry point.
Electromagnetic systems absorb the bulk of installed capacity; optical tracking is expanding most quickly.
Application:
Radiation therapy commands the deepest margin pool where established CPT codes protect pricing power, while diagnostic imaging applications climb the fastest as CT and PET protocols adopt respiratory synchronization.
- Radiation Therapy:Beam-interruption systems synchronize linac delivery to specific breathing phases. United States oncology centers represent the core revenue base with mature reimbursement infrastructure.
- Diagnostic Imaging:CT and PET respiratory gating reduces motion artifact in cardiac and pulmonary scans. German university hospitals are expanding adoption here for research-grade imaging protocols.
- Cardiac Monitoring:ECG-gated imaging correlates heart motion with respiratory phase. Cardiology units in Japan deploy this for stress-test imaging.
- Pulmonary Function Assessment:Spirometry-linked tracking evaluates lung mechanics. Research laboratories use this for longitudinal COPD studies.
- Motion Management:Integrates multi-modal tracking into unified workflow platforms. Academic institutions pilot these for adaptive therapy protocols.
Radiation therapy retains the largest revenue footprint; diagnostic imaging is gaining share fastest.
End User:
Oncology centers concentrate procurement authority for high-value systems, while diagnostic clinics represent the volume expansion opportunity as respiratory gating penetrates outpatient imaging.
- Oncology Centers:Radiation therapy departments with dedicated medical physics staff. United States community oncology networks are unbundling service contracts here.
- Diagnostic Clinics:Outpatient imaging facilities adopting CT and PET gating. German metropolitan clusters show steepest adoption curves.
- Cardiology Units:Hospital departments integrating respiratory synchronization into cardiac MRI and CT protocols.
- Research Laboratories:Academic and commercial R&D facilities developing next-generation tracking algorithms.
- Academic Institutions:University hospitals serving as reference sites for vendor clinical trials and early technology validation.
Oncology centers dominate current procurement volume; diagnostic clinics are expanding most rapidly.
Deployment:
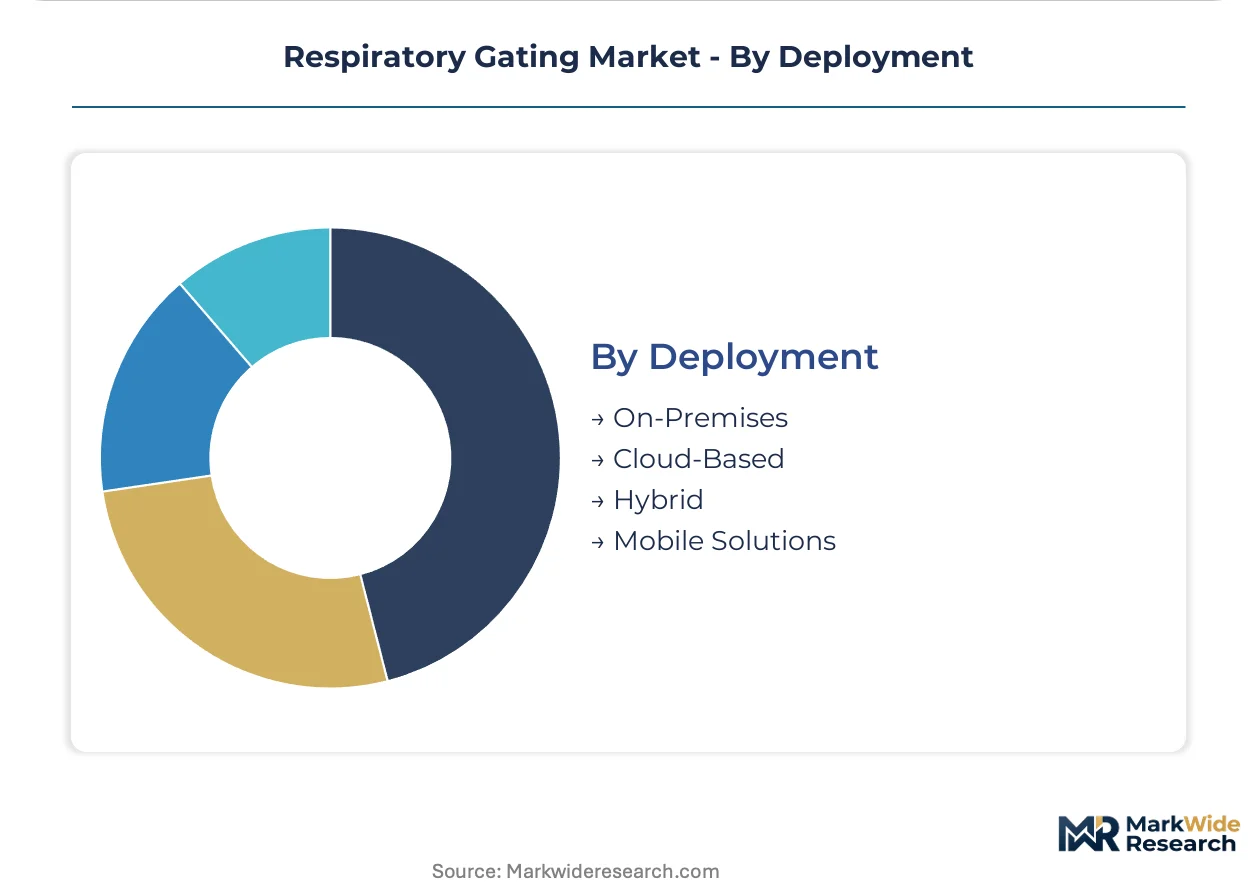
On-premises architectures require substantial server infrastructure and IT support, while cloud-based and hybrid models shift capital burden to recurring subscription streams.
- On-Premises:Local server installation with full data sovereignty. Japan's PMDA software-as-medical-device classification delays favor this model in Tokyo and Osaka hospital clusters.
- Cloud-Based:Remote processing with analytics delivered via subscription. United States community oncology centers are piloting this for operational flexibility.
- Hybrid:Processing shifts between local servers and cloud analytics based on workload. Philips Healthcare and Siemens Healthineers are anchoring portfolio strategies here.
- Mobile Solutions:Portable tracking hardware for intra-facility deployment or clinical trials. Research laboratories and academic institutions drive niche demand.
On-premises systems retain the largest installed base; hybrid deployment is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of electromagnetic tracking sensors concentrates among German and Japanese precision electronics suppliers, while consumption of respiratory gating systems clusters in oncology centers across the United States, Germany, and Japan where proton therapy infrastructure is most densely installed.
United States
Community oncology networks and academic medical centers drive procurement of motion management systems alongside proton therapy facility construction. FDA 510(k) clearance pathways for real-time tracking software bundles compress time-to-market for algorithmic improvements. The Houston and Boston metropolitan clusters anchor demand as proton facilities expand in Texas and Massachusetts.
Germany
University hospitals and research institutions pilot MR-linac integrated workflows that tighten diagnostic-therapeutic platform connectivity. EU Medical Device Regulation imposes stricter clinical evidence standards for electromagnetic and optical tracking systems, accelerating consolidation among vendors funding extensive trials. The Bavaria and North Rhine-Westphalia regions concentrate adoption through Siemens Healthineers reference-site effects.
Japan
Tokyo and Osaka metropolitan hospital clusters maintain preference for on-premises architectures due to PMDA software-as-medical-device classification rules that delay cloud-based deployment approvals. Domestic precision electronics suppliers feed electromagnetic sensor demand for linac installations. Cardiology units deploy respiratory synchronization for stress-test imaging protocols.
United Kingdom
NHS oncology centers evaluate hybrid deployment architectures that shift processing between local servers and cloud analytics for operational flexibility. MHRA alignment with EU MDR standards shapes vendor clinical evidence requirements for electromagnetic tracking submissions. London and Manchester academic medical centers serve as early validation sites for markerless optical tracking pilots.
South Korea
MFDS regulatory frameworks for software-as-medical-device create parallel approval tracks for domestic and imported respiratory gating systems. Seoul Capital Area hospitals concentrate demand for CT and PET respiratory synchronization in cardiac imaging protocols. Domestic electronics manufacturers supply infrared tracking components to regional linac vendors.
Respiratory Gating Market Competitive Landscape
Top-tier vendors anchor the premium hardware-software bundle tier, while mid-scale specialists occupy modular subscription and regional service contract segments. The vendor base stratifies across three tiers: integrated linac manufacturers with captive motion management portfolios, standalone tracking technology developers, and diagnostic imaging platform vendors attaching gating as workflow extension. Two dominant competitive moves are reshaping positioning: M&A activity consolidating electromagnetic sensor suppliers into platform vendors, and strategic partnerships between optical tracking developers and proton therapy facility constructors.
Among integrated platform vendors, Varian Medical Systems, Siemens Healthineers, and Philips Healthcare exemplify contrasting archetypes. Varian leverages its installed linear accelerator base to attach recurring software subscription revenue streams. Siemens anchors gating portfolios to MR-linac workflows, creating tighter diagnostic-therapeutic integration. Philips differentiates through hybrid deployment architectures enabling processing flexibility between on-premises infrastructure and cloud analytics.
| Leading Market Players |
|---|
| Varian Medical Systems |
| Siemens Healthineers |
| Philips Healthcare |
| GE HealthCare |
| Canon Medical Systems |
| Fujifilm |
| Brainlab |
| Elekta |
| C-RAD |
| Others |
Pricing and Supply Chain Analysis
United States community oncology networks concentrate procurement authority for respiratory gating systems, anchoring vendor pricing strategies to multi-year service contracts that bundle electromagnetic tracking hardware with predictive analytics subscriptions.
Pricing Analysis
Margin tightening in hardware tiers reflects software-defined motion tracking displacing sensor precision as the primary value driver. Three-tier pricing structure across premium, standard, and economy levels separates MR-linac integrated bundles from standalone electromagnetic systems and entry-level spirometry modules. Price differentiation hinges on FDA 510(k) clearance tier and after-sales calibration service bundling. Community oncology centers exhibit highest price sensitivity; proton therapy facilities show lowest sensitivity due to capital budget insulation.
Supply Chain Analysis
Regional distribution centers in Germany and Japan anchor hub-and-spoke patterns for electromagnetic sensor arrays serving North American and European linac installations. Precision field generators and optical camera modules draw from German and Japanese component suppliers. Single-source vulnerability concentrates in electromagnetic marker manufacturing. Distribution runs through authorized service depots tied to major linac vendor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical tracking systems are displacing electromagnetic marker-based workflows across greenfield installations, compressing renewal cycles for legacy hardware portfolios.
For Market Incumbents: Anticipate markerless optical substitution by accelerating hybrid deployment architectures that preserve installed base relationships through software subscription migration. Deepen vertical integration into predictive analytics modules to defend against modular unbundling. Prioritize FDA 510(k) pathway compression for real-time algorithm updates. For New Entrants and Emerging Players: Capture diagnostic imaging synchronization white space in German university hospitals where CT and PET respiratory gating protocols expand fastest. Target outpatient imaging clinics in United States metropolitan clusters seeking operational flexibility through cloud-based deployment. Lead with usage-based pricing tied to patient treatment volumes. For Investors and Strategic Acquirers: The window for entry favors standalone optical tracking developers with established camera calibration IP and proton therapy facility partnerships. Long-term viability rests on algorithm-centric competitive differentiation displacing hardware precision. Watch PMDA software-as-medical-device reclassification as inflection signal for Japanese cloud-deployment approval acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Deployment Architecture Development | Philips Healthcare and Siemens Healthineers anchor portfolio strategies around processing flexibility between on-premises and cloud analytics. |
| Markerless Optical Tracking Pilot Expansion | Academic medical centers in Houston and Boston metropolitan clusters validate surface imaging for lung SBRT protocols. |
| MR-Linac Workflow Integration | Siemens Healthineers creates reference-site effects in Bavaria and North Rhine-Westphalia for motion management attachment. |
| Software Subscription Unbundling | United States community oncology centers drive modular procurement separating hardware, motion management, and predictive analytics tiers. |
| EU MDR Clinical Evidence Investment | Stricter standards for electromagnetic tracking systems accelerate consolidation among vendors funding extensive trials. |
Research Methodology
FDA 510(k) filings, EMA MDR submissions, and hospital procurement databases formed the secondary backbone, cross-referenced against primary interviews with radiation oncology department heads, medical physicists, GPO contracts managers, and biomedical engineers. Bottom-up and top-down triangulation validated segment-level estimates against vendor-reported installed base data and reimbursement code utilization patterns.
Bottom-up modeling anchored projections to technology modality adoption curves and end-user procurement cycles, while top-down constraints applied macro healthcare infrastructure spending patterns across the analysis window. Segmentation dimensions included tracking technology, clinical application, deployment architecture, and regional regulatory cluster. CAGRs derived from fitted adoption curves incorporating proton therapy facility construction pipelines and diagnostic imaging protocol expansion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PMDA software-as-medical-device reclassification timing and electromagnetic component supply concentration. Forecasts reflect documented assumptions regarding reimbursement stability and clinical physics workforce availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Oscillating Positive Expiratory Pressure (OPEP) Devices Market
Respiratory Therapy
Breathing Disorders Treatment Market
Respiratory Therapy
Pneumoconiosis Treatment Market
Respiratory Therapy
Diaphragm Pacing Therapy System Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis Management Market
Respiratory Therapy
Home Respiratory Therapy Market
Respiratory Therapy
Virus-Induced Asthma Treatment Market
Respiratory Therapy
Chronic Obstructive Pulmonary Disease Treatment Market
Respiratory Therapy
Respiratory Biologics Market
Respiratory Therapy
Respiratory Inhaler Market
Respiratory Therapy
Bronchial Thermoplasty Market
Respiratory Therapy
Respiratory Trainer Market
Respiratory Therapy
Global Dyspnea Treatment Market
Respiratory Therapy
Global Pulmonary Surfactant Market
Respiratory Therapy
Severe Acute Respiratory Syndrome Treatment Market
Respiratory Therapy
Global Pneumonia Therapeutics Market