
 China Almond Market | 2026-2036
China Almond Market Size, Share, and Industry Trends Forecast 2026-2036
China Almond Market Insights
China's National Food Safety Standard for Nuts is recalibrating the cost-of-entry calculus for almond importers and domestic processors. Three Squirrels leverages its vertically integrated supply chain to control quality from sourcing to shelf-stable packaging. Blue Diamond Growers sustains its position through California-origin branding and bulk ingredient relationships with Chinese food manufacturers.
Almonds are the edible seeds of Prunus dulcis, typically containing 50-55% oil and 20-25% protein by dry weight, with blanching and dry-roasting constituting the primary processing methods for commercial use. Roasted almonds command premium shelf placement in supermarket chains, while almond flour is capturing margin pools from the gluten-free baking segment. Online retail channels are expanding fastest among distribution pathways, though specialty stores still dominate high-end gifting occasions.
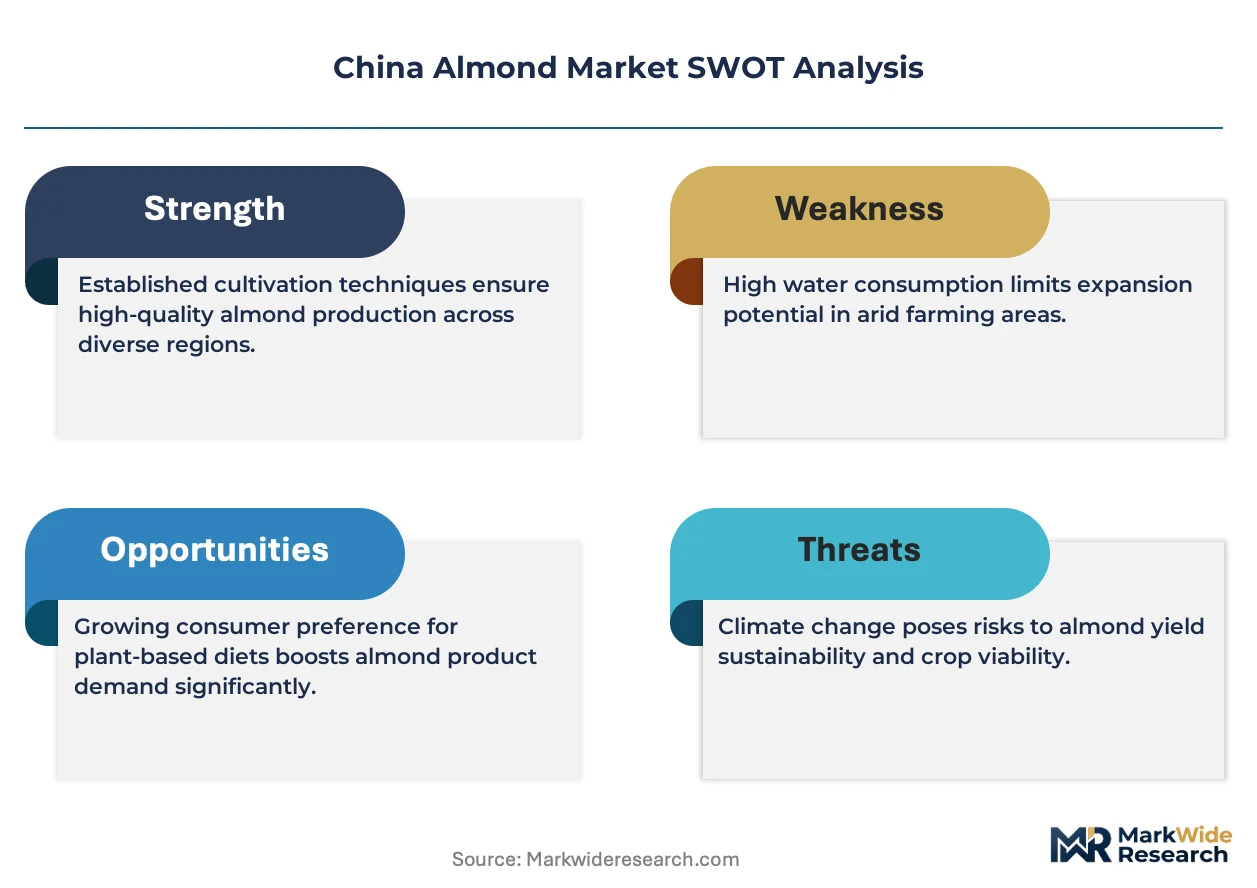
SAMR enforces labeling and food additive rules for packaged almond products, while GB standards set maximum residue limits for pesticides and heavy metals. China's customs administration coordinates with NMPA on import inspection protocols for tree nuts. Stakeholders must monitor how evolving green food certification requirements reshape sourcing decisions and consumer willingness to pay.
Market Dynamics
China's updated National Food Safety Standard for Nuts is recalibrating the cost-of-entry calculus for almond importers and domestic processors, tightening aflatoxin limits and import documentation requirements that reshape competitive positioning across the value chain.
Growth Catalysts
- Urban millennial snacking patterns:Metropolitan corridors in Shanghai, Guangzhou, and Beijing are driving premium packaged almond consumption as dietary protein diversification accelerates among younger consumers.
- GB standards enforcement:Stricter maximum residue limits for pesticides and heavy metals are consolidating market share toward processors with laboratory testing capabilities and traceable sourcing.
- Almond flour substitution:Gluten-free baking applications are displacing traditional wheat flour in commercial food manufacturing, creating new ingredient demand from Chinese bakery chains.
Market Restraints
- California supply concentration:Overwhelming dependence on a single origin state for raw almond supply exposes Chinese importers to drought-induced price volatility and shipping bottlenecks at Long Beach and Oakland ports.
- SAMR labeling compliance:Evolving food additive and nutritional labeling rules impose translation and reformulation costs that disproportionately burden smaller trading companies.
- Pistachio and cashew substitution:Alternative tree nuts from Iran, Vietnam, and domestic Chinese sources compete aggressively on price in mass-market retail channels.
Strategic Opportunities
- Green food certification expansion:China's dual carbon goals and MEE environmental directives are creating premium pricing tiers for almonds sourced through verified sustainable irrigation and low-carbon shipping routes.
- Online retail channel maturation:E-commerce platforms are capturing gifting occasions previously dominated by specialty stores, enabling direct-to-consumer relationships that bypass traditional wholesale markups.
- Third- and fourth-tier city penetration:Underdeveloped markets in central and western provincial capitals offer volume expansion potential as cold-chain infrastructure improves.
Industry Challenges
- Aflatoxin testing capacity constraints:Laboratory certification backlog at customs inspection points is extending clearance timelines and increasing working capital requirements for importers.
- Blanching and roasting equipment capex:Automated processing lines capable of meeting GB standards demand significant upfront investment that strains mid-scale domestic processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Almond Market |
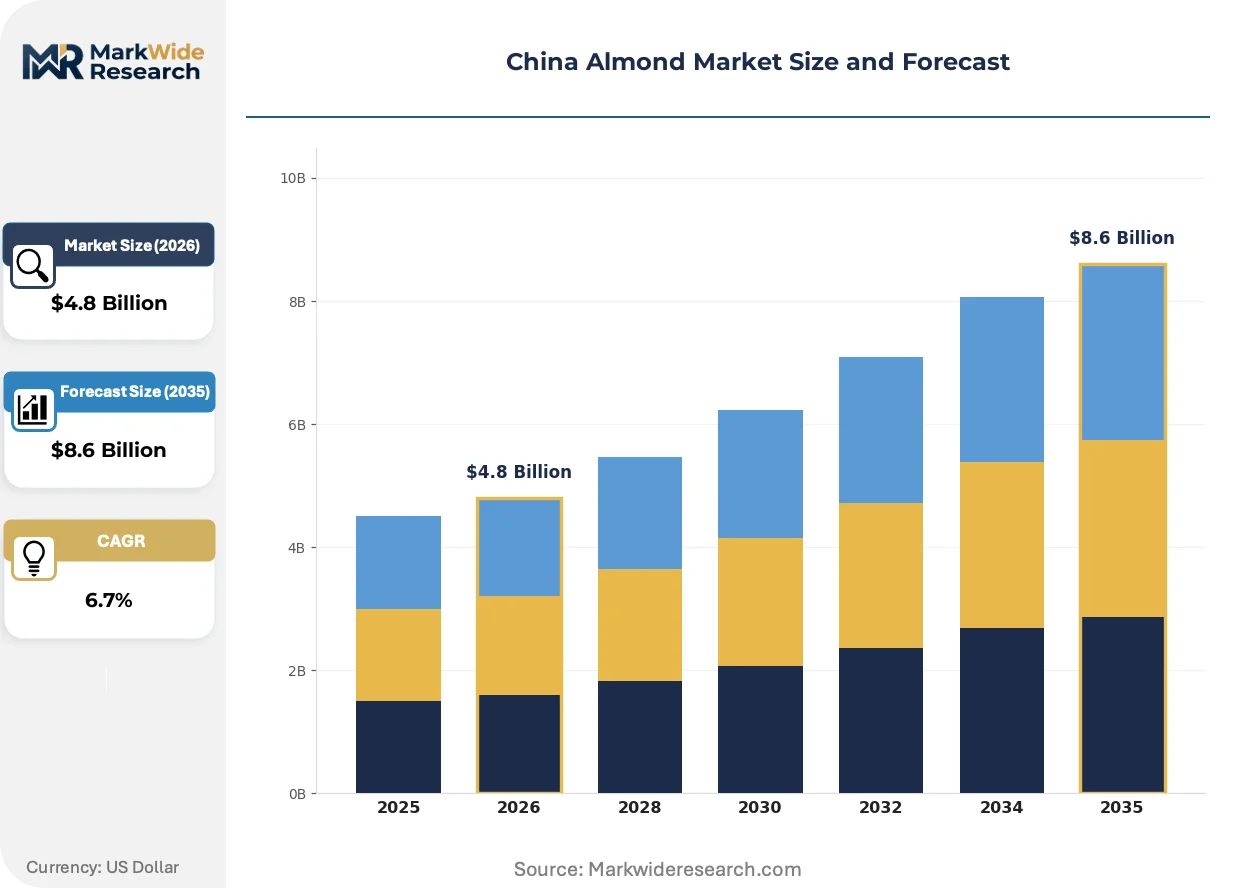
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Almonds, Roasted Almonds, Almond Flour, Almond Butter Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores End User: Food Manufacturers, Bakeries, Restaurants, Household Consumers Application: Snacking, Baking, Cooking, Health Supplements |
| Companies Covered | Hebei Chengde Lolo Co., Ltd., Three Squirrels, Huatai Foods, Lyfen Foods, Be & Cherry, Bestore, Yan Jin Pu Zi, Blue Diamond Growers, Select Harvests, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Almond Market Trends and Innovations
Processing technology and distribution infrastructure are actively reshaping how almonds move from California orchards to Chinese consumers, with quality verification systems and channel fragmentation driving capital allocation decisions across the value chain.
High-pressure pasteurization technology is decentralizing food safety assurance away from centralized import inspection points. Mid-scale Chinese processors are adopting in-house pathogen reduction systems to preempt customs delays. This capability shift is compressing clearance timelines and enabling just-in-time inventory models for domestic brands.
SAMR's evolving enforcement of GB standards for tree nuts is forcing reformulation of flavored and coated almond products. Manufacturers are removing certain food additives and redesigning packaging to meet stricter nutritional disclosure rules. Premium segments are responding fastest, with clean-label products capturing expanded shelf space in Shanghai and Beijing supermarket chains.
Live-streaming commerce is displacing traditional wholesale relationships in almond gifting segments. Influencer-led product demonstrations on short-video platforms are capturing Lunar New Year and Mid-Autumn Festival purchase occasions. This channel rotation is most visible in Guangdong and Zhejiang provinces, where digital-native consumers bypass brick-and-mortar specialty retailers for direct platform purchases.
China Almond Market Segmentation
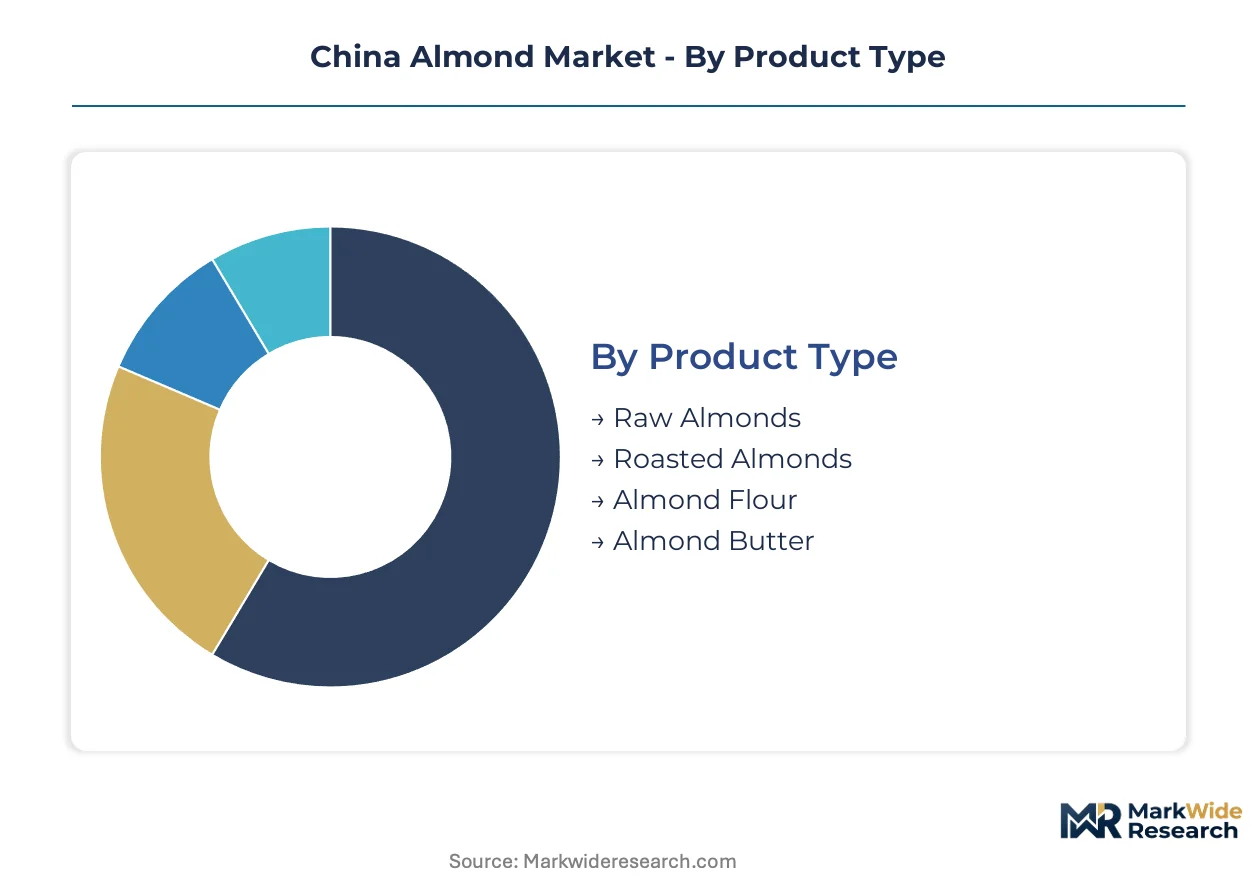
Almond segmentation in China reflects divergent compliance burdens across product formats and channels. SAMR's GB standards apply differential testing protocols to raw versus processed forms, while distribution pathways face distinct cold-chain and documentation requirements.
Product Type:
Certification intensity varies sharply across processing stages, with raw imports facing the heaviest aflatoxin scrutiny at customs and processed forms triggering additive and labeling reviews under SAMR jurisdiction.
- Raw Almonds:Unprocessed kernels enter China under stringent NMPA import inspection protocols with mandatory laboratory certification for aflatoxin B1 and total aflatoxin content. Demand concentrates among domestic roasters and food manufacturers in Guangdong and Shandong provinces, where processing capacity expansion is outpacing raw material availability.
- Roasted Almonds:Dry-heat processed kernels with moisture content below 5% undergo blanching, seasoning, and packaging operations subject to GB 19300 nut standards. Shanghai and Beijing supermarket chains command premium shelf placement for vacuum-sealed retail formats, driven by urban millennial preference for ready-to-eat protein snacks.
- Almond Flour:Finely ground blanched almonds serve gluten-free baking applications with protein content specifications typically ranging 20-25% by dry weight.
- Almond Butter:Paste products face dual scrutiny under GB standards for fat content and additive restrictions, with clean-label formulations gaining traction in specialty retail channels.
Raw almonds sit at the top of the volume ranking, with almond flour climbing the fastest.
Distribution Channel:
Channel selection determines margin capture and regulatory touchpoint density, with direct-to-consumer platforms bypassing wholesale markups but assuming greater labeling liability.
- Supermarkets:Bricks-and-mortar chains in tier-one cities allocate premium shelf space to roasted and packaged formats with visible green food certification logos. Carrefour, RT-Mart, and domestic chains like Yonghui enforce supplier qualification programs that exclude smaller importers lacking batch-level traceability systems.
- Online Retail:E-commerce platforms including Tmall and JD.com capture gifting occasions and subscription-based household replenishment with live-streaming commerce driving impulse purchases. Zhejiang and Guangdong consumers demonstrate highest per-capita online almond spending, with logistics networks enabling next-day delivery to provincial capitals.
- Convenience Stores:Small-format retail in urban corridors stocks single-serve roasted packages with limited SKU depth.
- Specialty Stores:Premium nut boutiques and import food shops in Shanghai and Beijing focus on gift-box assortments with origin labeling and organic certification.
Supermarkets retain the largest transaction volume, though online retail is expanding most quickly.
End User:
Downstream user categories exhibit divergent procurement scale and specification precision, with industrial buyers commanding volume discounts and household consumers driving premium pricing for convenience formats.
- Food Manufacturers:Industrial buyers in bakery, confectionery, and dairy substitute segments purchase bulk raw and blanched almonds with strict moisture and defect specifications. Yangtze River Delta processing clusters source container-scale shipments through direct California relationships, bypassing trading company markups.
- Household Consumers:Individual purchasers select packaged formats through omnichannel paths with snacking and home baking as primary use cases. Beijing and Shanghai households demonstrate highest willingness to pay for organic and green food certified products.
- Bakeries:Commercial bakery chains in tier-one and tier-two cities are adopting almond flour for gluten-free product lines.
- Restaurants:Foodservice procurement focuses on sliced and slivered almonds for garnish and texture applications.
Food manufacturers dominate procurement volume, while household consumers represent the steepest expansion trajectory.
Application:
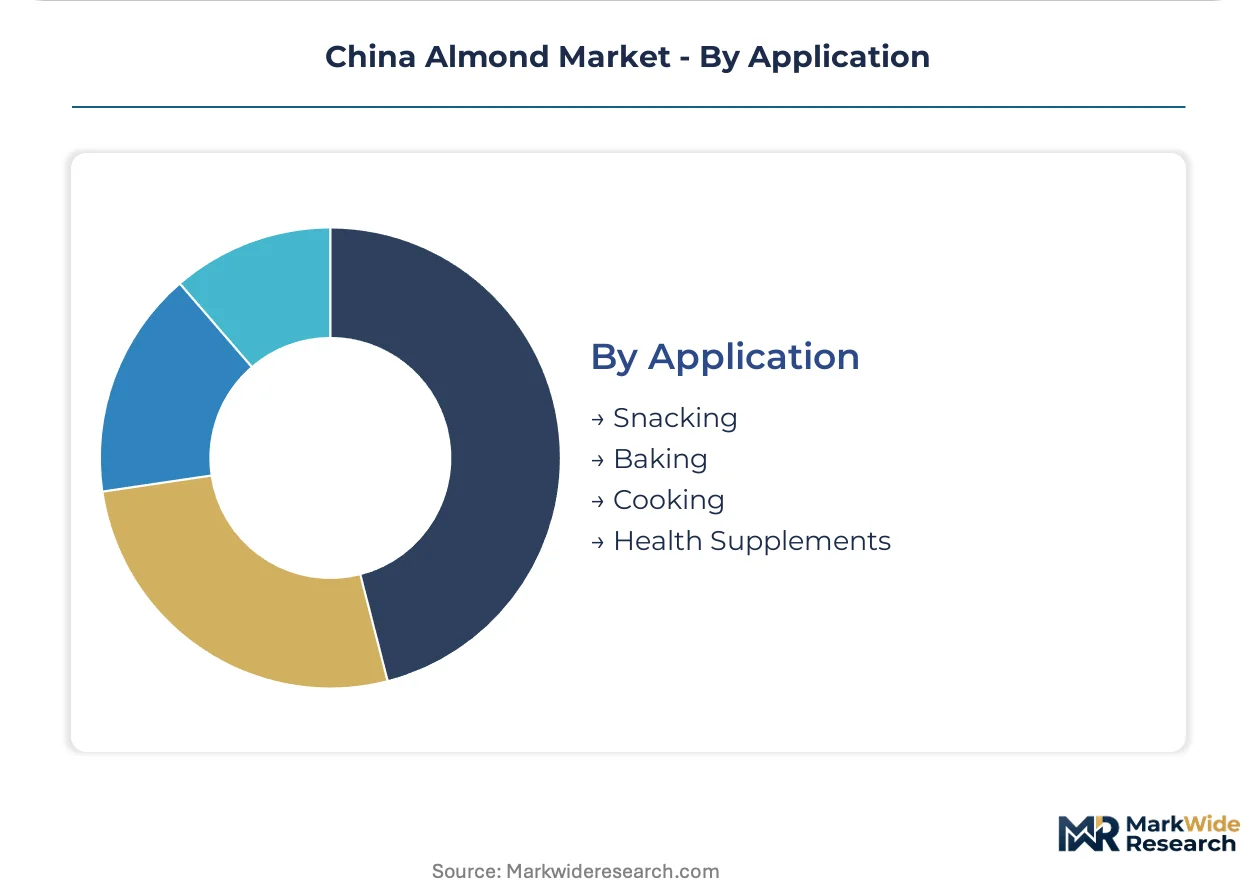
Use-case segmentation aligns with demographic and occasion-based demand patterns, with snacking applications capturing urban millennial spending and baking applications tied to health-conscious household formation.
- Snacking:Ready-to-eat roasted, flavored, and mixed nut formats target workplace consumption and transit-time eating occasions. Guangzhou, Shenzhen, and Shanghai metropolitan corridors generate disproportionate snacking demand among professionals aged 25-40 seeking protein diversification.
- Baking:Almond flour and sliced forms substitute for wheat flour in gluten-free recipes and add texture to traditional pastries. Domestic bakery chains and home baking enthusiasts in Jiangsu and Zhejiang provinces are accelerating ingredient demand.
- Cooking:Whole and slivered almonds appear in regional Chinese cuisine and Western-influenced restaurant preparations.
- Health Supplements:Oil extraction and powdered protein applications serve nutraceutical manufacturers with distinct purity specifications.
Snacking commands the highest absolute consumption volume, with baking applications gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Almond cultivation originated in Central Asia and the Middle East, with commercial scaling migrating to California's Central Valley during the twentieth century. Chinese consumption patterns now concentrate in coastal metropolitan corridors where cold-chain infrastructure and import logistics first matured.
Shanghai
Premium packaged almond demand concentrates among finance and technology professionals aged 25-40 seeking workplace protein snacks. SAMR's GB standards enforcement requires batch-level traceability documentation for all retail-bound shipments. Yangshan deep-water port and Pudong logistics clusters handle the largest import volumes, with bonded warehousing enabling just-in-time distribution to supermarket chains.
Guangzhou
Live-streaming commerce penetration exceeds national averages, with short-video platforms capturing Lunar New Year gifting occasions previously dominated by specialty retailers. NMPA coordinates customs inspection protocols with Guangdong provincial authorities at Nansha port. Pearl River Delta food manufacturers in Dongguan and Foshan process bulk raw almonds for bakery and confectionery ingredient supply.
Beijing
Household willingness to pay for organic and green food certified almonds exceeds other tier-one cities, driven by health-conscious consumption among dual-income professionals. MEE environmental directives on dual carbon goals shape municipal procurement preferences for low-carbon shipping routes. Daxing logistics hub and Tianjin port serve as the northern corridor's primary import gateways.
Zhejiang Province
E-commerce platform headquarters in Hangzhou anchor direct-to-consumer distribution models bypassing traditional wholesale markups. SAMR's evolving labeling rules impose reformulation costs on flavored almond products sold through Tmall and JD.com channels. Ningbo-Zhoushan port ranks second nationally for tree nut import tonnage, with cold-storage capacity expansion outpacing demand growth.
Sichuan-Chongqing
Third- and fourth-tier city penetration potential concentrates in Chengdu and Chongqing metropolitan areas where snacking culture converges with rising disposable incomes. GB standards laboratory certification requirements strain regional testing capacity, extending customs clearance timelines. Western China logistics infrastructure improvements enable next-day delivery to provincial capitals previously underserved by cold-chain networks.
China Almond Market Competitive Landscape
The competitive structure tilts toward domestic snack-food conglomerates with vertically controlled processing capabilities. Three Squirrels and Bestore anchor the premium branded segment through direct sourcing relationships and omnichannel distribution. California-origin cooperatives occupy the bulk ingredient tier supplying industrial food manufacturers. Strategic moves concentrate on cold-chain infrastructure partnerships and green food certification acquisition to meet MEE environmental directives.
Within the domestic branded tier, Three Squirrels exemplifies the vertically integrated archetype controlling quality from sourcing through shelf-stable packaging. Bestore and Lyfen Foods occupy positions emphasizing e-commerce native distribution and live-streaming commerce integration. Blue Diamond Growers anchors the import-origin segment through California-origin branding and bulk ingredient relationships with Yangtze River Delta food manufacturers. Hebei Chengde Lolo Co., Ltd. represents the regional processor archetype with concentration in northern China distribution networks.
| Leading Market Players |
|---|
| Hebei Chengde Lolo Co., Ltd. |
| Three Squirrels |
| Huatai Foods |
| Lyfen Foods |
| Be & Cherry |
| Bestore |
| Yan Jin Pu Zi |
| Blue Diamond Growers |
| Select Harvests |
| Others |
Pricing and Supply Chain Analysis
California-origin raw almond costs cascade through three distinct pricing tiers as shipments clear NMPA inspection at Yangshan, Ningbo-Zhoushan, and Tianjin ports, with aflatoxin testing backlogs and green food certification premiums determining final shelf positioning in Shanghai and Beijing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates green food certified organic almonds from conventional packaged formats and bulk unbranded kernels. Price differentiation hinges on certification tier and cold-chain integrity, with SAMR labeling compliance costs compressing margins in the standard tier. Pricing pressure stems from pistachio and cashew substitution in mass-market channels. Food manufacturers exhibit highest price sensitivity due to volume procurement scale, while gift-box purchasers in tier-one cities show lowest elasticity.
Supply Chain Analysis
Workforce availability constraints in Shandong and Guangdong processing clusters limit domestic roasting capacity expansion despite surging demand. Supply concentrates in California's Central Valley, with secondary sourcing from Australia and Spain emerging. Raw material dependencies center on irrigation-dependent almond orchards, ocean freight container allocation, and laboratory testing capacity at Chinese customs points. Single-source vulnerability to California drought cycles poses structural risk. Distribution runs through bonded warehousing at Yangshan and Ningbo-Zhoushan ports into omnichannel retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's almond market functions as a geographic-arbitrage play between California production costs and Chinese premium pricing, with NMPA inspection bottlenecks and MEE environmental directives creating regulatory spreads that favor compliant operators.
For Market Incumbents: Anchor defensive positioning through backward integration into California sourcing relationships and captive laboratory testing capacity to preempt customs delays. Three Squirrels and Bestore should expand cold-chain partnerships in Sichuan-Chongqing corridors before infrastructure maturation erodes first-mover advantage. SAMR's evolving GB standards for food additives threaten flavored product lines, requiring reformulation investment.
For New Entrants and Emerging Players: High-pressure pasteurization technology offers entry wedge into mid-scale processing tier, bypassing centralized inspection bottlenecks that constrain incumbents. Third- and fourth-tier city penetration in western China presents most penetrable white-space, with live-streaming commerce enabling direct-to-consumer bypass of entrenched wholesale relationships. Target green food certification acquisition as primary go-to-market differentiator.
For Investors and Strategic Acquirers: Consolidation pressure builds where laboratory testing capacity constraints meet working capital intensity for import clearance. Long-term viability favors vertically integrated processors with California direct relationships and domestic roasting infrastructure. Acquisition target archetype: mid-scale Guangdong or Shandong processors with NMPA-compliant facilities and underutilized capacity. Watch aflatoxin testing certification backlog duration as inflection signal for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Food Certification Acquisition | MEE environmental directives and dual carbon goals create premium pricing tiers for verified sustainable sourcing. |
| Cold-Chain Infrastructure Partnership | Western China logistics improvements unlock third- and fourth-tier city penetration in Sichuan-Chongqing corridors. |
| High-Pressure Pasteurization Deployment | In-house pathogen reduction systems compress NMPA customs clearance timelines and enable just-inventory models. |
| Direct-to-Consumer Platform Integration | Tmall and JD.com live-streaming commerce captures gifting occasions previously dominated by specialty retailers. |
| California Sourcing Relationship Deepening | Long-term offtake agreements with Central Valley cooperatives hedge drought-induced price volatility exposure. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with almond import managers, domestic roasting facility operators, SAMR regulatory affairs specialists, supermarket category buyers, and e-commerce platform merchants with secondary validation through NMPA import inspection protocols, GB standards documentation, MEE environmental directive filings, and customs trade records. Bottom-up shipment volume analysis and top-down consumer expenditure estimates were triangulated against processor capacity utilization data.
Comparable-period anchoring tied projection models to historical consumption patterns across the analysis window, with segmentation dimensions spanning product format, distribution channel, end-user category, and application use-case. CAGRs were derived through trend extrapolation moderated by regulatory enforcement intensity and infrastructure buildout schedules. Forecast inputs incorporated cold-chain network expansion timelines and live-streaming commerce penetration curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to California water policy shifts, NMPA laboratory certification capacity expansion, and MEE carbon accounting enforcement stringency. Forecasts reflect documented assumptions about continued urban millennial protein diversification and sustained pistachio substitution pressure. Material deviation in drought severity, customs clearance duration, or green food certification adoption rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Bambara Beans Market
Nuts and Seeds
South America Nut-Based Spread Market
Nuts and Seeds
Japan Fox Nuts Market
Nuts and Seeds
Almond with Shell Snack Market
Nuts and Seeds
Almond Kernels Market
Nuts and Seeds
Apricot Kernel Market
Nuts and Seeds
Nut Oil Market
Nuts and Seeds
Walnut Market
Nuts and Seeds
Processed Walnuts Market
Nuts and Seeds
United States Cashew Market
Nuts and Seeds
Baru Nuts Market
Nuts and Seeds
Thailand Fox Nuts Market
Nuts and Seeds
Low Fat Nut Butter Market
Nuts and Seeds
Europe Tahini Market
Nuts and Seeds
Nuts and Nut Products Market
Nuts and Seeds
Peanuts Market