
 China Pant Type Adult Diaper Market | 2026-2036
China Pant Type Adult Diaper Market Size, Share, and Industry Trends Forecast 2026-2036
China Pant Type Adult Diaper Market Insights
E-commerce platforms is narrowing the gap between pant diaper manufacturers and home caregivers across China's lower-tier cities. Hengan Group leverages its domestic supply chain to sustain price competitiveness in mass-market channels. Unicharm Corporation anchors its position through Japanese-engineered absorption technology that commands loyalty among premium buyers in Shanghai and Beijing. Vinda Paper competes aggressively on retail shelf space through partnerships with supermarket chains in South China.
Pant type adult diapers are pull-on disposable incontinence garments constructed with elasticized waistbands, breathable non-woven topsheets, and superabsorbent polymer cores designed for mobile users with moderate to heavy leakage. These products serve primarily community-dwelling elderly and post-surgical patients requiring dignity-preserving alternatives to tape-style briefs. Premium and overnight segments capture the deepest margin pools as Chinese consumers prioritize skin health and uninterrupted sleep. Eco-friendly variants incorporating bamboo fibers are expanding fastest among urban middle-class buyers despite higher unit pricing. Retail stores and hospital procurement channels still dominate volume, though e-commerce is capturing younger caregiver demographics seeking subscription convenience.
NMPA medical device registration requirements and GB/T standards for disposable hygiene products shape product safety benchmarks and factory audit protocols for domestic manufacturers. SAMR advertising enforcement restricts health claims that could mislead elderly consumers or their family purchasers. Stakeholders must monitor how provincial long-term care insurance pilots expand reimbursement eligibility for incontinence supplies in cities like Qingdao and Chengdu.
Market Dynamics
China's pant type adult diaper market is being fundamentally reshaped by the collision between NMPA medical device classification tightening and the rapid expansion of provincial long-term care insurance pilots that reimburse incontinence supplies.
Growth Catalysts
- Provincial LTC insurance pilots:Cities including Qingdao and Chengdu now reimburse pant diaper purchases, removing price barriers for home-based elderly care.
- GB standards elevation:Stricter GB/T benchmarks for disposable hygiene products are forcing factory upgrades that improve absorption performance and skin safety credentials.
- Jiangsu-Zhejiang manufacturing clusters:Proximity between aging populations and production hubs shortens logistics lead times and enables rapid SKU customization.
Market Restraints
- Superabsorbent polymer import dependency:Domestic SAP supply cannot yet match quality consistency of Japanese and Korean feedstock, exposing margins to yen-won exchange volatility.
- Non-woven topsheet concentration:Three coastal suppliers control over 60% of breathable SMS fabric capacity, creating bottleneck risk during peak seasonal demand.
- SAMR advertising friction:Health claims restrictions prevent manufacturers from communicating clinical benefits to family caregivers, compressing differentiation space.
Strategic Opportunities
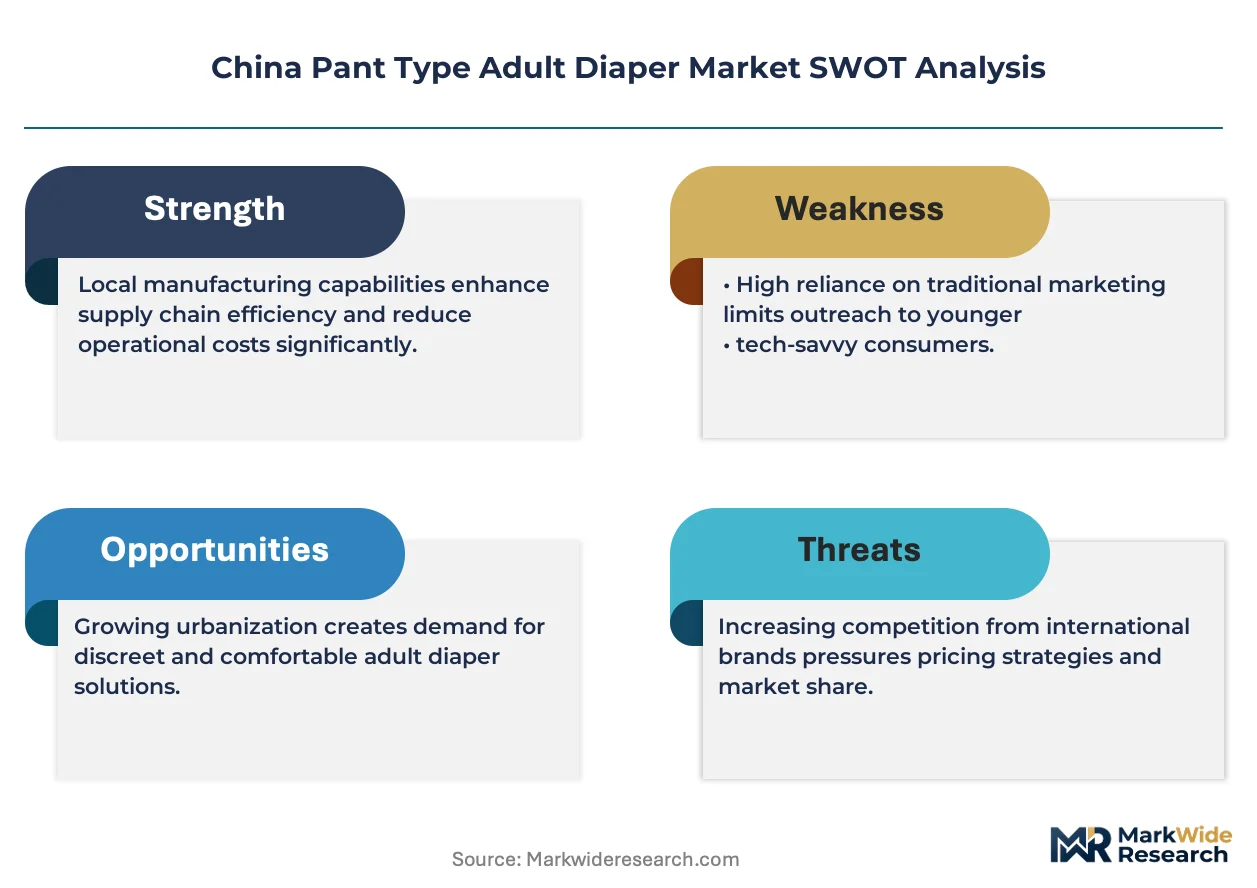
- Central province penetration:Henan and Sichuan provinces show 40% lower pant diaper usage rates than coastal peers despite comparable elderly demographics.
- Bamboo fiber premium tier:Eco-conscious urban middle-class buyers in Chengdu and Hangzhou are accepting 25-35% unit price premiums for biodegradable core materials.
- Subscription e-commerce channels:Tmall Health and JD Pharmacy are building auto-replenishment interfaces that lock in caregiver loyalty through convenience bundling.
Industry Challenges
- NMPA registration timeline compression:Medical device classification upgrades have extended product approval cycles to 14-18 months, delaying new absorption technology launches.
- Legacy tape-style brief substitution:Hospital procurement committees in tier-3 cities still favor lower-unit-cost tape products, forcing pant diaper suppliers to justify mobility benefits repeatedly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Pant Type Adult Diaper Market |
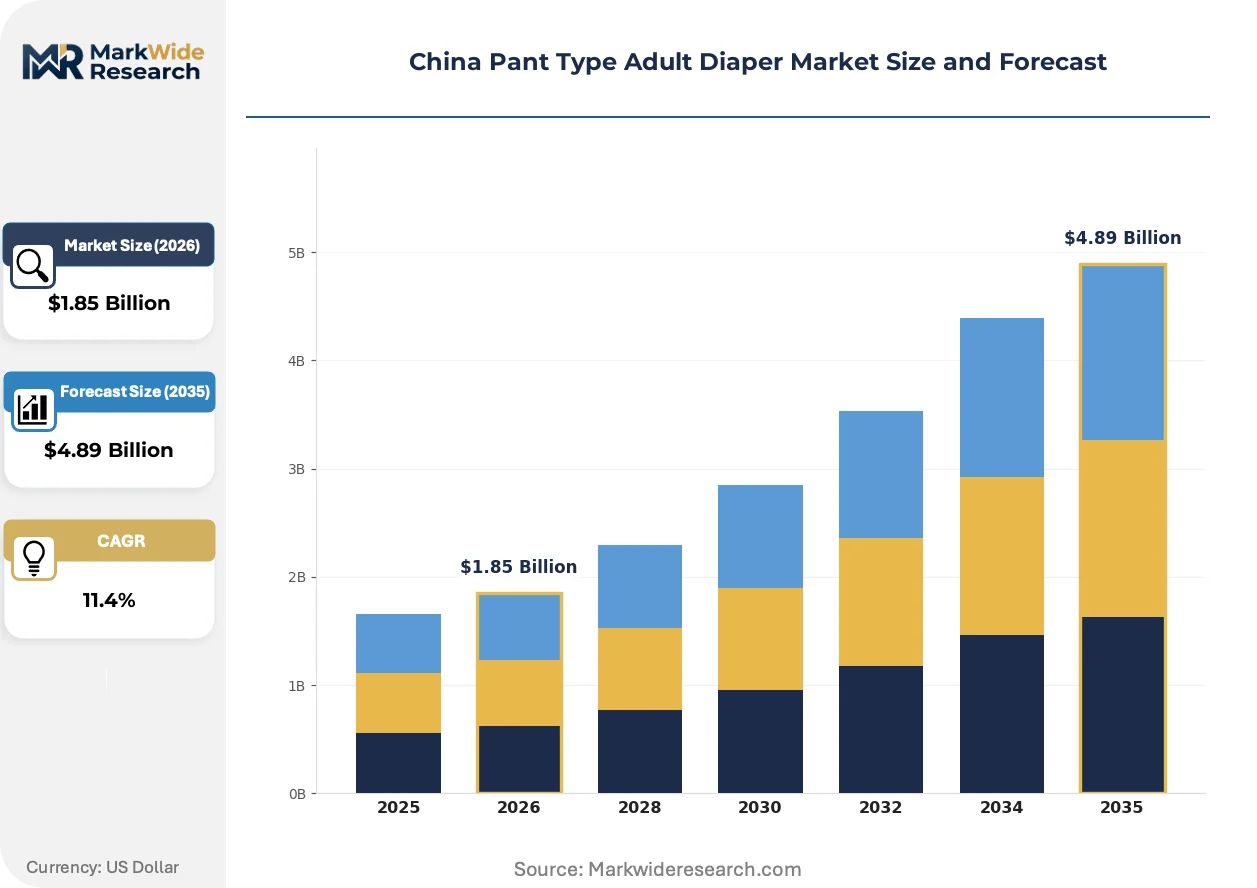
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Premium, Eco-friendly, Overnight Size: Small, Medium, Large, Extra Large Material: Cotton, Bamboo, Plastic, Non-woven Distribution Channel: Retail Stores, E-commerce, Pharmacies, Hospitals |
| Companies Covered | Hengan Group, Vinda Paper, Reliable Co., Ltd., Unicharm Corporation, Kimberly-Clark Corporation, Procter & Gamble Company, Kao Corporation, Sunkiss, Wehoo Hygiene, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Pant Type Adult Diaper Market Trends and Innovations
Product engineering and channel architecture are undergoing simultaneous transformation as Chinese manufacturers respond to reimbursement policy shifts and caregiver expectations for dignity-preserving design.
Superabsorbent polymer core engineering is migrating from petroleum-based sodium polyacrylate to bio-based alternatives derived from agricultural cellulose. Premium manufacturers in Zhejiang province are piloting these cores for overnight segments where skin breathability commands caregiver loyalty. This migration from synthetic to renewable feedstocks is compressing the cost gap between eco-certified and conventional products.
NMPA medical device registration rules now mandate clinical validation for products claiming moderate-to-heavy leakage protection. Factory audit protocols have expanded to include raw material traceability documentation. Manufacturers targeting hospital procurement channels are responding by segregating production lines between medical-grade and retail-grade SKUs.
Caregiver purchasing behavior is fragmenting across generational lines. Adult children in Shanghai and Beijing are consolidating orders through subscription platforms that bundle pant diapers with skin care accessories. This channel shift is displacing traditional supermarket bulk buying among younger caregivers while reinforcing retail loyalty among rural elderly who lack smartphone proficiency.
China Pant Type Adult Diaper Market Segmentation
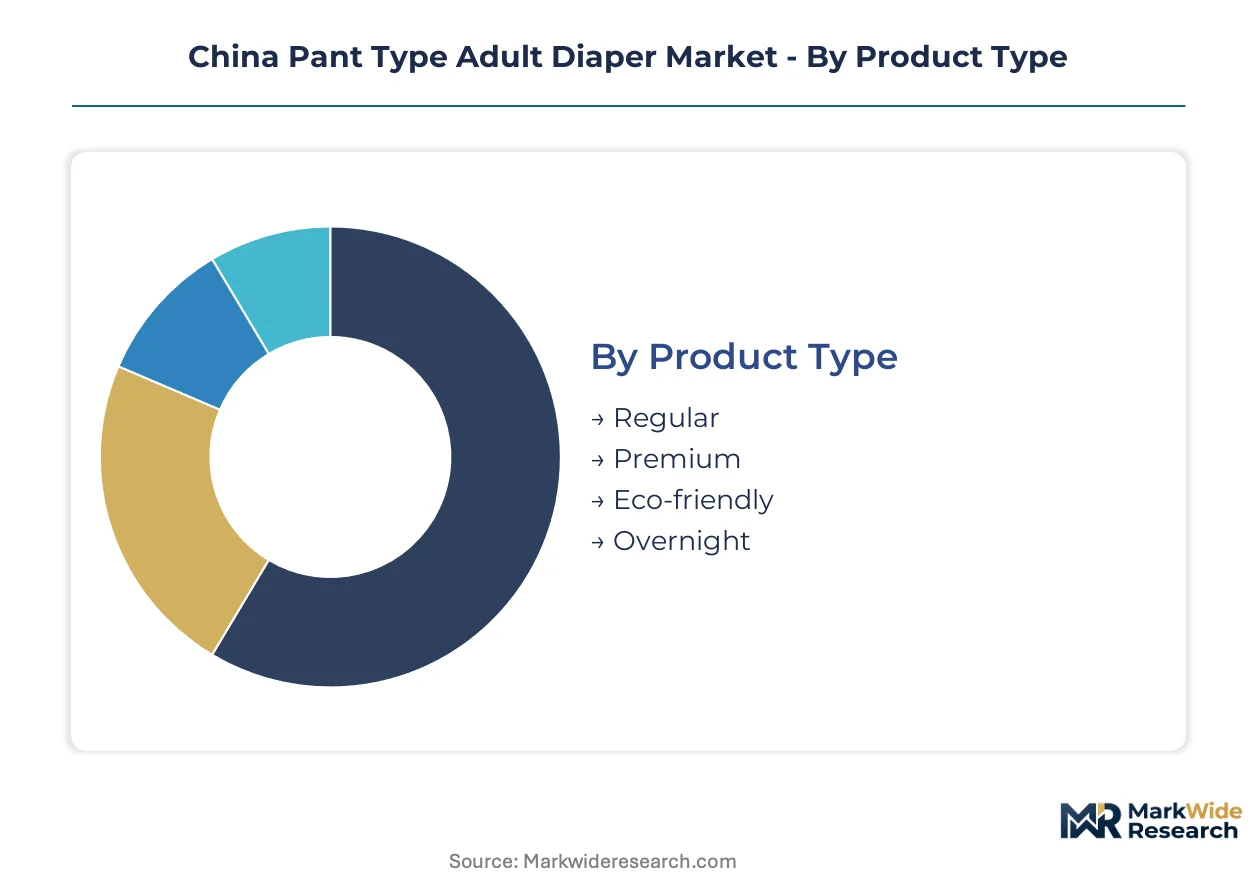
Segmentation in China's pant diaper market reveals how reimbursement policies, caregiver demographics, and manufacturing capabilities split demand across incompatible purchasing logics. Each dimension carries distinct margin profiles and regulatory exposure that shape competitive positioning.
Product Type:
Inventory velocity varies dramatically across performance tiers, with institutional buyers cycling through basic SKUs fastest while premium households stockpile for quarterly replenishment.
- Premium:Japanese-engineered absorption cores with breathable non-woven topsheets command loyalty among Shanghai and Beijing caregivers prioritizing skin health. Hospital procurement committees in tier-2 cities increasingly specify this tier for post-surgical discharge kits as NMPA medical device rules elevate quality benchmarks.
- Eco-friendly:Bamboo fiber cores and biodegradable backsheet films target urban middle-class buyers in Chengdu and Hangzhou accepting 25-35% unit price premiums. SAMR advertising restrictions on health claims compress marketing differentiation, forcing manufacturers to rely on packaging transparency and third-party certifications.
- Regular:Standard SAP cores with polyethylene backsheets serve price-sensitive rural elderly through supermarket bulk purchasing in Jiangsu province.
- Overnight:Extended-wear designs with dual-core engineering and leg cuff barriers address uninterrupted sleep priorities among community-dwelling dementia patients.
Regular dominates installed base. Eco-friendly is where expansion concentrates.
Size:
Production line changeover frequency and raw material waste rates scale inversely with size tier, making Extra Large the costliest to manufacture despite lower absolute volumes.
- Large:Elasticized waistbands with 90-120cm hip circumference specifications capture the densest elderly demographic cluster across Jiangsu and Zhejiang provinces. Manufacturing hubs near demand centers enable rapid SKU customization for regional body-type variations.
- Medium:75-95cm specifications serve post-surgical recovery patients and early-stage mobility impairment cases in provincial hospital systems.
- Extra Large:Reinforced leg gathers and wider chassis designs address bariatric elderly populations in northern Chinese provinces.
- Small:Narrow waistbands for petite elderly and certain neurological conditions requiring minimal bulk.
Large holds the deepest volume concentration. Extra Large shows the steepest expansion trajectory as obesity rates climb among aging populations.
Material:
Feedstock sourcing geography and import dependency create divergent margin stability across material categories, with domestic bamboo supply chains insulating against yen-won exchange volatility.
- Non-woven:SMS (spunbond-meltblown-spunbond) polypropylene topsheets from Zhejiang coastal suppliers control over 60% of breathable fabric capacity, creating bottleneck risk during peak seasonal demand around Lunar New Year caregiving spikes.
- Bamboo:Agricultural cellulose cores from Sichuan and Fujian plantations are climbing the fastest as bio-based alternatives compress cost gaps with petroleum-based sodium polyacrylate.
- Cotton:Natural fiber comfort layers for skin-sensitive users in premium retail channels.
- Plastic:Polyethylene backsheets and acquisition layers in economy-tier products for institutional bulk purchasing.
Non-woven dominates installed base. Bamboo is where expansion concentrates.
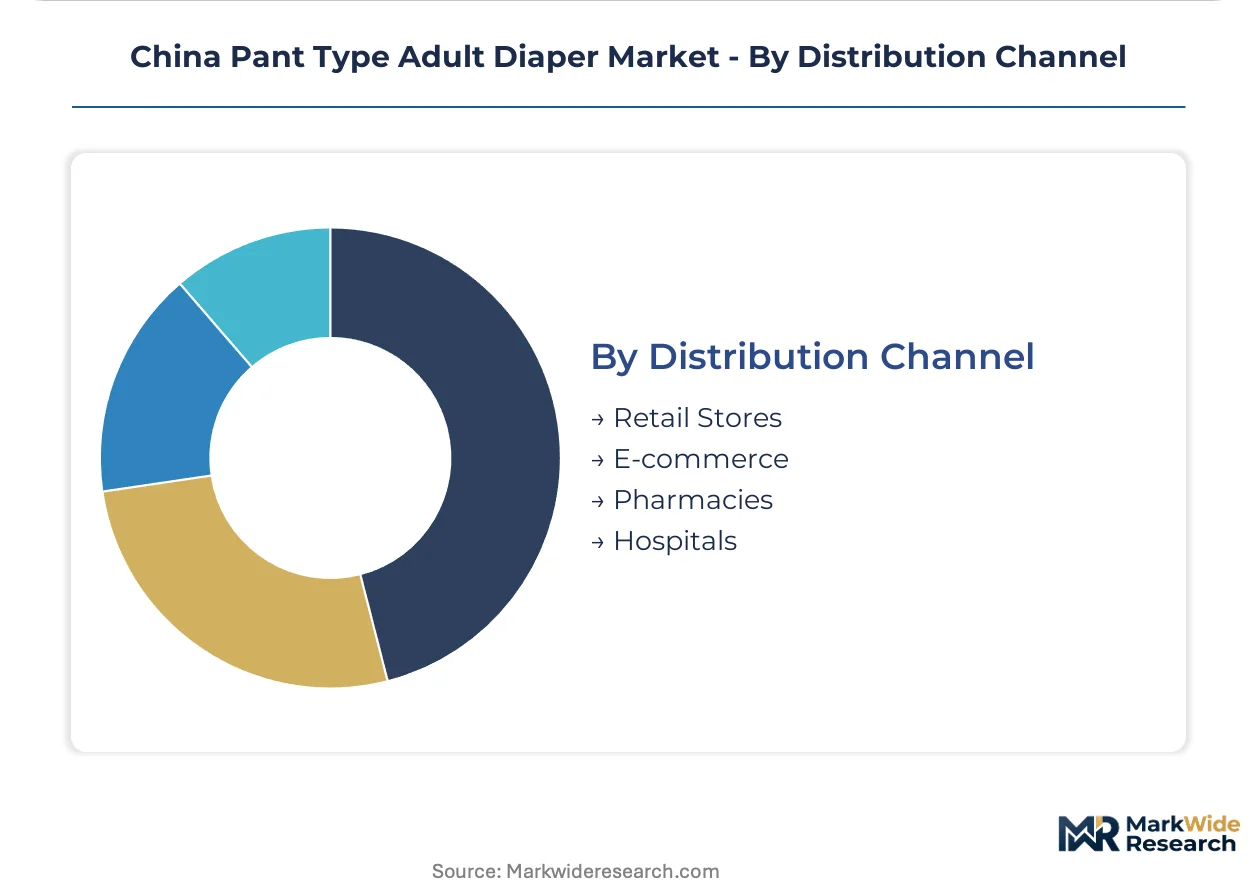
Distribution Channel:
Channel switching costs and caregiver age demographics segment purchasing behavior, with younger adult children consolidating through digital platforms while elderly users remain anchored to physical retail.
- E-commerce:Tmall Health and JD Pharmacy auto-replenishment interfaces lock in caregiver loyalty through subscription bundling with skin care accessories. Younger adult children in Shanghai and Beijing drive this channel's expansion.
- Retail Stores:Supermarket chains in South China and hypermarket bulk displays sustain loyalty among rural elderly lacking smartphone proficiency. Vinda Paper competes aggressively for shelf space through exclusive partnerships.
- Hospitals:NMPA medical device registration mandates clinical validation for moderate-to-heavy leakage claims, forcing manufacturers to segregate production lines between medical-grade and retail-grade SKUs.
- Pharmacies:JD Pharmacy and local drugstore chains serve emergency replenishment needs and LTC insurance reimbursement processing in pilot cities like Qingdao and Chengdu.
Retail Stores dominates installed base. E-commerce is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provincial long-term care insurance pilots are redistributing pant diaper demand across China's eastern manufacturing belt and interior provinces. Reimbursement eligibility in pilot cities is removing price barriers for home-based elderly care. Manufacturing proximity to aging demographic clusters is shortening logistics lead times and enabling rapid SKU customization.
Jiangsu
Home-based elderly care services are expanding pant diaper adoption across Suzhou and Nanjing metropolitan areas. NMPA medical device classification rules enforce clinical validation requirements for products claiming moderate-to-heavy absorption. Manufacturing hubs in Wuxi and Changzhou enable rapid customization of elasticized waistband specifications for regional body-type variations.
Zhejiang
Hangzhou's urban middle-class buyers are accepting 25-35% unit price premiums for bamboo fiber eco-friendly variants. GB standards for disposable hygiene products mandate stricter factory audit protocols including raw material traceability documentation. Ningbo coastal suppliers control over 60% of breathable SMS non-woven fabric capacity, creating seasonal bottleneck risk around Lunar New Year.
Sichuan
Chengdu's long-term care insurance pilot now reimburses pant diaper purchases, removing price barriers for dementia patient households. SAMR advertising enforcement restricts health claims that could mislead elderly consumers or family purchasers. Manufacturing clusters near Chongqing are piloting bio-based superabsorbent polymer cores derived from regional agricultural cellulose feedstocks.
Shandong
Qingdao's provincial LTC insurance expansion is driving institutional procurement of overnight dual-core designs for community-dwelling elderly. GB/T benchmarks for skin safety credentials are forcing factory upgrades among domestic manufacturers. Weihai and Yantai production facilities are segregating medical-grade and retail-grade SKUs to satisfy NMPA hospital channel requirements.
Guangdong
Pearl River Delta manufacturing bases are supplying South China retail chains through aggressive shelf space partnerships. SAMR health claims restrictions compress differentiation space for manufacturers targeting family caregivers. Shenzhen and Dongguan logistics networks are enabling e-commerce subscription fulfillment to younger adult children caregivers in Guangzhou and Foshan.
China Pant Type Adult Diaper Market Competitive Landscape
On the supply side, the industry is tiered across multinational absorption technology specialists, domestic supply chain integrators, and regional fabricators serving institutional procurement channels. Three strategic archetypes dominate: Japanese-engineered premium brands commanding loyalty in coastal tier-1 cities, Chinese mass-market players leveraging backward integration into pulp and non-woven feedstocks, and Korean-European hybrids targeting hospital discharge kit specifications. Capacity expansion and SKU segregation between medical-grade and retail-grade production lines represent the dominant competitive moves as NMPA registration timelines extend.
Among multinational specialists, Unicharm Corporation and Kimberly-Clark Corporation exemplify the premium-tier archetype through absorption core engineering that commands caregiver loyalty in Shanghai and Beijing. Hengan Group occupies a position within the domestic supply chain integrator tier, representing mass-market competitiveness through manufacturing proximity to Jiangsu-Zhejiang demand clusters.
| Leading Market Players |
|---|
| Hengan Group |
| Vinda Paper |
| Reliable Co., Ltd. |
| Unicharm Corporation |
| Kimberly-Clark Corporation |
| Procter & Gamble Company |
| Kao Corporation |
| Sunkiss |
| Wehoo Hygiene |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta freight corridors channel raw material inputs from Zhejiang non-woven suppliers to Jiangsu manufacturing hubs, with logistics cost volatility amplifying pricing power for coastal fabricators while compressing margins for inland distributors serving price-sensitive rural buyers.
Pricing Analysis
Certification level (NMPA medical device registration vs. retail-grade GB compliance) creates the primary spread between premium and economy tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with NMPA-registered hospital SKUs commanding the widest premiums over supermarket bulk packs. Cost compression in the economy tier is intensifying because Hengan and Vinda are competing for rural elderly volume through aggressive shelf-space payments. Hospital procurement committees show the least price sensitivity, while home-based caregivers in tier-3 cities demonstrate acute elasticity to unit cost changes.
Supply Chain Analysis
Contract manufacturing concentrates among Zhejiang coastal suppliers controlling SMS non-woven capacity and Sichuan-based bamboo fiber processors. Feedstock sourcing draws from Japanese and Korean superabsorbent polymer imports, domestic polypropylene resin, and Sichuan-Fujian agricultural cellulose. Single-source vulnerability in breathable topsheet fabric creates bottleneck risk during Lunar New Year demand spikes. Distribution runs through hospital procurement committees, supermarket chain partnerships, and Tmall Health subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate substitution pressure from reusable incontinence garments and smart monitoring devices that threaten to displace disposable pant diaper volumes in premium urban households.
For Market Incumbents: Pre-empt regulatory capture by accelerating NMPA medical device registration for overnight dual-core SKUs before timeline compression extends further. Secure backward integration into bamboo fiber supply through partnerships with Sichuan plantation operators to insulate margins from yen-won SAP import volatility. Defend against smart device substitution by bundling pant diapers with skin health monitoring accessories through JD Pharmacy subscription interfaces. For New Entrants and Emerging Players: Pursue white-space penetration in Henan and Sichuan provinces where LTC insurance reimbursement is expanding but pant diaper usage rates trail coastal benchmarks by 40%. Target pharmacy channel relationships in Qingdao and Chengdu pilot cities to capture reimbursement processing workflows before incumbent shelf-space deals harden. Differentiate through biodegradable core certifications that command urban middle-class premiums despite SAMR advertising restrictions. For Investors and Strategic Acquirers: Carve-out targets emerge from domestic hygiene conglomerates seeking to monetize non-core adult diaper divisions amid portfolio rationalization pressures. Long-term viability hinges on reimbursement policy expansion rather than demographic tailwinds alone. Monitor provincial LTC insurance pilot extensions beyond Qingdao and Chengdu as the critical inflection signal for volume acceleration in central provinces.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Medical Device Registration | Unlocks hospital procurement channels requiring clinical validation for moderate-to-heavy absorption claims. |
| Bamboo Fiber Supply Integration | Captures urban eco-premium demand while insulating margins from petroleum-based SAP import volatility. |
| Subscription E-Commerce Partnership | Locks in caregiver loyalty through Tmall Health auto-replenishment bundling with skin care accessories. |
| Provincial LTC Insurance Alignment | Positions products for reimbursement eligibility in expanding pilot cities like Chengdu and Qingdao. |
| Medical-Retail SKU Segregation | Enables dual-channel positioning while satisfying NMPA factory audit protocols for hospital-grade production. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement managers, GPO contract specialists, elderly care service operators, and NMPA regulatory consultants; and secondary validation against SAMR enforcement bulletins, provincial LTC insurance policy documents, GB standards technical specifications, and customs import records for superabsorbent polymer feedstocks. Bottom-up demand modeling triangulated against top-down manufacturing capacity assessments across Jiangsu-Zhejiang production clusters.
Forecast inputs incorporated absorption technology substitution curves, reimbursement policy diffusion patterns across provincial pilot cities, and caregiver demographic transitions from retail bulk buying to e-commerce subscription adoption. Segmentation dimensions spanned performance tier, size specification, material feedstock, and distribution channel. CAGRs were derived from volume build-ups across these segments calibrated to observed pricing elasticity in hospital versus retail channels.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Korean-European hybrid manufacturers or accelerated smart incontinence device launches would shift outcomes beyond modeled ranges. Quarterly review of provincial LTC insurance pilot announcements and NMPA registration backlog data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
Malaysia Diapers Market
Baby Diapers
UAE Baby Diapers Industry Market
Baby Diapers
Nonwoven Baby Diaper Market
Baby Diapers
GCC Diaper Market
Baby Diapers
Diaper Market
Baby Diapers
North America Diaper Market
Baby Diapers
Disposable Hygiene Products Market
Baby Diapers
Australia Pant Type Adult Diaper Market
Baby Diapers
Biodegradable Diapers Market
Baby Diapers
Baby Cloth Diaper Market
Baby Diapers
Africa and India Baby Diapers Market
Baby Diapers
Baby Disposable Diapers Market
Baby Diapers
Pet Diapers Market
Baby Diapers
Smart Connected Diaper Market
Baby Diapers
Adult Diapers Market
Baby Diapers
Baby Diaper Manufacturing Machine Market