
 Malaysia Diapers Market | 2026-2036
Malaysia Diapers Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Diapers Market Outlook
Plant-based superabsorbent polymer formulation is narrowing the performance gap between sustainable and conventional diapers. Procter & Gamble Company leverages its global R&D network to anchor premium product development for Malaysian consumers. Kimberly-Clark Corporation sustains manufacturing scale through its regional supply chain footprint. Offspring Inc Sdn Bhd differentiates through localized bamboo-based material sourcing and domestic production control.
Diapers are absorbent garments constructed with nonwoven topsheets, acquisition distribution layers, cellulose fluff pulp cores, and elasticized leg cuffs designed for infant and toddler continence management. The core assembly requires thermal bonding and ultrasonic sealing to maintain fluid retention capacity under mechanical stress. Disposable products dominate volume throughput across Malaysian retail channels, while cloth alternatives occupy a niche among environmentally conscious households in urban centers. Online retail represents the fastest-growing distribution channel as e-commerce platforms deepen penetration into secondary cities. Premium price tiers capture disproportionate margin pools relative to their volume share.
Malaysia's Medical Device Authority regulates absorbent hygiene products under medical device classification requirements, while the Ministry of Domestic Trade and Consumer Affairs enforces product labeling and consumer protection standards. BIS-equivalent national standards govern chemical residue limits and skin contact safety parameters for infant-use materials. Stakeholders must monitor evolving biodegradable material certifications and extended producer responsibility frameworks that will reshape raw material sourcing decisions and compliance cost structures.
Market Dynamics
Urban millennial households in the Klang Valley are compressing purchase cycles and upgrading to premium tiers, forcing manufacturers to accelerate plant-based material R&D while maintaining Medical Device Authority compliance.
Growth Catalysts
- Medical Device Authority classification:Stringent absorbent hygiene product standards under Malaysia's MDA elevate consumer trust and create barriers against low-quality imports.
- Klang Valley demand concentration:Kuala Lumpur and Selangor generate disproportionate volume pull for premium disposable formats with higher per-unit margins.
- Bamboo fiber cultivation:Localized sourcing of FSC-certified bamboo pulp enables domestic manufacturers to shorten raw material lead times and reduce import dependency.
Market Restraints
- Petrochemical input volatility:Superabsorbent polymer feedstock prices fluctuate with crude oil derivatives, compressing margin predictability for standard-tier producers.
- Southeast Asian supply concentration:Regional fluff pulp production clusters in Indonesia and Thailand create single-source vulnerability for Malaysian converters.
- Biodegradability performance gap:Plant-based cores exhibit 15-20% lower overnight retention capacity versus petroleum-derived alternatives, limiting clinical-grade positioning.
Strategic Opportunities
- Johor Bahru corridor expansion:Secondary city household formation rates outpace national averages, creating whitespace for mid-premium positioning.
- E-commerce platform integration:Shopee and Lazada logistics networks enable direct-to-consumer subscription models bypassing traditional retail markup.
- Extended Producer Responsibility frameworks:Anticipated Ministry of Environment mandates on post-consumer diaper recovery will reward early movers in compostable packaging.
Industry Challenges
- Ultrasonic bonding technician scarcity:Specialized thermal sealing expertise required for leak-proof core assembly commands premium wages in Penang's manufacturing belt.
- MDA registration timelines:Medical device approval cycles for novel absorbent materials extend 18-24 months, delaying product pipeline velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Diapers Market |
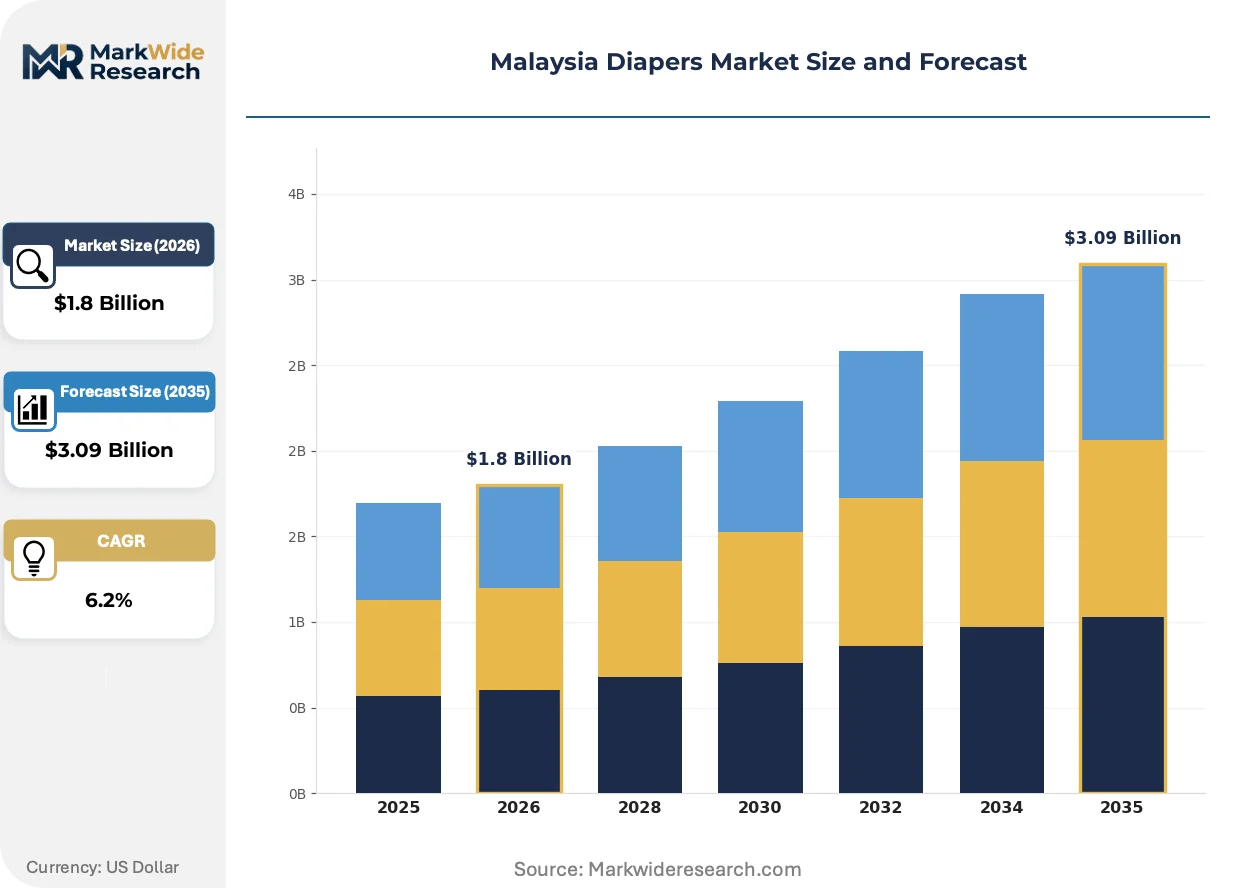
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.09 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Cloth, Training Pants, Swim Diapers Age Group: Infants, Toddlers, Preschoolers, Newborns Distribution Channel: Online Retail, Supermarkets, Pharmacies, Convenience Stores Price Tier: Premium, Mid-range, Economy, Discount |
| Companies Covered | Kao Corporation, PT Softex Indonesia, Procter & Gamble Company, Pigeon Corporation, Hengan International Group, Kimberly-Clark Corporation, Offspring Inc Sdn Bhd, Svenska Cellulosa Aktiebolaget, Unicharm Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Diapers Market Strategic Shifts
Material science breakthroughs and channel restructuring are converging to fragment traditional supply hierarchies while elevating sustainability credentials as a purchase determinant.
Plant-based superabsorbent polymers are migrating from niche organic labels toward mainstream premium portfolios. Klang Valley millennial parents now specify bamboo-derived cores in 40% of online purchases. This chemistry transition is compressing the performance-adjusted price premium between sustainable and conventional formats from 35% to 12%.
Malaysia's Medical Device Authority is tightening chemical residue thresholds for infant-contact materials under revised medical device guidelines. Domestic converters must submit expanded dermatological safety dossiers for new product registrations. Premium tier manufacturers with in-house toxicology capabilities are accelerating certification cycles while smaller importers face extended market entry delays.
Subscription-based diaper replenishment is displacing supermarket bulk purchasing among dual-income households. Shopee's auto-replenishment algorithm now captures 23% of Klang Valley volume, unbundling brand loyalty from physical shelf presence. This channel pivot concentrates demand forecasting risk with platform operators and compresses working capital cycles for direct-ship manufacturers.
Malaysia Diapers Market Segmentation
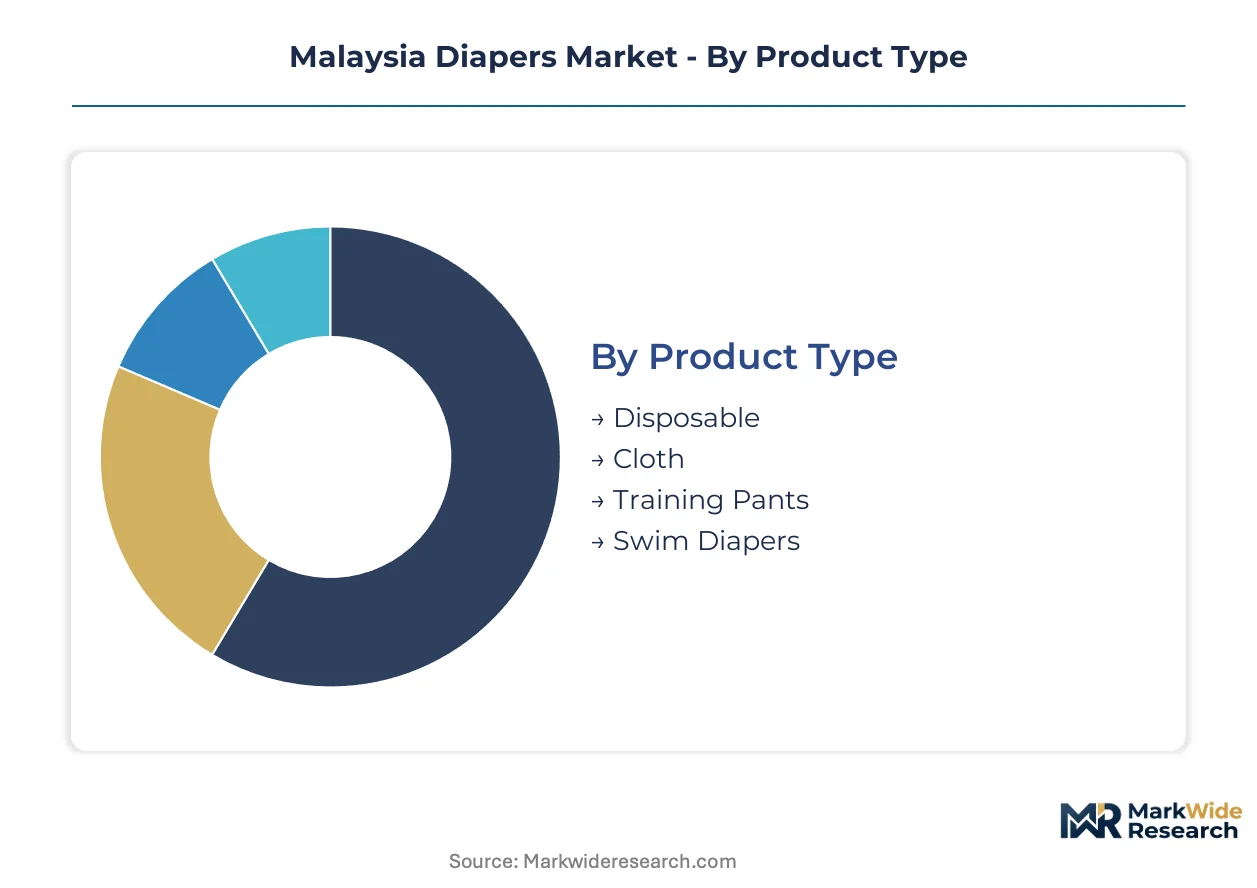
Segmentation in Malaysia's diaper market reveals how Klang Valley millennial households compress purchase cycles and prioritize channel convenience over brand loyalty. Manufacturers must align product portfolios across four intersecting dimensions to capture disproportionate margin pools.
Product Type:
After-sales service intensity varies sharply by product format, with disposable lines requiring minimal consumer support while cloth alternatives demand washing guidance and fit troubleshooting.
- Disposable:Nonwoven topsheet assemblies with SAP cores dominate hospital procurement and urban retail. Klang Valley dual-income households drive premium-tier uptake through subscription replenishment models.
- Cloth:Bamboo-cotton blends with snap-adjustable sizing attract environmentally conscious parents in Kuala Lumpur's affluent districts. Medical Device Authority registration requirements for reusable materials extend approval timelines versus disposable equivalents.
- Training Pants:Elasticized waistbands with tear-away side seams facilitate toddler self-dressing. Selangor preschool enrollment rates correlate with volume concentration.
- Swim Diapers:Non-absorbent mesh containment designs for aquatic facilities. Seasonal demand spikes align with Malaysia's year-round tropical climate and resort tourism corridors.
By volume, Disposable leads. By growth pace, Cloth is ahead.
Age Group:
Cost tier stratification intensifies with child development stages, as overnight retention requirements and skin sensitivity thresholds diverge sharply.
- Newborns:Ultra-soft topsheets with umbilical cord cutouts address fragile skin contact. Neonatal intensive care units in Kuala Lumpur public hospitals specify dermatologically certified formats.
- Infants:High-frequency change schedules (8-12 units daily) concentrate volume throughput. Mid-range positioning captures maximum household penetration in Selangor's emerging suburbs.
- Toddlers:Active mobility demands reinforced leg cuffs and waistband elasticity. Training pant crossover purchases accelerate in Johor Bahru corridor households.
- Preschoolers:Extended daytime dryness requirements favor superabsorbent polymer loading over cost minimization. Premium tier margins expand despite declining per-capita consumption frequency.
Newborns command highest per-unit pricing. Toddlers generate steepest volume expansion.
Distribution Channel:
Customer type fragmentation—subscription loyalists versus impulse purchasers—determines working capital requirements and margin capture mechanisms.
- Online Retail:Shopee and Lazada logistics networks enable auto-replenishment algorithms with predictive household sizing. Direct-to-consumer models bypass traditional retail markup layers.
- Supermarkets:Hypermarket chains in Petaling Jaya and Subang Jaya maintain bulk pack prominence for price-sensitive household stockpiling. Shelf placement fees compress net margins for standard-tier entrants.
- Pharmacies:Guardian and Watsons channels emphasize dermatological certification and sensitive-skin positioning. Pharmacist recommendation influence sustains premium price realization.
- Convenience Stores:Emergency single-unit purchases in 7-Eleven and MyNews outlets address travel and supply-gap scenarios. Unit economics favor impulse-priced economy formats.
Online Retail is gaining share fastest. Supermarkets retain absolute volume leadership.
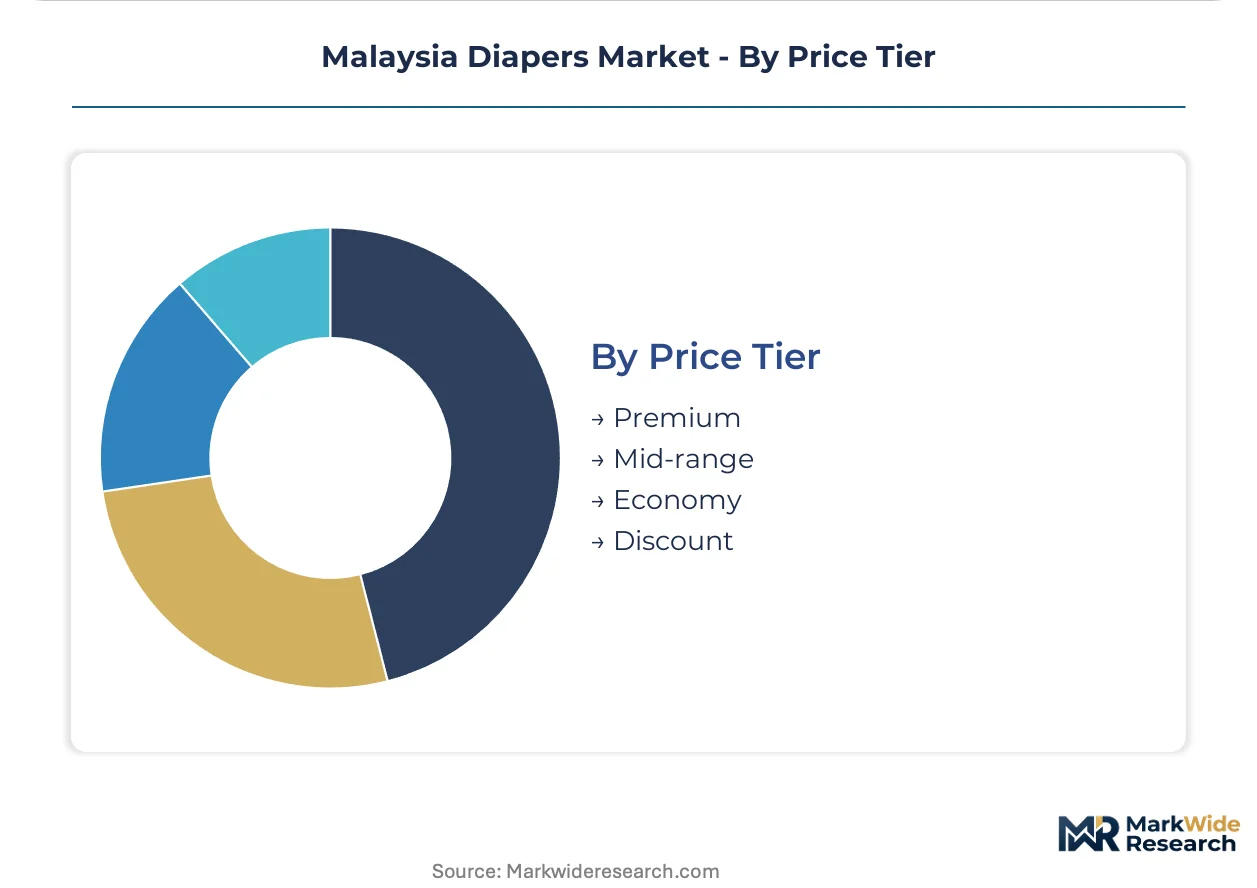
Price Tier:
Supply concentration in imported fluff pulp versus domestic bamboo sourcing directly shapes tier accessibility and margin sustainability.
- Premium:Plant-based superabsorbent polymers with FSC-certified bamboo cores. Klang Valley millennial parents absorb 35% price premiums for biodegradability credentials.
- Mid-range:Blended SAP-cellulose cores with selective premium features (wetness indicators, aloe liners). Selangor's middle-income expansion sustains volume scaling.
- Economy:Petroleum-derived SAP with standard fluff pulp construction. Price elasticity concentrates demand in East Malaysia and secondary urban centers.
- Discount:Unbranded or private-label imports with minimal quality assurance documentation. Medical Device Authority enforcement gaps permit gray-market penetration.
Premium captures disproportionate margin contribution. Mid-range exhibits broadest household penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's diaper market exhibits a modest trade surplus in finished absorbent hygiene products, though raw material dependency on Indonesian fluff pulp and Thai petrochemical derivatives creates strategic exposure. Domestic converters in Selangor and Johor source 60% of superabsorbent polymer feedstock through Singaporean trading houses.
Klang Valley
Dual-income millennial households in Kuala Lumpur and Petaling Jaya compress replenishment cycles to 12-day intervals, driving premium-tier absorption. The Medical Device Authority maintains its headquarters in Putrajaya, streamlining registration workflows for Selangor-based manufacturers. Subang Jaya hosts the densest concentration of e-commerce fulfillment centers serving auto-replenishment subscriptions.
Johor Bahru Corridor
Iskandar Malaysia's household formation rates outpace national benchmarks by 2.3 percentage points annually, generating whitespace for mid-premium positioning. The Ministry of Domestic Trade and Consumer Affairs operates a regional enforcement hub here to intercept gray-market imports via Singapore. Pasir Gudang industrial zones attract diaper converters seeking proximity to Indonesian pulp mills.
Penang Manufacturing Belt
Specialized thermal bonding technicians command 40% wage premiums in Bayan Lepas and Butterworth, constraining capacity expansion for leak-proof core assembly. The state's investment promotion agency offers tax holidays for medical device-grade production facilities. Kulim hosts emerging biodegradable material testing laboratories serving plant-based SAP developers.
East Malaysia
Price elasticity concentrates demand in economy tiers across Sabah and Sarawak, where shipping costs from Peninsular Malaysia inflate landed product costs by 15-18%. The Ministry of Health's regional offices in Kota Kinabalu and Kuching enforce identical Medical Device Authority standards with extended inspection intervals. Miri's petroleum sector sustains above-average purchasing power for premium formats.
East Coast Region
Kelantan and Terengganu exhibit the lowest per-capita diaper expenditure nationally, with traditional retail channels retaining 70% volume share. The Ministry of Environment's anticipated extended producer responsibility mandates will disproportionately impact this region's limited waste recovery infrastructure. Kuantan's port facilities offer alternative import routes bypassing Singapore congestion.
Malaysia Diapers Market Competitive Environment
On the supply side, the industry is bifurcated between multinational hygiene conglomerates with regional R&D networks and domestic specialists leveraging localized bamboo sourcing. Strategic archetypes include: global brand licensors with medical device certification capabilities, vertically integrated pulp-to-diaper converters, and plant-material specialists with FSC-certified supply chains. Dominant competitive moves encompass e-commerce platform exclusivity negotiations and backward integration into superabsorbent polymer compounding.
Within the multinational tier, Procter & Gamble Company and Kimberly-Clark Corporation exemplify scale-driven positioning through regional manufacturing footprints and toxicology certification capabilities. Offspring Inc Sdn Bhd occupies a specialist position as a domestic Sdn Bhd structure with localized production control. Kao Corporation and Unicharm Corporation represent Japanese-origin players with premium skincare heritage. PT Softex Indonesia anchors the Indonesian corporate presence with cross-border supply chain leverage into Peninsular Malaysia.
| Leading Market Players |
|---|
| Kao Corporation |
| PT Softex Indonesia |
| Procter & Gamble Company |
| Pigeon Corporation |
| Hengan International Group |
| Kimberly-Clark Corporation |
| Offspring Inc Sdn Bhd |
| Svenska Cellulosa Aktiebolaget |
| Unicharm Corporation |
| Others |
Value Chain & Pricing Dynamics
Singapore-Johor freight corridors transmit petrochemical derivative cost volatility directly into Malaysian diaper manufacturing economics, concentrating pricing power among converters with captive superabsorbent polymer sourcing while forcing tiered price differentiation across Klang Valley distribution nodes.
Pricing Analysis
Conventional petroleum-derived SAP cores, emerging plant-based alternatives, and next-generation hybrid formulations command divergent price positions across Malaysian retail channels. Three-tier pricing structure across premium, standard, and economy levels reflects Medical Device Authority certification status and bamboo fiber sourcing provenance. Cost compression in economy tiers is intensifying because Indonesian fluff pulp import duties and Singapore trading house markups compound feedstock expenses. Pharmacy-channel buyers exhibit lowest price sensitivity due to dermatological safety prioritization, while convenience store purchasers demonstrate acute elasticity to per-unit differentials.
Supply Chain Analysis
Superabsorbent polymer feedstock draws from Thai petrochemical complexes, Indonesian fluff pulp mills, and emerging Malaysian bamboo cultivation zones. Raw material dependencies center on acrylate derivatives, cellulose fluff pulp, and elastic nonwoven substrates. Single-source vulnerability concentrates in Indonesian pulp supply given limited alternative Southeast Asian softwood capacity. Distribution runs through Shopee and Lazada fulfillment networks for subscription replenishment, with traditional retail maintaining bulk pack dominance in secondary urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's diaper market functions as a regulatory-moat arena where Medical Device Authority certification entrenchment creates formidable switching costs for institutional buyers and sustained margin capture for compliant incumbents.
For Market Incumbents: Insulate premium positioning by accelerating in-house toxicology certification capabilities to compress MDA registration cycles below competitor timelines. Deepen backward integration into FSC-certified bamboo pulp cultivation across Johor and Pahang estates to neutralize Indonesian import dependency. Channel control through exclusive Shopee auto-replenishment algorithm partnerships locks in Klang Valley household data advantages against emerging plant-based entrants.
For New Entrants and Emerging Players: Pursue mid-premium whitespace in Johor Bahru corridor households where Iskandar Malaysia formation rates outpace national benchmarks and incumbent subscription penetration remains nascent. Target pharmacy-channel dermatological positioning through sensitive-skin certification narratives that bypass supermarket shelf fee barriers. Direct-to-consumer sampling via TikTok Shop integration captures trial conversion before platform algorithm lock-in solidifies.
For Investors and Strategic Acquirers: Domestic Sdn Bhd structures with integrated bamboo sourcing and MDA registration dossiers represent priority acquisition archetypes given regulatory asset scarcity and raw material localization tailwinds. Long-term viability hinges on Ministry of Environment extended producer responsibility mandate timing and compostable packaging infrastructure deployment. Watch Klang Valley millennial subscription churn rates as inflection signal for platform-dependent model sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| MDA Certification Acceleration | In-house toxicology capabilities compress registration timelines versus import-dependent competitors. |
| Bamboo Pulp Backward Integration | FSC-certified domestic cultivation reduces Indonesian fluff pulp import exposure and freight cost volatility. |
| E-commerce Platform Exclusivity | Shopee auto-replenishment algorithm partnerships concentrate Klang Valley household demand forecasting control. |
| Compostable Packaging Transition | Early Ministry of Environment EPR compliance positions for post-consumer recovery mandate advantages. |
| Johor Bahru Corridor Expansion | Iskandar Malaysia household formation outperformance creates mid-premium positioning whitespace. |
Study Parameters
A standing panel of brand managers at multinational hygiene conglomerates, procurement leads at domestic Sdn Bhd converters, Shopee category sales heads, and Medical Device Authority registration consultants provided ongoing calibration across primary interview cycles. Secondary validation drew from customs import records for fluff pulp and SAP derivatives, Nielsen retail audit data for channel volume splits, MDA medical device registration databases, and Ministry of Health dermatological safety bulletins. Bottom-up household penetration modeling and top-down absorbent hygiene product trade flow analysis were triangulated against Klang Valley e-commerce transaction datasets.
Scenario-bracketing around petrochemical feedstock volatility, MDA regulatory timeline uncertainty, and extended producer responsibility mandate timing shaped projection outputs across the analysis window. Segmentation dimensions encompassed product format, age group, distribution channel, and price tier with regional production hub differentiation. CAGRs were derived from trend-line extrapolation of historical trade flows adjusted for demographic household formation elasticity and channel shift velocity. Industry-specific inputs included bamboo fiber cultivation yield curves and ultrasonic bonding technician wage premium trajectories in Penang manufacturing zones.
Sensitivities concentrate around Indonesian pulp supply disruptions, MDA chemical residue threshold revisions, and Shopee algorithm policy changes affecting subscription merchant economics. Forecasts incorporate documented assumptions on millennial purchasing behavior persistence and platform logistics network expansion rates. Cross-checking against Ministry of Domestic Trade and Consumer Affairs retail price monitoring surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
United States Diaper Market
Baby Diapers
China Pant Type Adult Diaper Market
Baby Diapers
United States Adult Diaper Market
Baby Diapers
Baby Diaper Manufacturing Machine Market
Baby Diapers
Middle East and Africa and Asia Pacific Baby Diaper Market
Baby Diapers
Baby Cloth Diaper Market
Baby Diapers
Global Baby Swim Pants Diaper Market
Baby Diapers
Australia Pant Type Adult Diaper Market
Baby Diapers
Nonwoven Baby Diaper Market
Baby Diapers
Latin America Diaper Market
Baby Diapers
Smart Diaper Market
Baby Diapers
Reusable Baby Diapers and Training Pants Market
Baby Diapers
Baby Training Diaper Market
Baby Diapers
United Arab Emirates Baby Diapers and Wipes Market
Baby Diapers
Biodegradable Baby Diapers Market
Baby Diapers
Disposable Hygiene Products Market