
 GCC Diaper Market | 2026-2036
GCC Diaper Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Diaper Market Intelligence
Saudi manufacturing clusters is decoupling from import dependency as domestic absorbent hygiene capacity expands across the GCC. Procter & Gamble Company leverages its regional distribution infrastructure to sustain shelf presence in hypermarket channels. Kimberly-Clark Corporation anchors its competitive position through specialized adult care lines targeting institutional buyers. Essity AB differentiates via sustainability credentials in biodegradable product development.
A diaper constitutes a multi-layer absorbent garment engineered with superabsorbent polymer cores, nonwoven top sheets, and elasticized closures designed for urine and fecal containment across infant, child, and adult user groups. Disposable products dominate volume throughput across GCC retail channels, while biodegradable segments attract premium positioning among environmentally conscious consumers in the UAE. Adult incontinence applications represent the fastest-growing age group category as Gulf healthcare systems expand homecare coverage for elderly populations.
SASO (Saudi Standards, Metrology and Quality Organization) mandates product safety certification for all imported and domestically manufactured diapers sold in Saudi Arabia, creating compliance barriers for unverified suppliers. The UAE's Ministry of Industry and Advanced Technology enforces labeling and materials standards through its Emirates Conformity Assessment Scheme. Gulf Cooperation Council customs harmonization continues to streamline cross-border hygiene product movement. Stakeholders must monitor evolving biodegradable certification requirements as municipal waste regulations tighten across member states.
Market Dynamics
SASO certification requirements and domestic manufacturing expansion are restructuring competitive entry barriers across Saudi Arabia and neighboring emirates. Local production capacity is displacing import-reliant supply models while regulatory compliance costs filter marginal participants from distribution channels.
Growth Catalysts
- Institutional procurement reform:Saudi healthcare privatization is expanding homecare service contracts for elderly incontinence management. Government tenders now specify absorbent hygiene bundles for long-term care facilities.
- Superabsorbent polymer localization:Petrochemical feedstock advantages in the Eastern Province are attracting SAP precursor manufacturing. Downstream diaper producers secure captive raw material supply.
- Biodegradable certification pathways:UAE municipal waste regulations are creating premium positioning for compostable hygiene products. Emirates Conformity Assessment Scheme labeling accelerates retail placement.
Market Restraints
- Petrochemical price volatility:Polypropylene and polyethylene input costs fluctuate with crude oil benchmarks. Margins compress during feedstock spike periods without pricing power.
- Import concentration risk:Nonwoven fabric supply remains concentrated among Turkish and Chinese specialty mills. GCC producers face currency exposure and shipping timeline uncertainty.
- SASO testing bottlenecks:Laboratory capacity constraints extend product registration timelines. New market entrants encounter six-to-nine month approval delays.
Strategic Opportunities
- Kuwait and Bahrain penetration:Underdeveloped retail infrastructure in these markets offers first-mover shelf space advantages. Hypermarket expansion plans target underserved suburbs.
- E-commerce subscription models:Direct-to-consumer platforms are bypassing traditional distributor markups. Recurring delivery schedules lock in household purchasing patterns.
- Adult care institutional contracts:Hospital discharge planning now includes homecare hygiene provisioning. Medical equipment suppliers are bundling absorbent products with mobility aids.
Industry Challenges
- Technical talent scarcity:Polymer chemistry and nonwoven engineering expertise remains concentrated in European and Asian manufacturing hubs. Local vocational training programs lack specialized absorbent hygiene curricula.
- Legacy ERP integration:Domestic producers upgrading from manual inventory systems face data migration complexity. Real-time production monitoring requires substantial IT infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Diaper Market |
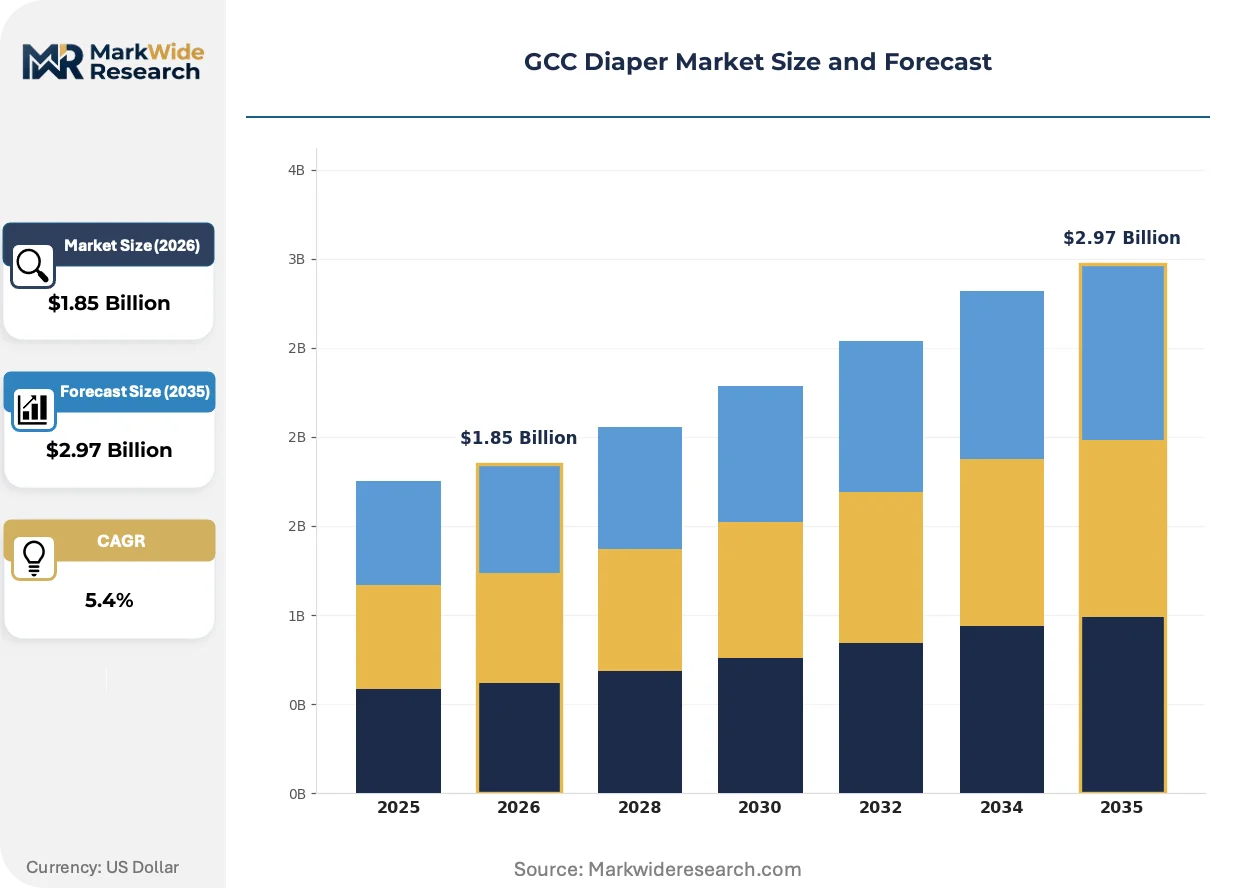
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Cloth, Biodegradable, Training Pants Age Group: Infants, Toddlers, Children, Adults Distribution Channel: Supermarkets, Pharmacies, Online Retail, Convenience Stores Price Tier: Premium, Mid-Range, Economy, Value Packs |
| Companies Covered | Essity AB, Hissam Group, Procter & Gamble Company, Hayat Kimya Sanayi A.S., Saudi Disposable Hygiene Products Co. Ltd., Kimberly-Clark Corporation, Fine Hygienic Holding, Abena Group, Unicharm Corporation, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Diaper Market Strategic Shifts & Innovations
Absorbent hygiene manufacturing is pivoting toward sustainability credentialing and supply chain regionalization. Technology deployment and procurement behavior are diverging from legacy import-dependent models.
Plant-based superabsorbent polymer formulations derived from starch and cellulose feedstocks are entering pilot production at Saudi manufacturing facilities. Premium product lines targeting UAE retail channels are adopting these materials to meet municipal composting standards. Core component sourcing is modularizing, allowing producers to swap petroleum-based inputs for certified biodegradable alternatives without line reconfiguration.
SASO implemented updated product safety labeling requirements in 2024, mandating Arabic-language ingredient disclosure and absorbency performance metrics. Importers must resubmit existing registrations, creating temporary SKU rationalization pressure. Adult incontinence segments face the steepest compliance burden due to medical device classification overlap.
Hospital purchasing departments are consolidating absorbent hygiene procurement through group purchasing organizations. Individual facility buying authority is contracting as health system centralization advances. Saudi Arabia's Ministry of Health standardization directives are accelerating this concentration, with specified product categories and volume commitments replacing fragmented spot purchasing.
GCC Diaper Market Segmentation
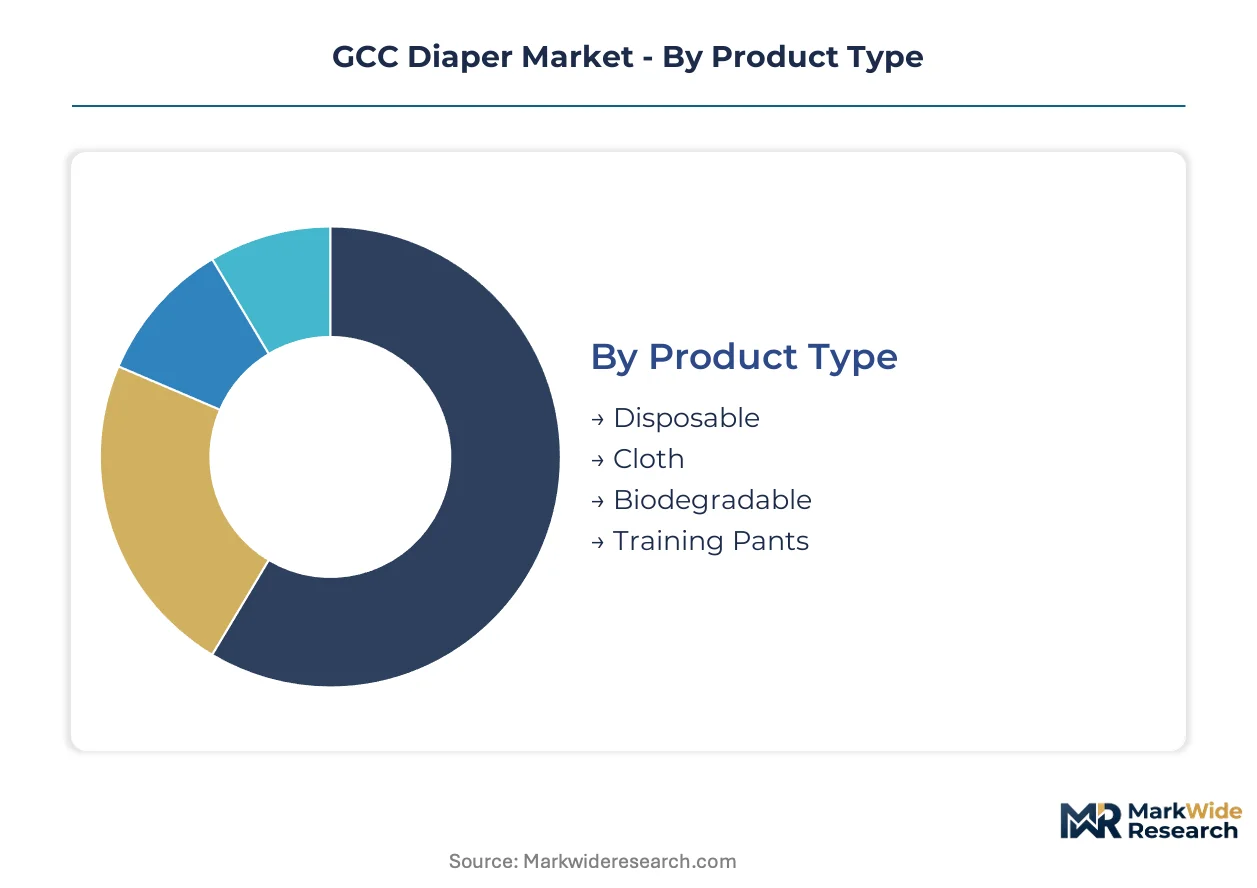
Segmentation in the GCC diaper market reveals how procurement patterns diverge across institutional and retail channels. Product specifications, age-targeted formulations, and price positioning create distinct competitive arenas that manufacturers must navigate simultaneously.
Product Type:
Supply concentration varies sharply by product technology, with domestic manufacturing clusters favoring high-throughput formats over specialized alternatives.
- Disposable:Multi-layer construction with superabsorbent polymer cores and elasticized closures dominates hospital procurement and household bulk purchasing. Saudi Arabia's Eastern Province petrochemical corridor supplies captive raw materials to regional producers, insulating margins from import volatility.
- Biodegradable:Plant-based superabsorbent formulations derived from starch and cellulose feedstocks target UAE municipal composting compliance. Premium positioning in Dubai and Abu Dhabi retail channels absorbs certification costs through price architecture.
- Cloth:Reusable cotton and bamboo blends serve cost-conscious segments and environmental advocates in smaller Gulf markets.
- Training Pants:Pull-up designs with tear-away sides address toddler mobility requirements in urban Saudi households.
Disposable formats absorb the bulk of installed capacity; biodegradable alternatives are expanding most quickly.
Age Group:
Demand concentration tracks demographic structure and healthcare system coverage expansion across member states.
- Adults:Incontinence management products for elderly homecare and long-term care facilities represent the steepest expansion trajectory. Saudi healthcare privatization drives tender specifications for absorbent hygiene bundles in Riyadh and Jeddah corridors.
- Infants:Newborn-specific sizing with umbilical cord cutouts and ultra-soft top sheets concentrates volume in hypermarket channels.
- Toddlers:Higher absorbency cores and active-fit engineering target mobility-stage development in UAE urban centers.
- Children:Overnight and bedwetting solutions serve delayed toilet-training segments in Kuwait and Bahrain.
Adult segments command premium pricing power; infant formats maintain volume leadership.
Distribution Channel:
Channel economics reflect inventory carrying costs and regulatory compliance burdens that reshape margin structures.
- Supermarkets:Hypermarket chains in Riyadh, Jeddah, and Dubai anchor volume throughput with dedicated aisle space and private label placement. Shelf fees and promotional calendars concentrate negotiating leverage among three retail groups.
- Online Retail:Subscription platforms bypass distributor markups with recurring delivery schedules. Direct-to-consumer growth concentrates in UAE emirates with mature logistics infrastructure.
- Pharmacies:Adult incontinence products with medical device classification overlap dominate prescription-adjacent purchasing.
- Convenience Stores:Emergency and travel-size SKUs serve immediate-need occasions in petrol station retail networks.
Supermarkets retain the largest share of volume throughput; online channels are gaining share fastest.
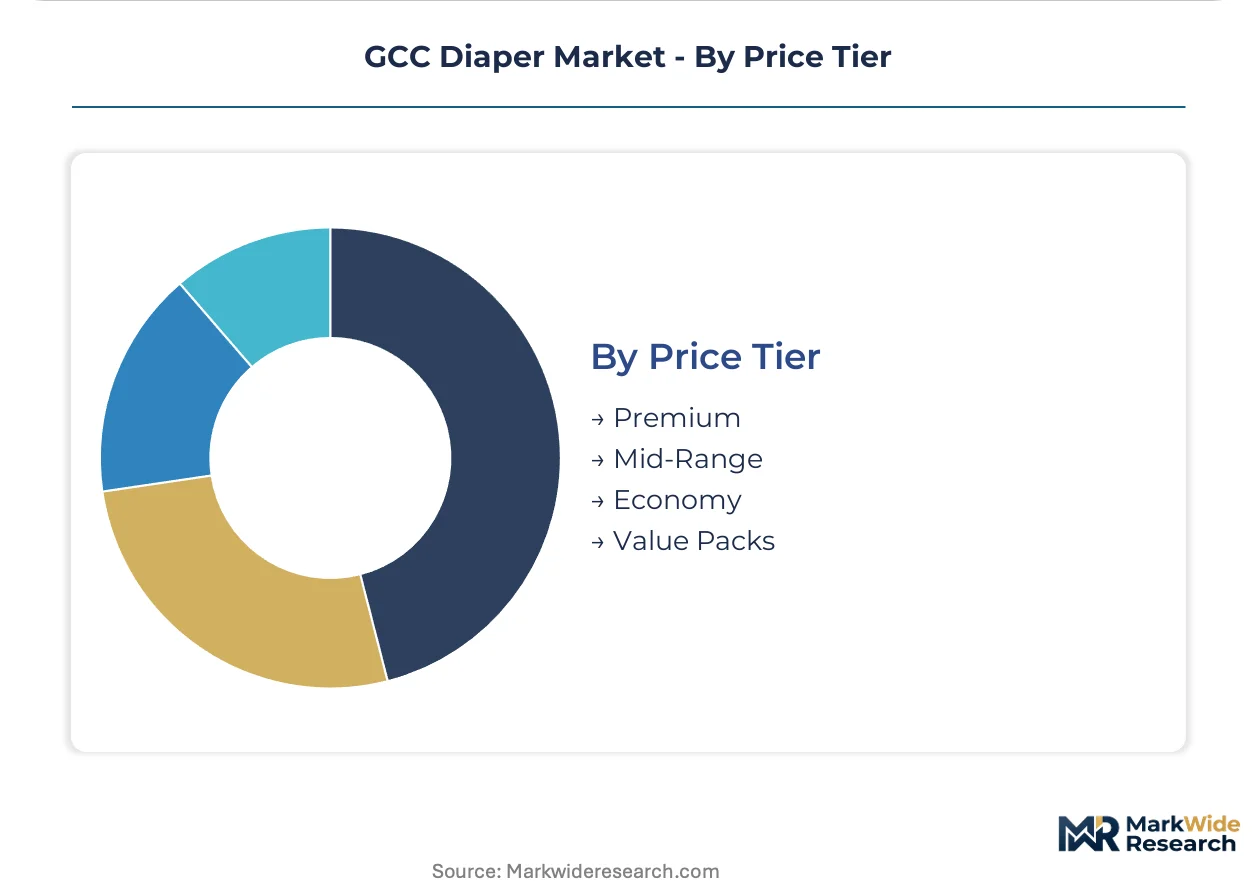
Price Tier:
Pricing architecture stratifies across certification grade, absorbency performance, and packaging scale rather than brand equity alone.
- Premium:Biodegradable certification, dermatological testing, and imported European formulations target UAE environmentally conscious consumers. Emirates Conformity Assessment Scheme labeling accelerates retail placement.
- Economy: Basic polymer cores and simplified packaging serve price-sensitive households in Saudi Arabia's secondary cities. Local manufacturing eliminates import duty exposure.
- Mid-Range:Balanced feature sets with regional brand recognition dominate repeat purchasing in Kuwait.
- Value Packs:Bulk sizing with per-unit discounts locks in household commitment in hypermarket promotion cycles.
Economy tiers absorb manufacturing volume; premium positioning is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability in Saudi Arabia's Eastern Province anchors absorbent hygiene manufacturing across the GCC, with superabsorbent polymer precursor plants supplying downstream diaper producers throughout the peninsula.
Saudi Arabia
SASO certification mandates reshape competitive entry as domestic manufacturing clusters in Jubail and Yanbu displace import-reliant supply models. Healthcare privatization expands homecare service contracts for elderly incontinence management in Riyadh and Jeddah corridors. The Ministry of Health standardization directives consolidate procurement through specified product categories.
United Arab Emirates
Emirates Conformity Assessment Scheme labeling accelerates retail placement for biodegradable hygiene products targeting Dubai and Abu Dhabi municipal composting standards. Premium positioning absorbs certification costs through price architecture in hypermarket channels. MOHAP enforces materials standards through product safety frameworks.
Kuwait
Underdeveloped retail infrastructure offers first-mover shelf space advantages as hypermarket expansion plans target underserved suburbs. Mid-range pricing tiers with regional brand recognition dominate repeat purchasing patterns. The country's national standards body maintains alignment with GCC customs harmonization protocols.
Bahrain
Smaller market scale concentrates demand in pharmacy and convenience store channels with limited domestic manufacturing presence. Import dependency persists across nonwoven fabric supply. The national quality regulator enforces labeling requirements consistent with broader Gulf Cooperation Council frameworks.
Qatar
Institutional procurement for healthcare facilities drives volume concentration in Doha metropolitan supply chains. Premium-tier imported formulations serve expatriate household segments. The national health regulator oversees medical device classification overlap for adult incontinence products.
GCC Diaper Market Key Industry Players
Global majors compete with regional champions across distribution infrastructure and regulatory compliance capabilities. Market structure tilts toward consolidated shelf presence in hypermarket channels while domestic manufacturing expansion filters marginal participants. Three archetypes dominate: multinational consumer goods conglomerates with regional distribution networks, Turkish and Saudi integrated hygiene specialists with captive raw material access, and European sustainability-focused innovators with biodegradable certification expertise. Competitive moves concentrate on backward integration into superabsorbent polymer production and strategic partnerships with healthcare procurement consolidators.
Among the multinational tier, Procter & Gamble Company and Kimberly-Clark Corporation represent scale-driven market presence through established retail relationships. Essity AB exemplifies sustainability credentialing within the European-origin specialist segment. Saudi Disposable Hygiene Products Co. Ltd. anchors domestic manufacturing expansion alongside Turkish integrated producers like Hayat Kimya Sanayi A.S.
| Leading Market Players |
|---|
| Essity AB |
| Hissam Group |
| Procter & Gamble Company |
| Hayat Kimya Sanayi A.S. |
| Saudi Disposable Hygiene Products Co. Ltd. |
| Kimberly-Clark Corporation |
| Fine Hygienic Holding |
| Abena Group |
| Unicharm Corporation |
| Others |
Cost & Logistics Intelligence
Polypropylene spot indices on the Arabian Gulf benchmark cascade through diaper manufacturing cost structures, compressing margins in economy tiers while premium biodegradable lines absorb volatility through Emirates Conformity Assessment Scheme-certified price architecture. Feedstock fluctuations from Jubail petrochemical complexes reshape procurement strategies across Saudi Arabia's domestic producers and import-dependent competitors in Bahrain and Kuwait.
Pricing Analysis
After-sales service bundling separates institutional contract winners from spot-market suppliers, with SASO-certified producers including technical training and compliance documentation in tender pricing. Three-tier pricing structure across premium biodegradable, standard disposable, and economy polymer-core levels tracks certification grade and volume scale. Pricing pressure stems from Turkish and Chinese nonwoven import competition in mid-range segments. Government hospital procurement committees exhibit lowest price sensitivity; convenience store emergency purchasers show highest elasticity.
Supply Chain Analysis
Post-consumer diaper collection and industrial composting infrastructure remain underdeveloped across the GCC, limiting biodegradable product circularity claims to industrial pilot programs in Dubai and Abu Dhabi. Manufacturing concentrates in Saudi Arabia, Turkey, and China, with Saudi Arabia's Eastern Province petrochemical corridor anchoring superabsorbent polymer precursor supply. Raw material dependencies center on polypropylene nonwoven fabrics, elastomeric closures, and SAP granules. Single-source vulnerability persists in Turkish specialty nonwoven mills. Distribution runs through hypermarket chain consolidation in Riyadh, Jeddah, and Dubai metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
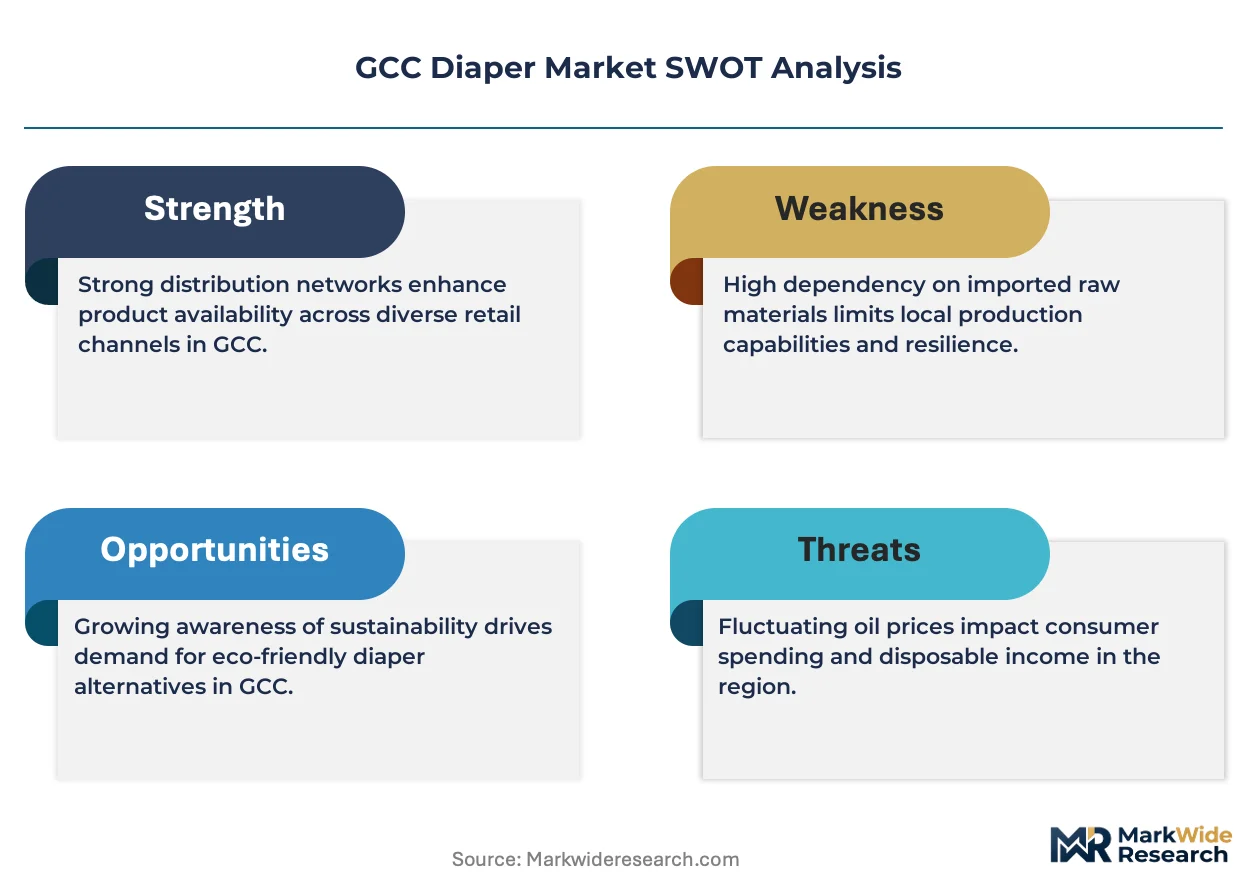
The GCC diaper market functions as a cost-of-compliance arena where SASO certification timelines and laboratory capacity constraints erect six-to-nine month entry barriers that protect incumbent positions against unverified import competition.
For Market Incumbents: Acquire captive superabsorbent polymer production capacity in Saudi Arabia's Eastern Province to insulate margins from petrochemical price volatility and Turkish nonwoven currency exposure. Secure exclusive distribution partnerships with hospital group purchasing organizations consolidating procurement under Ministry of Health standardization directives. Defend against Turkish integrated hygiene specialists by accelerating biodegradable certification pipelines for UAE municipal waste compliance. For New Entrants and Emerging Players: Rural Saudi households in secondary cities beyond Riyadh and Jeddah corridors represent the most penetrable buyer archetype, with underdeveloped hypermarket presence and price sensitivity unaddressed by premium-focused multinationals. Kuwait's underserved suburban retail infrastructure offers first-mover shelf space advantages ahead of planned hypermarket expansion. Bahrain's pharmacy-channel concentration permits niche positioning for adult incontinence medical-device classifications. Launch through e-commerce subscription platforms to bypass established distributor markups and lock in recurring revenue. For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic Saudi manufacturers with existing SASO registrations and underutilized production capacity in Jubail and Yanbu industrial clusters. Long-term viability hinges on backward integration into petrochemical feedstocks and healthcare procurement consolidation participation. Monitor Emirates Conformity Assessment Scheme biodegradable certification adoption rates as inflection signal for premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SAP Production | Captive superabsorbent polymer supply from Saudi petrochemical feedstock eliminates import currency exposure. |
| Biodegradable Certification Pathway | Emirates Conformity Assessment Scheme labeling unlocks premium positioning in UAE municipal composting zones. |
| Hospital GPO Partnership | Ministry of Health procurement consolidation favors suppliers with standardized absorbent hygiene bundles. |
| E-commerce Subscription Launch | Direct-to-consumer platforms bypass traditional distributor markups in UAE logistics-mature emirates. |
| Kuwait Retail Expansion | Hypermarket development in underserved suburbs creates first-mover shelf space advantages. |
Research Approach
Trade statistics from Saudi Customs Authority, UAE Ministry of Economy industrial surveys, and GCC central bank petrochemical price indices formed the secondary backbone of this analysis. Primary interviews with procurement managers at Saudi hospital group purchasing organizations, category buyers at Dubai and Riyadh hypermarket chains, and technical directors at domestic manufacturing facilities in Jubail and Yanbu validated demand-side assumptions. Bottom-up production capacity estimates triangulated against top-down healthcare expenditure projections.
Historical trendline analysis of absorbent hygiene manufacturing output, import penetration rates, and institutional procurement volumes established baseline growth patterns across the analysis window. Segmentation modeling incorporated product technology tiers, age-group demand concentrations, distribution channel economics, and price-positioning stratification. CAGRs derived from regression analysis of petrochemical feedstock cost trajectories, healthcare privatization spending curves, and retail channel development timelines. Forecast inputs included SASO laboratory capacity expansion schedules and Emirates Conformity Assessment Scheme certification adoption curves.
Revisions become necessary when Saudi healthcare privatization timelines accelerate, UAE municipal composting mandates expand beyond Dubai and Abu Dhabi, or Turkish nonwoven supply disruptions materialize. Forecasts reflect assumptions regarding regulatory compliance stability and petrochemical feedstock availability. Practitioners should monitor SASO testing bottleneck resolution and biodegradable certification cost trajectories for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
Malaysia Diapers Market
Baby Diapers
Africa and India Baby Diapers Market
Baby Diapers
Baby Cloth Diaper Market
Baby Diapers
Europe Diaper Market
Baby Diapers
Middle East and Africa and Asia Pacific Baby Diaper Market
Baby Diapers
Mexico Pant Type Adult Diaper Market
Baby Diapers
Diaper Market
Baby Diapers
East Africa Baby Diaper Market
Baby Diapers
Nonwoven Baby Diaper Market
Baby Diapers
Smart Connected Diaper Market
Baby Diapers
Adult Diapers Market
Baby Diapers
United States Adult Diaper Market
Baby Diapers
North America Diaper Market
Baby Diapers
Baby Diapers Market
Baby Diapers
United Arab Emirates Baby Diapers and Wipes Market
Baby Diapers
United States Diaper Market