
 Smart Connected Diaper Market | 2026-2036
Smart Connected Diaper Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Connected Diaper Market Insights
CE marking under the EU Medical Device Regulation is redrawing competitive boundaries for sensor-embedded infant care products. Procter & Gamble leverages its manufacturing scale to anchor North American supply chains for Bluetooth-enabled diaper systems. Monit Corp. specializes in data analytics platforms that differentiate its offering from commodity hygiene manufacturers. Kimberly-Clark Corporation sustains R&D intensity across monitoring sensor integration, navigating the gap between consumer electronics and medical device classifications.
Smart connected diapers combine absorbent hygiene cores with moisture-detecting electrodes, wireless transmitters, and cloud-based alert systems to track urination events, skin pH shifts, and irregular elimination patterns in real time. The primary commercial purpose centers on early detection of urinary tract infections, dehydration markers, and incontinence-related skin breakdown in infants and elderly patients. Disposable product types dominate unit economics due to single-use sensor cost structures, while monitoring sensors represent the fastest-growing technology layer as semiconductor miniaturization reduces power draw. Healthcare providers constitute the highest-margin end user segment because institutional procurement absorbs premium pricing for FDA-cleared clinical variants.
FDA 510(k) pathways and EU MDR Class IIa requirements govern market access for devices claiming diagnostic or monitoring functions, forcing manufacturers to maintain quality management systems that consumer diaper brands historically avoided. HIPAA compliance obligations in the United States and GDPR data governance in Europe constrain how biometric data from infant wearables flows to parents, caregivers, and third-party platforms. Stakeholders must monitor whether national health technology assessment bodies will designate connected diapers as reimbursable medical supplies or premium consumer electronics, a classification choice that will determine addressable market breadth across institutional and retail channels.
Market Dynamics
Semiconductor miniaturization is compressing power draw requirements for moisture-detecting electrodes, enabling single-use sensor economics that previously required reusable hardware. This shift is redrawing unit cost structures across both institutional procurement and direct-to-consumer retail channels.
Growth Catalysts
- Pediatric telehealth reimbursement codes:United States payers now cover connected incontinence management systems, expanding addressable demand for FDA-cleared clinical variants in hospital networks and home health settings.
- Neonatal intensive care unit protocols:Remote patient monitoring standards in hospital networks are mandating real-time moisture and skin pH tracking for premature infants, creating institutional pull for sensor-embedded products.
- Bluetooth Low Energy integration:Wireless transmitter modules with sub-milliwatt power profiles are eliminating battery replacement cycles, reducing total cost of ownership for elderly care facilities.
Market Restraints
- Single-use sensor cost structures:Disposable electrodes and transmitters embedded in each diaper unit create material cost premiums that commodity hygiene manufacturers struggle to absorb without pricing out retail segments.
- FDA 510(k) pathway duration:Quality management system requirements and clinical validation timelines for devices claiming diagnostic functions compress development bandwidth for new entrants lacking medical device expertise.
- GDPR biometric data governance:European restrictions on cloud-based infant biometric data flows constrain parent-facing alert architectures and force localized data infrastructure investments.
Strategic Opportunities
- Japan's aging demographic:METI-supported smart care initiatives for elderly incontinence management create regulatory tailwinds for clinical-grade monitoring systems in institutional long-term care.
- Home health channel expansion:Direct-to-consumer subscription models bypass traditional retail pharmacy distribution, capturing recurring revenue streams from caregiver segments seeking predictive health alerts.
- AI-enabled pattern recognition:Convergence of edge computing with cloud-based analytics platforms enables early UTI detection algorithms that differentiate premium offerings from basic moisture alarms.
Industry Challenges
- Medical device quality management systems:ISO 13485 certification requirements demand specialized regulatory affairs talent that consumer hygiene manufacturers historically lacked, creating hiring bottlenecks.
- Cross-functional integration complexity:Product development teams must bridge absorbent materials engineering, semiconductor packaging, and HIPAA-compliant software architecture, stretching organizational capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Connected Diaper Market |
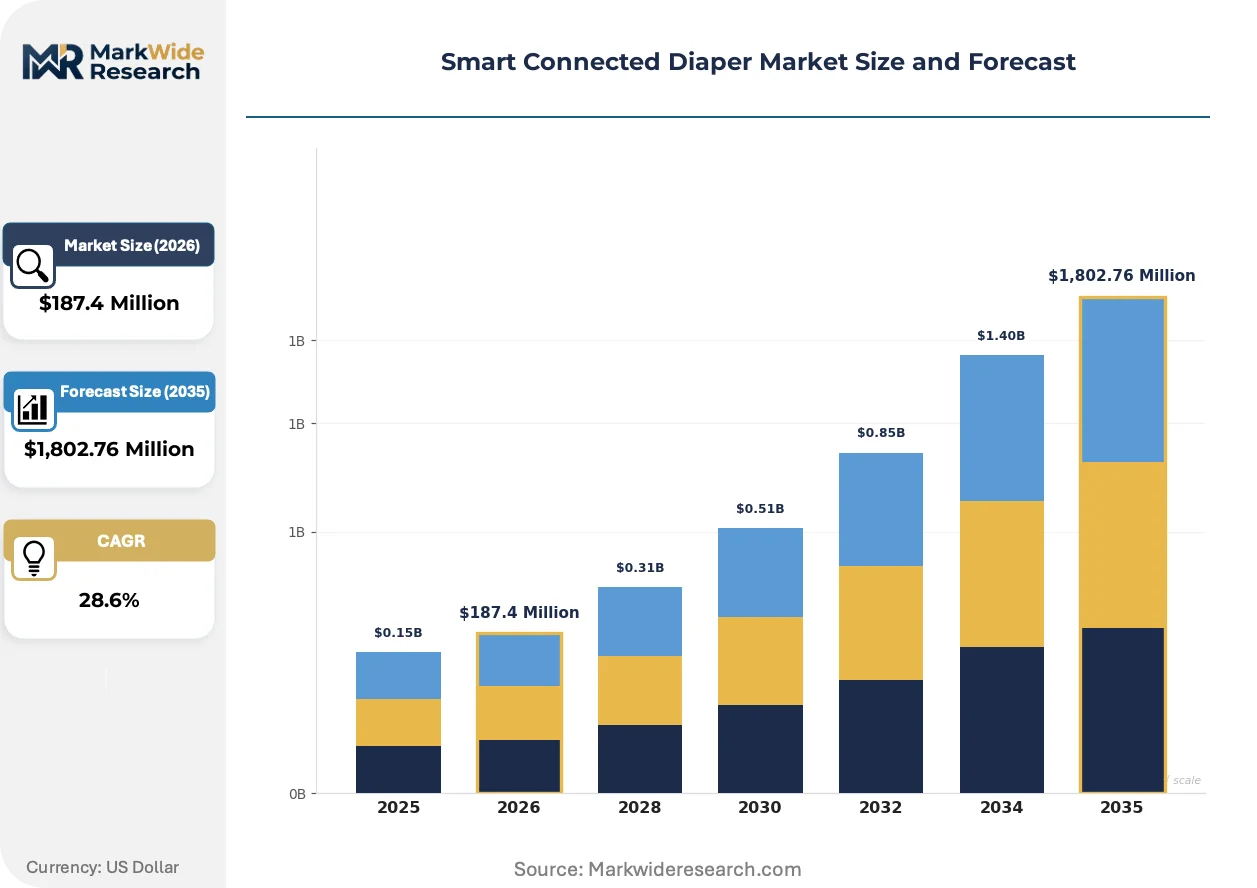
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Hybrid, Eco-friendly Technology: Bluetooth, RFID, Monitoring Sensors, Data Analytics End User: Parents, Caregivers, Healthcare Providers, Retailers Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Procter & Gamble, Kimberly-Clark Corporation, Unicharm Corporation, Essity Aktiebolag, Ontex BV, Verily Life Sciences, Monit Corp., Pixie Scientific, Simavita Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Connected Diaper Market Trends and Innovations
Active developments across sensor hardware, regulatory classification, and procurement models are compressing development cycles while fragmenting competitive positioning between medical device and consumer electronics paradigms.
Printed flexible electronics with integrated pH-sensitive hydrogels are displacing rigid PCB-based moisture detectors in next-generation diaper architectures. Neonatal intensive care units in tertiary hospital networks are adopting these platforms within single procurement cycles. The shift is displacing capital-intensive reusable monitoring hardware with disposable-integrated alternatives that eliminate sterilization workflows.
EU MDR Class IIa designation requirements for sensor-embedded infant care products are forcing manufacturers to maintain post-market surveillance systems that consumer brands previously avoided. Quality management system audits and clinical evidence dossiers now govern market access for any device claiming diagnostic interpretation of elimination patterns. European notified bodies are prioritizing cybersecurity validation for wireless transmitters, compressing clearance timelines for products with end-to-end encryption architectures.
Institutional procurement teams in United States health systems are consolidating vendor relationships around FDA-cleared platforms that satisfy both clinical quality and supply chain rationalization mandates. Group purchasing organizations are negotiating multi-year sole-source agreements with manufacturers offering predictive analytics dashboards, displacing spot-buying of commodity incontinence supplies. This concentration is most visible in integrated delivery networks spanning acute care, skilled nursing, and home health segments across Midwest and Southeast states.
Smart Connected Diaper Market Segmentation
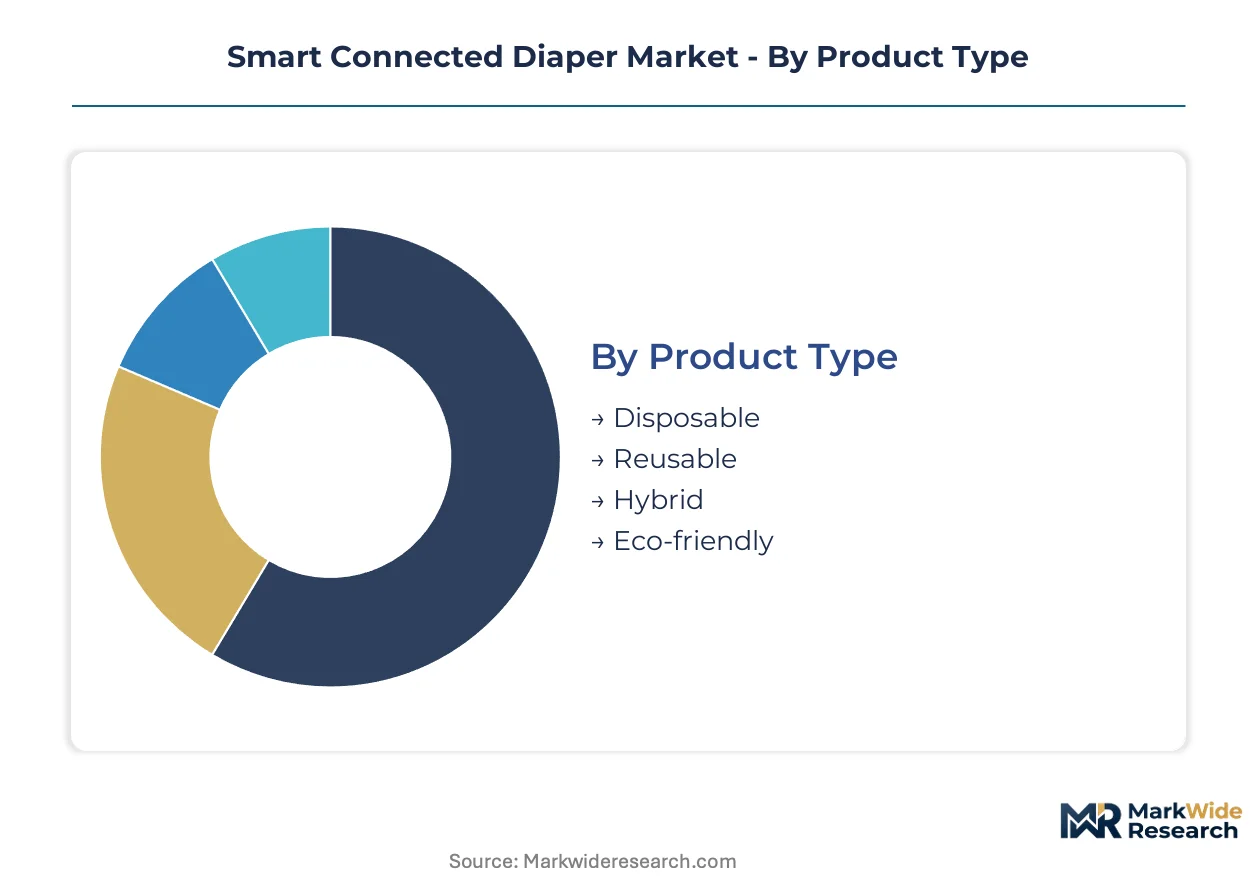
Smart connected diaper segmentation reflects competing pressures between single-use convenience and reusable hardware economics. Manufacturers must align sensor integration strategies with distinct procurement logics across institutional healthcare and direct-to-consumer channels.
Product Type:
Disposable formats face substitution pressure from reusable monitoring hardware as semiconductor miniaturization compresses the cost gap between single-use and multi-use sensor platforms.
- Disposable:Absorbent cores embed moisture-detecting electrodes and wireless transmitters designed for single-use disposal. Demand concentrates in United States hospital networks where FDA-cleared clinical variants command premium pricing under pediatric telehealth reimbursement codes. Single-use sensor cost structures create material premiums that strain retail segment price elasticity.
- Reusable:Detachable sensor modules clip onto standard diaper chassis for repeated use across 50-100 change cycles. Elderly care facilities in Japan's METI-supported smart care initiatives absorb higher upfront hardware costs to eliminate per-unit sensor expenditure. Bluetooth Low Energy integration with sub-milliwatt power profiles eliminates battery replacement cycles.
- Hybrid:Semi-reusable architectures separate absorbent components from electronic housings for partial replacement.
- Eco-friendly:Biodegradable substrates with compostable sensor substrates target sustainability-mandated procurement in European institutional buyers.
Disposable retains volume leadership; reusable holds the steepest expansion curve.
Technology:
Cost tier stratification separates basic wireless alerting from predictive analytics platforms that command institutional subscription pricing.
- Bluetooth:Low-energy wireless protocols transmit moisture and pH data to parent or caregiver smartphones with sub-10 meter range. United States direct-to-consumer channels dominate unit volumes as HIPAA-compliant cloud architectures enable home health monitoring without clinical infrastructure. FCC certification requirements govern transmitter power profiles.
- Monitoring Sensors:Printed flexible electronics with integrated pH-sensitive hydrogels detect skin chemistry shifts and irregular elimination patterns. Neonatal intensive care units in tertiary United States hospital networks mandate real-time tracking for premature infants under remote patient monitoring protocols. Semiconductor miniaturization reduces power draw to enable single-use economics.
- RFID:Passive identification tags enable inventory tracking and basic wetness indication without active power.
- Data Analytics:Cloud-based pattern recognition platforms process elimination data for early UTI detection algorithms.
Bluetooth captures the broadest installed base; monitoring sensors are climbing the fastest.
End User:
Margin concentration tilts toward institutional buyers who absorb premium pricing for diagnostic-grade platforms.
- Healthcare Providers:Hospital networks, skilled nursing facilities, and home health agencies procure FDA-cleared clinical variants with predictive analytics dashboards. United States group purchasing organizations negotiate multi-year sole-source agreements that displace spot-buying of commodity supplies. Institutional procurement absorbs premium pricing for quality management system certification.
- Parents:Direct-to-consumer buyers purchase basic moisture-alert systems through online retail subscriptions. GDPR biometric data governance in Europe constrains cloud-based data flows and forces localized infrastructure investments.
- Caregivers:Professional and family caregivers seek predictive health alerts for elderly incontinence management.
- Retailers:Pharmacy and supermarket channels intermediate mass-market sensor-embedded products.
Healthcare providers command the highest margin tier; parents represent the largest addressable population.
Distribution Channel:
Volume flows through diverging pathways as subscription models bypass traditional retail pharmacy economics.
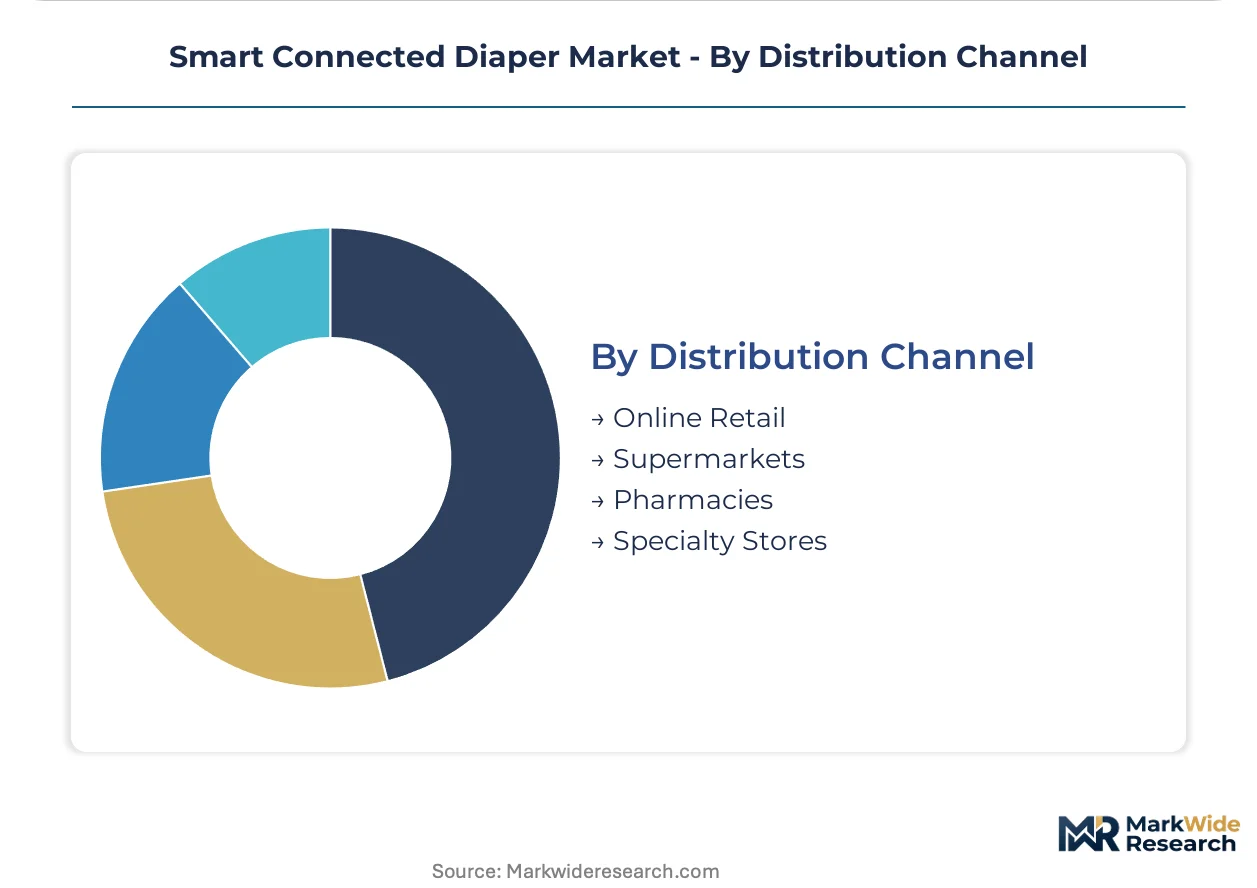
- Online Retail:Direct-to-consumer subscription platforms capture recurring revenue from caregiver segments seeking predictive health alerts. United States home health channel expansion enables manufacturers to bypass wholesale distribution markups. HIPAA-compliant data architectures determine platform eligibility for institutional procurement.
- Pharmacies:Retail pharmacy chains stock FDA-cleared clinical variants for prescription-adjacent purchase. United States reimbursement code coverage expands shelf placement for connected incontinence management systems.
- Supermarkets:Mass-market channels distribute basic moisture-alert products to price-sensitive consumer segments.
- Specialty Stores:Medical supply retailers serve institutional procurement with volume contracting.
Online retail is gaining share fastest; pharmacies retain institutional access advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement codes and regulatory clearance pathways are redrawing geographic demand concentration for sensor-embedded infant care products. Pediatric telehealth coverage in the United States and METI-backed elderly care initiatives in Japan are accelerating institutional procurement cycles. CE marking complexity under EU MDR is compressing market access timelines for new entrants lacking medical device quality systems.
United States
FDA-cleared clinical variants command premium pricing through pediatric telehealth reimbursement codes that now cover connected incontinence management systems. Group purchasing organizations negotiate multi-year sole-source agreements with manufacturers offering predictive analytics dashboards. Neonatal intensive care units across Midwest and Southeast hospital networks mandate real-time moisture tracking for premature infants.
Japan
METI-supported smart care initiatives for elderly incontinence management create regulatory tailwinds for clinical-grade monitoring systems in institutional long-term care. Bluetooth Low Energy integration with sub-milliwatt power profiles eliminates battery replacement cycles in elderly care facilities. Kanto region manufacturers supply sensor modules to nursing home chains seeking disposable-integrated alternatives.
Germany
EU MDR Class IIa designation requirements force manufacturers to maintain post-market surveillance systems that consumer brands previously avoided. Notified bodies prioritize cybersecurity validation for wireless transmitters with end-to-end encryption architectures. Bavaria-based medical device specialists navigate quality management system audits for sensor-embedded infant care products.
United Kingdom
NHS procurement teams evaluate FDA-cleared platforms for remote patient monitoring protocols in pediatric and geriatric care pathways. GDPR biometric data governance constrains cloud-based infant biometric data flows to parent-facing alert architectures. London health technology assessment bodies weigh reimbursement designation for connected diapers as medical supplies versus premium consumer electronics.
China
NMPA pathway compression for Class II medical devices accelerates market entry for sensor-based wearable products claiming diagnostic functions. Domestic semiconductor miniaturization reduces power draw requirements for moisture-detecting electrodes in single-use sensor economics. Yangtze River Delta manufacturers integrate printed flexible electronics with pH-sensitive hydrogels for next-generation diaper architectures.
Smart Connected Diaper Market Competitive Landscape
Player mix skews toward diversified hygiene conglomerates with medical device regulatory capabilities and specialized sensor technology developers. Tiered competitive structure separates FDA-cleared clinical variants from direct-to-consumer moisture-alert systems. Two dominant archetypes occupy distinct positions: absorbent hygiene manufacturers leveraging manufacturing scale for North American supply chains, and data analytics platforms differentiating through predictive health algorithms. Competitive moves concentrate on strategic partnerships bridging semiconductor packaging with quality management system certification, and portfolio diversification into HIPAA-compliant software architectures.
Within the diversified hygiene tier, Procter & Gamble and Kimberly-Clark Corporation occupy positions anchored by manufacturing scale and R&D intensity across monitoring sensor integration. Monit Corp. represents the specialized analytics archetype, sitting within the data platform segment that differentiates offerings from commodity hygiene manufacturers. These three companies exemplify the structural split between consumer electronics and medical device classification paradigms that governs competitive positioning.
| Leading Market Players |
|---|
| Procter & Gamble |
| Kimberly-Clark Corporation |
| Unicharm Corporation |
| Essity Aktiebolag |
| Ontex BV |
| Verily Life Sciences |
| Monit Corp. |
| Pixie Scientific |
| Simavita Limited |
| Others |
Pricing and Supply Chain Analysis
FDA 510(k) clearance pathways gate both supplier qualification and price tier separation in the smart connected diaper market, compressing development timelines for new entrants while enabling premium capture for ISO 13485-certified manufacturers serving institutional procurement channels.
Pricing Analysis
Certification level creates the primary spread between commodity hygiene pricing and clinical-grade premiums. Three-tier pricing structure across premium FDA-cleared variants, standard CE-marked clinical systems, and economy direct-to-consumer moisture alerts governs market access. Cost compression in the disposable sensor tier intensifies because semiconductor miniaturization reduces per-unit electronics expenditure. Parents exhibit highest price sensitivity in online retail subscriptions, while United States hospital networks absorb premium pricing for predictive analytics dashboards under pediatric telehealth reimbursement coverage.
Supply Chain Analysis
Port congestion on trans-Pacific lanes elevates inbound logistics costs for semiconductor modules sourced from Taiwan, South Korea, and China. Printed flexible electronics draw from Yangtze River Delta substrate manufacturers and Bavaria-based sensor packaging specialists. Single-source vulnerability concentrates in pH-sensitive hydrogel suppliers serving neonatal intensive care unit procurement. Distribution runs through group purchasing organization contracts for institutional buyers and direct-to-consumer subscription platforms for retail segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart connected diaper market operates as a regulatory-moat business where FDA 510(k) entrenchment and ISO 13485 certification requirements create switching costs that institutional buyers cannot easily circumvent.
For Market Incumbents: Shield market position by deepening backward integration into printed flexible electronics manufacturing and accelerating HIPAA-compliant cloud architecture development. Emerging sensor-embedded infant care specialists threaten premium tier capture through AI-enabled pattern recognition platforms. Certification investment in EU MDR Class IIa post-market surveillance systems remains the critical defensive lever against European notified body cybersecurity validation demands. For New Entrants and Emerging Players: Anchor in Japan's METI-supported elderly care initiatives where Bluetooth Low Energy integration with sub-milliwatt power profiles addresses battery replacement cycle pain points in institutional long-term care. Home health channel expansion offers the most penetrable white space, bypassing traditional retail pharmacy distribution markups through direct-to-consumer subscription models targeting caregiver predictive alert demand. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified hygiene conglomerates seeking to divest non-core medical device regulatory capabilities amid quality management system hiring bottlenecks. Long-term viability hinges on whether national health technology assessment bodies designate connected diapers as reimbursable medical supplies versus premium consumer electronics. Watch FDA pediatric telehealth reimbursement code expansion as the primary inflection signal for addressable market breadth acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses quality management system validation timelines for diagnostic-grade moisture detection platforms. |
| CE Marking Pathway Investment | Enables European notified body cybersecurity validation for wireless transmitters with end-to-end encryption. |
| Hospital System Partnership | Secures multi-year sole-source agreements with group purchasing organizations across Midwest and Southeast states. |
| Software Companion Development | Delivers predictive analytics dashboards that differentiate premium offerings from basic moisture alarm systems. |
| Reimbursement Strategy Execution | Expands pediatric telehealth code coverage to capture institutional procurement volume in neonatal intensive care units. |
Research Methodology
A standing panel of biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists provided ongoing calibration throughout the primary research phase. This study combined structured interviews with these stakeholders against secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body guidance documents. Bottom-up unit economics modeling and top-down addressable market sizing underwent iterative triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type architecture, technology layer sophistication, end user procurement logic, and distribution channel structure. CAGRs derived from semiconductor miniaturization curves, pediatric telehealth reimbursement expansion rates, and neonatal intensive care unit protocol adoption patterns.
Material uncertainties — regulatory reclassification of connected diapers as consumer electronics rather than medical supplies, GDPR biometric data governance enforcement shifts, and single-use sensor cost structure volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions about reimbursement code stability and quality management system certification timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
Baby Diaper Manufacturing Machine Market
Baby Diapers
Mexico Pant Type Adult Diaper Market
Baby Diapers
North America Diaper Market
Baby Diapers
Smart Diaper Market
Baby Diapers
United States Adult Diaper Market
Baby Diapers
Disposable Hygiene Products Market
Baby Diapers
Baby Disposable Diapers Market
Baby Diapers
Pet Diapers Market
Baby Diapers
Baby Diapers Market
Baby Diapers
East Africa Baby Diaper Market
Baby Diapers
United Arab Emirates Baby Diapers and Wipes Market
Baby Diapers
United States Diaper Market
Baby Diapers
Australia Pant Type Adult Diaper Market
Baby Diapers
Baby Training Diaper Market
Baby Diapers
Reusable Baby Diapers and Training Pants Market
Baby Diapers
Baby Cloth Diaper Market