
 Mexico Pant Type Adult Diaper Market | 2026-2036
Mexico Pant Type Adult Diaper Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Pant Type Adult Diaper Market Insights
Home-based caregivers are reorganizing purchase patterns for pant type adult diapers as institutional procurement gives way to direct consumer buying. Essity Aktiebolag leverages its Nordic hygiene technology heritage to dominate premium absorbency tiers. Kimberly-Clark Corporation anchors retail shelf presence through pharmacy and supermarket networks across central Mexico. Ontex BV competes on manufacturing scale, operating a regional production footprint that reduces import dependency.
Pant type adult diapers are pull-up garments with elasticized waistbands and leg cuffs, typically constructed from nonwoven topsheets, acquisition distribution layers, superabsorbent polymer cores, and breathable backsheet films; they function as wearable continence management systems permitting self-dressing for semi-ambulatory users. Disposable products lead volume due to convenience expectations, while biodegradable variants represent the fastest-growing segment as environmental scrutiny intensifies. Distribution through pharmacies captures the highest margin pools because of pharmacist-assisted selection and reimbursement processing.
COFEPRIS, Mexico's national health regulator, enforces medical device classification and absorbency performance labeling that shapes product registration timelines and market access costs. NOM standards for textile and hygiene products establish baseline safety requirements that manufacturers must satisfy before commercialization. Stakeholders must monitor evolving extended producer responsibility frameworks and reimbursement policy shifts that could alter channel economics and consumer price sensitivity.
Market Dynamics
COFEPRIS medical device reclassification is compressing registration timelines and forcing absorbency performance disclosures that reshape competitive positioning among domestic and imported suppliers.
Growth Catalysts
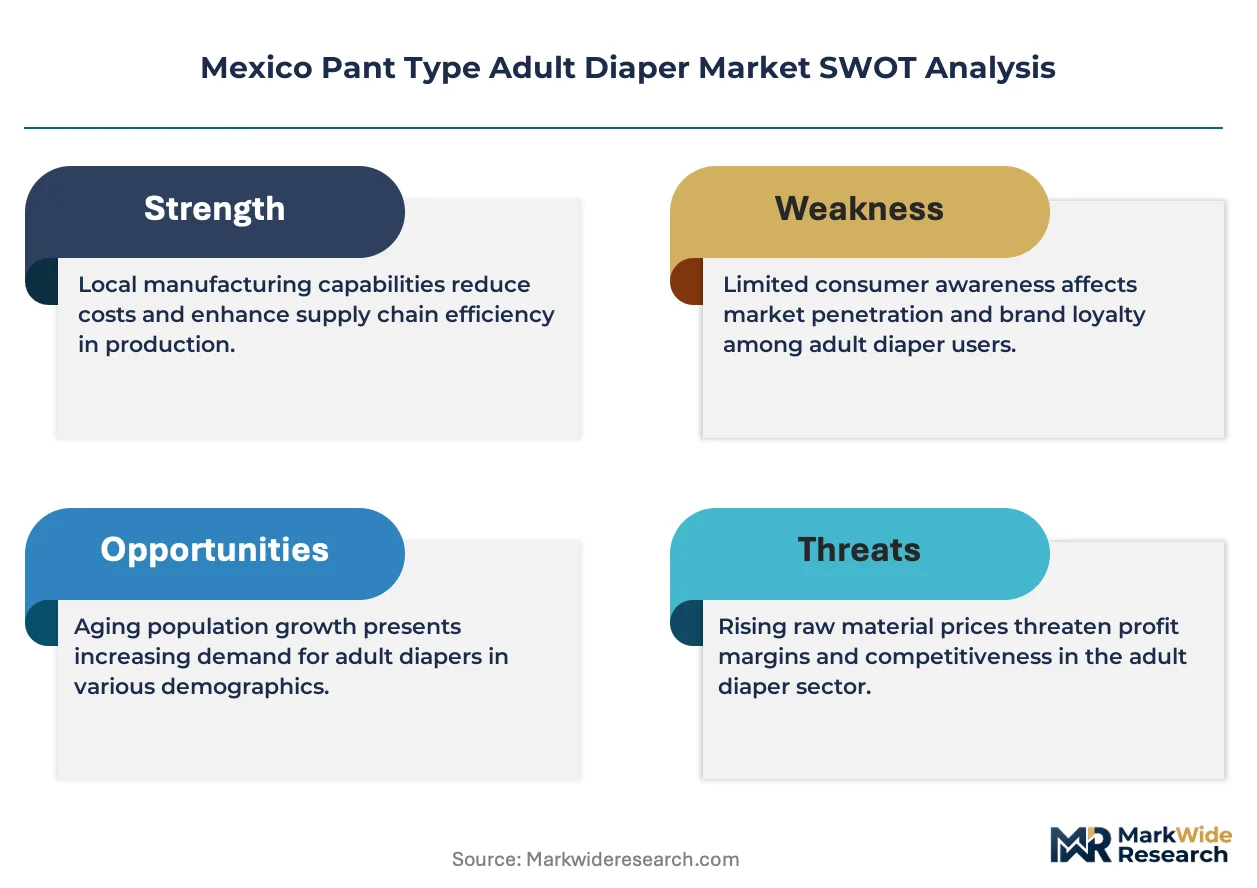
- Aging-in-place policy momentum:Mexico's national senior care framework incentivizes home-based geriatric services, expanding direct-to-consumer purchase volumes for pull-up continence garments.
- Superabsorbent polymer core advances:Acquisition distribution layer engineering now permits thinner profiles without leakage compromise, appealing to semi-ambulatory users prioritizing discretion.
- COFEPRIS harmonization with ISO 11948:Standardized absorbency testing protocols reduce technical barriers for EU and US manufacturers seeking Mexican market entry.
Market Restraints
- Pulp and SAP input cost volatility:Fluctuating wood pulp prices and petrochemical-derived superabsorbent polymer feedstock costs squeeze margin structures for non-integrated producers.
- Import dependency for breathable backsheet films:Limited domestic blown film extrusion capacity concentrates supply risk with Asian petrochemical suppliers.
- Extended producer responsibility framework uncertainty:Pending waste management regulations for single-use hygiene products create capital planning ambiguity for manufacturing facility investments.
Strategic Opportunities
- Biodegradable topsheet materials:PLA and cellulose-based nonwoven alternatives command premium positioning as environmental scrutiny intensifies among institutional purchasers.
- Pharmacy channel pharmacist-assisted selection:Reimbursement processing integration at retail pharmacy chains captures higher-margin consumer segments seeking guidance.
- Private nursing facility expansion in Guadalajara:Clustered geriatric care infrastructure creates concentrated demand pools for bulk procurement contracts.
Industry Challenges
- COFEPRIS registration timeline compression:Medical device classification requirements extend product launch cycles by 12-18 months for new absorbency tier introductions.
- Legacy absorbent core equipment retooling:Transitioning manufacturing lines to thinner SAP configurations demands capital-intensive die and forming section upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Pant Type Adult Diaper Market |
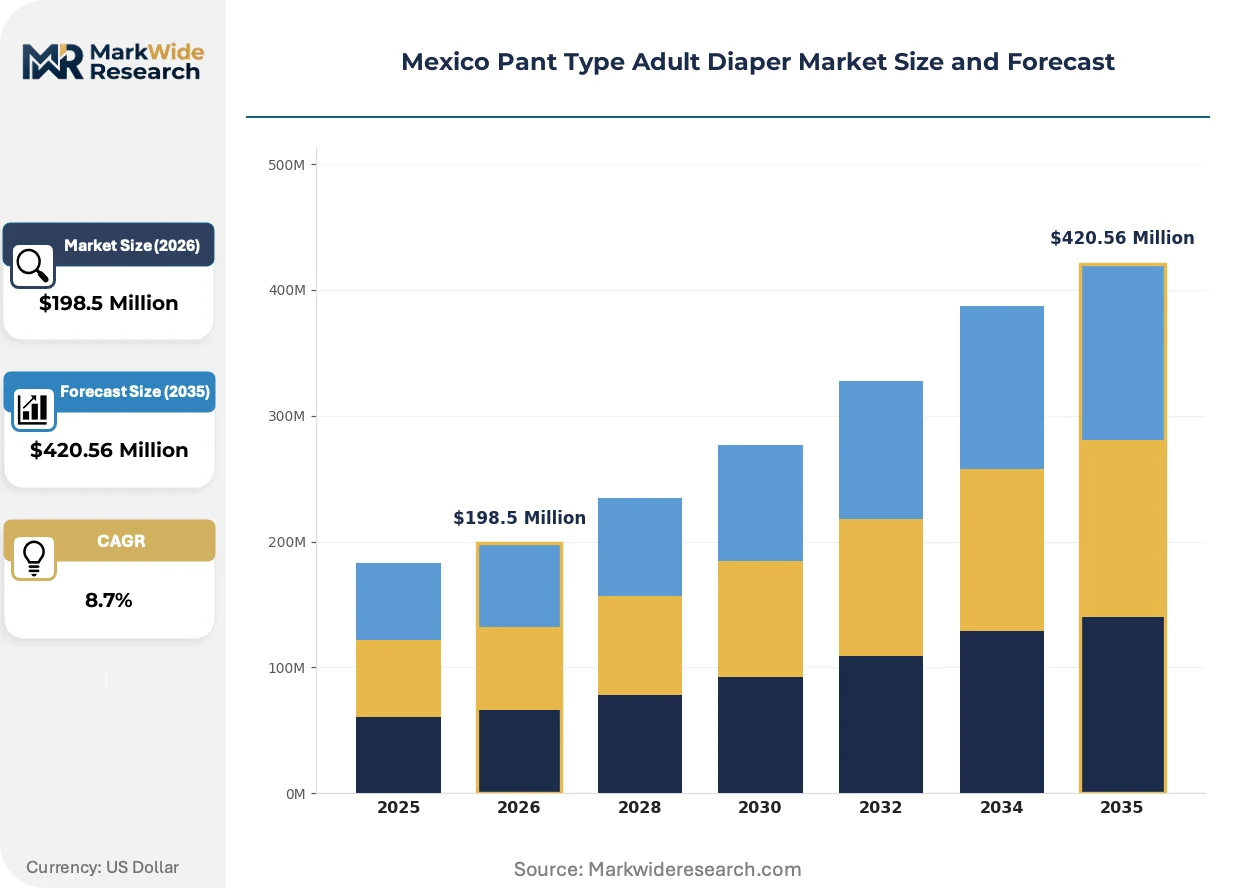
| Market Size in 2026 | $198.5 Million |
| Market Size in 2035 | $420.56 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Biodegradable, Waterproof End User: Seniors, Persons with Disabilities, Caregivers, Clinics Distribution Channel: Pharmacies, Supermarkets, Online Retail, Medical Supply Stores Size: Small, Medium, Large, Extra Large |
| Companies Covered | Essity Aktiebolag, First Quality Enterprises, Kimberly-Clark Corporation, Ontex BV, Medline Industries, Unicharm Corporation, Kao Corporation, Daio Paper Corporation, Procter & Gamble Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Pant Type Adult Diaper Market Trends and Innovations
Odor-neutralization chemistry and elasticized waistband engineering are converging to redefine performance expectations, while regulatory disclosure mandates and channel restructuring simultaneously compress pricing transparency and expand access points.
Plant-derived superabsorbent polymers derived from modified starch and cellulose grafting are fragmenting the petroleum-SAP supply base. Domestic compounders in Querétaro and Puebla are piloting production at 2,000-tonne annual scales. This biomaterial transition is fragmenting raw material sourcing strategies as multinational hygiene manufacturers dual-source between conventional and bio-based cores to hedge regulatory and consumer preference risks.
COFEPRIS NOM-252-SCFI/SSA1-2014 amendments mandate explicit absorbency capacity labeling in milliliters and standardized wetness indicator specifications. Manufacturers must reformulate packaging artwork and validate claims through third-party laboratory testing. The premium absorbency tier faces disproportionate compliance burden as higher-capacity products trigger more stringent clinical evidence requirements.
Direct-to-consumer subscription models are displacing institutional procurement for home-based caregivers. Pharmacy chains in Mexico City now offer auto-replenishment with pharmacist consultation hotlines. This channel pivot is most visible among adult children coordinating parental care remotely from the United States.
Mexico Pant Type Adult Diaper Market Segmentation
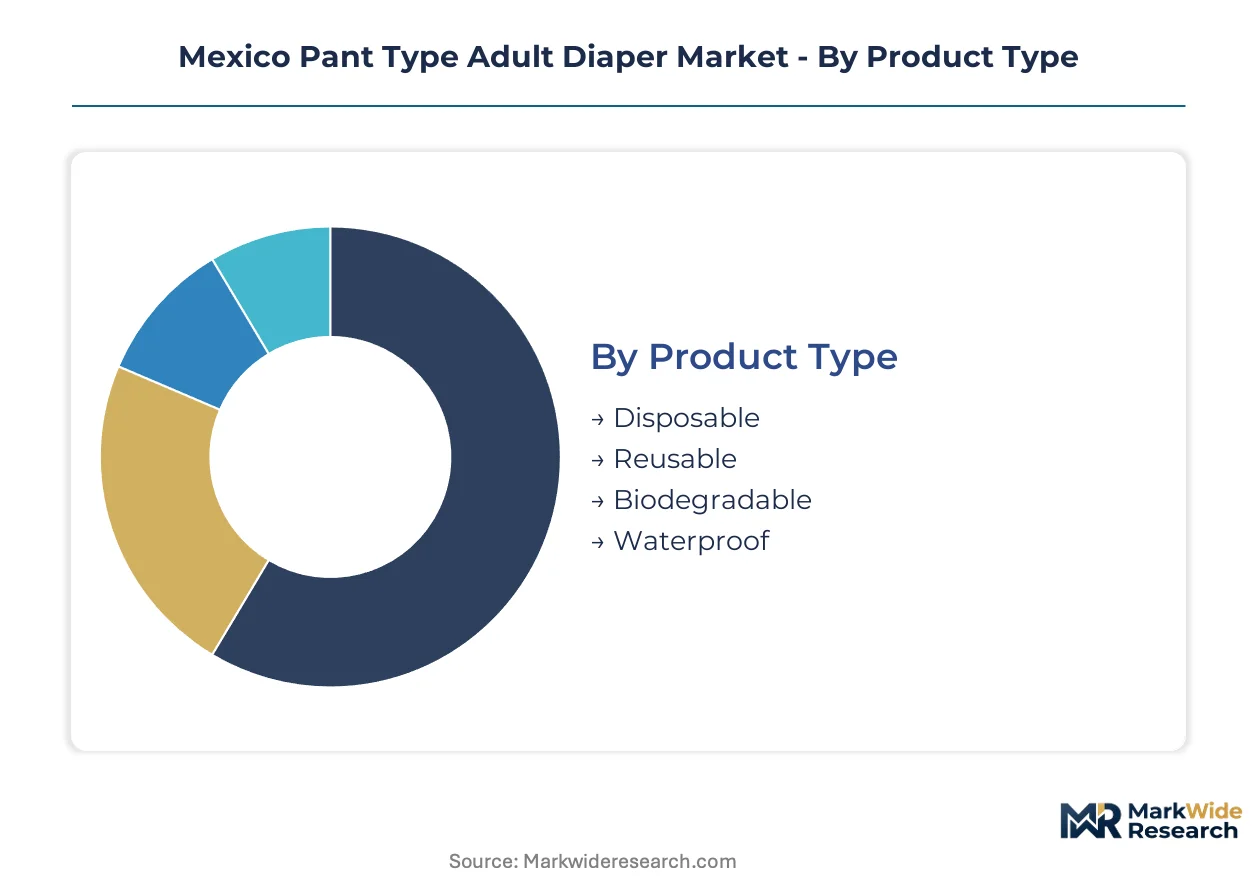
Segmentation in the Mexico pant type adult diaper market reveals how COFEPRIS absorbency classifications, channel reimbursement structures, and end-user mobility profiles reshape procurement economics. Manufacturers configure product portfolios across four intersecting dimensions to capture divergent margin pools.
Product Type:
COFEPRIS medical device registration tiers create divergent compliance burdens across material compositions, with biodegradable variants facing emerging extended producer responsibility scrutiny.
- Disposable:Nonwoven topsheet-SAP core-backsheet laminates dominate institutional procurement for incontinence management. Mexico City nursing facilities and Guadalajara private care clusters absorb bulk volumes through distributor contracts, though pulp and petrochemical input volatility squeezes non-integrated producers.
- Reusable:Cotton-polyester blend shells with removable absorbent inserts target cost-conscious home caregivers. Demand concentrates in extended family care arrangements across Jalisco and Puebla states where washing infrastructure exists and reimbursement gaps persist.
- Biodegradable:PLA and modified starch nonwoven alternatives command premium positioning amid environmental scrutiny.
- Waterproof:PVC or polyurethane laminate barriers serve swimming and therapeutic activity applications.
Established volume favors disposable configurations; emerging adoption favors biodegradable alternatives.
End User:
Mobility status and reimbursement eligibility segment demand into distinct purchasing behaviors with divergent price sensitivity profiles.
- Seniors:Semi-ambulatory aging-in-place beneficiaries drive pull-up garment adoption for self-dressing independence. Federal senior care framework subsidies expand direct-to-consumer volumes, particularly among Mexico City metropolitan zone households with US-based adult children coordinating remote care.
- Persons with Disabilities:Neurological and spinal cord impairment populations require higher absorbency tiers with specialized fit engineering.
- Caregivers:Family and paid home care providers balance discretion preferences against cost constraints in pharmacy channel selection.
- Clinics:Outpatient rehabilitation and post-acute care facilities source through medical supply distributors with volume pricing.
Institutional procurement concentrates among clinics; steepest expansion trajectory appears in caregiver-directed purchasing.
Distribution Channel:
Channel economics fragment across margin capture, reimbursement integration, and consultation intensity.
- Pharmacies:Pharmacist-assisted selection with COFEPRIS absorbency labeling validation captures highest-margin consumer segments. Chains in Mexico City and Guadalajara now integrate auto-replenishment with teleconsultation hotlines for remote caregiver coordination.
- Supermarkets:Mass retail placement anchors economy-tier volume for unassisted purchasing.
- Online Retail:Subscription models displace institutional procurement for US-based adult children managing parental care.
- Medical Supply Stores:Distributor networks serve clinic and nursing facility bulk contracting with invoice-based reimbursement processing.
Margin concentration favors pharmacy channels; volume scaling favors supermarket placement.
Size:
Anthropometric fit engineering and SAP core dimensioning segment production runs and inventory risk.
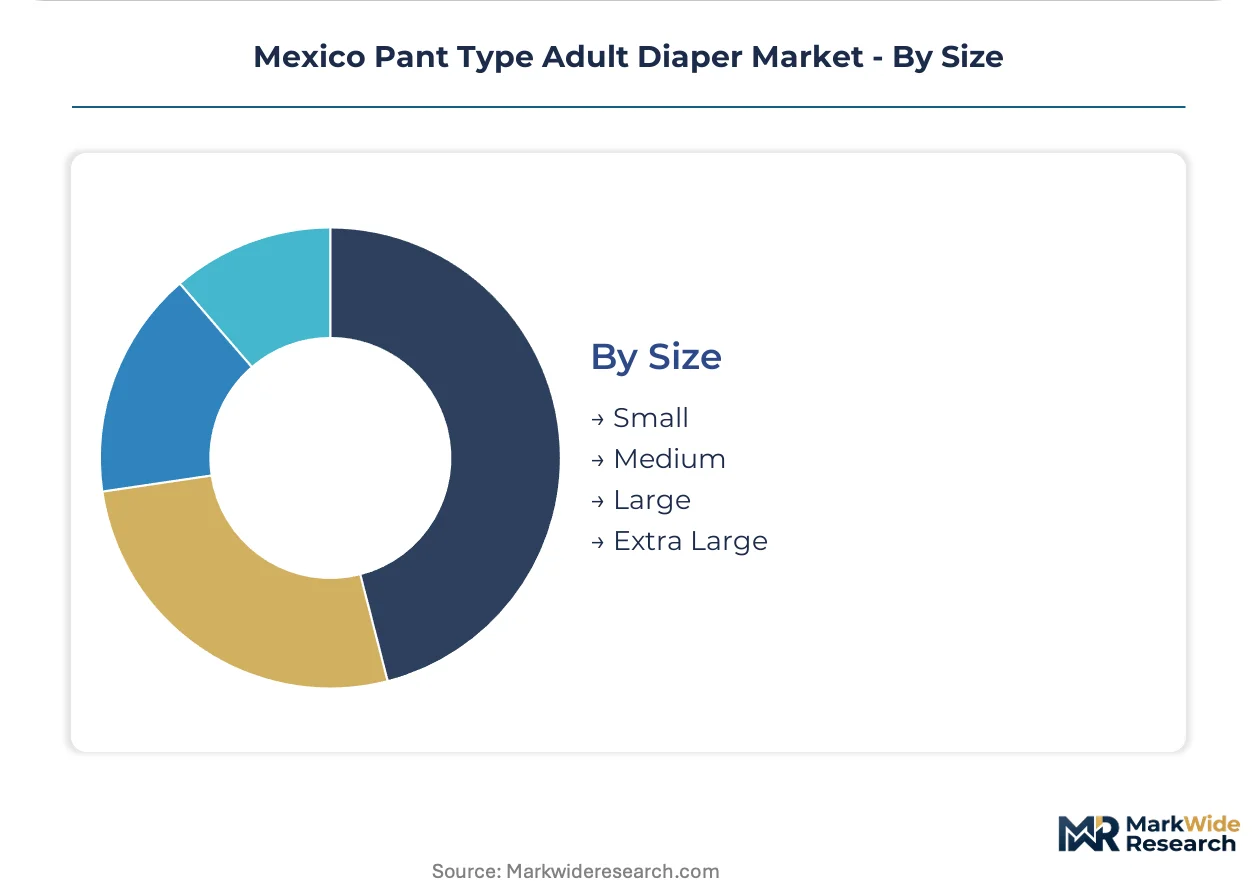
- Small:Narrow hip circumference specifications serve petite frame seniors and certain disability populations.
- Medium:Core volume SKU absorbs highest production run allocation.
- Large:Expanded waistband elastic engineering addresses Mexico's obesity prevalence in senior demographics.
- Extra Large:Reinforced leg cuff construction and extended SAP core length manage severe incontinence with bariatric fit requirements.
Production planning centers on medium and large configurations; emerging demand favors extra large specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US-Mexico cross-border supply chains channel superabsorbent polymer feedstocks and breathable backsheet films through Laredo-Nuevo Laredo corridors, while domestic production clusters concentrate demand pull in central and northern metropolitan zones.
Mexico City Metro
Semi-ambulatory seniors and remote US-based caregivers drive pharmacy channel auto-replenishment adoption. COFEPRIS NOM-252-SCFI/SSA1-2014 amendments mandate milliliter-scale absorbency labeling that pharmacy chains now integrate into consultation workflows. Hospital corridors in Tlalpan and Coyoacán anchor institutional procurement for post-acute rehabilitation facilities.
Jalisco
Guadalajara's private nursing facility expansion creates concentrated bulk contracting opportunities for medical supply distributors. The state's extended family care culture sustains parallel demand for reusable cotton-polyester blend configurations in rural municipalities. Zapopan and Tlaquepaque cluster geriatric care infrastructure with invoice-based reimbursement processing.
Nuevo León
Monterrey's manufacturing base hosts regional distribution centers serving northern border states with reduced logistics dwell time. Monterrey-based caregivers balance discretion preferences against cost constraints through supermarket economy-tier purchasing. Apodaca industrial parks concentrate medical supply warehousing for cross-border fulfillment.
Bajío Region
Querétaro's pilot-scale plant-derived superabsorbent polymer compounders at 2,000-tonne annual capacity fragment raw material sourcing strategies. León and Irapuato absorb production planning for medium and large size configurations serving obesity-prevalent senior demographics. State-level senior care subsidies expand direct-to-consumer volumes in semi-urban municipalities.
Northern Border States
Chihuahua and Baja California absorb cross-border caregiver coordination through pharmacy teleconsultation hotlines serving US-based adult children. Tijuana and Ciudad Juárez retail channels integrate reimbursement processing for dual-nationality households. Extended producer responsibility framework uncertainty delays manufacturing facility investments in the zone.
Mexico Pant Type Adult Diaper Market Competitive Landscape
Player mix skews toward multinational hygiene conglomerates with Nordic and North American technology heritage dominating premium absorbency tiers, while regional manufacturing specialists compete on import substitution and logistics proximity. Structure consolidates around three archetypes: integrated absorbent core engineers, retail shelf presence anchors, and scale-driven regional producers. Competitive moves concentrate on pharmacy channel pharmacist-assisted selection integration and manufacturing line retooling for thinner SAP configurations.
Among Nordic-origin hygiene technology conglomerates, Essity Aktiebolag exemplifies premium-tier absorbency engineering heritage. Ontex BV and Kimberly-Clark Corporation occupy positions on the regional manufacturing and retail distribution vectors respectively, with the former representing scale-driven import substitution strategies and the latter anchoring mass retail pharmacy network penetration. These three entities collectively illustrate the competitive tension between technology-led premium positioning and logistics-proximate volume scaling.
| Leading Market Players |
|---|
| Essity Aktiebolag |
| First Quality Enterprises |
| Kimberly-Clark Corporation |
| Ontex BV |
| Medline Industries |
| Unicharm Corporation |
| Kao Corporation |
| Daio Paper Corporation |
| Procter & Gamble Company |
| Others |
Pricing and Supply Chain Analysis
Regional manufacturing scale at Ontex BV's Querétaro operations compresses unit economics for domestic producers while import-dependent competitors absorb Asian petrochemical feedstock volatility through margin compression. This scale asymmetry concentrates pricing power among integrated absorbent core engineers and fragments margin structures for non-integrated assemblers sourcing breathable backsheet films through Laredo-Nuevo Laredo corridors.
Pricing Analysis
Next-generation plant-derived superabsorbent polymer cores command premium positioning against petroleum-based SAP configurations and legacy pulp-dominant absorbent systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by COFEPRIS absorbency certification tier and pharmacist-assisted channel integration. Cost compression in economy tiers intensifies because supermarket private-label expansion erodes branded shelf space. Family caregivers in Jalisco's extended care arrangements exhibit highest price sensitivity; pharmacy-integrated subscribers in Mexico City demonstrate lowest elasticity due to reimbursement processing convenience.
Supply Chain Analysis
Thailand and China anchor superabsorbent polymer feedstock production for Mexican hygiene manufacturers, while domestic Querétaro compounders pilot modified starch alternatives at pilot scale. Raw material sourcing draws from Southeast Asian petrochemical complexes, Brazilian pulp plantations, and regional PLA biopolymer development. Single-source vulnerability concentrates in breathable backsheet film extrusion where limited domestic blown film capacity forces Asian supplier dependency. Distribution runs through pharmacy chain auto-replenishment networks and medical supply distributor bulk contracting for institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern as COFEPRIS harmonization with ISO 11948 testing protocols reduces technical barriers and accelerates premium product refresh cycles.
For Market Incumbents: Compound channel control through pharmacist-assisted selection integration at Mexico City and Guadalajara pharmacy chains to defend against direct-to-consumer subscription displacement. Secure backward integration into plant-derived SAP sourcing from Querétaro compounders before feedstock cost volatility reshapes input economics. Prioritize COFEPRIS registration pipeline investment to compress 12-18 month timeline disadvantages against EU and US entrants. For New Entrants and Emerging Players: COFEPRIS fast-track pathways for ISO 11948 pre-validated absorbency claims offer lowest-friction market entry for EU and US manufacturers with existing third-party laboratory relationships. Target biodegradable topsheet positioning in Guadalajara's private nursing facility expansion where environmental scrutiny concentrates procurement preference. Deploy teleconsultation-integrated subscription models for US-based adult children coordinating parental care remotely from California and Texas. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmacy chain auto-replenishment subscribers with integrated reimbursement processing, suggesting durable cash flow quality in channel-integrated assets. Five-to-ten year viability favors manufacturers with captive SAP core engineering and regional production footprints that hedge import dependency. Monitor COFEPRIS extended producer responsibility framework finalization as inflection signal for capital allocation toward biodegradable material production capacity.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Registration Pipeline Investment | Compresses 12-18 month product launch cycles for new absorbency tier introductions. |
| Pharmacy Channel Integration | Captures highest-margin consumer segments through pharmacist-assisted selection and reimbursement processing. |
| Plant-Derived SAP Backward Integration | Hedges petrochemical feedstock volatility through Querétaro compounder partnerships. |
| Biodegradable Topsheet Production Scale-Up | Positions for extended producer responsibility framework compliance and premium institutional procurement. |
| Direct-to-Consumer Subscription Launch | Displaces institutional procurement for US-based adult children managing remote parental care. |
Research Methodology
A spread of perspectives from COFEPRIS regulatory affairs specialists, pharmacy chain category managers, nursing facility procurement directors, and absorbent core manufacturing engineers converged on the working assumptions for market sizing and growth trajectory. Primary fieldwork combined structured interviews with secondary validation against COFEPRIS medical device registration databases, NOM-252-SCFI/SSA1-2014 amendment filings, and customs import records for SAP and backsheet film feedstocks. Bottom-up demand modeling from end-user mobility profiles and top-down supply validation from manufacturing capacity disclosures were triangulated to establish volume and value estimates.
Segmentation dimensions modeled include product type composition, end-user mobility status, distribution channel economics, and anthropometric size specifications across the projection horizon. CAGRs were derived from regression analysis of historical demand elasticities against aging demographic projections and policy subsidy expansion trajectories. Forecast inputs incorporated COFEPRIS registration timeline distributions, pharmacy channel auto-replenishment adoption curves, and plant-derived SAP production scale-up schedules from Querétaro and Puebla compounders.
Underlying assumptions cover sustained aging-in-place policy momentum and ISO 11948 harmonization stability, with deviation risk concentrated in extended producer responsibility framework implementation timing and pulp-SAP input cost volatility. Recalibration cycles align with material shifts in COFEPRIS regulatory amendments and cross-border caregiver coordination pattern changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
Biodegradable Baby Diapers Market
Baby Diapers
Smart Connected Diaper Market
Baby Diapers
Nonwoven Baby Diaper Market
Baby Diapers
United States Diaper Market
Baby Diapers
Latin America Diaper Market
Baby Diapers
Baby Disposable Diapers Market
Baby Diapers
Cat Diapers Market
Baby Diapers
Malaysia Diapers Market
Baby Diapers
Australia Pant Type Adult Diaper Market
Baby Diapers
Diaper Market
Baby Diapers
Europe Diaper Market
Baby Diapers
Baby Cloth Diaper Market
Baby Diapers
Adult Diapers Market
Baby Diapers
Disposable Hygiene Products Market
Baby Diapers
China Pant Type Adult Diaper Market
Baby Diapers
North America Diaper Market