
 Baby Cloth Diaper Market | 2026-2036
Baby Cloth Diaper Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Cloth Diaper Market Analytics
Direct-to-consumer subscription channels is tilting toward bundling and replenishment models that lock in repeat purchases. Cotton Babies leverages its vertically integrated manufacturing to control cost and quality across organic cotton supply chains. GroVia differentiates through hybrid systems that bridge disposable convenience with reusable cores. Thirsties Baby sustains domestic production in the United States, anchoring its brand in local sewing and quick-turn customization.
A baby cloth diaper is a reusable absorbent garment constructed from layered natural or synthetic textiles—typically cotton, hemp, bamboo, or microfiber—with waterproof outer shells and adjustable closures, designed for repeated washing and extended wear across infant development stages. Manufacturing employs textile cutting, ultrasonic welding or stitching, and snap or hook-and-loop fastening assembly to achieve durability through hundreds of laundering cycles. Pocket diapers lead volume due to their modular insert system that lets parents customize absorbency. Bamboo fiber segments attract margin concentration as antimicrobial properties and sustainability claims command premium positioning. All-in-One designs compete for convenience-oriented buyers who prioritize simplicity over customization flexibility.
REACH in Europe mandates full chemical disclosure for textile dyes and finishes, pushing suppliers toward certified organic inputs or OEKO-TEX Standard 100 compliance. The FDA regulates absorbent products marketed with medical or dermatological claims in the United States, creating a compliance threshold for brands positioning around rash prevention. China's GB standards for infant textile safety add testing requirements for formaldehyde content and colorfastness that exporters must satisfy. Stakeholders should monitor how tightening chemical regulations across multiple jurisdictions reshape material sourcing strategies and supplier qualification timelines.
Market Dynamics
Millennial parents are driving a structural shift toward subscription-based replenishment models that lock in recurring revenue streams while simultaneously demanding chemical transparency certifications from textile suppliers.
Growth Catalysts
- REACH compliance mandates:ECHA's chemical disclosure requirements for absorbent textiles push European suppliers toward OEKO-TEX Standard 100 certification, creating quality differentiation that premium brands exploit.
- Bamboo fiber processing scale-up:China's domestic bamboo textile infrastructure expansion reduces raw material costs and enables antimicrobial positioning claims that command shelf price premiums.
- Direct-to-consumer subscription mechanics:Bundled replenishment programs reduce customer acquisition costs and flatten demand volatility for vertically integrated manufacturers.
Market Restraints
- Organic cotton input volatility:Weather-dependent fiber harvests and irrigation constraints in India and Turkey create raw material cost instability that compresses margin predictability.
- China supply concentration:GB standards compliance requirements and domestic processing dominance create single-source vulnerability for bamboo-derived absorbent layers.
- Disposable diaper substitution:Convenience-oriented parents in dual-income households frequently default to single-use alternatives during travel or daycare transitions.
Strategic Opportunities
- Underpenetrated Southeast Asian markets:Indonesia and Vietnam present white space where rising middle-class formation outpaces established brand presence.
- EU Green Deal procurement incentives:Public sector and corporate parental benefit programs increasingly favor reusable textile products with verified carbon footprint reductions.
- Smart textile convergence:Integration of moisture-sensing polymers with washable electronics creates premium positioning for tech-forward parents monitoring infant hydration.
Industry Challenges
- Specialized textile engineering talent scarcity:Ultrasonic welding and antimicrobial finish application require skills concentrated in legacy European and Japanese manufacturing clusters.
- Multi-jurisdiction certification timelines:Simultaneous FDA dermatological claim reviews, REACH chemical dossier preparation, and GB standard testing create 18-24 month product launch delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Cloth Diaper Market |
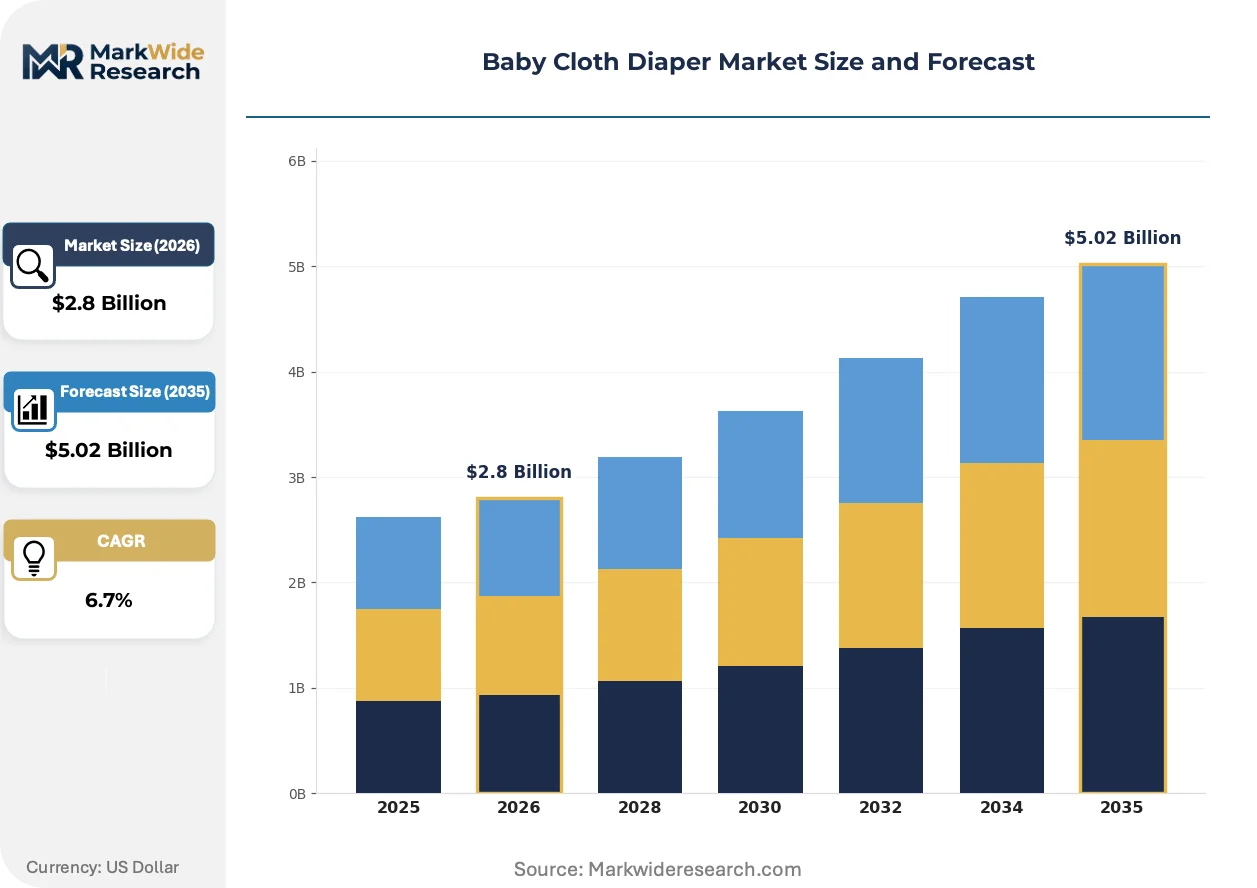
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-in-One, Pocket Diapers, Fitted Diapers, Pre-fold Diapers Material: Cotton, Hemp, Bamboo, Microfiber Age Group: Newborns, Infants, Toddlers, Preschoolers Distribution Channel: Online Retail, Baby Specialty Stores, Department Stores, Grocery Chains |
| Companies Covered | Cotton Babies, LittleLamb, The Procter & Gamble Company, GroVia, Charlie Banana, Babee Greens, Modern Cloth Nappies, Bumkins, Thirsties Baby, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Cloth Diaper Market Evolving Landscape
Active material science advances and regulatory transparency mandates are compressing product development cycles while simultaneously fragmenting buyer segments into certification-preference clusters.
Modular insert systems are hybridizing natural and synthetic absorbent layers to balance wicking speed against skin sensitivity. First-time parents in urban China adopt these configurations fastest, treating customization as a hygiene optimization tool. The technology is hybridizing previously separate premium and mass-market tiers into single product architectures with tiered insert options.
ECHA's REACH enforcement expansion into textile finishing agents is forcing dye suppliers to reformulate colorfast chemistries. European importers now demand full material safety data sheet disclosure that adds 8-12 weeks to supplier qualification. Pocket diaper categories face the steepest compliance cost increases due to multi-component sourcing complexity.
Subscription bundling is displacing single-unit trial purchases as the dominant acquisition path. Direct-to-consumer channels capture parents during third-trimester preparation phases, locking preference before hospital discharge samples introduce disposable alternatives. This behavioral shift concentrates most visibly in US coastal metro markets where delivery infrastructure and parental leave duration support home-based laundry routines.
Baby Cloth Diaper Market Segmentation
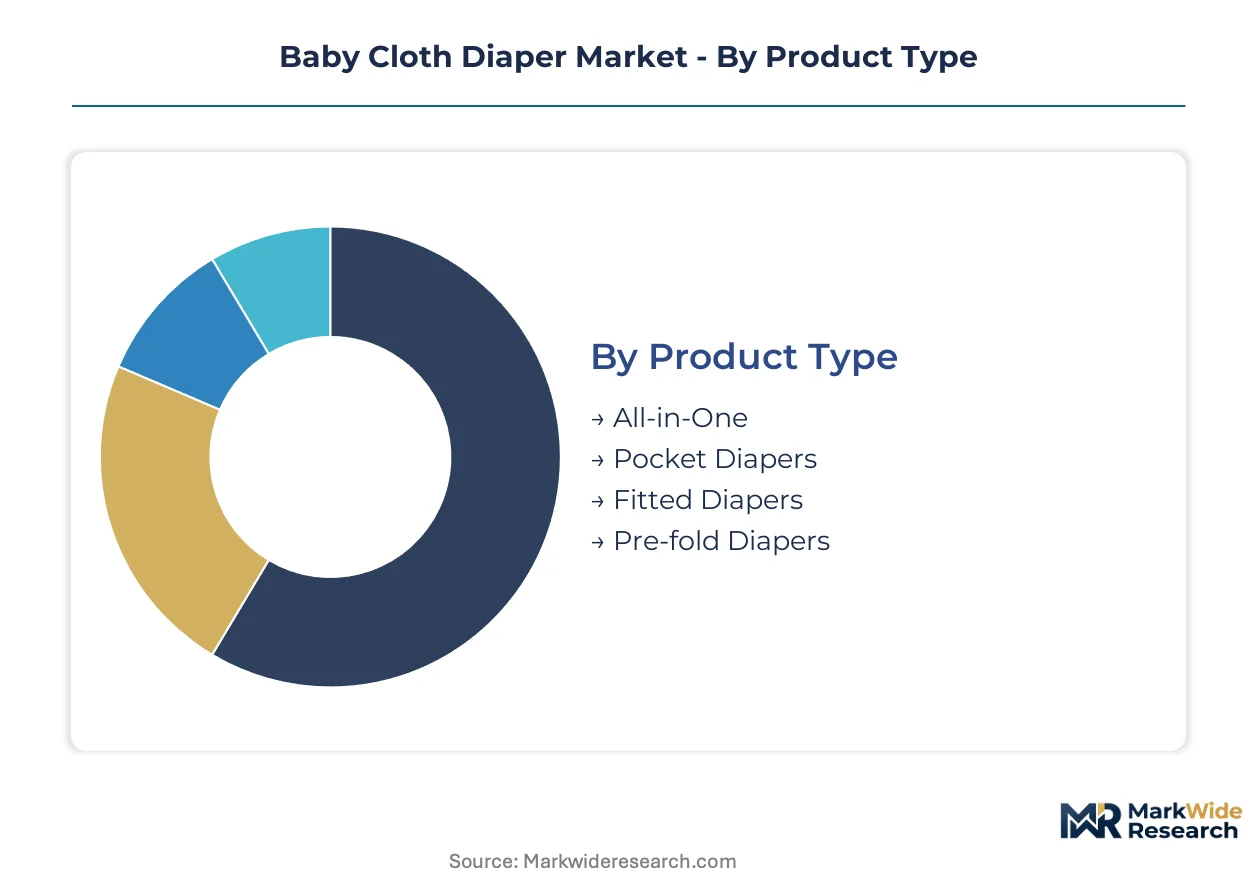
Segmentation in the baby cloth diaper market reveals how product architecture, material sourcing, and channel access fragment purchasing decisions across parent demographics. Each dimension carries distinct margin profiles and regulatory exposure that shape competitive positioning.
Product Type:
Product architecture separates convenience-oriented parents from customization-seekers, with design complexity driving price tiering and repeat purchase patterns.
- Pocket Diapers:Modular insert systems with stay-dry lining and removable absorbent layers allow parents to adjust thickness for daytime or overnight use. Demand concentrates in urban China where millennial parents treat customization as hygiene optimization, though multi-component sourcing complexity elevates REACH compliance costs for European importers.
- All-in-One:Sewn-in absorbent layers eliminate assembly steps, appealing to daycare environments and dual-income households prioritizing speed. Adoption runs strongest in US coastal metros where subscription bundling locks preference before hospital discharge samples introduce disposable alternatives.
- Fitted Diapers:Contoured absorbent shapes require separate waterproof covers, preserving natural fiber breathability for rash-prone infants.
- Pre-fold Diapers:Rectangular cotton layers demand folding skill and pin or snappi fastening, retaining price-sensitive traditionalists and institutional buyers.
Pocket diapers command the established base. The steepest expansion runs through All-in-One designs.
Material:
Raw material selection determines antimicrobial claims, carbon footprint positioning, and supply chain vulnerability to agricultural volatility.
- Bamboo:Cellulose fibers processed through closed-loop viscose or mechanical crushing yield natural antimicrobial properties that support premium shelf positioning. China's domestic bamboo textile infrastructure expansion reduces input costs and enables verified sustainability claims for EU Green Deal procurement programs.
- Cotton:Conventional and organic cultivars dominate volume through established processing infrastructure, though weather-dependent harvests in India and Turkey create margin unpredictability.
- Hemp:Bast fibers offer superior absorbency retention and durability across hundreds of laundering cycles, attracting eco-conscious longevity seekers.
- Microfiber:Synthetic polyester-polyamide blends deliver rapid wicking speed at mass-market price points, though petroleum dependency conflicts with circular economy positioning.
Cotton retains the volume base. Bamboo fibers are climbing the fastest on antimicrobial and sustainability premiums.
Age Group:
Developmental stage segmentation aligns product sizing with physiological changes in elimination frequency and mobility patterns.
- Infants:Three to twelve months represents peak diaper dependency with highest daily change frequency, driving subscription replenishment velocity and insert customization experimentation.
- Newborns:Umbilical cord cutouts and lower absorbency requirements define specialized designs for the first weeks, though shorter usage duration limits per-customer lifetime value.
- Toddlers:Walking mobility demands trimmer fits and pull-up style transitions, reducing cloth retention as potty training approaches.
- Preschoolers:Overnight bedwetting solutions sustain limited demand for extended-size waterproof covers and heavy-duty inserts.
Infant sizing commands the established base. Toddler transition products face the steepest competitive pressure from disposable pull-up alternatives.
Distribution Channel:
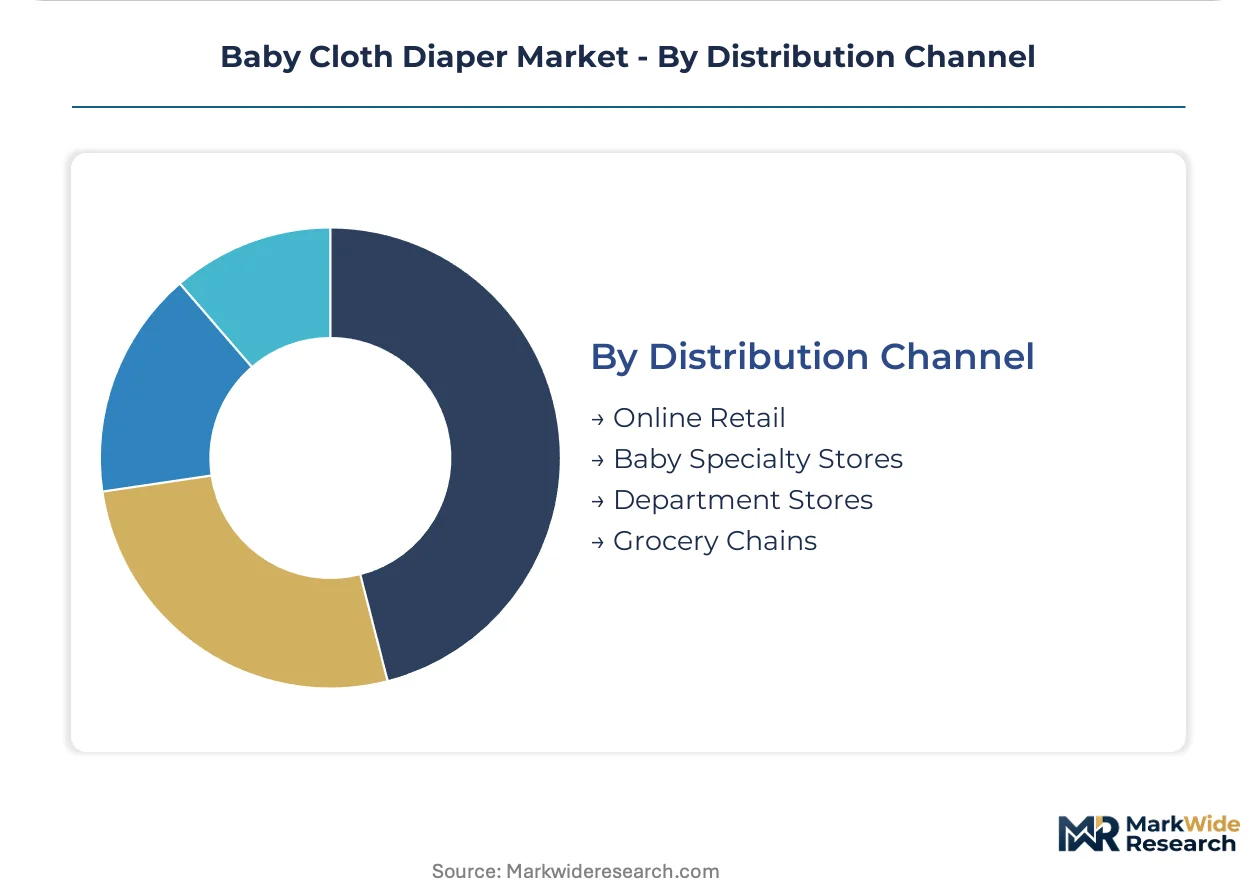
Channel selection separates discovery-driven trial from replenishment efficiency, with digital infrastructure reshaping customer acquisition economics.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enable third-trimester targeting with bundled trial packs that lock preference before birth. Subscription mechanics flatten demand volatility for vertically integrated manufacturers while capturing parental data for personalized insert recommendations.
- Baby Specialty Stores:Staff expertise and tactile product examination support first-time parent education, particularly for hybrid system configurations requiring fitting guidance.
- Department Stores:Mass-market presence exposes brands to convenience-oriented shoppers seeking single-unit trial before online replenishment migration.
- Grocery Chains:Impulse placement near disposable alternatives captures emergency purchases and travel kit assembly, though limited SKU depth constrains customization options.
Online retail commands the established base. Baby specialty stores retain the steepest strategic value for complex system education and premium conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH enforcement anchors European compliance architecture, while China's GB standards and domestic bamboo processing infrastructure reshape raw material economics across Asia.
United States
Millennial parents in coastal metros drive subscription bundling adoption, with third-trimester targeting locking preference before hospital discharge samples introduce disposable alternatives. FDA dermatological claim reviews create compliance thresholds for rash-prevention positioning. Domestic sewing clusters in Colorado and North Carolina sustain quick-turn customization for vertically integrated brands.
China
Urban millennial parents treat modular insert customization as hygiene optimization, accelerating pocket diaper adoption fastest among first-time buyers. GB standards for infant textile safety mandate formaldehyde content testing and colorfastness verification that exporters must satisfy. Sichuan and Zhejiang provinces anchor domestic bamboo-fiber processing scale-up, reducing raw material costs for antimicrobial-claim products.
Germany
EU Green Deal procurement incentives push public sector parental benefit programs toward reusable textiles with verified carbon footprint reductions. ECHA's chemical disclosure requirements for textile dyes and finishes force reformulation of colorfast chemistries, adding supplier qualification timelines. North Rhine-Westphalia hosts legacy textile engineering clusters where ultrasonic welding skills concentrate.
United Kingdom
Dual-income households in London and Southeast England prioritize All-in-One convenience designs for daycare transitions and speed of use. OEKO-TEX Standard 100 certification serves as quality differentiation that premium brands exploit in retail positioning. Midlands manufacturing heritage supports specialist sewing operations for fitted diaper covers requiring waterproof layer integration.
India
Organic cotton cultivars in Gujarat and Maharashtra face weather-dependent harvest volatility and irrigation constraints that compress margin predictability for export-oriented brands. BIS textile safety standards add testing layers for imported absorbent products. Tamil Nadu's established garment processing infrastructure enables contract manufacturing for international labels seeking cost-competitive natural fiber assembly.
Baby Cloth Diaper Market Competitive Landscape
Vertically integrated manufacturers and specialist hybrid-system designers split the market between cost-control architectures and convenience-positioned premium tiers. The vendor base concentrates around three strategic archetypes: captive-supply cotton processors, modular-system innovators, and domestic-production anchors. Capacity expansion in bamboo-fiber processing and strategic partnerships for antimicrobial finish licensing represent dominant competitive moves reshaping material sourcing advantages.
Among North American specialists, Cotton Babies and Thirsties Baby exemplify contrasting production philosophies, while GroVia occupies a position bridging disposable convenience with reusable cores. Chinese contract manufacturers and European dye-chemistry reformulators sit within the compliance-driven supplier tier, with ECHA REACH dossier preparation capabilities determining market access velocity. The competitive map rewards players controlling upstream fiber processing or downstream subscription data capture.
| Leading Market Players |
|---|
| Cotton Babies |
| LittleLamb |
| The Procter & Gamble Company |
| GroVia |
| Charlie Banana |
| Babee Greens |
| Modern Cloth Nappies |
| Bumkins |
| Thirsties Baby |
| Others |
Value Network & Pricing Analysis
China's domestic bamboo-fiber processing infrastructure concentrates raw material supply for antimicrobial-claim products, anchoring margin pools in premium positioning tiers where OEKO-TEX certification commands shelf price premiums. This upstream concentration directly shapes downstream pricing power for brands able to verify sustainable sourcing claims.
Pricing Analysis
Coastal US metros exhibit 15-25% price premiums over Midwest markets due to subscription bundling density and third-trimester targeting intensity. Pricing stratifies across premium, standard, and economy tiers, with certification grade and volume scale driving differentiation. Cost compression in organic cotton tiers is intensifying because weather-dependent harvests in India and Turkey create input volatility. First-time parents in urban China show lowest price sensitivity, while institutional buyers in India represent the most price-constrained segment.
Supply Chain Analysis
Export-control scrutiny on textile dye chemistry under ECHA's REACH enforcement restricts flow of certain colorfast formulations into European markets, forcing supplier reformulation. Manufacturing draws from China, India, and Turkey for absorbent textiles, with bamboo pulp, organic cotton fiber, and hemp bast as core inputs. Single-source vulnerability concentrates in Sichuan and Zhejiang provinces for antimicrobial fiber processing. Distribution runs through direct-to-consumer subscription platforms, baby specialty retail, and grocery impulse placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Millennial subscription adoption and REACH chemical transparency mandates constitute a dual inflection reshaping competitive economics in this high-growth segment.
For Market Incumbents: Insulate market position through captive supply of certified organic cotton and backward integration into bamboo-fiber processing. Prioritize OEKO-TEX Standard 100 investment to defend against emerging private-label entrants exploiting compliance gaps. Lock in subscription data capture before hospital discharge samples introduce disposable alternatives. For New Entrants and Emerging Players: Southeast Asian middle-class formation in Indonesia and Vietnam represents the most penetrable entry point, with underdeveloped subscription infrastructure and rising hygiene awareness. Target EU Green Deal procurement programs for public sector parental benefit contracts. Lead with antimicrobial bamboo positioning and direct-to-consumer trial bundling to bypass established retail gatekeepers. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated manufacturers with captive fiber processing and established subscription mechanics. Five-to-ten-year viability hinges on regulatory compliance velocity rather than scale alone. Monitor ECHA enforcement expansion into textile finishing agents as the critical inflection signal for supplier qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Bamboo-Fiber Processing Scale-Up | China's Sichuan and Zhejiang infrastructure expansion reduces raw material costs for antimicrobial claims. |
| Subscription Platform Integration | Third-trimester targeting locks parental preference before hospital discharge samples introduce disposables. |
| OEKO-TEX Certification Investment | REACH compliance creates quality differentiation that premium brands exploit in European retail positioning. |
| Direct-to-Consumer Channel Expansion | Digital acquisition economics flatten demand volatility for vertically integrated manufacturers. |
| Sustainability Repositioning | EU Green Deal procurement incentives favor reusable textiles with verified carbon footprint reductions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across brand managers at Cotton Babies and GroVia, procurement leads at bamboo-fiber processors, category buyers at baby specialty retailers, and regulatory affairs specialists navigating REACH dossier preparation. Secondary validation drew from ECHA chemical disclosure filings, GB standards testing protocols, customs records for absorbent textile trade flows, and OEKO-TEX certification databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Calibration anchored historical volume trajectories to known subscription adoption curves and regulatory enforcement timelines. Segmentation dimensions spanned product architecture, material sourcing, age-based sizing, and channel access patterns across the projection horizon. CAGRs derived from elasticity modeling against millennial parent income trajectories and bamboo-fiber cost curves. Forecast inputs incorporated REACH compliance cost pass-through rates and subscription retention benchmarks.
Practitioners should monitor ECHA enforcement expansion, GB standards revision cycles, and organic cotton harvest volatility for early signals of forecast deviation. Material shifts in chemical regulatory stringency or fiber input economics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
Cat Diapers Market
Baby Diapers
Australia Pant Type Adult Diaper Market
Baby Diapers
United Arab Emirates Baby Diapers and Wipes Market
Baby Diapers
United States Adult Diaper Market
Baby Diapers
GCC Diaper Market
Baby Diapers
Dog Diapers Market
Baby Diapers
Baby Training Diaper Market
Baby Diapers
Diaper Market
Baby Diapers
United States Diaper Market
Baby Diapers
UAE Baby Diapers Industry Market
Baby Diapers
Middle East and Africa and Asia Pacific Baby Diaper Market
Baby Diapers
Europe Diaper Market
Baby Diapers
Smart Connected Diaper Market
Baby Diapers
Mexico Pant Type Adult Diaper Market
Baby Diapers
East Africa Baby Diaper Market
Baby Diapers
Global Baby Swim Pants Diaper Market