
 Baby Disposable Diapers Market | 2026-2036
Baby Disposable Diapers Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Disposable Diapers Market Analysis
The EU Green Deal is realigning procurement criteria for absorbent hygiene products across European retail chains. Procter & Gamble leverages its North American manufacturing scale to supply chlorine-free pulp variants at volume. Kimberly-Clark Corporation anchors its competitive position through sustained R&D spending on plant-based top-sheet technologies. Unicharm Corporation dominates Southeast Asian pharmacy and convenience channels with localized sizing for regional infant anthropometrics.
Baby disposable diapers are single-use absorbent garments comprising fluff pulp cores, polyethylene back-sheets, non-woven fabric topsheets, and elasticized leg cuffs designed for urine and fecal containment in non-toilet-trained infants. Superabsorbent polymer loading typically ranges from eight to fifteen grams per unit depending on size classification and intended wear duration. The newborn product type commands premium shelf positioning due to higher unit sensitivity and parental willingness to pay for dermatological certifications. Online retailers represent the fastest-expanding distribution channel as subscription replenishment models reduce price elasticity among time-constrained caregiver segments.
The US EPA regulates volatile organic compound emissions from adhesive and polymer processing facilities, while the EU REACH framework restricts certain phthalate plasticizers in elastic components. China's SAMR enforces GB standards for infant product safety labeling and migration limits on aromatic amines from printed outer layers. Stakeholders must monitor evolving extended producer responsibility schemes that shift end-of-life collection costs toward manufacturers.
Market Dynamics
EU Green Deal single-use plastic directives are forcing absorbent hygiene manufacturers to reconfigure material sourcing and end-of-life collection systems ahead of compliance deadlines. This regulatory pressure cascades through procurement criteria at major European retail chains.
Growth Catalysts
- Plant-based top-sheet technologies:R&D advances in bio-derived non-woven fabrics reduce petrochemical dependency while meeting dermatological certification standards for sensitive infant skin.
- Urban millennial parent segments in emerging economies:Rising disposable incomes in metropolitan Southeast Asian corridors drive premium eco-diaper adoption through modern retail pharmacy channels.
- Subscription replenishment models:Online retailers capture time-constrained caregiver segments via automated reordering systems that reduce price elasticity and improve inventory predictability.
Market Restraints
- Fluff pulp input cost volatility:Chlorine-free pulp sourcing faces pricing pressure from competing tissue and packaging demand in North American timber markets.
- Superabsorbent polymer supply concentration:SAP manufacturing clusters in Northeast Asian chemical corridors create geographic vulnerability for European and North American converters.
- REACH phthalate restrictions:ECHA limitations on plasticizers in elastic leg cuff components force reformulation cycles that extend product development timelines.
Strategic Opportunities
- Extended producer responsibility schemes:EU member state mandates for manufacturer-funded diaper collection infrastructure create first-mover advantages for integrated waste-management partnerships.
- Biodegradable back-sheet convergence:Compostable polyethylene alternatives combined with microbial degradation technologies open premium positioning in German and French urban markets.
- Localized sizing for regional anthropometrics:Southeast Asian pharmacy channels reward brands offering tailored fit specifications for regional infant body proportions.
Industry Challenges
- GB standards migration testing:SAMR enforcement of aromatic amine limits from printed outer layers requires extensive third-party laboratory validation for China market entry.
- Legacy adhesive system reconfiguration:EPA volatile organic compound emission limits for polymer processing facilities demand capital-intensive scrubber installations at North American manufacturing sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Disposable Diapers Market |
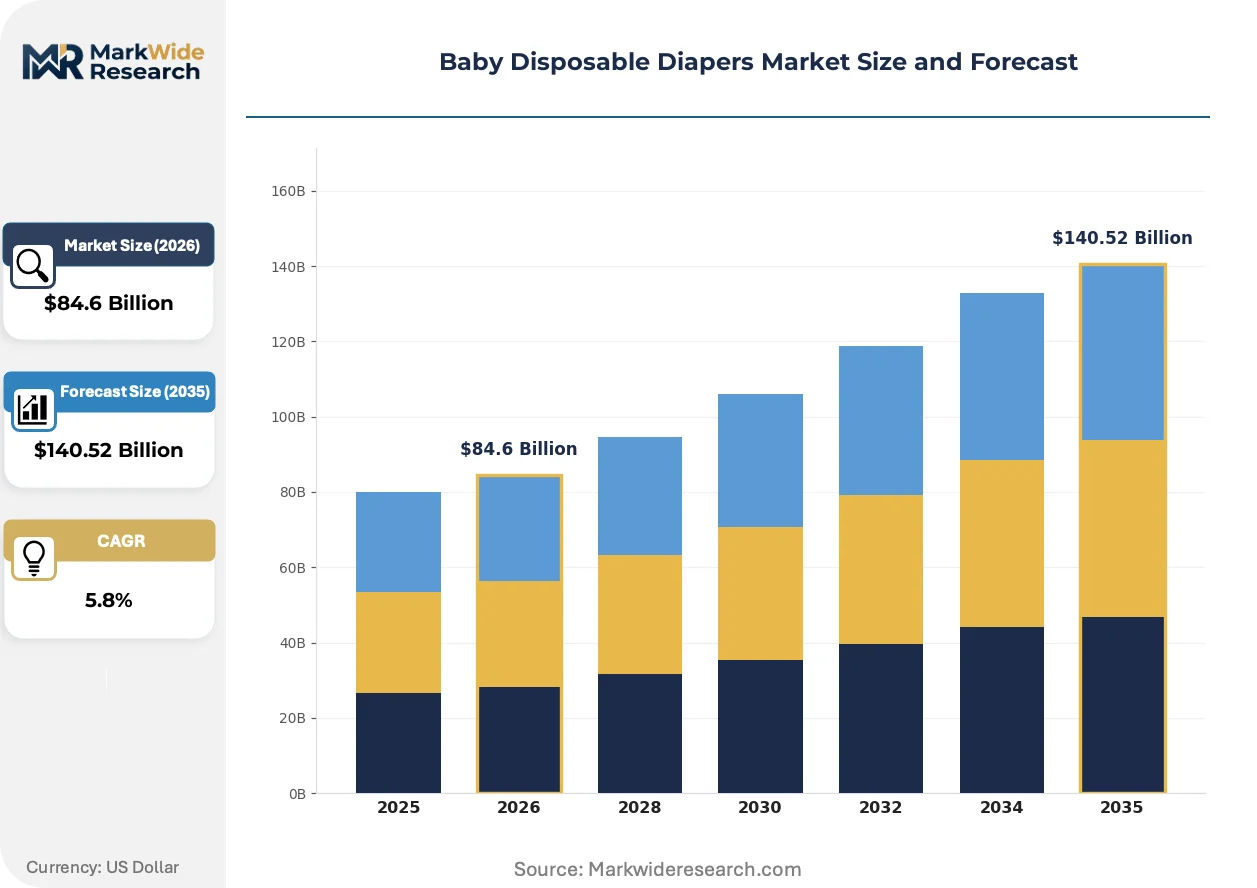
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $140.52 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Newborn, Infants, Toddlers, Multi-size Material: Fluff Pulp, Polyethylene, Adhesives, Non-woven Fabrics Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Pharmacies Customer Type: Parents, Caregivers, Hospitals, Daycare Centers |
| Companies Covered | Procter & Gamble, Kimberly-Clark Corporation, Unicharm Corporation, Kao Corporation, Essity AB, Ontex International, Hengan International Group, First Quality Enterprises, The Honest Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Disposable Diapers Market Emerging Trajectories
Material science advances and regulatory compliance pressures are restructuring competitive advantage around biodegradability credentials and circular supply chain architectures rather than unit cost alone.
Biodegradable superabsorbent polymers derived from polysaccharide and protein-based feedstocks are decentralizing the historical dominance of petroleum-derived sodium polyacrylate in premium diaper segments. European specialty chemical suppliers and Japanese trading houses are accelerating pilot production to secure offtake agreements with multinational hygiene brands. This technology shift is decentralizing supply chain control from established petrochemical conglomerates toward agricultural biotechnology processors and regional compounding facilities.
REACH authorization requirements for persistent organic pollutants in absorbent hygiene products are tightening migration limits for formaldehyde-releasing preservatives and fragrance allergens. ECHA's 2024 updated guidance on skin-sensitizing substances forces reformulation of lotion-infused topsheets and printed outer layers. German and Scandinavian retail chains are responding with private-label certification programs that exceed baseline regulatory thresholds to capture environmentally conscious parent segments.
Direct-to-consumer subscription platforms are compressing traditional wholesale-distributor relationships in urban North American and Western European markets. Pharmacy and convenience channel incumbents face disintermediation as millennial caregivers prioritize automated replenishment over in-store brand comparison. This channel migration is most pronounced in metropolitan corridors of California, Ontario, and the Netherlands where digital payment penetration and delivery logistics density support same-day fulfillment models.
Baby Disposable Diapers Market Segmentation
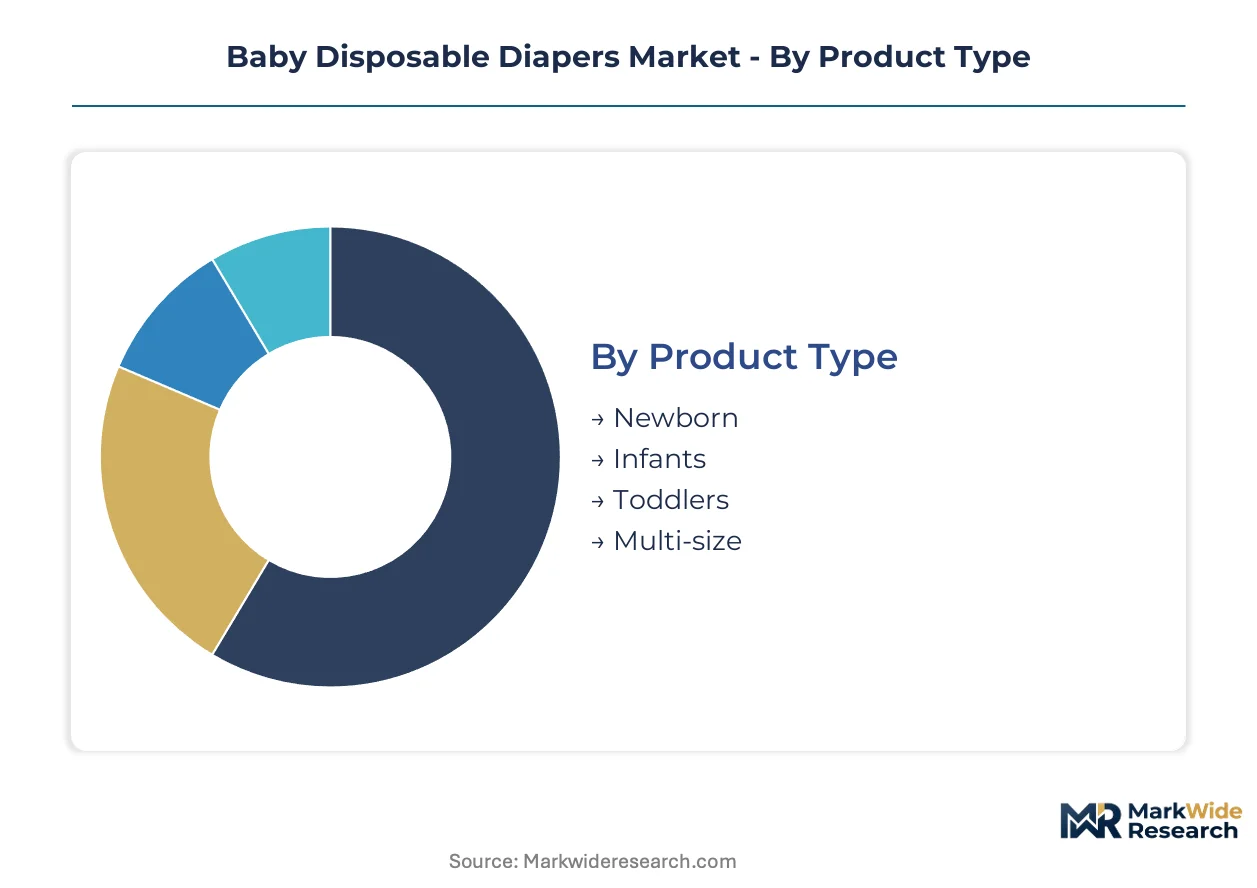
Segmentation in baby disposable diapers reveals how material specifications, sizing architectures, and channel economics create distinct profit pools. Manufacturers configure production lines and marketing investments around these divides rather than treating the category as uniform.
Product Type:
Size-classification systems align with developmental milestones and absorbency engineering requirements rather than simple age brackets.
- Newborn:Ultra-soft top-sheets and umbilical cord cutouts address fragile skin and healing tissue in the first weeks of life. Demand clusters in hospital maternity wards and pharmacy channels across Germany, France, and the Netherlands where parental willingness to pay for dermatological certifications peaks.
- Infants:Mid-range absorbency cores with wetness indicators dominate volume production. Southeast Asian metropolitan corridors in Indonesia, Vietnam, and Thailand drive procurement as modern retail penetration deepens and birth rates remain elevated.
- Toddlers:Pull-up configurations with tear-away side panels support toilet-training transitions. Elasticized waistbands require reformulation under REACH phthalate restrictions.
- Multi-size:Adjustable fastening systems reduce SKU complexity for subscription replenishment models. Online retailers favor these for inventory efficiency.
Newborn leads on scale; Infants leads on momentum.
Material:
Input composition determines regulatory exposure and circular economy positioning across manufacturing footprints.
- Fluff Pulp:Chlorine-free bleaching processes command premium positioning in North American markets. Sourcing faces pricing pressure from competing tissue and packaging demand in timber markets.
- Polyethylene:Back-sheet layers face EU Green Deal single-use plastic directives forcing transitions toward compostable alternatives. German and French urban markets reward biodegradable credentials.
- Adhesives:Hot-melt systems for core stabilization and leg cuff attachment face EPA volatile organic compound emission limits at processing facilities. Scrubber installations add capital intensity.
- Non-woven Fabrics:Plant-based top-sheet technologies from bio-derived feedstocks reduce petrochemical dependency. Japanese trading houses and European specialty chemical suppliers accelerate pilot production.
Fluff Pulp dominates current tonnage; Non-woven Fabrics shows steepest expansion trajectory.
Distribution Channel:
Channel selection shapes pricing architecture and customer acquisition economics through fulfillment density.
- Supermarkets:Mass-market volume with high shelf-fee burdens and promotional intensity. Private-label competition compresses branded margins.
- Online Retailers:Subscription replenishment models capture time-constrained caregiver segments in California, Ontario, and the Netherlands. Automated reordering reduces price elasticity and improves inventory predictability.
- Convenience Stores:Emergency purchase occasions with severe SKU truncation. Limited to standard sizes and economy tiers.
- Pharmacies:Premium positioning through dermatological certification and pharmacist recommendation. Unicharm anchors this channel in Southeast Asia with localized sizing.
Supermarkets retain volume leadership; Online Retailers gains share fastest.
Customer Type:
Procurement authority and volume concentration vary sharply across institutional and household buyers.
- Parents:Primary decision-makers with high price sensitivity for daily-use items but willingness to pay premiums for certification claims. Digital payment penetration supports subscription adoption.
- Caregivers:Secondary purchasers including grandparents and nannies with lower brand loyalty and higher in-store substitution rates.
- Hospitals:Bulk procurement through group purchasing organizations with stringent absorbency and skin-safety specifications. Maternity ward sampling programs influence take-home brand selection.
- Daycare Centers:Mid-scale institutional demand with standardized sizing requirements and cost-minimization mandates. Regional chains negotiate direct with manufacturers.
Parents anchor household volume; Hospitals concentrate procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mass-market diaper manufacturing originated in the United States during the post-war consumer goods expansion, with Procter & Gamble's 1961 Pampers launch establishing the modern disposable format. Production subsequently dispersed across industrialized economies as absorbent polymer chemistry and non-woven fabrication matured.
United States
Millennial parents in California and the Pacific Northwest drive premium eco-diaper subscription adoption through automated replenishment platforms. EPA volatile organic compound emission limits for adhesive processing facilities mandate capital-intensive scrubber installations at manufacturing sites. North American timber markets supply chlorine-free fluff pulp to converters clustered in the Southeast and Midwest regions.
Germany
Urban parents in Berlin, Hamburg, and the Rhine-Ruhr corridor demonstrate elevated willingness to pay for dermatological certifications and biodegradable back-sheet credentials. EU Green Deal single-use plastic directives force material transitions ahead of compliance deadlines, with ECHA REACH restrictions on phthalate plasticizers affecting elastic leg cuff formulations. Private-label certification programs at major retail chains exceed baseline regulatory thresholds to capture environmentally conscious segments.
China
Rising disposable incomes in Shanghai, Beijing, and the Pearl River Delta metropolitan corridors expand demand for mid-range and premium infant diaper tiers. SAMR enforces GB standards for infant product safety labeling and migration limits on aromatic amines from printed outer layers. Domestic manufacturers in Fujian and Guangdong provinces scale production to serve both local consumption and export markets across Southeast Asia.
Japan
Declining birth rates concentrate demand in Tokyo, Osaka, and Nagoya metropolitan areas where parental spending per unit remains elevated. METI industrial policy supports advanced materials R&D in bio-derived non-woven fabrics and superabsorbent polymer alternatives. Trading houses accelerate pilot production partnerships with multinational hygiene brands seeking technology licensing arrangements.
Indonesia
Elevated birth rates in Jakarta, Surabaya, and Bandung metropolitan corridors sustain volume growth as modern retail pharmacy penetration deepens. Localized sizing specifications for regional infant anthropometrics reward brands adapting fit architectures to Southeast Asian body proportions. Unicharm anchors distribution through convenience and pharmacy channel dominance in Java and Sumatra population centers.
Baby Disposable Diapers Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tiers and material sophistication gradients. The vendor base organizes into three strategic archetypes: multinational consumer goods conglomerates with integrated pulp-to-shelf supply chains, regional specialists leveraging localized sizing and channel relationships, and direct-to-consumer entrants capturing subscription economics in digitally penetrated markets. Dominant competitive moves include portfolio diversification into plant-based material variants and strategic partnerships with waste-management operators under extended producer responsibility schemes.
Within the multinational conglomerate tier, Procter & Gamble and Kimberly-Clark Corporation occupy positions defined by North American manufacturing scale and sustained R&D spending on chlorine-free pulp and plant-based top-sheet technologies. Unicharm Corporation exemplifies the regional specialist archetype through its dominance of Southeast Asian pharmacy and convenience channels. These three entities represent distinct competitive positioning vectors—scale-driven supply security, innovation-led material transitions, and localized channel anchoring—rather than direct substitutability.
| Leading Market Players |
|---|
| Procter & Gamble |
| Kimberly-Clark Corporation |
| Unicharm Corporation |
| Kao Corporation |
| Essity AB |
| Ontex International |
| Hengan International Group |
| First Quality Enterprises |
| The Honest Company |
| Others |
Supply Flow & Price Mechanics
Fluff pulp sourcing costs cascade through three-tier pricing structures across premium, standard, and economy levels as North American timber markets face competing tissue and packaging demand. Chlorine-free bleaching premiums concentrate in newborn diaper tiers where parental willingness to pay for dermatological certifications peaks in German and Dutch pharmacy channels.
Pricing Analysis
Subscription replenishment models anchor pricing architecture for time-constrained caregiver segments in California and Ontario metropolitan corridors. Price differentiation separates dermatologically certified premium tiers from standard absorbency cores through certification grade and volume scale economics. Cost compression in economy tiers intensifies because private-label competition at European supermarket chains compresses branded margins. Daycare center procurement teams exhibit highest price sensitivity while hospital group purchasing organizations concentrate volume authority with stringent absorbency specifications.
Supply Chain Analysis
Workforce availability constraints in Fujian and Guangdong provinces limit scaling flexibility for domestic Chinese manufacturers serving Southeast Asian export markets. Geographic supply concentration centers on China, Indonesia, and Vietnam for finished goods assembly while superabsorbent polymer feedstocks draw from Northeast Asian chemical corridors. Single-source vulnerability in SAP manufacturing clusters creates geographic risk for European and North American converters. Distribution runs through pharmacy and convenience channel dominance in Java and Sumatra population centers anchored by regional specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in plant-based material transitions and subscription platform economics as fluff pulp input volatility compresses economy-tier returns. Premium-tier shift toward biodegradable back-sheet credentials in German and French urban markets supports pricing power.
For Market Incumbents: Extend plant-based top-sheet R&D partnerships with Japanese trading houses to secure technology licensing arrangements ahead of REACH phthalate compliance deadlines. Consolidate channel control through integrated waste-management partnerships under extended producer responsibility schemes to defend against direct-to-consumer subscription disintermediation in California and Ontario corridors.
For New Entrants and Emerging Players: Compostable polyethylene back-sheet technologies offer entry wedge into German and French urban markets where EU Green Deal directives accelerate material transitions ahead of incumbent reformulation cycles. Target Southeast Asian pharmacy channels with localized sizing specifications for regional infant anthropometrics in Jakarta and Surabaya metropolitan corridors. Pursue pharmacist recommendation programs as primary go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for regional specialists with pharmacy channel anchoring because fragmented convenience store distribution in Indonesia and Vietnam resists scale consolidation by multinational conglomerates. Five-to-ten-year viability hinges on biodegradable superabsorbent polymer pilot production partnerships securing offtake agreements. Watch ECHA migration limit updates on formaldehyde-releasing preservatives as inflection indicator for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Plant-Based Material Transition | Reduces petrochemical dependency while meeting REACH dermatological certification standards for sensitive infant skin. |
| Subscription Platform Launch | Captures time-constrained millennial caregivers in California and Ontario through automated replenishment reducing price elasticity. |
| Extended Producer Responsibility Partnership | Creates first-mover advantage in EU member state diaper collection infrastructure mandates shifting end-of-life costs. |
| Localized Sizing Development | Rewards pharmacy channel penetration in Southeast Asia with tailored fit specifications for regional infant body proportions. |
| Biodegradable Back-Sheet Certification | Opens premium positioning in German and French urban markets under EU Green Deal single-use plastic directives. |
Methodological Framework
Direct dialogue with brand managers, category buyers at major retail chains, supply planners at pulp converters, and channel sales heads in Southeast Asian pharmacy networks grounded qualitative insights. Secondary validation drew from Nielsen retail audit data, customs and trade records for fluff pulp and superabsorbent polymer flows, SEC filings of listed hygiene manufacturers, and ECHA regulatory guidance documents. Bottom-up and top-down triangulation cross-checked volume assumptions against production capacity disclosures and channel inventory turns.
Bottom-up modeling segmented volume and value across product type, material composition, distribution channel, and customer archetype dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical birth rate trajectories, modern retail penetration curves, and regulatory compliance cost absorption patterns. Industry-specific inputs included SAP manufacturing capacity expansion announcements and EU member state extended producer responsibility implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to birth rate volatility in Southeast Asian metropolitan corridors and REACH authorization updates on skin-sensitizing substances. Forecasts reflect assumptions on material substitution cost curves and subscription platform adoption rates. Material deviation in ECHA migration limit enforcement or Northeast Asian SAP supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
Biodegradable Diapers Market
Baby Diapers
Adult Diapers Market
Baby Diapers
Pet Diapers Market
Baby Diapers
Diaper Market
Baby Diapers
Nonwoven Baby Diaper Market
Baby Diapers
Malaysia Diapers Market
Baby Diapers
GCC Diaper Market
Baby Diapers
United States Diaper Market
Baby Diapers
Baby Training Diaper Market
Baby Diapers
Baby Diaper Manufacturing Machine Market
Baby Diapers
Biodegradable Baby Diapers Market
Baby Diapers
United Arab Emirates Baby Diapers and Wipes Market
Baby Diapers
Disposable Hygiene Products Market
Baby Diapers
Global Baby Swim Pants Diaper Market
Baby Diapers
Europe Diaper Market
Baby Diapers
Smart Diaper Market