
 Disposable Hygiene Products Market | 2026-2036
Disposable Hygiene Products Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Hygiene Products Market Intelligence
ISO 9001 quality management certification is reorganizing supplier eligibility across the disposable hygiene supply chain, raising barriers for uncertified converters and raw material vendors. Procter & Gamble leverages its North American manufacturing scale to secure shelf space across mass retail and pharmacy channels. Kimberly-Clark Corporation sustains R&D intensity in superabsorbent polymer formulations that reduce core thickness while maintaining fluid retention benchmarks. Ontex Group NV specializes in private-label adult incontinence production, occupying a defensible position with European healthcare procurement authorities.
Disposable hygiene products encompass single-use absorbent articles engineered from layered nonwoven topsheets, acquisition distribution layers, superabsorbent polymer cores, and breathable backsheet films, manufactured through hot-melt adhesive lamination and elastic strand integration processes. These articles serve containment and skin-health functions for infant elimination management, menstrual hygiene, adult urinary incontinence, and clinical surface disinfection. Diapers and sanitary pads represent mature volume categories where margin pools have shifted toward premium-tier variants with organic cotton or plant-based backsheet claims. Adult incontinence products represent the fastest-expanding end-user segment as demographic aging and reduced institutional care stigma expand addressable populations. Biodegradable materials within the material segmentation command price premiums but face scale constraints in pulp sourcing and composting infrastructure availability.
The U.S. FDA regulates medical-grade incontinence products through 510(k) clearance pathways that differentiate reimbursable clinical supplies from general consumer goods. The EU ECHA enforces REACH chemical restrictions on residual monomers in SAP and fragrance allergens in scented wipes, directly reformulating product development pipelines. China's NMPA and GB standards for disposable hygiene impose microbial limit testing that determines factory audit frequency and import license validity. Stakeholders must monitor evolving extended producer responsibility frameworks that will determine whether post-consumer collection infrastructure becomes a competitive differentiator or a compliance cost burden.
Market Dynamics
The EU Green Deal's single-use plastics directive is forcing converters to abandon petroleum-based backsheet films and requalify entire lamination lines for biodegradable substrates, compressing margin structures while opening premium positioning for certified sustainable alternatives.
Growth Catalysts
- REACH chemical restrictions:ECHA enforcement on residual monomers in superabsorbent polymers is accelerating SAP reformulation investments that reduce core thickness while maintaining fluid retention benchmarks.
- Long-term care infrastructure:Aging populations in institutional settings across Germany, Japan, and the United States are expanding addressable demand for medical-grade adult incontinence products with reimbursable supply status.
- Urban birth-rate policies:China's municipal childcare subsidy programs sustain volume leadership in infant diaper consumption despite national fertility decline.
Market Restraints
- Pulp sourcing concentration:Nordic and Brazilian softwood pulp suppliers control critical input for biodegradable topsheet alternatives, exposing converters to fiber price volatility and shipping disruption.
- Composting infrastructure gaps:Industrial composting facility scarcity in North American and Asian markets limits end-of-life claims for plant-based backsheet products, constraining marketing differentiation.
- 510(k) clearance timelines:FDA medical device pathways for reimbursable incontinence products extend product development cycles by 18-24 months versus general consumer goods.
Strategic Opportunities
- Healthcare procurement centralization:European Union joint purchasing authorities are consolidating adult incontinence contracts, creating volume consolidation opportunities for ISO 9001-certified private-label manufacturers.
- Extended producer responsibility frameworks:France and Italy are piloting post-consumer diaper collection mandates that will differentiate competitors with established reverse logistics infrastructure.
- Dual carbon goals alignment:China's MEE carbon intensity targets for manufacturing are accelerating demand for energy-efficient hot-melt adhesive lamination equipment upgrades.
Industry Challenges
- Microbial limit testing compliance:China's NMPA GB standards impose factory audit frequency tied to contamination control performance, requiring dedicated quality assurance headcount and cleanroom capital investment.
- Elastic strand integration complexity:Legacy equipment retrofits for biodegradable elastic alternatives demand mechanical engineering expertise scarce among mid-scale converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Hygiene Products Market |
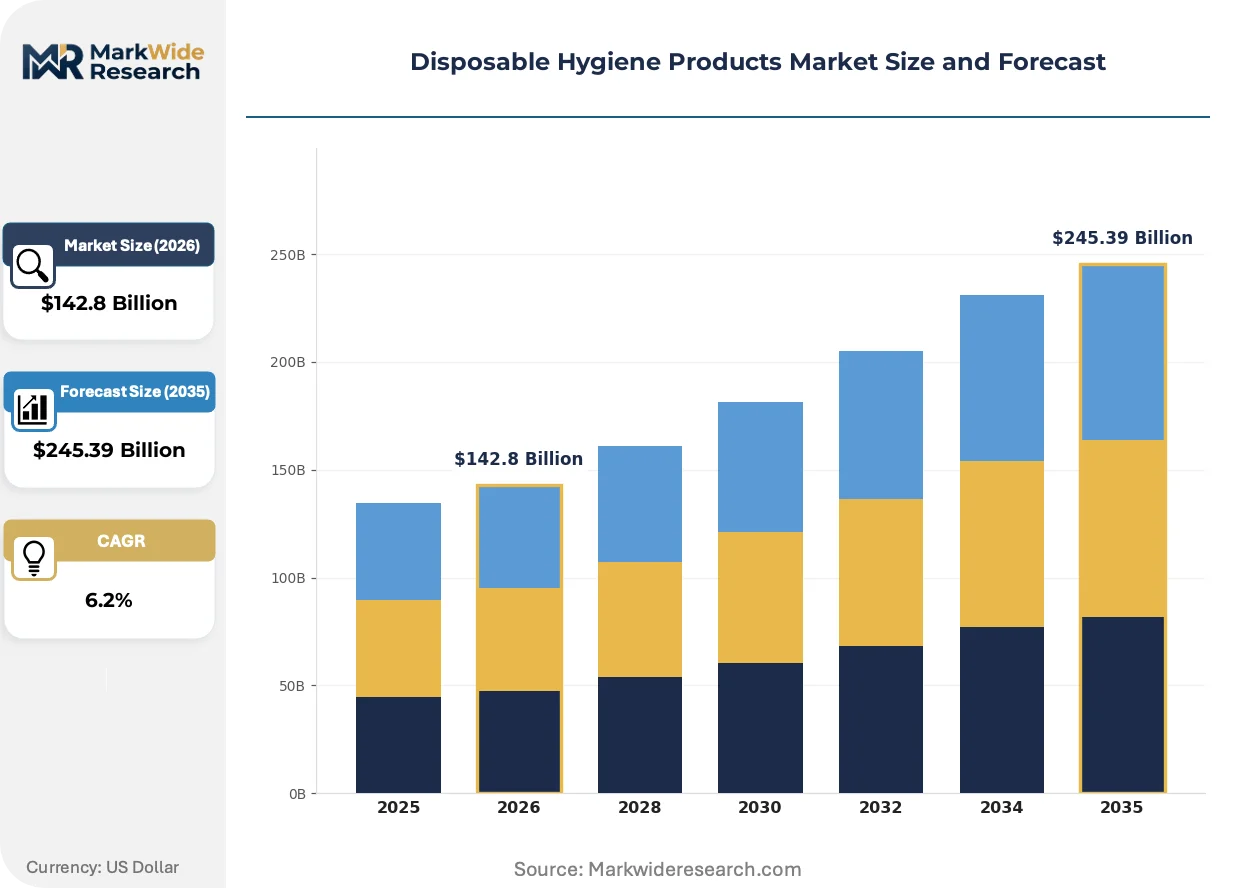
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $245.39 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diapers, Sanitary Pads, Adult Incontinence Products, Wipes End User: Infants, Women, Elderly, Healthcare Facilities Material: Nonwoven Fabric, Plastic, Biodegradable Materials, Cotton Distribution Channel: Supermarkets, Online Retail, Pharmacies, Convenience Stores |
| Companies Covered | Essity AB, Ontex Group NV, Procter & Gamble, Johnson & Johnson Services, Inc., Kao Corporation, Kimberly-Clark Corporation, Hengan International Group, Edgewell Personal Care Company, Unicharm Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Hygiene Products Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory chemistry restrictions are converging to reshape product architectures, with sustainability certifications becoming gatekeepers for shelf space rather than optional premium claims.
Plant-based superabsorbent polymers derived from corn starch and cellulose grafting are decomposing the petroleum-SAP supply oligopoly. European healthcare procurement authorities are mandating bio-based content thresholds in tender specifications. This chemistry transition is compressing incumbent polymer margins while enabling new entrants with agricultural feedstock partnerships to capture premium-tier positioning.
ECHA enforcement of REACH Annex XVII restrictions on fragrance allergens in scented wipes is eliminating entire product lines from European pharmacy channels. Reformulation pipelines are prioritizing unscented variants with natural antimicrobial claims. Baby care and feminine hygiene segments in Germany and Benelux markets are responding fastest, with private-label converters accelerating SKU rationalization to avoid regulatory detention at port.
Hospital system buying cooperatives in the United States are consolidating annual incontinence supply contracts into multi-year sole-source agreements with performance guarantees. Distributor intermediaries face disintermediation as GPOs negotiate direct manufacturer relationships with penalty clauses for stockout events. This concentration is most visible in the Southeast and Midwest regions where Catholic health system networks command substantial volume leverage.
Disposable Hygiene Products Market Segmentation
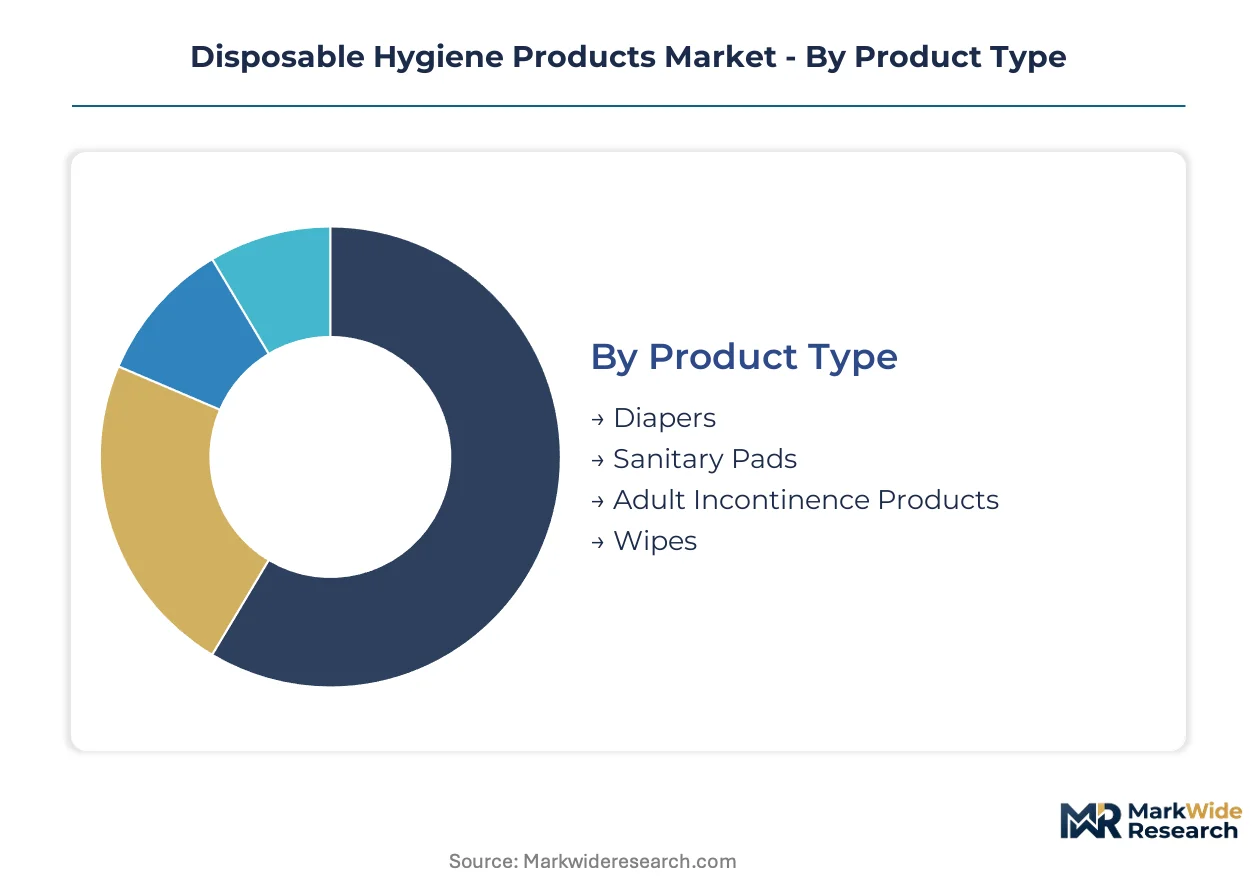
Segmentation in disposable hygiene reveals where margin pools concentrate and which product architectures face imminent regulatory displacement. Material composition and end-user demographics determine vulnerability to EU Green Deal mandates and procurement certification requirements.
Product Type:
Substitute pressure intensifies for petroleum-derived formats as biodegradable alternatives capture pharmacy and premium retail shelf space.
- Diapers:Layered nonwoven topsheets with SAP cores dominate infant and adult formats. China's municipal childcare subsidies sustain volume in urban centers despite national fertility decline.
- Sanitary Pads:Acquisition distribution layers with breathable backsheet films serve menstrual hygiene management. India's BIS certification requirements and rural distribution expansion concentrate demand in tier-2 cities.
- Adult Incontinence Products:Medical-grade variants with reimbursable status in German and Japanese long-term care facilities anchor the steepest expansion trajectory across all product types.
- Wipes:REACH Annex XVII fragrance allergen restrictions in Europe are eliminating scented SKUs from pharmacy channels, forcing rapid reformulation toward unscented natural antimicrobial claims.
Diapers anchor the volume base while adult incontinence products gain share at the steepest rate.
End User:
Demographic concentration determines pricing power, with institutional procurement commanding volume discounts unavailable in consumer channels.
- Infants:Urban birth-rate policies in Chinese municipalities sustain diaper consumption despite broader fertility trends. Premium organic cotton variants command shelf space in tier-1 city supermarkets.
- Women:Menstrual hygiene demand concentrates in India and Southeast Asia where BIS and national standardization efforts expand addressable populations through rural distribution.
- Elderly:Home-based care transitions in Germany and Japan reduce institutional stigma while expanding reimbursable product eligibility under national health frameworks.
- Healthcare Facilities:US hospital GPO consolidation into multi-year sole-source agreements with stockout penalties disintermediates traditional distributor relationships.
Healthcare facilities procurement anchors the volume base while elderly home-care segments gain share at the steepest rate.
Material:
Cost tier stratification separates certified sustainable inputs from commodity petroleum derivatives facing regulatory phase-out timelines.
- Nonwoven Fabric:Spunbond-meltblown-spunbond polypropylene structures provide acquisition distribution layers. Nordic and Brazilian softwood pulp concentration exposes converters to fiber price volatility.
- Plastic:Petroleum-based backsheet films face EU single-use plastics directive abandonment, forcing lamination line requalification for biodegradable alternatives.
- Biodegradable Materials:Corn starch and cellulose-graft superabsorbent polymers decompose the petroleum-SAP oligopoly. European healthcare tenders now mandate bio-based content thresholds.
- Cotton:Organic certification claims differentiate premium-tier feminine hygiene in German and Benelux pharmacy channels where ECHA enforcement eliminates synthetic alternatives.
Nonwoven fabric anchors the volume base while biodegradable materials gain share at the steepest rate.
Distribution Channel:
Channel control determines margin capture, with direct manufacturer relationships displacing intermediary distributors in concentrated procurement systems.
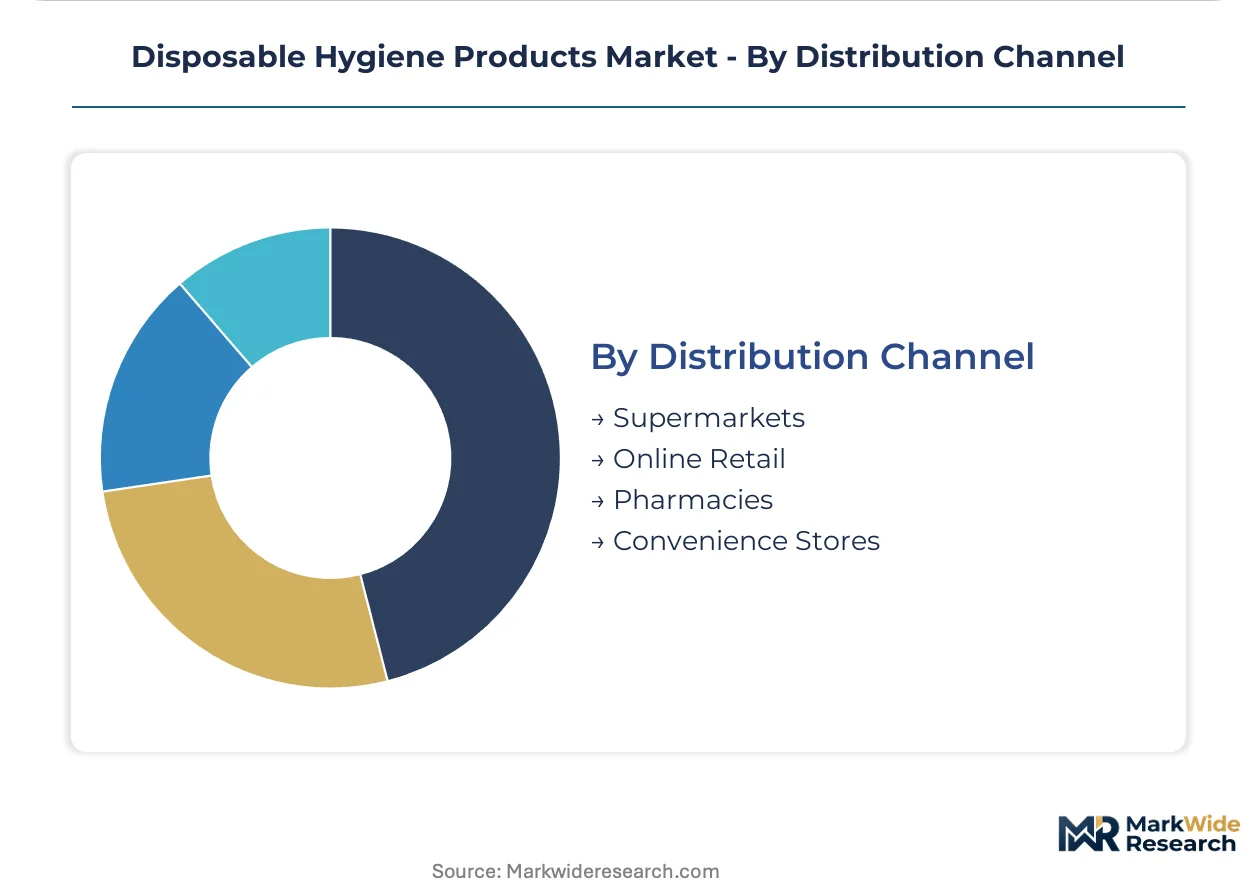
- Supermarkets:Mass retail shelf space in North American and European markets favors P&G scale advantages and private-label ISO 9001-certified converters with consistent supply guarantees.
- Online Retail:Subscription models for adult incontinence reduce purchase stigma while capturing recurring revenue pools outside pharmacy reimbursement systems.
- Pharmacies:REACH-compliant unscented wipes and medical-grade incontinence products with 510(k) clearance dominate European and US pharmacy channel assortments.
- Convenience Stores:Emergency purchase occasions for feminine hygiene and infant diapers command premium pricing in urban clusters with limited retail density.
Supermarkets anchor the volume base while online retail gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal mandates on single-use plastics and China's municipal childcare subsidies are redirecting manufacturing investment toward biodegradable substrates and urban diaper capacity. Germany, Japan, and the United States anchor medical-grade incontinence demand through reimbursable long-term care frameworks.
United States
FDA 510(k) clearance pathways differentiate reimbursable clinical supplies from consumer goods, extending development cycles for medical-grade incontinence products. Hospital GPO consolidation in the Southeast and Midwest regions concentrates procurement into multi-year sole-source agreements with stockout penalties. The Pacific Northwest and Northeast corridor host pilot composting infrastructure for plant-based backsheet alternatives.
Germany
ECHA REACH enforcement on fragrance allergens and residual SAP monomers eliminates non-compliant wipes from pharmacy channels. Joint purchasing authorities consolidate adult incontinence contracts, favoring ISO 9001-certified private-label manufacturers. The North Rhine-Westphalia and Bavaria industrial clusters house lamination equipment retrofits for biodegradable elastic integration.
China
NMPA GB microbial limit standards and MEE carbon intensity targets raise factory audit frequency and energy-efficient equipment requirements. Municipal childcare subsidies in tier-1 cities sustain infant diaper volume despite national fertility decline. The Yangtze River Delta and Pearl River Delta concentrate superabsorbent polymer reformulation capacity.
Japan
METI long-term care insurance expansion reduces institutional stigma while extending reimbursable product eligibility to home-based elderly care. PMDA medical device classifications align with reimbursement tiers for moderate-to-severe incontinence grades. The Kanto and Kansai regions anchor premium-tier adult diaper distribution networks.
India
BIS certification requirements and rural distribution expansion concentrate sanitary pad demand in tier-2 cities. National standardization efforts for menstrual hygiene management expand addressable populations through subsidized procurement programs. The Maharashtra and Gujarat industrial corridors host nonwoven topsheet manufacturing for domestic and export markets.
Disposable Hygiene Products Market Key Industry Players
Player mix skews toward integrated multinationals with captive polymer supply and specialized private-label converters serving healthcare procurement. Market structure concentrates around three archetypes: North American mass-market scale players, European healthcare-certified specialists, and Asia-Pacific diversified consumer goods conglomerates. Dominant competitive moves include lamination line requalification for biodegradable substrates and direct manufacturer relationships with consolidated hospital GPOs.
Within the healthcare-certified specialist tier, Ontex Group NV and Kimberly-Clark Corporation exemplify divergent scale positions serving European reimbursable incontinence markets. Procter & Gamble anchors the mass-market multinational archetype with integrated North American manufacturing scale. These three entities represent the competitive spectrum from private-label ISO 9001 certification to vertically controlled retail shelf space.
| Leading Market Players |
|---|
| Essity AB |
| Ontex Group NV |
| Procter & Gamble |
| Johnson & Johnson Services, Inc. |
| Kao Corporation |
| Kimberly-Clark Corporation |
| Hengan International Group |
| Edgewell Personal Care Company |
| Unicharm Corporation |
| Others |
Cost & Logistics Intelligence
ISO 9001 certification gates both supplier eligibility and price differentiation simultaneously, forcing uncertified converters into commodity tiers while certified manufacturers capture healthcare procurement premiums. This dual-gating mechanism concentrates margin pools among qualified players as ECHA REACH and FDA 510(k) pathways add compliance layers that separate reimbursable clinical tiers from consumer-grade pricing.
Pricing Analysis
Cost-plus contracts with Nordic softwood pulp indexation dominate raw material procurement for biodegradable topsheet alternatives. Three-tier pricing structure across premium organic cotton, standard polypropylene, and economy petroleum-based variants separates certified sustainable claims from commodity tiers. Pricing pressure stems from EU Green Deal lamination line requalification costs compressing converter margins. Healthcare facilities exhibit lowest price sensitivity due to reimbursable supply status, while convenience store channels face highest elasticity on emergency purchase occasions.
Supply Chain Analysis
Just-in-time inventory strategies prevail for mass retail diaper replenishment, whereas strategic stockpiling of superabsorbent polymers buffers against Nordic and Brazilian pulp supply volatility. Geographic concentration centers on China for lamination equipment manufacturing, Germany for elastic strand integration engineering, and the United States for FDA-cleared medical-grade distribution. Raw material dependencies include corn starch feedstocks for plant-based SAP, breathable backsheet films, and hot-melt adhesive formulations. Single-source vulnerability in pulp sourcing exposes converters to shipping disruption. Distribution runs through consolidated hospital GPOs in North America and European joint purchasing authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based adult incontinence delivery services expand faster than hardware unit sales, creating recurring revenue attachment opportunities that reduce purchase stigma while locking in customer lifetime value.
For Market Incumbents: Consolidate lamination line capacity for biodegradable substrate qualification before EU directive phase-out deadlines tighten. Acquire ISO 9001-certified private-label converters in Germany to secure healthcare procurement positioning against Ontex Group NV specialization. Deepen backward integration into corn starch SAP feedstocks to capture agricultural partnership premiums. For New Entrants and Emerging Players: Differentiate on compostable backsheet claims targeting Pacific Northwest pilot infrastructure zones where industrial composting facility scarcity constrains incumbent marketing. Penetrate India's tier-2 sanitary pad distribution through BIS-certified rural subsidy programs. Pursue direct-to-clinic sales models bypassing disintermediated distributor relationships. For Investors and Strategic Acquirers: EU Green Deal implementation timelines reshape the acquisition landscape toward biodegradable-capable asset bases. Five-to-ten year viability favors converters with lamination line requalification completed and healthcare certification in hand. Target acquisition archetype: mid-scale European private-label manufacturers with ISO 9001 credentials and existing hospital GPO relationships. Watch China's MEE carbon intensity enforcement as inflection signal for energy-efficient equipment upgrade demand.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Substrate Transition | EU Green Deal mandates force lamination line requalification for certified sustainable alternatives. |
| Healthcare Procurement Certification | ISO 9001 credentials unlock European joint purchasing authority contract consolidation opportunities. |
| SAP Feedstock Backward Integration | Corn starch agricultural partnerships decompose petroleum-polymer oligopoly pricing power. |
| Subscription Model Launch | Recurring revenue capture in adult incontinence reduces stigma while bypassing pharmacy reimbursement systems. |
| Composting Infrastructure Partnership | Pilot facility alliances in North America enable end-of-life claims that differentiate premium positioning. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with supply chain directors at nonwoven converters, procurement managers at hospital GPOs, regulatory affairs leads navigating FDA 510(k) pathways, and sustainability officers managing ECHA REACH compliance; alongside secondary validation through customs trade records for pulp and SAP imports, SEC filings of publicly listed hygiene manufacturers, EU tender documentation from joint purchasing authorities, and NMPA factory audit disclosure databases. Bottom-up volume modeling triangulated against top-down macroeconomic consumption projections.
Across the projection horizon, the analytical framework segmented demand by product architecture, material composition tier, end-user demographic, and distribution channel concentration. CAGRs derived from elasticity-adjusted consumption trajectories incorporating urban birth-rate policy impacts, aging population institutionalization rates, and regulatory compliance cost pass-through assumptions. Industry-specific inputs included superabsorbent polymer reformulation timelines and composting infrastructure rollout schedules.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement intensity or unexpected pulp supply disruption would require recalibration. Forecasts reflect documented assumptions regarding certification adoption curves and procurement centralization momentum. Revision becomes warranted when biodegradable substrate scale constraints or extended producer responsibility mandate implementation crosses threshold viability for mass-market tier penetration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
Dog Diapers Market
Baby Diapers
Baby Training Diaper Market
Baby Diapers
Africa and India Baby Diapers Market
Baby Diapers
Baby Disposable Diapers Market
Baby Diapers
United States Diaper Market
Baby Diapers
Reusable Baby Diapers and Training Pants Market
Baby Diapers
Australia Pant Type Adult Diaper Market
Baby Diapers
Smart Diaper Market
Baby Diapers
Pet Diapers Market
Baby Diapers
GCC Diaper Market
Baby Diapers
United States Adult Diaper Market
Baby Diapers
Middle East and Africa and Asia Pacific Baby Diaper Market
Baby Diapers
Europe Diaper Market
Baby Diapers
Global Baby Swim Pants Diaper Market
Baby Diapers
Cat Diapers Market
Baby Diapers
Malaysia Diapers Market