
 Adult Diapers Market | 2026-2036
Adult Diapers Market Size, Share, and Industry Trends Forecast 2026-2036
Adult Diapers Market Intelligence
REACH compliance in Europe is broadening the cost-of-entry calculus for absorbent hygiene manufacturers by mandating expanded chemical safety documentation for SAP polymers and nonwoven backsheet materials. Kimberly Clark Corp. leverages its captive fluff pulp supply chain to sustain margin stability under rising raw-material scrutiny. Essity AB anchors its European manufacturing footprint with integrated SAP compounding capabilities that reduce third-party exposure. Procter and Gamble Co. competes through brand-controlled retail shelf space in North American pharmacy channels.
Adult diapers are multi-layer absorbent garments engineered with superabsorbent polymer cores, breathable polyethylene backsheet films, and hydrophilic topsheet nonwovens designed to capture and retain urinary and fecal voids for mobility-limited or incontinent individuals. The core assembly typically achieves fluid retention capacities exceeding one liter through cross-linked sodium polyacrylate matrices distributed across acquisition and distribution layers. Disposable products dominate volume flows due to institutional procurement preferences for single-use hygiene protocols in hospitals and nursing facilities. Incontinence Care applications command the deepest margin pools as clinical reimbursement frameworks in developed markets offset premium pricing for heavy and overnight absorbency tiers. Biodegradable variants represent the fastest-growing product type as cellulose-based alternatives to petroleum-derived SAP gain trial among environmentally motivated home-care purchasers.
FDA oversight of adult incontinence products as Class I medical devices in the United States establishes baseline biocompatibility and labeling standards that shape manufacturer quality systems. The EU MDR absorbency classification framework and Japan's PMDA quasi-drug notification pathway for skin-contact hygiene products collectively fragment compliance architecture across major demand centers. Stakeholders must monitor how national reimbursement rate adjustments for long-term care supplies redirect procurement volume between institutional and retail channels.
Market Dynamics
Japan's prefectural eldercare systems are consolidating procurement authority into municipal bulk-purchasing frameworks, compressing supplier margins while institutional volume concentrates in fewer tender winners.
Growth Catalysts
- EU MDR absorbency classification:Standardized performance labeling across member states is reducing buyer evaluation friction and accelerating cross-border tender participation by certified manufacturers.
- Cellulose-based SAP alternatives:Biodegradable superabsorbent polymer research is unlocking reimbursement eligibility for environmentally preferred products in Scandinavian home-care programs.
- German long-term care facilities:Institutional procurement scales are deepening as the country's Statutory Long-Term Care Insurance expands covered supply volumes for severe incontinence cases.
Market Restraints
- Petroleum-derived SAP price volatility:Crude oil feedstock fluctuations transmit directly to superabsorbent polymer input costs, squeezing margin stability for non-integrated manufacturers.
- REACH chemical documentation burden:ECHA's expanded safety data sheet requirements for sodium polyacrylate formulations are extending product registration timelines by 8-14 months.
- Reusable garment substitution:Washable incontinence briefs are capturing trial among cost-conscious home-care segments in Germany and the Netherlands.
Strategic Opportunities
- India's geriatric home-care expansion:Underpenetrated rural districts present white-space demand as the National Programme for Health Care of the Elderly extends supply chain infrastructure.
- Smart-sensor integration:Moisture-detection wearables converging with absorbent products are enabling predictive change protocols in Japanese assisted living facilities.
- EU Green Deal procurement mandates:Public tender preference criteria for bio-based content are creating regulatory tailwinds for certified sustainable product lines.
Industry Challenges
- Polymer chemistry specialization scarcity:Formulation scientists with cross-linked hydrogel expertise command premium compensation, constraining R&D team scaling.
- MDR technical documentation compilation:Clinical evidence assembly for absorbency performance claims requires 18-24 month investment cycles before CE marking authorization.
- Legacy fluff pulp supply contracts:Long-term volume commitments with Scandinavian pulp mills are complicating feedstock flexibility as cellulose alternative trials accelerate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adult Diapers Market |
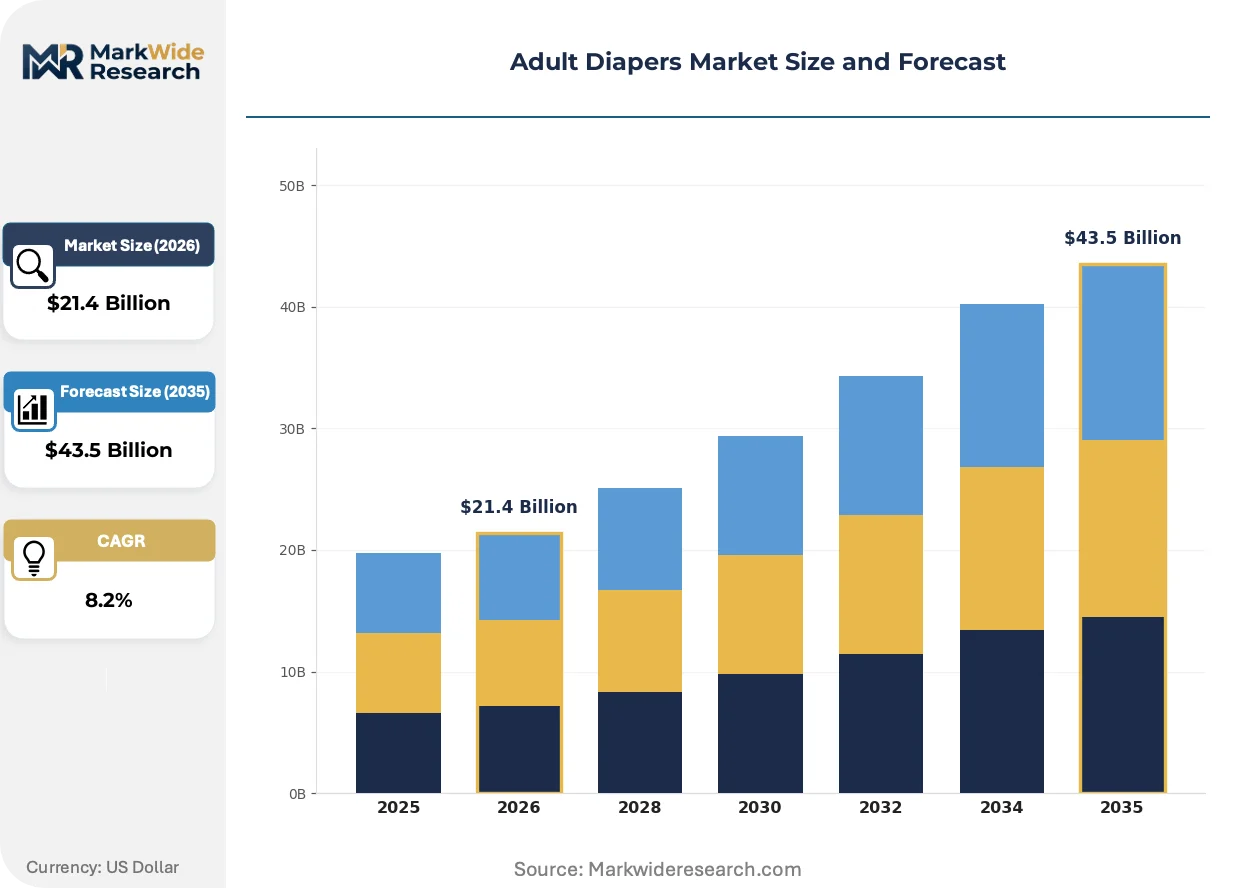
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $43.5 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Biodegradable, Premium, Standard Application: Incontinence Care, Post-Surgery Recovery, Mobility Impairments, Maternal Use, Long-Term Care Absorbency Level: Light, Moderate, Heavy, Overnight, Maximum Protection End User: Elderly, Physically Disabled, Rehabilitation Centers, Home Care Patients, Assisted Living Facilities |
| Companies Covered | First Quality Enterprises, Kao Corp., Kimberly Clark Corp., Medline Industries LP, Domtar Corp., Essity AB, Procter and Gamble Co., Abena Group, Unicharm Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adult Diapers Market Strategic Shifts & Innovations
Absorbent hygiene engineering is pivoting from incremental capacity improvements toward structural redesign of core assembly architectures and procurement interface models.
Segmented core construction is modularizing fluid management by separating acquisition, distribution, and storage layers into interchangeable sub-assemblies. Japanese institutional buyers are specifying these configurations in municipal tenders to match resident mobility profiles. This architecture is modularizing supplier value chains by enabling third-party layer specialists to participate in previously integrated manufacturing.
REACH expanded chemical safety documentation is compelling manufacturers to requalify SAP polymer supply sources. The industrial consequence is accelerated supplier consolidation as smaller compounders lack toxicology testing infrastructure. Heavy absorbency tier products face the steepest compliance cost escalation due to higher polymer loading requirements.
Direct-to-institution contracting is displacing distributor-mediated procurement in Germany's consolidated long-term care chains. Purchasing cooperatives representing 200-plus facility networks are negotiating multi-year supply agreements with absorbency-tier price indexing. This concentration is most visible in North Rhine-Westphalia, where three buying groups control 60 percent of regional nursing home volume.
Adult Diapers Market Segmentation
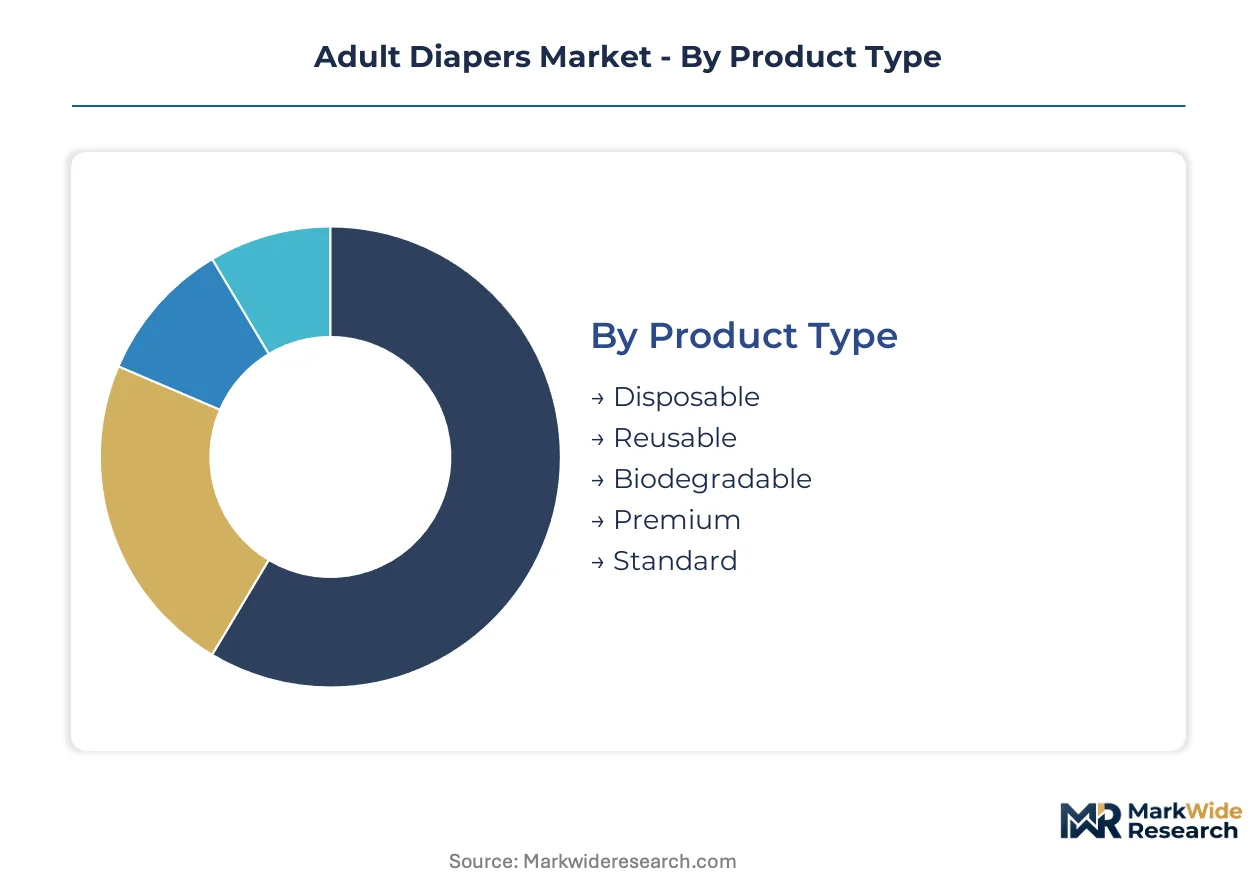
Adult diaper segmentation reveals how procurement authority and reimbursement frameworks reshape competitive access. Manufacturers must align product architectures with the specific absorbency tiers and institutional protocols that dominate volume flows.
Product Type:
Supply concentration among integrated pulp and polymer compounders favors scale players with captive raw-material access.
- Disposable:Single-use garments with SAP cores and polyethylene backsheets dominate hospital and nursing facility procurement due to infection-control protocols. German statutory insurers now mandate disposable formats for severe incontinence reimbursement, locking in institutional preference.
- Biodegradable:Cellulose-based alternatives to petroleum-derived SAP are gaining trial among environmentally motivated purchasers. Scandinavian home-care programs have introduced preferential reimbursement for certified bio-based products, creating regulatory tailwinds for this segment.
- Reusable:Washable briefs with moisture-wicking synthetic layers are capturing cost-conscious segments in Germany and the Netherlands.
- Premium:Enhanced breathability films and skin-conditioning topsheets target private-pay home-care purchasers.
- Standard:Basic acquisition-distribution-storage configurations serve price-sensitive bulk tenders.
Today's leader: Disposable. Tomorrow's challenger: Biodegradable.
Application:
Cost tier stratification separates clinical reimbursement-eligible applications from private-pay segments.
- Incontinence Care:Heavy and overnight absorbency products for urinary and fecal management command the deepest margins. Japan's prefectural eldercare systems bulk-purchase these tiers through municipal tender frameworks.
- Long-Term Care:Institutional procurement scales are deepening as Germany's Statutory Long-Term Care Insurance expands covered supply volumes.
- Post-Surgery Recovery:Short-duration absorbency products serve acute hospital discharge protocols.
- Mobility Impairments:Adjustable-fit designs address bedridden and wheelchair-user requirements.
- Maternal Use:Postpartum absorbency garments occupy a niche retail channel position.
Reimbursement eligibility concentrates volume in Incontinence Care, while Long-Term Care procurement consolidation is compressing supplier margins.
Absorbency Level:
Volume flows concentrate at performance tiers that match documented clinical need severity.
- Heavy:Multi-liter retention capacity through high-SAP-loading cores serves immobile residents with severe incontinence. EU MDR absorbency classification standardization is reducing buyer evaluation friction for this tier across member states.
- Overnight:Extended-wear designs with reinforced leakage barriers target eight-hour protection intervals. Japanese assisted living facilities specify these in municipal tenders to reduce nighttime change disruptions.
- Light:Low-profile designs for active users with stress incontinence.
- Moderate:Mid-tier capacity for daytime mobility-limited users.
- Maximum Protection:Specialized configurations for fecal incontinence management.
Heavy absorbency products face steepest REACH compliance cost escalation due to higher polymer loading requirements.
End User:
Customer type determines whether procurement flows through institutional tenders or retail pharmacy channels.
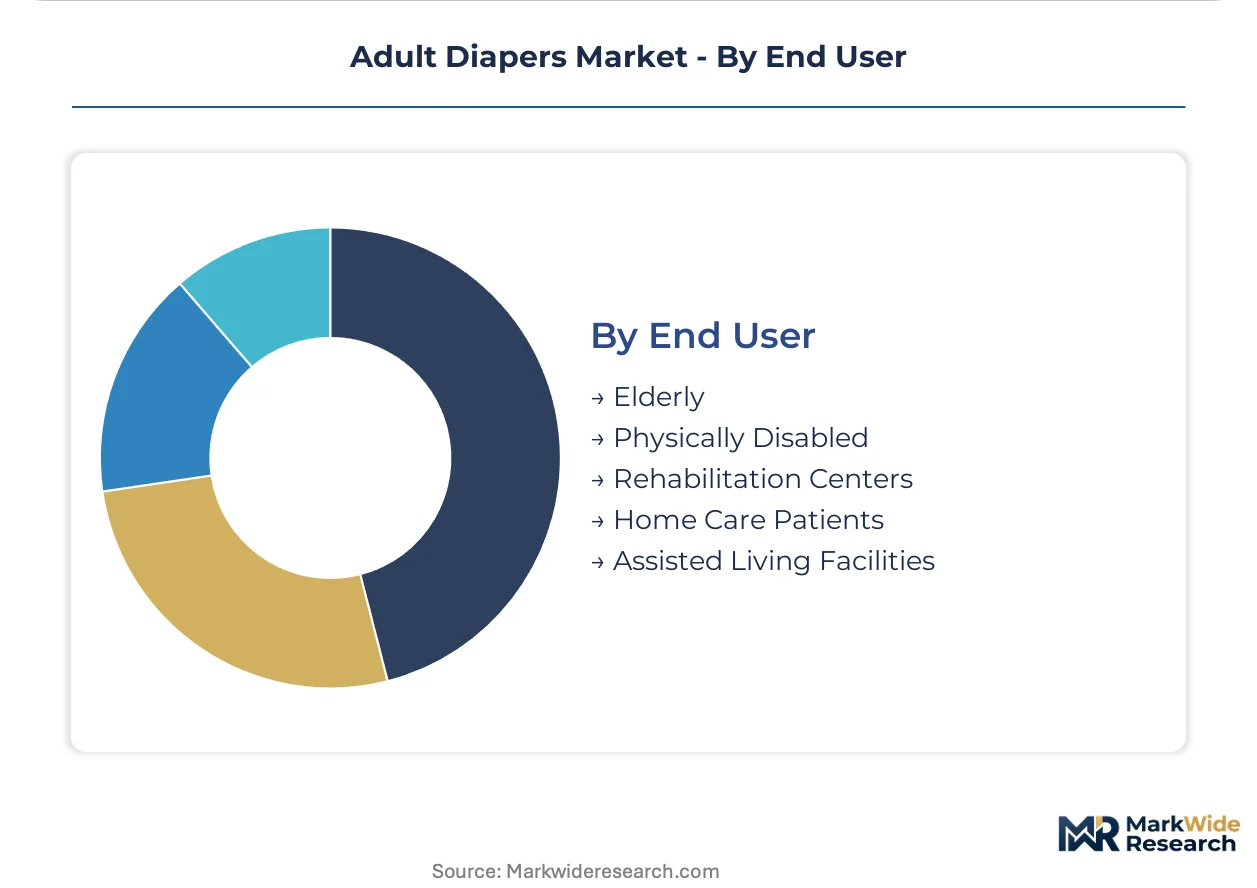
- Elderly:Age-related incontinence drives the largest addressable population, with demand concentrating in Japan's municipal eldercare systems and Germany's consolidated nursing home chains.
- Assisted Living Facilities:Purchasing cooperatives representing 200-plus facility networks negotiate multi-year supply agreements with absorbency-tier price indexing.
- Home Care Patients:Individual purchasers accessing products through retail pharmacy or direct-to-consumer channels.
- Physically Disabled:Specialized fit requirements for spinal cord injury and neuromuscular condition patients.
- Rehabilitation Centers:Transitional care settings with mixed acute and long-term supply needs.
Elderly segments anchor current volume, while Assisted Living Facilities procurement consolidation is reshaping supplier access patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer chemists and absorbent hygiene engineers concentrate in Japan's Kansai industrial corridor and Germany's Rhine-Ruhr manufacturing belt, anchoring product development capacity for institutional procurement markets.
Japan
Prefectural eldercare systems in Osaka and Hyogo bulk-purchase premium overnight absorbency tiers through municipal tender frameworks. METI's quasi-drug notification pathway for skin-contact hygiene products shapes compliance timelines for new product introductions. Kansai-based manufacturing clusters supply reinforced leakage-barrier designs to assisted living networks across western Honshu.
Germany
Consolidated nursing home chains in North Rhine-Westphalia negotiate multi-year supply agreements through purchasing cooperatives representing 200-plus facilities. Statutory Long-Term Care Insurance expansion drives covered supply volumes for severe incontinence cases. REACH documentation requirements for sodium polyacrylate formulations extend registration timelines for SAP-dependent product lines.
United States
FDA Class I medical device classification establishes baseline biocompatibility standards that shape manufacturer quality systems for hospital and nursing facility procurement. Retail pharmacy channel concentration in the Southeast and Midwest determines brand-controlled shelf space allocation. Private-pay home-care purchasers in Florida and Arizona drive demand for enhanced breathability films.
India
The National Programme for Health Care of the Elderly extends supply chain infrastructure into underpenetrated rural districts across Maharashtra and Gujarat. Central Drugs Standard Control Organization oversight of medical device imports frames entry pathways for multinational manufacturers. Domestic compounding capabilities in Tamil Nadu are scaling to meet institutional tender specifications.
Sweden
Scandinavian home-care programs have introduced preferential reimbursement for certified bio-based products, creating regulatory tailwinds for cellulose-based SAP alternatives. EU Green Deal procurement mandates in public tenders favor certified sustainable product lines. Absorbent hygiene R&D clusters in Stockholm and Gothenburg specialize in biodegradable core assembly architectures.
Adult Diapers Market Key Industry Players
The competitive structure tilts toward integrated pulp and polymer compounders with captive raw-material access. Scale players dominate institutional tender participation, while regional specialists serve price-sensitive bulk procurement. Three archetypes define positioning: vertically integrated multinationals with fluff pulp supply chains, SAP compounding specialists with in-house polymer capabilities, and brand-centric consumer goods groups controlling retail pharmacy channels. Capacity consolidation and direct-to-institution contracting represent the dominant competitive moves reshaping supplier access.
Within the integrated multinational tier, Kimberly Clark Corp. and Essity AB exemplify scale-driven positioning through upstream control over critical inputs. Procter and Gamble Co. anchors the brand-centric archetype with pharmacy channel presence. Kao Corp. and Unicharm Corp. represent Asia-Pacific-based specialists with regional tender expertise. Abena Group occupies a position serving European institutional procurement with compliance-focused product lines.
| Leading Market Players |
|---|
| First Quality Enterprises |
| Kao Corp. |
| Kimberly Clark Corp. |
| Medline Industries LP |
| Domtar Corp. |
| Essity AB |
| Procter and Gamble Co. |
| Abena Group |
| Unicharm Corp. |
| Others |
Cost & Logistics Intelligence
Municipal bulk-purchasing consolidation in Japan's prefectural eldercare systems is compressing supplier margins and forcing manufacturers to reconfigure production economics around tender-winning scale rather than brand premium extraction. This procurement concentration is transmitting cost pressure upstream into raw-material sourcing decisions and polymer compounding investments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates institutional procurement, with differentiation driven by SAP loading density and EU MDR absorbency certification tier. Price differentiation separates heavy absorbency products with full clinical documentation from economy tiers serving cost-sensitive home-care segments. Cost compression in standard tiers is intensifying because REACH chemical documentation requirements extend registration timelines and inflate compliance overhead. Municipal purchasing cooperatives in Germany exhibit the highest price sensitivity, while private-pay home-care purchasers in Japan's assisted living networks show lowest sensitivity to premium positioning.
Supply Chain Analysis
Single-source vulnerability sits with Scandinavian fluff pulp mills and Saudi Arabian petrochemical feedstocks for SAP precursor acrylate monomers. Manufacturing draws from Germany's Rhine-Ruhr compounding belt, Japan's Kansai hygiene cluster, and Tamil Nadu's emerging domestic capacity. Tariff exposure on petroleum-derived SAP imports into India complicates cost forecasting for multinational supply planners. Distribution runs through purchasing cooperatives representing consolidated nursing home networks rather than traditional wholesale-medical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-burdened European manufacturing and India's underpenetrated rural districts where regulatory compliance costs remain lower and reimbursement infrastructure is expanding.
For Market Incumbents: Lock in captive fluff pulp supply through long-term offtake agreements with Scandinavian mills before cellulose-alternative trials accelerate feedstock switching costs. Secure multi-year tender participation status in Japan's prefectural systems by pre-positioning MDR technical documentation for heavy absorbency tiers, as emerging SAP compounding specialists threaten margin stability through lower polymer sourcing costs. For New Entrants and Emerging Players: Purchasing cooperatives in Germany's consolidated nursing home chains represent the most penetrable channel archetype for regional specialists lacking global brand recognition. Target rural districts in Maharashtra and Gujarat under India's National Programme for Health Care of the Elderly where supply chain infrastructure gaps create white-space for domestic compounding capabilities. Lead with biodegradable product lines certified under EU Green Deal procurement mandates to differentiate from petroleum-dependent incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with SAP compounding specialists possessing in-house cross-linked hydrogel formulation expertise and toxicology testing infrastructure compliant with ECHA documentation requirements. Long-term viability across the analysis window favors targets with demonstrated municipal tender-winning track records in Japan or Germany rather than retail-channel-dependent brand assets. Watch for cellulose-based SAP alternative trials achieving Scandinavian home-care program reimbursement eligibility as the inflection signal for feedstock transition acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluff Pulp Supply | Kimberly Clark Corp.'s captive pulp sourcing sustains margin stability under raw-material scrutiny. |
| MDR Technical Documentation Investment | CE marking authorization for heavy absorbency tiers opens cross-border tender participation across EU member states. |
| Smart-Sensor Product Integration | Moisture-detection wearables enable predictive change protocols in Japanese assisted living facilities. |
| Biodegradable Core Assembly Development | Cellulose-based SAP alternatives unlock preferential reimbursement in Scandinavian home-care programs. |
| Direct-to-Institution Contracting | Multi-year supply agreements with German purchasing cooperatives displace distributor-mediated procurement. |
Research Approach
Coverage spans Japan, Germany, the United States, India, and Sweden, with primary inputs from each market's institutional procurement decision-makers. The research combines structured interviews with long-term care facility purchasing directors, SAP compounding plant managers, and ECHA regulatory compliance officers with secondary validation from EU MDR technical documentation databases, Japanese municipal tender award records, and German Statutory Long-Term Care Insurance reimbursement schedules. Bottom-up volume estimates from facility-level procurement data triangulate against top-down market sizing from customs trade records and pulp mill production disclosures.
Rate-of-change decomposition separates volume growth from pricing dynamics across the modeling period. The analytical framework segments by product type (disposable, biodegradable, reusable), application (incontinence care, long-term care, post-surgery recovery), absorbency level (heavy, overnight, light, moderate, maximum protection), and end user (elderly, assisted living facilities, home care patients). CAGRs derive from regression analysis against demographic aging trajectories and reimbursement expansion schedules. Forecast inputs include polymer chemistry specialization scarcity indices and REACH registration timeline distributions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petroleum feedstock volatility, cellulose-SAP substitution rates, and municipal procurement authority consolidation trajectories. The analytical envelope assumes continued statutory insurance expansion in Germany and sustained prefectural tender consolidation in Japan. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
China Pant Type Adult Diaper Market
Baby Diapers
Baby Cloth Diaper Market
Baby Diapers
Baby Diaper Manufacturing Machine Market
Baby Diapers
Nonwoven Baby Diaper Market
Baby Diapers
Baby Training Diaper Market
Baby Diapers
Baby Diapers Market
Baby Diapers
GCC Diaper Market
Baby Diapers
Disposable Hygiene Products Market
Baby Diapers
Pet Diapers Market
Baby Diapers
Smart Connected Diaper Market
Baby Diapers
United States Diaper Market
Baby Diapers
East Africa Baby Diaper Market
Baby Diapers
Dog Diapers Market
Baby Diapers
Cat Diapers Market
Baby Diapers
Global Baby Swim Pants Diaper Market
Baby Diapers
Reusable Baby Diapers and Training Pants Market