
 Pet Diapers Market | 2026-2036
Pet Diapers Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Diapers Market Analytics
China's manufacturing expansion is reconfiguring supply dynamics for absorbent pet hygiene products. The Hartz Mountain leverages vertical integration across raw material sourcing and finished goods to sustain cost advantages in mass-market channels. Petco Animal Supplies anchors its position through veterinary clinic partnerships and subscription-based replenishment programs. OUT! Petcare differentiates via specialized sizing systems for large-breed canines, occupying a premium tier with limited direct competition.
Pet diapers are absorbent garments engineered with superabsorbent polymer cores, breathable outer layers, and elasticized leg gathers to contain excretions from incontinent, estrous, or untrained companion animals. Manufacturing employs thermal bonding and ultrasonic sealing to achieve leak-proof construction without irritating skin contact. The disposable segment leads volume due to convenience-driven purchasing among urban pet owners, while the biodegradable material category captures expanding margin pools as sustainability premiums justify higher unit economics. Veterinarians represent the fastest-growing end-user channel as clinical recommendations normalize diaper use for post-surgical recovery and geriatric care protocols.
The US FDA regulates pet product safety claims under the Federal Food, Drug, and Cosmetic Act, while the EPA oversees disposal pathways for synthetic absorbent materials. The EU REACH framework restricts certain chemical treatments in textiles contacting animal skin, compelling reformulation of conventional plastic-backed designs. Stakeholders must monitor evolving state-level extended producer responsibility legislation and decide whether to front-run compliance costs or risk channel exclusion in jurisdictions with advancing packaging mandates.
Market Dynamics
The EU's Single-Use Plastics Directive is forcing material transitions across absorbent pet hygiene supply chains, compelling manufacturers to abandon conventional plastic-backed designs and absorb reformulation costs ahead of enforcement deadlines.
Growth Catalysts
- Veterinary channel expansion:Clinical protocols for post-surgical recovery and geriatric incontinence management are normalizing diaper recommendations, with veterinary clinics emerging as the fastest-growing end-user segment.
- REACH chemical restrictions:The EU framework's limitations on skin-contact textile treatments are accelerating development of hypoallergenic alternatives that command sustainability premiums.
- Urban pet ownership density:Apartment-dwelling companion animal populations in metropolitan United States clusters sustain convenience-driven purchasing for disposable solutions.
Market Restraints
- Superabsorbent polymer cost volatility:Petroleum-derived SAP core materials expose margins to crude price swings and petrochemical supply tightness.
- China manufacturing concentration:Absorbent product fabrication clusters in coastal provinces create geographic supply risk and logistics vulnerability.
- Composting infrastructure gaps:Biodegradable diaper disposal requires municipal organic waste streams that remain underdeveloped across most United States jurisdictions.
Strategic Opportunities
- Extended producer responsibility tailwinds:Advancing state-level packaging mandates in California and New York create first-mover advantages for circular-design compliance.
- Large-breed sizing white space:Specialized garment engineering for canine breeds exceeding 50 pounds remains underserved relative to standard companion animal dimensions.
- Subscription replenishment channels:Direct-to-consumer auto-ship models bypass retail slotting fees and capture recurring revenue with predictable demand signals.
Industry Challenges
- Biodegradable certification timelines:ASTM D6400 and EN 13432 industrial composting standards require 12-18 month validation cycles that delay product launches.
- Thermal bonding equipment capex:Ultrasonic sealing machinery for leak-proof construction demands seven-figure capital commitments that strain mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Diapers Market |
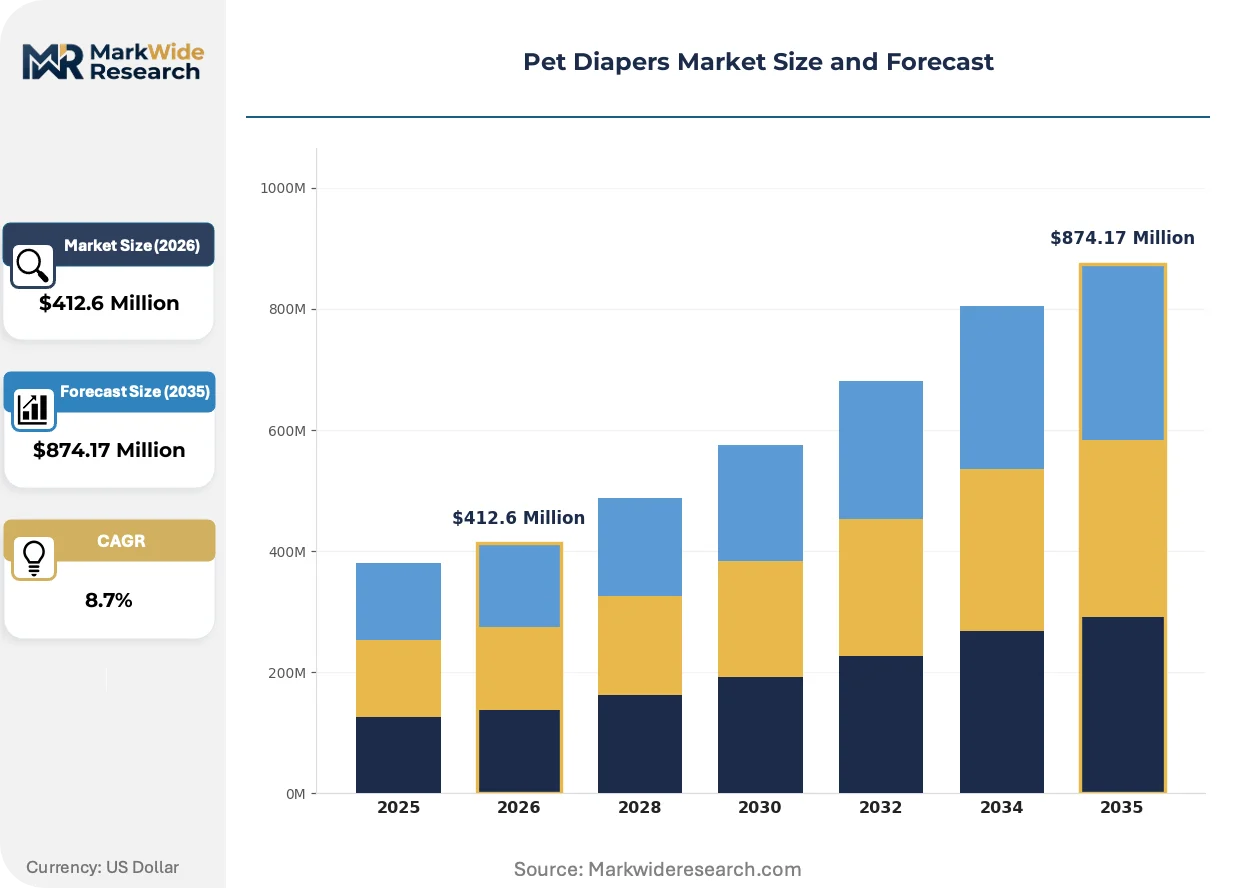
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Washable, Eco-friendly, Training End User: Pet Owners, Veterinarians, Pet Care Facilities, Shelters Size: Small, Medium, Large, Extra Large Material: Plastic, Cotton, Microfiber, Biodegradable |
| Companies Covered | Petco Animal Supplies, The Hartz Mountain, The Bramton Company, HoneycarePet, Wegreeco, Pet Parents, Four Paws, OUT! Petcare, U-PLAY USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Diapers Market Evolving Landscape
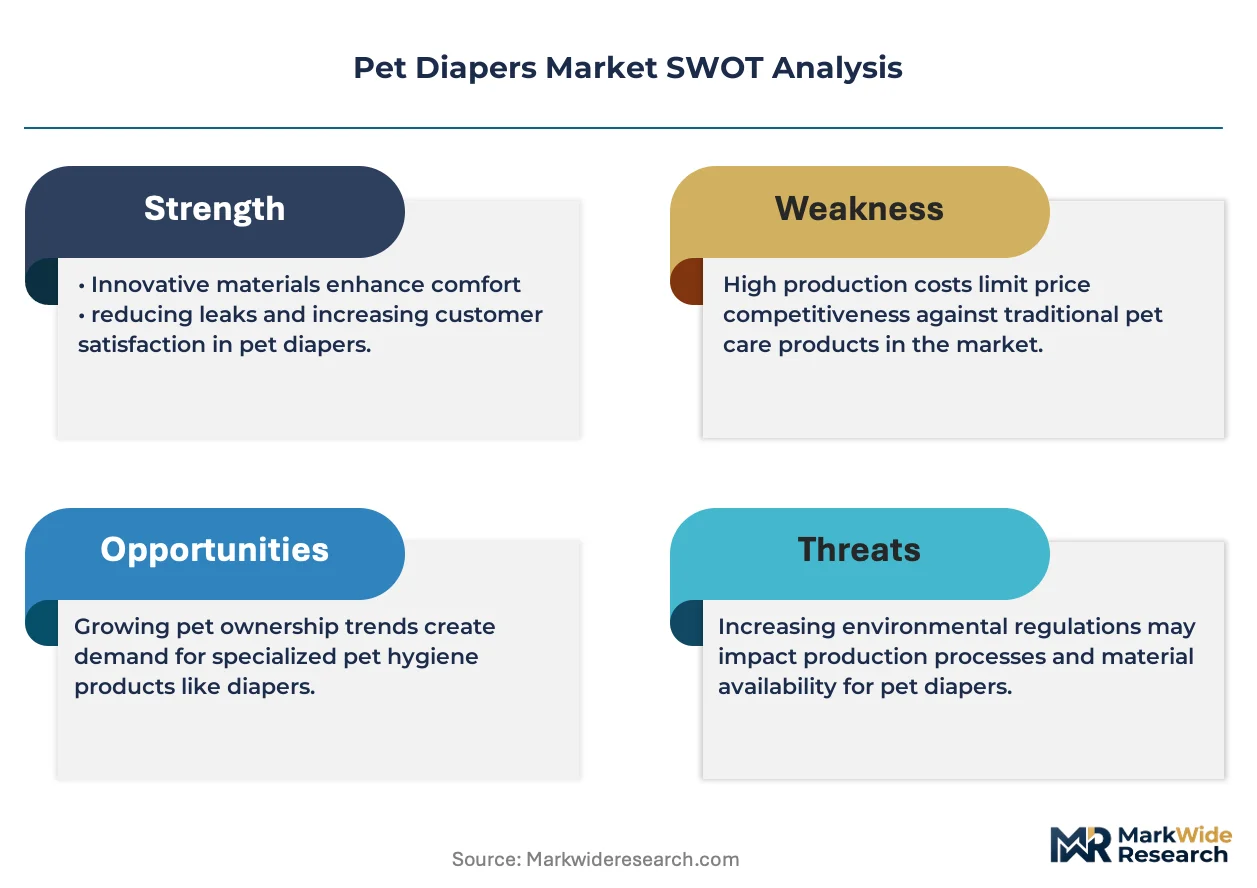
Material science breakthroughs and regulatory compression are restructuring competitive advantage in pet hygiene, rewarding suppliers who integrate biodegradable performance with manufacturing scale.
Plant-derived superabsorbent polymers derived from cornstarch and cellulose feedstocks are collapsing the performance gap between petroleum-based and bio-based absorbent cores. Premium pet care brands in the United States and Germany are adopting these materials at pilot scale ahead of EU mandate deadlines. The technology is collapsing conventional plastic-backed architectures into obsolescence within sustainability-positioned product tiers.
REACH Annex XVII restrictions on phthalates and heavy metals in textiles contacting animal skin are compelling reformulation of conventional diaper laminates. Manufacturers serving EU distribution channels must certify alternative adhesive and waterproofing chemistries by enforcement dates. The biodegradable material segment absorbs disproportionate compliance investment as synthetic alternatives face channel exclusion.
Veterinary clinic procurement coalitions are consolidating purchasing decisions through group purchasing organizations and preferred supplier agreements. Independent clinics surrender sourcing autonomy to veterinary service networks that negotiate volume terms with contracted manufacturers. This concentration is most advanced in United States metropolitan veterinary practice aggregations.
Pet Diapers Market Segmentation
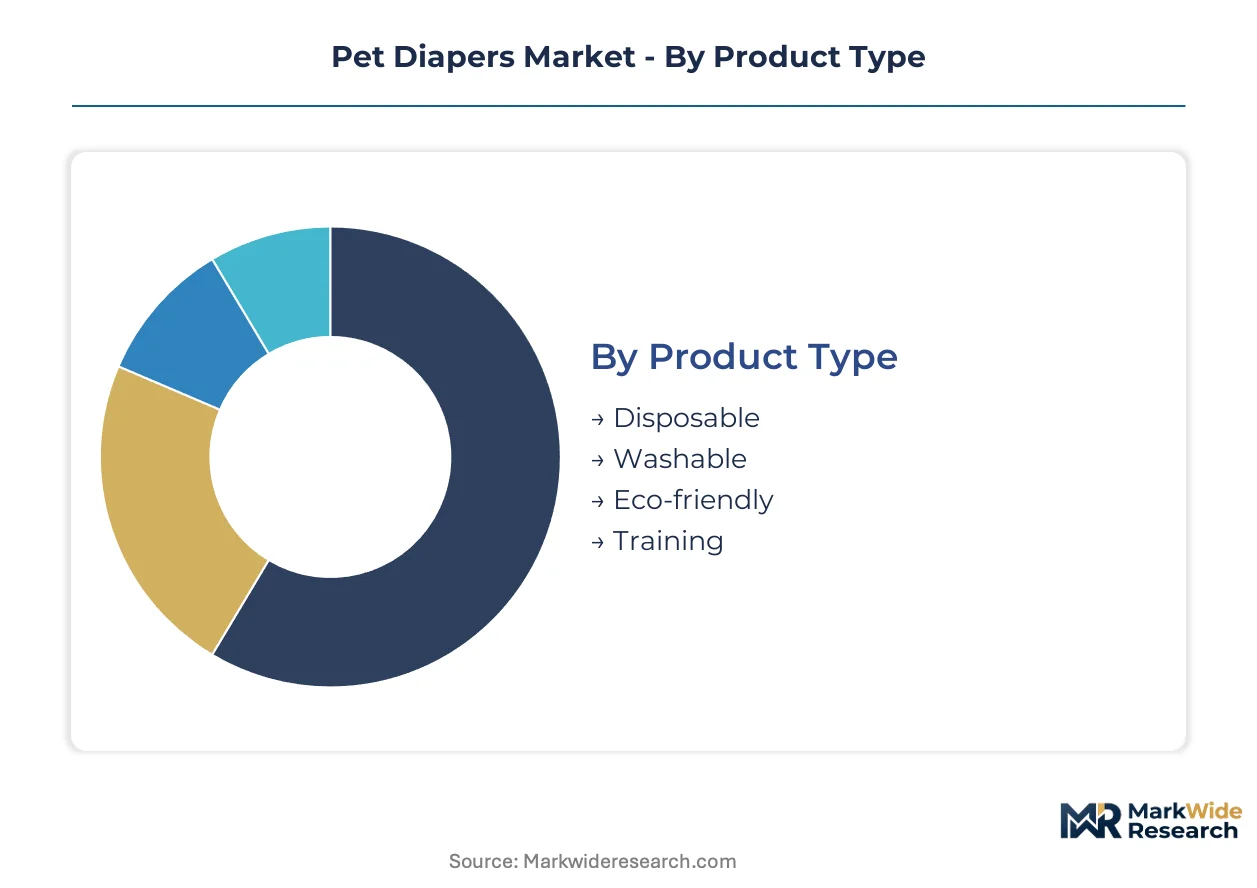
Pet diaper segmentation reveals distinct turnover velocities across product lifecycles, with disposable formats cycling rapidly through household pantries while durable alternatives extend replacement intervals. Understanding these velocity differentials shapes inventory planning, margin capture, and channel positioning strategies for manufacturers and retailers alike.
Product Type:
Cycle times vary dramatically across formats, with single-use products turning over weekly versus multi-year lifespans for reusable alternatives.
- Disposable:Superabsorbent polymer cores bonded to breathable nonwoven topsheets deliver maximum convenience for urban pet owners managing high-frequency changes. Demand concentrates in United States metropolitan clusters where apartment-dwelling dog populations prioritize hygiene convenience over lifecycle cost. The segment absorbs the steepest volume growth as veterinary clinics normalize post-surgical diaper protocols.
- Eco-friendly:Plant-derived absorbent matrices from cornstarch and cellulose feedstocks achieve industrial composting certification under ASTM D6400 and EN 13432 standards. German and California markets drive adoption ahead of EU Single-Use Plastics Directive enforcement deadlines, with sustainability premiums justifying unit economics that exceed conventional plastic-backed alternatives by meaningful margins.
- Washable:Multi-layer cotton or microfiber constructions with waterproof PUL laminates support 200+ wash cycles for cost-conscious households. Penetration remains highest in suburban United States markets with in-home laundry facilities and larger-breed ownership profiles.
- Training:Adjustable waist systems and moisture-wicking liners accelerate housebreaking for puppies and rescue animals. Pet specialty retailers in Japan and South Korea merchandise these alongside behavioral training services.
Disposable formats anchor the volume base while eco-friendly alternatives gain share at the steepest rate.
End User:
Procurement authority concentrates differently across customer types, with individual households driving fragmentation while institutional buyers consolidate purchasing power.
- Veterinarians:Clinical recommendations for post-operative recovery and geriatric incontinence management are normalizing diaper prescriptions as standard care protocols. United States veterinary service networks negotiate preferred supplier agreements through group purchasing organizations, concentrating procurement decisions that independent clinics previously controlled.
- Pet Owners:Direct purchasing through mass-market retail, specialty pet chains, and subscription auto-ship programs sustains the largest addressable base. Convenience-oriented urban households in New York, Los Angeles, and Chicago generate disproportionate per-capita consumption.
- Pet Care Facilities:Boarding kennels and daycare operations require high-volume disposable solutions for multi-animal environments. These buyers prioritize bulk pricing and consistent supply reliability over product differentiation.
- Shelters:Nonprofit and municipal adoption centers represent price-sensitive demand with irregular funding cycles, often relying on donated or discounted inventory from manufacturers seeking brand exposure.
Individual pet owners generate the revenue base while veterinary channels expand most aggressively.
Size:
Manufacturing complexity escalates with garment dimensions, as larger formats demand reinforced elastic systems and higher superabsorbent polymer loading.
- Large:Engineered for canine breeds between 35-65 pounds, these garments require enhanced leg gather construction and extended core coverage. United States ownership of Labrador Retrievers, German Shepherds, and Golden Retrievers sustains concentrated demand.
- Extra Large:Specialized patterns for breeds exceeding 65 pounds remain technically challenging due to fit variability across body conformations. OUT! Petcare and select premium specialists occupy this underserved white space with limited direct competition.
- Small:Compact designs for toy breeds and cats utilize reduced polymer loading with equivalent absorbency efficiency. Japanese and South Korean markets show elevated penetration given smaller average pet sizes.
- Medium:Standardized patterns targeting 15-35 pound animals serve the broadest breed diversity, supporting economy-tier manufacturing scale.
Medium sizes dominate unit volume while extra-large formats command the highest per-unit margins.
Material:
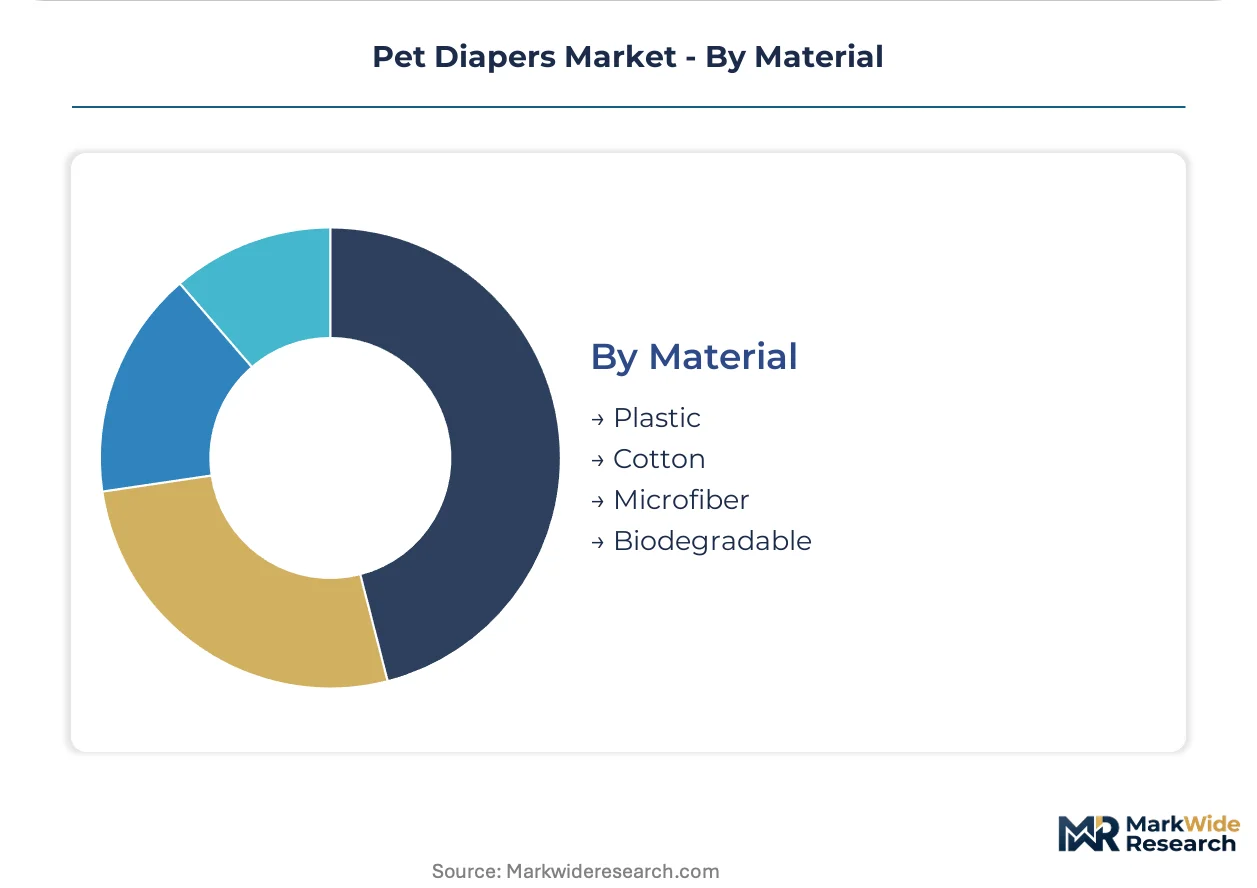
Regulatory pressure on skin-contact textiles is forcing rapid substitution away from petroleum-derived laminates toward certified biodegradable alternatives.
- Biodegradable:Cornstarch-based superabsorbent polymers and cellulose-derived waterproofing layers achieve compostability certification without performance degradation. EU REACH Annex XVII restrictions on phthalates and heavy metals accelerate adoption as synthetic alternatives face channel exclusion.
- Plastic:Conventional polyethylene backings and polypropylene nonwovens retain cost advantages in mass-market channels but confront regulatory headwinds from California extended producer responsibility legislation and EU directive timelines.
- Cotton:Natural fiber topsheets and absorbent batting serve washable product lines and premium disposable tiers targeting skin-sensitive animals. Organic certification commands additional price premiums in German and Nordic markets.
- Microfiber:Synthetic polyester blends deliver rapid moisture wicking for training and light-incontinence applications, though petroleum sourcing exposes margins to feedstock volatility.
Plastic-based materials retain volume leadership while biodegradable alternatives capture the most rapid share expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with United States households prioritizing convenience-driven disposable formats while German buyers absorb sustainability premiums for certified biodegradable alternatives.
United States
Urban pet ownership density in New York, Los Angeles, and Chicago sustains the highest per-capita consumption of disposable solutions. The FDA regulates product safety claims under the Federal Food, Drug, and Cosmetic Act, while California's advancing extended producer responsibility legislation pressures material transitions. Veterinary service networks in metropolitan clusters negotiate preferred supplier agreements through group purchasing organizations.
Germany
Sustainability-conscious households in Berlin, Munich, and Hamburg drive adoption of compostable formats ahead of EU mandate deadlines. The ECHA REACH framework restricts phthalates and heavy metals in skin-contact textiles, compelling reformulation of conventional laminates. Manufacturing clusters in North Rhine-Westphalia pilot plant-derived superabsorbent polymer production at industrial scale.
China
Coastal manufacturing provinces dominate absorbent product fabrication, with Zhejiang and Guangdong housing thermal bonding and ultrasonic sealing equipment clusters. The MIIT oversees industrial standards for pet product exports, while SAMR monitors domestic market compliance. Yangtze River Delta facilities supply mass-market channels across Southeast Asian export markets.
Japan
Smaller average pet sizes in Tokyo, Osaka, and Nagoya elevate penetration of compact garment formats. METI promotes circular economy transitions through packaging reduction guidelines affecting disposable product design. Kanto region specialty retailers merchandise training diapers alongside behavioral services for puppy housebreaking.
United Kingdom
London and Southeast England concentrate premium pet care spending, with subscription auto-ship models gaining traction among time-constrained professionals. The UK's post-EU regulatory framework maintains REACH-aligned chemical restrictions through retained EU law. Midlands-based distribution hubs serve veterinary clinic procurement coalitions consolidating purchasing decisions.
Pet Diapers Market Competitive Landscape
Capability concentration sits with specialized sizing engineers; scale advantage sits with mass-market distributors with veterinary channel access. The vendor base separates into three tiers: multinational pet care conglomerates with retail shelf dominance, mid-tier specialists with veterinary network relationships, and regional fabricators serving price-sensitive bulk buyers. Competitive moves center on subscription platform deployment and biodegradable certification acceleration ahead of regulatory deadlines.
Among United States-based distributors, Petco Animal Supplies anchors the veterinary partnership tier, while The Hartz Mountain exemplifies backward integration into raw material sourcing. OUT! Petcare occupies a position within the specialized sizing segment for large-breed applications. These three entities represent distinct strategic archetypes: channel control through clinic networks, upstream cost management, and premium-tier white-space exploitation respectively.
| Leading Market Players |
|---|
| Petco Animal Supplies |
| The Hartz Mountain |
| The Bramton Company |
| HoneycarePet |
| Wegreeco |
| Pet Parents |
| Four Paws |
| OUT! Petcare |
| U-PLAY USA |
| Others |
Value Network & Pricing Analysis
Trans-Pacific container freight corridors from Shanghai to Long Beach transmit volatile bunker fuel surcharges into landed costs for superabsorbent polymer cores, compressing margins for distributors lacking long-term carrier contracts while amplifying price spreads between mass-market and veterinary-tier product lines.
Pricing Analysis
United States retail shelves show wider price dispersion than German equivalents, where REACH compliance costs compress the premium tier. Three-tier pricing structure across premium, standard, and economy levels prevails, with certification grade and volume scale as primary differentiation drivers. Cost compression in the economy tier is intensifying because of petroleum-derived SAP feedstock volatility. Pet care facilities demonstrate highest price sensitivity, while veterinary clinics absorb premiums for clinically validated formats.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for raw material procurement in Zhejiang manufacturing clusters, straining working capital for mid-tier fabricators. Supply concentrates in China, with secondary fabrication nodes in Vietnam and India for cotton-based washable alternatives. Superabsorbent polymer cores, breathable nonwoven topsheets, and elastic leg gather components feed from petrochemical and textile feedstocks. Single-source vulnerability around ultrasonic sealing equipment creates chokepoint exposure. Distribution runs through veterinary service networks, mass-market retail chains, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pet diapers market is emerging from a cyclical trough driven by veterinary protocol normalization, creating selective expansion opportunities for positioned players.
For Market Incumbents: Build certification moats around ASTM D6400 and EN 13432 compostability standards ahead of EU enforcement deadlines. Secure preferred supplier status with consolidating veterinary service networks through group purchasing organization contracting. Invest in captive supply of plant-derived superabsorbent polymers to offset petroleum feedstock volatility threatening margin stability. For New Entrants and Emerging Players: Southeast Asian veterinary channels show underpenetration relative to United States and German benchmarks, offering expansion corridors with lower competitive density. Target extra-large breed sizing white space where technical complexity has limited incumbent response. Deploy direct-to-consumer subscription auto-ship models to bypass retail slotting fee barriers and establish recurring revenue foundations. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pet care conglomerates seeking to divest non-core hygiene assets amid portfolio rebalancing toward pharmaceutical and nutrition verticals. Five-to-ten year viability hinges on biodegradable material transition execution rather than conventional plastic-backed legacy positioning. Monitor state-level extended producer responsibility legislative advancement in California and New York as inflection signals for compliance investment urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Certification Acceleration | ASTM D6400 validation secures channel access in California and EU markets ahead of mandate deadlines. |
| Veterinary Network Partnership Expansion | Group purchasing organization contracts with United States metropolitan clinic aggregations lock in recurring volume commitments. |
| Plant-Derived SAP Supply Integration | Cornstarch and cellulose feedstock sourcing from North Rhine-Westphalia pilots reduces petrochemical cost exposure. |
| Subscription Platform Deployment | Auto-ship replenishment models bypass Petco and mass-market slotting fees while capturing predictable demand signals. |
| Large-Breed Sizing Engineering Investment | Specialized patterns for canines exceeding 65 pounds exploit underserved white space with limited direct competition. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA enforcement records, EPA disposal pathway documentation, EU REACH Annex XVII restriction updates, and veterinary clinic procurement database filings. Primary interviews engaged product development directors at absorbent hygiene manufacturers, veterinary service network procurement leads, retail category buyers at specialty pet chains, and regulatory affairs specialists navigating state-level extended producer responsibility legislation. Secondary validation drew from customs trade data, SEC 10-K disclosures, and ECHA substance restriction timelines. Bottom-up demand modeling triangulated against top-down market sizing across product format, end-user channel, and material certification segments.
Forecast inputs encompass superabsorbent polymer feedstock price indices, veterinary clinic consolidation rates, EU Single-Use Plastics Directive enforcement phasing, and municipal composting infrastructure deployment across United States jurisdictions. The analytical framework segments by disposable versus washable versus biodegradable product type, veterinarians versus pet owners versus institutional facilities as end users, and plastic versus plant-derived versus cotton material categories. CAGRs derive from regression analysis of historical volume trajectories against projected regulatory compression and channel shift dynamics. Veterinary protocol normalization and extended producer responsibility legislative advancement serve as primary demand and supply-side modeling variables.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private-label entrants or cross-category hygiene conglomerates would shift outcomes. Macroeconomic contraction in pet care discretionary spending, accelerated EU chemical restriction timelines, or breakthroughs in reusable garment absorbency technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
Africa and India Baby Diapers Market
Baby Diapers
Cat Diapers Market
Baby Diapers
United States Adult Diaper Market
Baby Diapers
Dog Diapers Market
Baby Diapers
Baby Disposable Diapers Market
Baby Diapers
Malaysia Diapers Market
Baby Diapers
Global Baby Swim Pants Diaper Market
Baby Diapers
UAE Baby Diapers Industry Market
Baby Diapers
Smart Diaper Market
Baby Diapers
Reusable Baby Diapers and Training Pants Market
Baby Diapers
Adult Diapers Market
Baby Diapers
Smart Connected Diaper Market
Baby Diapers
Australia Pant Type Adult Diaper Market
Baby Diapers
Middle East and Africa and Asia Pacific Baby Diaper Market
Baby Diapers
Biodegradable Diapers Market
Baby Diapers
Disposable Hygiene Products Market