
 Nonwoven Baby Diaper Market | 2026-2036
Nonwoven Baby Diaper Market Size, Share, and Industry Trends Forecast 2026-2036
Nonwoven Baby Diaper Market Intelligence
Asset-light contract manufacturing and third-party tolling arrangements is narrowing the capital barrier for mid-tier entrants challenging legacy producers. Procter & Gamble leverages its captive pulp supply chains and North American mill network to sustain cost advantages at scale. Kimberly-Clark anchors its position through hospital and maternity-ward sampling programs that lock in brand preference from birth. Unicharm competes aggressively in Southeast Asian pharmacy channels where it controls shelf placement through direct distributor relationships.
Nonwoven baby diapers are disposable hygiene products constructed from spunbond-meltblown-spunbond laminates, superabsorbent polymer cores, and elasticized leg cuffs designed to capture liquid waste while maintaining skin breathability through 800-1,500 g/m²/24hr moisture vapor transmission rates. Ultra-absorbent formulations dominate volume shipments but carry thinning margins as polymer costs fluctuate, while eco-friendly segments built on biodegradable fibers attract premium positioning in European pharmacy and online retail channels where consumers trade up for compostability certifications. Breathable backsheet technologies using microporous polyethylene films lead R&D allocation among Japanese and Korean manufacturers seeking humidity reduction and dermatitis prevention.
FDA biocompatibility standards for infant contact materials, EU REACH restrictions on formaldehyde-releasing preservatives, and China's GB/T 28004 national hygiene standard collectively elevate testing burdens and exclude uncertified regional suppliers from supermarket and hospital procurement channels. The EU Green Deal's packaging waste directives are accelerating shifts to bio-based polypropylene and wood pulp substitution that reshape raw material sourcing geography. Stakeholders must monitor how divergent chemical disclosure regimes between the EU, China, and the US fragment formulation strategies and complicate centralized manufacturing footprints.
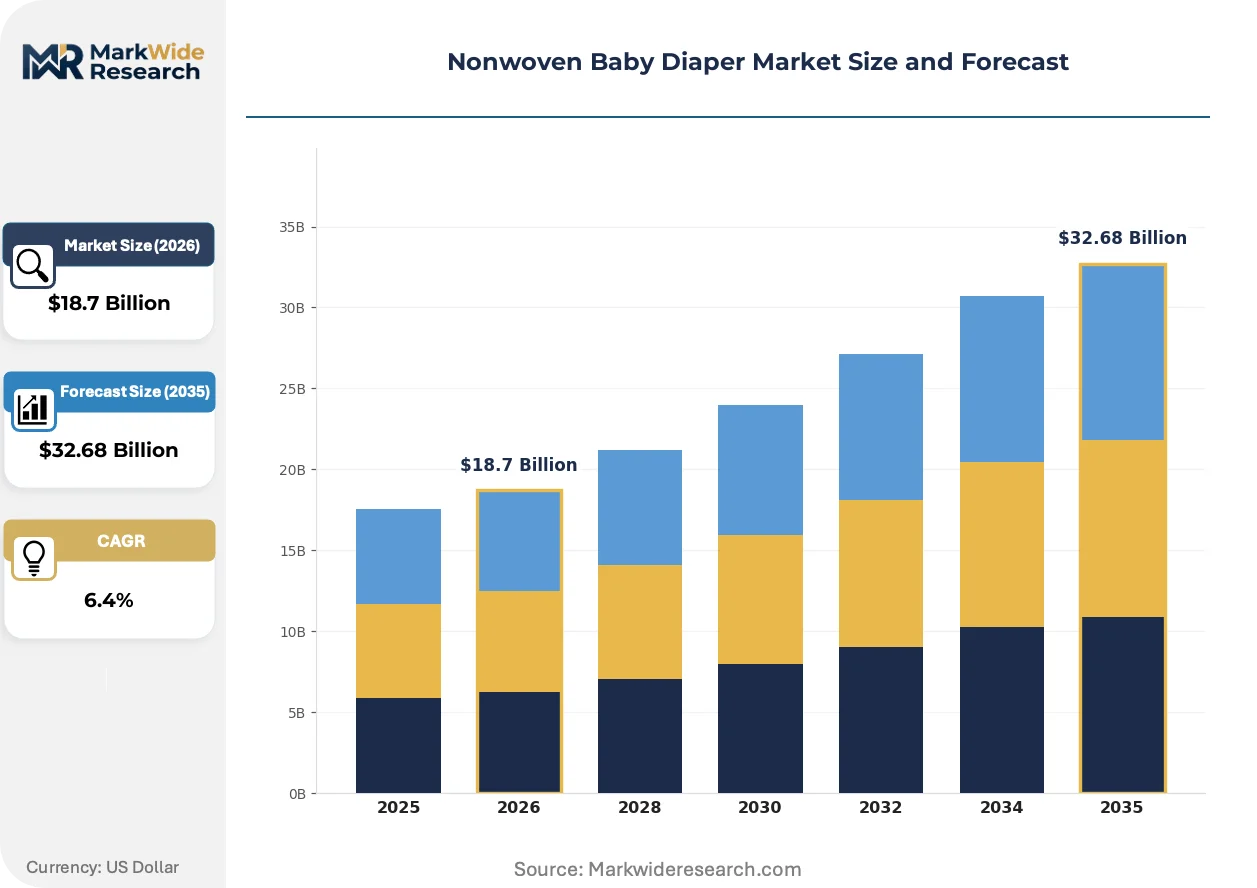
Market Dynamics
EU REACH chemical restrictions and the EU Green Deal's packaging waste directives are forcing raw material substitutions that fragment formulation strategies and complicate centralized manufacturing footprints across absorbent hygiene supply chains.
Growth Catalysts
- Urban Household Expansion:Parents of newborns and toddlers in dense metropolitan areas across China, India, and Brazil represent accelerating demand concentration as birth rates flatten in mature economies.
- REACH Compliance Migration:European chemical disclosure mandates on formaldehyde-releasing preservatives push certified suppliers into supermarket and hospital procurement channels that exclude uncertified regional competitors.
- Biodegradable Fiber Adoption:Plant-based absorbent cores and compostable backsheet films attract premium positioning in pharmacy and online retail channels where certification-driven trade-up behavior concentrates.
Market Restraints
- Polymer Cost Volatility:Superabsorbent polymer price swings compress margins on ultra-absorbent formulations that still dominate volume shipments despite thinning profitability.
- Testing Burden Escalation:FDA biocompatibility standards for infant contact materials, layered atop divergent chemical disclosure regimes between the EU, China, and the US, elevate compliance costs that exclude smaller regional suppliers.
- Pulp Supply Concentration:Captive pulp supply chains controlled by integrated North American producers create input access barriers for mid-tier entrants lacking backward integration into wood pulp sourcing.
Strategic Opportunities
- Pharmacy Channel Control:Direct distributor relationships in Southeast Asian markets enable shelf placement dominance that locks in brand preference from maternity-ward sampling through toddler transitions.
- Hospital Sampling Lock-In:Institutional procurement relationships at birth create switching costs that extend brand loyalty across the full diaper-wearing lifecycle.
- Asset-Light Manufacturing:Third-party tolling arrangements and contract manufacturing narrow capital barriers for challengers seeking to displace legacy producers without mill network investments.
Industry Challenges
- Multi-Jurisdiction Formulation Complexity:Divergent chemical disclosure regimes between the EU, China, and the US force product line fragmentation that complicates centralized production and inventory management.
- Microporous Film R&D Allocation:Japanese and Korean manufacturers dominate breathable backsheet technology development, creating capability gaps for competitors lacking humidity reduction and dermatitis prevention expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonwoven Baby Diaper Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultra-Absorbent, Breathable, Eco-Friendly, Hypoallergenic Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Pharmacies Material: Polypropylene, Polyethylene, Biodegradable Fibers, Wood Pulp Age Group: Infants, Toddlers, Newborns, Others |
| Companies Covered | Essity, Johnson & Johnson, Procter & Gamble, First Quality Enterprises, Drylock Technologies, Kimberly-Clark, Kao, Ontex, Unicharm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonwoven Baby Diaper Market Strategic Shifts & Innovations
Absorbent core engineering and backsheet breathability technologies are converging with bio-based material substitutions that reshape competitive positioning around sustainability credentials and infant skin health outcomes.
Spunbond-meltblown-spunbond laminate construction is hybridizing with biodegradable fiber integration to maintain structural integrity while meeting compostability certifications demanded by European pharmacy and premium online retail segments. German and French buyers prioritize moisture vapor transmission rates of 800-1,500 g/m²/24hr alongside biodegradability metrics. This hybridization compresses the performance gap between conventional petroleum-based laminates and emerging plant-derived alternatives.
EU Green Deal packaging waste directives are accelerating bio-based polypropylene adoption and wood pulp substitution mandates that reshape raw material sourcing geography toward Nordic and Baltic pulp suppliers. ECHA enforcement of REACH restrictions on preservative systems forces reformulation timelines that disadvantage suppliers lacking European testing infrastructure. Hospital and maternity-ward procurement channels in Germany, France, and the Netherlands now require dual certification under both REACH and GB/T 28004 equivalency standards.
Urban household buyers in São Paulo, Shanghai, and Mumbai are consolidating purchases through subscription-based direct-to-consumer channels that displace traditional supermarket stock-up behavior. Pharmacy chains in Southeast Asia respond with private-label biodegradable offerings that match premium brand performance claims at standard-tier price points. This channel migration concentrates demand visibility with platforms that capture consumption data for predictive replenishment algorithms.
Nonwoven Baby Diaper Market Segmentation
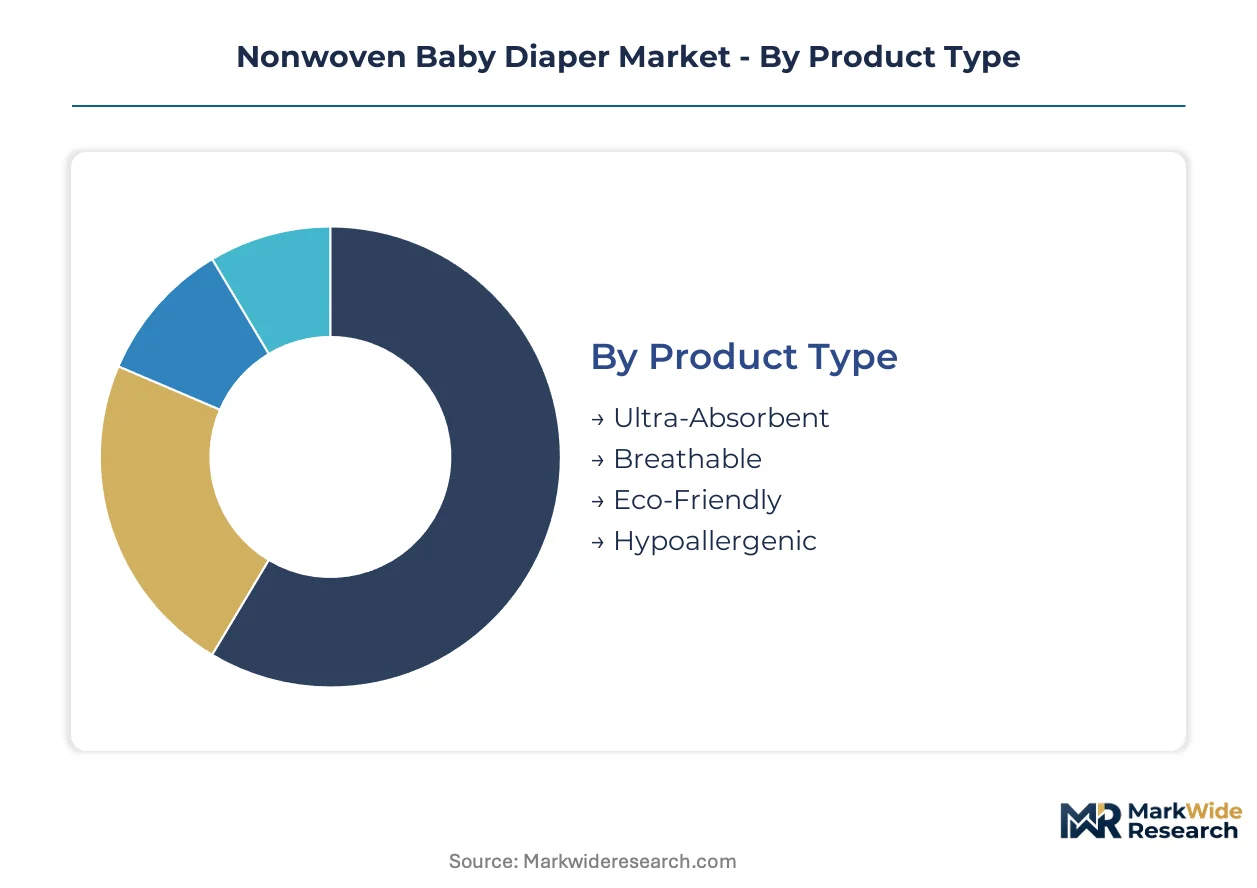
Diaper manufacturers navigate four distinct segmentation axes that determine formulation priorities, channel investments, and margin architecture. Product type and material choices drive R&D allocation and regulatory compliance burdens, while distribution channel and age group segmentation shape customer acquisition costs and lifetime value calculations.
Product Type:
Ultra-absorbent formulations turn inventory fastest through mass retail channels, while eco-friendly variants sit longer on pharmacy shelves awaiting certification-conscious buyers.
- Ultra-Absorbent:These diapers employ superabsorbent polymer cores capable of retaining multiple wettings while maintaining structural integrity. Demand concentrates in São Paulo and Mumbai supermarkets where price-sensitive urban households prioritize leakage prevention over sustainability credentials. Polymer cost volatility compresses margins despite volume dominance.
- Eco-Friendly:Plant-based absorbent cores and compostable backsheet films target European pharmacy channels and premium online retail segments. German and French buyers trade up for biodegradability certifications that satisfy EU Green Deal packaging waste directives, creating margin premiums that offset slower inventory turns.
- Breathable:Microporous polyethylene films deliver 800-1,500 g/m²/24hr moisture vapor transmission rates for dermatitis prevention. Japanese and Korean manufacturers lead this technology segment.
- Hypoallergenic:Formaldehyde-free formulations comply with EU REACH restrictions and FDA biocompatibility standards for infant contact materials. Hospital procurement channels in the Netherlands and France require this specification.
Ultra-absorbent dominates installed base. Eco-friendly is where expansion concentrates.
Distribution Channel:
Channel selection correlates directly with customer lifetime value capture, from subscription-driven online platforms to institutional lock-in through hospital sampling programs.
- Online Retail:Direct-to-consumer platforms in Shanghai and Mumbai deploy predictive replenishment algorithms based on consumption data capture. Subscription models displace traditional supermarket stock-up behavior among urban households with predictable usage patterns.
- Supermarkets:Mass retail channels in Brazil and India move ultra-absorbent volume at thin margins, requiring scale efficiencies to offset polymer cost volatility.
- Pharmacies:Southeast Asian pharmacy chains leverage private-label biodegradable offerings that match premium brand performance claims. Unicharm controls shelf placement through direct distributor relationships in these channels.
- Convenience Stores:Emergency purchase occasions capture travelers and secondary household shoppers with limited brand loyalty and minimal cross-selling potential.
Supermarkets anchor volume throughput. Online retail is climbing the fastest as subscription penetration deepens.
Material:
Raw material geography is fragmenting as EU Green Deal mandates force substitution away from petroleum-based feedstocks toward Nordic and Baltic pulp suppliers.
- Polypropylene:Spunbond-meltblown-spunbond laminates provide structural integrity and cost efficiency for mass-market production. Bio-based polypropylene adoption is accelerating under EU packaging waste directives.
- Wood Pulp:Captive pulp supply chains controlled by integrated North American producers create input access barriers for mid-tier entrants lacking backward integration.
- Biodegradable Fibers:Wood pulp substitution and plant-based alternatives reshape sourcing geography toward certified sustainable forestry operations in Scandinavia.
- Polyethylene:Microporous films for breathable backsheet applications face regulatory pressure under REACH chemical disclosure regimes.
Polypropylene and polyethylene dominate current production. Biodegradable fibers represent the steepest expansion trajectory as certification requirements tighten.
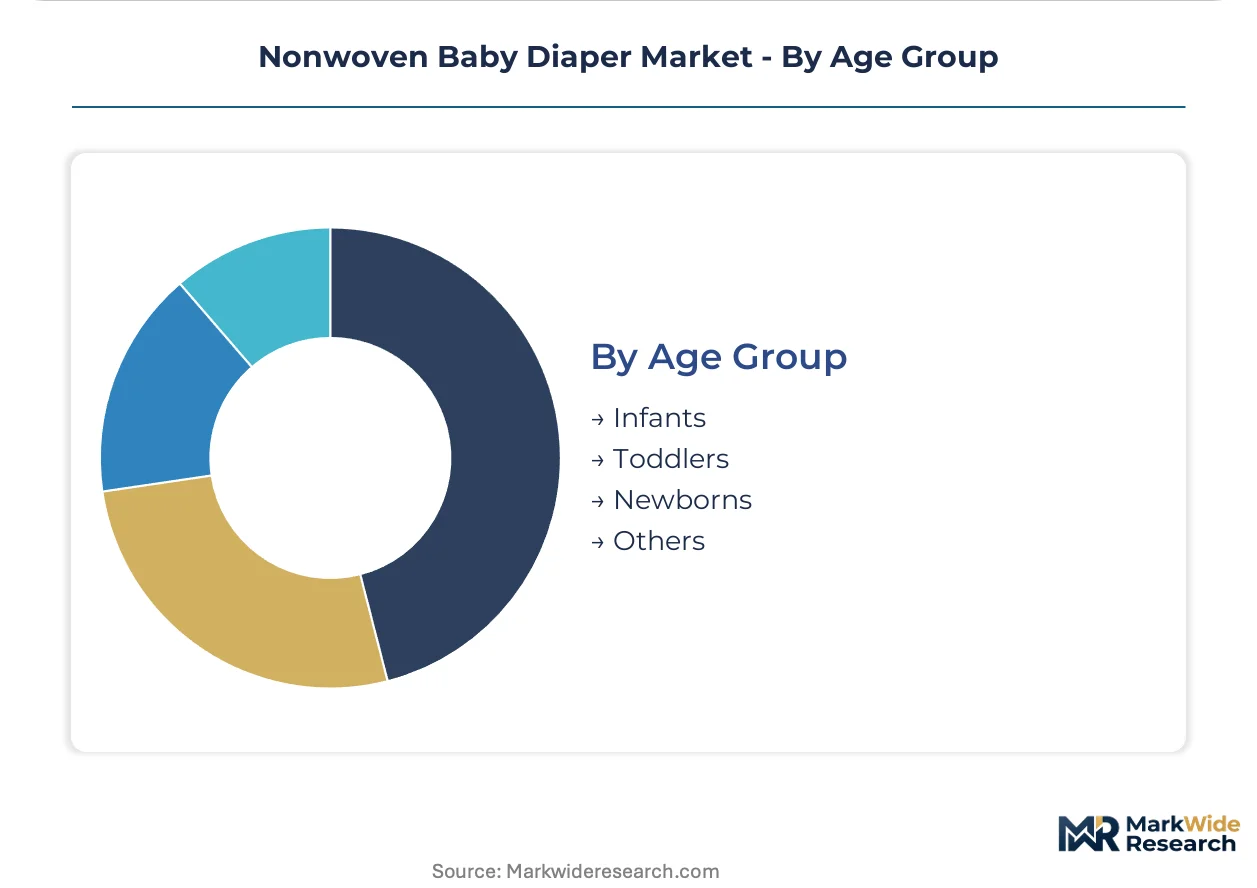
Age Group:
Usage duration and switching costs vary dramatically across developmental stages, from maternity-ward brand lock-in through toddler transition economics.
- Newborns:Hospital sampling programs at birth create switching costs that extend brand loyalty across the full diaper-wearing lifecycle. Kimberly-Clark anchors its position through maternity-ward procurement relationships.
- Infants:Peak consumption volume segment with highest per-unit purchase frequency and strongest subscription platform adhesion.
- Toddlers:Transition timing to training pants varies by geography, compressing the addressable window in markets with early potty-training cultural norms.
- Others:Specialty sizing for premature infants and medical applications commands premium pricing through hospital and home healthcare channels.
Infants drive absolute volume. Newborns is where brand preference formation yields the highest lifetime value returns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH chemical restrictions and the EU Green Deal's packaging waste directives are forcing raw material substitutions that fragment formulation strategies across absorbent hygiene supply chains. Birth rate flattening in Western Europe and North America concentrates expansion opportunity in high-growth urban centers across Asia and Latin America.
China
Urban household expansion in Shanghai and Beijing drives demand concentration as subscription-based direct-to-consumer platforms displace traditional supermarket stock-up behavior. GB/T 28004 national hygiene standards elevate testing burdens that exclude uncertified regional suppliers from hospital procurement channels. The Yangtze River Delta manufacturing cluster hosts spunbond-meltblown-spunbond laminate producers serving both domestic consumption and export markets.
United States
FDA biocompatibility standards for infant contact materials create compliance barriers that favor established suppliers with dedicated testing infrastructure. Captive pulp supply chains controlled by integrated North American producers sustain cost advantages at scale for legacy manufacturers. The Southeast manufacturing corridor spanning Georgia and South Carolina concentrates absorbent hygiene production capacity serving mass retail distribution networks.
Germany
ECHA enforcement of REACH restrictions on formaldehyde-releasing preservatives forces reformulation timelines that disadvantage suppliers lacking European testing infrastructure. EU Green Deal packaging waste directives accelerate bio-based polypropylene adoption and wood pulp substitution mandates. The North Rhine-Westphalia industrial region anchors conversion capacity for biodegradable fiber integration meeting compostability certifications.
Brazil
Urban household buyers in São Paulo consolidate purchases through pharmacy chains responding with private-label biodegradable offerings matching premium brand performance claims. ANVISA pharmaceutical regulations govern infant contact material safety standards for hospital and retail channels. The São Paulo state manufacturing cluster serves as the distribution hub for Southeast Latin American markets.
India
Parents of newborns and toddlers in Mumbai and Delhi represent accelerating demand concentration as urban household formation outpaces mature economy birth rates. BIS certification requirements and state-level procurement standards fragment compliance pathways for multinational entrants. The Gujarat industrial corridor hosts emerging contract manufacturing capacity serving domestic and export markets.
Nonwoven Baby Diaper Market Key Industry Players
Channel-controlling players compete with product-specialist players across divergent competitive terrain defined by procurement access rather than manufacturing scale alone. The market structure consolidates around three strategic tiers: integrated multinationals with captive pulp networks, regional specialists with pharmacy channel dominance, and asset-light contract manufacturers leveraging third-party tolling arrangements. Competitive moves concentrate on maternity-ward sampling lock-in and direct distributor relationships controlling shelf placement in Southeast Asian pharmacy channels.
Among integrated North American consumer goods manufacturers, Procter & Gamble and Kimberly-Clark exemplify distinct strategic archetypes. Procter & Gamble occupies a position anchored by captive pulp supply chains and mill network investments that sustain cost advantages at volume scale. Kimberly-Clark represents the hospital and maternity-ward sampling model that creates brand preference formation from birth. Unicharm sits within the Asia-Pacific pharmacy channel control archetype through direct distributor relationships in Southeast Asian markets. Essity and Ontex exemplify European-based specialists navigating REACH compliance migration and bio-based material substitution mandates.
| Leading Market Players |
|---|
| Essity |
| Johnson & Johnson |
| Procter & Gamble |
| First Quality Enterprises |
| Drylock Technologies |
| Kimberly-Clark |
| Kao |
| Ontex |
| Unicharm |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta port congestion cycles transmit freight cost volatility directly into polymer-based input pricing, amplifying margin compression for ultra-absorbent tier producers while enabling certification-backed premium capture for REACH-compliant suppliers serving European pharmacy channels.
Pricing Analysis
Certification level (REACH/FDA/GB-Tier) creates the primary spread between standard mass-market units and hospital-grade specifications. Three-tier pricing structure across premium, standard, and economy levels stratifies by biodegradability credentials and dermatitis prevention claims. Pricing pressure stems from superabsorbent polymer cost swings that squeeze ultra-absorbent formulations despite volume dominance. Urban households in São Paulo and Mumbai exhibit highest price sensitivity through supermarket channels, while European pharmacy buyers show lowest sensitivity when compostability certifications are displayed.
Supply Chain Analysis
Extended payment terms from Nordic pulp suppliers and supply-chain finance facilities anchored in Singapore trading desks shape working capital structures for mid-tier entrants. Raw material sourcing draws from US Gulf Coast petrochemical corridors for polypropylene, Scandinavian forestry operations for biodegradable fiber substitution, and Chinese Yangtze Delta clusters for spunbond-meltblown-spunbond laminate production. Single-source vulnerability concentrates in superabsorbent polymer feedstock channels controlled by integrated North American producers. Distribution runs through direct-to-consumer platforms in Shanghai and Mumbai, pharmacy chains in Southeast Asia, and mass retail networks in Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nonwoven baby diaper market sits at an inflection where EU Green Deal packaging mandates and REACH chemical disclosure regimes are accelerating bio-based material substitution faster than incumbent cost structures can absorb.
For Market Incumbents: Insulate margin architecture by deepening backward integration into Nordic pulp sourcing corridors and accelerating microporous film R&D partnerships with Japanese manufacturers. Lock in maternity-ward procurement contracts before hospital channels mandate dual REACH-GB/T equivalency certification. Counter polymer cost volatility through long-term offtake agreements with Gulf Coast petrochemical producers. For New Entrants and Emerging Players: Build out asset-light contract manufacturing capacity in Gujarat and São Paulo state industrial corridors to challenge legacy producers without mill network investments. Target subscription-based direct-to-consumer platforms in Mumbai and Delhi where predictive replenishment algorithms concentrate demand visibility. Lead with private-label biodegradable offerings matching premium brand performance claims at standard-tier price points through Southeast Asian pharmacy chains. For Investors and Strategic Acquirers: Carve-out targets emerge from consumer goods conglomerates divesting non-core hygiene assets lacking REACH compliance infrastructure or bio-based material conversion capability. Five-to-ten year viability hinges on certification moats and channel control rather than manufacturing scale alone. Monitor ECHA enforcement timelines for formaldehyde-releasing preservative restrictions as the signal indicating which formulation strategies will capture hospital procurement channel access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Pulp Sourcing | Captive wood pulp supply hedges REACH-driven raw material substitution mandates and insulates margin compression. |
| Dual Certification Investment (REACH/GB-Tier) | Hospital procurement channels in Germany, France, and Netherlands now require equivalency standards that exclude regional competitors. |
| Direct-to-Consumer Platform Launch | Subscription algorithms in Shanghai and Mumbai capture consumption data that displaces traditional supermarket stock-up behavior. |
| Microporous Film R&D Partnership | Japanese and Korean manufacturers dominate breathable backsheet technology for dermatitis prevention claims. |
| Pharmacy Channel Shelf Placement Control | Unicharm's direct distributor relationships in Southeast Asia demonstrate lock-in potential from maternity-ward through toddler transitions. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with supply chain directors at spunbond-meltblown-spunbond laminate producers, procurement leads at Southeast Asian pharmacy chains, regulatory affairs specialists navigating REACH-GB/T equivalency, and brand managers at direct-to-consumer platforms; and secondary validation against customs records, Nielsen retail audit data, ECHA substance restriction announcements, FDA biocompatibility guidance documents, and GB/T 28004 national hygiene standard updates. Bottom-up volume modeling triangulated against top-down market sizing across product type, material composition, distribution channel, and age group segmentation dimensions.
Forecast inputs considered urban household formation rates in São Paulo, Shanghai, and Mumbai; polymer cost volatility indices; ECHA enforcement timelines for preservative restrictions; and subscription platform penetration curves. CAGRs were derived through regression analysis of historical volume trajectories adjusted for regulatory inflection points and material substitution elasticities. Segmentation modeling tracked ultra-absorbent versus eco-friendly product mix shifts, biodegradable fiber adoption rates, and channel migration from mass retail to online platforms across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive moves by asset-light contract manufacturers or unexpected ECHA acceleration of formaldehyde restrictions would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
Mexico Pant Type Adult Diaper Market
Baby Diapers
Dog Diapers Market
Baby Diapers
Baby Diaper Manufacturing Machine Market
Baby Diapers
UAE Baby Diapers Industry Market
Baby Diapers
Australia Pant Type Adult Diaper Market
Baby Diapers
Baby Training Diaper Market
Baby Diapers
Baby Cloth Diaper Market
Baby Diapers
Reusable Baby Diapers and Training Pants Market
Baby Diapers
Middle East and Africa and Asia Pacific Baby Diaper Market
Baby Diapers
Diaper Market
Baby Diapers
Biodegradable Baby Diapers Market
Baby Diapers
Disposable Hygiene Products Market
Baby Diapers
Smart Connected Diaper Market
Baby Diapers
Pet Diapers Market
Baby Diapers
United Arab Emirates Baby Diapers and Wipes Market
Baby Diapers
Baby Disposable Diapers Market