
 Africa and India Baby Diapers Market | 2026-2036
Africa and India Baby Diapers Market Size, Share, and Industry Trends Forecast 2026-2036
Africa and India Baby Diapers Market Outlook
Urban parent demand is decoupling from traditional unbranded cloth alternatives toward organized retail channels across African metros and Indian cities. Procter & Gamble leverages its distribution depth to sustain shelf presence in modern trade formats throughout Nigeria and South Africa. Hindustan Unilever Limited anchors its portfolio through regional manufacturing scale that competes on cost with local assemblers. Kimberly-Clark differentiates via absorbent technology leadership in premium segments across both geographies.
Africa and India baby diapers constitute absorbent hygiene products engineered with superabsorbent polymers, nonwoven topsheets, and elastic leg gathers designed for infant containment and skin health. Manufacturing employs hot-melt adhesive bonding and fluff pulp cores to achieve retention capacities exceeding multiple wettings. Disposable products lead volume due to convenience parity with cloth alternatives in water-scarce regions, while training pants represent the fastest-growing structural segment as toilet-training ages extend in urban households. Distribution through supermarkets and online retail captures margin pools as pharmacy dependence fades in tier-1 Indian cities and African capitals.
India's BIS certification mandates mechanical and chemical safety thresholds for infant contact materials, while Nigeria's national standards agency enforces import quality checks that filter substandard Asian supply. The EU REACH framework indirectly shapes export-oriented Indian manufacturers who supply African markets with European-compliant stock. Stakeholders must monitor regulatory divergence between India's formalizing standards regime and Africa's fragmented enforcement landscapes to align product portfolios with diverging compliance costs.
Market Dynamics
Urban parent demand in Lagos, Nairobi, and Mumbai is decoupling from traditional unbranded cloth alternatives toward organized retail channels, reshaping distribution economics and margin capture across both geographies.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for manufacturing scale attract domestic capacity expansion in absorbent hygiene products. This reduces import dependence and compresses unit economics for regional brands.
- Superabsorbent polymer advances:Core material innovations enable thinner designs with higher retention capacity. Millennial parents in water-scarce regions prioritize convenience parity with cloth alternatives.
- Retail formalization in Nigeria:Modern trade penetration along commercial corridors expands shelf access for packaged diapers. Pharmacy dependence fades as supermarkets capture volume.
Market Restraints
- Fluff pulp cost volatility:Imported softwood pulp exposes manufacturers to currency and freight fluctuations. Margin compression limits pricing flexibility for mid-tier products.
- Import quality barriers:Nigeria's national standards agency filters substandard Asian supply, creating compliance friction for unregistered exporters. Entry costs rise for new market participants.
- Cloth diaper substitution:Lower-income households in rural India and East Africa retain traditional alternatives. Price elasticity constrains volume expansion at the base of the pyramid.
Strategic Opportunities
- Tier-2 Indian cities:Underpenetrated markets beyond Mumbai and Delhi present whitespace for regional manufacturing scale. Distribution infrastructure investments unlock first-mover positioning.
- Eco-friendly variants:Biodegradable topsheets and plant-based cores align with BIS safety thresholds and urban parent preferences. Certification differentiation commands shelf premium.
- Online retail expansion:E-commerce platforms bypass traditional pharmacy and kirana store dependence in African capitals. Direct-to-parent subscription models capture recurring revenue pools.
Industry Challenges
- Hot-melt adhesive formulation expertise:Bonding chemistry specialization remains concentrated among multinational technical teams. Local assemblers face yield and consistency gaps.
- BIS certification timelines:Mechanical and chemical safety testing for infant contact materials extends product launch cycles. Regulatory backlog delays market entry for reformulated SKUs.
- Legacy channel integration:Modern trade expansion requires reconfiguration of distributor incentives and credit terms. Fragmented wholesale networks resist margin compression.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa and India Baby Diapers Market |
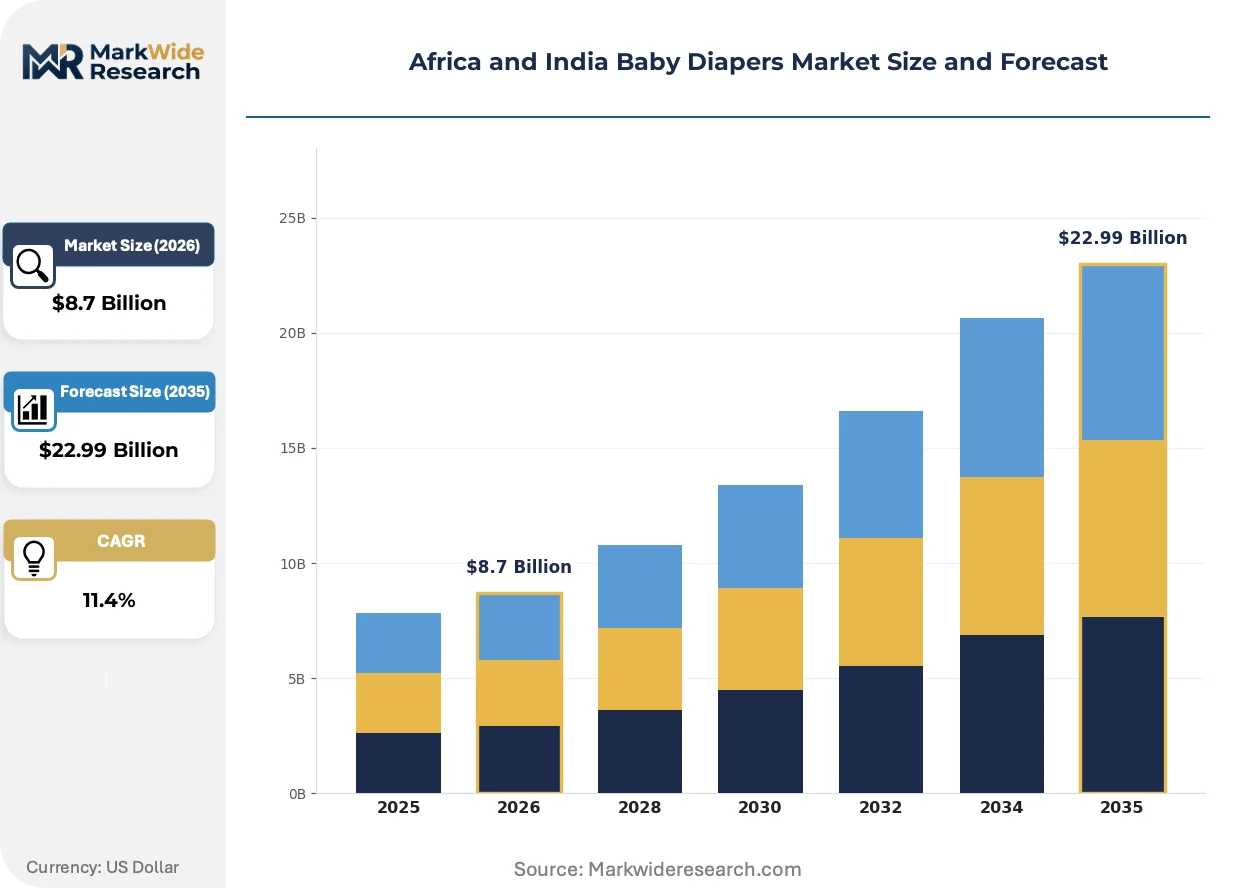
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Cloth, Training Pants, Swim Diapers Distribution Channel: Online Retail, Supermarkets, Baby Specialty Stores, Pharmacies Customer Type: Parents, Caregivers, Hospitals, Daycares Price Tier: Premium, Mid-range, Budget, Value Packs |
| Companies Covered | Honasa Consumer Ltd (Mamaearth), Dabur India Limited, Procter & Gamble, Hengan International Group Company Limited, Piramal Pharma Limited, Kimberly-Clark, Hindustan Unilever Limited, Essity AB, Unicharm Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa and India Baby Diapers Market Strategic Shifts
Absorbent technology convergence with sustainability mandates and channel digitization is compressing traditional competitive moats across African and Indian diaper markets. Product differentiation increasingly depends on material science rather than brand equity alone.
Plant-based superabsorbent polymers derived from agricultural waste streams are consolidating technical leadership in premium diaper segments. Manufacturers serving export-oriented Indian producers who supply African markets now prioritize European REACH compliance as a baseline specification. This material shift enables thinner core designs that reduce shipping cube and warehouse footprint.
India's BIS certification mandates for mechanical and chemical safety thresholds are tightening enforcement scope for infant contact materials. Domestic manufacturers must upgrade testing protocols to maintain market access, while importers face enhanced documentation requirements. Tier-1 Indian cities see fastest compliance adaptation as modern trade retailers demand certified stock.
Subscription-based replenishment models through e-commerce platforms are displacing traditional pharmacy and supermarket purchasing cycles among urban millennial parents. Direct-to-consumer channels capture margin pools previously allocated to wholesale distributors. Lagos and Nairobi demonstrate highest adoption velocity where mobile payment infrastructure enables automated reordering.
Africa and India Baby Diapers Market Segmentation
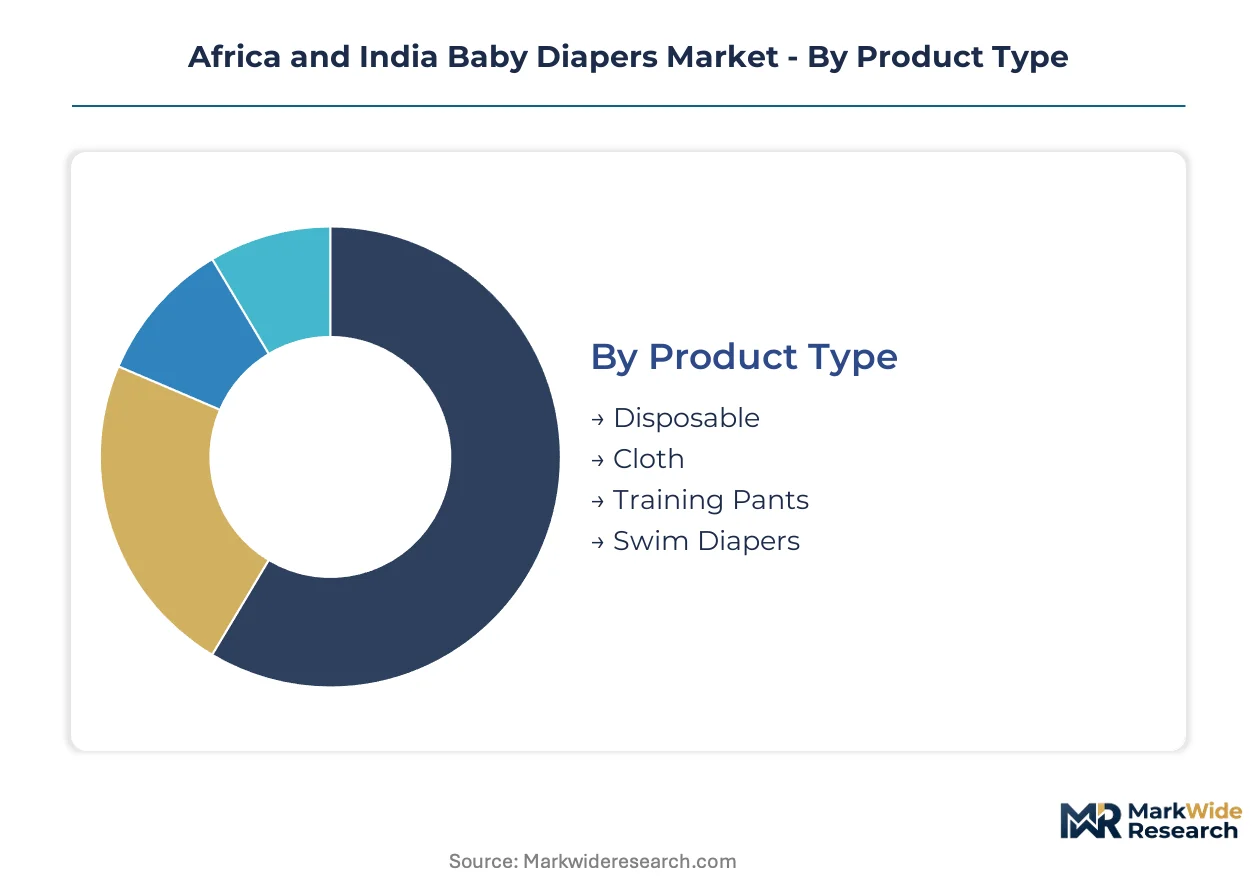
Segmentation across Africa and India reveals how supply concentration, channel formalization, and price tier stratification create distinct competitive battlegrounds. Manufacturers must align product portfolios with divergent compliance costs and retail infrastructure maturity across both geographies.
Product Type:
Supply concentration in polymer chemistry and fluff pulp sourcing determines competitive positioning across absorbent hygiene formats.
- Disposable:Superabsorbent polymer cores with nonwoven topsheets dominate volume through convenience parity in water-scarce Lagos and Mumbai. Urban millennial parents drive organized retail adoption as pharmacy dependence fades.
- Training Pants:Elastic waistband designs with tear-away sides accommodate extended toilet-training ages in urban households. Demand concentrates in tier-1 Indian cities and Nigerian commercial corridors where modern trade penetration expands shelf access.
- Cloth:Traditional unbranded alternatives retain price-sensitive rural households in East Africa and India's hinterland. Lower-income segments constrain volume expansion at the base of the pyramid.
- Swim Diapers:Specialized containment for aquatic environments captures seasonal demand in coastal metros and premium resort markets. Niche positioning limits manufacturing scale.
Today's leader: Disposable. Tomorrow's challenger: Training Pants.
Distribution Channel:
Margin capture shifts as channel formalization reconfigures distributor economics and credit terms across fragmented wholesale networks.
- Supermarkets:Modern trade formats along commercial corridors expand shelf access for packaged diapers in Lagos and Nairobi. Retail formalization displaces traditional pharmacy dependence.
- Online Retail:E-commerce platforms bypass kirana store intermediation in tier-1 Indian cities and African capitals. Mobile payment infrastructure enables subscription-based replenishment models among urban millennial parents.
- Baby Specialty Stores:Curated assortments with certified stock serve BIS-conscious consumers in Mumbai and Delhi. Premium positioning commands shelf margin through safety differentiation.
- Pharmacies:Legacy channel retains rural penetration where modern trade infrastructure remains underdeveloped. Margin compression accelerates as supermarkets capture volume.
Supermarkets anchor current volume. Online retail is climbing the fastest.
Customer Type:
Procurement authority concentrates with institutional buyers whose compliance requirements exceed individual consumer thresholds.
- Parents:Urban millennial decision-makers in Lagos, Nairobi, and Mumbai prioritize convenience parity and BIS-certified materials. Direct-to-consumer channels capture recurring revenue pools.
- Hospitals:Bulk procurement with stringent safety documentation requirements filters substandard supply. BIS mechanical and chemical testing mandates shape vendor qualification.
- Caregivers:Extended family and domestic staff influence purchase timing in multi-generational households. Price elasticity constrains premium adoption.
- Daycares:Institutional volume with standardized SKU requirements favors mid-range products with consistent supply reliability. Procurement runs through wholesale distributors.
Parents dominate purchase frequency. Hospitals set the compliance baseline.
Price Tier:
Three-tier pricing structure across premium, standard, and economy levels reflects raw material grade differentiation and manufacturing scale advantages.
- Premium:Plant-based cores and biodegradable topsheets align with BIS safety thresholds and urban parent preferences. European REACH compliance commands shelf premium in export-oriented supply.
- Mid-range:Balanced absorbent capacity with regional manufacturing scale competes on cost with local assemblers. Tier-2 Indian cities present whitespace for first-mover positioning.
- Budget:Basic polymer cores with simplified leg gathers serve price-sensitive segments retaining cloth alternatives. Fluff pulp cost volatility compresses margin flexibility.
- Value Packs:Volume bundling reduces per-unit shipping cube and warehouse footprint for e-commerce subscription models. Direct-to-parent channels capture margin pools.
Premium commands margin expansion. Mid-range holds volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled manufacturing workforces in absorbent hygiene technology anchor production capacity across Nigeria, South Africa, and India's western industrial corridor. Technical talent concentration in polymer chemistry and nonwoven engineering shapes competitive positioning in these markets.
Nigeria
Lagos millennial parents drive organized retail adoption of disposable diapers as pharmacy dependence fades along commercial corridors. The national standards agency enforces import quality checks that filter substandard Asian supply. Manufacturing clusters in Lagos and Port Harcourt attract regional distribution investments from multinational hygiene players.
South Africa
Urban households in Johannesburg and Cape Town prioritize premium absorbent products with certified safety documentation. The country's national consumer regulator maintains quality thresholds for infant contact materials. Retail formalization in Gauteng and Western Cape provinces expands modern trade shelf access for packaged diaper brands.
India
Tier-2 cities beyond Mumbai and Delhi present whitespace demand as regional manufacturing scale reduces import dependence. BIS certification mandates mechanical and chemical safety testing for infant contact materials. Gujarat and Maharashtra industrial corridors host domestic capacity expansion under PLI scheme incentives.
Kenya
Nairobi's urban parent demographic accelerates adoption of convenience-oriented disposable formats over traditional cloth alternatives. The country's national standards body regulates imported hygiene product quality through pre-shipment verification. Distribution infrastructure investments concentrate in Nairobi's commercial zones and Mombasa port corridors.
Egypt
Cairo and Alexandria households drive volume in mid-range diaper segments as modern trade penetration expands. The national quality and standards organization enforces safety documentation for imported infant hygiene products. Manufacturing activity clusters in Cairo's industrial zones with supply chain linkages to Suez Canal logistics.
Africa and India Baby Diapers Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered price-positioning bands. Market structure consolidates around multinational hygiene leaders with polymer chemistry expertise and regional manufacturing scale. Three archetypes dominate: global consumer goods conglomerates with distribution depth, Asian manufacturing specialists with cost-optimized production, and domestic Indian players with regulatory compliance advantages. Capacity expansion and portfolio diversification constitute the dominant competitive moves as participants defend shelf position in formalizing retail channels.
Within the multinational conglomerate tier, Procter & Gamble and Kimberly-Clark occupy positions defined by absorbent technology leadership and distribution infrastructure depth. Hindustan Unilever Limited exemplifies the domestic Indian archetype with regional manufacturing scale that competes on cost positioning. Among Asia-based specialists, Hengan International Group Company Limited and Unicharm Corporation represent manufacturing-driven competitive positioning with supply chain integration across absorbent hygiene categories.
| Leading Market Players |
|---|
| Honasa Consumer Ltd (Mamaearth) |
| Dabur India Limited |
| Procter & Gamble |
| Hengan International Group Company Limited |
| Piramal Pharma Limited |
| Kimberly-Clark |
| Hindustan Unilever Limited |
| Essity AB |
| Unicharm Corporation |
| Others |
Value Chain & Pricing Dynamics
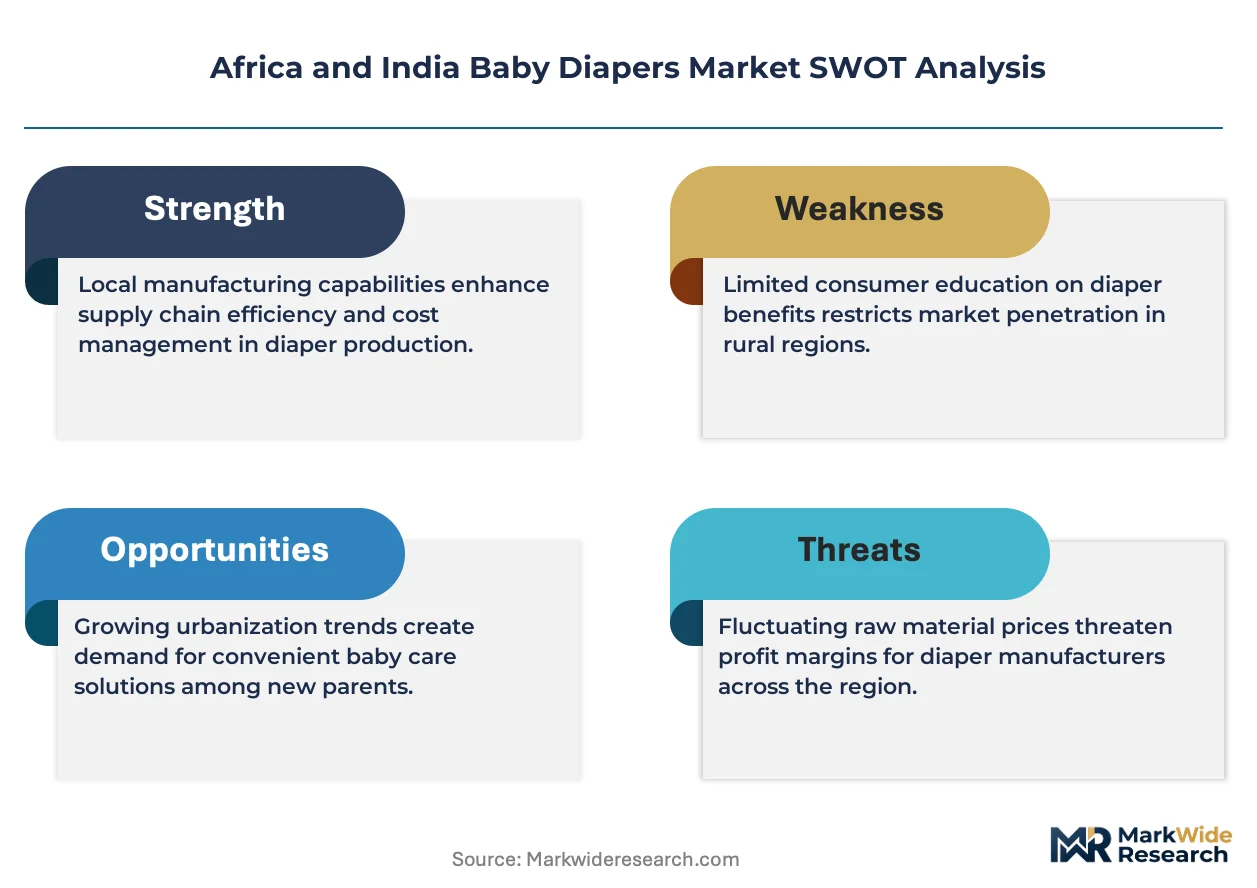
Skilled manufacturing workforces in Gujarat and Maharashtra's polymer chemistry clusters anchor production economics that compress labor-cost differentials between premium and economy diaper tiers across India and Africa.
Pricing Analysis
Bundled subscription services compete against unbundled per-unit supermarket transactions across urban Indian and African markets. Three-tier pricing structure across premium, standard, and economy levels separates plant-based certified products from regional manufacturing scale offerings and basic polymer-core alternatives. Price differentiation hinges on BIS certification grade and volume scale in tier-2 Indian cities. Cost compression in the budget tier is intensifying because fluff pulp import volatility exposes local assemblers to currency fluctuations. Rural households retaining cloth alternatives exhibit highest price sensitivity, while hospital procurement committees demonstrate lowest elasticity due to stringent safety documentation requirements.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for superabsorbent polymer feedstock away from pure import dependence. Manufacturing gravity centers on India, China, and South Korea for polymer chemistry and nonwoven engineering capacity. Raw material dependencies draw from imported softwood fluff pulp, petroleum-derived superabsorbent polymers, and hot-melt adhesive formulations. Single-source vulnerability concentrates in Asian polymer suppliers serving export-oriented Indian producers. Distribution runs through modern trade supermarkets and e-commerce platforms that displace legacy pharmacy wholesale networks in Lagos, Nairobi, and Mumbai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder underpinned by urban millennial parent demand that sustains recurring consumption through toilet-training age extensions.
For Market Incumbents: Deepen backward integration into superabsorbent polymer production to insulate margins from fluff pulp cost volatility. Expand certified manufacturing capacity in Gujarat and Maharashtra industrial corridors to exploit PLI scheme incentives. Channel control through direct-to-parent subscription platforms defends against emerging Asian manufacturing specialists penetrating via e-commerce.
For New Entrants and Emerging Players: Launch via mobile-enabled subscription models targeting Nairobi and Lagos urban corridors where pharmacy dependence fades fastest. Tier-2 Indian cities beyond Mumbai and Delhi present the most penetrable whitespace for regional manufacturing scale. White-space targets include biodegradable topsheet variants aligned with BIS safety thresholds and eco-conscious urban parent preferences.
For Investors and Strategic Acquirers: Consumer goods conglomerates with distribution depth represent the most active acquirer in this space, consolidating regional manufacturing scale to defend shelf position. Long-term viability centers on 5-10 year demographic tailwinds from urbanization and organized retail formalization. Acquisition target archetypes include domestic Indian players with regulatory compliance advantages and established BIS certification protocols. The signal to watch is modern trade penetration velocity in tier-2 Indian cities as an inflection indicator for volume concentration shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Production | Captive superabsorbent supply insulates Procter & Gamble and Kimberly-Clark from fluff pulp currency exposure. |
| BIS Certification Investment | Enhanced testing protocols enable Hindustan Unilever Limited to command shelf premium in tier-1 Indian supermarkets. |
| Direct-to-Consumer Subscription Launch | Automated replenishment models bypass wholesale distributor margins in Lagos and Nairobi mobile payment corridors. |
| Tier-2 City Distribution Expansion | First-mover infrastructure investments unlock whitespace demand in underpenetrated Indian markets beyond Delhi and Mumbai. |
| Sustainability Repositioning | Plant-based core certification aligns Honasa Consumer Ltd with urban parent preferences and BIS safety thresholds. |
Study Parameters
Multiple input streams — primary interviews with supply chain directors, regulatory affairs specialists, and category buyers at modern trade retailers; secondary validation through BIS certification databases, customs import records, and PLI scheme disclosure filings; plus Nielsen retail audit data from tier-1 and tier-2 Indian cities — were reconciled through bottom-up and top-down triangulation. Conversations with polymer chemistry R&D leads, fluff pulp procurement managers at absorbent hygiene manufacturers, and e-commerce platform supply heads informed raw material cost dynamics and channel shift velocities. Trade data from Nigeria's national standards agency and Kenya's pre-shipment verification records filtered import quality patterns.
Data-stream reconciliation across product type segmentation, distribution channel evolution, price tier stratification, and regional manufacturing cluster development shaped the analytical framework over the projection horizon. CAGRs were derived from modeled volume and value trajectories reflecting urban parent adoption curves, toilet-training age extensions, and modern trade penetration rates. Forecast inputs incorporated BIS certification timeline backlogs, PLI scheme capacity addition schedules, and mobile payment infrastructure adoption in African capitals.
Several conditions sit outside the modeled scope, including macroeconomic currency shocks affecting fluff pulp import costs, abrupt regulatory enforcement shifts in fragmented African standards landscapes, and unforeseen substitution acceleration toward cloth alternatives in rural segments. Forecasts reflect documented assumptions regarding urbanization velocity and organized retail formalization pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
Pet Diapers Market
Baby Diapers
Baby Disposable Diapers Market
Baby Diapers
Diaper Market
Baby Diapers
United States Diaper Market
Baby Diapers
Middle East and Africa and Asia Pacific Baby Diaper Market
Baby Diapers
Europe Diaper Market
Baby Diapers
Disposable Hygiene Products Market
Baby Diapers
Cat Diapers Market
Baby Diapers
United Arab Emirates Baby Diapers and Wipes Market
Baby Diapers
Australia Pant Type Adult Diaper Market
Baby Diapers
Mexico Pant Type Adult Diaper Market
Baby Diapers
China Pant Type Adult Diaper Market
Baby Diapers
Adult Diapers Market
Baby Diapers
Biodegradable Diapers Market
Baby Diapers
GCC Diaper Market
Baby Diapers
Biodegradable Baby Diapers Market