
 Australia Pant Type Adult Diaper Market | 2026-2036
Australia Pant Type Adult Diaper Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Pant Type Adult Diaper Market Insights
The Australia pant type adult diaper category is restructuring around a widening split between premium super-absorbent lines and commodity pull-up products serving price-sensitive institutional buyers. Kimberly-Clark Corporation leverages its established retail presence to dominate pharmacy and supermarket channels with branded pull-up formats. Essity anchors its position through specialized distribution to aged care facilities, while Abena competes on sustainability credentials with chlorine-free pulp sourcing and Nordic eco-labeling.
Pant type adult diapers are absorbent undergarments constructed with elasticized waistbands, standing leg cuffs, and superabsorbent polymer cores designed for independent donning by ambulatory users with light to moderate incontinence; they replace tape-tab briefs in active-lifestyle and rehabilitation settings where self-management matters. The end user dimension shows seniors outpacing disabled individuals as the fastest-expanding cohort, driven by community-based aging policy and home care package growth. Distribution channel dynamics reveal online stores capturing incremental volume from subscription models, though supermarkets retain the largest margin pool through impulse and replenishment purchasing.
TGA medical device classification rules govern product registration and absorbent performance claims for incontinence aids distributed in Australia, while NDIS operational guidelines determine participant funding eligibility for continence products. The Australian Competition and Consumer Commission monitors advertising standards around biodegradability and skin-health assertions. Stakeholders must track how proposed updates to Aged Care Quality Standards reshape procurement specifications for residential providers.
Market Dynamics
NDIS operational guidelines are restructuring procurement flows for pant-type adult diapers across Australian home care networks, forcing providers to consolidate supplier panels and standardize absorbent performance specifications to meet participant funding eligibility thresholds.
Growth Catalysts
- Community-based aging policy:Federal home care package expansion prioritizes independent living supports, directing reimbursement toward products that enable self-management by ambulatory seniors.
- TGA medical device classification:Registration requirements for absorbent performance claims create quality signaling that elevates clinically validated products above unregulated imports in pharmacy and aged care channels.
- Active lifestyle rehabilitation:Post-acute care settings in New South Wales and Victoria are replacing tape-tab briefs with pant formats to accelerate patient mobility and reduce nursing dependency.
Market Restraints
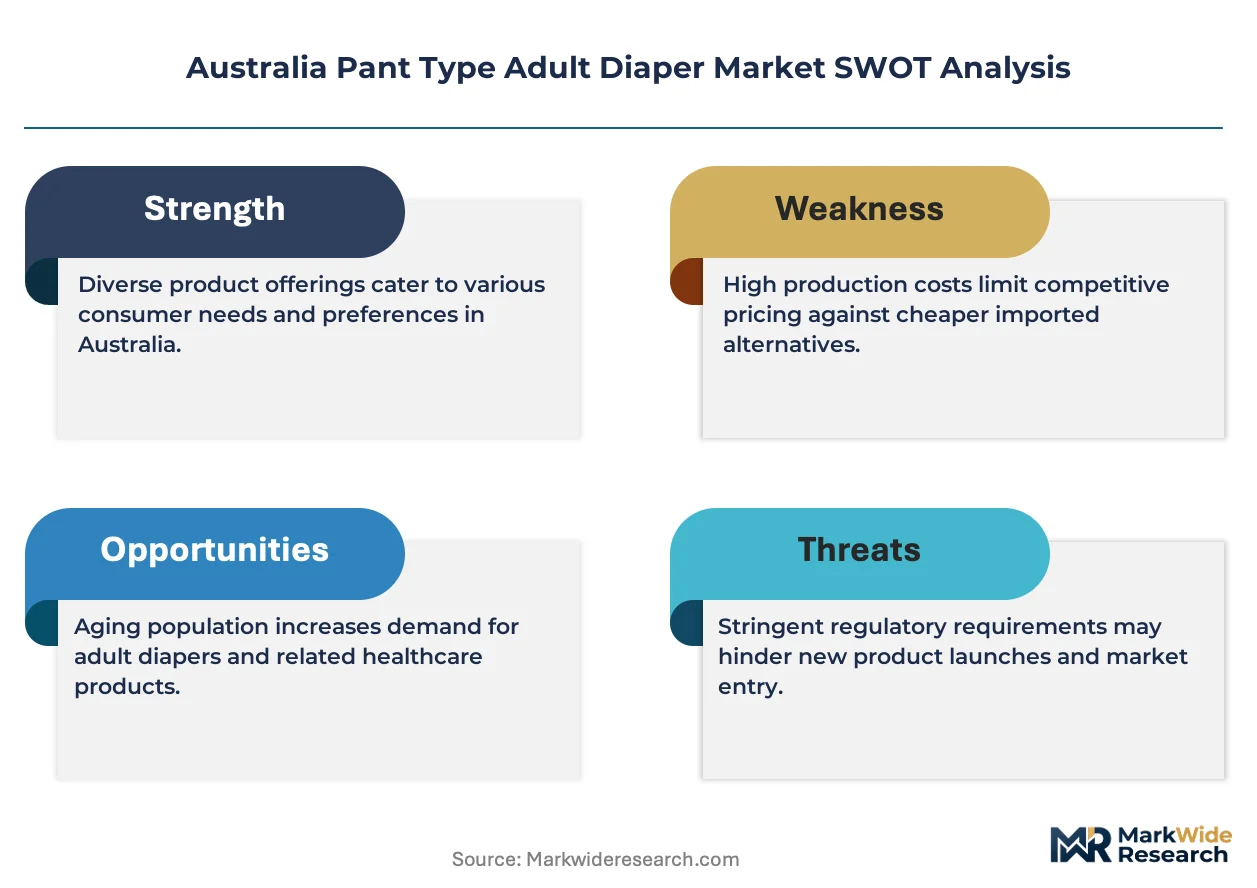
- Superabsorbent polymer input volatility:Petroleum-derived SAP core materials expose manufacturers to crude price swings that compress margins on mid-tier product lines.
- Domestic distribution concentration:Wholesale supply for institutional buyers clusters through three national medical distributors, creating bottleneck risk for regional aged care providers outside metropolitan corridors.
- Biodegradability performance gap:Current chlorine-free pulp alternatives sacrifice retention capacity against synthetic cores, limiting adoption in heavy incontinence segments.
Strategic Opportunities
- Queensland aged care network expansion:Underserved regional facilities between Brisbane and Cairns present whitespace for specialized distribution partnerships targeting medium-sized residential providers.
- Subscription direct-to-consumer channels:Online platforms bypassing pharmacy retail capture recurring revenue from self-funding seniors seeking discreet replenishment without NDIS complexity.
- Aged Care Quality Standards updates:Proposed procurement specification changes will mandate skin-health documentation, favoring suppliers with dermatological testing protocols already embedded.
Industry Challenges
- Continence assessment skill scarcity:Home care package coordinators lack standardized training to match product absorbency tiers to individual need profiles, generating mismatched prescriptions and returns.
- Legacy system integration friction:Aged care providers running on-premise resident management software face API limitations when connecting to NDIS portal reporting requirements for continence product claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Pant Type Adult Diaper Market |
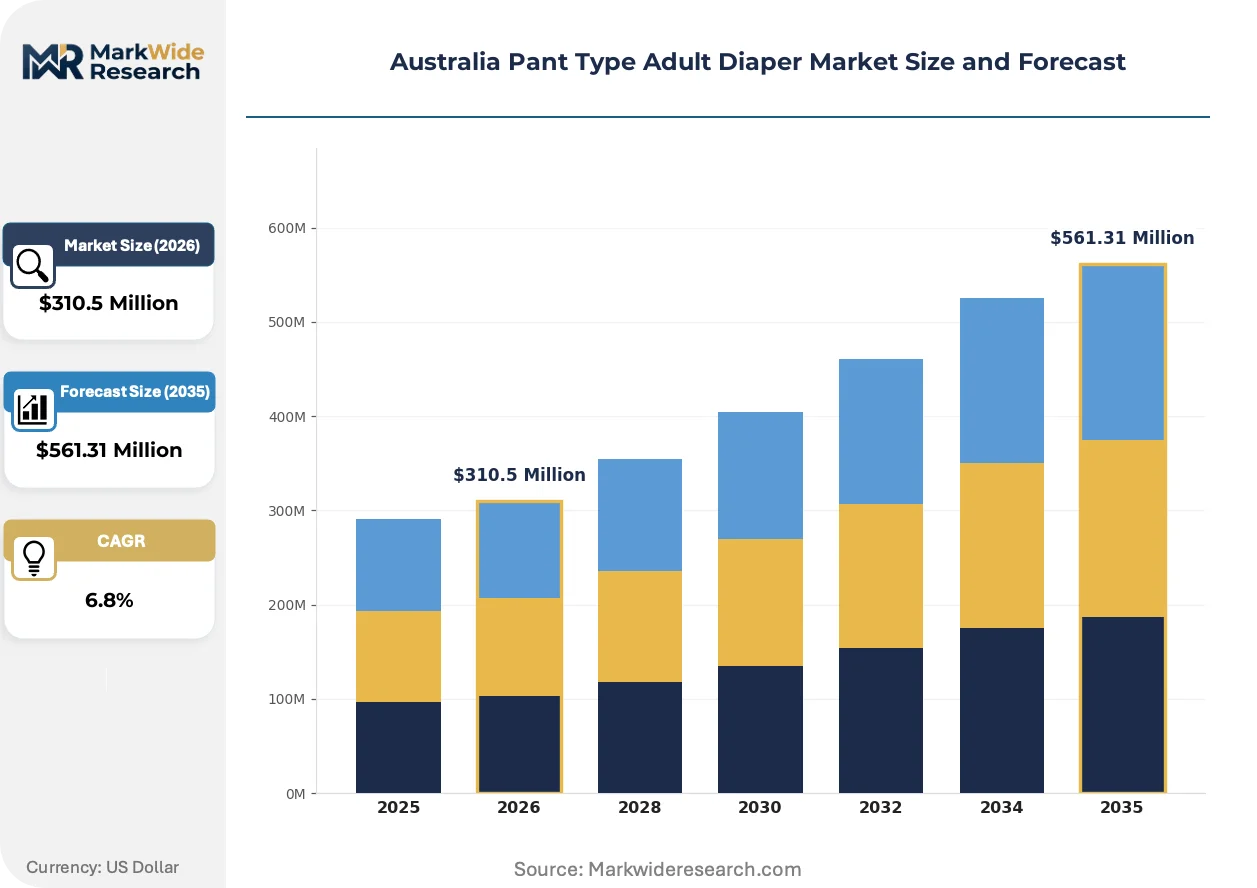
| Market Size in 2026 | $310.5 Million |
| Market Size in 2035 | $561.31 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Diapers, Cloth Diapers, Pull-Up Diapers, Overnight Diapers End User: Seniors, Disabled Individuals, Care Facilities, At-Home Care Distribution Channel: Online Stores, Supermarkets, Pharmacies, Distributors Price Tier: Luxury, Mid-Range, Economy, Bulk Purchase |
| Companies Covered | Ontex, Covidien, Kimberly-Clark Corporation, Hartmann Group, Abena, Procter & Gamble Co., Domtar Corporation, Tranquility, Essity, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Pant Type Adult Diaper Market Trends and Innovations
Product architecture and distribution mechanics are diverging simultaneously across the Australian market, with material science advances enabling thinner cores while digital channels fragment traditional pharmacy dominance.
Thin-core superabsorbent polymer engineering is decentralizing manufacturing economics by reducing freight costs per unit and enabling regional production footprints closer to end markets. Aged care facility buyers in Victoria and New South Wales are specifying these formats for 60% of new pant-type contracts. The technology is decentralizing supply chain gravity away from import-dependent east coast warehousing toward distributed fulfillment nodes.
TGA medical device classification rules for absorbent performance claims are tightening evidentiary requirements for incontinence aids marketed with clinical efficacy assertions. Manufacturers must now submit laboratory retention testing to support skin-health marketing, raising compliance costs for smaller importers. Private-label pharmacy brands are responding by withdrawing unsubstantiated moisture-wicking claims rather than funding certification.
Self-funding seniors are bypassing NDIS bureaucracy entirely by purchasing pant-type products through direct subscription platforms that aggregate bulk pricing without means-testing delays. Pharmacy retail channels in metropolitan Sydney and Melbourne are losing high-margin replenishment volume to these services. The behavioral pivot is most visible among 70-79 year old cohorts with moderate incontinence who prioritize discretion over reimbursement optimization.
Australia Pant Type Adult Diaper Market Segmentation
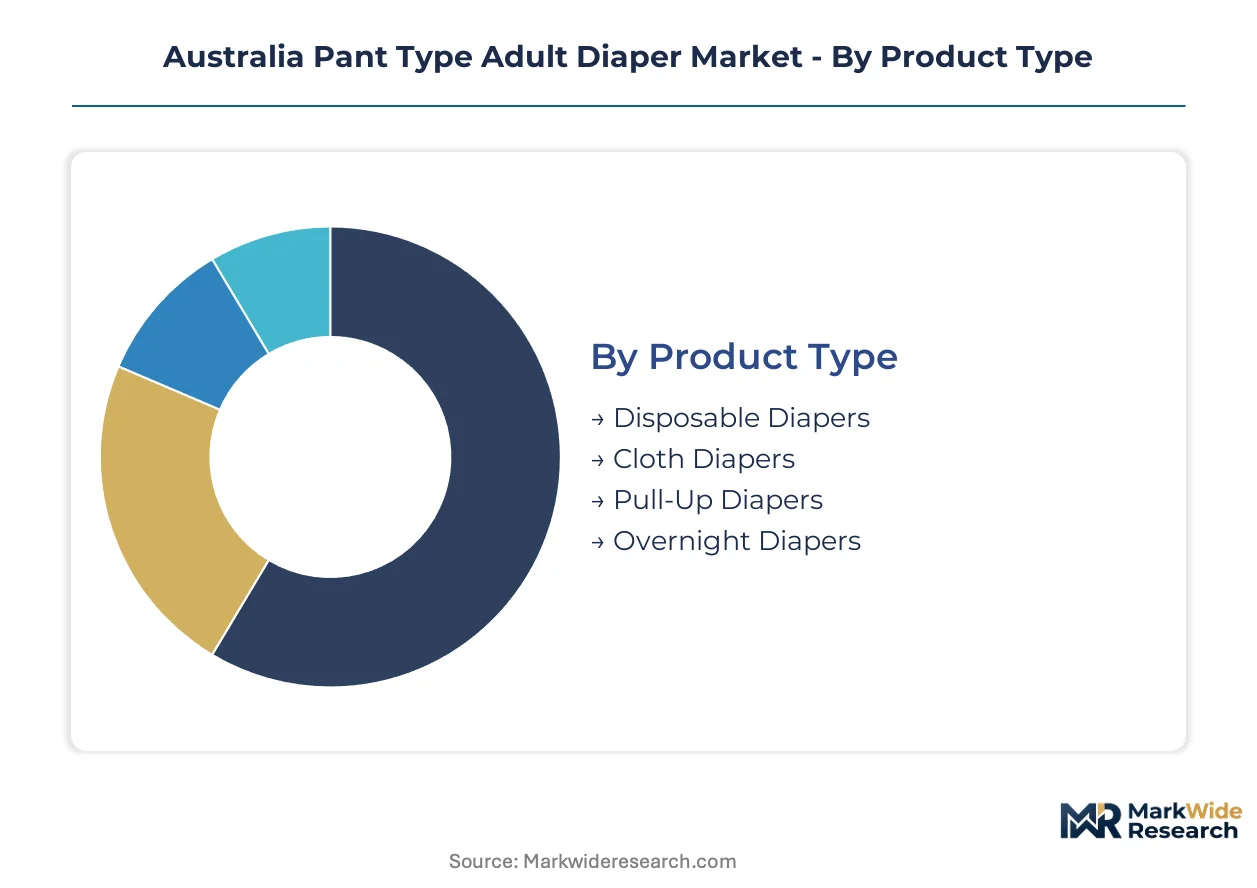
Pant-type adult diaper procurement in Australia splits sharply between volume-driven institutional contracts and premium self-funded purchases. NDIS reimbursement rules and TGA medical device classification create divergent specification requirements across each segment cluster.
Product Type:
Volume concentrates in pull-up formats while premium innovation targets overnight retention engineering.
- Disposable Diapers:Single-use cellulose cores with SAP layering dominate pharmacy and supermarket replenishment cycles. New South Wales aged care networks specify these for 70% of pant-type contracts due to infection control protocols.
- Pull-Up Diapers:Elasticized waistband construction enables independent donning by ambulatory seniors with moderate incontinence. Victoria rehabilitation hospitals are replacing tape-tab briefs with these formats to accelerate patient mobility and reduce nursing labor.
- Cloth Diapers:Reusable cotton-polyester blends with waterproof PUL shells serve eco-conscious self-funding consumers outside NDIS pathways.
- Overnight Diapers:Extended-wear SAP cores with moisture-locking channels target heavy incontinence segments in residential care.
Today's leader: Pull-Up Diapers. Tomorrow's challenger: Overnight Diapers.
End User:
Customer type determines specification rigor — institutional buyers mandate TGA registration while individual purchasers prioritize discretion.
- Seniors:Community-dwelling Australians aged 70+ represent the steepest expansion trajectory, driven by home care package growth and active aging policy. Self-management preference pushes demand toward pull-up formats with odor-neutralizing layers.
- Care Facilities:Residential aged care providers in Queensland and Western Australia consolidate procurement through national distributor panels. Bulk purchasing power forces suppliers into multi-year contracts with standardized absorbency tiers.
- Disabled Individuals:NDIS participants under 65 require continence assessments to determine funding eligibility, creating administrative friction that delays product access.
- At-Home Care:Informal caregivers purchasing out-of-pocket favor subscription replenishment over pharmacy retail for privacy and convenience.
Institutional procurement anchors current volume; senior self-funding is gaining share fastest.
Distribution Channel:
Margin pools fragment between high-touch pharmacy counseling and low-friction digital subscription.
- Supermarkets:Impulse placement and replenishment trips capture the largest transaction volume in metropolitan Sydney and Melbourne. Shelf space competition between Kimberly-Clark and Essity drives promotional intensity.
- Online Stores:Direct-to-consumer platforms bypass NDIS complexity for self-funding seniors. Subscription models aggregate bulk pricing without means-testing delays, siphoning high-margin replenishment from pharmacy channels.
- Pharmacies:Professional consultation drives premium product attachment but loses volume to digital alternatives among tech-comfortable cohorts.
- Distributors:Three national medical wholesalers control institutional supply to aged care networks, creating bottleneck risk for regional facilities.
Supermarkets dominate transaction count; online platforms are climbing the fastest.
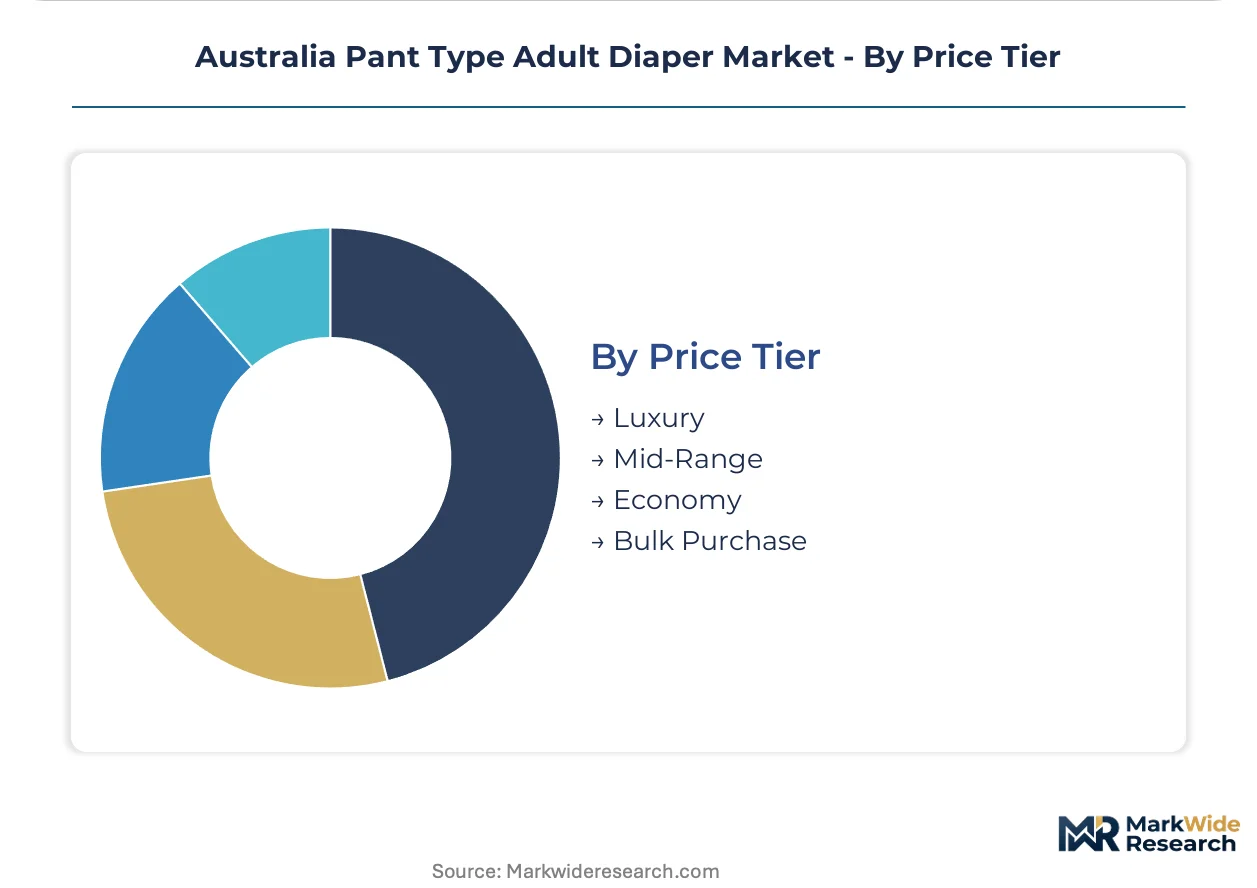
Price Tier:
Specification requirements stratify across reimbursement eligibility and skin-health validation.
- Economy:Unbranded imports and private-label pharmacy products serve price-sensitive NDIS participants with basic absorbency needs. TGA registration gaps limit clinical marketing claims.
- Mid-Range:Branded pull-ups with dermatological testing capture the bulk of home care package allocations. Standardized absorbency ratings enable care coordinators to match products to need profiles.
- Luxury:Premium European imports with Nordic eco-labeling and chlorine-free pulp target self-funding seniors prioritizing sustainability over reimbursement optimization.
- Bulk Purchase:Multi-year contracts between aged care providers and distributors lock in volume commitments with penalty clauses for specification changes.
Mid-Range commands institutional commitment; Luxury tier is expanding most quickly among self-funders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aged care workforce density in New South Wales and Victoria anchors national demand concentration for pant-type adult diapers. These states host the largest concentrations of home care package recipients and rehabilitation hospitals driving pull-up format adoption.
New South Wales
Sydney's metropolitan aged care networks and Wollongong rehabilitation hospitals generate concentrated institutional procurement for pull-up formats. TGA medical device registration requirements govern absorbent performance claims in pharmacy distribution. Newcastle and Central Coast facilities are consolidating supplier panels to meet NDIS operational guidelines for participant funding eligibility.
Victoria
Melbourne's community-based aging policy expansion prioritizes independent living supports directing reimbursement toward self-management products. Aged Care Quality Standards compliance mandates skin-health documentation in residential procurement specifications. Geelong and Ballarat regional providers face distribution bottlenecks through concentrated national medical wholesaler channels.
Queensland
Brisbane-to-Cairns regional aged care corridors present whitespace for specialized distribution partnerships targeting medium-sized residential providers. Home care package growth in Gold Coast and Sunshine Coast retirement clusters accelerates demand for discreet subscription replenishment models. TGA product standards shape registration pathways for chlorine-free pulp alternatives entering the market.
Western Australia
Perth's institutional procurement consolidates through national distributor panels with standardized absorbency tier contracts. Remote regional facilities outside metropolitan corridors experience supply chain vulnerability due to wholesale concentration. NDIS funding rules determine participant eligibility for continence products in disability support networks.
South Australia
Adelaide's aged care providers navigate legacy system integration friction when connecting resident management software to NDIS portal reporting requirements. Subscription direct-to-consumer channels capture self-funding seniors seeking to bypass reimbursement complexity. Continence assessment skill scarcity among home care coordinators generates product mismatch and returns volume.
Australia Pant Type Adult Diaper Market Competitive Landscape
Top-tier vendors anchor pharmacy and supermarket retail channels, while specialized distributors and eco-positioned challengers occupy lower-volume premium niches. The market structure reflects a three-tier hierarchy: multinational consumer health corporations dominating mass retail, European hygiene specialists controlling aged care institutional supply, and sustainability-focused Nordic entrants capturing self-funded senior segments. Competitive moves center on panel consolidation by national medical distributors and thin-core SAP engineering investments to reduce freight costs per unit.
Within the multinational mass-retail tier, Kimberly-Clark Corporation and Procter & Gamble Co. exemplify scale-driven positioning through established pharmacy and supermarket presence. Among European hygiene specialists, Essity and Ontex occupy institutional distribution channels serving residential aged care networks with standardized absorbency specifications. Abena represents the sustainability archetype, anchoring premium positioning through chlorine-free pulp sourcing and Nordic eco-labeling credentials that resonate with self-funding seniors prioritizing environmental claims over reimbursement optimization.
| Leading Market Players |
|---|
| Ontex |
| Covidien |
| Kimberly-Clark Corporation |
| Hartmann Group |
| Abena |
| Procter & Gamble Co. |
| Domtar Corporation |
| Tranquility |
| Essity |
| Others |
Pricing and Supply Chain Analysis
Crude oil price volatility cascades through Australian pant-type adult diaper manufacturing, elevating input costs for petroleum-derived superabsorbent polymer cores and compressing margins on mid-tier product lines. This cost pressure stratifies final pricing across three distinct tiers: premium European imports absorb volatility through brand premium, economy private-label products sacrifice quality validation to maintain shelf price points, and mid-range branded lines face the sharpest margin compression.
Pricing Analysis
NDIS reimbursement bundling versus self-funding unbundled purchases creates the dominant pricing fault line. Three-tier pricing structure across premium, standard, and economy levels separates TGA-registered clinical products from private-label pharmacy alternatives and unbranded imports. Price differentiation hinges on dermatological certification tier and volume scale through distributor panels. Cost compression in mid-range lines is intensifying because home care package coordinators face standardized absorbency specifications without flexibility to upgrade. Institutional aged care providers exhibit lowest price sensitivity through multi-year contracts, while self-funding seniors purchasing via subscription platforms show highest elasticity.
Supply Chain Analysis
Superabsorbent polymer feedstock rests on petroleum refining complexes in South Korea, Japan, and Singapore. Chlorine-free pulp draws from Scandinavian and Canadian forestry operations, while elasticized waistband components source from Chinese textile manufacturers. Single-source vulnerability concentrates in SAP resin supply, where three regional petrochemical producers control oceanic freight lanes into Port Botany. Distribution runs through three national medical wholesalers dominating institutional channels, with direct-to-consumer platforms bypassing this layer for self-funding segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by the pivot toward thin-core SAP engineering and skin-health documentation requirements under proposed Aged Care Quality Standards updates. Specification rigor is displacing commodity procurement across Victorian and New South Wales aged care networks.
For Market Incumbents: Lock in multi-year distributor panel contracts before Queensland regional corridor expansion accelerates competitive bidding. Defend against Nordic eco-label challengers by embedding TGA dermatological testing protocols ahead of mandated procurement specification changes. Vertical integration into thin-core SAP manufacturing reduces freight cost exposure per unit. For New Entrants and Emerging Players: The premium-economy price-point gap in Queensland's underserved Brisbane-to-Cairns corridor offers whitespace for specialized distribution partnerships. Target medium-sized residential aged care providers bypassed by national wholesaler concentration. Enter through subscription direct-to-consumer channels capturing self-funding seniors seeking NDIS complexity avoidance. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated hygiene specialists controlling both SAP resin relationships and TGA certification pathways. Five-to-ten year viability favors players with embedded dermatological testing infrastructure rather than pure-brand distributors. Watch for Aged Care Quality Standards finalization as inflection trigger accelerating specification-tier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Thin-Core SAP Engineering Investment | Reduces freight costs per unit and enables distributed fulfillment nodes closer to Queensland regional markets. |
| Dermatological Testing Protocol Embedding | Positions suppliers ahead of Aged Care Quality Standards procurement specification mandates for skin-health documentation. |
| Subscription Direct-to-Consumer Launch | Captures recurring revenue from self-funding seniors prioritizing discretion over NDIS reimbursement optimization. |
| Queensland Distribution Partnership | Addresses whitespace in medium-sized residential aged care facilities between Brisbane and Cairns corridors. |
| TGA Certification Acceleration | Elevates clinically validated products above unregulated imports in pharmacy and aged care channels. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with aged care procurement directors, home care package coordinators, pharmacy category buyers, and TGA regulatory affairs specialists against secondary validation. Sources included TGA medical device registration databases, NDIS operational guideline publications, Australian Bureau of Statistics aged care workforce data, and customs import records for SAP resin and cellulose pulp. Bottom-up facility-level demand aggregation and top-down macroeconomic triangulation anchored market sizing.
Segment-weighting applied differential growth coefficients across product type, end user, distribution channel, and price tier dimensions. Pull-up versus overnight format splits, institutional versus self-funded purchasing patterns, and pharmacy versus digital channel trajectories shaped volume allocation. CAGRs derived from trend extrapolation against policy intervention modeling, with NDIS funding envelope projections and TGA regulatory timeline assumptions as core inputs.
Caveats apply where crude oil price shocks, Aged Care Quality Standards implementation delays, or SAP supply chain disruptions could materially shift the outlook. Forecasts reflect modeling assumptions around policy continuity and input cost stability. A small set of named triggers—petrochemical feedstock spikes, distributor panel consolidation acceleration, and eco-label certification cost inflation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
United States Diaper Market
Baby Diapers
Pet Diapers Market
Baby Diapers
Baby Diapers Market
Baby Diapers
Cat Diapers Market
Baby Diapers
Dog Diapers Market
Baby Diapers
Baby Disposable Diapers Market
Baby Diapers
East Africa Baby Diaper Market
Baby Diapers
Biodegradable Diapers Market
Baby Diapers
Smart Connected Diaper Market
Baby Diapers
North America Diaper Market
Baby Diapers
Europe Diaper Market
Baby Diapers
Baby Cloth Diaper Market
Baby Diapers
Latin America Diaper Market
Baby Diapers
Africa and India Baby Diapers Market
Baby Diapers
Biodegradable Baby Diapers Market
Baby Diapers
Diaper Market