
 Diaper Market | 2026-2036
Diaper Market Size, Share, and Industry Trends Forecast 2026-2036
Diaper Market Intelligence
Subscription-based direct-to-consumer financing is reconfiguring capital requirements for emerging diaper brands, lowering barriers to recurring revenue models without heavy retail slotting investments. Procter & Gamble leverages its manufacturing scale to dominate North American shelf space and secure favorable wholesale terms. Kimberly-Clark sustains R&D intensity in absorbent core technologies, while Unicharm anchors its competitive position through deep channel control across Asian pharmacy networks.
A diaper is an absorbent undergarment engineered with superabsorbent polymer cores, nonwoven topsheets, and elasticized leg cuffs designed to capture bodily waste while maintaining skin dryness and structural integrity during active use. Disposable variants incorporate petroleum-derived polypropylene layers and adhesive fastening systems, whereas cloth alternatives utilize woven cotton or bamboo fibers with snap or hook-and-loop closures for repeated laundering. The adult end-user segment leads absolute value contribution as incontinence stigma declines and specialized retail pharmacy distribution expands access. Biodegradable material formulations represent the fastest-growing structural category, though margin pools remain concentrated in premium disposable tiers where polymer efficiency and thin-core engineering command price premiums.
The EPA regulates volatile organic compound emissions from adhesive and polymer manufacturing facilities supplying diaper components, while REACH restricts certain phthalates and skin-sensitizing chemicals in products distributed across Europe. China's SAMR enforces national standards for infant product safety labeling and absorbent performance claims, creating compliance complexity for multinational suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks for single-use hygiene products, as these policies will determine which material platforms and reverse-logistics investments secure long-term market access.
Market Dynamics
The diaper market's structural evolution pivots on EU Green Deal mandates forcing petroleum-derived polymer substitution with bio-based absorbents, compressing legacy supply chains while opening margin pools for certified sustainable tiers.
Growth Catalysts
- Aging Demographics in Developed Economies:Japan, Germany, and the United States exhibit expanding adult incontinence prevalence as median age exceeds 40 years, creating durable demand for high-capacity absorbent products through pharmacy and institutional channels.
- REACH Chemical Restrictions:ECHA's tightening controls on phthalates and skin-sensitizing additives accelerate R&D investment in plant-derived superabsorbent polymers and cellulose-based acquisition distribution layers.
- China's Birth-Rate Policy Adjustments:SAMR-enforced infant safety standards combined with urban household income expansion sustain premium-tier volume concentration in tier-one and tier-two cities.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and superabsorbent polymer prices fluctuate with crude oil benchmarks, compressing gross margins for manufacturers lacking backward integration into resin production.
- Single-Use Product Stigma:Municipal waste diversion targets in France, Italy, and the Netherlands impose landfill surcharges on synthetic diaper disposal, elevating total cost of ownership for conventional disposable formats.
- Biodegradable Performance Gap:Current bio-based cores exhibit 15-30% lower fluid retention under dynamic loading compared to petroleum-derived SAP, limiting clinical acceptance in heavy-incontinence segments.
Strategic Opportunities
- Subscription Direct-to-Consumer Channels:Recurring revenue models bypass retail slotting fees and capture first-party consumption data, with highest penetration in United Kingdom and Scandinavian urban markets.
- Extended Producer Responsibility Frameworks:France's AGEC law and impending EU-wide hygiene-product EPR schemes create competitive moats for brands with certified compostable supply chains and reverse-logistics infrastructure.
- Smart Diaper Sensor Integration:Convergence of printed electronics with moisture-detection algorithms enables remote monitoring for institutional care settings, with pilot deployments accelerating in Japanese eldercare facilities.
Industry Challenges
- Bio-Polymer Scale-Up Timeline:Commercial-grade bacterial cellulose and alginate-based SAP production requires 3-5 year fermentation facility commissioning, delaying cost parity with petroleum alternatives.
- Cross-Border Labeling Complexity:Divergent infant product safety claims between SAMR's GB standards, FDA 21 CFR requirements, and EU's General Product Safety Regulation fragment packaging and marketing asset development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diaper Market |
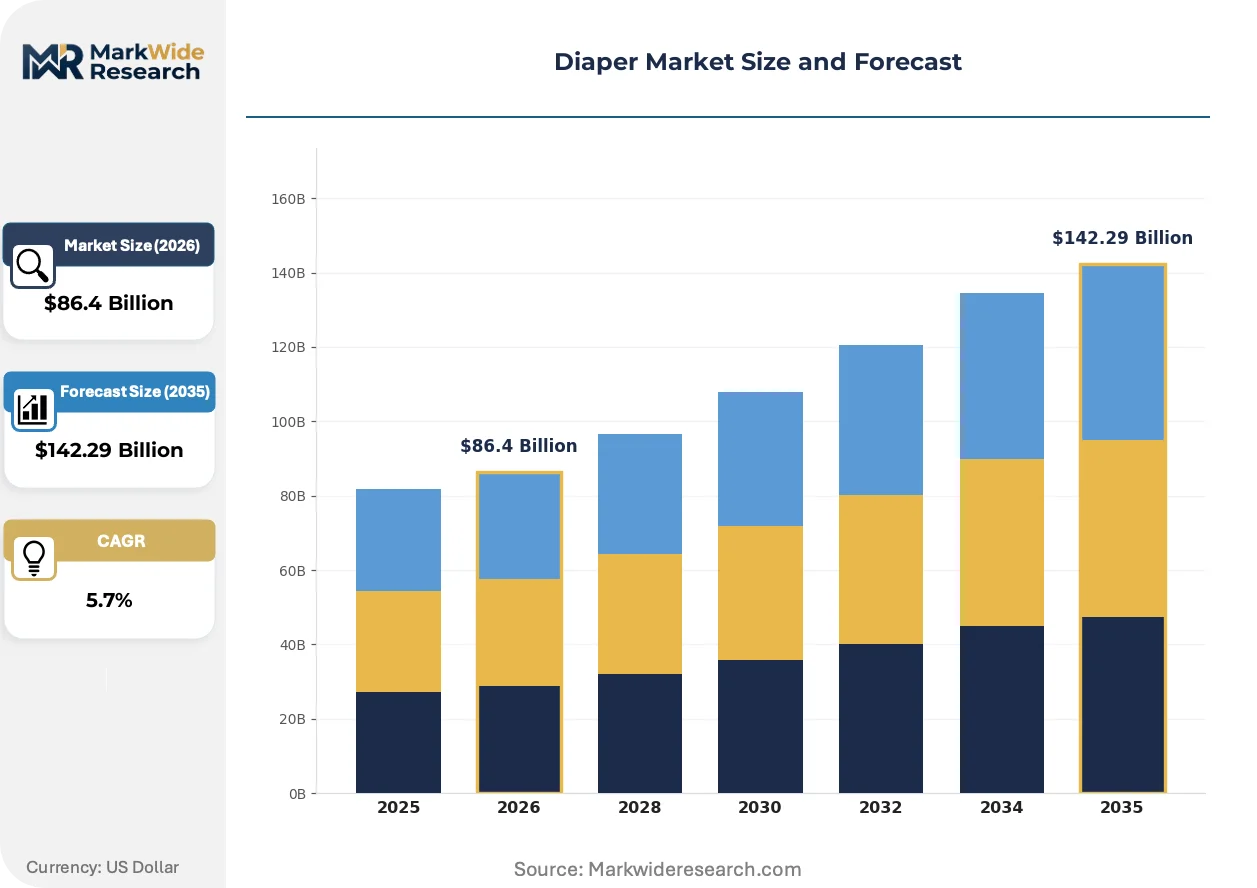
| Market Size in 2026 | $86.4 Billion |
| Market Size in 2035 | $142.29 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Cloth, Training Pants, Swim Diapers End User: Infants, Toddlers, Special Needs, Adults Material: Polyester, Cotton, Biodegradable, Composite Distribution Channel: Supermarkets, Online Retail, Pharmacies, Specialty Stores |
| Companies Covered | Procter & Gamble, Kimberly-Clark, Unicharm, Essity AB, Ontex International, Kao Corporation, Hengan International Group, Domtar Corporation, The Honest Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diaper Market Strategic Shifts & Innovations
Material science convergence with digital health integration is fragmenting traditional absorbent hygiene into condition-specific, data-enabled product categories that command subscription premiums and displace commoditized shelf-stable formats.
Plant-derived superabsorbent technology is hybridizing petroleum and bio-based polymer matrices to maintain fluid retention while satisfying EU Green Deal biodegradability thresholds. Adult incontinence manufacturers in Germany and the Netherlands are piloting these hybrid cores at 15-20% premium price points. The technology is compressing conventional SAP suppliers into specialty chemical partnerships or vertical integration into fermentation-based production.
REACH Annex XVII restrictions on skin-sensitizing chemicals are forcing reformulation of adhesive and lotion components across European diaper supply chains. Industrial consequence includes 18-24 month product recertification cycles and accelerated supplier consolidation toward ECHA-registered chemical houses. Infant diaper tiers face the steepest compliance burden, with German and French pharmacy channels now requiring full material disclosure for shelf placement.
Institutional procurement in Japanese eldercare facilities is unbundling diaper supply from comprehensive hygiene service contracts, creating spot-market purchasing for performance-tier products. Traditional distributors in the Osaka and Tokyo metropolitan corridors are losing share to manufacturer-direct tenders and GPO-negotiated frameworks. This pattern is most visible in for-profit nursing home chains where occupancy pressure demands unit-cost transparency.
Diaper Market Segmentation
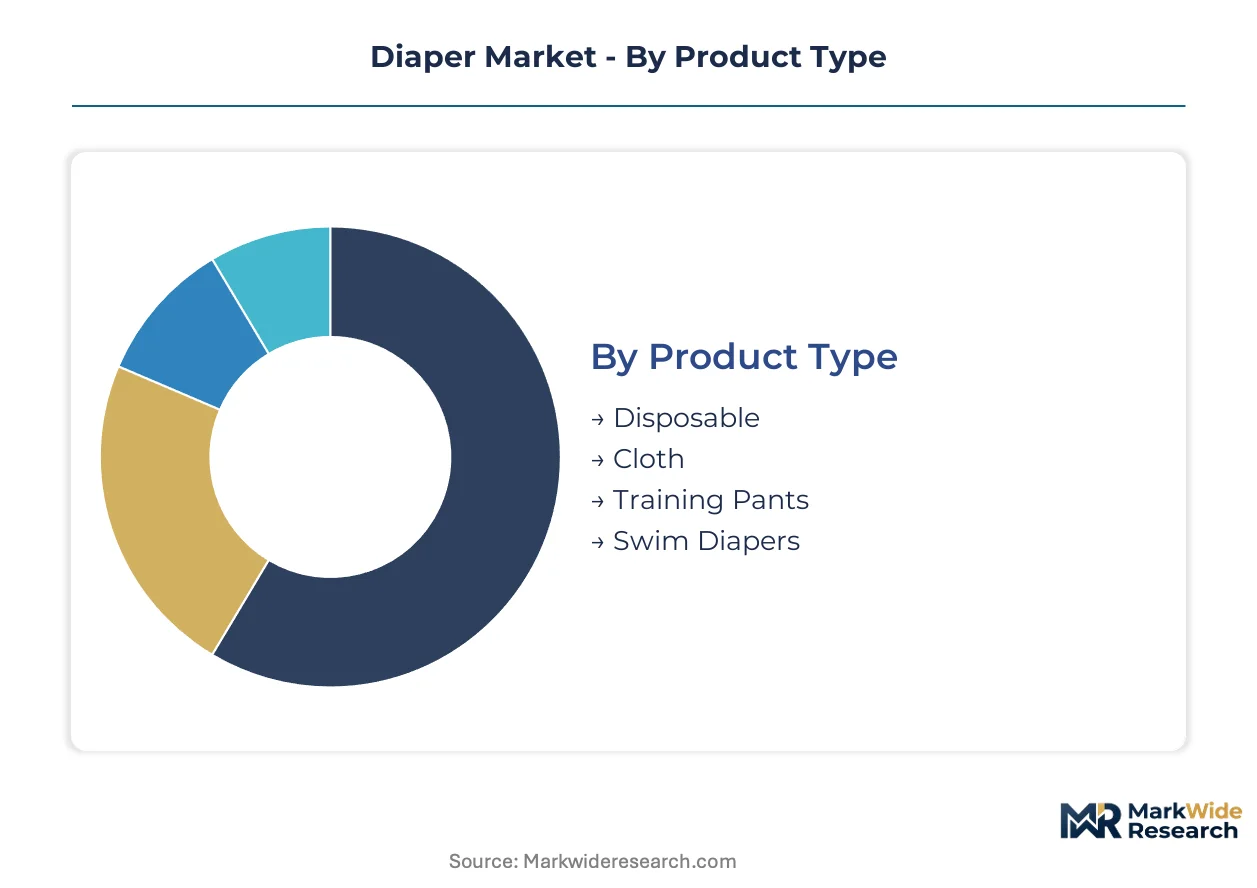
Diaper market segmentation reveals divergent margin profiles across material platforms and channel economics. Manufacturers configure production assets around end-user physiology and regulatory compliance requirements rather than unified scale economies.
Product Type:
Mature formats dominate absolute volume while emerging variants capture premium positioning through functional specialization.
- Disposable:Multi-layer construction bonds superabsorbent polymer cores with nonwoven topsheets and elasticized leg cuffs for single-use waste containment. Demand concentrates in urban China and the United States where dual-income households prioritize convenience over laundering labor.
- Cloth:Woven cotton or bamboo fiber assemblies with snap or hook-and-loop closures enable repeated washing cycles. German and Dutch municipalities subsidize reusable formats through waste diversion incentives, compressing total cost of ownership gaps against disposables.
- Training Pants:Pull-up designs with tear-away side seams transition toddlers from diapers to underwear. Elastic waistbands accommodate motor skill development stages.
- Swim Diapers:Non-absorbent mesh linings contain solid waste without swelling in aquatic environments. Seasonal demand spikes concentrate in Australian and Floridian coastal markets.
Disposable handles the majority of throughput; biodegradable hybrids are the fastest mover on share.
End User:
Application-driven segmentation separates institutional procurement from household purchasing patterns.
- Adults:High-capacity absorbent cores address urinary and fecal incontinence with gender-specific anatomical shaping. Japanese eldercare facilities and German pharmacy networks drive category expansion as median age exceeds 45 years in both markets.
- Infants:Newborn-specific designs incorporate umbilical cord cutouts and wetness indicators. SAMR-enforced safety standards in China elevate compliance costs for imported brands.
- Toddlers:Active-movement engineering reinforces standing and walking mobility with flexible chassis designs. Daycare procurement in France and Italy favors bulk formats.
- Special Needs:Extended-size ranges and reinforced fastening systems accommodate adolescent and adult users with developmental disabilities. Medicaid reimbursement in the United States determines accessible pricing tiers.
Adult incontinence commands the highest per-unit pricing; infant tiers expand most quickly in absolute volume.
Material:
Cost tier stratification separates petroleum-dependent supply chains from certified sustainable alternatives.
- Biodegradable:Bacterial cellulose and alginate-based superabsorbent polymers decompose under industrial composting conditions. EU Green Deal mandates accelerate pilot production in the Netherlands and Germany despite 15-30% fluid retention deficits versus petroleum SAP.
- Polyester:Petroleum-derived polypropylene and polyethylene nonwoven layers deliver cost-efficient liquid acquisition and distribution. Crude oil price volatility compresses margins for manufacturers lacking captive resin supply.
- Cotton:Natural fiber topsheets and acquisition layers reduce dermatological irritation in sensitive-skin segments. Organic certification commands 20-25% shelf price premiums in United Kingdom pharmacy channels.
- Composite:Hybrid matrices blend bio-based and synthetic polymers to balance biodegradability thresholds with performance specifications. REACH Annex XVII compliance drives reformulation timelines.
Polyester handles the majority of throughput; biodegradable platforms are gaining share fastest.
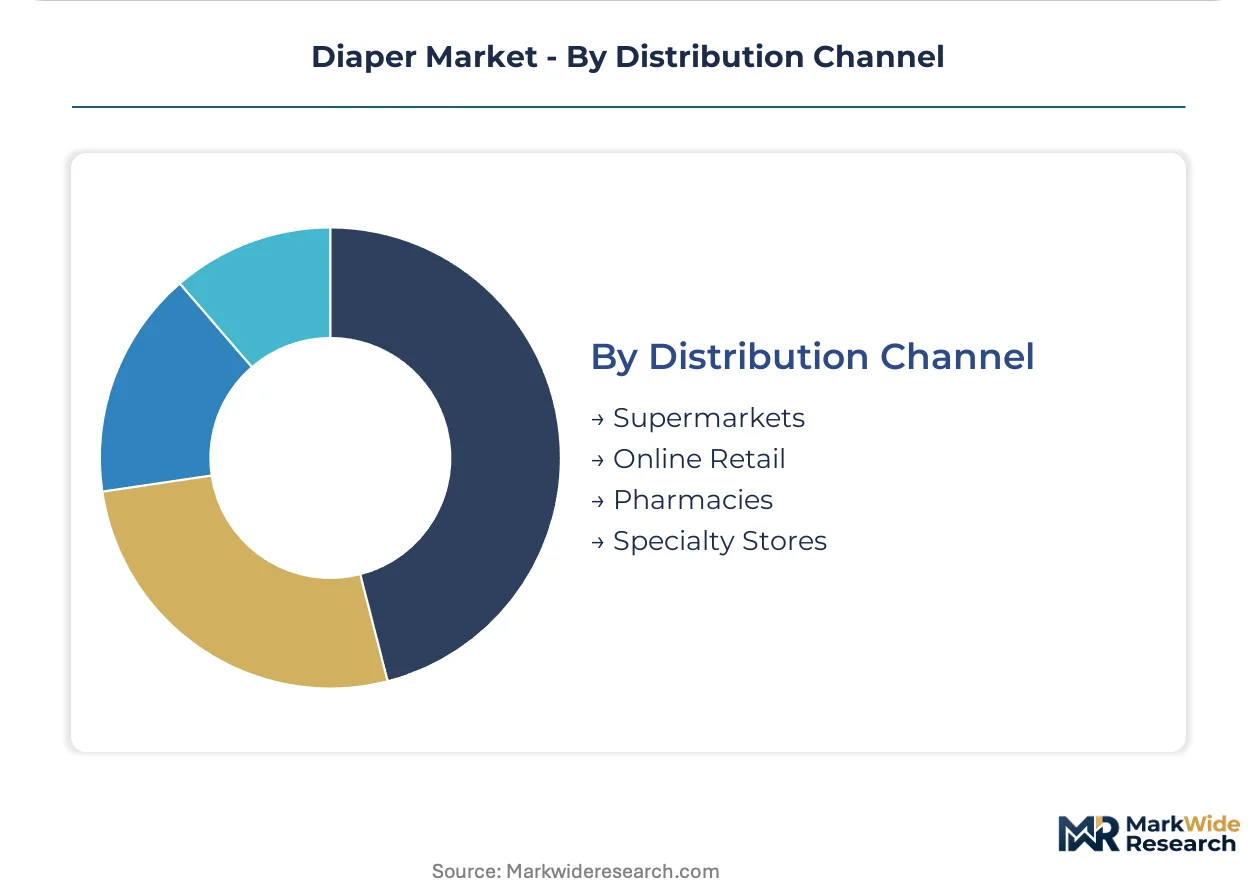
Distribution Channel:
Channel concentration patterns reflect urbanization density and regulatory access requirements.
- Pharmacies:Professional recommendation environments support incontinence product discretion and insurance reimbursement processing. German and French networks require ECHA-registered material disclosure for shelf placement.
- Online Retail:Subscription models bypass retail slotting fees and capture first-party consumption data. United Kingdom and Scandinavian urban markets show highest recurring revenue penetration.
- Supermarkets:Mass-market infant diaper volume concentrates in hypermarket chains across Chinese tier-one cities. Slotting fee structures favor manufacturers with manufacturing scale.
- Specialty Stores:Boutique formats curate organic and eco-certified assortments for environmentally conscious households. Premium positioning in Australian and Canadian metropolitan corridors.
Supermarkets handle the majority of throughput; online retail is climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal mandates and REACH Annex XVII restrictions on skin-sensitizing chemicals are redirecting manufacturing investment toward bio-based polymer platforms across developed economies. China's SAMR infant safety standards and birth-rate policy adjustments sustain premium-tier demand concentration. Japan's eldercare procurement reforms unbundle diaper supply from comprehensive hygiene contracts.
United States
Medicaid reimbursement frameworks determine accessible pricing for adult incontinence products through institutional pharmacy channels. FDA 21 CFR labeling requirements fragment compliance timelines against EU and Chinese standards. Manufacturing scale concentrates in the Midwest corridor where petrochemical feedstock access supports superabsorbent polymer production.
Germany
AGEC extended producer responsibility law imposes reverse-logistics requirements on single-use hygiene products distributed through pharmacy networks. ECHA-registered material disclosure is now mandatory for shelf placement in Berlin and Frankfurt metropolitan retail corridors. Bacterial cellulose pilot facilities in the Rhine-Ruhr industrial cluster are scaling hybrid bio-polymer production.
China
Urban household income expansion in tier-one and tier-two cities sustains premium infant diaper volume concentration. SAMR enforces GB standards for absorbent performance claims and safety labeling that elevate compliance costs for imported brands. Yangtze River Delta manufacturing clusters integrate superabsorbent polymer production with nonwoven fabric assembly.
Japan
Median age exceeding 45 years drives durable demand for high-capacity adult incontinence products through pharmacy and eldercare channels. METI procurement guidelines unbundle diaper supply from comprehensive hygiene service contracts in for-profit nursing home chains. Osaka and Tokyo metropolitan distributors are losing share to manufacturer-direct tenders and GPO-negotiated frameworks.
Netherlands
Municipal waste diversion targets impose landfill surcharges on synthetic diaper disposal, elevating total cost of ownership for conventional disposable formats. EU Green Deal biodegradability thresholds accelerate pilot production of alginate-based superabsorbent polymers in Rotterdam chemical corridors. Dutch pharmacy networks subsidize reusable cloth formats through circular economy incentive programs.
Diaper Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented procurement environments. The vendor base separates into three strategic archetypes: multinational consumer goods conglomerates with manufacturing scale, regional hygiene specialists with pharmacy network penetration, and direct-to-consumer subscription platforms with first-party data capture. Competitive moves concentrate on backward integration into resin production and strategic partnerships with bio-polymer fermentation facilities.
Within the multinational tier, Procter & Gamble and Kimberly-Clark occupy positions anchored by North American retail shelf space dominance and absorbent core R&D intensity respectively. Unicharm exemplifies the Asia-Pacific pharmacy-channel archetype through deep distribution control across Japanese and Southeast Asian markets. Essity AB and Ontex International represent the European specialist configuration, with corporate structures organized around institutional procurement and private-label manufacturing.
| Leading Market Players |
|---|
| Procter & Gamble |
| Kimberly-Clark |
| Unicharm |
| Essity AB |
| Ontex International |
| Kao Corporation |
| Hengan International Group |
| Domtar Corporation |
| The Honest Company |
| Others |
Cost & Logistics Intelligence
Superabsorbent polymer production clusters in the Yangtze River Delta and US Gulf Coast petrochemical corridors concentrate upstream margin capture, forcing finished goods manufacturers to compete on subscription pricing models and pharmacy channel rebates rather than raw material arbitrage.
Pricing Analysis
Certification level creates the primary spread across EU pharmacy networks, where ECHA-registered material disclosure commands 15-20% shelf price premiums over conventional tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by biodegradability certification and absorbent core performance ratings. Pricing pressure stems from REACH Annex XVII reformulation costs compressing mid-tier margins. Institutional procurement in Japanese eldercare facilities exhibits lowest price sensitivity, while mass-market infant tiers in Chinese hypermarkets face acute cost compression.
Supply Chain Analysis
REACH chemical restrictions and EU Green Deal biodegradability mandates function as de facto export controls on petroleum-derived superabsorbent polymers, limiting conventional material flows into European pharmacy channels. Manufacturing concentrates in China, the United States, and Germany, with bacterial cellulose pilot facilities scaling in the Netherlands. Supply chains draw from polypropylene resin, nonwoven fabric, and adhesive chemical inputs. Single-source vulnerability runs through concentrated petrochemical feedstock suppliers. Distribution runs through pharmacy networks in developed economies and hypermarket chains in urban China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diaper market is entering a high-growth disruption phase as EU Green Deal mandates and smart sensor integration fragment traditional absorbent hygiene into data-enabled, condition-specific categories with subscription pricing power.
For Market Incumbents: Build reverse-logistics infrastructure moats around certified compostable supply chains to capture AGEC law and impending EU-wide EPR scheme advantages. Secure captive supply of bacterial cellulose through fermentation facility partnerships or in-house production investments. Deepen pharmacy channel control in Germany and France where material disclosure requirements consolidate shelf access. For New Entrants and Emerging Players: Subscription direct-to-consumer channels in United Kingdom and Scandinavian urban markets represent the most penetrable entry point, bypassing retail slotting fees and capturing first-party consumption data. Target biodegradable hybrid cores at 15-20% premium positioning where fluid retention performance gaps are narrowing. Deploy smart diaper sensor integration as a differentiated go-to-market angle for institutional eldercare procurement. For Investors and Strategic Acquirers: Capital is best deployed toward bio-polymer fermentation specialists with 3-5 year commercial-grade scale-up timelines and ECHA-registered chemical houses consolidating under REACH Annex XVII pressure. Long-term viability hinges on extended producer responsibility framework compliance and certified compostable supply chain certification. Monitor pilot deployment velocity of moisture-detection algorithms in Japanese eldercare facilities as inflection indicator for smart diaper category formation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Polymer Production | Fermentation facility partnerships in Rotterdam and Rhine-Ruhr corridors secure EU Green Deal compliance and margin capture. |
| Subscription Direct-to-Consumer Launch | Recurring revenue models in United Kingdom and Scandinavian markets bypass retail slotting fees and capture consumption data. |
| Smart Sensor Technology Integration | Printed electronics convergence with moisture-detection algorithms enables remote monitoring premiums in Japanese eldercare. |
| Extended Producer Responsibility Compliance | Certified compostable supply chains and reverse-logistics infrastructure create competitive moats under France's AGEC law. |
| Pharmacy Network Distribution Expansion | ECHA-registered material disclosure requirements in Berlin and Frankfurt metropolitan corridors consolidate shelf access. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brand managers, category buyers at retailers, channel sales heads, and supply planners across diaper manufacturers and pharmacy networks. Secondary validation drew from customs and trade data, SEC 10-K filings, ECHA chemical registration databases, and Nielsen retail audit data. Bottom-up volume modeling and top-down value triangulation were cross-referenced for consistency.
Calibration against historical absorption patterns and regulatory implementation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, end-user physiology, material platform certification, and distribution channel type. CAGRs were derived from fitted growth curves adjusted for policy inflection points. Forecast inputs incorporated REACH Annex XVII reformulation timelines and SAMR infant safety standard enforcement intensity.
Practitioners should monitor bio-polymer scale-up velocity and extended producer responsibility framework adoption for early signals of supply chain restructuring. Forecasts reflect assumptions around petrochemical feedstock price bands and biodegradability performance gap closure rates. Material shifts in EU Green Deal enforcement stringency or smart diaper sensor clinical validation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
Cat Diapers Market
Baby Diapers
GCC Diaper Market
Baby Diapers
Middle East and Africa and Asia Pacific Baby Diaper Market
Baby Diapers
Biodegradable Diapers Market
Baby Diapers
Reusable Baby Diapers and Training Pants Market
Baby Diapers
Malaysia Diapers Market
Baby Diapers
Dog Diapers Market
Baby Diapers
Baby Diaper Manufacturing Machine Market
Baby Diapers
Baby Disposable Diapers Market
Baby Diapers
Latin America Diaper Market
Baby Diapers
East Africa Baby Diaper Market
Baby Diapers
United Arab Emirates Baby Diapers and Wipes Market
Baby Diapers
Mexico Pant Type Adult Diaper Market
Baby Diapers
UAE Baby Diapers Industry Market
Baby Diapers
Nonwoven Baby Diaper Market
Baby Diapers
Australia Pant Type Adult Diaper Market