
 Biodegradable Diapers Market | 2026-2036
Biodegradable Diapers Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Diapers Market Intelligence
ASTM D6400 and EN 13432 compostability certification is bifurcating the competitive landscape into qualified incumbents and uncertified challengers. The Honest Company leverages its DTC subscription model to sustain repeat purchase rates among environmentally conscious households. GroVia anchors its position through vertical control over bamboo fiber sourcing and domestic cut-and-sew operations. Kimberly-Clark competes by extending its conventional diaper manufacturing scale into plant-based polymer pilot lines.
Biodegradable diapers are absorbent hygiene products constructed with bamboo fiber cores, wood pulp acquisition layers, and plant-based backsheet films designed to decompose under industrial composting conditions within 90 to 180 days. Their primary commercial purpose is to replace petroleum-based disposables in markets where landfill diversion mandates and parental environmental preferences converge. The material dimension shows bamboo and plant-based polymers capturing margin pools as cotton struggles with water-intensive cultivation reputational risk. End-user segmentation reveals adult incontinence emerging as a faster-growing application than infant care, driven by aging demographics in Japan and Western Europe.
The EPA regulates absorbent hygiene products through landfill leachate standards, while the EU F-Gas Regulation and REACH restrict fluorinated water-repellent treatments in diaper backsheet films. These frameworks force reformulation of conventional moisture barriers and create compliance costs that favor larger producers with dedicated regulatory affairs teams. Stakeholders must monitor composting infrastructure build-out rates, as certified biodegradability delivers zero environmental benefit without industrial composting facility access.
Market Dynamics
REACH compliance deadlines and the EU F-Gas Regulation are forcing wholesale reformulation of petroleum-based superabsorbent polymers, concentrating competitive advantage among manufacturers with captive regulatory affairs capabilities and certified composting partnerships.
Growth Catalysts
- EU Green Deal procurement mandates:Public healthcare systems across Germany, France, and the Netherlands now specify EN 13432 certification in tender documents, redirecting institutional purchasing toward verified biodegradable alternatives.
- Millennial parental cohort expansion:First-time parents born between 1981 and 1996 demonstrate elevated willingness-to-pay premiums for bamboo fiber and plant-based backsheet films, particularly in urban coastal markets.
- Industrial composting infrastructure build-out:Municipal facilities in Austria, Belgium, and Sweden now accept certified infant hygiene products, closing the disposal loop that previously undermined environmental claims.
Market Restraints
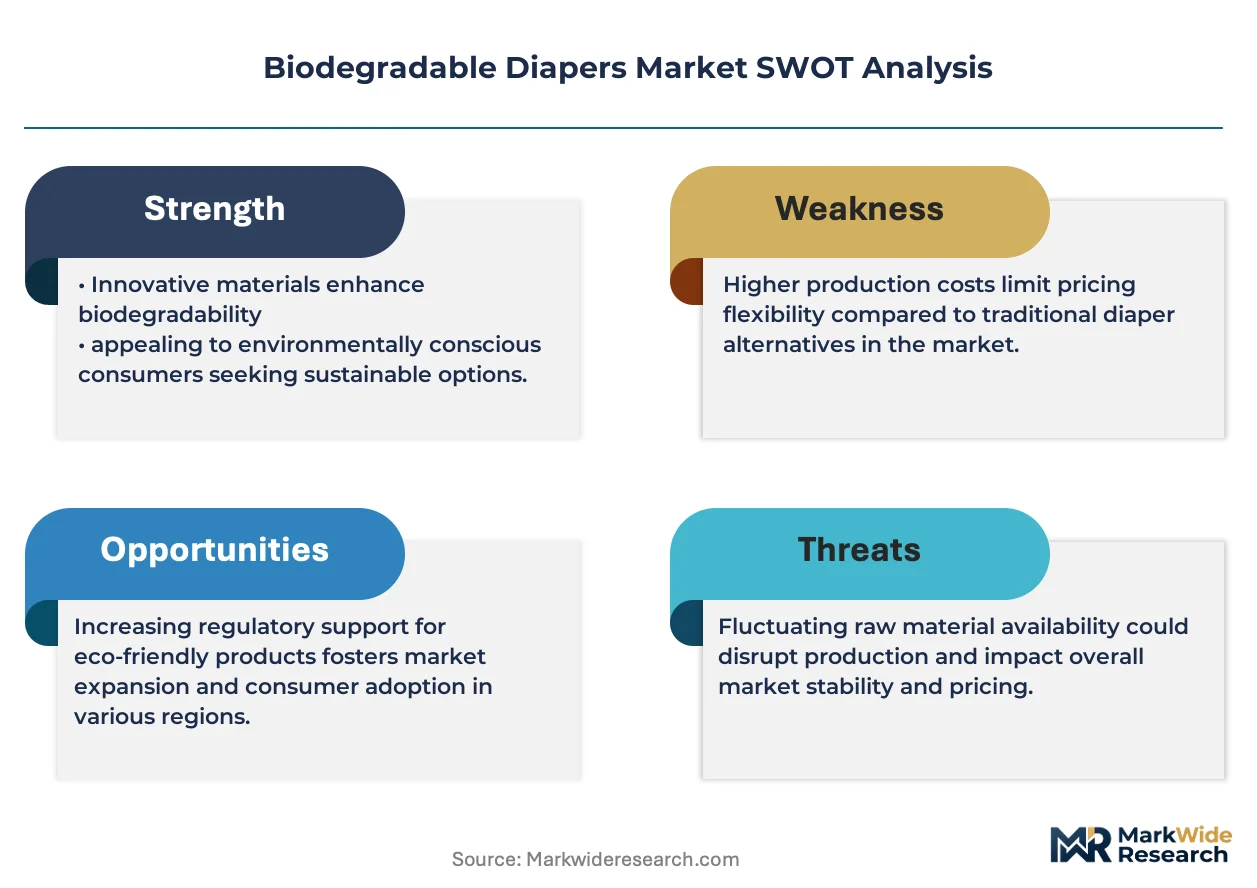
- Bamboo fiber supply concentration:Raw material sourcing clusters in China's Sichuan and Yunnan provinces, exposing converters to weather-induced harvest volatility and export quota uncertainty.
- Petroleum-based polymer cost asymmetry:Conventional superabsorbent polymers derived from acrylic acid maintain 40-60% cost advantages over plant-based alternatives, compressing margin recovery in mass-market tiers.
- ASTM D6400 certification timeline:Laboratory testing and field validation cycles extend 18-24 months, creating capital lockup that disadvantages smaller entrants against scaled incumbents.
Strategic Opportunities
- Adult incontinence application expansion:Aging demographics in Japan, Germany, and Italy generate demand for biodegradable absorbent hygiene products in institutional care settings where procurement officers face landfill diversion targets.
- Subscription direct-to-consumer channel maturation:Recurring revenue models bypass traditional retail slotting fees and build predictable demand signals for raw material procurement.
- Carbon border adjustment mechanism alignment:EU importers of conventional diapers face embedded emissions accounting from 2026, tilting landed cost economics toward regional biodegradable production.
Industry Challenges
- Composting facility access fragmentation:Post-consumer disposal requires household proximity to industrial composting sites, creating geographic service gaps that undermine product value propositions in rural and suburban catchments.
- Cross-contamination in waste streams:Co-collection with conventional plastics in municipal bins degrades biodegradable materials before processing, requiring consumer education investments that dilute marketing budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Diapers Market |
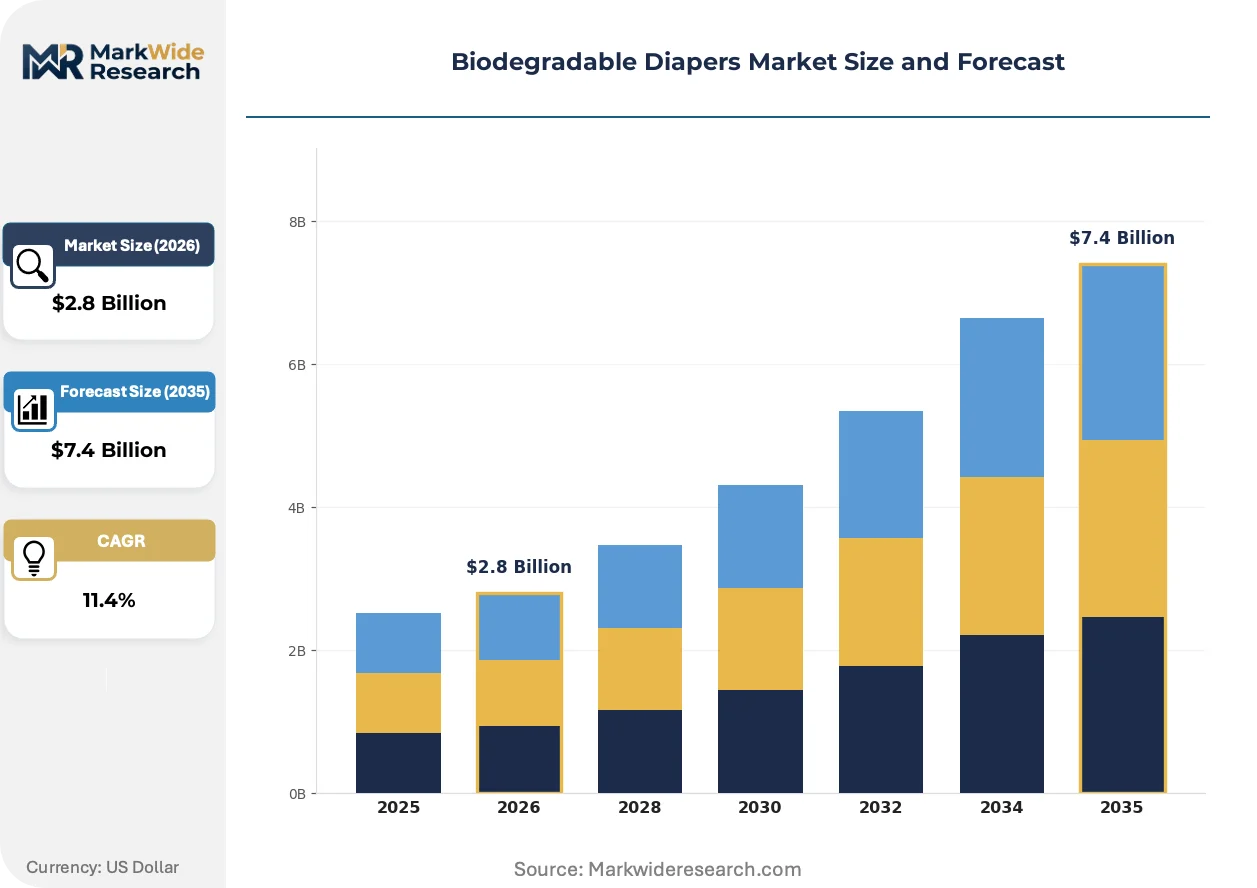
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloth, Biodegradable, Organic, Reusable Material: Cotton, Bamboo, Wood Pulp, Plant-Based Polymers End User: Infants, Toddlers, Special Needs, Adult Incontinence Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | The Honest Company, GroVia, Bamboo Nature, Earth's Best, Pampers, Seventh Generation, Naty, Dyper, Kimberly-Clark, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Diapers Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry restrictions are compressing reformulation cycles across the absorbent hygiene supply base. Three developments warrant particular attention from stakeholders positioning for the 2026-2035 window.
Bio-based superabsorbent polymers synthesized from itaconic acid and starch derivatives are bifurcating the raw material tier. Premium infant care brands in Germany and the Netherlands have converted pilot lines to these inputs, while mass-market manufacturers delay adoption pending cost curve improvements. This technology is bifurcating supplier relationships into exclusive bio-polymer partnerships versus conventional petroleum contracts.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances (PFAS) are eliminating fluorinated water-repellent treatments from diaper backsheet films. German and French manufacturers face 2025 compliance deadlines, accelerating R&D investment in silicone-based and paraffin alternatives. The infant care segment bears disproportionate adjustment costs due to stringent skin-contact safety requirements that limit substitute options.
Certification-driven preference formation is redirecting household purchasing toward third-party verified products. Parents in Scandinavian markets now filter e-commerce searches by EN 13432 or TÜV Austria OK Compost INDUSTRIAL labels, displacing brand loyalty as the primary selection heuristic. This behavioral shift concentrates volume among qualified manufacturers while marginalizing uncertified challengers in premium positioning attempts.
Biodegradable Diapers Market Segmentation
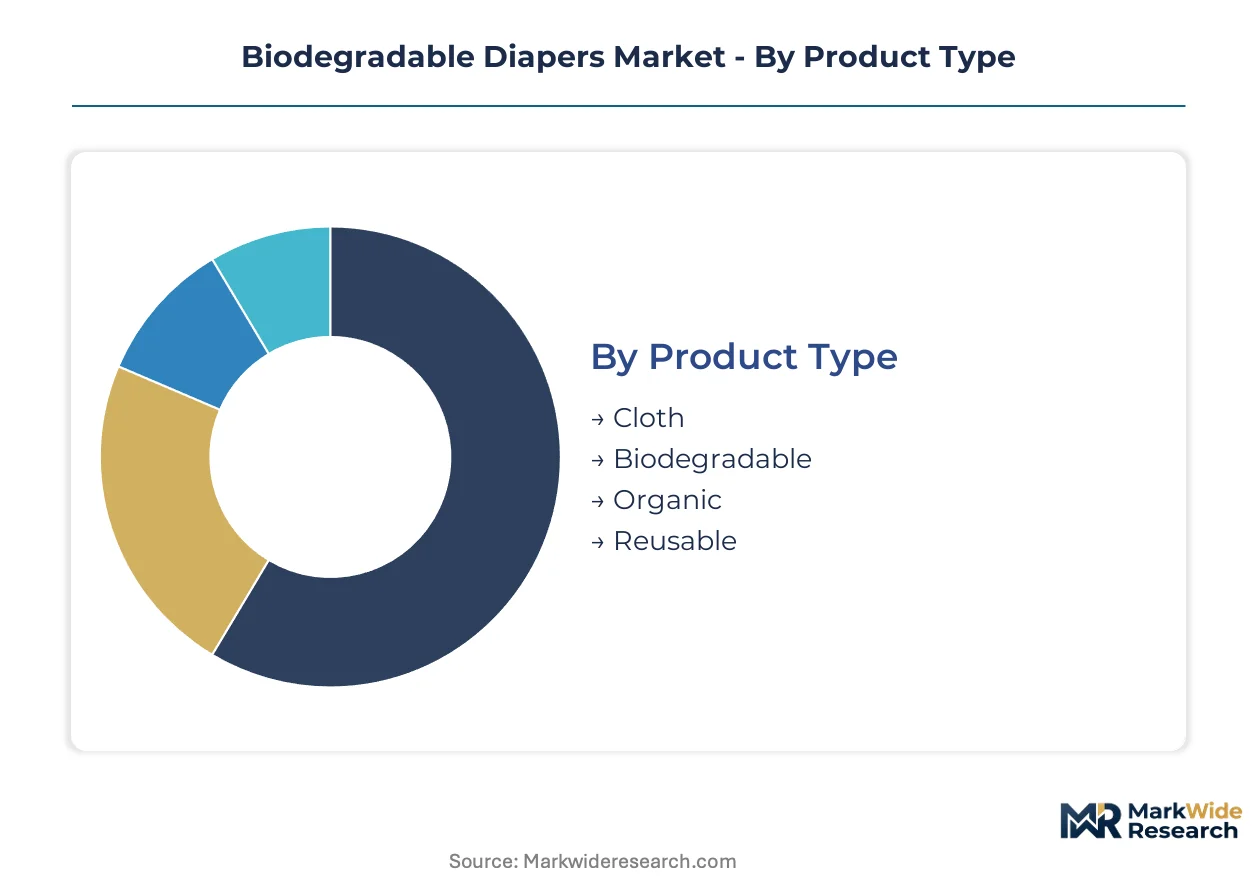
Segmentation in biodegradable diapers reveals how certification requirements and composting infrastructure access reshape channel economics. Manufacturers must align product specifications with disposal capabilities in each geographic market.
Product Type:
Channel mix varies sharply by product format, with subscription services favoring biodegradable and organic variants while mass retail retains cloth and reusable penetration.
- Biodegradable:Constructed with bamboo fiber cores and plant-based backsheet films certified to ASTM D6400 or EN 13432 standards. Demand concentrates in Germany, Austria, and the Netherlands where municipal composting infrastructure supports post-consumer disposal. EU Green Deal procurement mandates in public healthcare systems accelerate institutional purchasing.
- Organic:Uses GOTS-certified cotton and excludes synthetic chemical treatments. Premium positioning in Scandinavian markets and urban coastal US cities attracts millennial parents with elevated willingness-to-pay. REACH compliance requirements for skin-contact materials elevate production costs.
- Cloth:Traditional woven cotton designs requiring laundering infrastructure. Retains volume in price-sensitive segments and regions with limited composting facility access.
- Reusable:Hybrid designs combining washable covers with biodegradable inserts. Emerging traction among zero-waste consumer communities in France and Belgium.
Biodegradable dominates installed base in markets with composting infrastructure. Organic is where expansion concentrates among premium urban households.
Material:
Cost tier stratification separates commodity inputs from certified sustainable alternatives, with margin pools shifting toward controlled-origin bamboo and bio-polymer supply chains.
- Bamboo:Rapid-renewable grass fiber with superior absorbency and lower water footprint than cotton. Sourcing clusters in China's Sichuan and Yunnan provinces expose converters to harvest volatility and export quota uncertainty. GroVia and similar manufacturers pursue backward integration through direct plantation partnerships.
- Plant-Based Polymers:Starch-derived and itaconic acid-based superabsorbent polymers replacing petroleum-based acrylic acid. German and Dutch pilot lines have converted, while mass-market manufacturers await cost curve improvements. EU F-Gas Regulation and REACH restrictions on fluorinated treatments accelerate R&D investment.
- Cotton:Conventional natural fiber facing reputational pressure from water-intensive cultivation. Retains cost advantage in economy-tier positioning.
- Wood Pulp:Acquisition layer material from certified sustainable forestry. Price volatility tracks packaging industry demand cycles.
Bamboo dominates installed base among certified sustainable producers. Plant-based polymers are where expansion concentrates as petroleum cost asymmetries narrow.
End User:
Application maturity diverges sharply, with infant care representing established volume and adult incontinence emerging as the steepest expansion trajectory.
- Adult Incontinence:Absorbent hygiene products for aging populations in institutional care settings. Japan, Germany, and Italy drive demand as procurement officers face landfill diversion targets. EN 13432 certification increasingly specified in tender documents.
- Infants:Core market for first-time parents seeking environmental alternatives. Subscription direct-to-consumer channels capture repeat purchase loyalty among millennial cohorts in North America and Western Europe.
- Toddlers:Transition-phase products with reduced absorbency requirements. Lower per-unit pricing compresses margin recovery for bio-based material costs.
- Special Needs:Customized sizing and absorbency for pediatric medical applications. Smaller addressable market with specialized distribution through medical supply channels.
Infant applications dominate installed base. Adult incontinence is where expansion concentrates as demographic aging accelerates across developed economies.
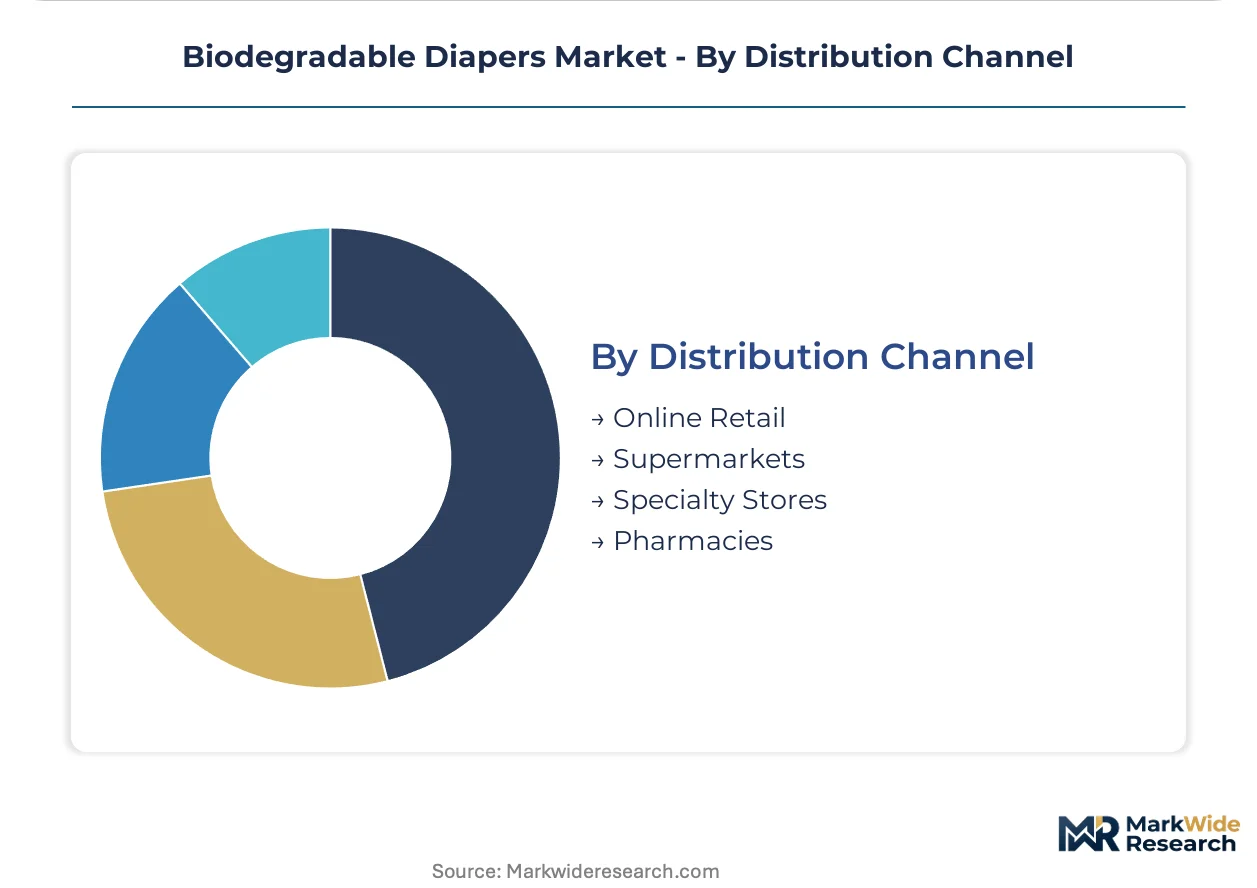
Distribution Channel:
Customer type stratification separates subscription-committed environmental advocates from transactional retail purchasers, with channel choice correlating to certification awareness.
- Online Retail:Direct-to-consumer subscription models bypass traditional slotting fees and build predictable demand signals. Parents in Scandinavian markets filter searches by EN 13432 or TÜV Austria OK Compost INDUSTRIAL labels, displacing brand loyalty as primary selection heuristic.
- Specialty Stores:Curated brick-and-mortar environments with educated staff explaining composting requirements and certification differences. Concentrated in urban centers with adjacent industrial composting facilities.
- Supermarkets:Mass-market volume with limited shelf space for certified variants. Conventional petroleum-based alternatives retain price advantage in this channel.
- Pharmacies:Medical-adjacent positioning for adult incontinence and special needs segments. Institutional procurement relationships leverage existing healthcare supply contracts.
Online retail dominates installed base among certified biodegradable volume. Specialty stores are where expansion concentrates as consumer education requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal procurement mandates and municipal composting infrastructure build-out are redirecting demand toward certified biodegradable alternatives in select developed economies. National regulations on landfill diversion and superabsorbent polymer chemistry are creating divergent market access conditions across major consuming countries.
Germany
Public healthcare procurement officers specify EN 13432 certification in tender documents for institutional adult incontinence products. The EU F-Gas Regulation and REACH Annex XVII restrictions force reformulation of conventional moisture barriers by 2025. Municipal composting facilities in Bavaria and Baden-Württemberg now accept certified infant hygiene products, closing the post-consumer disposal loop.
United States
Millennial parental cohorts in urban coastal markets demonstrate elevated willingness-to-pay premiums for bamboo fiber and plant-based backsheet films. EPA landfill leachate standards regulate absorbent hygiene product disposal without mandating biodegradability. Subscription direct-to-consumer channels concentrate in California and New York Metro, bypassing traditional retail slotting fees.
Japan
Aging demographics drive adult incontinence applications faster than infant care, with procurement officers in institutional settings facing landfill diversion targets. METI industrial standards and municipal waste management policies shape product specification requirements. The Kansai region around Osaka anchors demand concentration for certified absorbent hygiene in eldercare facilities.
Netherlands
Municipal composting infrastructure in the Randstad corridor supports post-consumer disposal of certified-biodegradable infant products. EU Green Deal alignment redirects institutional purchasing toward verified alternatives. Amsterdam and Rotterdam harbor logistics clusters facilitate bio-based polymer import and conversion operations for regional distribution.
Sweden
Industrial composting facility access in Stockholm and Gothenburg metropolitan areas enables complete disposal loop closure for certified products. National waste hierarchy regulations prioritize landfill diversion for absorbent hygiene categories. Consumer filtering of e-commerce searches by TÜV Austria OK Compost INDUSTRIAL labels displaces brand loyalty as primary selection heuristic.
Biodegradable Diapers Market Key Industry Players
Player mix skews toward vertically integrated natural fiber specialists and scaled hygiene conglomerates with regulatory affairs capabilities. Market structure concentrates among manufacturers with ASTM D6400 or EN 13432 certification and established composting partnerships. Three archetypes dominate: bamboo fiber converters with plantation supply control, petroleum-based incumbents piloting plant-based polymer lines, and subscription-native direct-to-consumer brands. Competitive moves center on backward integration into raw material sourcing and exclusive bio-polymer partnerships with starch derivative suppliers.
Within the certified sustainable tier, The Honest Company and GroVia exemplify divergent strategic positions. The Honest Company occupies the subscription-native archetype, leveraging recurring revenue models to build predictable demand signals and repeat purchase loyalty. GroVia anchors the vertical supply control archetype through direct partnerships in bamboo fiber sourcing regions. Kimberly-Clark represents the scaled incumbent pivot, extending conventional manufacturing infrastructure into plant-based polymer pilot operations while maintaining mass-market distribution reach.
| Leading Market Players |
|---|
| The Honest Company |
| GroVia |
| Bamboo Nature |
| Earth's Best |
| Pampers |
| Seventh Generation |
| Naty |
| Dyper |
| Kimberly-Clark |
| Others |
Cost & Logistics Intelligence
Plant-based superabsorbent polymer substitution for petroleum-derived acrylic acid simultaneously redistributes manufacturing gravity toward European pilot facilities and compresses margin recovery timelines for mass-market tier producers. This input transition amplifies pricing power for converters with captive bio-polymer partnerships while exposing uncertified challengers to cost asymmetry pressures.
Pricing Analysis
Certification level creates the primary spread between ASTM D6400 or EN 13432 qualified products and uncertified alternatives. Three-tier pricing structure across premium subscription, standard retail, and economy private-label levels stratifies the market. Cost compression in the mass-market tier intensifies because petroleum-based superabsorbent polymers maintain substantial input cost advantages. Institutional procurement officers in German healthcare systems demonstrate lowest price sensitivity, while suburban US households with limited composting access exhibit highest elasticity.
Supply Chain Analysis
China anchors bamboo fiber cultivation across Sichuan and Yunnan provinces, while Germany and the Netherlands host bio-polymer conversion pilot operations. Raw material procurement draws from grass fiber harvests, starch derivative feedstocks, and certified sustainable wood pulp. Single-source vulnerability concentrates in Chinese bamboo export quotas subject to weather-induced harvest volatility. Distribution runs through direct-to-consumer subscription platforms, specialty retail channels, and institutional procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable diapers function as a subscription-attach business where recurring revenue models expand faster than per-unit transactional sales. Composting infrastructure partnerships and certification compliance services represent the fastest-growing after-sales layers.
For Market Incumbents: Shield market position by securing exclusive bio-polymer supply contracts with itaconic acid derivative producers before cost curve improvements democratize access. Deepen backward integration into bamboo plantation partnerships to neutralize Chinese export quota volatility. Prioritize regulatory affairs team expansion to navigate REACH Annex XVII and EU F-Gas compliance deadlines.
For New Entrants and Emerging Players: Subscription-native customer education services present an underexploited layer where scaled incumbents underinvest in composting guidance and certification explanation. Target adult incontinence procurement officers in Japanese institutional care settings facing landfill diversion mandates. Pursue direct-to-consumer launch with industrial composting facility mapping as core value proposition.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed subscription-native brands possessing recurring revenue visibility but lacking raw material supply control. Five-to-ten year viability hinges on composting infrastructure build-out rates closing the disposal loop. Monitor municipal facility certification expansion as inflection indicator for volume concentration among qualified manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bamboo Sourcing | Captive supply from Sichuan plantations neutralizes export quota volatility for certified converters. |
| EN 13432 Certification Investment | EU Green Deal procurement mandates in German healthcare systems redirect institutional purchasing toward verified alternatives. |
| Subscription Platform Launch | Recurring revenue models bypass retail slotting fees and build predictable demand signals for bio-polymer procurement. |
| Adult Incontinence Line Extension | Japanese eldercare procurement officers facing landfill targets generate faster expansion than infant care saturation. |
| Composting Partnership Program | Municipal facility alignment in Randstad and Bavaria closes post-consumer disposal loop for environmental claims. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with supply chain planners, regulatory affairs directors, category buyers at subscription platforms, and composting facility operators; and secondary validation against customs records, EU tender databases, and REACH compliance filings. Bottom-up volume triangulation across product type, material, end user, and distribution channel dimensions anchored the forecast framework.
Across the analysis window, projections integrate segment-level adoption curves with composting infrastructure build-out assumptions. Modeled dimensions span product certification tier, material input type, end-user application, and channel format. CAGRs derive from regression against historical subscription growth patterns and institutional procurement specification shifts. Bio-polymer cost curve trajectories and municipal facility certification expansion serve as key sensitivity inputs.
Underlying assumptions cover EU Green Deal enforcement continuity and REACH compliance timeline adherence, with deviation risk concentrated in Chinese bamboo export policy shifts and industrial composting facility access fragmentation. Recalibration cycles align with material shifts in regulatory chemistry restrictions and municipal waste hierarchy implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
Global Baby Swim Pants Diaper Market
Baby Diapers
Malaysia Diapers Market
Baby Diapers
GCC Diaper Market
Baby Diapers
United States Diaper Market
Baby Diapers
Baby Disposable Diapers Market
Baby Diapers
Baby Training Diaper Market
Baby Diapers
Europe Diaper Market
Baby Diapers
United Arab Emirates Baby Diapers and Wipes Market
Baby Diapers
Mexico Pant Type Adult Diaper Market
Baby Diapers
Australia Pant Type Adult Diaper Market
Baby Diapers
Dog Diapers Market
Baby Diapers
United States Adult Diaper Market
Baby Diapers
Disposable Hygiene Products Market
Baby Diapers
China Pant Type Adult Diaper Market
Baby Diapers
Middle East and Africa and Asia Pacific Baby Diaper Market
Baby Diapers
Latin America Diaper Market