
 Baby Diaper Manufacturing Machine Market | 2026-2036
Baby Diaper Manufacturing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Diaper Manufacturing Machine Market Insights
Software-defined machine monitoring is hardening into a standard contractual layer, with vendors bundling predictive maintenance subscriptions alongside hardware sales. Zuiko Corporation leverages its Japanese installed base to anchor long-term service revenue streams. Fameccanica Data S.p.A. competes through embedded IoT modules that extend machine lifecycle value. GDM S.p.A. specializes in retrofit packages that upgrade legacy pneumatic lines to electronic control architectures without full replacement.
A baby diaper manufacturing machine is an integrated production system that assembles absorbent cores, nonwoven topsheets, elastic leg gathers, and fastening components at speeds typically exceeding 600 units per minute; its primary commercial purpose is to deliver consistent, high-throughput output for consumer hygiene brands. Fully automated lines dominate capital deployment among OEM manufacturers seeking labor cost reduction, while servo drive technology represents the fastest-growing segment as it enables precision tension control and format flexibility. Semi automated equipment retains relevance in small scale workshops where lower throughput requirements match constrained capital budgets.
CE marking under the EU Machinery Directive and REACH chemical compliance shape equipment specifications for European-bound exports, while FDA facility requirements influence machine validation protocols for US market access. China's GB standards and NMPA hygiene product regulations create parallel certification tracks for equipment serving domestic versus export-oriented producers. Stakeholders must weigh regional regulatory divergence against platform standardization when configuring production footprints.
Market Dynamics
Servo-drive retrofits and EU Green Deal compliance mandates are forcing European producers into accelerated equipment refresh cycles while Southeast Asian OEMs scale capacity to capture private-label brand demand.
Growth Catalysts
- Servo-drive technology:Electronic tension control systems enable format flexibility and precision at speeds exceeding 600 units per minute, attracting capital deployment from labor-cost-sensitive manufacturers.
- EU Green Deal:Carbon border adjustments and machinery efficiency standards are compelling European producers to replace legacy pneumatic lines with energy-efficient electronic architectures.
- Indonesia-Vietnam-Thailand cluster:Export-oriented hygiene manufacturing hubs in these countries are driving concentrated demand for fully automated lines serving regional private-label brands.
Market Restraints
- Steel and electronic component volatility:Servo motors, PLCs, and precision rollers face input cost swings that compress equipment margin structures during contract negotiation windows.
- Supplier concentration in East Asia:Critical motion control systems and industrial IoT modules rely on concentrated semiconductor and sensor supply bases, exposing delivery timelines to single-source risks.
- REACH chemical compliance friction:Adhesive and polymer specifications for machine-contact materials create certification bottlenecks that extend European market entry timelines.
Strategic Opportunities
- Vietnam domestic market underpenetration:Local diaper consumption growth outpaces installed machine base capacity, creating demand for mid-speed semi-automated lines in regional workshops.
- Predictive maintenance convergence:Embedded IoT modules combined with cloud analytics platforms enable vendors to unbundle software subscriptions from hardware sales, capturing recurring revenue streams.
- India PLI scheme:Production-linked incentives for domestic hygiene product manufacturing are drawing first-time capital equipment investments from contract manufacturers seeking tariff advantages.
Industry Challenges
- Mechatronics skill scarcity:Servo system commissioning and electronic control troubleshooting require specialized technician labor that remains scarce in emerging manufacturing clusters.
- Legacy pneumatic integration complexity:Retrofit projects face mechanical incompatibility risks when electronic control architectures must interface with existing line configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Diaper Manufacturing Machine Market |
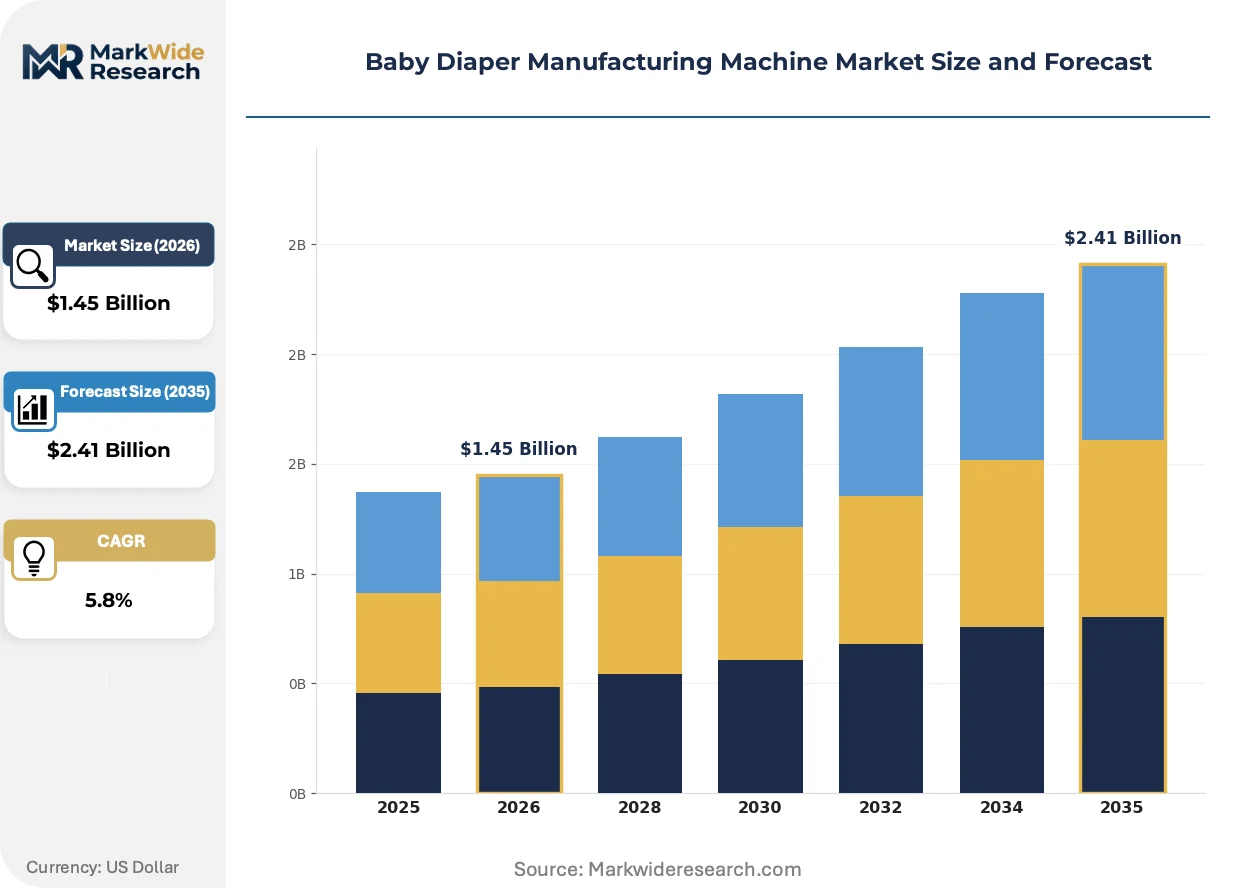
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Automated, Semi Automated, Fly Tape, Wet Wipe Machines Technology: Hydraulic, Pneumatic, Mechanical, Electronic, Servo Drive Application: Disposable Diapers, Training Pants, Adult Incontinence, Sanitary Napkins End User: OEM Manufacturers, Contract Manufacturers, Private Labelers, Small Scale Workshops |
| Companies Covered | Zuiko Corporation, Fameccanica Data S.p.A., GDM S.p.A., Curt G. Joa, Inc., MD Viola Machine, Hanwei Machinery Manufacturing Co., Ltd., Jiangsu JWC Machinery Co., Ltd., Bicma Hygiene Technologie GmbH, Anqing Hengchang Machinery Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Diaper Manufacturing Machine Market Trends and Innovations
Software-defined machine architectures are hardening into standard contractual layers, with predictive maintenance subscriptions and embedded IoT modules reshaping how vendors capture lifetime value from equipment deployments.
Machine learning algorithms are absorbing vibration and thermal sensor data to forecast bearing wear and tension roller degradation before failure-induced downtime occurs. Tier-one hygiene manufacturers in Germany and Japan are deploying these systems at scale, compressing unplanned maintenance intervals and extending effective machine lifecycles beyond traditional depreciation schedules.
REACH chemical compliance under ECHA oversight is forcing adhesive specification changes for machine components that contact finished products. Equipment vendors serving European-bound exports must now validate polymer and lubricant compositions against restricted substance lists, adding documentation burdens that smaller fabricators struggle to absorb.
After-sales service unbundling is accelerating as buyers resist bundled maintenance premiums in favor of outcome-based contracts tied to uptime guarantees. Indonesian and Vietnamese private-label producers are driving this shift, pressuring vendors to separate hardware procurement from multi-year service agreements.
Baby Diaper Manufacturing Machine Market Segmentation
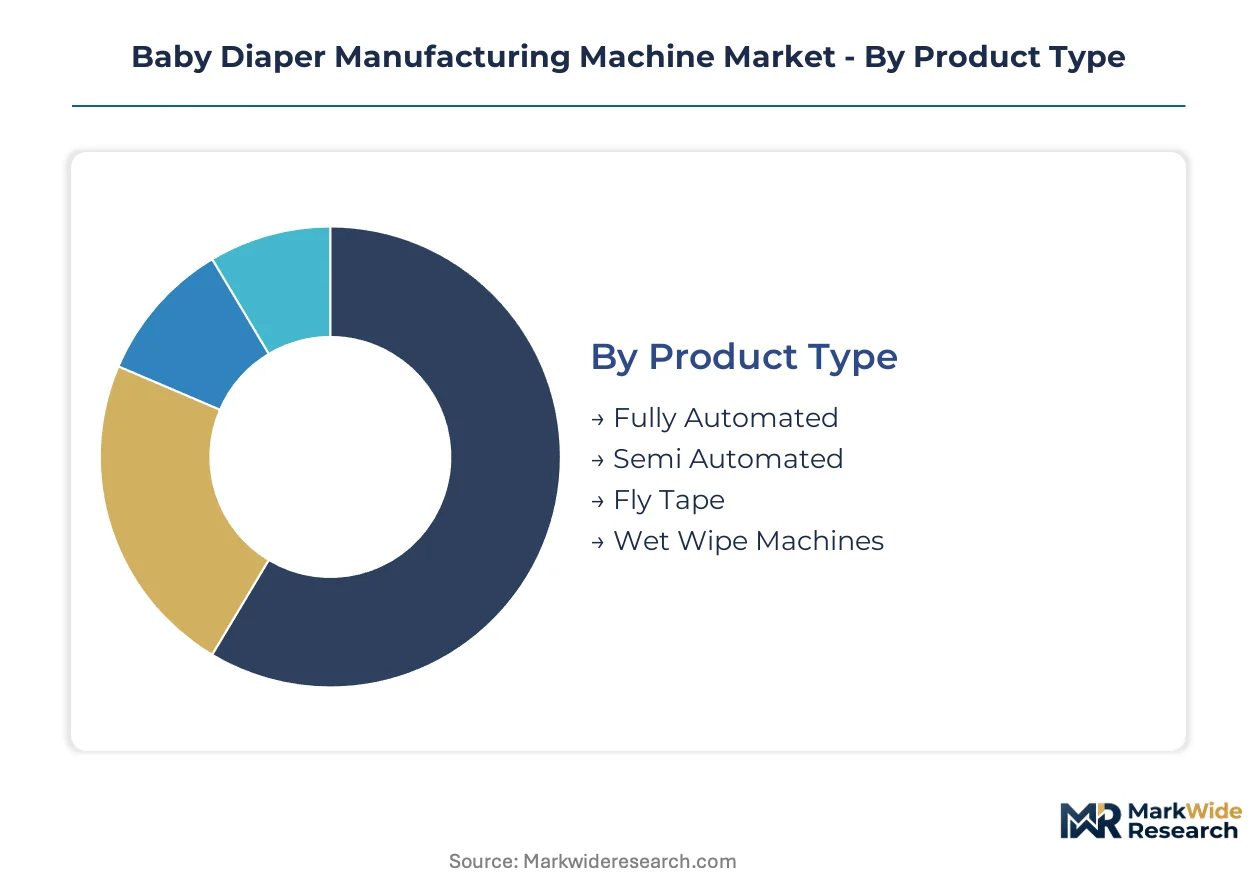
Segmentation in baby diaper manufacturing equipment reveals how capital allocation, technical specifications, and buyer economics split demand across divergent production architectures. Equipment choices cascade through facility layout, labor requirements, and regulatory compliance pathways.
Product Type:
Capital intensity varies sharply across automation tiers, with fully automated lines demanding the largest upfront outlays but compressing per-unit labor costs at scale.
- Fully Automated:Integrated systems assemble absorbent cores, elastic leg gathers, and fastening components at speeds exceeding 600 units per minute with minimal operator intervention. OEM manufacturers in Indonesia and Vietnam deploy these lines to serve export-oriented private-label brands demanding consistent throughput.
- Semi Automated:Modular configurations separate core forming from final assembly, requiring staged operator handling but reducing initial capital requirements by substantial margins. Small-scale workshops in Vietnam's regional manufacturing clusters favor this tier where throughput requirements match constrained budgets.
- Fly Tape:Specialized adhesive application modules for elastic attachment and closure system integration.
- Wet Wipe Machines:Cross-category equipment serving adjacent hygiene product lines with shared nonwoven handling infrastructure.
Most installed capacity flows through Fully Automated lines. Expansion is steepest in Semi Automated configurations.
Technology:
Energy efficiency and precision control separate the technology tiers, with electronic architectures commanding premium positioning against legacy mechanical alternatives.
- Servo Drive:Electronic tension control systems enable real-time format adjustments and precision web handling at high speeds. European producers facing EU Green Deal machinery efficiency standards are accelerating replacement of legacy pneumatic systems with servo architectures.
- Electronic:PLC-controlled architectures with integrated HMI interfaces and diagnostic capabilities. Contract manufacturers in Thailand select these systems to balance flexibility against capital constraints.
- Pneumatic:Compressed-air actuation systems prevalent in legacy installations now targeted for retrofit programs.
- Hydraulic:High-force actuation for heavy-duty forming operations in specialized applications.
- Mechanical:Cam-driven synchronization systems with limited adjustability but proven reliability in stable product formats.
Technology migration concentrates on Servo Drive adoption. Electronic platforms are gaining share fastest among mid-cap producers.
Application:
Product format requirements dictate machine specifications, with diaper-specific architectures dominating capital deployment against multi-format flexibility investments.
- Disposable Diapers:Dedicated lines optimize for absorbent core formation, leg elastic integration, and tape or hook-and-loop closure application. Private-label producers across the Indonesia-Vietnam-Thailand cluster anchor capacity in this segment.
- Training Pants:Modified architectures with pull-on assembly stations and side panel welding systems. OEM manufacturers serving pediatric care brands in Japan and Germany deploy specialized configurations here.
- Adult Incontinence:Upscaled forming widths and higher basis weight handling for larger product formats.
- Sanitary Napkins:Cross-utilized nonwoven and film handling equipment with distinct folding and packaging modules.
Disposable Diapers absorb the majority of installed base investment. Training Pants configurations are expanding most quickly as regional brands diversify product portfolios.
End User:
Buyer scale and commercial model create divergent procurement patterns, from integrated OEM capital programs to workshop-level equipment financing.
- OEM Manufacturers:Vertically integrated hygiene brands with captive production assets and multi-line facility strategies. These buyers negotiate platform standardization and long-term service bundling with vendors like Zuiko Corporation.
- Contract Manufacturers:Third-party producers serving multiple brand clients with format flexibility requirements. India's PLI scheme beneficiaries are entering this tier with first-time capital investments.
- Private Labelers:Regional brands with concentrated demand in Southeast Asian export hubs.
- Small Scale Workshops:Local-market suppliers with limited throughput needs and compressed capital budgets.
OEM Manufacturers command the largest share of high-value equipment shipments. Contract Manufacturers are climbing the fastest as outsourcing trends reshape production geography.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia commands faster capacity expansion than Vietnam, yet both nations anchor Southeast Asian demand for fully automated diaper lines serving export-oriented private-label brands.
Indonesia
Domestic diaper consumption growth and regional private-label export contracts drive equipment procurement. The Ministry of Industry's Making Indonesia 4.0 initiative subsidizes automation upgrades for hygiene manufacturers. Surabaya and Jakarta industrial corridors concentrate new fully automated line installations serving ASEAN-bound shipments.
Vietnam
Mid-speed semi-automated lines attract regional workshop investments where local consumption outpaces existing capacity. The Ministry of Planning and Investment coordinates production-linked incentive packages for domestic hygiene product manufacturing. Ho Chi Minh City and Binh Duong province host expanding clusters of contract manufacturers scaling first-time capital equipment.
Thailand
Established OEM manufacturers refresh servo-drive architectures to maintain competitiveness against Indonesian and Vietnamese rivals. The Thailand Board of Investment privileges machinery imports for export-oriented hygiene production through tax incentive windows. Eastern Economic Corridor industrial estates attract Japanese and European vendor technical service centers.
Germany
EU Green Deal machinery efficiency standards and carbon border adjustment mechanisms accelerate replacement of legacy pneumatic installations. ECHA REACH compliance requirements for machine-contact materials extend certification timelines for European-bound equipment exports. Baden-Württemberg and Bavaria maintain concentrated vendor R&D facilities for predictive maintenance module development.
India
Production-linked incentive schemes for domestic hygiene manufacturing draw first-time capital investments from contract manufacturers seeking tariff advantages. BIS machinery safety standards and CDSCO hygiene product regulations create dual certification tracks for equipment serving local versus export markets. Maharashtra and Gujarat industrial zones concentrate pilot deployments of mid-speed automated lines.
Baby Diaper Manufacturing Machine Market Competitive Landscape
Top-tier vendors anchor premium-tier positioning through integrated IoT and predictive maintenance bundling, while mid-cap fabricators compete on retrofit flexibility and regional service proximity. Market structure tilts toward consolidation among Japanese and European specialists with established installed bases, though Chinese and Italian machinery builders fragment the mid-market with price-competitive electronic architectures. Two strategic archetypes dominate: full-system integrators delivering turnkey lines above 600 units per minute, and retrofit specialists upgrading legacy pneumatic installations without full replacement. Competitive moves concentrate on technology licensing partnerships for servo-drive modules and geographic expansion through regional service hub establishment.
Among Japanese-headquartered specialists, Zuiko Corporation occupies a position exemplifying the installed-base service revenue model, leveraging long-term maintenance contracts to anchor lifetime value capture. Italian S.p.A. structured entities including Fameccanica Data S.p.A. and GDM S.p.A. represent the European precision-engineering archetype, with the latter specializing in retrofit packages that transition legacy lines to electronic control architectures. These three entities collectively illustrate how geographic origin and corporate structure map to divergent competitive positioning within tiered market segmentation.
| Leading Market Players |
|---|
| Zuiko Corporation |
| Fameccanica Data S.p.A. |
| GDM S.p.A. |
| Curt G. Joa, Inc. |
| MD Viola Machine |
| Hanwei Machinery Manufacturing Co., Ltd. |
| Jiangsu JWC Machinery Co., Ltd. |
| Bicma Hygiene Technologie GmbH |
| Anqing Hengchang Machinery Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Mechatronics technician scarcity in Vietnam and Indonesia widens labor-cost differentials between fully automated and semi-automated tiers, compressing pricing spreads for entry-level equipment while premium servo-drive lines command wider margins.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for mid-speed semi-automated configurations. Three-tier pricing structure across premium, standard, and economy levels separates Japanese and European full-system integrators from Chinese electronic-architecture fabricators and regional retrofit specialists. Price differentiation centers on after-sales service bundling and CE marking compliance tiers. Pricing pressure stems from steel and electronic component volatility compressing equipment margins during contract windows. Small-scale workshops in Vietnam exhibit highest price sensitivity, while OEM manufacturers in Indonesia prioritize uptime guarantees over upfront capital outlays.
Supply Chain Analysis
Single-source vulnerability sits with concentrated semiconductor and sensor supply bases in Taiwan, South Korea, and Japan. Critical motion control systems and industrial IoT modules draw from these geographies, with servo motors, PLCs, and precision rollers anchoring raw material dependencies. Supply chain risk centers on tariff exposure from carbon border adjustments affecting European-bound exports. Distribution runs through vendor-direct technical service centers in Surabaya, Ho Chi Minh City, and Bangkok industrial corridors, supplemented by regional agent networks for spare parts and commissioning support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Servo-drive technology migration and predictive maintenance unbundling create margin-expansion opportunities as buyers shift from bundled premiums toward outcome-based contracts tied to uptime performance.
For Market Incumbents: Cement installed-base service revenue through predictive maintenance subscription anchoring, leveraging long-term contracts to offset hardware margin compression. Deepen backward integration into motion control system supply to mitigate semiconductor concentration risk. Prioritize CE marking and REACH compliance investment as ECHA oversight tightens adhesive and polymer specifications for European-bound exports.
For New Entrants and Emerging Players: Begin with Vietnam's domestic consumption gap where local diaper demand outpaces installed machine base capacity. Target mid-speed semi-automated lines for regional workshops with constrained capital budgets. Pursue retrofit specialization positioning electronic control architectures that interface with legacy pneumatic installations without full replacement.
For Investors and Strategic Acquirers: Japanese OEM manufacturers are the most active acquirer in this space, seeking regional service hub expansion and technology licensing partnerships. Long-term viability hinges on software-defined machine architectures capturing recurring revenue streams beyond traditional depreciation schedules. Monitor predictive maintenance adoption rates among Tier-one hygiene manufacturers as inflection indicator for vendor lifetime value capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Drive Retrofit Deployment | European producers accelerate replacement of legacy pneumatic lines under EU Green Deal machinery efficiency standards. |
| Predictive Maintenance Subscription Launch | Vendors unbundle software from hardware sales to capture recurring revenue from Indonesian and Vietnamese private-label producers. |
| Regional Service Hub Establishment | Japanese and European specialists expand technical service centers in Eastern Economic Corridor to defend premium positioning. |
| IoT Module Integration | Embedded sensors enable cloud analytics platforms that forecast bearing wear before failure-induced downtime occurs. |
| Backward Integration into Motion Control | Mid-cap fabricators reduce semiconductor supply concentration risk through captive servo motor and PLC sourcing. |
Research Methodology
Coverage spans Southeast Asia, Europe, and South Asia, with primary inputs from each region combining interviews with plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors alongside secondary validation. Primary research draws from machinery vendor technical sales leads, hygiene product manufacturing executives, and regional distributor channel partners. Secondary sources include customs and trade data, SEC filings from listed equipment manufacturers, industrial machinery import registries, and national automation subsidy program disclosures. Bottom-up unit economics triangulate against top-down capacity expansion announcements across the analysis window.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions span automation tier, control technology architecture, product format application, and end-user commercial model. CAGRs derive from installed base turnover rates, replacement cycle acceleration under regulatory compliance mandates, and greenfield capacity addition trajectories in export-oriented manufacturing hubs. Industry-specific forecast inputs incorporate EU Green Deal machinery efficiency standard implementation timelines and PLI scheme disbursement patterns for Indian contract manufacturers.
Caveats apply where semiconductor supply disruptions, REACH chemical compliance friction, or mechatronics skill scarcity could materially shift the outlook. Forecasts reflect assumptions around servo-drive adoption curves and predictive maintenance penetration rates that remain sensitive to buyer budget cycles and vendor service unbundling negotiations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
North America Diaper Market
Baby Diapers
Global Baby Swim Pants Diaper Market
Baby Diapers
China Pant Type Adult Diaper Market
Baby Diapers
Cat Diapers Market
Baby Diapers
Smart Diaper Market
Baby Diapers
Biodegradable Baby Diapers Market
Baby Diapers
Europe Diaper Market
Baby Diapers
Nonwoven Baby Diaper Market
Baby Diapers
UAE Baby Diapers Industry Market
Baby Diapers
United States Adult Diaper Market
Baby Diapers
Latin America Diaper Market
Baby Diapers
GCC Diaper Market
Baby Diapers
Baby Diapers Market
Baby Diapers
Middle East and Africa and Asia Pacific Baby Diaper Market
Baby Diapers
Biodegradable Diapers Market
Baby Diapers
United Arab Emirates Baby Diapers and Wipes Market