
 UAE Baby Diapers Industry Market | 2026-2036
UAE Baby Diapers Industry Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Baby Diapers Industry Market Insights
Premium absorbent-core specifications is redrawing competitive dynamics in the UAE baby diapers industry. Procter & Gamble Company leverages its global R&D infrastructure to sustain innovation leadership in ultra-thin core technologies. Kimberly-Clark Corporation anchors its position through deep pharmacy and supermarket channel control across the Emirates. Essity AB differentiates via specialized sustainability credentials that resonate with environmentally conscious UAE consumers.
The UAE baby diapers industry encompasses absorbent hygiene garments engineered with superabsorbent polymers, nonwoven topsheets, and elasticized closures, manufactured through hot-melt adhesive bonding and thermal calendering processes to manage infant excreta with skin-protecting dryness. Disposable products dominate volume throughput while biodegradable alternatives capture the fastest expansion trajectory as ESMA-aligned environmental standards tighten material compliance requirements. Online retail channels are gaining structural importance alongside traditional supermarkets, though pharmacies retain margin-rich positioning in premium-tier transactions.
MOHAP oversees pharmaceutical and hygiene product registration, ESMA governs textile and polymer safety standards, and the UAE's consumer protection framework mandates labeling transparency that shapes import eligibility and domestic manufacturing protocols. These regulatory layers elevate compliance costs for new entrants while reinforcing incumbent quality benchmarks. Stakeholders must monitor evolving biodegradability certification requirements and channel-specific distribution licensing as the market matures toward differentiated service models.
Market Dynamics
ESMA's tightening biodegradability certification requirements are compressing material substitution timelines across UAE manufacturing facilities, forcing rapid retooling of absorbent core formulations and nonwoven sourcing strategies.
Growth Catalysts
- Urban Premiumization:Dubai and Abu Dhabi parents are prioritizing skin-sensitive formulations and overnight leak protection, pulling volume toward higher-margin product tiers.
- MOHAP Registration Pathways:Streamlined hygiene product approvals are accelerating import clearance for innovative absorbent technologies from European and Asian suppliers.
- Superabsorbent Polymer Advances:Next-generation sodium polyacrylate derivatives are enabling thinner cores without capacity sacrifice, reducing shipping cube and retail shelf footprint.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and polyethylene resin costs fluctuate with Gulf crude pricing, compressing margin predictability for domestic converters.
- Single-Source SAP Concentration:Superabsorbent polymer supply concentrates among three global chemical conglomerates, creating vulnerability for UAE-based finished goods manufacturers.
- Biodegradability Technical Ceiling:Current cellulose-based alternatives fail to match petroleum-derived cores on total absorption capacity, limiting full material substitution.
Strategic Opportunities
- Sharjah and Northern Emirates Penetration:Retail infrastructure expansion in Ajman, Ras Al Khaimah, and Fujairah presents whitespace beyond saturated Dubai-Abu Dhabi corridors.
- Subscription Direct-to-Consumer Models:Auto-replenishment platforms are bypassing traditional pharmacy markups while capturing predictable recurring revenue streams.
- ESMA Green Label Incentives:Early certification under emerging environmental standards unlocks preferential retail placement and municipal procurement access.
Industry Challenges
- Specialized Nonwoven Engineering Talent:UAE universities produce limited graduates in polymer science and thermal bonding process engineering, forcing reliance on expatriate technical staff.
- Legacy ERP Integration with Traceability Mandates:Batch-level serialization requirements for MOHAP compliance demand expensive middleware upgrades at mid-sized converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Baby Diapers Industry Market |
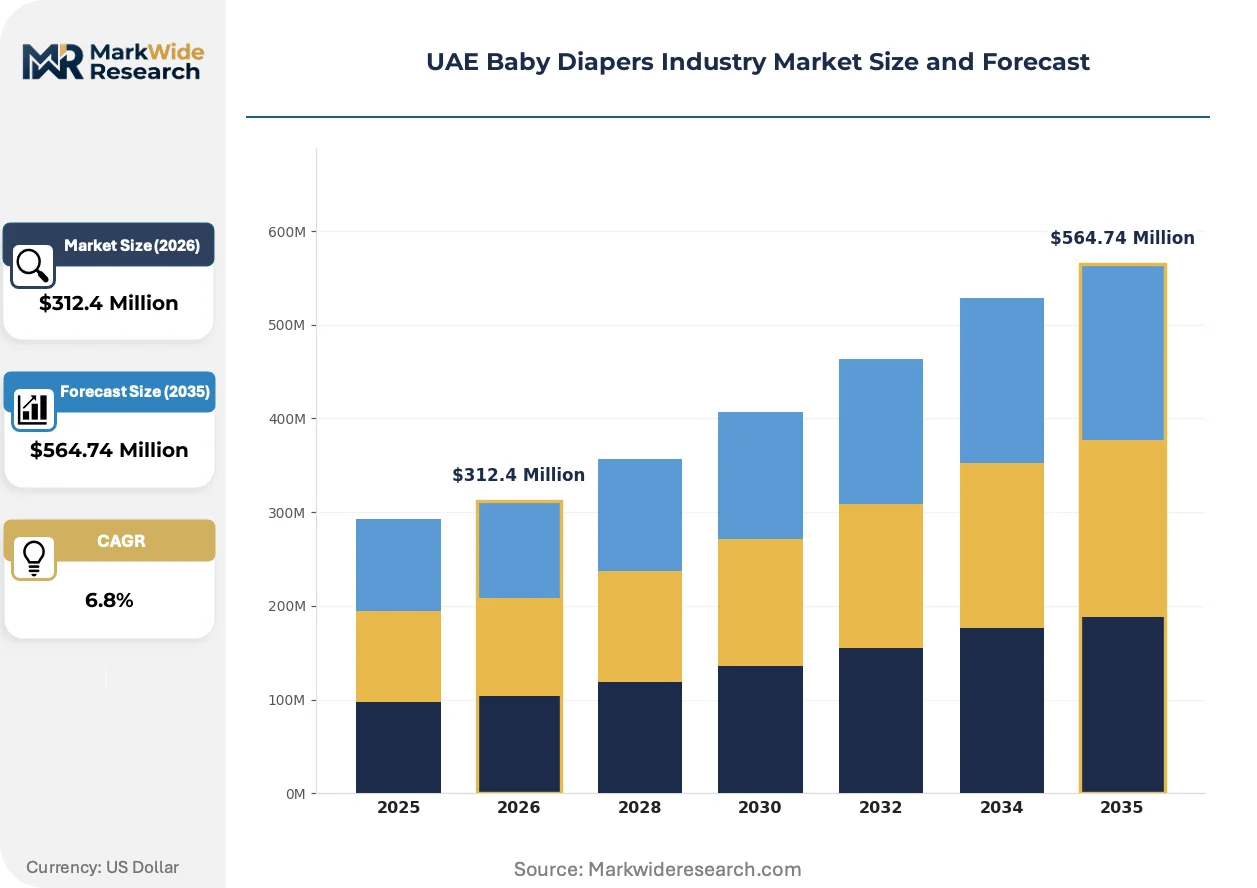
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Cloth, Biodegradable, Training Pants Distribution Channel: Supermarkets, Online Retail, Pharmacies, Convenience Stores End User: Parents, Caregivers, Hospitals, Daycare Centers Price Tier: Premium, Mid-range, Budget, Value |
| Companies Covered | Procter & Gamble Company, Kimberly-Clark Corporation, Unicharm Corporation, Kao Corporation, Essity AB, Ontex Group NV, Fine Hygienic Holding, Popees Baby Care, PureBorn, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Baby Diapers Industry Market Trends and Innovations
Absorbent hygiene manufacturing is undergoing material science transformation as sustainability imperatives collide with performance benchmarks, reshaping supplier qualification criteria and capital allocation priorities across Emirates production facilities.
Ultra-thin core architectures utilizing compressed airlaid pulp and microfiber distribution layers are miniaturizing product profiles while maintaining fluid retention specifications. Premium-tier buyers in Dubai's Marina and Downtown districts are adopting these slim-format diapers for portability and discretion. This compression is eliminating bulk inventory requirements at retail and enabling smaller-format convenience store distribution.
ESMA's draft technical regulations for biodegradable hygiene products are mandating compostability testing under industrial facility conditions. Domestic converters must reformulate hot-melt adhesives and elastic spandex components to meet disintegration timelines. Pharmacy chains are already demanding pre-certification documentation from suppliers ahead of formal enforcement dates.
Pharmacy-led purchasing for infant hygiene is fragmenting as hypermarket private-label quality improves and telehealth platforms bundle diaper subscriptions with pediatric consultations. First-time parents in Abu Dhabi's Al Reem Island and Al Raha Beach developments are bypassing traditional pharmacist recommendations in favor of algorithm-driven personalization engines. This disintermediation is most pronounced among digitally native consumers aged 25-34.
UAE Baby Diapers Industry Market Segmentation
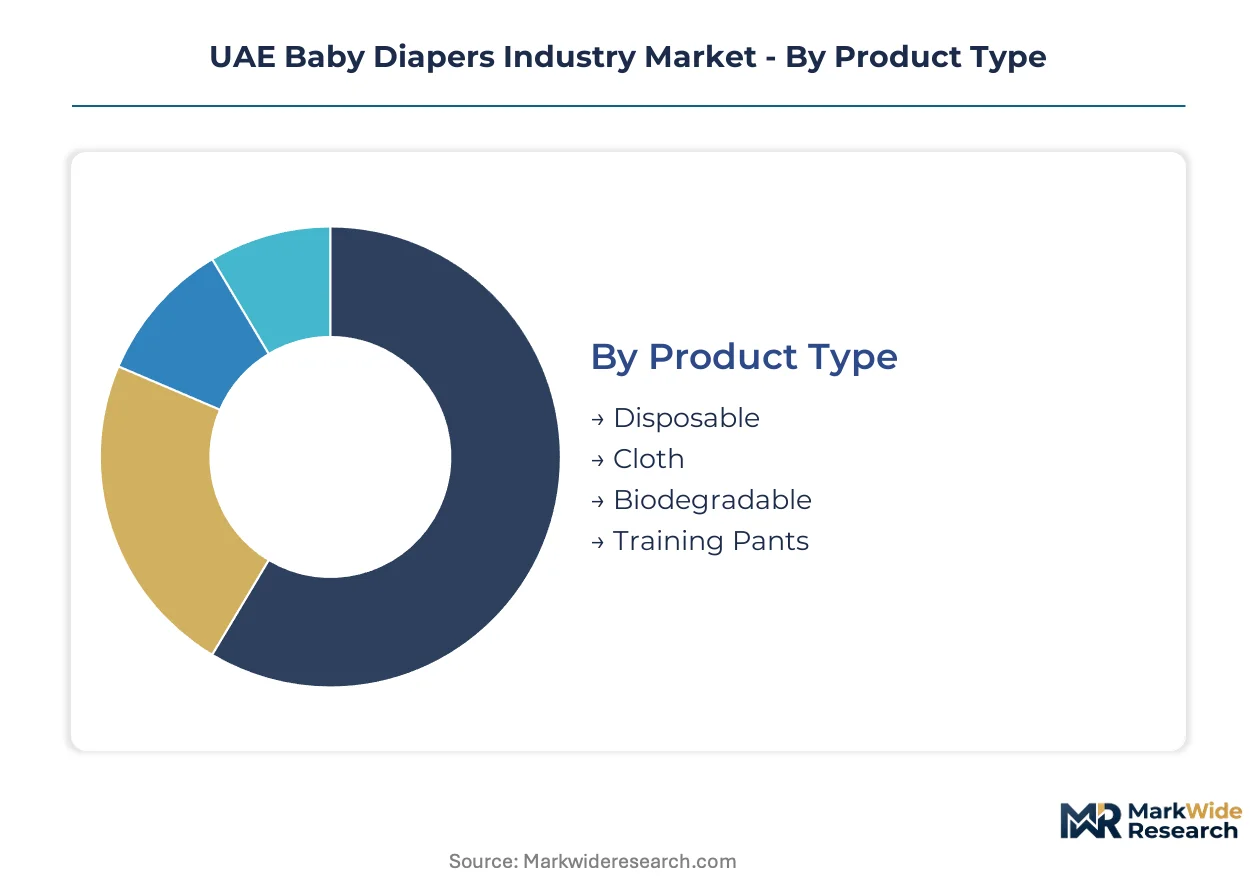
Segmentation in the UAE baby diapers industry reveals how purchasing decisions fragment across channel preferences, product philosophies, and price sensitivity. Understanding these divisions exposes where manufacturers must configure separate supply chains and marketing investments to capture value.
Product Type:
Premium margins concentrate in products commanding shelf space through performance claims and sustainability credentials rather than unit economics alone.
- Disposable:Petroleum-derived superabsorbent polymer cores bonded with hot-melt adhesives dominate hospital procurement and mass retail. Dubai hypermarkets move volume through bulk-pack promotions targeting cost-conscious expatriate families.
- Biodegradable:Plant-based absorbent cores and compostable backsheet films carry ESMA certification premiums. Abu Dhabi parents in Al Raha Beach and Saadiyat Island developments prioritize these for environmental alignment despite higher per-unit cost.
- Cloth:Reusable cotton and bamboo fiber designs serve sustainability-committed households willing to absorb laundry labor. Sharjah and Northern Emirates communities show stronger adoption due to multi-child household economics.
- Training Pants:Elasticized waistbands and tear-away sides facilitate toddler independence. Preschool enrollment growth in Dubai's Jumeirah and Umm Suqeim districts drives demand for pull-up formats.
The dominant share belongs to Disposable, while Biodegradable is closing the gap fastest.
Distribution Channel:
Channel selection determines margin capture through markup structures and inventory velocity differences across Emirates retail ecosystems.
- Pharmacies:Pharmacist-mediated sales of dermatologically tested formulations command premium positioning. MOHAP registration requirements create barrier-protected shelf access for compliant suppliers in Abu Dhabi pharmacy chains.
- Supermarkets:High-frequency foot traffic and promotional stacking enable volume throughput. Carrefour and Lulu Hypermarket locations across Dubai Marina and Deira rotate diaper SKUs through end-cap displays.
- Online Retail:Subscription auto-replenishment and bundled pediatric product offerings bypass traditional intermediaries. First-time parents aged 25-34 in Downtown Dubai favor algorithm-driven personalization over physical comparison.
- Convenience Stores:Emergency purchase occasions and travel-size formats address immediate need states. ENOC and ADNOC petrol station retail networks stock compact packs for highway corridor access.
Supermarkets still process the highest transaction volume, though Online Retail is expanding most quickly.
End User:
Institutional procurement patterns diverge sharply from household purchasing in specification requirements and contract structures.
- Parents:Primary decision-makers balancing skin sensitivity concerns, leakage protection, and unit economics. Dubai's dual-income professional households demonstrate strongest premium-tier willingness-to-pay.
- Hospitals:Bulk procurement through MOHAP-registered tenders prioritizes infection control and standardization. Neonatal intensive care units specify ultra-soft topsheet materials for pre-term infant skin integrity.
- Daycare Centers:Volume purchasing with simplified change protocols favors economy-tier disposables. Ajman and Ras Al Khaimah facility expansion creates new institutional demand nodes.
- Caregivers:Extended family and domestic staff purchasing on behalf of employers. Discretion and reliability matter more than brand loyalty in this proxy-buyer segment.
Parents control the largest spending pool, while Hospitals are tightening specification standards fastest.
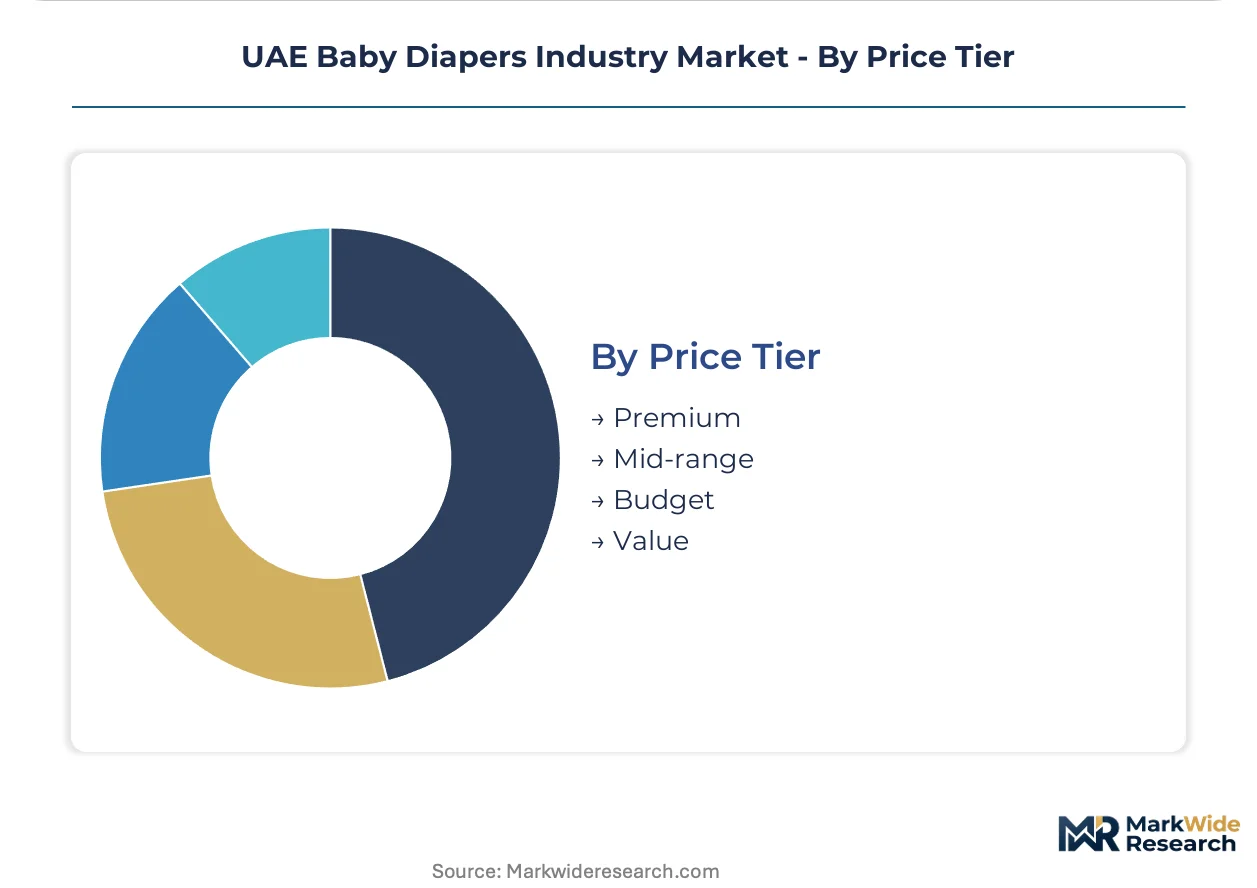
Price Tier:
Emirates consumer wealth dispersion creates distinct tier boundaries that resist convergence despite quality improvements at lower price points.
- Premium:Dermatologically certified formulations with overnight absorption guarantees and biodegradable credentials. Al Reem Island and Palm Jumeirah households treat diaper selection as visible parenting quality signal.
- Mid-range:Balanced performance positioning targeting value-conscious quality seekers. Fujairah and Umm Al Quwain retail expansion captures this tier's growth trajectory.
- Budget:Functional absorption without specialized features serves price-elastic demand. Large expatriate families in Deira and Bur Dubai trade down here during remittance pressure periods.
- Value:Promotional pack sizing and private-label alternatives from hypermarket chains. Seasonal discounting concentrates volume in Ramadan and back-to-school periods.
Premium commands the highest margin per unit, though Mid-range is gaining household penetration fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UAE baby diapers industry operates as a net import market with finished goods flowing from European and Asian manufacturing hubs while domestic converters focus on final assembly and packaging for Gulf Cooperation Council re-export.
Dubai
Marina and Downtown districts concentrate premium-tier demand where dual-income professional households prioritize dermatologically certified formulations. Dubai Municipality enforces product labeling standards that exceed federal baselines. Jebel Ali Free Zone hosts regional distribution centers serving re-export corridors into Saudi Arabia and Oman.
Abu Dhabi
Al Reem Island and Al Raha Beach developments generate concentrated demand for biodegradable and overnight absorption products. MOHAP registration requirements create barrier-protected shelf access for compliant suppliers in pharmacy chains. Khalifa Industrial Zone attracts converters seeking proximity to institutional procurement channels.
Sharjah
Mid-range product penetration accelerates as retail infrastructure expands beyond Dubai-Abu Dhabi saturation. ESMA textile safety standards govern polymer content in locally assembled goods. Hamriyah Free Zone offers tariff advantages for Asian raw material importers serving Northern Emirates distribution.
Northern Emirates
Ajman, Ras Al Khaimah, and Fujairah present whitespace growth as family household economics favor value-tier and cloth diaper alternatives. Federal consumer protection frameworks mandate batch traceability that shapes local converter compliance investments. Ras Al Khaimah Economic Zone is emerging as a cost-competitive alternative for packaging and finishing operations.
UAE Baby Diapers Industry Market Competitive Landscape
Listed leaders compete with private specialists across channel control and sustainability certification dimensions. The vendor base consolidates around three multinational conglomerates commanding pharmacy and hypermarket shelf space, while regional specialists capture subscription and direct-to-consumer niches. Strategic archetypes include R&D-driven global brands, sustainability-focused Nordic entrants, and Gulf-based private-label converters. Competitive moves concentrate on biodegradability pre-certification and pharmacy chain exclusive arrangements.
Within the premium-tier vector, Procter & Gamble Company and Kimberly-Clark Corporation occupy positions reflecting global scale advantages in absorbent core technology. Essity AB exemplifies the sustainability-focused archetype with specialized environmental credentials. Fine Hygienic Holding represents regional private specialists leveraging Gulf manufacturing proximity. These anchors illustrate how competitive positioning fragments across multinational R&D depth, Nordic sustainability branding, and local supply chain responsiveness.
| Leading Market Players |
|---|
| Procter & Gamble Company |
| Kimberly-Clark Corporation |
| Unicharm Corporation |
| Kao Corporation |
| Essity AB |
| Ontex Group NV |
| Fine Hygienic Holding |
| Popees Baby Care |
| PureBorn |
| Others |
Pricing and Supply Chain Analysis
Plant-based absorbent core substitution for petroleum-derived superabsorbent polymers is simultaneously redrawing raw material procurement geography toward Southeast Asian biomass suppliers and compressing margin structures across Emirates-based finished goods manufacturers. ESMA's emerging biodegradability mandates accelerate this dual transformation, forcing converters to absorb certification premiums while renegotiating supplier terms.
Pricing Analysis
Parents in Dubai's premium districts anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates dermatologically certified ESMA-compliant tiers from functional absorption grades, with certification investment and brand heritage commanding measurable premiums. Cost compression in the mid-range tier is intensifying because hypermarket private-label quality improvements erase perceived performance gaps. Large expatriate families in Deira and Bur Dubai exhibit highest price sensitivity, while Al Reem Island households demonstrate least elasticity.
Supply Chain Analysis
Strategic stockpiling of superabsorbent polymer feedstock dominates inventory strategy among Emirates converters seeking insulation from petrochemical price volatility. Raw material supply concentrates in Germany, Japan, and South Korea for specialized polymer grades, while nonwoven topsheet production draws from China and India. Single-source vulnerability concentrates among three global chemical conglomerates controlling SAP derivatives. Distribution runs through Jebel Ali Free Zone regional hubs serving Gulf Cooperation Council re-export corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloth diaper rental services and reusable hybrid formats pose substitution threats that incumbent manufacturers must neutralize through performance innovation and sustainability repositioning.
For Market Incumbents: Consolidate pharmacy channel control through exclusive ESMA pre-certification arrangements that lock shelf access ahead of formal enforcement dates. Deepen backward integration into nonwoven manufacturing through Hamriyah Free Zone facility investments to capture tariff advantages and reduce Asian import dependency. Biodegradable material cost premiums represent the primary margin pressure point requiring absorption through scale economies. For New Entrants and Emerging Players: Lead with subscription direct-to-consumer models targeting first-time parents aged 25-34 in Downtown Dubai and Al Reem Island developments, bypassing traditional pharmacy markups. The Northern Emirates whitespace—Ajman, Ras Al Khaimah, and Fujairah—offers lowest competitive density for value-tier and cloth-alternative positioning. Bundle pediatric telehealth consultations with auto-replenishment platforms to establish algorithm-driven personalization differentiation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with Gulf-based private-label converters lacking biodegradability certification infrastructure but possessing established hypermarket relationships. Five-to-ten year viability hinges on ESMA compliance investment completion and raw material sourcing diversification beyond single-source SAP dependence. The signal to watch is pharmacy chain pre-certification documentation demands ahead of formal regulatory enforcement dates.| Strategic Initiative | Industry Significance |
|---|---|
| ESMA Green Label Pre-Certification | Early certification unlocks preferential pharmacy placement and municipal procurement access ahead of competitors. |
| Backward Integration into Nonwoven Production | Hamriyah Free Zone manufacturing reduces Asian import dependency and captures tariff advantages for GCC re-export. |
| Subscription Direct-to-Consumer Launch | Auto-replenishment platforms bypass traditional pharmacy markups while capturing predictable recurring revenue from digital-native parents. |
| Northern Emirates Distribution Expansion | Ajman, Ras Al Khaimah, and Fujairah retail infrastructure growth addresses whitespace beyond saturated Dubai-Abu Dhabi corridors. |
| Sustainability Repositioning | Biodegradable core formulations and compostable packaging align with Al Raha Beach and Saadiyat Island environmental priorities. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers at multinational hygiene manufacturers, category buyers at Carrefour and Lulu Hypermarket chains, pharmacy procurement leads across Abu Dhabi and Dubai, and supply planners at Emirates-based converters, then refined through secondary validation. Customs records, ESMA technical regulation drafts, MOHAP registration databases, and Nielsen retail audit data provided quantitative grounding. Bottom-up volume modeling and top-down value triangulation cross-validated segment-level estimates.
Variance decomposition across product type, distribution channel, price tier, and end-user segmentation dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-unit assumptions, with superabsorbent polymer cost curves and pharmacy channel mix shifts serving as key industry-specific forecast inputs.
Forecasts assume regulatory continuity in ESMA biodegradability timelines and MOHAP registration pathways; material policy acceleration or relaxation would require re-modeling. Raw material supply concentration, petrochemical feedstock volatility, and pharmacy channel disintermediation by subscription platforms constitute specific risk factors. Revision becomes warranted when biodegradable core cost premiums compress below threshold levels enabling mass-market penetration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
North America Diaper Market
Baby Diapers
Middle East and Africa and Asia Pacific Baby Diaper Market
Baby Diapers
Biodegradable Baby Diapers Market
Baby Diapers
Global Baby Swim Pants Diaper Market
Baby Diapers
China Pant Type Adult Diaper Market
Baby Diapers
Baby Training Diaper Market
Baby Diapers
GCC Diaper Market
Baby Diapers
Reusable Baby Diapers and Training Pants Market
Baby Diapers
Latin America Diaper Market
Baby Diapers
United States Diaper Market
Baby Diapers
Dog Diapers Market
Baby Diapers
Europe Diaper Market
Baby Diapers
Diaper Market
Baby Diapers
Australia Pant Type Adult Diaper Market
Baby Diapers
Smart Connected Diaper Market
Baby Diapers
Baby Diapers Market