
 Floor Screeds Market | 2026-2036
Floor Screeds Market Size, Share, and Industry Trends Forecast 2026-2036
Floor Screeds Market Analysis
Aftermarket service revenue is fragmenting across installation support, specification consulting, and warranty-backed maintenance programs. Sika AG leverages its global distribution network to capture recurring specification-driven sales. BASF SE anchors its position through captive supply of polymer additives for high-performance screed formulations. Mapei S.p.A. differentiates via specialized technical service teams embedded with major flooring contractors.
Floor screeds are levelling compounds applied over structural concrete or insulation boards to create a flat, stable substrate for final floor finishes, typically ranging from 25 mm to 75 mm in thickness and formulated with cement, sand, calcium sulfate, or synthetic polymers to achieve specified compressive strengths. Cementitious screeds dominate volume due to cost efficiency and compatibility with underfloor heating systems, while polymer screeds command premium positioning in fast-track commercial projects requiring rapid curing. Floating screeds over acoustic insulation layers represent the fastest-growing installation category as multi-occupancy buildings face stricter sound transmission standards.
European regulators including ECHA through REACH chemical restrictions and national building codes incorporating EU Green Deal energy performance targets are elevating demand for low-carbon and thermally efficient screed systems. The UK's Building Regulations Part L and Germany's EnEV standards directly shape product specification by mandating minimum thermal resistance values in new construction. Stakeholders must monitor evolving carbon accounting rules for construction materials and position their portfolios toward factory-controlled pre-blended formulations that reduce site waste and enable environmental product declaration compliance.
Market Dynamics
European energy performance mandates are compressing specification timelines for thermally efficient screed systems, forcing manufacturers to pre-certify formulations before national building code revisions take effect.
Growth Catalysts
- Underfloor heating compatibility:Cementitious screed formulations with enhanced thermal conductivity capture specification share in residential retrofit programs across Germany and France.
- EU Green Deal integration:National building codes incorporating EU Green Deal energy performance targets mandate minimum thermal resistance values, accelerating replacement cycles in commercial construction.
- Acoustic insulation layering:Floating screed installations over mineral wool and rubber mat systems address stricter sound transmission standards in multi-occupancy buildings.
Market Restraints
- Calcium sulfate raw material concentration:Synthetic gypsum supply chains concentrate in northwestern European industrial clusters, exposing formulators to energy-price-linked input volatility.
- REACH chemical restrictions:ECHA's evolving substance authorization requirements create formulation reformulation costs and compliance timeline uncertainty for polymer-modified screed producers.
- Dry-mix logistics constraints:Bulk powder transport economics limit effective distribution radius to 250-300 kilometers from production facilities, constraining market reach for regional specialists.
Strategic Opportunities
- Pre-blended factory production:Controlled manufacturing environments enable environmental product declaration compliance and waste reduction, unlocking public procurement preference in France and the Netherlands.
- Fast-cure polymer convergence:Hybrid cement-polymer formulations combining rapid strength development with thermal mass performance capture fast-track commercial project specifications.
- Technical service embedding:On-site specification consulting and warranty-backed installation support create recurring revenue streams independent of commodity screed volume.
Industry Challenges
- Skilled installer scarcity:Floating screed and underfloor heating integration demands specialized training that outpaces vocational program output in the United Kingdom and Germany.
- Certification timeline compression:Environmental product declaration and CE marking documentation requirements extend product development cycles while national code revisions accelerate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floor Screeds Market |
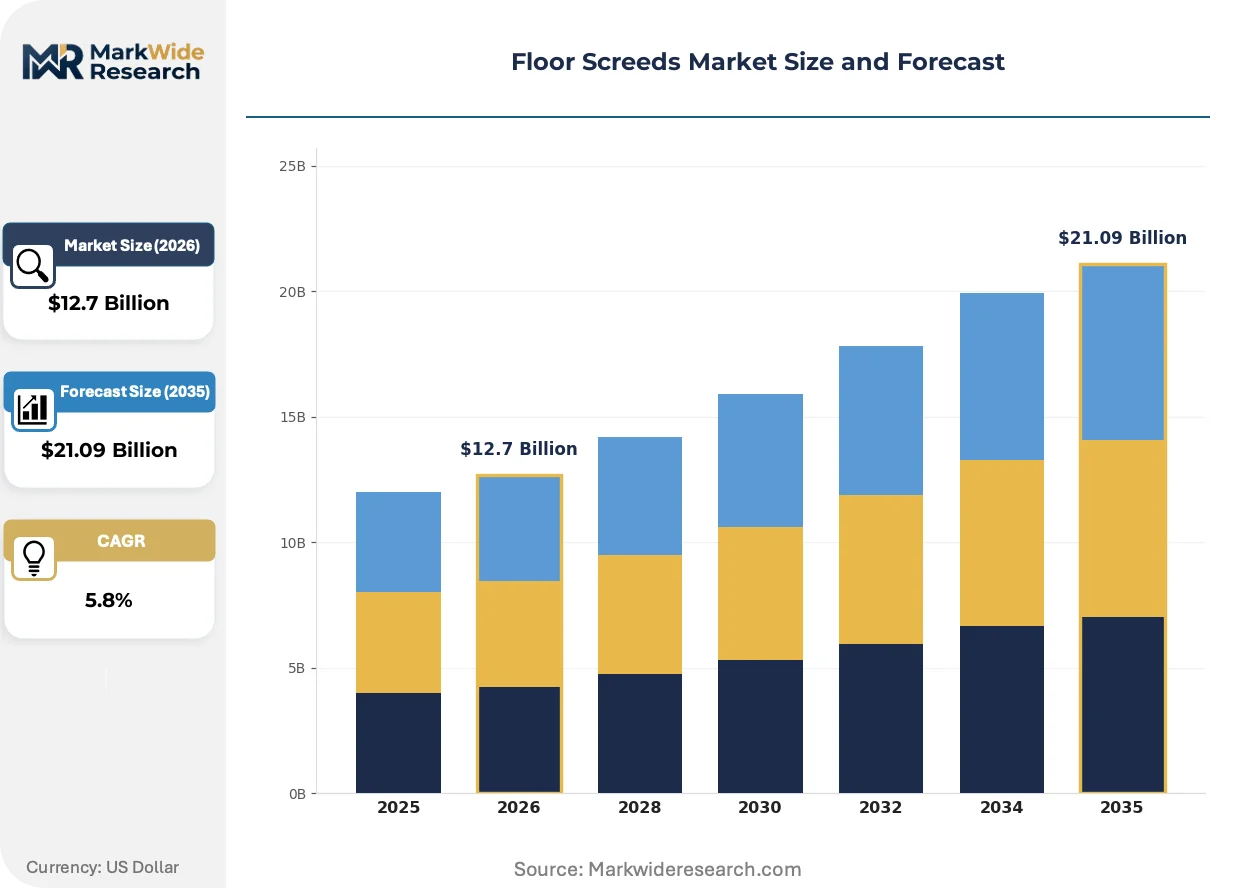
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $21.09 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cementitious Screeds, Gypsum Screeds, Polymer Screeds, Lightweight Screeds Installation Type: Bonded Screeds, Unbonded Screeds, Floating Screeds, Steel Reinforced Screeds End User: Residential, Commercial, Industrial, Institutional Functionality: Thermal Mass, Acoustic Insulation, Load Bearing, Aesthetic Finish |
| Companies Covered | BASF SE, Bostik, Sika AG, Flowcrete Group, LafargeHolcim, Ardex Group, Saint-Gobain, Knauf Gips, Mapei S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floor Screeds Market Emerging Trajectories
Formulation chemistry and installation methodology are converging to address thermal performance mandates while compressing project delivery schedules in commercial construction.
Self-levelling calcium sulfate screeds with polymer modification are collapsing traditional multi-stage installation timelines by combining flow characteristics with rapid strength development. Major flooring contractors in mixed-use developments specify these systems for programmes requiring 24-hour return-to-service. The technology is collapsing the historical trade-off between thermal mass performance and fast-track delivery.
REACH chemical restrictions through ECHA are forcing reformulation of traditional polymer additives used in high-performance screeds. Manufacturers face substance authorization costs that disproportionately burden mid-volume formulators. German and French specification consultants are responding by prioritizing pre-certified low-VOC formulations in public sector tenders.
Buyer concentration among national flooring contractors is consolidating procurement decisions toward specification-locked supply agreements. Independent distributors lose share to direct manufacturer relationships with technical service components. The United Kingdom and Netherlands show the fastest channel consolidation as warranty-backed installation packages disarm price-only competition.
Floor Screeds Market Segmentation
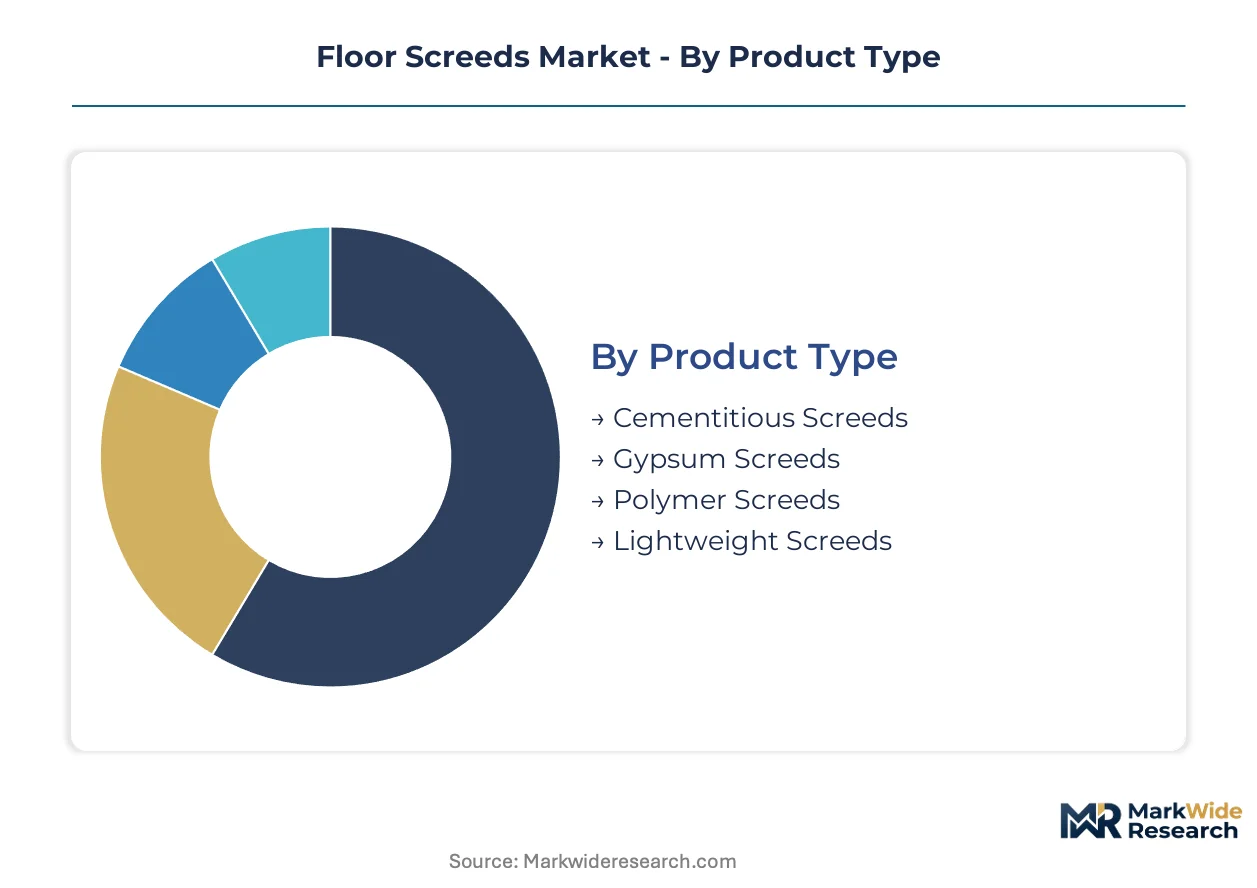
Segmentation in floor screeds reveals how specification priorities diverge across construction verticals. Product chemistry and installation methodology determine thermal performance, curing speed, and labor requirements. Understanding these trade-offs enables manufacturers to align R&D investment with procurement patterns in residential retrofit versus commercial new-build channels.
Product Type:
Cementitious formulations turn over on 15-20 year replacement cycles in existing stock, while polymer and lightweight systems capture specification share in fast-track projects demanding accelerated return-to-service.
- Cementitious Screeds:Portland cement and sand mixtures with standard 28-day compressive strength development dominate volume due to cost efficiency and broad compatibility with underfloor heating pipework. Demand concentrates in German residential retrofit programs where EnEV thermal performance mandates drive replacement of legacy uninsulated floors.
- Polymer Screeds:Acrylic or epoxy-modified formulations achieve walkable hardness within 4-6 hours, collapsing traditional curing timelines. Fast-track commercial specifications in UK mixed-use developments prioritize these systems where programme compression outweighs material cost premiums.
- Gypsum Screeds:Calcium sulfate hemihydrate bases deliver self-levelling flow characteristics without mechanical compaction.
- Lightweight Screeds:Expanded clay or perlite aggregates reduce dead load on structural frames.
Cementitious screeds dominate installed base. Polymer screeds are where expansion concentrates.
Installation Type:
Cost tiering separates specification approaches: bonded systems minimize material outlay while floating installations command premium positioning through acoustic and thermal performance bundling.
- Floating Screeds:Unbonded installations over mineral wool or rubber acoustic matting achieve impact sound reduction ratings required by multi-occupancy building codes. UK Building Regulations Part E and German DIN 4109 standards directly mandate these systems in apartment construction above ground-floor retail.
- Bonded Screeds:Direct adhesion to structural concrete substrates eliminates separation layers, reducing material cost and build-up height. Cost-sensitive residential developers in France specify bonded cementitious systems where acoustic performance requirements remain below regulatory thresholds.
- Unbonded Screeds:Separation membrane interfaces with structural slabs allow differential movement.
- Steel Reinforced Screeds:Mesh or fiber incorporation addresses crack control in high-load industrial bays.
Bonded screeds dominate installed base. Floating screeds are where expansion concentrates.
End User:
Volume concentration sits with residential construction, while margin capture concentrates in commercial and institutional segments where specification consulting and warranty-backed installation support create recurring revenue attachment.
- Commercial:Mixed-use developments, office fit-outs, and retail environments demand rapid-cure systems compatible with phased handover schedules. UK and French general contractors increasingly specify factory-blended formulations with environmental product declarations to satisfy public procurement criteria.
- Residential:Single-family and multi-family housing represents the largest addressable volume, driven by underfloor heating retrofit penetration in German and French existing stock.
- Industrial:Manufacturing and logistics facilities prioritize abrasion resistance and point-load capacity.
- Institutional:Healthcare and education projects emphasize low-VOC emissions and slip-resistant finish compatibility.
Residential dominates installed base. Commercial is where expansion concentrates.
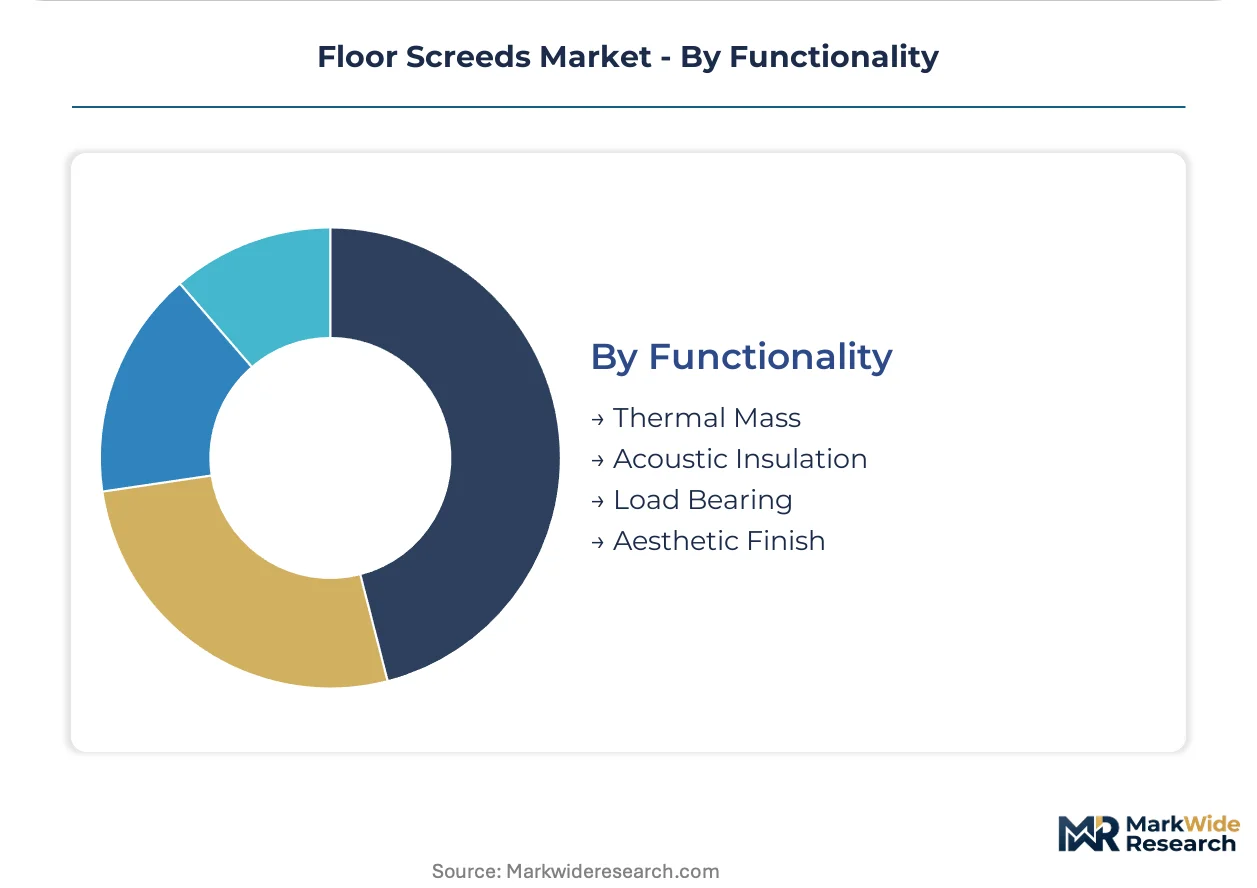
Functionality:
Maturity differentiation separates established thermal mass applications from emerging acoustic specification, where regulatory acceleration is compressing product development timelines.
- Thermal Mass:Screed systems with enhanced thermal conductivity optimize underfloor heating response times and reduce energy consumption. German EnEV and UK Part L building codes mandate minimum thermal resistance values that cementitious formulations with conductive aggregates satisfy.
- Acoustic Insulation:Impact and airborne sound attenuation through floating screed assemblies addresses stricter multi-occupancy standards. UK Building Regulations Part E revisions and French acoustic quality labels are expanding addressable demand beyond minimum compliance tiers.
- Load Bearing:High compressive strength specifications support industrial rack loading and vehicle traffic.
- Aesthetic Finish:Polished or dyed screed surfaces serve as final wearing layers in retail and exhibition spaces.
Thermal mass dominates installed base. Acoustic insulation is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and France exhibit the lowest price elasticity, prioritizing thermal certification and warranty-backed installation support over material cost. Specifiers in Southern Europe remain more sensitive to upfront outlay, driving bonded cementitious systems over floating assemblies.
Germany
Residential retrofit programs and EnEV thermal performance mandates sustain demand for underfloor heating-compatible cementitious formulations. The national building code mandates minimum thermal resistance values that accelerate replacement cycles in existing housing stock. Industrial clusters around Cologne and the Ruhr region concentrate synthetic gypsum supply chains and pre-blended formulation plants.
United Kingdom
Fast-track commercial specifications in mixed-use developments prioritize rapid-cure polymer systems where programme compression outweighs cost premiums. Building Regulations Part L and Part E revisions tighten thermal and acoustic performance thresholds. Greater London contractors increasingly lock into specification-locked supply agreements with embedded technical service components.
France
Public procurement criteria emphasizing environmental product declarations unlock preference for factory-controlled pre-blended formulations. The country's acoustic quality labels expand addressable demand for floating screed assemblies beyond minimum compliance tiers. Industrial concentration in the Île-de-France and Auvergne-Rhône-Alpes regions supports distribution logistics within the 250-300 kilometer effective radius.
Netherlands
Waste reduction mandates and carbon accounting rules for construction materials elevate specification of pre-blended systems with verified environmental product declarations. National building codes incorporate EU Green Deal energy performance targets that compress product development timelines. The Randstad urban corridor concentrates flooring contractor consolidation and direct manufacturer relationships.
Italy
Cost-sensitive residential developers specify bonded cementitious systems where acoustic performance requirements remain below regulatory thresholds. Regional building codes in Lombardy and Veneto adopt EU energy performance standards at varying implementation schedules. Northern industrial districts around Milan and Turin anchor formulation blending capacity serving Alpine climate thermal mass specifications.
Floor Screeds Market Vendor Landscape
Integrated chemical conglomerates and specialized construction chemical groups split the market along capability depth versus geographic breadth. The structure consolidates around three archetypes: captive additive suppliers with backward integration into polymer chemistry, formulation specialists with embedded technical service teams, and scale-driven building materials conglomerates with distribution density. Competitive moves concentrate on pre-certification of low-carbon formulations ahead of national code revisions and warranty-backed installation packages that disarm price-only competition.
Among German-origin chemical conglomerates, BASF SE anchors the captive supply archetype through in-house production of polymer additives for high-performance formulations. Swiss-based Sika AG exemplifies the technical service-embedded model with specification consulting capabilities. Italian specialist Mapei S.p.A. occupies a position representing formulation expertise with on-site support infrastructure.
| Leading Market Players |
|---|
| BASF SE |
| Bostik |
| Sika AG |
| Flowcrete Group |
| LafargeHolcim |
| Ardex Group |
| Saint-Gobain |
| Knauf Gips |
| Mapei S.p.A. |
| Others |
Supply Flow & Price Mechanics
REACH chemical authorization timelines through ECHA compress formulation certification windows and simultaneously widen pricing spreads between pre-certified low-VOC systems and legacy products awaiting reformulation, concentrating procurement power with manufacturers holding captive additive supply.
Pricing Analysis
Specification-locked warranty packages drive lifetime value capture across installation support, technical consulting, and maintenance programs. Three-tier pricing structure across premium polymer-modified, standard cementitious, and economy bonded systems separates procurement decisions by project urgency and certification requirements. Pricing pressure stems from buyer consolidation among national flooring contractors demanding bundled service components. Residential retrofit segments in Southern Europe exhibit highest price sensitivity, while German and French commercial specifiers prioritize thermal certification over material cost.
Supply Chain Analysis
Export-control scrutiny on synthetic polymer additives limits formulation flexibility for producers dependent on specialized acrylic and epoxy modifiers. Supply concentrates in Germany, France, and the United Kingdom, with raw material dependencies spanning synthetic gypsum from northwestern European industrial clusters, Portland cement from regional kilns, and polymer additives from captive chemical conglomerates. Single-source vulnerability concentrates in calcium sulfate supply chains exposed to energy-price-linked volatility. Distribution runs through direct manufacturer relationships with embedded technical service teams, displacing independent distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Floor screeds demand tracks construction cycle recovery, with residential retrofit programs and commercial new-build acceleration in Germany and the United Kingdom providing cyclical uplift.
For Market Incumbents: Insulate specification position by deepening captive supply of polymer additives and accelerating environmental product declaration certification ahead of national code revisions. Pre-certify low-carbon formulations before EU Green Deal implementation tightens. Anchor distribution through warranty-backed installation packages that neutralize price-only competition from regional specialists.
For New Entrants and Emerging Players: Build out technical service infrastructure targeting acoustic insulation specification in UK multi-occupancy construction, where Building Regulations Part E revisions expand addressable demand beyond incumbent capture. Prioritize floating screed installations over mineral wool systems in mixed-use developments. Establish direct contractor relationships in the Netherlands and France where procurement consolidation favors embedded support models.
For Investors and Strategic Acquirers: ECHA substance authorization deadlines reshape the acquisition landscape toward mid-volume formulators with pre-certified low-VOC portfolios and established technical service teams. Long-term viability hinges on positioning for carbon accounting rules and factory-controlled pre-blended production. Monitor CE marking documentation backlogs as inflection indicator for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Additives | Captive supply of acrylic and epoxy modifiers secures formulation flexibility against REACH authorization delays. |
| Factory Pre-Blended Production Scale-Up | Controlled manufacturing enables environmental product declaration compliance for French and Dutch public procurement. |
| Technical Service Team Embedding | On-site specification consulting with major UK flooring contractors locks in recurring revenue attachment. |
| Low-VOC Formulation Pre-Certification | Pre-certified systems capture German and French public sector tenders ahead of ECHA substance restrictions. |
| Acoustic Insulation System Partnerships | Collaboration with mineral wool and rubber mat suppliers addresses UK Building Regulations Part E mandates. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, national building code filings, and chemical regulatory submissions. Primary interviews engaged formulation chemists at pre-blended manufacturing plants, procurement leads at national flooring contractors, technical specification consultants, and distribution channel managers. Secondary validation drew from ECHA REACH substance databases, EU energy performance directive implementations, and construction materials trade association reports. Bottom-up volume estimates triangulated against top-down market sizing.
Forecast inputs span product chemistry segmentation, installation methodology categories, end-use verticals, and functionality requirements across the projection horizon. Modeled dimensions include cementitious versus polymer versus gypsum formulations, bonded versus floating versus unbonded installations, residential versus commercial versus institutional demand, and thermal mass versus acoustic insulation functionality. CAGRs derived from elasticity-adjusted demand curves incorporating underfloor heating penetration rates and building code revision schedules.
Stress conditions across synthetic gypsum price volatility, REACH authorization timeline extensions, and skilled installer availability constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions on regulatory implementation pace and construction cycle recovery trajectory. Material shifts in ECHA substance restriction scope or EU Green Deal carbon accounting methodology would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
China Concrete Superplasticizer Market
Building & Construction Materials
Fire Hydrant System Market
Building & Construction Materials
Europe I-Joist Market
Building & Construction Materials
Polished Concrete Market
Building & Construction Materials
North America Particle Board Market
Building & Construction Materials
North America Gypsum Board Market
Building & Construction Materials
Door System Market
Building & Construction Materials
Global Roofing Market
Building & Construction Materials
North America Roofing Market
Building & Construction Materials
North America Insulated Concrete Form (ICF) Market
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market
Building & Construction Materials
Europe Sandwich Panels Market
Building & Construction Materials
Building Insulation Materials Market
Building & Construction Materials
Insulated Wall Panels Market
Building & Construction Materials
Mineral Wool Ceiling Tiles Market
Building & Construction Materials
India UPVC Doors and Windows Market