
 Ocular Implants Market | 2026-2036
Ocular Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Ocular Implants Market Intelligence
The procedural shift towards Ambulatory Surgical Centers is hardening the competitive landscape for ocular implant manufacturers. Alcon Inc. leverages its extensive portfolio of intraocular lenses and surgical equipment to secure contracts with these centers. Johnson & Johnson Services Inc. sustains its market position through continuous R&D in new materials and lens designs. Carl Zeiss AG differentiates by integrating its advanced diagnostic systems with its surgical implant offerings.
Ocular implants are medical devices surgically placed inside or on the surface of the eye to correct vision or treat ophthalmic diseases. These devices are often fabricated from biocompatible polymers like hydrophobic acrylic or silicone to minimize inflammatory responses. Intraocular lenses used in cataract surgery constitute the largest product segment by volume. Glaucoma implants represent a high-growth category, addressing a significant unmet need in chronic eye pressure management.
Market access requires stringent regulatory approvals, such as the FDA's Premarket Approval process in the United States and CE marking under the EU's Medical Device Regulation. In China, the National Medical Products Administration oversees clearance for all ophthalmic devices. Manufacturers must navigate these complex and diverging regulatory pathways while investing in clinical data to prove long-term safety and efficacy.
Market Dynamics
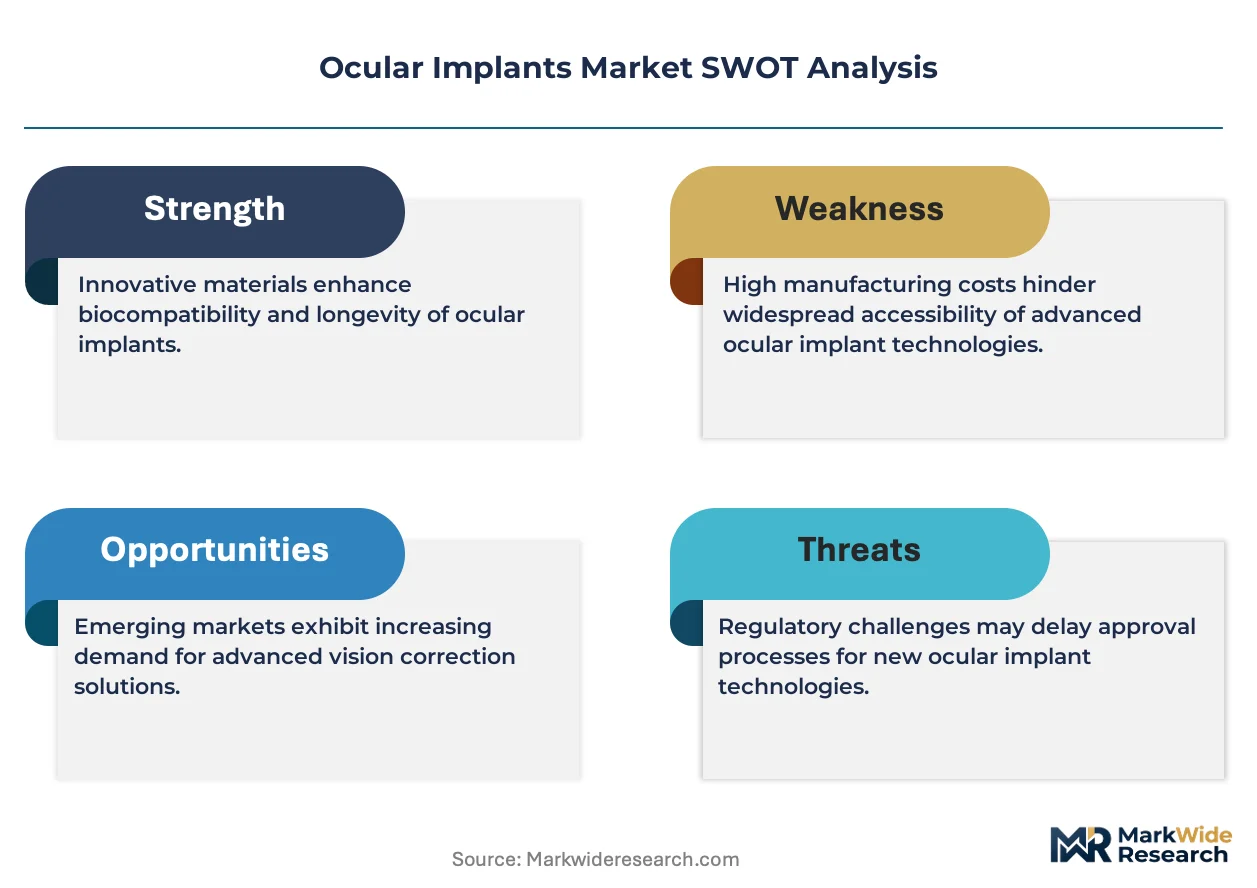
The central force shaping the ocular implants market is the intersection of an aging global demographic, which increases the procedural volume for cataracts and glaucoma, and the escalating regulatory demand for extensive long-term clinical data to prove implant safety and efficacy.
Growth Catalysts
- Advanced Materials:The development of new biocompatible polymers, such as enhanced hydrophobic acrylics and silicone hydrogels, improves patient outcomes by reducing postoperative inflammation and improving visual acuity.
- Demographic Shifts:A rising prevalence of age-related eye conditions like cataracts and presbyopia, particularly in populous countries such as China and India, is expanding the addressable patient population.
- Surgical Technique Evolution:The adoption of micro-invasive glaucoma surgery (MIGS) and femtosecond laser-assisted cataract surgery (FLACS) creates demand for specialized implants compatible with these less invasive procedures.
Market Restraints
- Cost and Reimbursement:High out-of-pocket expenses for premium, presbyopia-correcting intraocular lenses act as a significant barrier for patients in markets with limited insurance coverage for advanced technologies.
- Regulatory Hurdles:The stringent Premarket Approval (PMA) process by the FDA and the complex requirements of the EU's Medical Device Regulation (MDR) create long and costly pathways to market entry.
- Surgical Risks:Potential postoperative complications, including posterior capsular opacification or endothelial cell loss, can deter some patients and surgeons from choosing certain types of implants despite their benefits.
Strategic Opportunities
- Technology Convergence:Integrating micro-electro-mechanical systems (MEMS) into implants offers a pathway to create smart devices capable of continuous intraocular pressure monitoring for glaucoma management.
- Underserved Geographies:Expanding access to affordable cataract surgery and basic intraocular lenses in rural regions of Southeast Asia and Africa represents a substantial volume opportunity.
- Drug-Eluting Implants:Developing implants that can provide sustained release of medications, such as steroids to control inflammation or drugs to lower eye pressure, addresses a key unmet clinical need.
Industry Challenges
- Specialized Skill Gaps:A shortage of ophthalmic surgeons trained on the newest surgical platforms and advanced implant insertion techniques can slow the adoption of next-generation products in some regions.
- Interoperability Standards:The lack of standardization between diagnostic equipment, surgical systems, and implant data from different manufacturers complicates workflow integration within ophthalmic clinics and surgical centers.
- Clinical Data Demands:Generating the extensive, long-term patient follow-up data required by regulators like the NMPA in China and the PMDA in Japan is a costly and time-consuming challenge for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ocular Implants Market |
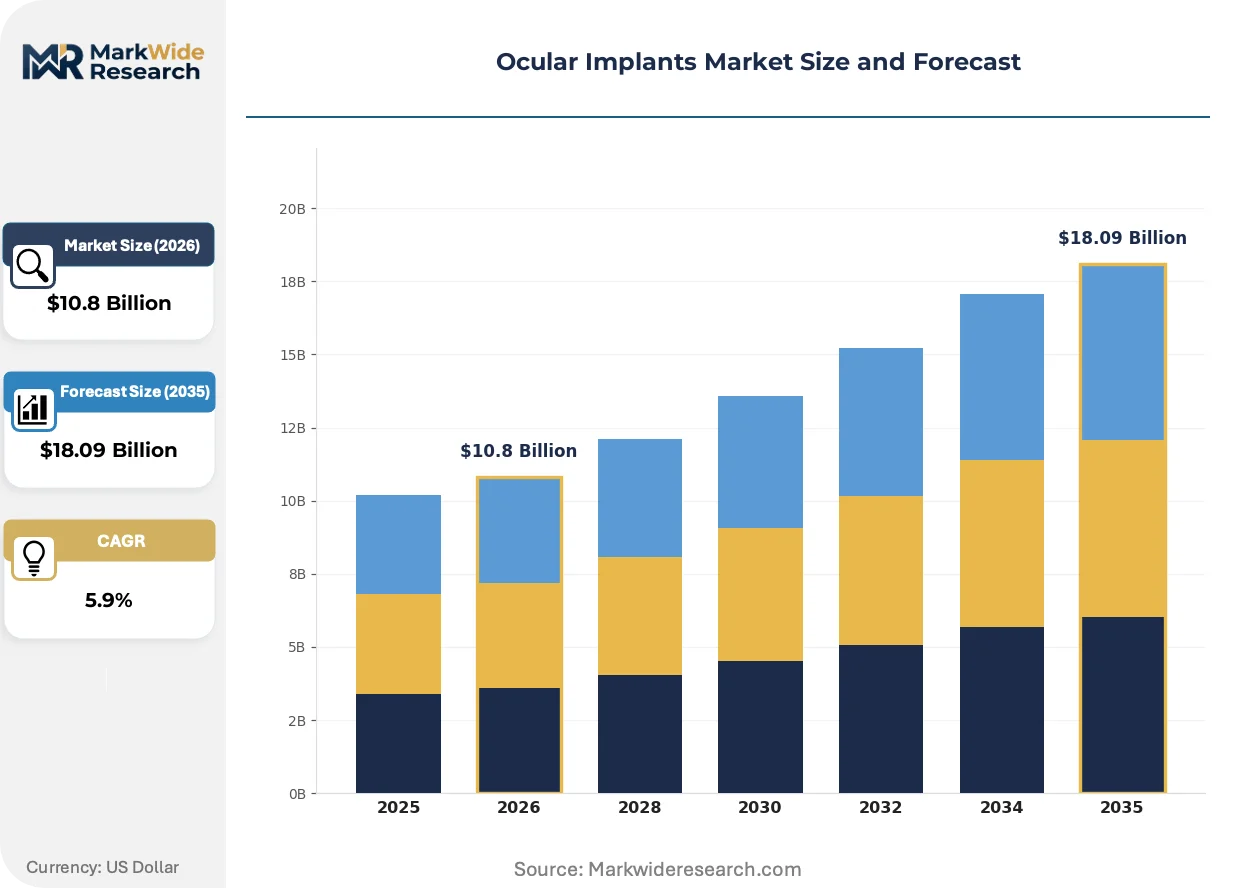
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $18.09 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
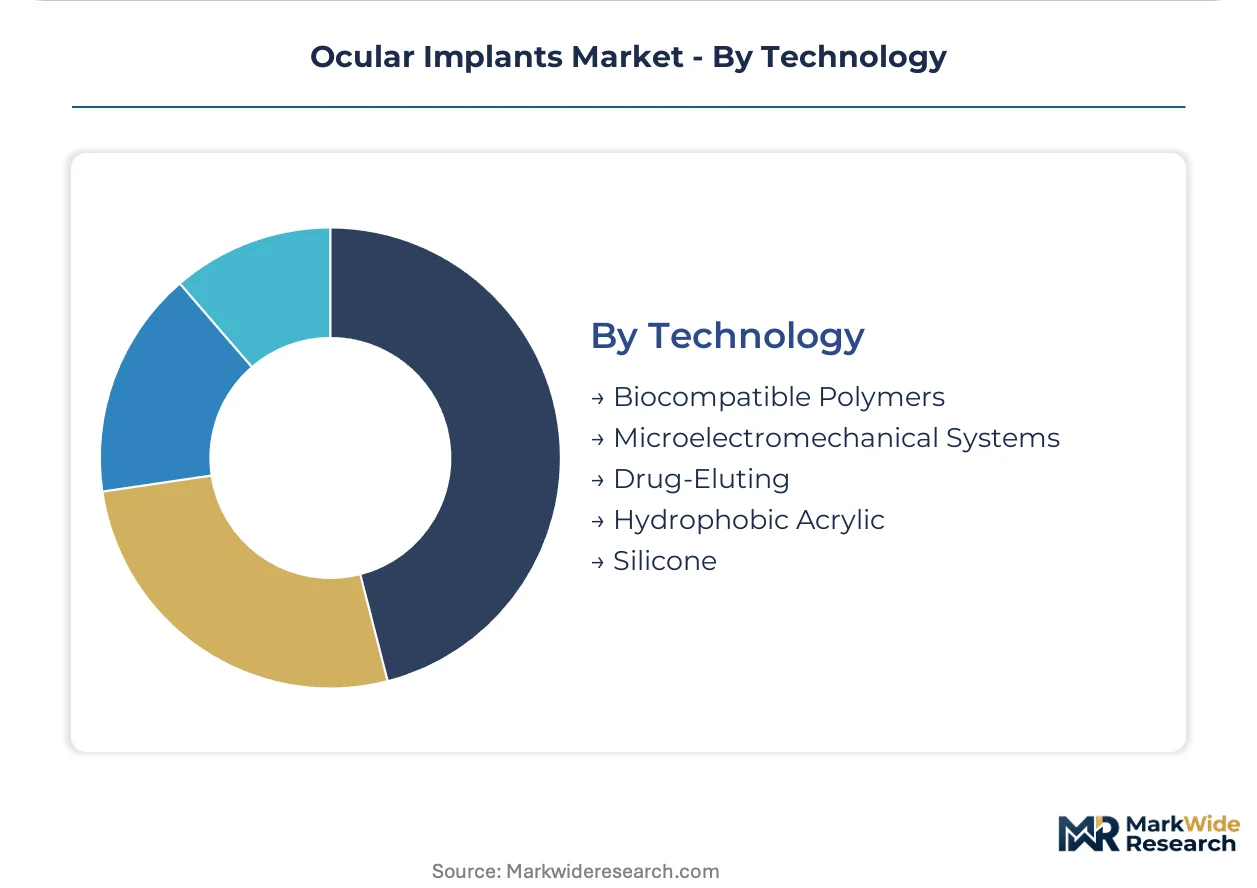
| Segmentation | Product Type: Intraocular Lenses, Glaucoma Implants, Retina Implants, Corneal Implants, Orbital Implants Therapy Area: Cataract, Glaucoma, Age-Related Macular Degeneration, Diabetic Retinopathy, Retinitis Pigmentosa End User: Ophthalmic Clinics, Eye Hospitals, Specialty Clinics, Ambulatory Surgical Centers Technology: Biocompatible Polymers, Microelectromechanical Systems, Drug-Eluting, Hydrophobic Acrylic, Silicone |
| Companies Covered | Johnson & Johnson Services Inc., Morcher GmbH, Alcon Inc., Hoya Corp., Glaukos Corporation, Bausch & Lomb Inc., STAAR Surgical Company, Rayner Intraocular Lenses Limited, Carl Zeiss AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ocular Implants Market Strategic Shifts & Innovations
A convergence of material science and data integration is redefining implant functionality. The market is moving beyond simple vision correction toward implants that offer therapeutic benefits, personalized visual outcomes, and data-generating capabilities for chronic disease management.
Extended depth of focus (EDOF) intraocular lenses represent a significant product evolution, engineered to provide a continuous range of vision from near to far. Patients seeking greater independence from glasses after cataract surgery are the primary adopters of this technology. This lens design is consolidating the premium implant segment by offering a more favorable balance of visual range and reduced optical disturbances compared to older multifocal lens designs.
The European Union’s Medical Device Regulation (MDR) has fundamentally altered the compliance landscape. This framework imposes stricter requirements for clinical evidence and post-market surveillance on all medical devices, including ocular implants. The glaucoma implant and intraocular lens segments are most affected, as manufacturers must now invest in more rigorous and continuous clinical follow-up studies to maintain their CE marking and market access in Europe.
Patient decision-making is undergoing a notable transformation, with individuals conducting extensive independent research on different implant technologies before surgery. This behavioral shift disrupts the traditional model where surgeons were the sole arbiters of lens selection, forcing manufacturers to engage in more direct patient education. The trend is most visible in developed markets with high internet penetration, such as the United States and Australia.
Ocular Implants Market Segmentation
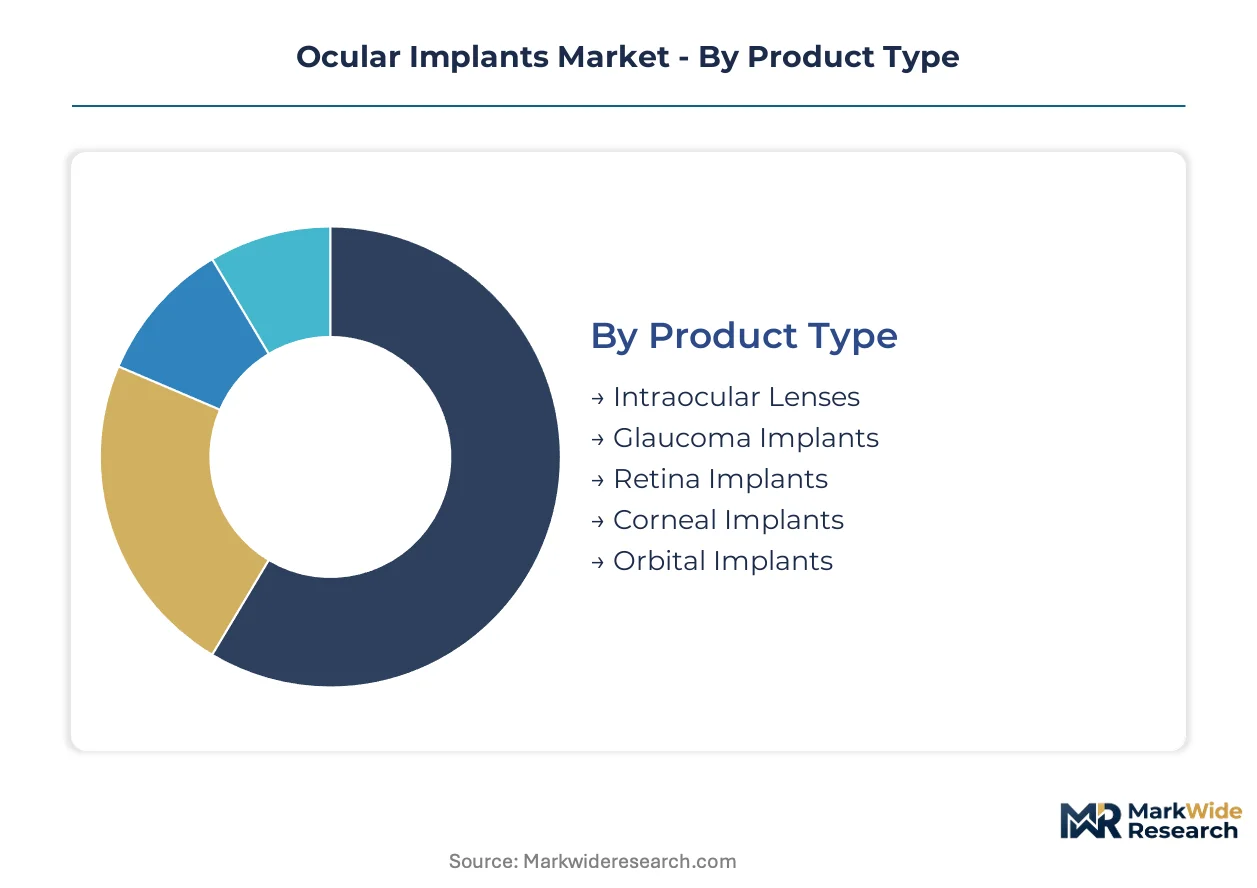
Understanding the segmentation of the ocular implants market is crucial for manufacturers to align their product development and market strategies with evolving clinical needs. This granular view reveals where investment is concentrating and which patient populations are benefiting most from advanced ophthalmic solutions.
Product Type:
The development of ocular implants often demands substantial upfront investment, particularly in product types requiring extensive R&D and advanced manufacturing capabilities.
- Intraocular Lenses:These devices are surgically implanted to replace the eye's natural lens, primarily during cataract surgery, and are often made from biocompatible materials like hydrophobic acrylic or silicone. Demand for these lenses is concentrating in China and India, driven by an aging demographic and increasing access to ophthalmic care.
- Glaucoma Implants:Designed to manage intraocular pressure in patients with glaucoma, these implants include shunts and micro-invasive devices that facilitate fluid drainage. Demand is strong in developed markets where chronic eye pressure management is a significant unmet need.
- Retina Implants:These advanced prostheses are used to restore partial vision in patients with severe retinal degeneration, often incorporating microelectronics.
- Corneal Implants:Employed to replace or reshape a damaged cornea, these implants can be synthetic or derived from donor tissue.
- Orbital Implants:Placed in the eye socket after enucleation, these devices help restore facial symmetry and support an ocular prosthesis.
Most installed capacity flows through Intraocular Lenses. Expansion is steepest in Glaucoma Implants.
Therapy Area:
Therapy areas dictate the overall volume of procedures performed, reflecting the prevalence of specific eye conditions and their treatability with implants.
- Cataract:This therapy area involves the surgical removal of a clouded natural lens and its replacement with an intraocular lens, representing the highest volume of ocular implant procedures globally. Demand is universal, but particularly high in populous countries with aging populations.
- Glaucoma:Management of glaucoma involves implants to lower intraocular pressure, preventing further optic nerve damage and vision loss, often using micro-invasive surgical techniques. Developed markets show high demand due to early diagnosis and chronic disease management.
- Age-Related Macular Degeneration:This condition, a leading cause of vision loss, is increasingly addressed by retinal implants and other advanced therapeutic devices.
- Diabetic Retinopathy:A complication of diabetes, this therapy area may involve drug-eluting implants for sustained medication delivery to the retina.
- Retinitis Pigmentosa:A rare genetic disorder, this area utilizes highly specialized retinal prostheses to restore some visual function.
Procedural volume is dominated by Cataract. New therapeutic approaches are gaining share most rapidly in Glaucoma.
End User:
The choice of end-user facility for ocular implant procedures is increasingly influenced by operational efficiency and the ability to manage patient flow effectively.
- Ambulatory Surgical Centers:These centers specialize in outpatient surgical procedures, including many ocular implant surgeries, offering cost-effective and efficient care. These facilities are increasingly preferred in the United States for routine cataract surgeries.
- Eye Hospitals:Comprehensive facilities offering a full spectrum of ophthalmic care, from diagnostics to complex surgeries and inpatient services, accommodating a wider range of patient needs. Expanding access to specialized ophthalmic care in China drives demand in these settings.
- Ophthalmic Clinics:These clinics primarily focus on diagnostic services, consultations, and non-surgical treatments, often referring patients for implant procedures.
- Specialty Clinics:Dedicated to specific eye conditions or procedures, these clinics provide focused expertise and advanced treatment options.
Efficiency gains are most pronounced in Ambulatory Surgical Centers. Comprehensive care remains centered in Eye Hospitals.
Technology:
Technological segmentation highlights the evolution from established material sciences to advanced, integrated systems that enhance implant functionality and patient outcomes.
- Biocompatible Polymers:These advanced materials, such as hydrophobic acrylic and silicone, form the foundation of many ocular implants, minimizing inflammatory responses and enhancing long-term patient outcomes. Continuous R&D by companies like Johnson & Johnson Services Inc. focuses on improving these materials.
- Microelectromechanical Systems:MEMS technology is being integrated into smart implants for continuous monitoring, such as intraocular pressure for glaucoma management, representing a significant leap in device functionality. This technology offers strategic opportunities in chronic disease management.
- Drug-Eluting:This technology involves implants designed to release medication slowly over time, providing sustained therapeutic effects for conditions like inflammation or high eye pressure.
- Hydrophobic Acrylic:A widely used material for intraocular lenses, valued for its optical clarity, stability, and low rate of posterior capsular opacification.
- Silicone:This polymer is used in various ocular implants due to its flexibility, biocompatibility, and optical properties.
Established material science underpins Biocompatible Polymers. Future innovation is significantly driven by Microelectromechanical Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta region in China anchors global demand for ocular implants, driven by its large aging population and expanding access to specialized ophthalmic care. This market experiences significant regional variations in regulatory pathways and healthcare infrastructure. Manufacturers must navigate diverse reimbursement policies and surgical practice standards across different geographies.
China
Demand for intraocular lenses and glaucoma implants is concentrating in China, propelled by an aging demographic and increasing access to specialized ophthalmic care. The National Medical Products Administration (NMPA) oversees clearance for all ophthalmic devices, requiring extensive clinical data. Major ophthalmic centers in the Yangtze River Delta region are expanding their capacity for advanced ocular procedures.
United States
The United States market for ocular implants is characterized by a procedural shift towards Ambulatory Surgical Centers, which prioritize efficiency and cost-effectiveness. The FDA's Premarket Approval (PMA) process ensures stringent regulatory oversight for new devices. Medical device clusters in regions like Boston-Cambridge drive innovation in ophthalmic technology and surgical techniques.
Germany
Germany maintains strong demand for advanced ocular implants, supported by a robust healthcare system and a focus on high-quality patient outcomes. CE marking under the EU's Medical Device Regulation (MDR) establishes strict requirements for clinical evidence and post-market surveillance. The Baden-Württemberg region, a hub for medical technology, fosters R&D in biocompatible materials and integrated diagnostic systems.
Japan
Japan's significantly aging population creates a consistent demand for cataract and glaucoma implants, alongside an emphasis on precision and technological sophistication. The Pharmaceuticals and Medical Devices Agency (PMDA) imposes rigorous standards for device approval and post-market safety. Research and development activities, particularly in the Tokyo metropolitan area, focus on next-generation implant designs.
India
India presents a substantial volume opportunity for affordable cataract surgery and basic intraocular lenses, driven by a large, underserved population. The Central Drugs Standard Control Organization (CDSCO) regulates medical devices, with efforts to streamline approval processes for essential ophthalmic products. Bengaluru's growing medical technology ecosystem supports the development of cost-effective implant solutions.
Ocular Implants Market Key Industry Players
Portfolio diversification dominates the current landscape for ocular implant manufacturers, as companies seek to offer comprehensive solutions across various ophthalmic conditions. The market structure is tiered, with established global players competing alongside specialized technology innovators and regional niche providers. Key competitive moves include strategic partnerships to expand product portfolios and significant R&D investments in new materials and designs.
Within the established global player archetype, Alcon Inc. leverages its extensive portfolio of intraocular lenses and surgical equipment to secure contracts with Ambulatory Surgical Centers. Johnson & Johnson Services Inc. sustains its market position through continuous research and development in new materials and lens designs. Carl Zeiss AG exemplifies a player that differentiates by integrating its advanced diagnostic systems with its surgical implant offerings, providing a comprehensive solution to ophthalmic clinics.
| Leading Market Players |
|---|
| Johnson & Johnson Services Inc. |
| Morcher GmbH |
| Alcon Inc. |
| Hoya Corp. |
| Glaukos Corporation |
| Bausch & Lomb Inc. |
| STAAR Surgical Company |
| Rayner Intraocular Lenses Limited |
| Carl Zeiss AG |
| Others |
Cost & Logistics Intelligence
Captive material production, particularly for specialized biocompatible polymers, anchors the supply position for leading ocular implant manufacturers and confers significant pricing power for premium intraocular lenses.
Pricing Analysis
Input-cost pass-through remains critical for advanced ocular implants, given the high R&D and regulatory compliance expenses. Value-based pricing models dominate, reflecting the therapeutic benefits and improved patient outcomes. Price differentiation occurs based on the implant's technological sophistication, such as extended depth of focus lenses, and the brand premium associated with established manufacturers like Alcon Inc. Pricing softness affects basic intraocular lenses due to increased competition in developing markets. Patients with limited insurance coverage for advanced technologies represent the most price-sensitive segment, while those seeking optimal visual outcomes prioritize quality over cost.
Supply Chain Analysis
Direct-to-hospital and Ambulatory Surgical Center distribution models handle the majority of ocular implant sales, emphasizing specialized logistics and inventory management. Geographic supply concentration for raw materials like hydrophobic acrylic and silicone rests primarily in East Asia and Europe. The supply chain relies heavily on specialized component manufacturers for microelectronics in advanced implants. Regulatory restriction, particularly the stringent approval processes in China and the EU, represents a significant structural risk. Manufacturers often manage inventory through consignment models to streamline hospital procurement processes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ocular implants market presents a clear margin-expansion story, driven by the increasing adoption of premium lens technologies that command higher price points.
For Market Incumbents: Cement market leadership through continuous investment in R&D for next-generation materials and lens designs. Portfolio diversification across intraocular lenses and glaucoma implants mitigates the threat from specialized technology innovators. Strategic partnerships with Ambulatory Surgical Centers enhance channel control and procedural volume. Investment in clinical data generation for long-term safety and efficacy is a critical lever for maintaining regulatory approvals and brand trust.
For New Entrants and Emerging Players: A price-point gap exists between premium and basic intraocular lenses in underserved geographies like Southeast Asia. Target the high-growth glaucoma implant segment with innovative micro-invasive devices, leveraging a focused R&D approach. India presents the most penetrable geography for affordable cataract surgery solutions. A direct-to-ophthalmic clinic sales model, emphasizing specialized training and technical support, offers a viable go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for ophthalmic device specialists because structural fragmentation exists among smaller technology innovators. The long-term viability of this market is strong, supported by an aging global demographic and continuous innovation in material science. Acquisition targets should include firms with proprietary drug-eluting implant technologies or advanced MEMS integration capabilities. A signal to watch is the increasing reimbursement coverage for premium presbyopia-correcting lenses.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Acceleration | Expedites market access for innovative ocular implants in the United States. |
| Advanced Biocompatible Polymer R&D | Enhances implant longevity and reduces postoperative complications for patients. |
| Hospital System Partnership Expansion | Secures preferred vendor status and streamlines procurement for high-volume procedures. |
| Glaucoma Implant Portfolio Diversification | Addresses a significant unmet need in chronic eye pressure management globally. |
| Digital Integration with Diagnostic Systems | Improves surgical planning and patient outcomes through data-driven approaches. |
Research Approach
Multiple input streams—primary interviews with industry stakeholders, secondary validation from regulatory filings, and market intelligence reports—were reconciled to construct a comprehensive market view. This approach involved extensive discussions with ophthalmic surgeons, hospital purchasing committees, GPO contracts managers, and R&D directors to gather qualitative insights. Secondary data sources included FDA 510(k) and PMA documents, NMPA clearance records, medical device registries, and clinical trial databases, ensuring robust data triangulation from both bottom-up and top-down perspectives.
Historical data, cross-referenced with expert panel input, informed the analytical framework across the projection horizon. The forecast model integrated segmentation dimensions such as product type, therapy area, end user, technology, and key geographies. Compound Annual Growth Rates (CAGRs) were derived from projected market values, considering factors like demographic shifts, technological advancements, and regulatory changes. Industry-specific forecast inputs included cataract surgery volumes and glaucoma prevalence rates.
Caveats apply where significant regulatory changes, unforeseen material science breakthroughs, or shifts in reimbursement policy could materially shift the outlook. Forecasts reflect a specific set of assumptions regarding market dynamics and technological adoption over the analysis window. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Quadripodal Implants Market
Medical Devices
Esophagoscopes and Gastroscopes Market
Medical Devices
Infusion Pump Market
Medical Devices
PET-CT Scanner Device Market
Medical Devices
Germanium-68/Gallium-68 Generators Market
Medical Devices
Electric Handpiece Market
Medical Devices
Endoluminal Device Systems Market
Medical Devices
Upper Limb Prosthetics Market
Medical Devices
Canada General Surgical Devices Market
Medical Devices
Flexible and Semi-Rigid Ureteroscopy Market
Medical Devices
Global Surgical Visualization Products Market
Medical Devices
Hemorrhage Control System Market
Medical Devices
Breathing Exercise Devices Market
Medical Devices
Heated Humidifiers Market
Medical Devices
Global PC-Based Audiometer Market
Medical Devices
Endoscope Flushing Pumps Market