
 Turkmenistan Oil and Gas Upstream Market | 2026-2036
Turkmenistan Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Turkmenistan Oil and Gas Upstream Market Analytics
Buyer concentration among Chinese petrochemical importers is recalibrating contract structures across Turkmenistan's upstream sector. JSC Türkmennebit leverages state-backed field development rights across onshore supergiant structures. China National Petroleum Corp anchors cross-border pipeline offtake through its Central Asia-China gas corridor investments. Dragon Oil PLC competes on offshore Caspian recovery rates using extended-reach drilling platforms.
Turkmenistan oil and gas upstream encompasses exploration, drilling, production, and reservoir management of hydrocarbon reserves, with wells frequently exceeding depths of 4,500 meters in carbonate formations beneath the South Caspian Basin. The primary purpose is extracting raw natural gas and crude oil for pipeline export and domestic processing into petroleum products and liquefied natural gas. Natural gas dominates product-type volumes given Galkynysh and Dauletabad field scale, while crude oil segments face steeper decline rates at mature onshore assets. Geophysical services command premium pricing in offshore blocks where complex salt tectonics obscure seismic imaging.
Turkmenistan's national hydrocarbon regulator and the State Agency for Management and Use of Hydrocarbon Resources enforce local-content thresholds and environmental permitting for Caspian offshore operations. These frameworks shape contractor selection, equipment sourcing rules, and field abandonment bonding requirements. Stakeholders must monitor how evolving local-content mandates affect service-type procurement and whether reservoir-management technology transfers accelerate under amended partnership terms.
Market Dynamics
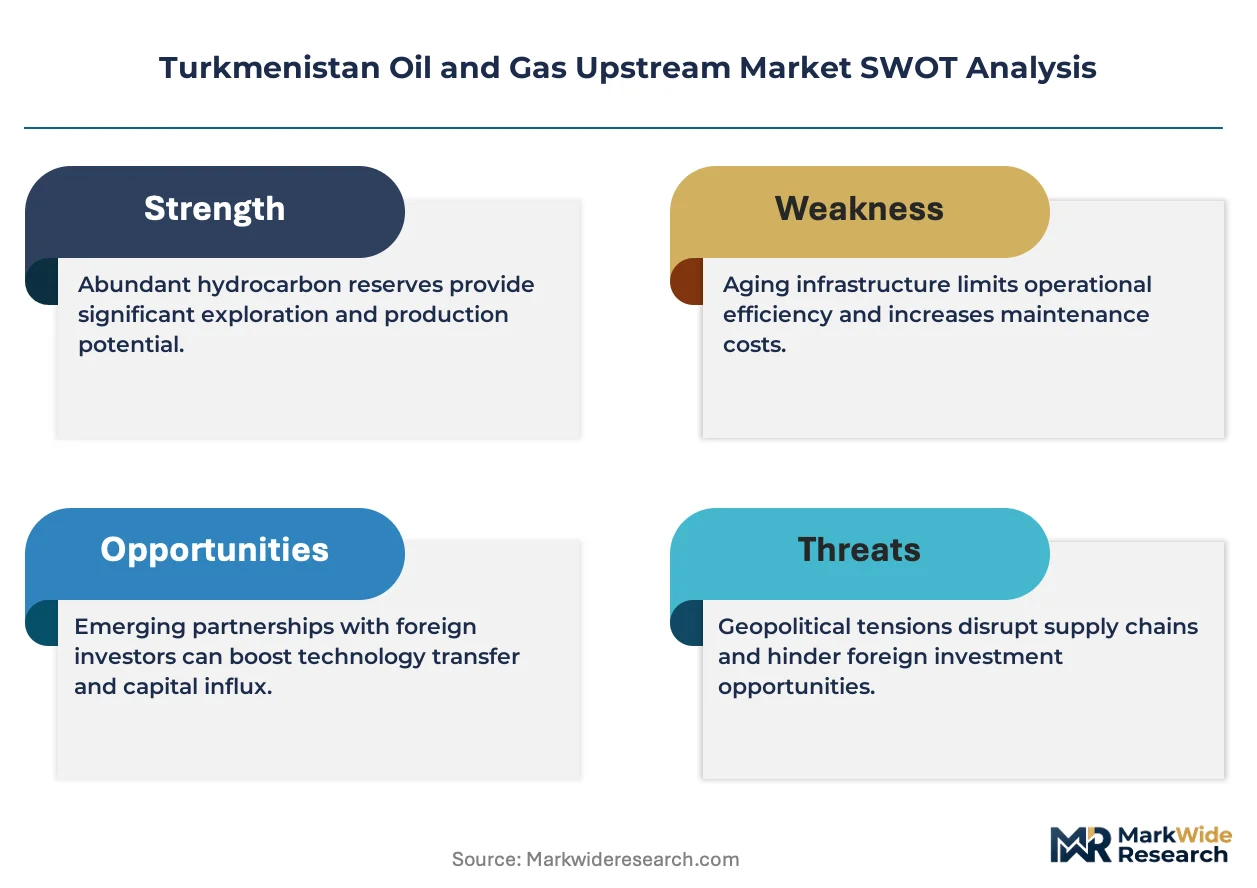
Chinese petrochemical procurement consolidation is restructuring contract economics across Turkmenistan's upstream sector, compressing offtake margins while amplifying volume commitments through the Central Asia-China gas corridor.
Growth Catalysts
- Local-content mandates:The State Agency for Management and Use of Hydrocarbon Resources enforces rising domestic procurement thresholds for offshore Caspian blocks, redirecting service spend toward Turkmen contractors and fabrication yards.
- Extended-reach drilling:Advanced directional drilling capabilities are unlocking stranded reserves beneath complex salt tectonics in the South Caspian Basin, expanding recoverable volumes from existing platforms.
- Pipeline infrastructure anchoring:The Central Asia-China gas corridor locks in multi-decade offtake volumes, de-risking field development capex through guaranteed export routes.
Market Restraints
- Capital intensity of ultra-deep targets:Carbonate formations exceeding 4,500 meters require specialized high-pressure drilling equipment, inflating per-well costs beyond breakeven at moderate gas prices.
- Buyer concentration risk:Chinese state-owned importers dominate offtake contracting, creating asymmetric negotiating leverage that compresses Turkmenistan's fiscal terms.
- Seismic imaging limitations:Complex salt diapirs in offshore blocks obscure reservoir delineation, elevating exploration risk and deterring non-state investment.
Strategic Opportunities
- Eastern Caspian untapped structures:Unlicensed blocks near the Galkynysh cluster offer scale potential for integrated service providers with enhanced oil recovery expertise.
- Reservoir management technology transfer:Amended partnership terms now permit foreign operators to deploy real-time production optimization systems previously restricted under legacy contracts.
- Geophysical premium services:Advanced 3D seismic processing for salt-proximal targets commands pricing power unavailable in conventional onshore surveys.
Industry Challenges
- Specialized drilling talent scarcity:Extended-reach and high-pressure well construction require expertise concentrated among international service firms, creating staffing bottlenecks during campaign ramps.
- Legacy contract renegotiation complexity:Existing production-sharing agreements contain technology-transfer clauses that conflict with amended local-content rules, generating legal friction.
- Environmental bonding compliance:Field abandonment requirements demand upfront capital reserves that strain contractor cash flows, particularly for smaller service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkmenistan Oil and Gas Upstream Market |
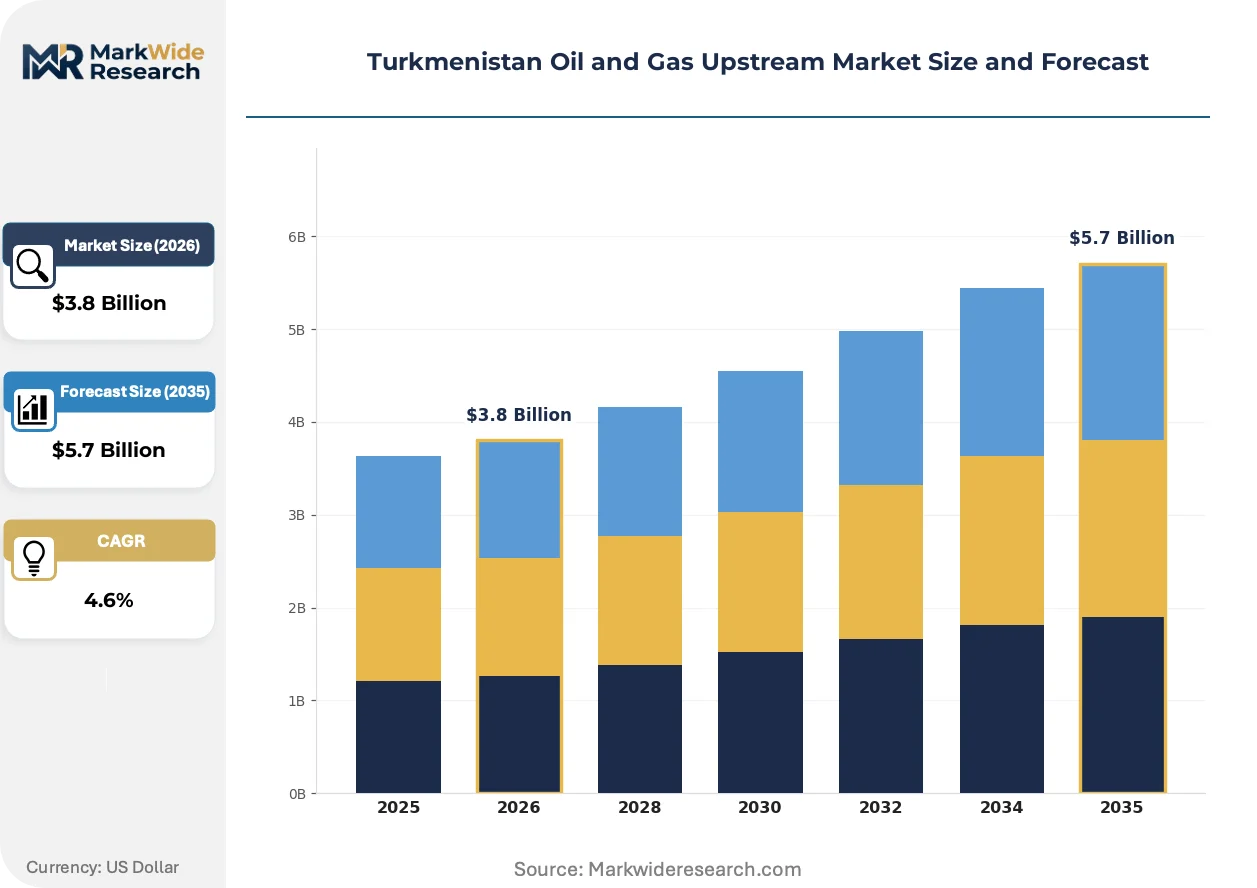
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Drilling, Exploration, Production, Reservoir Management Product Type: Natural Gas, Crude Oil, Petroleum Products, Liquefied Natural Gas Service Type: Geophysical Services, Well Services, Engineering Services, Maintenance Services End User: Oil Companies, National Oil Companies, Independent Producers, Contractors |
| Companies Covered | JSC Türkmennebit, Eni SpA, Dragon Oil PLC, Hyundai Engineering & Construction Co, Buried Hill Energy, China National Petroleum Corp, Petronas Carigali, ADNOC, JSC Türkmengaz, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkmenistan Oil and Gas Upstream Market Evolving Landscape
Digital instrumentation and automated subsurface analytics are displacing manual reservoir interpretation across Turkmenistan's supergiant fields, compressing decision cycles while tightening integration between geoscience and production operations.
Real-time drilling telemetry is automating wellbore steering decisions in carbonate formations beneath the South Caspian Basin. Dragon Oil PLC and other offshore operators deploy networked downhole sensors to adjust trajectory without surface intervention. This capability is automating geosteering workflows that previously required 12-hour lab turnaround, reducing non-productive time in high-angle sections.
The State Agency for Management and Use of Hydrocarbon Resources has tightened environmental permitting timelines for Caspian offshore drilling campaigns. Operators now submit integrated digital twins alongside traditional impact assessments. Offshore blocks in the Galkynysh corridor face the steepest compliance burden, with proponents pre-positioning monitoring buoys before spudding to accelerate approval.
Chinese petrochemical buyers are consolidating annual procurement into multi-year framework agreements with volume floors and price collars. This restructuring displaces spot cargo contracting that historically dominated Turkmen gas trade. The shift is most visible in methanol and ammonia feedstock sourcing, where importers now demand supply security over price flexibility.
Turkmenistan Oil and Gas Upstream Market Segmentation
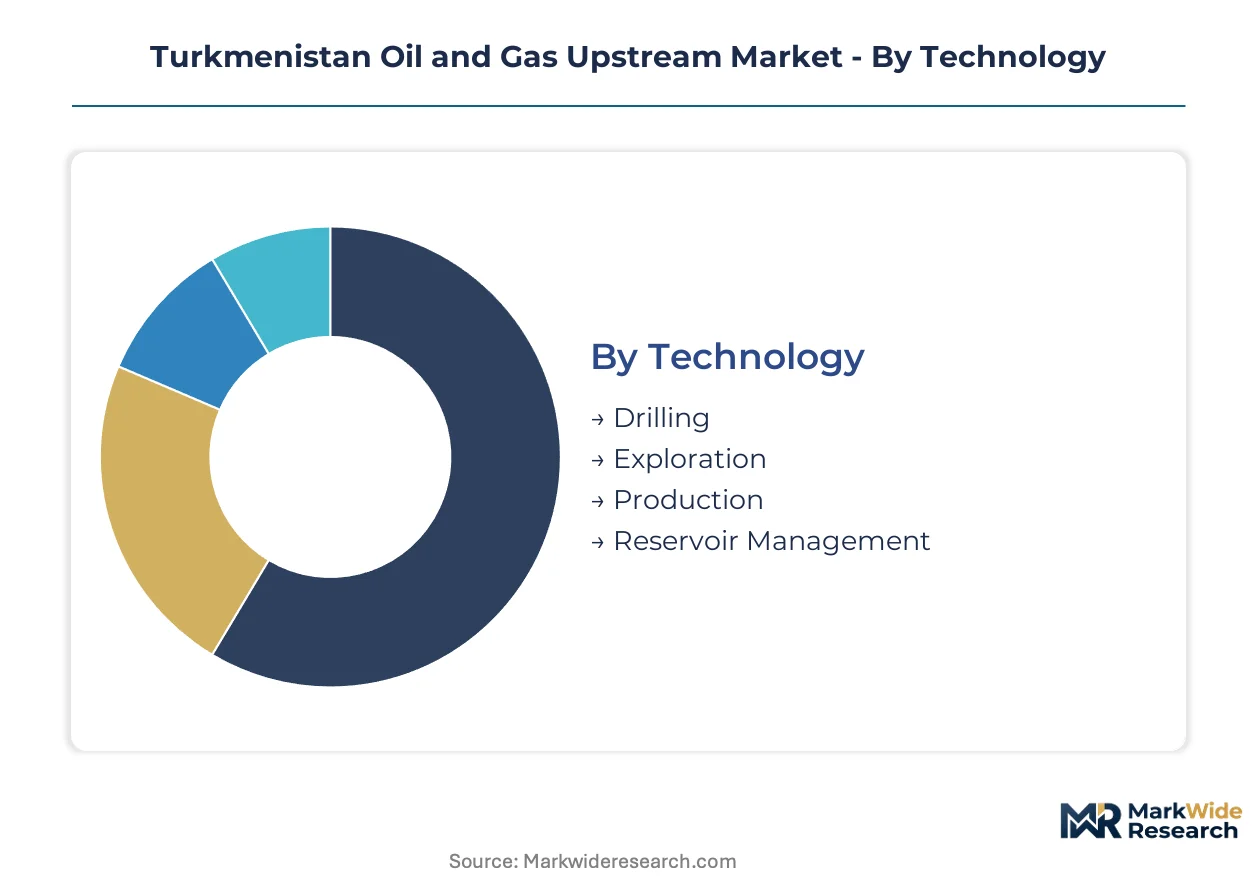
Segmentation in Turkmenistan's upstream market reveals how technology choices, product focus, and service procurement align with the State Agency's local-content mandates and Chinese offtake contract structures. Understanding these divisions exposes where capital concentrates and where regulatory pressure reshapes contractor selection.
Technology:
Buyers prioritize drilling and production technologies that satisfy volume commitments to the Central Asia-China gas corridor while meeting escalating local-content thresholds for offshore Caspian blocks.
- Drilling:Extended-reach directional systems penetrate carbonate formations exceeding 4,500 meters beneath the South Caspian Basin. Demand clusters at the Galkynysh field cluster where high-angle well construction unlocks stranded reserves trapped beneath complex salt tectonics, though specialized high-pressure equipment inflates per-well capex.
- Production:Real-time optimization systems automate subsurface analytics across supergiant fields, compressing decision cycles between geoscience and operations. Chinese petrochemical buyers now require guaranteed volume floors in offtake contracts, forcing operators to prioritize production reliability over exploration risk.
- Exploration:Advanced 3D seismic processing targets salt-proximal structures in offshore blocks where imaging limitations historically deterred investment.
- Reservoir Management:Digital twins and automated wellbore steering reduce non-productive time in high-angle sections.
Volume sits with Production; growth tilts toward Drilling as operators push into ultra-deep targets.
Product Type:
Contract economics hinge on whether output feeds pipeline export commitments or domestic processing, with natural gas commanding structural preference due to locked-in corridor offtake.
- Natural Gas:Galkynysh and Dauletabad field scale anchors multi-decade supply contracts through the Central Asia-China gas corridor. Chinese state-owned importers now consolidate procurement into multi-year frameworks with volume floors, displacing spot cargo contracting that historically dominated Turkmen trade.
- Crude Oil:Mature onshore assets face steeper decline rates and limited export route diversification. Output serves domestic refineries and regional swap arrangements rather than long-haul pipeline commitments, compressing fiscal terms relative to gas.
- Petroleum Products:Refined output from Turkmenbashi complex supplies Central Asian markets.
- Liquefied Natural Gas:Small-scale LNG serves remote domestic demand and limited marine export.
Revenue concentrates in Natural Gas; expansion potential clusters in Liquefied Natural Gas if marine infrastructure develops.
Service Type:
Margin capture depends on technical specialization depth, with geophysical and engineering services commanding premiums unavailable in commoditized maintenance work.
- Geophysical Services:Complex salt diapirs in offshore Caspian blocks obscure reservoir delineation, elevating exploration risk and pricing power for advanced seismic processing. The State Agency now mandates integrated digital twins alongside traditional impact assessments, tightening compliance timelines for drilling campaign approval.
- Engineering Services:Extended-reach drilling platform design and high-pressure well construction require expertise concentrated among international service firms. Local-content rules redirect spend toward Turkmen contractors, creating staffing bottlenecks during campaign ramps.
- Well Services:Completion and intervention work scales with active well count in supergiant fields.
- Maintenance Services:Routine asset integrity work faces margin compression from domestic procurement mandates.
Procurement value pools in Geophysical Services; capability buildout targets Engineering Services under amended partnership terms.
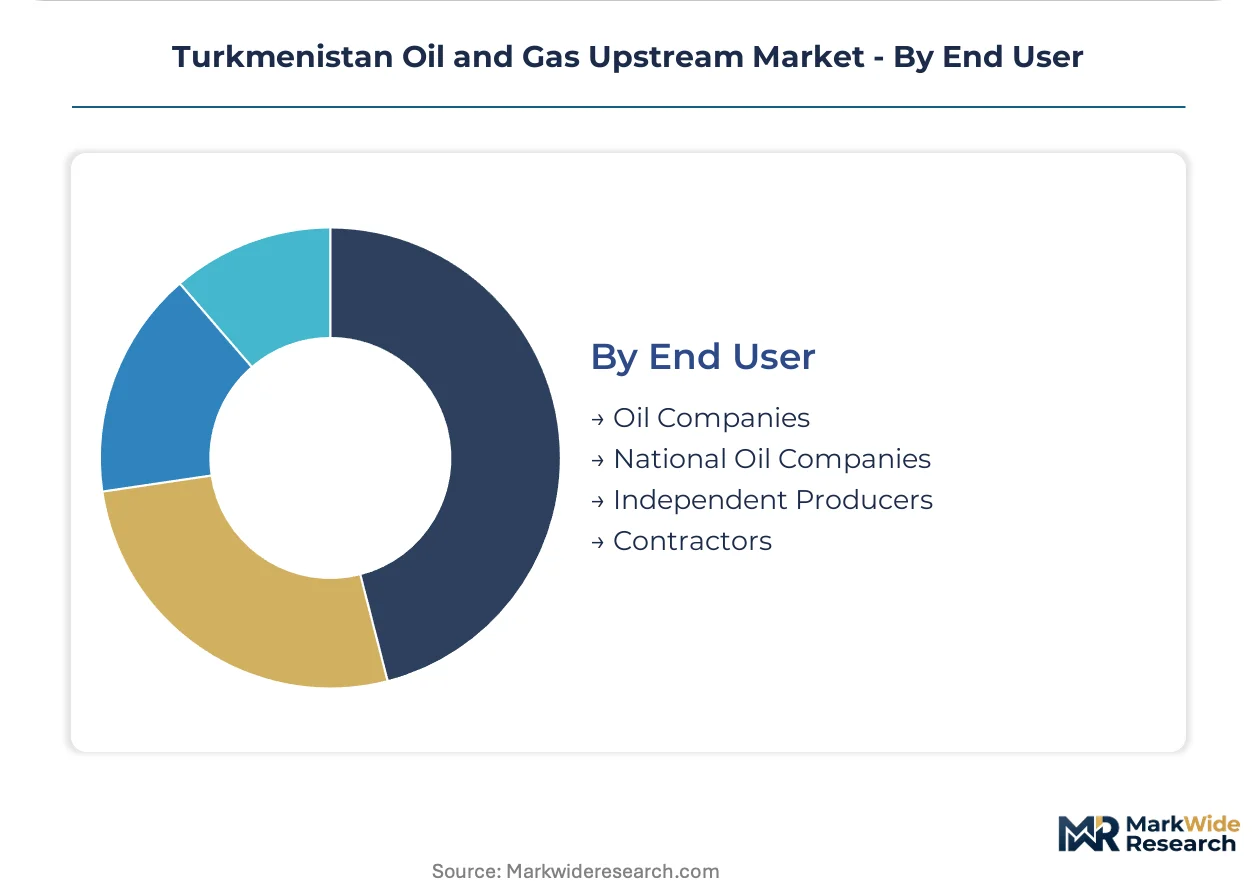
End User:
Contract access stratifies by state backing and field development rights, with national oil companies controlling supergiant structures and independents competing on technical recovery rates.
- National Oil Companies:JSC Türkmennebit leverages state-backed field development rights across onshore supergiant structures. The State Agency's tightening local-content rules for offshore blocks reinforce NOC primacy in licensing and contractor selection.
- Oil Companies:Dragon Oil PLC competes on offshore Caspian recovery rates using extended-reach drilling platforms. Amended partnership terms now permit foreign operators to deploy real-time production optimization systems previously restricted under legacy contracts.
- Independent Producers:Smaller operators target marginal onshore assets and service partnerships.
- Contractors:Service providers navigate rising domestic procurement thresholds and field abandonment bonding requirements that strain cash flows.
Investment authority rests with National Oil Companies; operational innovation emerges from Oil Companies under revised technology-transfer provisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese petrochemical buyers anchor demand concentration across Central Asian upstream corridors, restructuring contract flows through the Central Asia-China gas pipeline network. Field development rights concentrate near the Galkynysh cluster and South Caspian offshore blocks where local-content enforcement tightens.
Ashgabat Metropolitan Corridor
The capital region hosts Turkmenistan's hydrocarbon regulatory apparatus and state oil company headquarters. The State Agency for Management and Use of Hydrocarbon Resources operates permitting frameworks from Ashgabat, enforcing domestic procurement thresholds that redirect service contracts toward Turkmen fabrication yards. Engineering procurement concentrates in the capital's administrative district where amended partnership terms are negotiated.
Balkan Province Offshore Zone
Offshore Caspian blocks beneath complex salt tectonics drive geophysical service demand. Dragon Oil PLC deploys extended-reach drilling platforms from coastal supply bases near Turkmenbashi. The State Agency mandates integrated digital twins alongside environmental impact assessments, compressing approval timelines for drilling campaigns in this corridor.
Lebap Province Eastern Fields
The Dauletabad gas field cluster anchors pipeline export volumes through the Central Asia-China corridor. China National Petroleum Corp locks in multi-decade offtake commitments that de-risk field development capex. Service providers face rising domestic procurement thresholds as the State Agency redirects spend toward Lebap-based contractors.
Mary Province Supergiant Cluster
The Galkynysh field complex represents Turkmenistan's largest hydrocarbon structure, driving natural gas production scale. JSC Türkmennebit leverages state-backed development rights across these onshore supergiant formations. Real-time production optimization systems now deploy under amended partnership terms previously restricted under legacy contracts.
Dashoguz Province Northern Assets
Mature onshore oil fields face steeper decline rates and limited export route diversification. Output serves domestic refineries rather than long-haul pipeline commitments, compressing fiscal terms relative to gas-focused provinces. Smaller independent producers target marginal assets through service partnerships with limited capital intensity.
Turkmenistan Oil and Gas Upstream Market Competitive Landscape
Turkmenistan-based state operators anchor one tier; international specialists hold operational positions under amended production-sharing terms. The market structure reflects state primacy in licensing supergiant onshore structures alongside foreign technical participation in offshore recovery optimization. Two archetypes dominate: state-backed national oil companies controlling field development rights, and international oil companies competing on technical recovery rates. Competitive moves center on technology transfer renegotiation and local-content compliance restructuring.
Among state-backed operators, JSC Türkmennebit and JSC Türkmengaz exemplify the national oil company archetype with field development rights across onshore supergiant structures. Dragon Oil PLC occupies a position among international specialists deploying extended-reach capabilities in offshore Caspian blocks. These entities represent contrasting competitive positions: state operators leverage licensing authority while international players compete through technical differentiation in complex salt-tectonic environments.
| Leading Market Players |
|---|
| JSC Türkmennebit |
| Eni SpA |
| Dragon Oil PLC |
| Hyundai Engineering & Construction Co |
| Buried Hill Energy |
| China National Petroleum Corp |
| Petronas Carigali |
| ADNOC |
| JSC Türkmengaz |
| Others |
Value Network & Pricing Analysis
Specialized drilling engineers concentrated in Azerbaijan and Kazakhstan service corridors command wage premiums that widen spreads between standard and premium-tier geophysical contracts across Turkmenistan's Caspian blocks. Labor-cost differentials between international specialists and domestic trainees under amended local-content rules compress margins at the mid-tier while sustaining premium pricing for salt-proximal seismic processing.
Pricing Analysis
Volume commitments to the Central Asia-China gas corridor dominate contract economics, with long-term offtake agreements locking in floor prices that shield upstream operators from spot-market volatility. Price differentiation hinges on recovery-rate guarantees and real-time production optimization system inclusion, with Chinese state-owned importers least sensitive to unit pricing given supply-security priorities. Cost compression in standard drilling services intensifies as domestic procurement mandates redirect spend toward Turkmen fabrication yards with limited high-pressure equipment expertise. Smaller independent contractors face acute price sensitivity due to field abandonment bonding requirements that strain working capital.
Supply Chain Analysis
ISO 45001 and API Q2 certification requirements gate entry for directional drilling contractors serving offshore Caspian blocks, filtering qualified suppliers to a narrow tier of international service firms with Turkmen joint-venture structures. Equipment sourcing draws from China, South Korea, and Germany for high-pressure blowout preventers, managed pressure drilling systems, and subsea wellheads. Single-source vulnerability concentrates in advanced downhole sensor networks where two manufacturers control telemetry hardware. Distribution runs through coastal supply bases near Turkmenbashi and overland logistics corridors to the Galkynysh field cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkmenistan's upstream market operates as a supply-constrained system where extended-reach drilling talent scarcity props pricing power for certified international service providers despite local-content mandates.
For Market Incumbents: Deploy real-time production optimization technology licensing as the primary lever to defend margin position against emerging digital-native entrants offering automated reservoir analytics. Backward integration into high-pressure equipment maintenance capabilities in Balkan Province reduces dependency on South Korean OEM service windows. Counter the State Agency's escalating domestic procurement thresholds by pre-qualifying Turkmen joint-venture partners with transferable API certifications. For New Entrants and Emerging Players: Remote diagnostics platforms offer the lowest-friction entry vector for penetrating the geophysical services segment without immediate capital commitment to offshore vessel assets. White-space opportunity clusters in Dauletabad field cluster reservoir management services where legacy contracts lack digital-twin provisions. Target Lebap Province engineering procurement through partnerships with state-backed fabrication yards seeking technology-transfer credibility. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap drilling contractors holding API Q2 certification and existing Turkmen joint-venture structures given the State Agency's amended partnership terms permitting foreign technology deployment. Long-term viability frames around five-to-ten year windows anchored by Central Asia-China gas corridor volume commitments. Monitor Chinese petrochemical buyer consolidation patterns as the inflection signal for contract-structure shifts toward or away from spot-market exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Agreement | Dragon Oil PLC and similar offshore operators now deploy real-time optimization systems previously restricted under legacy production-sharing terms. |
| Joint Venture with Local Fabrication | Turkmenbashi-based yards gain API certification credibility while international partners satisfy State Agency local-content mandates. |
| Long-term Supply Agreement | China National Petroleum Corp locks in multi-decade offtake volumes through Central Asia-China gas corridor investments. |
| Backward Integration into Equipment Servicing | High-pressure drilling system maintenance capabilities reduce South Korean OEM dependency and compress non-productive time. |
| Digital Twin Certification Program | Integrated environmental monitoring systems accelerate State Agency permitting timelines for Galkynysh corridor drilling campaigns. |
Research Methodology
Multi-period observation of drilling campaign costs, local-content compliance rates, and Chinese offtake contract structures anchored the trend analysis, supplemented by interviews with upstream operations directors at international oil companies, procurement leads at Turkmen state oil enterprises, geophysical service firm technical managers, and Central Asia-China pipeline logistics coordinators. Secondary validation drew from State Agency regulatory filings, customs equipment import records, CNPC infrastructure investment disclosures, and South Caspian Basin seismic survey databases. Bottom-up field-level cost builds triangulated against top-down corridor export volume assessments.
Segment-weighting applied technology-type splits across drilling, production, and exploration categories, with product-type differentiation between natural gas and crude oil output streams, and service-type stratification by technical specialization depth. Modeled dimensions spanned well depth tiers, recovery mechanism categories, and regional regulatory enforcement clusters. CAGRs derived from production volume trajectories tied to pipeline infrastructure commissioning schedules and reserve replacement ratios across the projection horizon. Forecast inputs incorporated carbonate formation drilling success rates and salt-tectonic imaging cost curves.
The model holds under sustained Central Asia-China gas corridor throughput commitments and stable local-content enforcement intensity; deviation in Chinese petrochemical demand patterns or State Agency technology-transfer rule amendments would shift upstream investment viability thresholds. Forecasts reflect documented assumptions around drilling cost inflation and offshore block licensing timelines. A model refresh is warranted upon material change in CNPC procurement consolidation pace or Galkynysh cluster production plateau timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Offshore Drilling Riser Market
Offshore Oil and Gas
Marine Scrubber Market
Offshore Oil and Gas
Denmark Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Floating Production Storage and Offloading Market
Offshore Oil and Gas
North Sea Oil and Gas Market
Offshore Oil and Gas
Europe Offshore Energy Market
Offshore Oil and Gas
Asia-Pacific Offshore Energy Market
Offshore Oil and Gas
Norway Oil and Gas Downstream Market
Offshore Oil and Gas
Africa Oil and Gas Downstream Market
Offshore Oil and Gas
India Oil and Gas Upstream Market
Offshore Oil and Gas
Europe Floating Offshore Wind Power Market
Offshore Oil and Gas
FPSO Market
Offshore Oil and Gas
Brazil Offshore Energy Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
Norway Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Asia-Pacific Floating Offshore Wind Power Market