
 South Korea Digital X-Ray Market | 2026-2036
South Korea Digital X-Ray Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Digital X-Ray Market Analytics
Multi-source procurement of flat-panel detectors is restructuring how South Korean health systems negotiate equipment refresh cycles. Samsung Medison Co. Ltd leverages its domestic manufacturing footprint to shorten delivery timelines for public hospital tenders. GE Healthcare competes through service contract bundling that anchors long-term customer relationships.
Digital X-ray systems capture projection radiographs using solid-state detectors with spatial resolution typically exceeding 2.5 line pairs per millimeter, converting ionizing radiation directly into electronic images for diagnostic interpretation. Portable X-Ray equipment leads volume shipments as clinics prioritize point-of-care flexibility over fixed-room installations. Digital Radiography technology captures the dominant margin pool, while Wireless Imaging represents the fastest-expanding configuration as cable-free workflow integration spreads through outpatient networks.
MFDS device licensing and KIS radiation safety standards govern product registration and clinical deployment across South Korean territory. MFDS enforcement of electromagnetic compatibility testing shapes import timelines for multinational suppliers. Stakeholders must monitor how reimbursement rate adjustments for advanced imaging modalities influence capital allocation between public and private provider networks.
Market Dynamics
Flat-panel detector supply consolidation is restructuring how South Korean health systems negotiate equipment refresh cycles, with domestic manufacturing proximity becoming a decisive tender criterion over pure unit economics.
Growth Catalysts
- MFDS Certification Streamlining:The Ministry of Food and Drug Safety has compressed review timelines for domestically manufactured Class II medical devices, accelerating hospital fleet replacement schedules in Seoul's metropolitan network.
- Gyeonggi-do Diagnostic Cluster Expansion:Provincial health authorities are consolidating outpatient imaging services into centralized diagnostic hubs, generating concentrated demand for wireless digital radiography systems.
- Wireless Imaging Protocol Standardization:KIS standards for cable-free workflow integration have unified interoperability requirements across public hospital networks, reducing integration friction for new equipment deployments.
Market Restraints
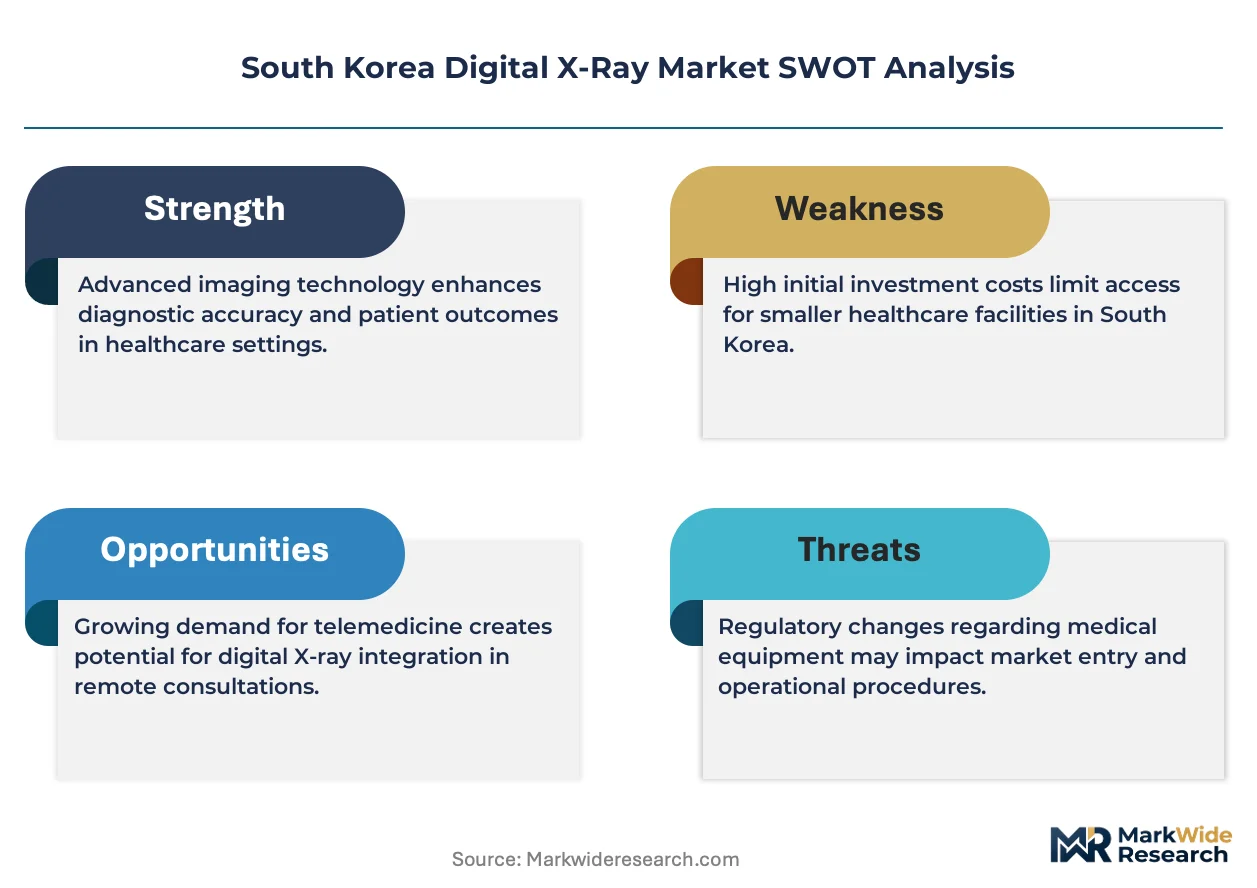
- Flat-Panel Detector Import Dependency:South Korean manufacturers remain reliant on amorphous silicon sensor substrates from concentrated East Asian foundry sources, exposing procurement timelines to regional supply volatility.
- KIS Radiation Safety Compliance Costs:Tightening electromagnetic compatibility testing requirements under Korean Industrial Standards have extended validation periods for multinational suppliers without domestic assembly facilities.
- Computed Tomography Substitution Pressure:Low-dose CT protocols are capturing diagnostic volumes previously assigned to projection radiography in oncology and trauma screening applications.
Strategic Opportunities
- Busan-Ulsan Medical Manufacturing Belt:Underpenetrated diagnostic infrastructure in South Korea's southeastern industrial corridor presents whitespace for mobile X-ray deployments serving shipyard occupational health programs.
- AI-Assisted Image Interpretation Convergence:Integration of deep-learning diagnostic algorithms with digital radiography workstations is creating premium pricing tiers for equipment bundles that include automated abnormality flagging.
- Public Hospital Leasing Programs:Korea Health Industry Development Institute financing instruments are shifting capital allocation from outright purchase toward operational expenditure models for mid-tier clinic networks.
Industry Challenges
- MFDS Electromagnetic Compatibility Certification Timelines:Multinational suppliers face 8-14 month validation periods for software-upgraded hardware variants, compressing product lifecycle competitiveness against domestic manufacturers.
- PACS Integration Architecture Complexity:Legacy hospital information systems in South Korea's aging public hospital infrastructure require costly middleware development for seamless DICOM connectivity with wireless detector platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Digital X-Ray Market |
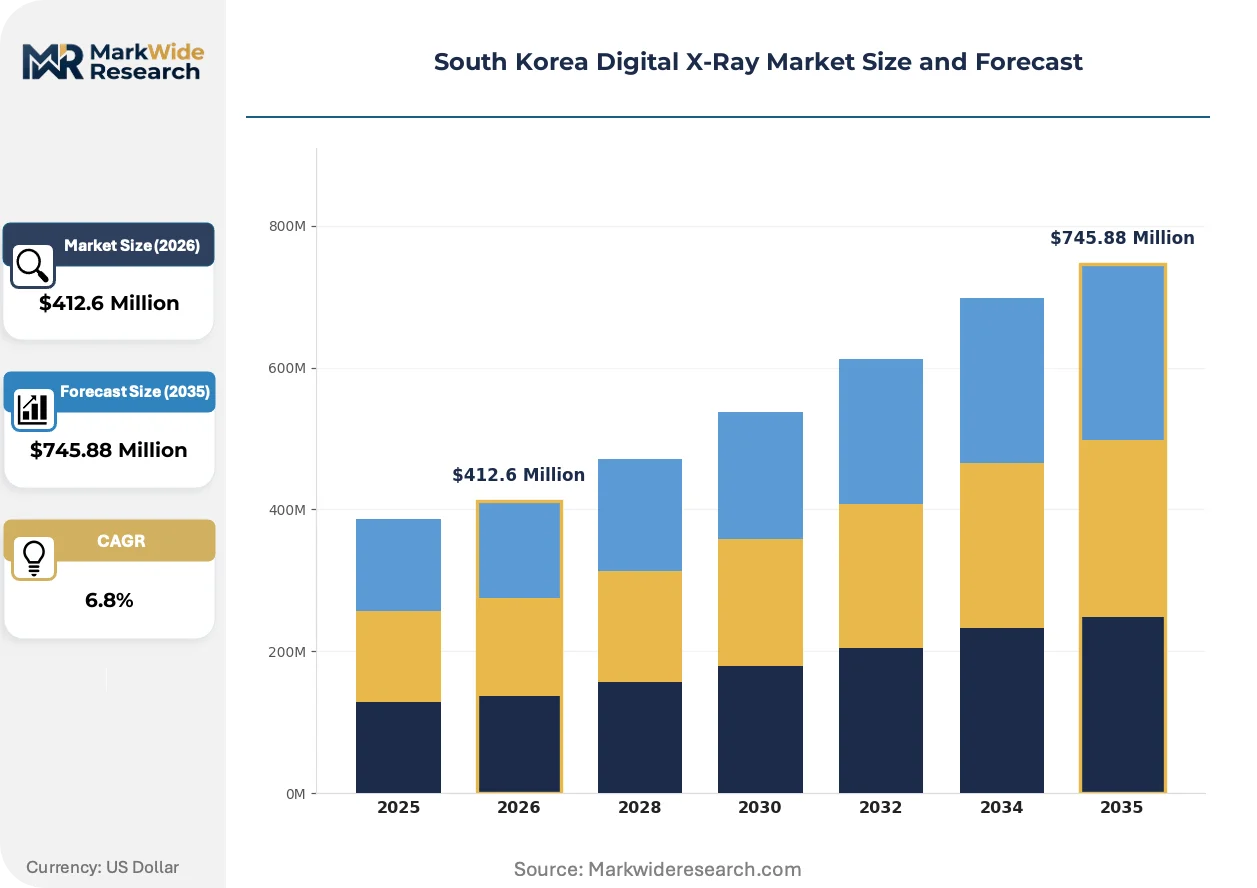
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable X-Ray, Fixed X-Ray, Fluoroscopy, Computed Radiography End User: Hospitals, Clinics, Diagnostic Centers, Research Facilities Technology: Digital Radiography, Computed Tomography, Wireless Imaging, Hybrid Imaging Application: Orthopedics, Dentistry, Cardiology, Oncology |
| Companies Covered | Carestream Health, GE Healthcare, Siemens Healthineers AG, Koninklijke Philips NV, Canon Medical Systems Corporation, Samsung Medison Co. Ltd, Genoray Co. Ltd, Medonica Co. Ltd, DK Medical System, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Digital X-Ray Market Evolving Landscape
Wireless detector configurations are overtaking fixed-room installations as the dominant procurement specification, with outpatient network flexibility now prioritized over throughput optimization in equipment selection criteria.
Direct-conversion cadmium-zinc-telluride sensors are overtaking indirect-conversion scintillator technologies in premium system configurations. Seoul's tertiary hospital networks are specifying these detectors for musculoskeletal and mammography applications where spatial resolution demands exceed 3.5 line pairs per millimeter. The structural consequence is compressing margin pools for manufacturers without captive semiconductor fabrication capabilities or deep partnerships with compound semiconductor foundries.
MFDS enforcement of electromagnetic compatibility testing under KIS C 61000-6-1 standards is reshaping import timelines for multinational suppliers. Device registration dossiers now require South Korea-specific radiated immunity validation that duplicates EU CE marking test protocols but demands local laboratory certification. European and North American manufacturers are responding by establishing domestic assembly partnerships to qualify for streamlined domestic manufacturer review pathways.
After-sales service unbundling is fragmenting traditional equipment procurement relationships. Gyeonggi-do clinic networks are separating detector hardware acquisition from maintenance contracts, awarding multi-vendor service agreements to independent technical service organizations. This pattern is most visible in the outpatient diagnostic segment where equipment utilization rates do not justify captive manufacturer technician deployment.
South Korea Digital X-Ray Market Segmentation
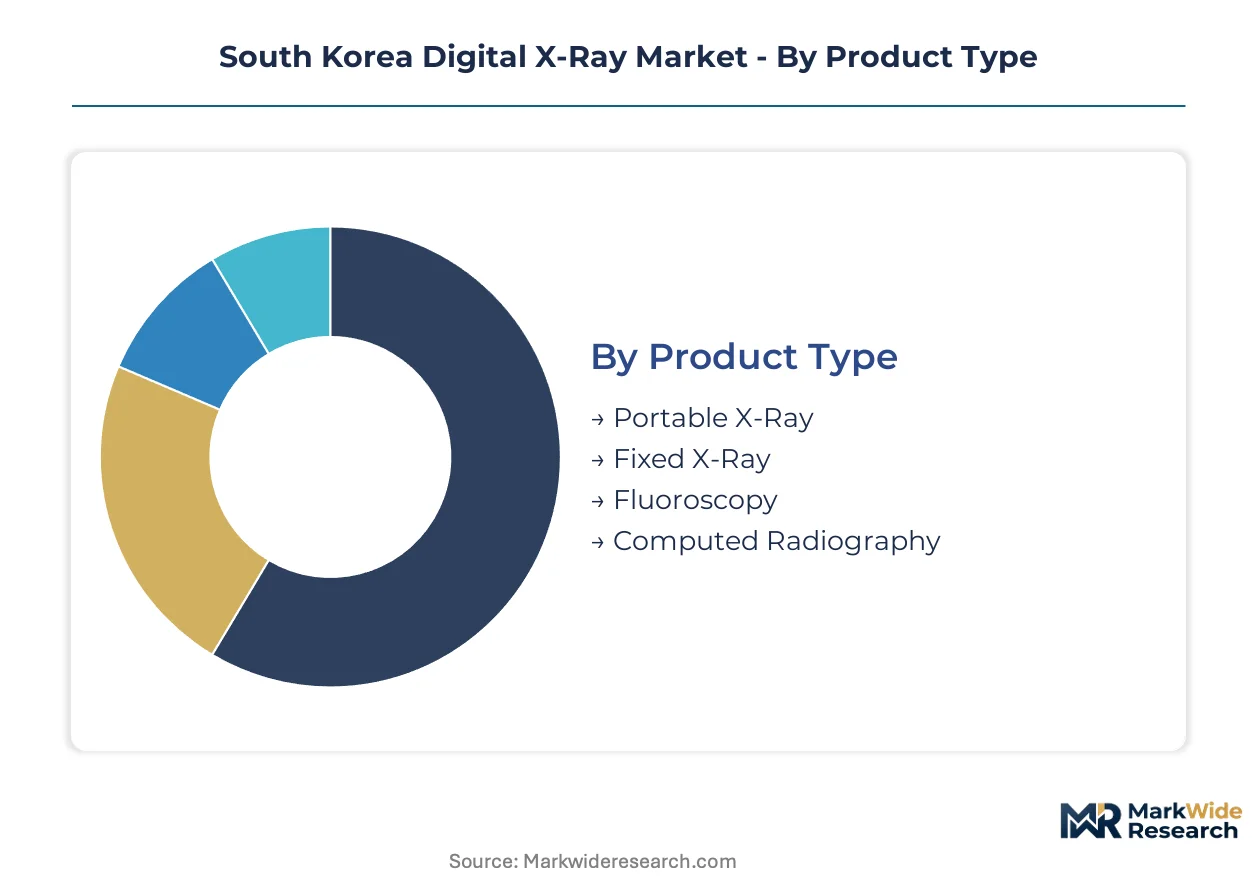
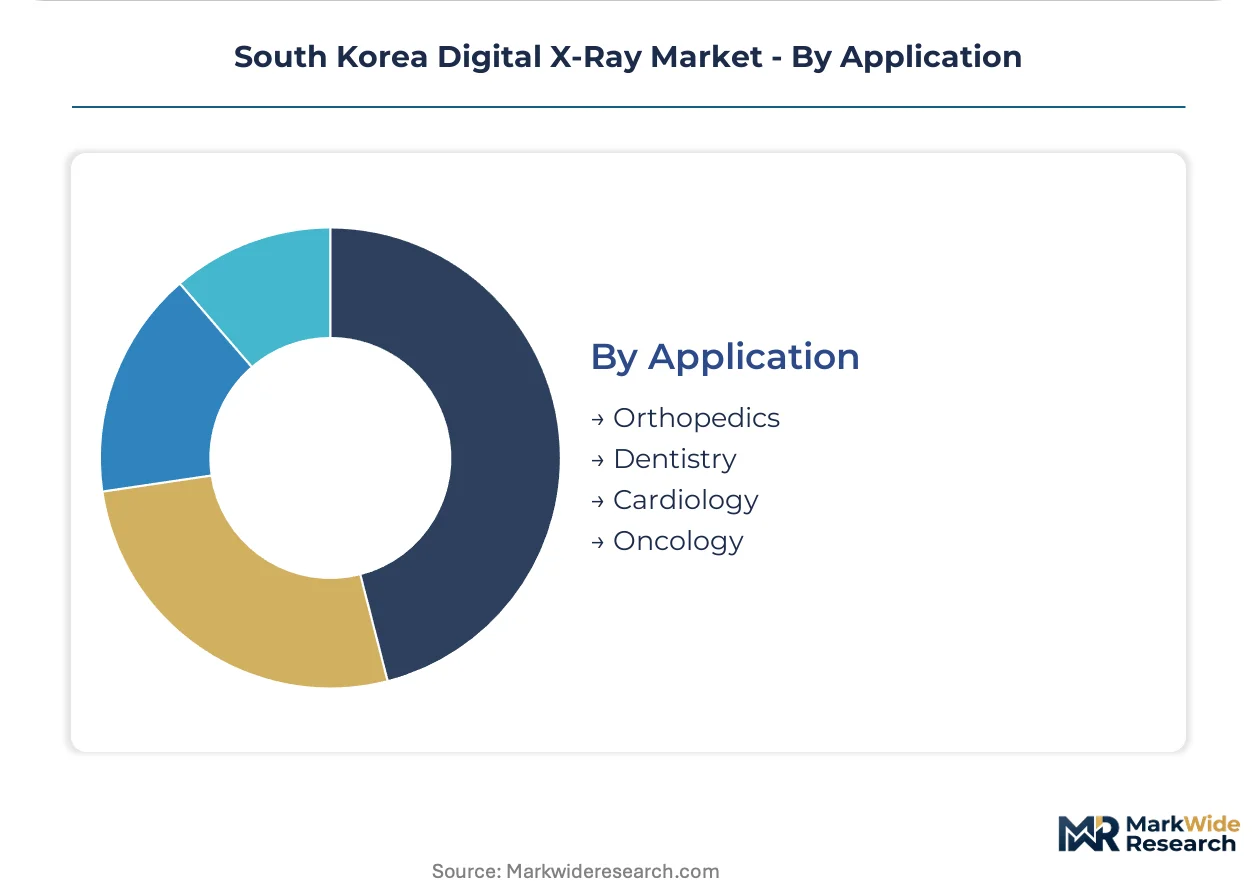
Equipment specification and procurement pathways diverge sharply across South Korean healthcare settings. MFDS certification requirements and KIS interoperability standards create distinct compliance burdens that reshape segment economics.
Product Type:
Hospital procurement committees weight mobility against throughput capacity when allocating capital budgets across installation categories.
- Portable X-Ray:Battery-powered mobile units with wireless detector pairing enable bedside imaging in Seoul's overcrowded tertiary wards. Gyeonggi-do outpatient networks prioritize these configurations for multi-site deployment flexibility.
- Fixed X-Ray:Ceiling-suspended or floor-mounted systems deliver higher tube power for bariatric patients and complex positioning. Seoul metropolitan hospitals specify these for emergency department throughput where patient volumes exceed mobile unit capacity.
- Fluoroscopy:Continuous X-ray imaging systems with image intensifier chains support interventional procedures and contrast studies.
- Computed Radiography:Cassette-based digital systems using photostimulable phosphor plates persist in budget-constrained public hospital networks.
Portable X-Ray leads volumes today; Wireless-enabled portable configurations are gaining share fastest.
End User:
Capital availability and patient throughput economics separate institutional buyers across South Korea's tiered healthcare system.
- Hospitals:Tertiary medical centers in Seoul and Busan deploy multi-room digital radiography suites with PACS integration. These institutions drive demand for premium detector resolution specifications above 3.0 line pairs per millimeter.
- Clinics:Neighborhood primary care practices favor single-detector configurations with lease financing through Korea Health Industry Development Institute instruments. Gyeonggi-do clinic consolidation is shifting procurement toward shared-service models.
- Diagnostic Centers:Specialized imaging facilities concentrate high-volume screening workflows for occupational health and preventive medicine programs.
- Research Facilities:University-affiliated hospitals and KAIST-linked medical engineering centers source pre-commercial detector technologies for clinical validation studies.
Hospitals absorb the dominant equipment expenditure; Diagnostic centers are expanding detector counts most rapidly.
Technology:
Detector architecture and connectivity protocols determine integration complexity with existing South Korean hospital information infrastructure.
- Digital Radiography:Direct-capture flat-panel detectors with amorphous silicon or selenium substrates dominate installed base economics. Seoul's metropolitan hospital network specifies these for general radiography rooms requiring sub-10-second acquisition-to-archive workflow.
- Computed Tomography:Cross-sectional imaging systems with digital radiography compatibility for scout views and localization. Oncology screening programs in Busan-Ulsan corridor are displacing projection radiography with low-dose CT protocols.
- Wireless Imaging:Battery-integrated detectors with 5 GHz DICOM transmission eliminate cable tethering. KIS C 61000-6-1 electromagnetic compliance certification is accelerating adoption across public hospital procurement tenders.
- Hybrid Imaging:Combined digital radiography and fluoroscopy platforms with shared detector substrates for interventional suites.
Digital Radiography anchors current installed value; Wireless Imaging is climbing the fastest as cable-free workflow standardization spreads.
Application:
Clinical imaging requirements dictate detector specification, with resolution and dose efficiency priorities varying by medical specialty.
- Orthopedics:Weight-bearing extremity imaging and trauma positioning demand robust detector housing and rapid image acquisition. Seoul's sports medicine centers specify direct-conversion cadmium-zinc-telluride sensors for musculoskeletal detail.
- Dentistry:Intraoral and panoramic imaging systems with specialized sensor geometries for maxillofacial applications. Private dental clinic chains in Gyeonggi-do drive volume for compact digital panoramic units.
- Cardiology:High-frame-rate fluoroscopy and digital radiography for catheterization laboratory integration.
- Oncology:Low-dose screening protocols and treatment planning imaging with PACS archive requirements.
Orthopedics generates the largest procedure volume; Dentistry is expanding detector installations most quickly among outpatient specialties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic assembly partnerships are proliferating as multinational suppliers seek MFDS certification streamlining, compressing the cost-of-compliance gap between imported and locally manufactured digital radiography systems across South Korean territory.
Seoul Capital Area
Seoul's tertiary hospital network drives premium detector specifications above 3.0 line pairs per millimeter for trauma and musculoskeletal imaging. MFDS Class II device licensing requirements concentrate regulatory expertise in the metropolitan corridor, accelerating product registration timelines for domestic manufacturers. The Gangnam-Seongnam medical cluster hosts the densest concentration of digital radiography installations serving high-volume outpatient networks.
Busan-Ulsan
South Korea's southeastern industrial corridor generates concentrated demand for mobile X-ray systems serving shipyard occupational health programs. KIS radiation safety standards for electromagnetic compatibility govern equipment deployment across heavy manufacturing facilities. The Busan metropolitan medical zone is consolidating diagnostic infrastructure to serve port logistics workers and maritime industry screening protocols.
Gyeonggi-do
Provincial health authorities are centralizing outpatient imaging services into diagnostic hubs, generating fleet-scale procurement for wireless digital radiography configurations. Korea Health Industry Development Institute financing instruments support lease-based equipment acquisition across clinic networks. The Suwon-Yongin corridor anchors the fastest-expanding detector installation base outside Seoul proper.
Daegu-Gyeongbuk
Regional medical centers are upgrading aging analog systems under national health information modernization mandates. MFDS electromagnetic compatibility testing requirements shape import timelines for multinational suppliers serving this secondary market. The Daegu medical technology district is emerging as a validation site for pre-commercial detector technologies from domestic engineering partnerships.
Daejeon-Sejong
Government research institutes and KAIST-linked medical engineering centers source experimental detector substrates for clinical validation studies. Public procurement regulations favor domestic manufacturers in national laboratory equipment tenders. The Sejong administrative city complex is piloting integrated PACS architectures for rural hospital network connectivity standardization.
South Korea Digital X-Ray Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-assisted diagnostic convergence and wireless workflow specialization. The South Korea digital X-ray market exhibits consolidated supply-side dynamics with multinational imaging conglomerates anchoring premium hospital contracts while domestic manufacturers capture mid-tier clinic volume. Three archetypes dominate competitive positioning: integrated healthcare technology conglomerates with captive semiconductor fabrication, specialized radiography equipment manufacturers with regional service networks, and emerging AI-software bundlers seeking hardware partnerships. Capacity expansion through domestic assembly facilities and strategic partnerships for flat-panel detector supply security represent the dominant competitive moves reshaping procurement relationships.
Among multinational imaging conglomerates, GE Healthcare and Siemens Healthineers AG exemplify the premium-tier archetype through service contract bundling that anchors long-term hospital relationships. Samsung Medison Co. Ltd occupies a distinctive position leveraging domestic manufacturing proximity to compress delivery timelines for public hospital tenders. Canon Medical Systems Corporation represents the mid-tier specialist archetype competing through portfolio breadth across fixed and portable system configurations.
| Leading Market Players |
|---|
| Carestream Health |
| GE Healthcare |
| Siemens Healthineers AG |
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| Samsung Medison Co. Ltd |
| Genoray Co. Ltd |
| Medonica Co. Ltd |
| DK Medical System |
| Others |
Value Network & Pricing Analysis
Public hospital procurement committees in Seoul's metropolitan network anchor pricing power through consolidated tender volumes, compressing margins for multinational suppliers while rewarding domestic manufacturers with MFDS certification streamlining. Equipment vendors respond with lease-based operational expenditure models that shift capital risk onto Korea Health Industry Development Institute financing instruments.
Pricing Analysis
Direct-to-hospital discount structures dominate premium system transactions, with distributor margins thinning to single-digit percentages for fixed-room installations. Three-tier pricing structure across premium, standard, and economy levels separates direct-conversion cadmium-zinc-telluride configurations from indirect-conversion amorphous silicon systems and legacy computed radiography cassettes. Price differentiation hinges on detector resolution specifications and KIS electromagnetic compliance certification tiers. Cost compression in mid-tier portable systems is intensifying because Gyeonggi-do clinic networks unbundle hardware from service contracts. Public hospitals exhibit lowest price sensitivity due to national reimbursement rate protection, while independent diagnostic centers face acute margin pressure.
Supply Chain Analysis
Regional distribution centers in Incheon and Busan orchestrate hub-and-spoke delivery patterns for detector hardware serving Seoul's dense hospital corridor. Amorphous silicon sensor substrates draw from concentrated East Asian foundry sources in Taiwan, South Korea, and Japan, creating single-source vulnerability for flat-panel detector assembly. Selenium deposition layers and cadmium-zinc-telluride compound semiconductor wafers rest on specialized chemical suppliers without geographic diversification. Tariff exposure on photomultiplier tubes and image intensifier chains imported from European component houses compresses procurement timelines. Distribution runs through manufacturer-authorized technical service organizations that fragment traditional bundled relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's digital X-ray market reads as a late-cycle quality story where detector resolution specifications above 3.0 line pairs per millimeter now dominate Seoul tertiary hospital procurement criteria. This specification shift rewards suppliers with captive semiconductor fabrication or deep compound semiconductor foundry partnerships.
For Market Incumbents:Cement service contract bundling as the primary defensive mechanism against Gyeonggi-do clinic network procurement unbundling. Deepen backward integration into amorphous silicon sensor substrate production to compress delivery timelines against Samsung Medison's domestic manufacturing proximity. Prioritize MFDS electromagnetic compatibility pre-certification for software-upgraded hardware variants to neutralize validation period disadvantages. Channel control through exclusive technical service organization partnerships anchors long-term relationships where equipment utilization rates justify captive technician deployment.
For New Entrants and Emerging Players:The price-point gap between premium direct-conversion systems and economy computed radiography cassettes creates viable entry territory for wireless-enabled portable configurations. Busan-Ulsan's shipyard occupational health programs represent the most penetrable whitespace, with mobile X-ray demand concentrated in underpenetrated diagnostic infrastructure. AI-assisted image interpretation bundling offers a differentiated go-to-market angle that commands premium positioning without competing on detector hardware specifications alone. KIS C 61000-6-1 electromagnetic compliance certification accelerates public hospital tender eligibility for new market entrants.
For Investors and Strategic Acquirers:Domestic medical device conglomerates with existing MFDS regulatory infrastructure are the most active acquirer in this space, seeking wireless imaging workflow capabilities and AI diagnostic software assets. The long-term viability window favors suppliers with compound semiconductor fabrication partnerships or captive detector substrate production. Acquisition target archetypes include specialized radiography equipment manufacturers with established Gyeonggi-do service networks and pre-commercial AI algorithm developers with hospital validation partnerships. The signal to monitor is MFDS enforcement intensity on electromagnetic compatibility testing, which would accelerate domestic assembly partnership formation among multinational suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Pre-Certification Investment | Compresses validation timelines for software-upgraded hardware variants against domestic competitors. |
| Wireless Detector Platform Launch | Captures Gyeonggi-do diagnostic hub procurement specifications prioritizing cable-free workflow integration. |
| AI Algorithm Hospital Partnership | Creates premium pricing tiers through automated abnormality flagging bundled with radiography workstations. |
| Compound Semiconductor Foundry Alliance | Secures direct-conversion cadmium-zinc-telluride sensor supply for musculoskeletal imaging specifications. |
| Technical Service Organization Acquisition | Restores channel control fragmented by Gyeonggi-do clinic unbundling of hardware and maintenance contracts. |
Research Methodology
Multiple input streams — hospital procurement database analysis, MFDS device registration filings, and GPO contract documentation — were reconciled against primary interviews with biomedical engineers, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from Korea Health Industry Development Institute financing instrument disclosures, customs import records for flat-panel detector substrates, and KIS standards documentation. Bottom-up equipment shipment tallies and top-down healthcare capital expenditure estimates were triangulated to anchor market sizing.
Data-stream reconciliation across product type, technology architecture, end-user institution tier, and regional procurement cluster shaped the analytical framework over the projection horizon. CAGRs were derived from equipment replacement cycle modeling and wireless imaging adoption curve analysis. Forecast inputs included MFDS certification timeline assumptions, KIS electromagnetic compliance enforcement intensity, and low-dose CT substitution rates in oncology screening applications.
The model assumes a particular technology adoption path; alternative pathways for direct-conversion cadmium-zinc-telluride sensors would alter the outlook if compound semiconductor foundry capacity constraints ease faster than projected. Forecasts reflect documented assumptions about reimbursement rate stability and public hospital leasing program expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Nuclear Magnetic Resonance Spectroscopy Market
Medical Imaging
AI-Assisted Radiology Market
Medical Imaging
Global Stroke Post Processing Software Market
Medical Imaging
Positron Emission Tomography Devices (PET) Market
Medical Imaging
Preclinical MRI Equipment Market
Medical Imaging
Asia-Pacific Digital X-Ray Devices Market
Medical Imaging
Breast Imaging Technologies Market
Medical Imaging
Fluoroscopy Devices Market
Medical Imaging
Canada Nuclear Medicine Market
Medical Imaging
Global Medical Cameras Market
Medical Imaging
Breast Imaging Market
Medical Imaging
Asia Pacific Nuclear Imaging Devices Market
Medical Imaging
Digital Mammography Market
Medical Imaging
Europe Digital X-Ray Market
Medical Imaging
Artificial Intelligence in Medical Imaging Market
Medical Imaging
Spain Nuclear Imaging Market