
 Sensor Development Kit Market | 2026-2036
Sensor Development Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Sensor Development Kit Market Analytics
The capability gap between captive fab operators and fabless design houses is reorganizing competitive tiers in sensor development kits. Texas Instruments leverages vertical integration to control silicon-to-software stack margins. Silicon Labs sustains wireless protocol leadership through dedicated RF design centers. STMicroelectronics anchors European supply security with multi-source manufacturing footprints.
A sensor development kit bundles calibrated sensing elements, signal conditioning circuitry, microcontroller interfaces, and reference firmware to accelerate prototype-to-production cycles for IoT and embedded systems. Typical kits integrate MEMS transducers with I2C or SPI digital outputs, sampling rates from 1 Hz to 4 kHz, and evaluation software supporting Arduino, Raspberry Pi, or proprietary IDE platforms. Pressure sensor kits currently occupy the largest revenue pool across product types due to automotive and aerospace qualification requirements. Wireless technology segments are expanding fastest as Bluetooth Low Energy and LoRa protocols displace wired installations in environmental monitoring and smart home deployments.
The EU AI Act and CE marking directives under the MDR framework impose algorithmic transparency and safety integrity requirements on sensor kits deployed in autonomous and healthcare applications. FDA 510(k) pathways for wearable diagnostic sensors compel developers to maintain design history files and clinical validation documentation from kit selection through commercialization. Stakeholders must monitor how regional certification divergence between EMA, FDA, and NMPA standards fragments platform compatibility and forces parallel SKU strategies.
Market Dynamics
The EU AI Act is compressing certification timelines for sensor kits deployed in autonomous systems, forcing developers to front-load algorithmic transparency documentation before hardware finalization. This regulatory pressure is restructuring how kit vendors sequence their R&D investments and partner with notified bodies.
Growth Catalysts
- Industrial Predictive Maintenance:German automotive and machinery buyers are expanding kit procurement for vibration and temperature monitoring arrays. Munich and Stuttgart industrial corridors concentrate this demand acceleration.
- EU AI Act Compliance Mandate:The regulation's safety integrity requirements for autonomous sensor applications are creating mandatory upgrade cycles. CE marking under MDR framework compounds certification urgency for healthcare-adjacent kits.
- Bluetooth Low Energy Protocol Maturation:Environmental monitoring and smart home installers are specifying wireless kits over wired alternatives. LoRaWAN stack integration is following similar displacement patterns in agricultural sensing deployments.
Market Restraints
- MEMS Foundry Concentration:Taiwan and South Korea captive fabs control advanced MEMS wafer supply. Fabless design houses face allocation priority gaps during capacity crunches.
- RF Front-End Component Volatility:Gallium arsenide and silicon germanium substrate costs fluctuate with 5G infrastructure build-out competition. Wireless kit margins compress during these input spikes.
- Legacy Protocol Entrenchment:Industrial automation buyers maintain Modbus and Profibus wired installations. Retrofit economics delay wireless kit penetration in brownfield facilities.
Strategic Opportunities
- India PLI Scheme for Electronics:The production-linked incentive framework subsidizes local sensor kit assembly. Noida and Bengaluru emerging as design-to-manufacture hubs for export-oriented vendors.
- Digital Twin Convergence:Sensor kits paired with real-time simulation platforms are opening architecture-engineering-construction contracts. Physics-based sensor models reduce field calibration requirements.
- CE-MDR Accelerated Pathways:The EU's streamlined certification for Class IIa diagnostic sensors rewards early design history file preparation. Wearable health kit developers capture first-mover advantage in notified body queue positioning.
Industry Challenges
- Multi-Domain Firmware Expertise Scarcity:Developers combining signal conditioning, wireless stacks, and edge ML inference face recruitment bottlenecks. Compensation premiums in Munich and San Francisco distort talent distribution.
- FDA 510(k) Documentation Burden:Wearable diagnostic sensor kits require clinical validation traceability from evaluation board selection through commercialization. Design history file maintenance consumes engineering resources disproportionately.
- Regional Certification Divergence:Parallel SKU strategies for EMA, FDA, and NMPA compliance fragment platform economics. Firmware branching for divergent safety integrity levels multiplies validation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sensor Development Kit Market |
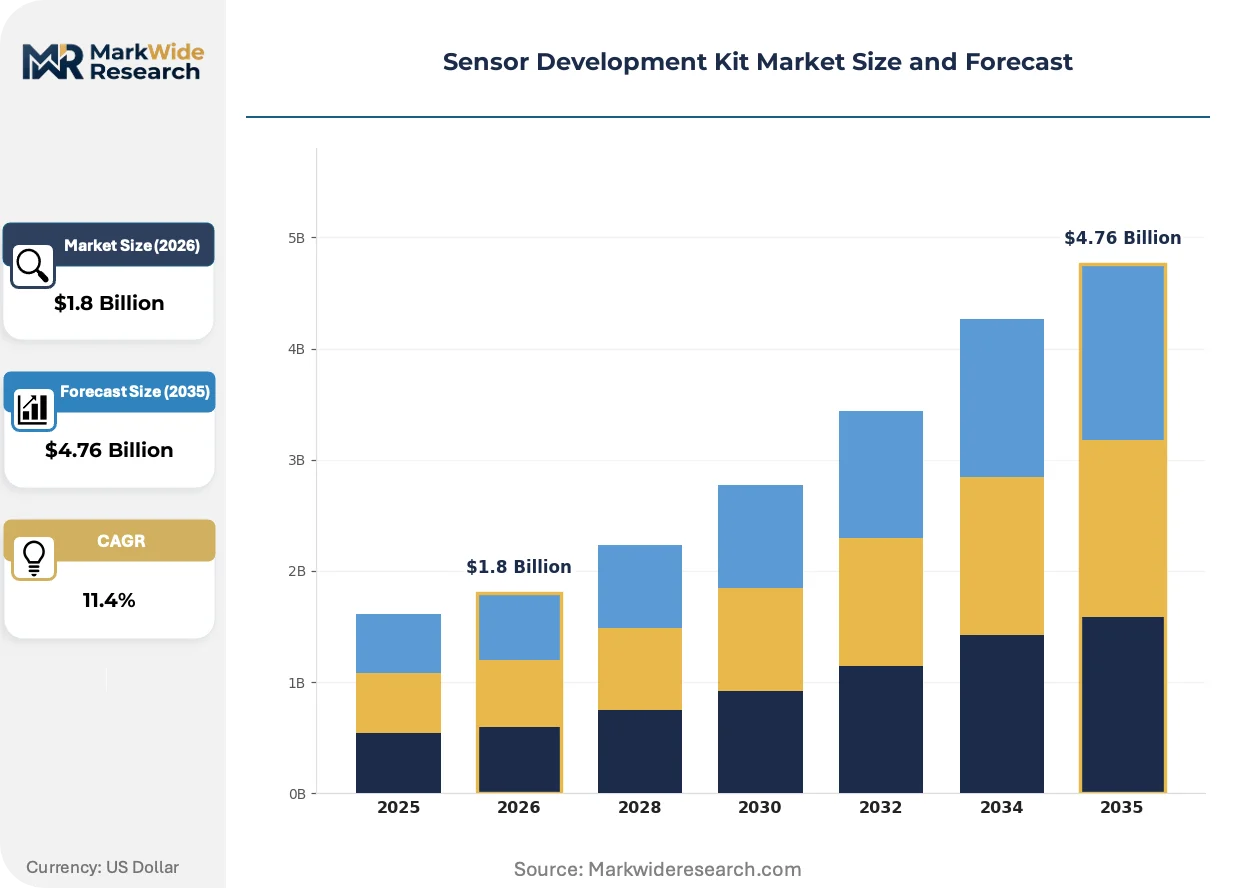
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Humidity Sensors, Temperature Sensors, Pressure Sensors, Proximity Sensors Technology: Analog, Digital, Wireless, Wired End User: Consumer Electronics, Industrial Automation, Automotive, Healthcare Application: Smart Home, Wearable Devices, Environmental Monitoring, Robotics |
| Companies Covered | ON Semiconductor, NXP Semiconductors, Silicon Labs, Dialog Semiconductor, PCTEL, Infineon Technologies, STMicroelectronics, Texas Instruments, Microchip Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sensor Development Kit Market Evolving Landscape
Sensor kit architectures are fragmenting into modular, software-defined layers that decouple hardware refresh cycles from protocol and algorithm updates. This decomposition is compressing vendor margin structures while accelerating end-user upgrade flexibility.
Edge ML inference engines are decomposing the traditional microcontroller-plus-sensor pairing into discrete neural processing units with dedicated sensor interfaces. Automotive Tier 1 suppliers are specifying these partitioned architectures for cabin monitoring and predictive maintenance applications. The separation of compute from sensing is enabling sensor head suppliers to compete independently of silicon platform vendors.
The EU AI Act's algorithmic transparency requirements are mandating documented decision pathways for sensor-triggered autonomous actions. Industrial automation buyers in Germany must now maintain model cards alongside hardware calibration certificates. Kit vendors are responding by embedding audit logging firmware that captures inference provenance without exposing proprietary weights.
Subscription-based firmware update models are displacing perpetual license structures among mid-scale IoT deployers. Dutch smart building integrators and Danish agricultural sensor networks are piloting annual telemetry platform fees that bundle security patches and protocol extensions. This recurring revenue shift is visible most prominently in North European markets with mature managed services infrastructure.
Sensor Development Kit Market Segmentation
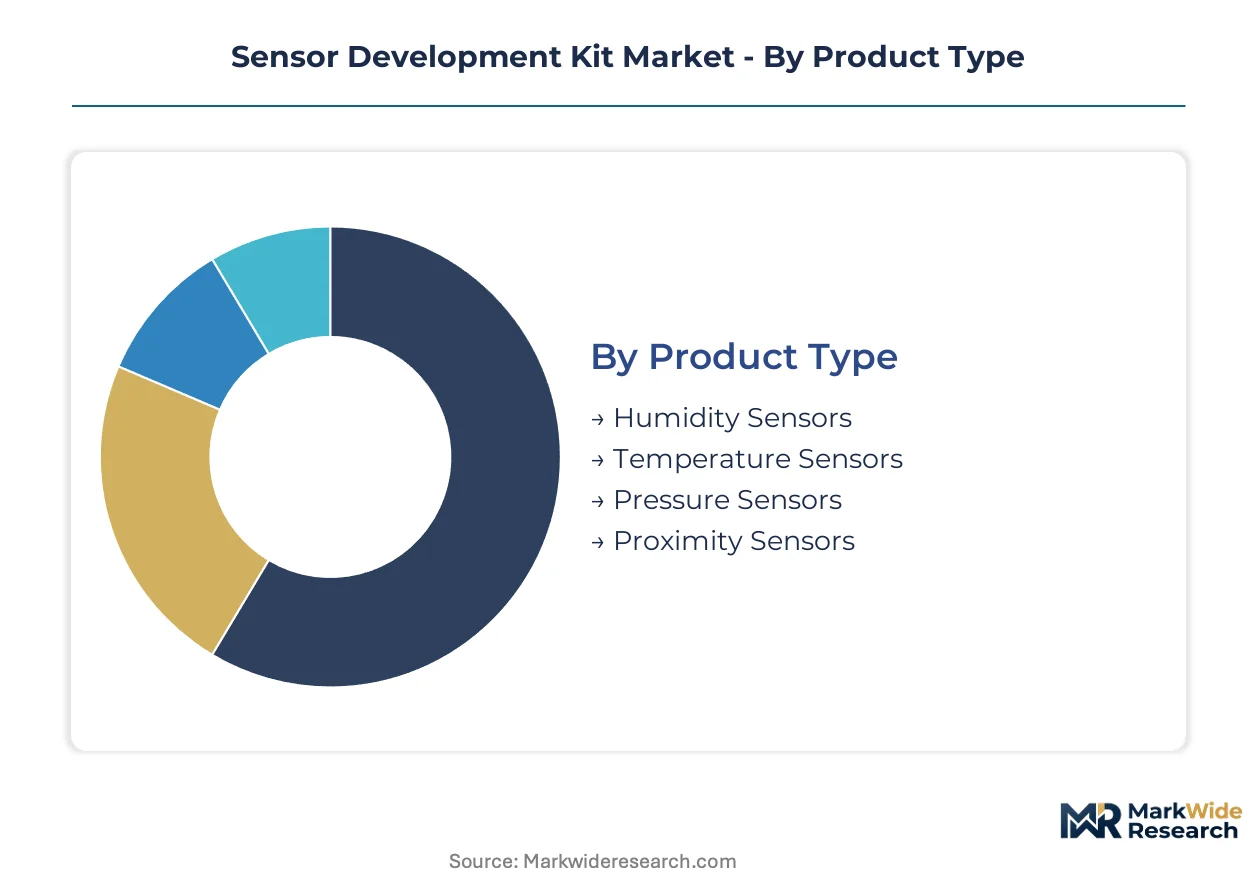
Segmentation in the sensor development kit market reveals how procurement patterns diverge across technical specifications and deployment contexts. Kit vendors must align hardware configurations with distinct certification requirements and integration complexity thresholds that vary by buyer segment.
Product Type:
Domestic demand in Germany's industrial corridor concentrates on pressure and temperature variants, while export-led growth flows through humidity and proximity sensors bound for Asian consumer electronics manufacturing.
- Pressure Sensors:MEMS-based transducers with automotive-grade calibration dominate kit configurations for aerospace qualification workflows. German automotive buyers in Stuttgart specify these for brake system and tire pressure monitoring prototypes, where ASIL-D safety integrity documentation accelerates procurement decisions.
- Temperature Sensors:Thermocouple and RTD interface boards with cold junction compensation span -40°C to 125°C industrial ranges. Munich machinery builders deploy these in predictive maintenance arrays, though foundry allocation bottlenecks for precision resistive elements constrain kit availability during capacity crunches.
- Humidity Sensors:Capacitive polymer sensing elements with I2C digital output target smart home and agricultural monitoring exports.
- Proximity Sensors:Inductive and capacitive detection modules serve robotics end-effector prototyping with sub-millimeter repeatability specifications.
Pressure sensors command the established base. The steepest expansion runs through humidity sensors.
Technology:
Cost tier separation distinguishes premium wireless stacks from economy analog configurations, with digital intermediate solutions capturing mid-scale industrial automation budgets.
- Wireless:Bluetooth Low Energy and LoRaWAN protocol stacks with integrated RF front-ends eliminate wiring harness costs in retrofit deployments. Dutch smart building integrators specify these for tenant submetering installations, though gallium arsenide substrate volatility compresses margins during 5G infrastructure competition spikes.
- Digital:SPI and I2C interface standards with embedded ADCs reduce microcontroller pin requirements. Healthcare wearable developers in Denmark favor these for FDA 510(k) pathway efficiency, as digital signal chains simplify clinical validation documentation.
- Analog:Voltage-output transducers with external conditioning requirements persist in legacy industrial automation brownfield sites.
- Wired:RS-485 and CAN bus physical layers maintain dominance in automotive EMC-critical applications.
Wireless protocols gain share fastest in new installations. Digital interfaces defend the replacement cycle base.
End User:
Application maturity separates volume-driven consumer electronics procurement from margin-rich healthcare qualification workflows.
- Industrial Automation:Vibration, temperature, and pressure kit arrays with Modbus TCP gateways anchor German machinery sector demand. Stuttgart OEMs require CE-MDR documentation bundles for safety-related control systems, compressing vendor sales cycle efficiency.
- Healthcare:Wearable diagnostic kits with FDA 510(k) and EMA parallel track compatibility command premium positioning. Design history file preparation from evaluation board selection through commercialization consumes disproportionate engineering resources.
- Automotive:ASIL-rated sensing elements with ISO 26262 traceability target cabin monitoring and battery management systems.
- Consumer Electronics:High-volume, low-margin kit configurations for smartphone and tablet integration face procurement consolidation.
Industrial automation commands the established base. Healthcare applications deliver the steepest margin expansion trajectory.
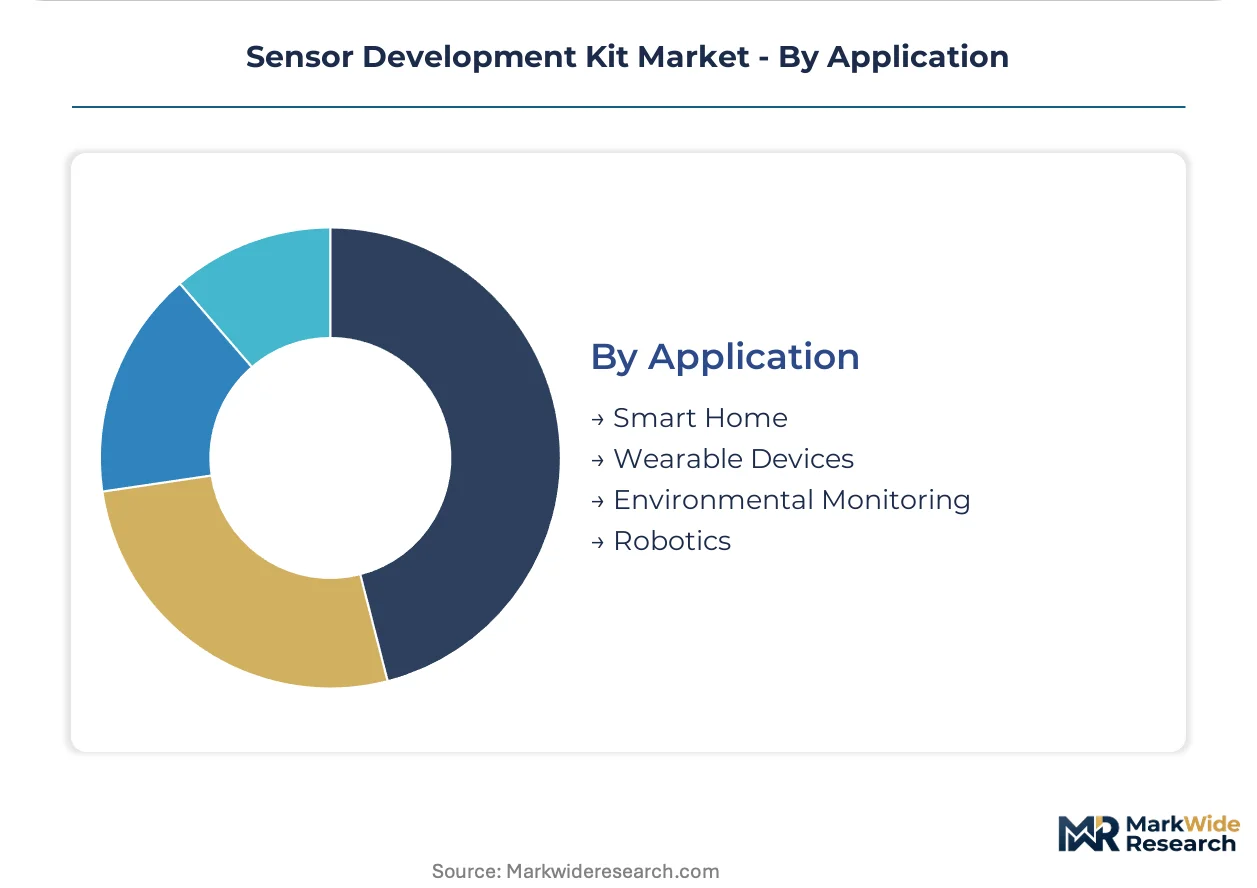
Application:
Customer type differentiation separates enterprise-scale robotics deployments from residential smart home installer procurement patterns.
- Environmental Monitoring:LoRaWAN-enabled multi-sensor nodes with solar harvesting target agricultural and air quality networks. Danish deployments pair these with subscription firmware models that bundle security patches and protocol extensions.
- Robotics:Force-torque and proximity sensing heads with ROS2 driver compatibility serve collaborative arm prototyping. Edge ML inference partitioning enables sensor head suppliers to compete independently of silicon platform vendors.
- Smart Home:Bluetooth mesh commissioning tools and battery-optimized humidity sensors address installer productivity requirements.
- Wearable Devices:Miniaturized biometric sensor modules with clinical-grade signal conditioning target diagnostic watch form factors.
Environmental monitoring commands the established base. Robotics applications show the steepest expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany's industrial corridor show the lowest price elasticity, absorbing premium kit costs for predictive maintenance arrays. Indian smart building integrators exhibit the highest elasticity, driving volume procurement of economy-tier wireless configurations.
Germany
Automotive and machinery builders in Stuttgart and Munich drive pressure and temperature kit procurement for brake system prototyping and vibration monitoring arrays. The EU AI Act compels algorithmic transparency documentation for autonomous sensor deployments, compressing vendor certification timelines. The Baden-Württemberg industrial cluster concentrates ASIL-D safety integrity qualification workflows.
United States
Healthcare wearable developers and automotive Tier 1 suppliers anchor demand for FDA 510(k) pathway kits and cabin monitoring prototypes. FDA design history file requirements consume disproportionate engineering resources from evaluation board selection through commercialization. Greater Boston and Silicon Valley house edge ML inference specialists partitioning neural processing from sensing elements.
China
Consumer electronics manufacturers and agricultural sensor network deployers propel humidity and LoRaWAN kit volumes. NMPA standards for wearable diagnostic devices fragment platform compatibility with EMA and FDA requirements, forcing parallel SKU strategies. The Yangtze River Delta dominates high-volume kit assembly for smartphone integration.
India
Smart building integrators and agricultural monitoring networks specify Bluetooth Low Energy and economy-tier wireless kits. The PLI scheme for electronics subsidizes local sensor kit assembly in Noida and Bengaluru design-to-manufacture hubs. Bengaluru's emerging ecosystem captures export-oriented vendor expansion.
Netherlands
Smart building integrators and tenant submetering installers drive Bluetooth mesh commissioning tool procurement. CE marking under the MDR framework compounds certification urgency for healthcare-adjacent kit deployments. Dutch agricultural sensor networks pilot subscription firmware models bundling security patches and protocol extensions.
Sensor Development Kit Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated semiconductor houses commanding silicon-to-software stack margins while fabless design houses compete on wireless protocol specialization. The market structures around three tiers: captive fab operators with in-house MEMS production, RF-centric wireless specialists, and modular platform vendors. Dominant competitive moves include backward integration into MEMS foundry capacity and strategic partnerships with notified bodies for EU AI Act pre-certification.
Among captive fab operators, Texas Instruments and STMicroelectronics exemplify the integrated archetype controlling upstream silicon supply. Silicon Labs occupies a position within the wireless protocol specialization tier. These three anchors demonstrate how competitive positioning separates silicon platform control from RF design center excellence.
| Leading Market Players |
|---|
| ON Semiconductor |
| NXP Semiconductors |
| Silicon Labs |
| Dialog Semiconductor |
| PCTEL |
| Infineon Technologies |
| STMicroelectronics |
| Texas Instruments |
| Microchip Technology |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with Taiwan and South Korea MEMS foundries lock in wafer allocation and stabilize unit economics for fabless kit vendors facing gallium arsenide substrate volatility. German automotive buyers in Stuttgart absorb premium pricing for ASIL-D certified pressure sensor kits, while Indian smart building integrators drive volume procurement of economy-tier Bluetooth Low Energy configurations.
Pricing Analysis
Subscription firmware and telemetry platform fees now drive lifetime value beyond hardware margins, with Dutch smart building integrators and Danish agricultural networks piloting annual service bundles. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k) pathway kits with design history file support from basic evaluation boards. Cost compression in wireless configurations is intensifying because gallium arsenide and silicon germanium substrate costs spike during 5G infrastructure build-out competition. Healthcare wearable developers show the lowest price sensitivity, absorbing documentation burden premiums, while Indian export-oriented assemblers exhibit the highest elasticity.
Supply Chain Analysis
Inventory cycles for precision resistive elements and RF front-end components stretch lead times during Taiwan and South Korea captive fab allocation crunches. MEMS wafer supply draws from Taiwan, South Korea, and domestic European sources for automotive-grade calibration workflows. Gallium arsenide substrate volatility and single-source vulnerability for advanced MEMS processes threaten kit availability. Distribution runs through authorized distributor networks serving Noida and Bengaluru design-to-manufacture hubs, with direct OEM relationships dominating German industrial corridor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sensor development kit market is recovering from MEMS foundry capacity constraints that compressed margins through the analysis window. Industrial automation capital expenditure cycles in Germany's automotive corridor provide cyclical uplift.
For Market Incumbents: Fortify MEMS foundry partnerships through multi-year offtake agreements with Taiwan and South Korea captive operators. Backward integration into RF design centers protects wireless protocol margins against gallium arsenide cost spikes. Texas Instruments and STMicroelectronics demonstrate how silicon-to-software stack control defends positioning against fabless competitors.
For New Entrants and Emerging Players: CE-MDR accelerated pathways for Class IIa diagnostic sensors offer fast-track positioning ahead of EU AI Act full implementation. White-space concentrates in Indian PLI-subsidized assembly for export-oriented Bluetooth Low Energy kits and ROS2-compatible robotics sensing heads. Target Bengaluru design-to-manufacture ecosystems with firmware subscription models bundling security patches.
For Investors and Strategic Acquirers: Wireless protocol specialists with dedicated RF design centers represent attractive acquisition targets as edge ML inference partitioning reshapes competitive tiers. Long-term viability hinges on algorithmic transparency firmware capabilities mandated by EU AI Act safety integrity requirements. Watch notified body queue positioning for CE-MDR and FDA 510(k) parallel track readiness as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification Partnership | Notified body alignment compresses vendor certification timelines for autonomous sensor deployments. |
| Backward Integration into MEMS Foundry Capacity | Taiwan and South Korea wafer supply security anchors kit availability during allocation crunches. |
| Subscription Firmware Platform Launch | Dutch and Danish integrators pilot annual telemetry fees bundling security patches and protocol extensions. |
| ROS2 Driver Compatibility Investment | Collaborative robotics prototyping demand enables sensor head suppliers to compete independently of silicon vendors. |
| India PLI Scheme Assembly Expansion | Noida and Bengaluru hubs capture export-oriented volume with government-subsidized manufacturing. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with MEMS design engineers, industrial automation procurement managers, regulatory affairs specialists at notified bodies, and smart building systems integrators. Secondary validation drew from FDA 510(k) filings, EMA medical device registration databases, EU AI Act implementation guidance, and customs trade data for sensor kit imports. Bottom-up kit shipment estimates triangulated against top-down semiconductor industry capacity reports.
Across the analysis window, forecasts modeled product type segmentation by pressure, temperature, humidity, and proximity variants; technology segmentation across wireless, digital, analog, and wired interfaces; and end-user segmentation spanning industrial automation, healthcare, automotive, and consumer electronics. CAGRs were derived from regression analysis against industrial capital expenditure indices and regulatory implementation timelines. Edge ML inference adoption curves and wireless protocol displacement rates informed technology segment trajectories.
Underlying assumptions cover sustained MEMS foundry capacity expansion, stable gallium arsenide substrate supply, and EU AI Act enforcement consistency, with deviation risk concentrated in Taiwan geopolitical exposure and FDA 510(k) pathway backlog fluctuations. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Acceleration and Yaw Rate Sensors Market
Sensors and Controls
Distributed Temperature Sensing Market
Sensors and Controls
Hydrogen Monitor Market
Sensors and Controls
Magnetometer Market
Sensors and Controls
Millimeter Wave Sensors and Modules Market
Sensors and Controls
South Korea Sensors Market
Sensors and Controls
Control Network Modules Market
Sensors and Controls
Global Ultrasonic Gas Leak Detector Market
Sensors and Controls
Global Pyrometer Market
Sensors and Controls
North America Occupancy Sensors Market
Sensors and Controls
Germany Digital Thermometer Market
Sensors and Controls
Wired Occupancy Sensors Market
Sensors and Controls
Gesture Control Market
Sensors and Controls
Marine Sensors Market
Sensors and Controls
Embedded Biometric Sensor Market
Sensors and Controls
Room Pressure Monitor Market