
 Solid Flow Rate Valve Control Market | 2026-2036
Solid Flow Rate Valve Control Market Size, Share, and Industry Trends Forecast 2026-2036
Solid Flow Rate Valve Control Market Outlook
Modular valve-actuator bundling is shifting procurement patterns across process industries. Emerson Electric Co. leverages integrated digital positioners to anchor premium positioning in automated control architectures. Schenck Process India Private Ltd competes through specialized heavy-duty rotary valves for abrasive solids handling. Parker Hannifin Corporation extends its pneumatic technology leadership into compact manifold assemblies for space-constrained installations.
Solid flow rate valve control encompasses mechanical and electromechanical devices engineered to meter, divert, or isolate granular and powdered materials with precision tolerances typically ranging from ±1% to ±5% of setpoint flow. These systems employ rotary airlock seals, slide gate mechanisms, or dome valve configurations to maintain pressure differentials while preventing fugitive dust emissions in pneumatic conveying lines. Automated valves command the dominant margin pool as end users prioritize remote diagnostics and predictive maintenance integration. Pneumatic actuation technology leads installed base volumes due to intrinsic safety in explosive atmospheres, though electric actuators gain share in food-grade stainless steel applications demanding washdown compatibility. Batch processing applications sustain higher replacement frequencies than continuous flow systems owing to cyclic mechanical stress on sealing surfaces.
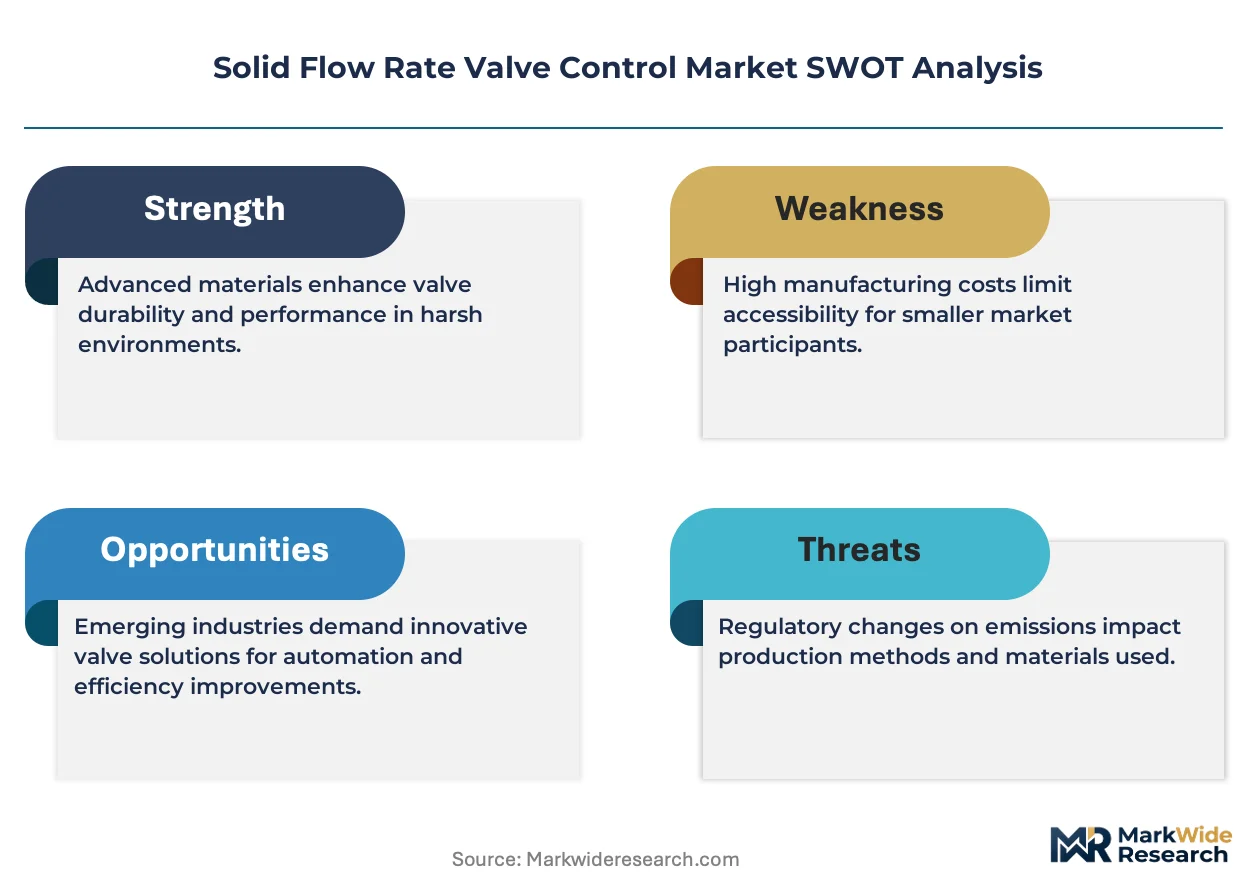
EPA New Source Performance Standards and REACH chemical facility directives compel valve manufacturers to certify zero-leakage packing designs and fugitive emissions testing protocols. OSHA combustible dust regulations and ATEX equipment directives further constrain material selection and surface temperature ratings for solids-handling components in hazardous zones. Stakeholders must weigh total cost of ownership against capital expenditure trade-offs as digital valve positioners redefine maintenance economics across process plant footprints.
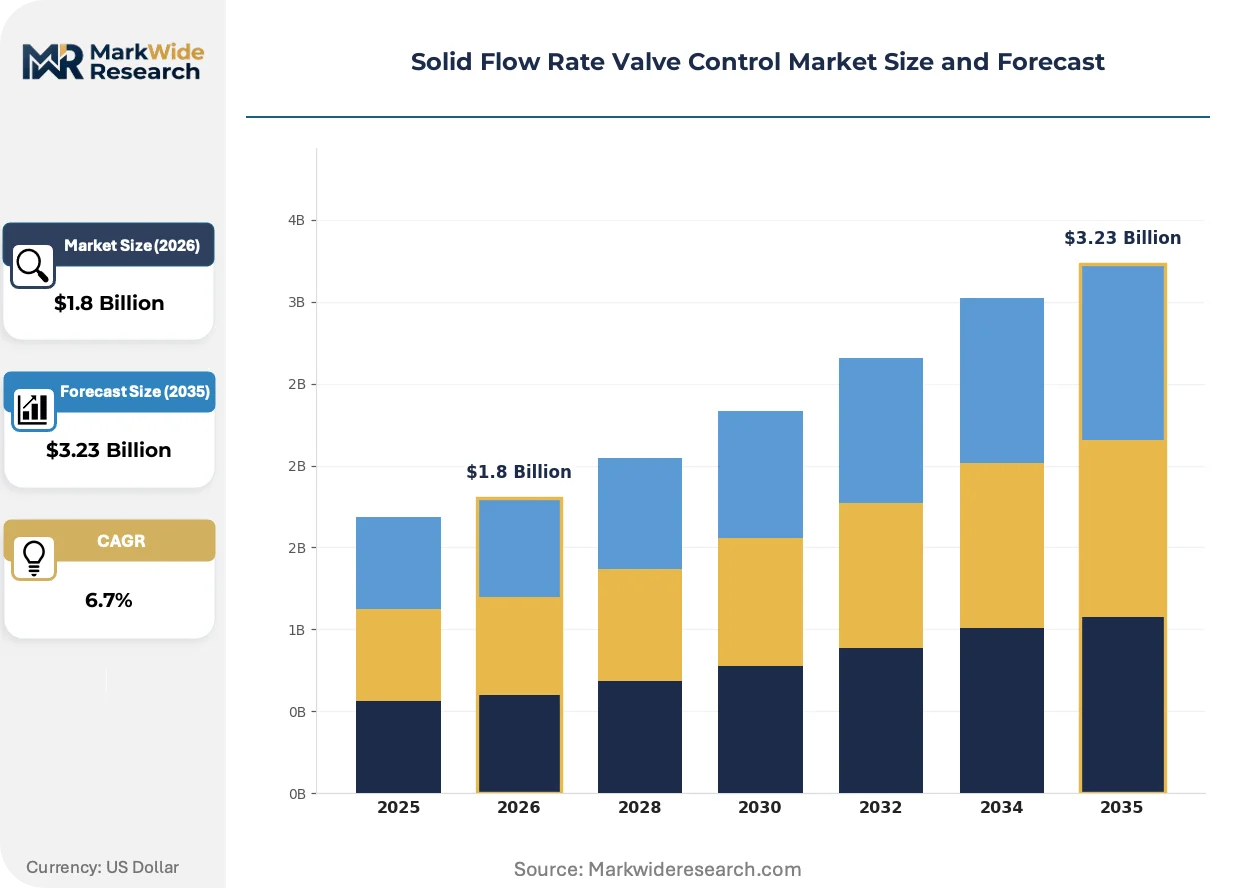
Market Dynamics
Modular valve-actuator bundling is consolidating procurement decisions around integrated digital architectures, forcing component suppliers to reposition as subsystem partners or face margin compression in standalone hardware sales.
Growth Catalysts
- EPA New Source Performance Standards:Chemical processing facilities in the United States are retrofitting pneumatic conveying lines with certified zero-leakage packing designs to meet fugitive emissions mandates, accelerating replacement cycles for legacy rotary airlock seals.
- Continuous flow shale gas operations:North American hydraulic fracturing sites demand pneumatic actuation systems for proppant and sand handling, sustaining installed base expansion in abrasive solids applications.
- REACH chemical facility directives:German process plants are automating valve installations to satisfy ECHA certification requirements for dust containment, pulling demand toward predictive maintenance-enabled positioners.
Market Restraints
- Stainless steel input volatility:Food-grade electric actuator housings require 316L stainless steel, exposing manufacturers to nickel price swings that compress fabrication margins without corresponding pricing power.
- Specialized seal supplier concentration:Perfluoroelastomer rotary shaft seals for high-temperature abrasive service concentrate among three European compounders, creating single-source vulnerability for heavy-duty valve OEMs.
- Intrinsic pneumatic energy inefficiency:Compressed air systems leak at rates exceeding thirty percent in aging plant infrastructure, inviting substitution pressure from direct-drive electric actuators in non-hazardous zones.
Strategic Opportunities
- Indian pharmaceutical solids handling:CDSCO-mandated containment upgrades for potent compound manufacturing are creating first-mover advantage for valve suppliers offering isolator-integrated dome valve configurations.
- Digital twin convergence:Valve positioners embedding edge computing capability are integrating with distributed control systems to enable real-time wear modeling, opening annuity revenue streams through predictive analytics subscriptions.
- EU Green Deal capital incentives:Process industry decarbonization grants in the Netherlands and Denmark are funding pneumatic-to-electric actuator conversions in food processing, accelerating technology transition timelines.
Industry Challenges
- ATEX certification timeline compression:Equipment directives for explosive atmosphere compliance now require extended surface temperature testing protocols, stretching product launch schedules by six to nine months for modified seal geometries.
- Legacy DCS integration friction:Brownfield chemical plants running proprietary communication buses demand costly protocol gateway development to connect smart positioners, delaying digital upgrade adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid Flow Rate Valve Control Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Valves, Manual Valves, Pressure Relief Valves, Control Valves Technology: Pneumatic, Hydraulic, Electric, Mechanical End User: Oil & Gas, Water Treatment, Chemical Processing, Food & Beverage Application: Batch Processing, Continuous Flow, Pressure Management, Level Control |
| Companies Covered | Polimak Grup Endüstriyel Üretim San. A.Ş., Parker Hannifin Corporation, Schenck Process India Private Ltd, Salina Vortex Corporation, Coperion GmbH, WAMGROUP S.p.A, Flowserve Corporation, Emerson Electric Co., IMI plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid Flow Rate Valve Control Market Strategic Shifts
Intelligent edge devices are embedding diagnostic capability directly into valve actuation hardware, compressing the traditional separation between mechanical components and plant-level control systems.
Smart positioners with embedded vibration sensors are integrating machine learning algorithms to predict seal degradation in rotary airlock applications. Food processors in Denmark and the Netherlands are deploying these units ahead of scheduled washdown cycles. The technology is integrating predictive maintenance workflows into capital equipment procurement decisions, shifting buyer evaluation criteria from first cost to total lifecycle value.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are compelling seal compounders to reformulate rotary shaft packing materials. German chemical processors face mandatory retooling of high-temperature conveying lines by 2026. Abrasive solids applications are responding fastest, with Schenck Process and specialized competitors accelerating bio-based elastomer qualification programs.
Buyer consolidation among multinational chemical processors is compressing vendor qualification lists and unbundling after-sales service contracts from hardware supply agreements. Procurement teams at BASF and Dow facilities are negotiating direct spare parts agreements with seal manufacturers, bypassing traditional valve OEM distribution. This pattern is most visible in German and US Gulf Coast petrochemical clusters, where maintenance centralization is eliminating regional distributor intermediaries.
Solid Flow Rate Valve Control Market Segmentation
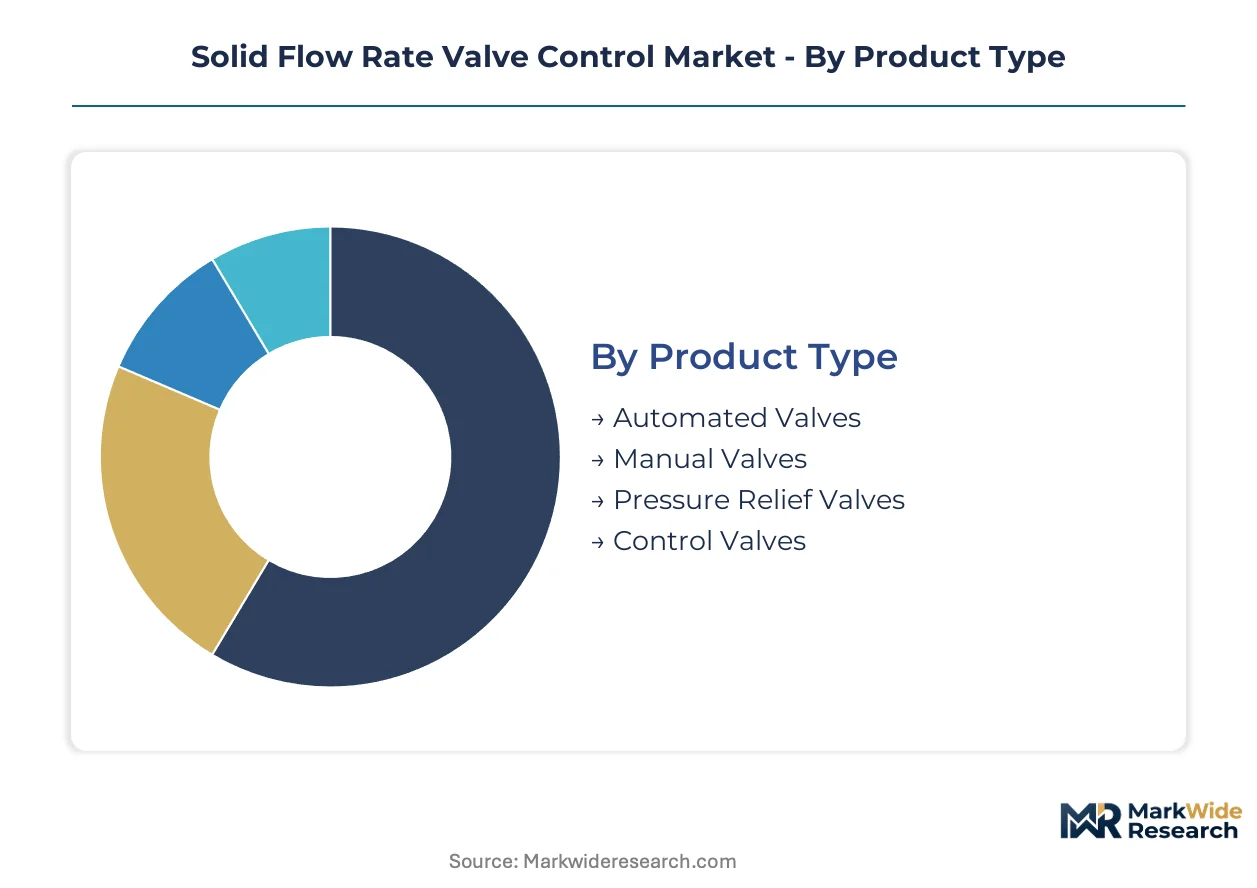
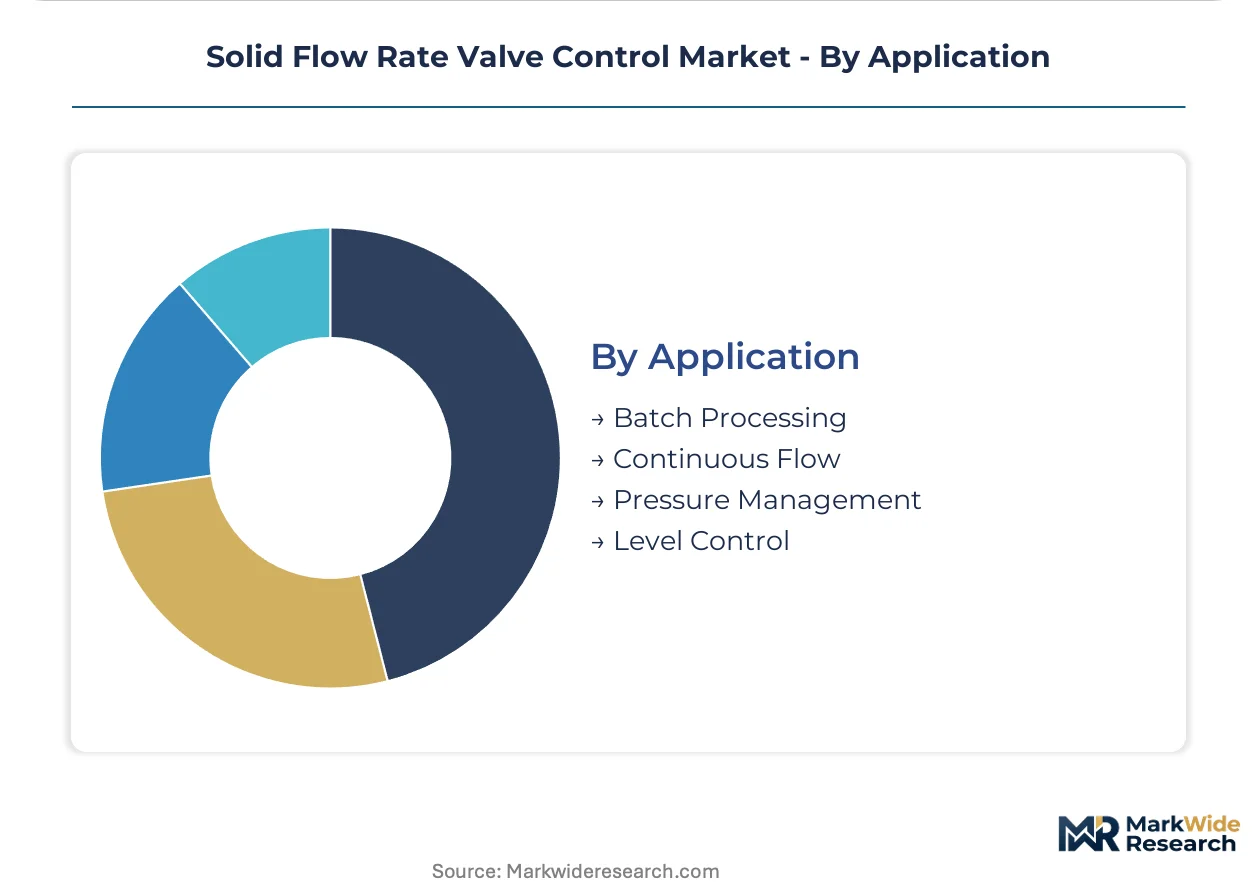
Segmentation in solid flow rate valve control reveals how procurement priorities diverge between standalone replacement hardware and integrated subsystem architectures. Buyers evaluate segments through the lens of total lifecycle cost rather than capital expenditure alone.
Product Type:
Standalone valve hardware dominates maintenance budgets, while bundled actuator-positioner systems anchor new installation specifications across process industries.
- Automated Valves:These systems integrate digital positioners with remote diagnostic capability for predictive maintenance workflows. Demand concentrates in German chemical processing facilities retrofitting for ECHA emissions certification, with pneumatic actuation variants commanding premium positioning in hazardous zone applications.
- Control Valves:Precision metering devices engineered for ±1% to ±5% flow tolerance in continuous solids handling. North American shale gas proppant operations sustain installed base expansion, though electric actuator conversions accelerate in EU food processing decarbonization grants.
- Manual Valves:Mechanical isolation devices for low-cycle service in non-critical process legs.
- Pressure Relief Valves:Safety-critical overpressure protection for pneumatic conveying line integrity.
Volume placements concentrate in Automated Valves; the faster expansion belongs to Control Valves.
Technology:
Actuation technology selection tracks hazardous zone classification, with intrinsic safety requirements preserving pneumatic dominance in explosive atmospheres.
- Pneumatic:Compressed air-driven actuation systems with proven safety in ATEX Zone 20/21 dust environments. Continuous flow shale gas operations in the United States sustain demand, though infrastructure leakage rates exceeding thirty percent invite substitution pressure from electric alternatives in non-hazardous zones.
- Electric:Direct-drive servo motor actuation with embedded edge computing for predictive analytics. Food-grade stainless steel variants gain share in Danish and Dutch washdown-compatible installations funded by EU Green Deal capital incentives.
- Hydraulic:High-force actuation for heavy-duty abrasive solids handling in mining and minerals processing.
- Mechanical:Simple lever or gear-operated systems for manual intervention in isolated process legs.
Pneumatic systems retain the largest installed base; electric technology is climbing the fastest as food processors prioritize washdown compatibility.
End User:
End-use verticals impose distinct certification burdens, with chemical and pharmaceutical applications demanding the most stringent emissions containment validation.
- Chemical Processing:Facilities handling abrasive and corrosive solids requiring zero-leakage packing designs. German and US Gulf Coast petrochemical clusters drive specification intensity as EPA New Source Performance Standards and REACH directives accelerate replacement cycles for legacy rotary airlock seals.
- Food & Beverage:Hygienic stainless steel installations with washdown-compatible electric actuators. Netherlands and Denmark process industry decarbonization grants are funding pneumatic-to-electric conversions, compressing technology transition timelines.
- Oil & Gas:Hydrocarbon solids handling and proppant logistics in hydraulic fracturing operations.
- Water Treatment:Lime and polymer dosing in municipal and industrial wastewater facilities.
Procurement volume concentrates in Chemical Processing; Food & Beverage is gaining share fastest on decarbonization incentive alignment.
Application:
Operating mode determines mechanical stress profiles and replacement frequency, with cyclic batch duty accelerating seal degradation versus continuous service.
- Continuous Flow:Uninterrupted solids conveying with steady-state mechanical loading. Pneumatic actuation systems anchor demand in North American shale gas proppant handling, where abrasive silica sand exposure tests seal compound durability.
- Batch Processing:Cyclic start-stop operation with repetitive sealing surface stress. Pharmaceutical solids handling in India faces CDSCO-mandated containment upgrades, creating specification pull for isolator-integrated dome valve configurations in potent compound manufacturing.
- Pressure Management:Differential pressure maintenance across rotary airlock and dome valve seals.
- Level Control:Silo and hopper discharge modulation for inventory management.
Continuous Flow holds the dominant installed base; Batch Processing shows the steepest specification intensity as containment mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of solid flow rate valve control systems concentrates in Germany and the United States, while consumption spreads across chemical processing clusters in Europe, North America, and Asia-Pacific. Regulatory divergence between EPA mandates and REACH directives shapes distinct specification requirements by geography.
United States
Shale gas proppant handling sustains pneumatic actuation demand across Texas and Pennsylvania hydraulic fracturing sites. EPA New Source Performance Standards compel zero-leakage packing retrofits in Gulf Coast petrochemical corridors. Houston-area chemical processors are automating legacy rotary airlock installations to meet fugitive emissions certification timelines.
Germany
Chemical processing facilities in Ludwigshafen and Leverkusen drive specification intensity for predictive maintenance-enabled positioners. REACH Annex XVII restrictions on fluorinated compounds force seal compound reformulation by 2026. Bavarian industrial valve manufacturers are accelerating bio-based elastomer qualification programs for high-temperature abrasive service.
India
Pharmaceutical solids handling in Hyderabad and Mumbai faces CDSCO-mandated containment upgrades for potent compound manufacturing. Domestic valve suppliers compete with European imports on isolator-integrated dome valve configurations. Gujarat-based process equipment fabricators are expanding capacity to serve export markets in Southeast Asia and Africa.
Netherlands
Food processing decarbonization grants fund pneumatic-to-electric actuator conversions in dairy and ingredient handling facilities. EU Green Deal capital incentives compress technology transition timelines for washdown-compatible stainless steel installations. Rotterdam-area chemical terminals specify integrated digital architectures for remote diagnostics capability.
China
Domestic pneumatic conveying equipment production scales to serve mining and cement processing demand across Shanxi and Inner Mongolia. GB standards for dust explosion protection constrain material selection in coal handling applications. Yangtze River Delta valve assemblers source actuators from Japanese and German component suppliers for premium positioning.
Solid Flow Rate Valve Control Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct margin tiers in solid flow rate valve control. Tier-one integrated automation suppliers anchor premium positioning through digital positioner bundling, while mid-scale fabricators defend share in heavy-duty abrasive applications. Three archetypes dominate: full-line automation conglomerates with control system integration capability, specialized solids handling engineers with rotary valve expertise, and regional pneumatic component assemblers serving price-sensitive maintenance markets. Competitive moves concentrate on strategic partnerships for smart positioner development and geographic expansion into pharmaceutical containment applications.
Among diversified automation conglomerates, Emerson Electric Co. and Flowserve Corporation exemplify the integrated subsystem approach, bundling valve hardware with distributed control system compatibility. Parker Hannifin Corporation anchors the pneumatic technology specialist tier, extending compressed air actuation expertise into compact manifold configurations. Schenck Process India Private Ltd occupies a position within heavy-duty rotary valve engineering for abrasive solids handling. These three represent distinct strategic postures: control system integration, pneumatic component depth, and application-specific mechanical engineering.
| Leading Market Players |
|---|
| Polimak Grup Endüstriyel Üretim San. A.Ş. |
| Parker Hannifin Corporation |
| Schenck Process India Private Ltd |
| Salina Vortex Corporation |
| Coperion GmbH |
| WAMGROUP S.p.A |
| Flowserve Corporation |
| Emerson Electric Co. |
| IMI plc |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between ATEX-compliant pneumatic systems and standard electric actuators manifests in divergent margin structures and sourcing footprints across the solid flow rate valve control market. Premium-tier hardware commands captive supply relationships with German seal compounders, while commodity pneumatic assemblies draw from distributed Asian component markets.
Pricing Analysis
Margin tightening in food-grade electric actuator tiers reflects 316L stainless steel input volatility and nickel price swings without corresponding pricing power. Three-tier pricing structure across premium ATEX-certified, standard industrial-grade, and economy maintenance-replacement levels anchors the dominant model. Price differentiation traces to certification burden and predictive maintenance integration depth. Chemical processors in Germany and the United States show lowest price sensitivity given regulatory compliance mandates; maintenance procurement teams in Asian shale gas operations exhibit highest sensitivity.
Supply Chain Analysis
Perfluoroelastomer rotary shaft seal supply rests on three European specialty compounders concentrated in Germany and Switzerland. Valve OEMs source 316L stainless steel from German and Japanese mills, pneumatic actuators from Italian and Chinese fabricators, and digital positioner electronics from Taiwanese semiconductor suppliers. Single-source vulnerability in high-temperature seal compounds creates concentrated supply risk. Distribution runs through regional valve distributors in maintenance markets and direct OEM relationships in greenfield project procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Perfluoroelastomer seal compound concentration props pricing power for integrated subsystem suppliers, constraining volume expansion for standalone hardware vendors.
For Market Incumbents: Acquire predictive maintenance software capabilities to anchor subscription revenue streams against electric actuator substitution pressure. Consolidate backward control over bio-based elastomer R&D programs ahead of REACH Annex XVII fluorinated compound restrictions. Defend installed base in North American shale gas corridors through pneumatic technology roadmaps that address compressed air leakage inefficiency. For New Entrants and Emerging Players: Direct-to-pharmaceutical-procurement digital channels bypass established distributor networks in Indian potent compound manufacturing. Target CDSCO-mandated containment upgrade cycles in Hyderabad and Mumbai with isolator-integrated dome valve configurations. Lead with edge-computing positioner bundles that compress DCS integration friction for brownfield chemical plants. For Investors and Strategic Acquirers: Re-rating potential sits with heavy-duty rotary valve specialists given abrasive solids handling demand in mining and shale gas proppant logistics. Five-to-ten year viability hinges on digital twin convergence and predictive analytics annuity capture. Watch EU Green Deal capital incentive exhaustion in Netherlands and Denmark food processing as technology transition inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seal Compounding | Captive supply of bio-based elastomers addresses REACH fluorinated compound restrictions for German chemical processors. |
| Smart Positioner Platform Launch | Edge-computing diagnostics compress maintenance economics for predictive-enabled valve architectures in Texas shale corridors. |
| Joint Venture for Indian Pharmaceutical Containment | Isolator-integrated dome valve partnerships capture CDSCO upgrade cycles in Hyderabad potent compound manufacturing. |
| Geographic Expansion into EU Decarbonization Grants | Pneumatic-to-electric conversion projects in Dutch dairy processing align with EU Green Deal capital incentive windows. |
| Long-term Supply Agreement for 316L Stainless Steel | Fixed-price mill contracts hedge nickel volatility exposure in food-grade electric actuator fabrication. |
Study Parameters
Independent corroboration across maintenance directors at chemical processing facilities, procurement leads at valve OEMs, and aftermarket service heads at pneumatic component distributors underwrites the qualitative findings. Primary fieldwork encompassed plant engineers in German petrochemical clusters, technical R&D directors at seal compounders, and channel partners in North American shale gas supply chains. Secondary validation drew from EPA New Source Performance Standards filings, ECHA REACH registration databases, SEC 10-K disclosures by listed automation conglomerates, and customs trade data for pneumatic conveying equipment. Bottom-up segment sizing triangulated against top-down industry association estimates from Cefic and the American Chemistry Council.
Comparable-period anchoring to historical retrofit cycle data and regulatory compliance deadline clustering established the forecast window boundaries. The analytical framework modeled technology substitution dynamics, end-use vertical intensity, and regional regulatory divergence across the projection horizon. Segmentation dimensions encompassed actuation technology type, certification tier, and application duty cycle. CAGRs derived from installed base replacement velocity and new installation specification pull in continuous versus batch processing environments. Forecast inputs incorporated nickel price trajectory assumptions and EU Green Deal capital incentive exhaustion curves.
Inputs from ECHA substance restriction timelines and EPA emissions certification protocols were available through the study window; gaps in real-time seal compound qualification data introduce uncertainty bands around bio-based elastomer adoption velocity. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology transition grant continuity. Abrasive solids exposure severity in proppant handling and fluorinated compound substitution pace warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
APAC Pressure Sensors Market
Sensors and Controls
Europe Vibration Sensors Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
Electronic Differential Control Module Market
Sensors and Controls
China Sensors Market
Sensors and Controls
Thermometer Market
Sensors and Controls
Global Smartphone Sensors Market
Sensors and Controls
Environmental Noise Cancellation Microphones Market
Sensors and Controls
Level Measuring Equipment Market
Sensors and Controls
Global Thermocouple Temperature Sensors Market
Sensors and Controls
Active Sensor Market
Sensors and Controls
Germany Digital Thermometer Market
Sensors and Controls
Level Transmitter Market
Sensors and Controls
Variable Reluctance Sensor Market
Sensors and Controls
Printed and Flexible Sensors Market
Sensors and Controls
High-End Accelerometer Market