
 Europe Fire Sprinklers Market | 2026-2036
Europe Fire Sprinklers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fire Sprinklers Market Intelligence
The capital-intensity gap between full-system integrators and component suppliers is collapsing as European contractors consolidate procurement around turnkey fire safety packages. Johnson Controls International PLC leverages its building automation footprint to bundle sprinkler systems with detection and alarm infrastructure across Nordic commercial portfolios. Minimax Fire Solutions International GmbH anchors its position through deep specialization in industrial deluge systems for German chemical and automotive plants. Siemens AG competes by extending its digital twin capabilities into predictive maintenance for sprinkler networks in Dutch logistics hubs.
Europe fire sprinklers are thermosensitive discharge devices comprising glass-bulb or fusible-link sprinkler heads, pressurized piping networks, and control valves designed to activate individually at predetermined temperatures between 57°C and 343°C depending on hazard classification. Their primary purpose is to suppress or control incipient fires in occupied structures until emergency services arrive, reducing property loss and life safety risk. Wet pipe configurations dominate residential and standard commercial installations across the region due to simplicity and reliability, while pre-action systems command premium positioning in institutional and cultural heritage applications where accidental discharge carries catastrophic water damage exposure. Deluge technology leads growth in industrial end uses where flammable liquid hazards require immediate total-flooding response.
The EU Construction Products Regulation harmonizes fire safety performance declarations across member states, while CE marking mandates and national building codes such as Germany's DIN 1988 and France's APSAD standards dictate installation protocols and product certification requirements. The EU Green Deal's building renovation wave is accelerating retrofit demand by embedding fire system upgrades within energy-efficiency refurbishment mandates. Stakeholders must monitor evolving MDR-related supply chain documentation requirements for electronic monitoring components and assess how national transpositions of the Energy Performance of Buildings Directive reshape installation timing and specification thresholds.
Market Dynamics
The EU Green Deal's building renovation wave is compressing installation timelines across member states, forcing contractors to synchronize fire safety upgrades with thermal envelope retrofits and HVAC replacements in a single mobilization window.
Growth Catalysts
- EU Green Deal integration:Energy-efficiency refurbishment mandates in Germany and France now embed sprinkler retrofits within building renovation permits, creating bundled demand streams that reduce customer acquisition costs for installers.
- Data center construction:Pre-action system demand from Spanish and Dutch hyperscale facilities is accelerating as thermal load densities exceed 50kW per rack, requiring water-mist suppression compatibility with IT equipment.
- CE marking harmonization:Mutual recognition of fire safety performance declarations across Poland, Czech Republic, and Hungary is eliminating duplicate certification costs for component suppliers expanding eastward.
Market Restraints
- Copper and steel input volatility:Pressurized piping networks represent 35-40% of system material costs, exposing integrators to London Metal Exchange price swings that compress bid margins on fixed-price contracts.
- Specialized valve supplier concentration:German and Italian precision foundries dominate high-pressure deluge valve production, creating single-source vulnerability for industrial system assemblers.
- Water chemistry limitations:Hard water regions in southern Spain and Portugal accelerate corrosion in wet pipe networks, shortening maintenance intervals and raising lifecycle cost objections from municipal buyers.
Strategic Opportunities
- Romanian and Bulgarian new construction:EU cohesion fund infrastructure projects in these member states are mandating NFPA-equivalent protection levels for the first time, opening greenfield specification battles.
- Digital twin convergence:Integration of BIM-enabled sprinkler network modeling with predictive maintenance platforms is creating recurring revenue streams for controls specialists in Dutch logistics hubs.
- Heritage building adaptive reuse:France's tax incentive schemes for converting historic industrial structures to hospitality or office use are driving demand for concealed pendant heads and dry pipe alternatives.
Industry Challenges
- Certified installer scarcity:Germany's chamber of crafts reports insufficient master sprinkler fitters to meet retrofit demand acceleration, extending project timelines and forcing wage inflation.
- Legacy detection protocol fragmentation:Integration of addressable sprinkler monitoring with 1980s-era fire alarm panels in Belgian and Austrian commercial portfolios requires costly gateway hardware and site-specific programming.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fire Sprinklers Market |
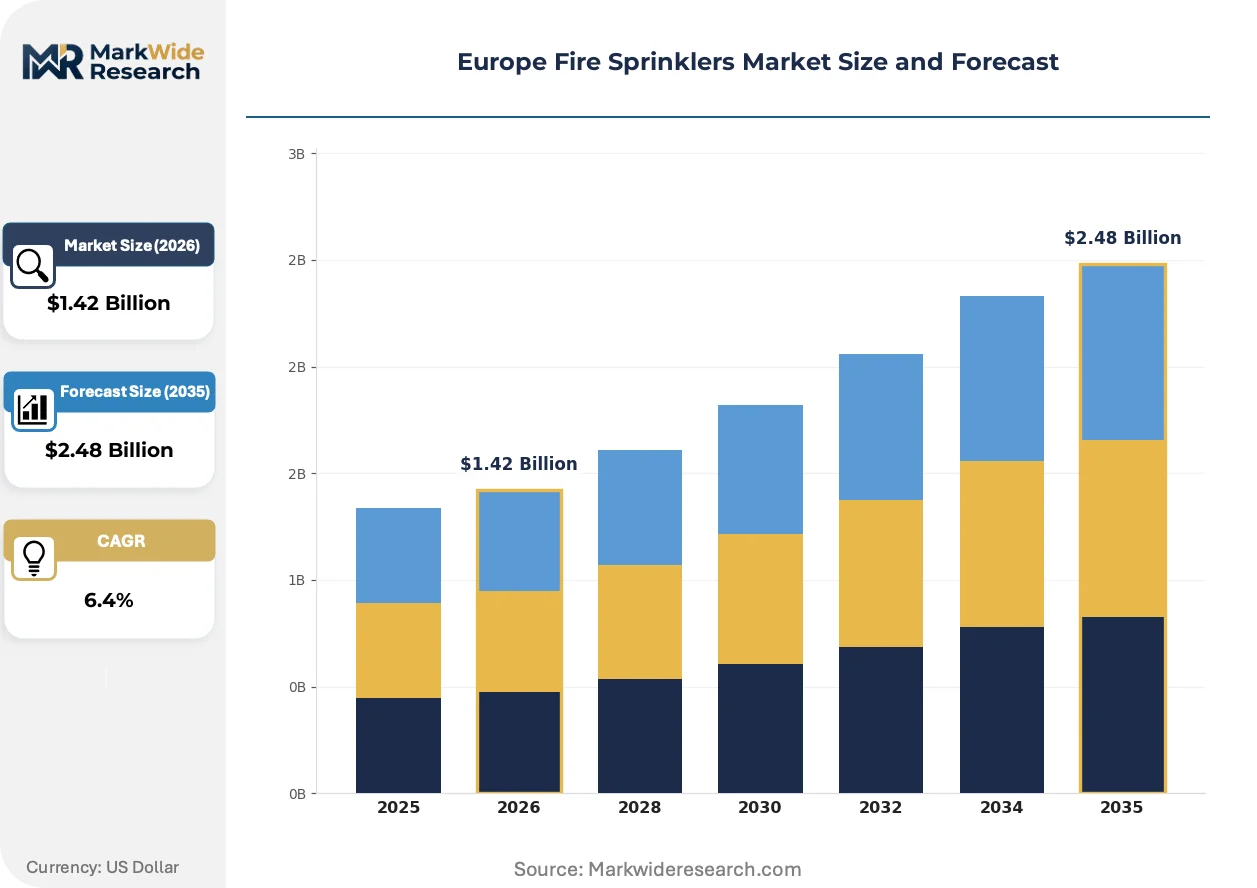
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Pipe, Dry Pipe, Pre-Action, Deluge End User: Commercial, Industrial, Residential, Institutional Installation Type: New Construction, Retrofit, Maintenance, Upgrades Component: Sprinkler Heads, Control Valves, Pumps, Piping |
| Companies Covered | Siemens AG, GW Sprinkler A/S, Minimax Fire Solutions International GmbH, Victaulic, Rapidrop Global Ltd., Johnson Controls International PLC, Robert Bosch GmbH, Potter Electric Signal Company, LLC, Honeywell International, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fire Sprinklers Market Strategic Shifts & Innovations
European fire protection is pivoting from passive compliance toward predictive risk management, with sensor-enabled sprinklers and automated inspection protocols reducing insurance premiums for early adopters.
Water-mist suppression technology is displacing traditional deluge systems in Scandinavian maritime and offshore energy applications. Norwegian shipyards and Danish wind turbine manufacturers are specifying high-pressure mist for machinery spaces and nacelle compartments. The shift is compressing water damage exposure while maintaining Class A fire control ratings.
REACH chemical registration requirements are reshaping material specifications for fusible-link alloys and glass-bulb fluids. ECHA scrutiny of lead and cadmium content in thermal elements is forcing reformulation of sprinkler head components. German and French manufacturers are accelerating nickel-based alloy substitution to maintain CE marking validity ahead of sunset dates.
Facility managers in Netherlands and Belgium are unbundling maintenance contracts from initial installation bids, creating standalone service revenue pools. Independent inspection firms are capturing recurring calibration and flow-testing work that integrators previously bundled. The separation is most visible in warehouse and distribution center portfolios where third-party logistics operators prioritize operational continuity over capital relationship loyalty.
Europe Fire Sprinklers Market Segmentation
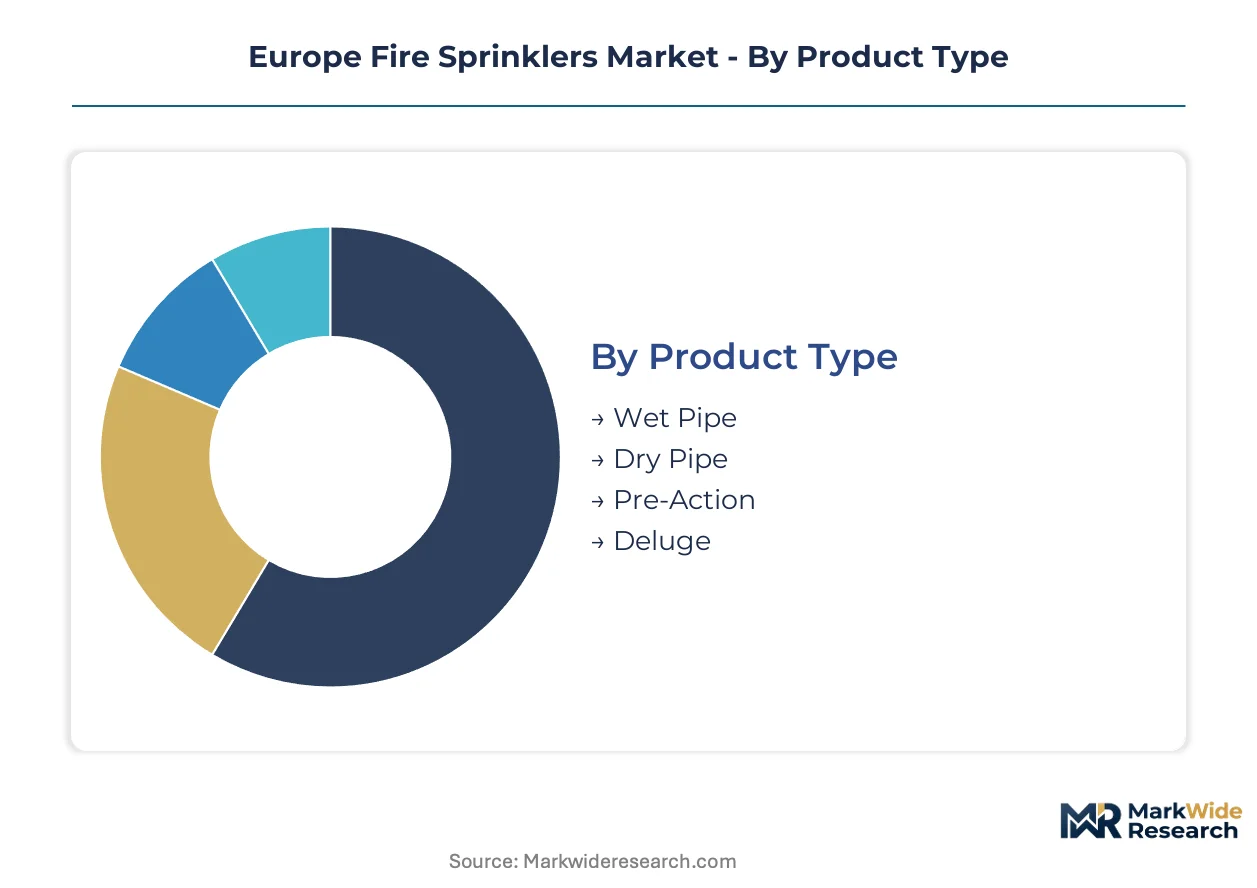
European fire sprinkler procurement channels diverge sharply between specification-driven new construction and compliance-driven retrofit work. Contractors bundle product selection with installation and maintenance contracts, making segment-channel alignment critical for component suppliers seeking direct access to end users.
Product Type:
Wet pipe systems flow through residential and standard commercial contractors in Poland and the Netherlands, while pre-action and deluge configurations concentrate in industrial integrators serving German chemical and Spanish data center projects.
- Wet Pipe:Pressurized water-filled piping networks with thermosensitive glass-bulb heads activate at 57°C to 79°C for standard hazard occupancies. German and Dutch residential developers specify these for new apartment construction under DIN 1988 and comparable national codes, prioritizing reliability and minimal maintenance over suppression sophistication.
- Pre-Action:Double-interlock systems requiring both detection and head activation before water enters pipes, protecting water-sensitive assets. Spanish hyperscale data centers and French museum storage facilities specify these for cleanroom and cultural heritage applications where accidental discharge would destroy irreplaceable assets or IT infrastructure.
- Dry Pipe:Air-pressurized piping suited for unheated spaces in Nordic logistics facilities and Alpine commercial structures, preventing freeze damage.
- Deluge:Open-head total-flooding systems triggered by detection systems alone, deployed in German automotive paint booths and offshore energy platforms.
Wet pipe dominates installed base across residential and standard commercial stock. Pre-action is where expansion concentrates as data center thermal densities and heritage adaptive reuse projects multiply.
End User:
Cost tier differentiation separates premium-specified industrial and institutional segments from price-sensitive residential procurement, with commercial occupying the contested middle ground where bundled service contracts determine supplier selection.
- Commercial:Office, retail, and hospitality properties across France and Germany drive retrofit bundling with energy-efficiency upgrades under EU Green Deal renovation mandates. Facility managers prioritize lifecycle cost over capital expenditure, favoring wet pipe simplicity in standard risk categories.
- Industrial:Chemical processing, automotive manufacturing, and pharmaceutical production in Germany and Spain command specialized deluge and pre-action configurations. German chemical plants under ECHA process safety requirements specify redundant high-pressure systems, while Spanish pharmaceutical cleanrooms demand stainless steel construction and validation documentation.
- Residential:Multi-family housing construction in Poland and the Netherlands absorbs volume wet pipe production, with developer procurement favoring CE-marked commodity heads over premium brands.
- Institutional:Healthcare, education, and government facilities in Belgium and Austria maintain legacy detection infrastructure requiring gateway hardware for modern sprinkler monitoring integration.
Commercial holds the largest project pipeline volume. Industrial is climbing the fastest as process safety regulations tighten and data center construction accelerates.
Installation Type:
Volume concentration in new construction is shifting toward retrofit as the EU Green Deal's building renovation wave compresses installation timelines across member states.
- New Construction:Greenfield commercial and residential projects in Romania and Bulgaria mandate NFPA-equivalent protection for the first time under cohesion fund requirements. Contractors specify complete wet pipe systems during structural framing, minimizing coordination costs.
- Retrofit:Energy-efficiency refurbishment in Germany and France embeds sprinkler upgrades within thermal envelope and HVAC replacement mobilizations. French tax incentive schemes for historic industrial conversion to hospitality use drive concealed pendant head and dry pipe specifications.
- Maintenance:Dutch and Belgian facility managers unbundle inspection contracts from installation, creating standalone revenue for independent calibration and flow-testing specialists.
- Upgrades:Addressable monitoring retrofits in Belgian and Austrian commercial portfolios require costly gateway hardware to integrate with 1980s-era fire alarm panels.
New construction retains volume leadership in eastern member states. Retrofit is gaining share fastest in western markets where building stock age and regulatory bundling coincide.
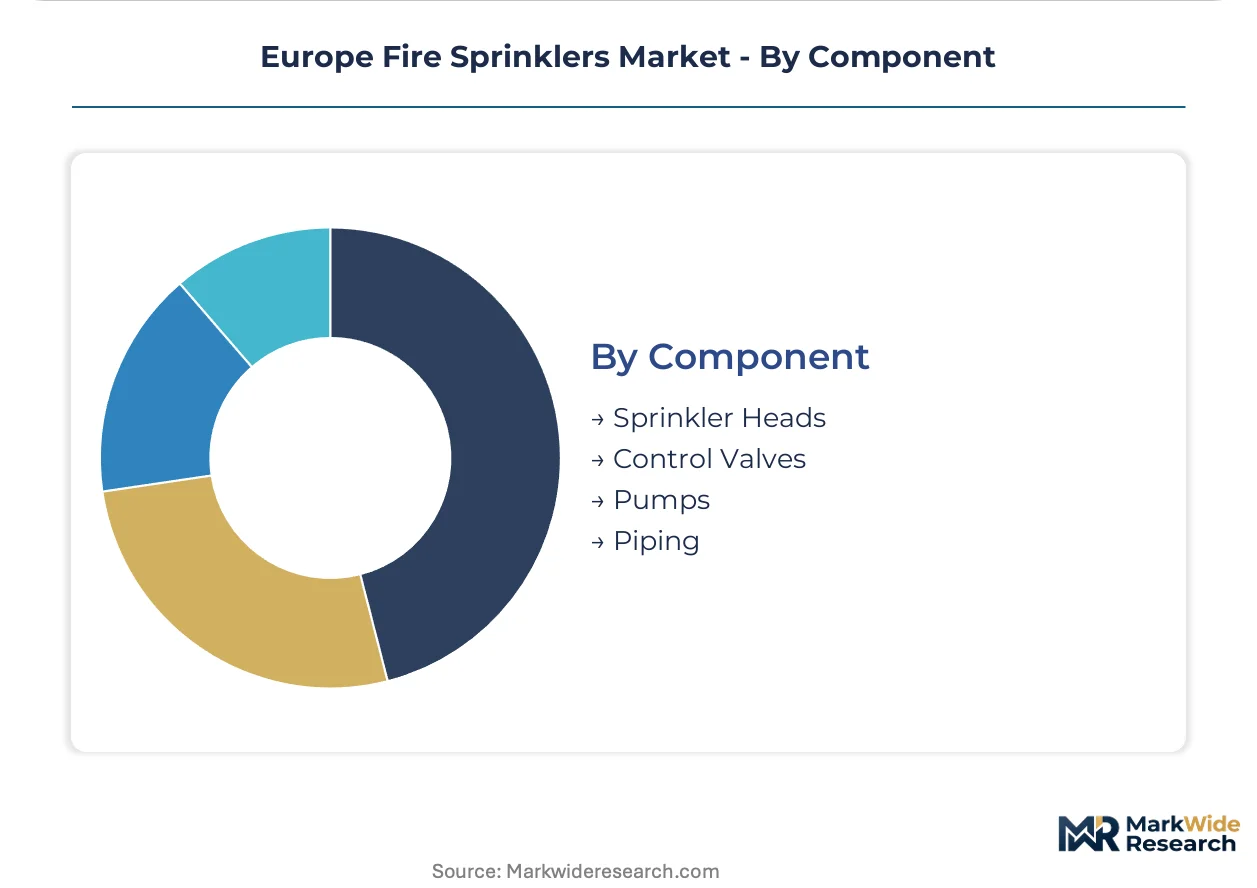
Component:
Supply concentration in German and Italian precision foundries for high-pressure valves creates margin pressure for system assemblers, while sprinkler head commoditization favors scale manufacturers.
- Sprinkler Heads:Glass-bulb and fusible-link discharge devices face REACH-driven reformulation of thermal elements as ECHA scrutiny of lead and cadmium accelerates nickel-based alloy substitution. German and French manufacturers prioritize CE marking continuity ahead of chemical sunset dates.
- Control Valves:High-pressure deluge and pre-action valve assemblies concentrate in German and Italian foundries, creating single-source vulnerability for industrial system integrators.
- Pumps:Diesel and electric fire pumps specified for high-hazard industrial applications require dedicated maintenance protocols in German chemical plant portfolios.
- Piping:Copper and steel pressurized networks represent 35-40% of system material costs, exposing integrators to London Metal Exchange volatility on fixed-price contracts.
Piping and heads dominate component value by volume. Control valves represent the steepest expansion trajectory as industrial deluge system demand accelerates and foundry capacity tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in German industrial sprinkler contracts exceeds French commercial retrofits by 15-20% due to stricter DIN 1988 certification requirements and chemical plant hazard classifications. Eastern member states absorb commodity wet pipe volumes at thinner margins as EU cohesion funds standardize NFPA-equivalent protection levels.
Germany
Automotive paint booths in Stuttgart and Wolfsburg drive deluge system specifications, while ECHA process safety mandates enforce redundant high-pressure configurations. DIN 1988 installation protocols govern residential wet pipe deployments across North Rhine-Westphalia apartment construction. Bavarian chemical clusters anchor premium valve demand through specialized foundry relationships.
France
Museum storage facilities in Paris and Lyon specify pre-action double-interlock systems to protect water-sensitive cultural assets from accidental discharge. APSAD standards dictate commercial installation protocols, embedding sprinkler upgrades within EU Green Deal thermal refurbishment permits. Tax incentive schemes for historic industrial conversion to hospitality use accelerate concealed pendant head demand in Bordeaux and Marseille.
Spain
Hyperscale data centers outside Madrid and Barcelona absorb pre-action systems as rack thermal densities exceed 50kW, requiring water-mist compatibility with IT infrastructure. Pharmaceutical cleanrooms in Catalonia demand stainless steel construction and validation documentation under national health ministry protocols. Southern hard water regions accelerate corrosion concerns in wet pipe networks.
Netherlands
Logistics hubs in Rotterdam and Eindhoven unbundle maintenance contracts from installation bids, creating standalone revenue for independent flow-testing specialists. BIM-enabled sprinkler network modeling converges with predictive maintenance platforms in Dutch distribution centers. Randstad commercial developers specify wet pipe simplicity under harmonized CE marking acceptance.
Poland
Multi-family residential construction in Warsaw and Kraków absorbs volume wet pipe production as developers prioritize CE-marked commodity heads over premium brands. EU cohesion fund infrastructure mandates NFPA-equivalent protection levels for the first time in public building stock. New construction pipelines dominate procurement channels with minimal retrofit penetration.
Europe Fire Sprinklers Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the European fire sprinkler value chain. Building automation conglomerates bundle sprinkler systems with detection infrastructure, while specialized industrial fabricators dominate high-pressure deluge applications. Three archetypes structure competition: full-system integrators leveraging controls portfolios, component specialists commanding foundry relationships, and scale manufacturers driving commoditized head production. M&A activity concentrates procurement around turnkey packages, and strategic partnerships between valve foundries and system assemblers tighten supply security.
Among building automation conglomerates, Johnson Controls International PLC and Siemens AG occupy positions spanning integrated fire safety portfolios. Johnson Controls leverages its Nordic commercial footprint to bundle detection and alarm infrastructure with sprinkler networks. Siemens extends digital twin capabilities into predictive maintenance platforms for logistics hub applications. Specialized industrial players include Minimax Fire Solutions International GmbH, which anchors its market presence through deep focus on German chemical and automotive plant configurations. These three companies exemplify divergent strategic vectors: bundled building systems, predictive digital services, and industrial hazard specialization.
| Leading Market Players |
|---|
| Siemens AG |
| GW Sprinkler A/S |
| Minimax Fire Solutions International GmbH |
| Victaulic |
| Rapidrop Global Ltd. |
| Johnson Controls International PLC |
| Robert Bosch GmbH |
| Potter Electric Signal Company, LLC |
| Honeywell International, Inc. |
| Others |
Cost & Logistics Intelligence
Foundry capacity utilization in German and Italian precision metalworking clusters shapes both supply concentration and price floors for high-pressure valve assemblies. Scale economies at these specialized facilities create tiered output costs that propagate through industrial sprinkler system pricing, while commodity head production in Eastern European stamping operations sets baseline competition for residential wet pipe segments.
Pricing Analysis
Configured-to-order pricing for pre-action and deluge systems commands a 15-20% premium over standard wet pipe configurations. Project-based pricing dominates as contractors bundle installation, commissioning, and maintenance into single-mobilization contracts. Price differentiation rests on CE marking tier and DIN 1988 certification grade, with German chemical plant specifications requiring redundant high-pressure architectures. Cost compression in residential wet pipe segments is intensifying because Polish and Dutch developers prioritize CE-marked commodity heads. Municipal buyers in Southern Europe exhibit highest price sensitivity due to hard-water corrosion concerns shortening lifecycle economics.
Supply Chain Analysis
Strategic stockpiling of copper and steel pressurized piping prevails among German integrators facing London Metal Exchange volatility, while just-in-time component flows dominate residential wet pipe procurement in Poland and the Netherlands. High-pressure deluge valve forging concentrates in Germany and Italy, with glass-bulb head stamping distributed across Czech and Hungarian facilities. Raw material dependencies draw from copper rod, carbon steel coil, and nickel-based alloys for REACH-compliant thermal elements. Single-source vulnerability runs through German automotive paint booth valve suppliers. Distribution runs through building automation conglomerates bundling detection infrastructure with sprinkler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward facility managers unbundling maintenance from installation contracts, fragmenting procurement relationships that previously locked integrators into long-term service revenue streams.
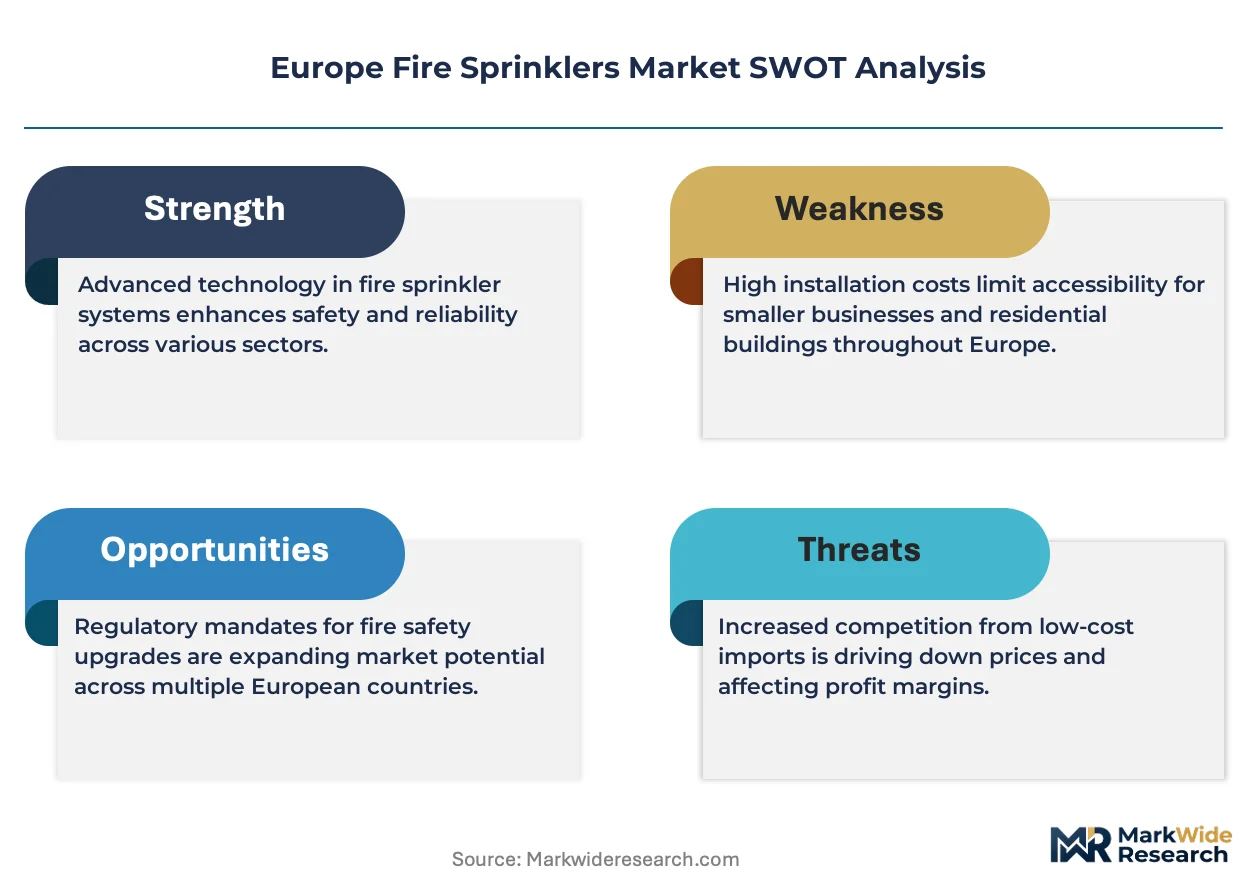
For Market Incumbents: Compound digital twin capabilities into predictive maintenance platforms for Dutch logistics hubs, capturing recurring revenue as facility managers prioritize operational continuity. Deepen backward integration into nickel-based alloy foundry relationships to secure REACH-compliant thermal element supply ahead of ECHA sunset dates. Address water-mist substitution threats in Scandinavian maritime applications by validating hybrid suppression compatibility with existing deluge infrastructure.
For New Entrants and Emerging Players: Lead with concealed pendant head specialization for French heritage adaptive reuse projects, where tax incentive schemes accelerate historic industrial conversion to hospitality use. Target Romanian and Bulgarian greenfield construction as EU cohesion funds mandate NFPA-equivalent protection for the first time. Pursue independent inspection and calibration certification to capture unbundled maintenance contracts in Belgian and Dutch warehouse portfolios.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component specialists commanding foundry relationships over scale manufacturers facing head commoditization. Long-term viability rests on digital service attachment rates and regulatory compliance moats rather than installation volume alone. Acquisition focus should center on German precision valve fabricators with ECHA process safety validation. Watch for inflection when BIM-enabled predictive maintenance penetration in logistics hubs crosses threshold adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Alloy Foundries | Secures REACH-compliant thermal element supply ahead of ECHA cadmium sunset deadlines. |
| BIM-Enabled Predictive Maintenance Platform | Captures recurring revenue from Dutch facility managers unbundling inspection contracts. |
| Heritage Concealed Pendant Head Certification | Unlocks French tax incentive-driven adaptive reuse projects in Bordeaux and Marseille. |
| Water-Mist Maritime Validation Program | Defends deluge positioning against Norwegian shipyard high-pressure mist substitution. |
| Cohesion Fund Specification Capture | Establishes NFPA-equivalent presence in Romanian and Bulgarian greenfield construction. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EU Construction Products Regulation filings, ECHA REACH registration databases, and national building code transpositions across DIN 1988 and APSAD standards. Interviews with fire protection contractors, facility managers at Dutch distribution centers, German chemical plant safety officers, and French heritage conversion developers informed demand segmentation. Secondary validation drew from CE marking notification body records, London Metal Exchange copper and steel pricing archives, and EU cohesion fund procurement disclosures. Bottom-up project pipeline analysis triangulates against top-down regulatory mandate sizing.
Segmentation dimensions modeled span product type, end user industry, installation channel, and component category across the projection horizon. The analytical framework weights retrofit bundling intensity under EU Green Deal renovation mandates against new construction standardization in Eastern member states. CAGRs derive from installation volume trajectories correlated with thermal envelope refurbishment permits and data center rack density specifications. Industry-specific forecast inputs include hyperscale facility pre-action adoption curves and REACH-driven material substitution timelines.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal funding continuity or ECHA enforcement intensity would require recalibration. Forecasts reflect assumptions regarding installer capacity expansion in Germany and copper price volatility ranges. Revision becomes warranted when BIM-predictive maintenance adoption in logistics hubs crosses threshold penetration rates or when cohesion fund disbursement timelines shift materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
UK Manufactured Homes Market
Construction and Engineering
Asia-Pacific Mobile Light Tower Market
Construction and Engineering
FRP Bridge Market
Construction and Engineering
Timber Construction Connectors Market
Construction and Engineering
Rough Terrain Lift Truck Market
Construction and Engineering
Casting Equipment Market
Construction and Engineering
Compact Loaders Market
Construction and Engineering
Geofoam Market
Construction and Engineering
Stair Lifts and Climbing Devices Market
Construction and Engineering
Sound Barriers Market
Construction and Engineering
Carry Deck Crane Market
Construction and Engineering
Industrial Wood Chipper Market
Construction and Engineering
Global Scaffolding Market
Construction and Engineering
DTH Drill Rig Market
Construction and Engineering
Latin America Prefab Wood Buildings Market
Construction and Engineering
Qatar Residential Construction Market