
 Global Industrial Fire Sprinklers Market | 2026-2036
Global Industrial Fire Sprinklers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Fire Sprinklers Market Outlook
UL-listed and FM-approved specification tiers is bifurcating procurement patterns across heavy industrial sites. Johnson Controls International leverages its building-systems integration to bundle sprinkler packages with detection electronics. Viking Group Inc. anchors its position through deep specialization in marine and offshore sprinkler configurations. Minimax GmbH & Co. KG competes on engineered deluge systems for German automotive and chemical complexes.
Industrial fire sprinklers are automatic water-discharging devices operating at rated pressures with fusible-element or glass-bulb activation temperatures between 57°C and 343°C, designed to control or suppress fire development in occupancies with high fuel loads. Wet pipe systems dominate installed base across manufacturing facilities and warehouses due to simplicity and maintenance economics, while pre-action configurations are gaining fastest in data centers where accidental discharge risks carry catastrophic equipment-replacement costs. Deluge systems command concentrated margin pools in oil and gas processing and power generation, where rapid total-flooding response overrides first-cost sensitivity.
NFPA 13 and FM Global data sheets govern product certification and installation practice in the United States, while the EU Construction Products Regulation and EN 12845 shape market access across European member states. China's GB 50084 standard and fire safety inspection regimes under the Ministry of Emergency Management are elevating retrofit obligations in legacy industrial zones. Stakeholders must monitor divergence between regional certification requirements and the pace of smart-sensor integration into conventional sprinkler infrastructure.
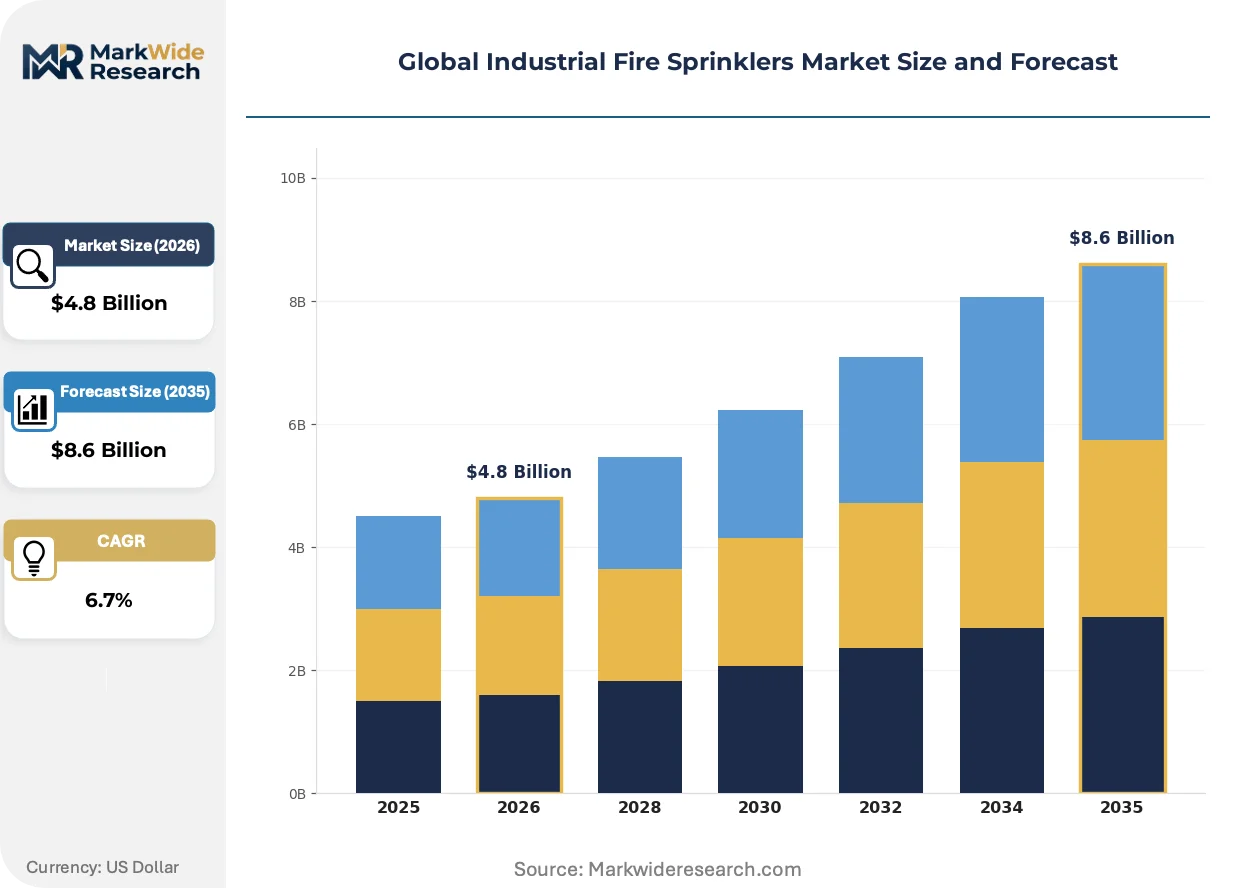
Market Dynamics
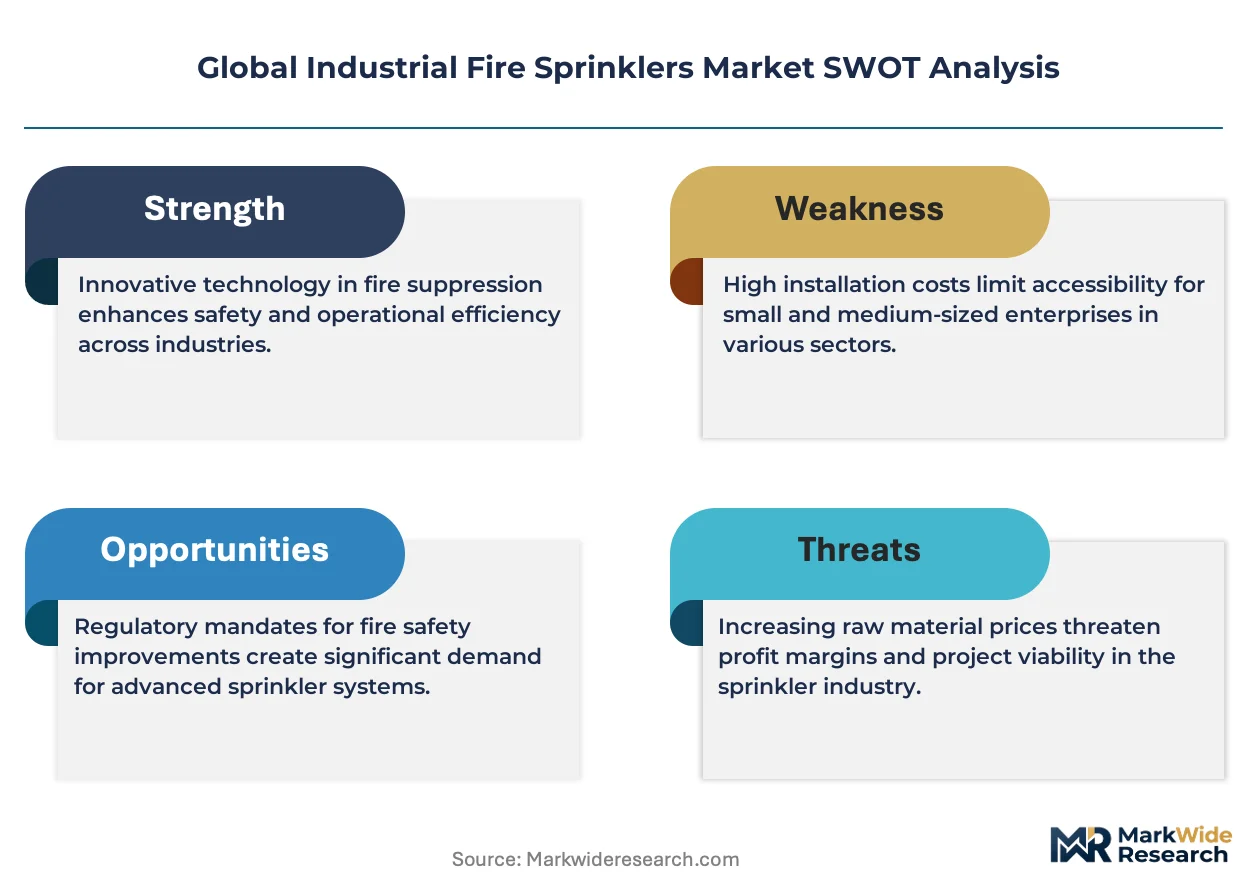
The industrial fire sprinkler market is experiencing structural pressure from tightening certification tiers that separate mission-critical installations from commodity specifications. UL-listed and FM-approved product lines now command procurement preference in data centers, chemical processing, and marine applications where failure costs exceed equipment replacement values.
Growth Catalysts
- NFPA 13 Standard Updates:The 2022 edition of NFPA 13 expanded coverage requirements for high-piled storage and automated warehouses, mandating faster-response sprinklers in rack configurations. This revision accelerates retrofit cycles across legacy distribution centers in the United States.
- Data Center Density:Hyperscale facilities are deploying pre-action systems with nitrogen-charged supervisory piping to eliminate accidental discharge risks while maintaining sub-30-second activation speeds for lithium-ion battery protection.
- China's Industrial Zone Expansion:The Ministry of Emergency Management is enforcing GB 50084 compliance audits across legacy manufacturing clusters in Jiangsu and Guangdong provinces, generating replacement demand for corroded wet-pipe infrastructure.
Market Restraints
- Copper and Brass Input Volatility:Sprinkler body and fitting production depends on copper alloy prices that fluctuate with Chilean and Peruvian mining output, compressing margin stability for mid-tier manufacturers without material hedging programs.
- Regional Certification Fragmentation:Divergent testing protocols between FM Global, UL, and EU Notified Bodies force product line duplication, raising inventory carrying costs for suppliers serving multiple continental markets.
- Water Scarcity Constraints:Arid regions in Australia and the southwestern United States face municipal supply restrictions that limit traditional wet-pipe system expansion, pushing specification toward chemical suppression alternatives in certain industrial categories.
Strategic Opportunities
- India's PLI-Linked Manufacturing:Production-linked incentive schemes for specialty steel and precision components create localized supply chain advantages for sprinkler assembly operations targeting domestic infrastructure buildout.
- Smart Sensor Convergence:Integration of IoT pressure transducers and thermal imaging with conventional sprinkler infrastructure enables predictive maintenance contracts and remote monitoring revenue streams for installation contractors.
- Offshore Wind Platform Protection:Unregulated marine fire suppression specifications in emerging North Sea and East Asian wind markets allow engineered deluge system providers to establish proprietary performance standards before codification.
Industry Challenges
- Certified Installer Shortage:NICET-certified technicians and licensed sprinkler fitters are concentrated in established industrial regions, constraining deployment velocity in rapidly developing manufacturing corridors.
- Legacy System Integration:Retrofit projects in 1980s-era facilities must reconcile obsolete pipe schedules and thread standards with modern K-factor sprinkler heads, extending project timelines and inspection failure rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Fire Sprinklers Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Pipe, Dry Pipe, Deluge, Pre-Action Application: Manufacturing Facilities, Warehouses, Power Plants, Data Centers Installation Type: New Installation, Retrofit, Maintenance, Inspection End User: Aerospace, Automotive, Pharmaceutical, Oil & Gas |
| Companies Covered | Johnson Controls International, Honeywell International, Viking Group Inc., Minimax GmbH & Co. KG, Robert Bosch GmbH, Siemens AG, Reliable Automatic Sprinkler Co., Inc., API Group Inc., Hochiki Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Fire Sprinklers Market Strategic Shifts
Product development is concentrating on activation reliability and water discharge precision rather than incremental pressure rating improvements. Manufacturers are embedding computational fluid dynamics into sprinkler head design to optimize droplet size distribution for specific fuel load categories.
Advanced glass-bulb formulations with glycerin-based liquids are bifurcating temperature response categories. Data center operators specify 68°C fast-response elements for aisle containment scenarios, while heavy industrial sites retain 141°C standard-response bulbs for ambient heat tolerance. This technical divergence is forcing manufacturers to maintain parallel production lines with distinct thermal calibration equipment.
REACH restrictions on hexavalent chromium plating are compelling European manufacturers to transition sprinkler components to zinc-nickel alloy coatings. The substitution requires revised salt-spray testing protocols under EN 12845, extending product recertification timelines by 8-12 months for suppliers with legacy chrome-plated inventories.
Specification authority is migrating from general contractors to specialized fire protection engineering consultants. Large industrial buyers in Germany and the Netherlands now retain independent fire risk assessors who mandate performance-based designs over prescriptive code compliance, elevating engineered system margins and compressing commodity product volumes in premium installations.
Global Industrial Fire Sprinklers Market Segmentation
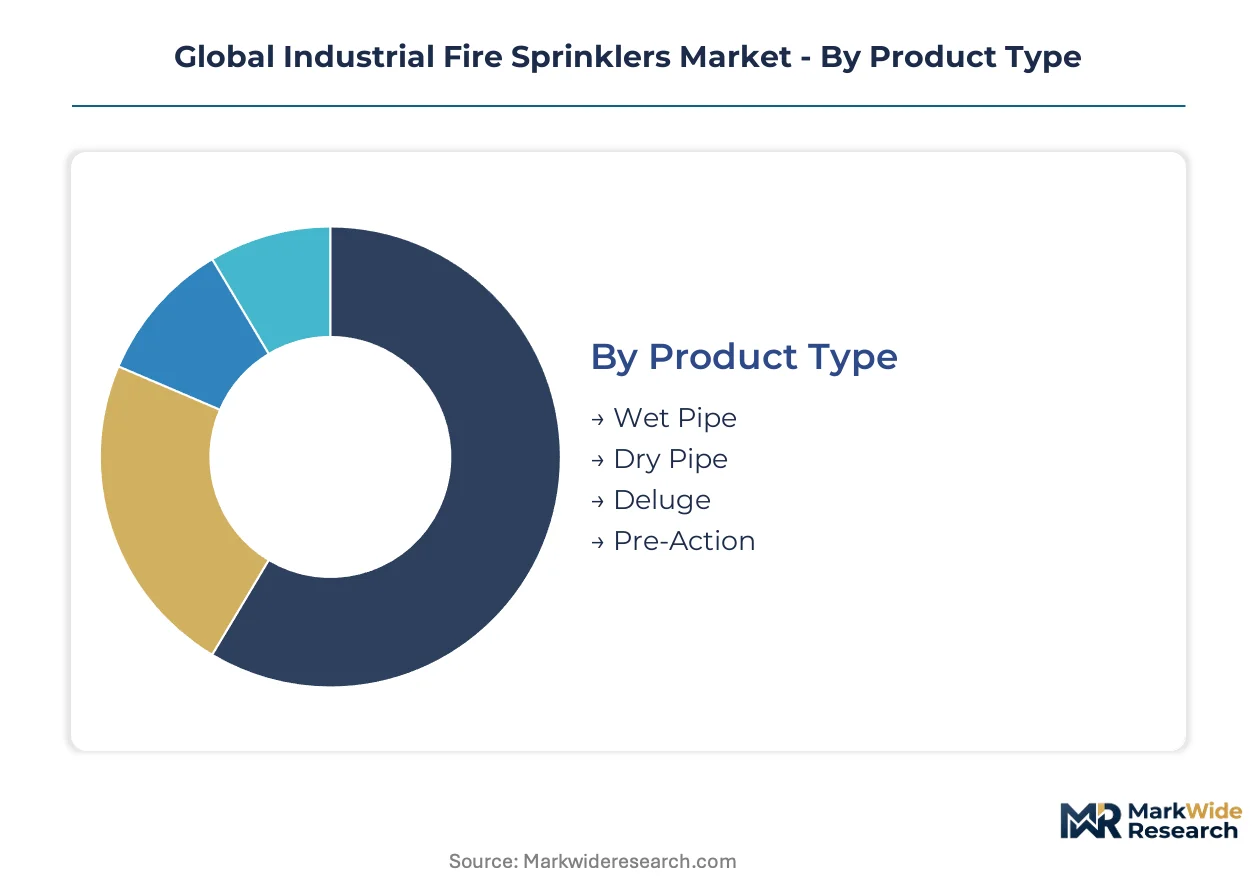
Industrial fire sprinkler procurement divides sharply between prescriptive code compliance and performance-engineered specifications. Regulatory tiering across NFPA 13, EN 12845, and GB 50084 creates divergent product qualification requirements that reshape competitive positioning in each segment.
Product Type:
NFPA 13 and FM Global data sheets differentiate system architectures through response time indices and water discharge densities, elevating certified configurations above commodity alternatives.
- Wet Pipe:Pressurized water-filled piping delivers immediate discharge upon fusible element activation. Manufacturing facilities and warehouses across the United States, Germany, and China specify wet pipe infrastructure for cost efficiency and maintenance simplicity in ambient-temperature environments.
- Pre-Action:Supervisory piping charged with compressed air or nitrogen prevents accidental discharge until detection system confirmation. Data centers in Northern Virginia, Frankfurt, and Singapore deploy pre-action architectures to protect server racks and lithium-ion battery storage from water damage.
- Dry Pipe:Air-filled piping with water held below the dry valve suits freezer warehouses and unheated industrial spaces where freeze protection dominates specification.
- Deluge:Open nozzles with rapid total-flooding discharge serve oil and gas processing and power generation applications where fuel load intensity overrides first-cost considerations.
Wet pipe infrastructure handles the majority of installed base throughput; pre-action configurations are climbing the fastest on specification share.
Application:
Facility density and asset replacement value determine suppression system sophistication, with hyperscale operators driving fastest upgrade cycles.
- Data Centers:Hyperscale facilities combine pre-action piping with VESDA early warning detection to achieve sub-30-second response for aisle containment scenarios. Operators in Ashburn, Dublin, and Singapore mandate nitrogen-charged supervisory systems to eliminate discharge risk during maintenance.
- Manufacturing Facilities:Wet pipe networks dominate automotive stamping plants and pharmaceutical cleanrooms where production continuity depends on reliable activation without false discharge. German automotive complexes and Indian PLI-linked component factories anchor demand concentration.
- Warehouses:High-piled storage configurations under NFPA 13 2022 edition require fast-response sprinklers in rack arrangements, accelerating retrofit demand across legacy distribution centers.
- Power Plants:Deluge and water mist systems protect turbine halls and transformer yards where rapid cooling of energized equipment takes priority over water conservation.
Manufacturing facilities command the largest installed base; data centers are expanding most quickly on capital deployment.
Installation Type:
Project economics bifurcate between greenfield specification authority and retrofit constraint management.
- New Installation:Greenfield industrial zones in Jiangsu province, Gujarat state, and Texas permit integrated fire protection design from foundation phase. Engineers specify K-factor optimized heads matched to computational fluid dynamics modeling of fuel load distributions.
- Retrofit:Legacy facilities from the 1980s face pipe schedule incompatibilities and thread standard obsolescence that extend project timelines. China's Ministry of Emergency Management audits across Guangdong legacy clusters generate replacement demand for corroded wet-pipe infrastructure.
- Maintenance:Annual inspection contracts and five-year hydrostatic testing sustain recurring revenue for certified contractors. NICET technician scarcity constrains service capacity in rapidly developing manufacturing corridors.
- Inspection:Regulatory compliance documentation under GB 50084, EN 12845, and NFPA 25 mandates systematic impairment reporting and valve exercising protocols.
New installation captures the dominant share of project value; retrofit activity is accelerating fastest on regulatory enforcement.
End User:
Process hazard classification and business interruption exposure differentiate suppression requirements across industrial verticals.
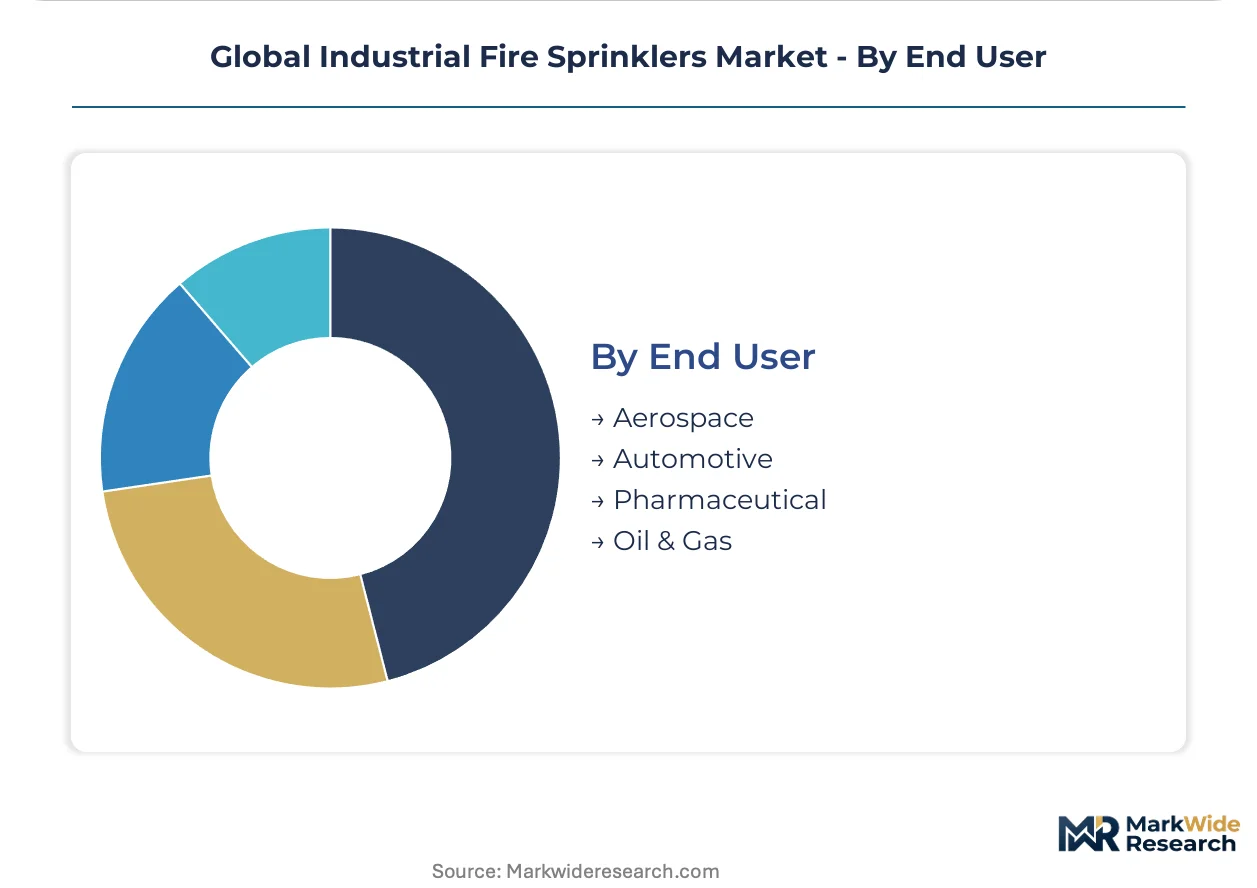
- Oil & Gas:Offshore platforms and refineries specify engineered deluge systems with foam injection capability for hydrocarbon pool fire scenarios. North Sea and East Asian wind platform protection markets remain pre-codification, allowing proprietary performance standard establishment.
- Pharmaceutical:FDA-regulated facilities and EMA-inspected plants demand stainless steel piping and clean agent pre-action systems to protect sterile manufacturing environments. Water damage to validated production lines drives specification toward nitrogen-supervised architectures.
- Automotive:Paint shops and battery assembly lines combine water mist with conventional sprinklers to address flammable liquid and thermal runaway risks simultaneously.
- Aerospace:Hangars and MRO facilities integrate foam-water sprinklers for aircraft fuel load protection under FAA and EASA certification requirements.
Oil and gas commands premium system margins; pharmaceutical end-use is expanding fastest on facility investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing clusters in Germany and China supply sprinkler components to retrofit markets across Southeast Asia and the Middle East, while the United States remains a net importer of specialized pre-action systems for data center construction.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives pre-action system imports from European suppliers. NFPA 13 2022 edition mandates accelerate warehouse retrofit cycles across legacy distribution corridors. Ashburn and Phoenix anchor domestic demand concentration for nitrogen-charged supervisory piping.
Germany
Automotive stamping plants in Bavaria and chemical complexes along the Rhine specify engineered deluge systems under EN 12845 certification tiers. The country's national construction products regulator enforces REACH-compliant zinc-nickel coating transitions. Stuttgart and Ludwigshafen concentrate premium system procurement.
China
Industrial zone expansion in Jiangsu and Guangdong provinces generates replacement demand for corroded wet-pipe infrastructure. The Ministry of Emergency Management enforces GB 50084 compliance audits across legacy manufacturing clusters. Suzhou and Shenzhen anchor domestic production capacity for copper-alloy fittings.
India
PLI-linked specialty steel and precision component factories in Gujarat and Maharashtra create localized supply chain advantages for sprinkler assembly operations. The Bureau of Indian Standards elevates product testing protocols for imported systems. Ahmedabad and Pune concentrate greenfield installation demand.
Singapore
Marine and offshore engineering hubs specify corrosion-resistant configurations for East Asian wind platform protection. The country's national workplace safety regulator mandates performance-based designs for petrochemical facilities on Jurong Island. The port city anchors regional distribution for deluge system components.
Global Industrial Fire Sprinklers Market Competitive Environment
Listed leaders compete with private specialists across certification tiers, creating a bifurcated structure where building-systems integrators face off against component-focused fabricators. Publicly traded conglomerates leverage balance sheet capacity to bundle fire protection with HVAC and detection electronics. Private specialists anchor positions through marine, offshore, and engineered deluge expertise. Dominant competitive moves include M&A-driven portfolio diversification and strategic partnerships for smart-sensor integration.
Within the building-systems integration tier, Johnson Controls International and Honeywell International exemplify scale-driven bundling strategies. Viking Group Inc. occupies a specialist position in marine and offshore configurations, while Minimax GmbH & Co. KG anchors the engineered deluge segment for automotive and chemical applications. Siemens AG and Robert Bosch GmbH represent diversified industrial conglomerates with fire protection divisions.
| Leading Market Players |
|---|
| Johnson Controls International |
| Honeywell International |
| Viking Group Inc. |
| Minimax GmbH & Co. KG |
| Robert Bosch GmbH |
| Siemens AG |
| Reliable Automatic Sprinkler Co., Inc. |
| API Group Inc. |
| Hochiki Corporation |
| Others |
Value Chain & Pricing Dynamics
Forty-five-day inventory cycles for copper-alloy fittings concentrate pricing power with German and Chinese mill suppliers, compressing margin flexibility for mid-tier sprinkler assemblers while amplifying procurement leverage for building-systems integrators with material-hedging programs.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium UL-FM certified, standard EN 12845-compliant, and economy-grade domestic tiers. Price differentiation rests on certification level and after-sales service bundling, with UL-FM dual-certified products commanding substantial premiums over single-standard alternatives. Cost compression in the economy tier intensifies as Chinese manufacturers expand GB 50084-certified export capacity. Data center operators show least price sensitivity due to business interruption exposure, while warehouse retrofit contractors face acute margin pressure on competitive bids.
Supply Chain Analysis
China and Germany anchor global production of copper-alloy castings and precision-machined sprinkler bodies, with India emerging as a secondary assembly hub under PLI-linked component schemes. Raw material dependencies draw from Chilean copper concentrate, Peruvian brass alloys, and specialty steel from Japanese and South Korean mills. Single-source vulnerability concentrates in precision glass-bulb manufacturing, where European thermal-element specialists control calibration equipment. Distribution runs through certified contractor networks with NICET technician requirements limiting channel expansion velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart-sensor convergence with conventional sprinkler infrastructure is reshaping competitive positioning, as NFPA 13 and EN 12845 standards accelerate specification migration toward predictive maintenance-enabled systems.
For Market Incumbents: Fortify certification portfolios through accelerated FM Global and UL dual-listing investments to defend against low-cost Chinese entrants in the data center segment. Deepen backward integration into copper-alloy casting capacity in Jiangsu province to offset input volatility and secure supply continuity for pre-action system contracts. For New Entrants and Emerging Players: Fast-track GB 50084-to-EN 12845 certification alignment to penetrate European retrofit markets where legacy system replacement demand outpaces incumbent service capacity. Target India's pharmaceutical manufacturing corridor with stainless steel pre-action configurations, leveraging localized assembly partnerships to bypass import duty exposure on finished systems. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming fire protection divisions lacking smart-sensor integration roadmaps. Long-term viability favors specialists with marine-offshore deluge expertise and predictive maintenance contract revenue streams. Monitor GB 50084 enforcement intensity across Guangdong legacy clusters as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Sensor Integration | Enables predictive maintenance contracts with data center operators under NFPA 13 standards. |
| Backward Integration into Casting | Secures copper-alloy supply continuity against Chilean mining output volatility. |
| Dual Certification Fast-Track | Accelerates market access across UL-FM and EN 12845 specification tiers simultaneously. |
| Marine-Offshore Deluge Expansion | Captures pre-codification margins in North Sea and East Asian wind platform protection. |
| India PLI-Linked Assembly | Localizes production for pharmaceutical and automotive end-use under BIS testing protocols. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, engaging fire protection engineering consultants, NICET-certified installation contractors, plant engineers at automotive and pharmaceutical facilities, and procurement leads at hyperscale data center operators. Secondary validation drew from NFPA 13 and EN 12845 standard documentation, FM Global data sheets, GB 50084 regulatory filings with China's Ministry of Emergency Management, and customs trade records for copper-alloy fitting imports. Bottom-up shipment data triangulated against top-down facility construction permits across Northern Virginia, Frankfurt, and Singapore data center clusters.
Across the analysis window, volume and value outputs reflect segmentation modeling across product type, application, installation category, and end-use vertical with regional regulatory cluster overlays. CAGRs were derived from regression analysis of historical installation data against projected facility square footage and code enforcement intensity. Industry-specific forecast inputs incorporated lithium-ion battery protection requirements in data center specifications and REACH-compliant coating transition timelines for European manufacturers.
The analysis sits within stated boundaries; outcomes outside continued NFPA 13 and EN 12845 standard convergence, sustained copper price bands, and NICET technician training pipeline expansion would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement velocity and smart-sensor adoption curves in retrofit applications. Recalibration cycles align with material shifts in GB 50084 audit intensity, copper alloy price volatility, and pre-action system specification share in hyperscale construction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
Portable Rolling Toolbox Market
Construction and Engineering
Industrial Ventilation Equipment Market
Construction and Engineering
Global Anchors and Grouts Market
Construction and Engineering
Global Airport Snow Removal Vehicles and Equipment Market
Construction and Engineering
Hybrid Air Conditioner Market
Construction and Engineering
GCC Faucet Market
Construction and Engineering
Construction and Mining Equipment Market
Construction and Engineering
Garage Equipment Market
Construction and Engineering
Cutting Equipment, Accessories and Consumables Market
Construction and Engineering
PVC Window Market
Construction and Engineering
Plaster Accelerator Market
Construction and Engineering
Submersible Dredge Pump Market
Construction and Engineering
Warm Air Heater Market
Construction and Engineering
Mechanical Hand Tools Market
Construction and Engineering
Vietnam Ceramic Tiles Market
Construction and Engineering
Cable Winches Market