
 Olivine Sand Market | 2026-2036
Olivine Sand Market Size, Share, and Industry Trends Forecast 2026-2036
Olivine Sand Market Insights
Market Context
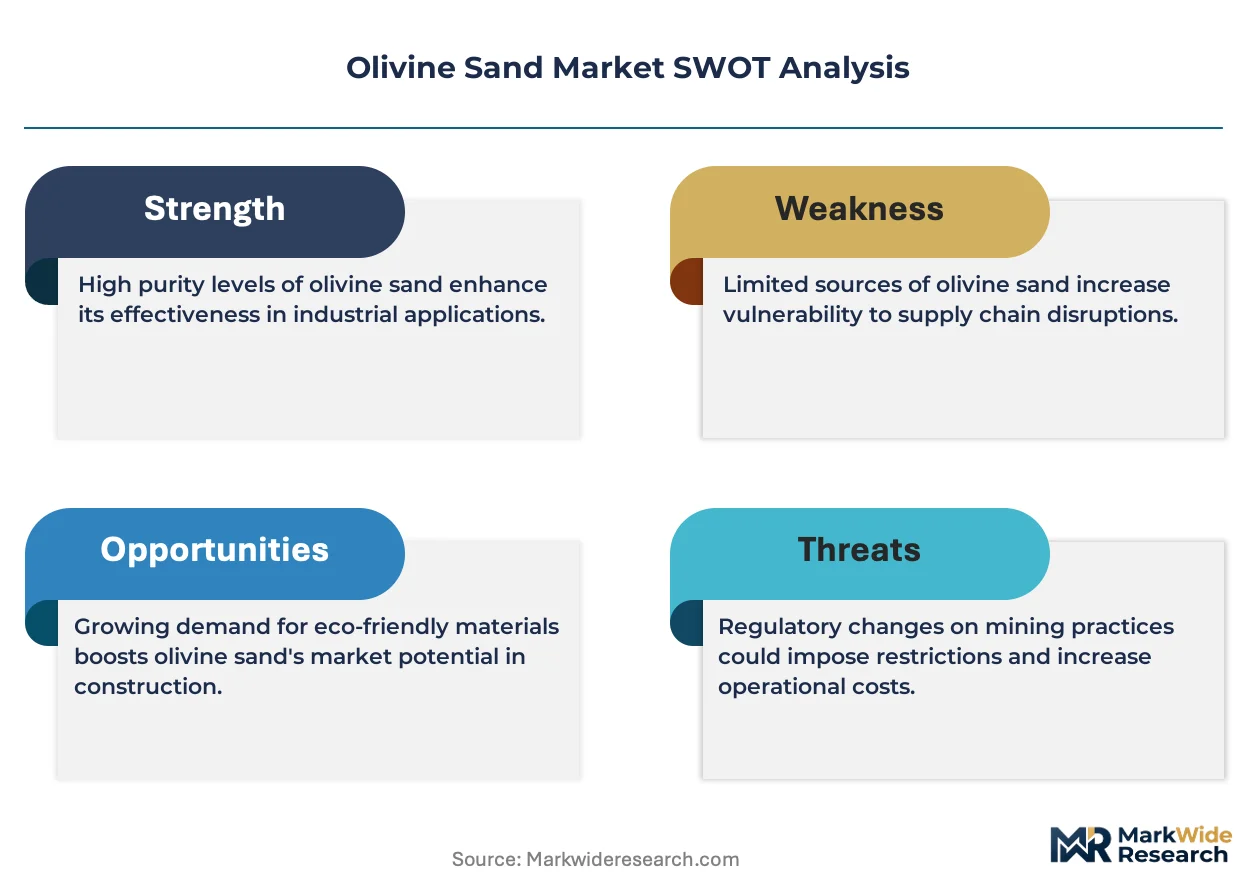
Silica sand displacement in ferrous foundries is realigning olivine sand economics toward premium-grade positioning. Sibelco leverages its Nordic deposit access to sustain supply continuity for European steel casters. Covia anchors North American distribution through vertically integrated mining and processing infrastructure. Steinsvik Olivin dominates Scandinavian technical-grade output with specialized flotation beneficiation.
Technical Definition and Segment Structure
Olivine sand comprises magnesium iron silicate grains with a Mohs hardness of 6.5–7.0 and a melting point near 1760°C, serving primarily as a non-silica molding aggregate and slag-conditioning flux in high-temperature metallurgical processes. The foundry end-use segment leads volume absorption due to olivine's thermal shock resistance and lower free-silica content relative to quartz sands. Premium-grade forsterite commands concentrated margin pools from aerospace and specialty alloy foundries requiring tight chemical specifications. Direct sales channels control bulk procurement relationships with integrated steel producers, while distributor networks fragment access for smaller abrasives and glass-manufacturing buyers.
Regulatory Frame and Outlook
OSHA respirable crystalline silica standards and REACH registration requirements are accelerating substitution audits at US and EU foundries, tightening product certification and traceability obligations. India's BIS quality marks and China's GB standards for refractory raw materials shape import acceptance criteria and domestic production compliance. Stakeholders must monitor evolving occupational exposure limits and carbon-border adjustment mechanisms that could restructure competitive access for mined versus synthetic refractory minerals.
Market Dynamics
Silica sand displacement in ferrous foundries is compressing procurement timelines and forcing specification upgrades across the olivine sand supply base. REACH registration deadlines and OSHA respirable crystalline silica enforcement are accelerating substitution audits at foundries in Europe and North America.
Growth Catalysts
- REACH silica restrictions:European foundries face mandatory substitution timelines for quartz-based molding aggregates, redirecting procurement toward olivine-based refractory materials with lower free-silica content.
- India's steel foundry expansion:Domestic steel production targets under the PLI scheme are expanding mold and core production capacity, concentrating demand absorption in Gujarat and Maharashtra clusters.
- Thermal shock resistance specification:Aerospace and specialty alloy foundries are tightening chemical purity requirements for forsterite grades, creating premium-grade margin pools distinct from standard foundry supply.
Market Restraints
- Nordic supply concentration:High-purity olivine deposits concentrate in Norway and Finland, exposing procurement continuity risks from single-source geological dependency.
- Energy input volatility:Beneficiation and calcination processes face electricity and natural gas cost swings that compress processing margins during price spikes.
- Synthetic forsterite substitution:Laboratory-synthesized magnesium silicate alternatives threaten premium-grade positioning in aerospace applications requiring ultra-high purity.
Strategic Opportunities
- Carbon-border adjustment positioning:EU CBAM implementation favors low-carbon-intensity mined minerals over synthetic alternatives, creating tariff advantages for Nordic-sourced olivine.
- Slag-conditioning flux expansion:Electric arc furnace operators in Turkey and Egypt are testing olivine-based flux packages as magnesium oxide sources for stainless steel refining.
- Direct-to-mill procurement platforms:Integrated steel producers are bypassing distributor networks for bulk refractory raw material sourcing, compressing channel margins and capturing traceability data.
Industry Challenges
- Flotation beneficiation expertise scarcity:Technical-grade olivine production requires specialized mineral processing engineers familiar with Nordic deposit mineralogy, constraining capacity expansion.
- Multi-jurisdiction certification timelines:Foundry sand suppliers must secure concurrent BIS marks for India, GB standard compliance for China, and REACH registration for Europe, extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Olivine Sand Market |
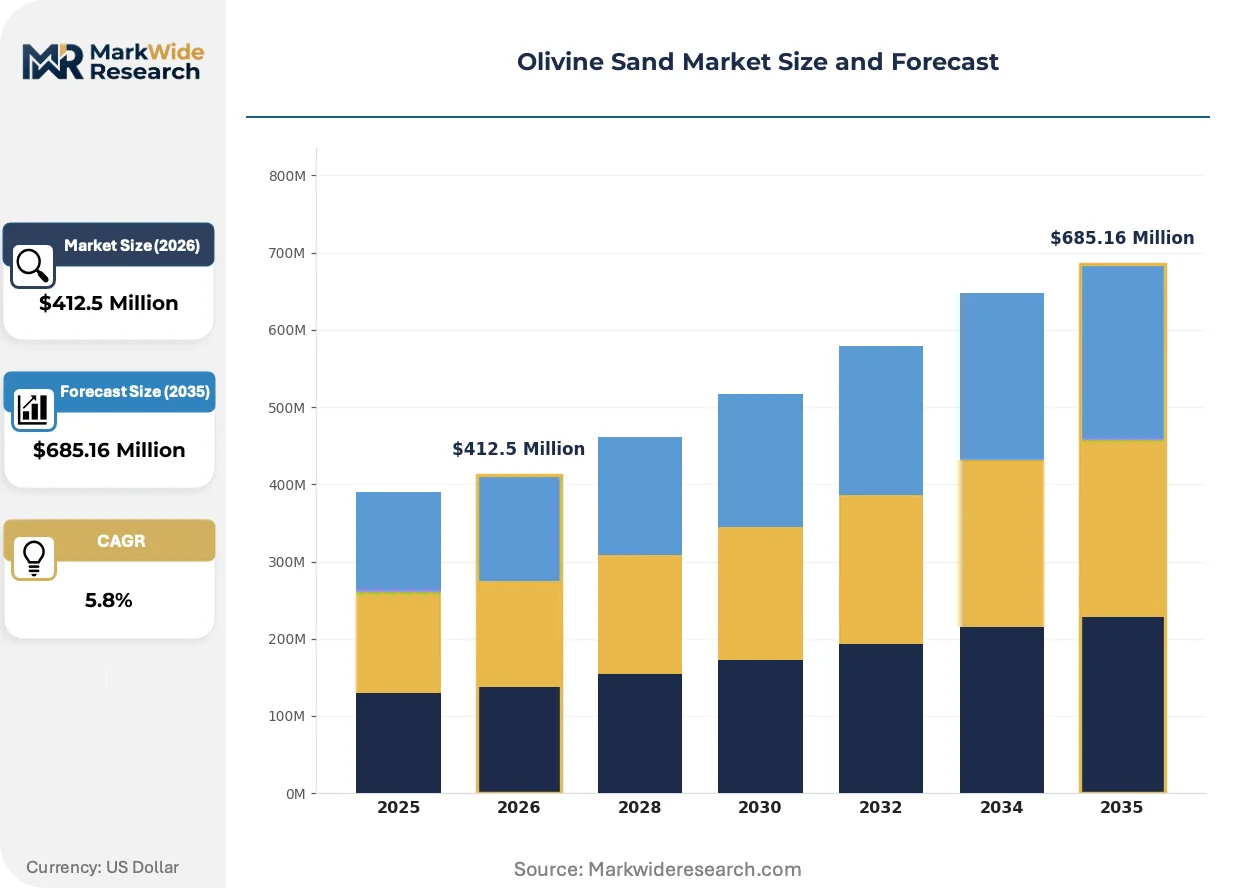
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnesite, Forsterite, Fayalite, Olivine End Use Industry: Foundry, Metallurgy, Glass Manufacturing, Abrasives Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers Grade: Industrial, Technical, Chemical, Premium |
| Companies Covered | Covia (Unimin), Yucheng Refractory Products, Sibelco, Ore-Met, Thermolith SA (Vitruvit), Steinsvik Olivin, Olivine India Group, Dakduklu Minerals, Eryas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Olivine Sand Market Trends and Innovations
Process intensification in foundry operations is compressing mold-making cycles and demanding refractory aggregates with faster heat-transfer characteristics. Specification convergence across automotive, aerospace, and energy sector casting is narrowing acceptable chemical variance bands.
High-purity forsterite sand is absorbing specification pressure from aerospace alloy foundries requiring tight magnesium-to-iron ratios. Tier-one automotive casters in Germany and Japan are adopting these grades for turbocharger housing production. The technology is absorbing margin compression in standard foundry grades by concentrating value capture in certified premium tiers.
OSHA's updated respirable crystalline silica permissible exposure limits are triggering foundry-wide substitution audits across the US Midwest casting belt. Enforcement inspections have accelerated in Wisconsin and Ohio since the standard's implementation. Smaller job shops face disproportionate compliance costs, consolidating procurement toward suppliers with pre-certified low-silica alternatives.
Buyer concentration among integrated steel producers is compressing distributor relevance in bulk refractory procurement. Direct mill relationships now govern annual contract negotiations for olivine sand volumes exceeding ten thousand tonnes. This pattern is most visible in China's eastern coastal manufacturing belt, where Baowu and Shagang Group have consolidated supplier panels.
Olivine Sand Market Segmentation
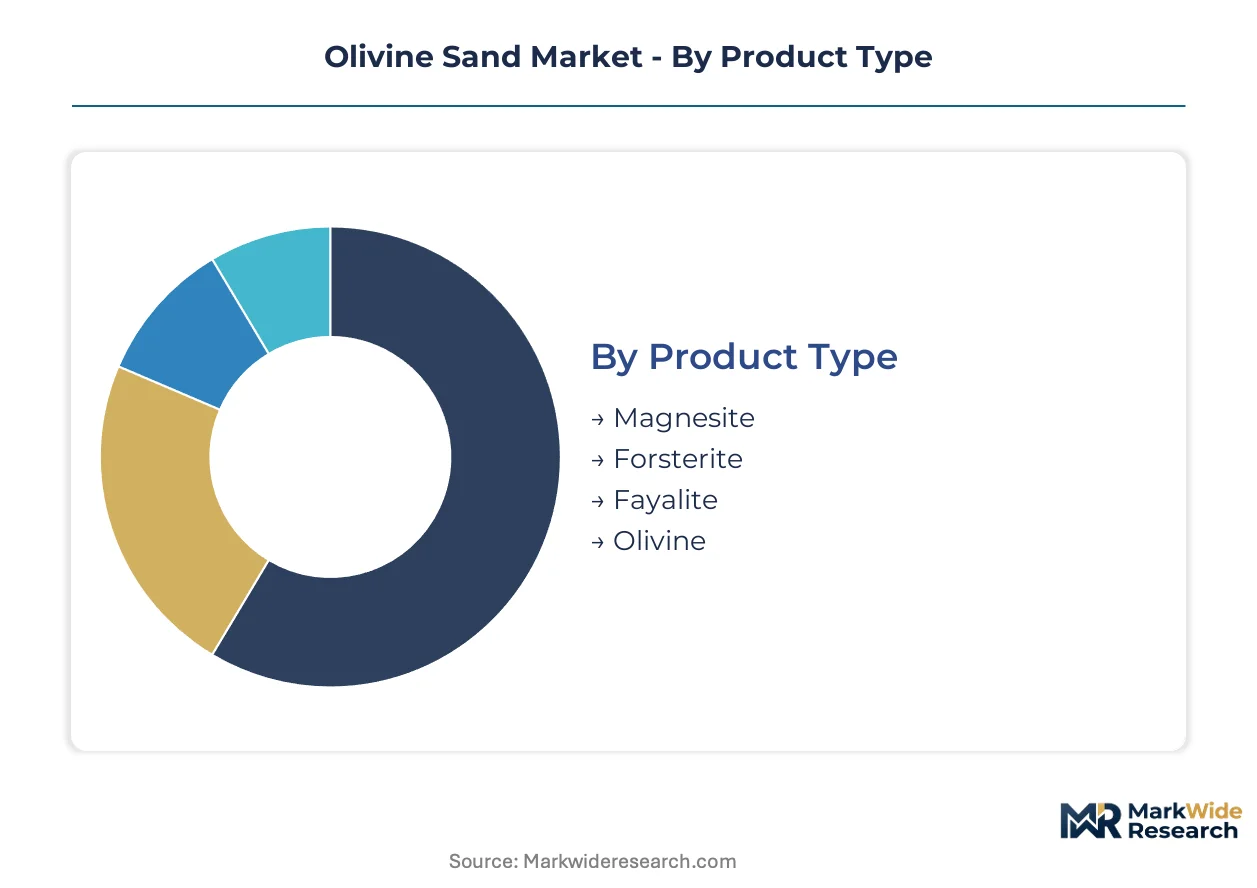
Olivine sand procurement patterns fragment across chemical composition, end-use thermal requirements, and certification tiers. Supply chain configuration varies dramatically by segment, with direct mill relationships governing bulk volumes while distributor networks handle fragmented specialty demand.
Product Type:
Deposit mineralogy concentrates supply economics around magnesium-to-iron ratios that determine refractory performance and pricing tiers.
- Forsterite:Magnesium-dominant silicate with near-zero iron content delivers the highest fusion point and thermal shock resistance. Aerospace foundries in Germany and Japan specify tight MgO/FeO ratios for turbocharger housings and turbine components, absorbing premium-grade output from Nordic flotation beneficiation circuits.
- Fayalite:Iron-rich olivine variant serves lower-temperature applications where cost sensitivity outweighs thermal performance. Glass manufacturers in China's Shandong province source fayalite for furnace refractory linings, trading purity for volume scale in non-critical heat zones.
- Magnesite:Carbonate-derived magnesium oxide precursor competes with olivine in slag-conditioning applications. Turkish EAF operators trial magnesite-olivine blends for stainless steel refining flux packages.
- Olivine:Generic mineral sand designation covers mixed-composition deposits used in standard foundry molding. Indian steel foundries in Gujarat clusters source bulk olivine for core production under PLI scheme expansion.
Forsterite absorbs the bulk of installed beneficiation capacity; fayalite is expanding most quickly in glass manufacturing feedstock substitution.
End Use Industry:
Application thermal regimes and silica exposure regulations reshape demand concentration across metal casting and materials processing sectors.
- Foundry:Mold and core production for ferrous casting dominates volume absorption, driven by OSHA silica substitution mandates and REACH registration deadlines. US Midwest job shops consolidate procurement toward pre-certified low-silica alternatives.
- Metallurgy:Slag-conditioning flux in electric arc and basic oxygen furnaces demands consistent MgO content for sulfur control. Turkish and Egyptian EAF operators test olivine-based flux packages as magnesium oxide sources.
- Glass Manufacturing:Furnace refractory linings and batch formulations utilize iron-tolerant olivine grades. Shandong province float glass producers absorb regional fayalite supply.
- Abrasives:Precision grinding and blasting media require controlled grain morphology and hardness. Scandinavian technical-grade output serves specialized surface preparation contractors.
Foundry applications command the dominant share of specification-grade supply; metallurgy is climbing the fastest on EAF route expansion.
Distribution Channel:
Customer scale and procurement sophistication determine channel economics, with integrated producers bypassing intermediaries for bulk refractory sourcing.
- Direct Sales:Annual contracts governing volumes above ten thousand tonnes link Nordic miners to integrated steel producers. Baowu and Shagang Group panels in China's eastern coastal belt exemplify this pattern.
- Distributors:Fragmented access for smaller foundries, abrasives contractors, and glass manufacturers. Regional stockists manage certification documentation and just-in-time delivery.
- Online Sales:Digital procurement platforms emerging for standardized technical grades with published specifications. Limited penetration in premium forsterite due to traceability requirements.
- Retailers:Minimal relevance in bulk refractory minerals; confined to packaged abrasives for maintenance and repair operations.
Direct sales capture the majority of value flow; distributor relevance is compressing fastest as mill procurement centralizes.
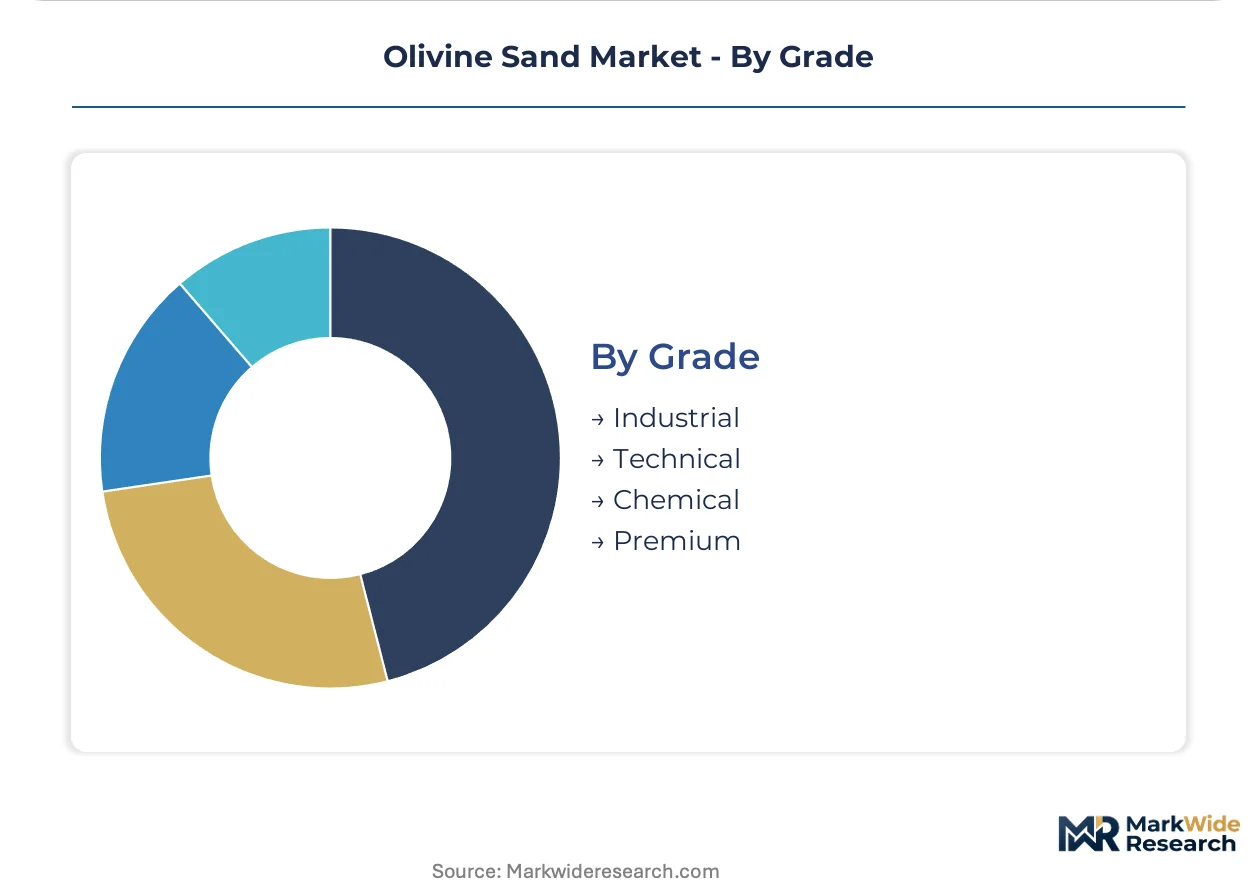
Grade:
Certification intensity and chemical variance bands stratify pricing power across standard industrial supply and premium technical tiers.
- Premium:Tight magnesium-to-iron ratios with full REACH registration and aerospace alloy foundry certification. Tier-one automotive casters in Germany adopt these grades for turbocharger housing production.
- Technical:Controlled chemistry for specialty alloy and precision casting applications. Steinsvik Olivin's flotation beneficiation output dominates Scandinavian supply.
- Industrial:Standard foundry molding with BIS mark compliance for Indian import acceptance. Gujarat and Maharashtra clusters absorb bulk volumes.
- Chemical:Reagent-grade purity for laboratory and specialized flux applications. Limited volume, high margin segment with synthetic forsterite competition.
Industrial grade moves the largest physical tonnage; premium grade is gaining share fastest on aerospace specification tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel foundry expansion and silica substitution mandates are concentrating procurement activity across five distinct national markets. Each geography presents unique regulatory pressures and industrial clustering patterns that reshape competitive access for olivine sand suppliers.
China
Baowu and Shagang Group consolidate annual contract negotiations for volumes exceeding ten thousand tonnes. GB standards for refractory raw materials shape import acceptance criteria and domestic production compliance. The eastern coastal manufacturing belt around Shanghai absorbs premium-grade forsterite for integrated steelworks.
India
Domestic steel production targets under the PLI scheme expand mold and core production capacity. BIS quality marks govern import acceptance for foundry sand suppliers entering the market. Gujarat and Maharashtra clusters concentrate demand absorption from expanding steel foundries.
United States
OSHA respirable crystalline silica enforcement triggers foundry-wide substitution audits across the Midwest casting belt. Updated permissible exposure limits accelerate procurement toward pre-certified low-silica alternatives. Wisconsin and Ohio job shops consolidate sourcing as enforcement inspections intensify.
Germany
Tier-one automotive casters specify tight magnesium-to-iron ratios for turbocharger housing production. REACH registration deadlines redirect procurement toward olivine-based refractory materials with documented traceability. Aerospace alloy foundries in southern industrial zones absorb certified premium-grade output.
Turkey
Electric arc furnace operators test olivine-based flux packages as magnesium oxide sources for stainless steel refining. The country's national metallurgical standards shape acceptance criteria for slag-conditioning materials. EAF route expansion in coastal industrial zones drives metallurgical-grade demand growth.
Olivine Sand Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with deposit access determining upstream positioning. Nordic miners control high-purity forsterite supply through geological concentration in Norway and Finland. Three archetypes dominate: vertically integrated deposit owners, regional beneficiation specialists, and distributor-anchored trading houses. Competitive moves concentrate on backward integration into mining assets and direct-to-mill procurement platform development.
Among Nordic deposit-based operators, Sibelco and Steinsvik Olivin exemplify the vertically integrated archetype, leveraging geological concentration to sustain supply continuity for European steel casters. Covia anchors North American distribution infrastructure. These three occupy positions that reflect the structural divide between geological endowment and market access capabilities.
| Leading Market Players |
|---|
| Covia (Unimin) |
| Yucheng Refractory Products |
| Sibelco |
| Ore-Met |
| Thermolith SA (Vitruvit) |
| Steinsvik Olivin |
| Olivine India Group |
| Dakduklu Minerals |
| Eryas |
| Others |
Pricing and Supply Chain Analysis
Magnesium oxide spot indices from Rotterdam chemical terminals cascade through Nordic beneficiation circuits into three-tier pricing structures across premium forsterite, technical-grade flotation output, and industrial foundry supply. Steel foundries in India and glass manufacturers in China's Shandong province absorb divergent cost pass-through rates based on volume scale and certification requirements.
Pricing Analysis
Volume-heavy industrial grades trade on thin margins while premium forsterite captures disproportionate value from aerospace certification requirements. Pricing stratifies across premium, standard, and economy tiers driven by magnesium-to-iron ratio precision and REACH registration status. Cost compression in standard foundry supply is intensifying because energy input volatility at Norwegian calcination facilities feeds into contract renegotiations. Small Midwest job shops exhibit acute price sensitivity; integrated steel producers with direct mill contracts show inelastic demand for certified low-silica alternatives.
Supply Chain Analysis
Direct-to-mill channels handle hyperscale procurement from Baowu and Shagang Group, while distributor networks fragment access for smaller abrasives contractors and glass manufacturers. Geographic supply concentrates in Norway, Finland, and India's Gujarat belt, with Nordic deposits feeding European and East Asian demand. Raw material dependencies center on electricity for flotation beneficiation, natural gas for calcination, and specialized reagents for iron separation. Single-source geological vulnerability in Scandinavia exposes continuity risks from weather disruptions or labor actions. Distribution runs through annual contract frameworks for bulk volumes and regional stockists for fragmented specialty demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deposit access and beneficiation expertise have become the decisive levers in a vertical-integration race, with backward control over Nordic mining assets separating price-setters from margin-takers.
For Market Incumbents: Anchor supply continuity through captive control of Norwegian and Finnish olivine deposits against synthetic forsterite substitution threats. Expand flotation beneficiation capacity to capture specification tightening in aerospace alloy foundries. Secure multi-jurisdiction certification pipelines to compress product launch cycles for Indian BIS marks and Chinese GB standards.
For New Entrants and Emerging Players: OSHA respirable crystalline silica enforcement in the United States opens a window for pre-certified low-silica alternative suppliers to capture consolidating Midwest job shop demand. Target slag-conditioning flux applications in Turkish and Egyptian electric arc furnace operations as the most penetrable metallurgical segment. Pursue direct-to-mill procurement platform partnerships with integrated steel producers to bypass compressed distributor margins.
For Investors and Strategic Acquirers: The window for entry favors Nordic deposit owners with existing flotation infrastructure and REACH registration assets. Acquisition targets should display proven beneficiation expertise and established direct sales relationships with tier-one automotive casters. Watch carbon-border adjustment mechanism implementation timing as the inflection indicator for competitive positioning between mined and synthetic refractory minerals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mining Assets | Captive olivine deposit control in Norway secures supply continuity for European steel casters facing REACH deadlines. |
| Flotation Beneficiation Capacity Expansion | Technical-grade output expansion captures aerospace specification tightening from German turbocharger housing producers. |
| Multi-Jurisdiction Certification Investment | Concurrent BIS, GB, and REACH compliance compresses product launch cycles for cross-border foundry sand supply. |
| Direct-to-Mill Procurement Platform Development | Bypassing distributor networks captures traceability data and annual contract value from Chinese integrated steel producers. |
| Slag-Conditioning Flux Package Formulation | Olivine-based magnesium oxide sourcing for Turkish EAF operators opens metallurgical-grade demand expansion. |
Research Methodology
Independent corroboration across foundry operations managers, refractory procurement leads at integrated steel producers, Nordic mining asset directors, and distributor network heads underwrites the qualitative findings. Secondary validation draws from customs trade data, SEC filings of listed mineral processors, REACH registration databases, and BIS certification records. Bottom-up volume modeling from individual beneficiation facilities triangulates against top-down demand absorption estimates from steel foundry capacity expansion announcements.
Historical reference periods spanning pre-pandemic baseline, silica substitution acceleration, and energy price volatility phases anchor the forecast window across the projection horizon. Segmentation dimensions modeled include product type mineralogy, end-use thermal regime, distribution channel structure, and grade certification intensity. CAGRs derive from installed capacity trajectories, substitution audit timelines, and regulatory enforcement intensity curves. Industry-specific inputs incorporate electric arc furnace route expansion rates and aerospace alloy foundry specification tightening patterns.
Caveats apply where carbon-border adjustment mechanism implementation timing, synthetic forsterite laboratory scale-up, or Nordic labor action disruptions could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Oman Industrial Salts Market
Industrial Minerals
Middle East Feed Minerals Market
Industrial Minerals
Mediterranean Sea Salt Micro-Mineral Complexes Market
Industrial Minerals
Global Feed Minerals Market
Industrial Minerals
Unexpanded Perlite Market
Industrial Minerals
Global Cristobalite Market
Industrial Minerals
Anhydrite Market
Industrial Minerals
Limestone Market
Industrial Minerals
Dolomite Powder Market
Industrial Minerals
Bentonite Market
Industrial Minerals
Strategic Mineral Materials Market
Industrial Minerals
Dolomite Mining Market
Industrial Minerals
Feldspathic Minerals Market
Industrial Minerals
Mineral Wool Material Market
Industrial Minerals
Potash Ores Market
Industrial Minerals
Solar Salt Market