
 Mineral Enrichment Ingredients Market | 2026-2036
Mineral Enrichment Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Mineral Enrichment Ingredients Market Foresight
Pharmaceutical-grade mineral specifications is redrawing competitive boundaries in mineral enrichment ingredients. Balchem Corporation leverages its encapsulated mineral technology to command premium positioning in dietary supplement channels. Cargill, Incorporated anchors its mineral salt portfolio through backward integration into bulk commodity sourcing. Kemin Industries specializes in chelated mineral complexes for high-bioavailability animal nutrition applications.
Mineral enrichment ingredients comprise inorganic and organic mineral compounds—typically iron, zinc, calcium, magnesium, and selenium salts at purity grades exceeding 99.5%—formulated for incorporation into food matrices, feed rations, and supplement tablets to address micronutrient deficiencies. Chelated minerals and mineral blends capture expanding margin pools as bioavailability claims differentiate finished products in nutraceutical channels. Powder and liquid forms dominate food and beverage processing lines, while tablet formats sustain pharmacy and health store distribution through dose-standardization requirements.
The FDA's Current Good Manufacturing Practice regulations for dietary supplements enforce identity testing and contaminant limits on mineral ingredient suppliers entering US commerce. EFSA's health claim authorization process shapes permissible marketing language for mineral-fortified products across European member states. India's FSSAI fortification standards mandate specific mineral levels in staple food categories, creating compliant-supplier bottlenecks. Stakeholders must monitor divergence between regional purity benchmarks and bioavailability certification requirements to avoid reformulation costs at market entry.
Market Dynamics
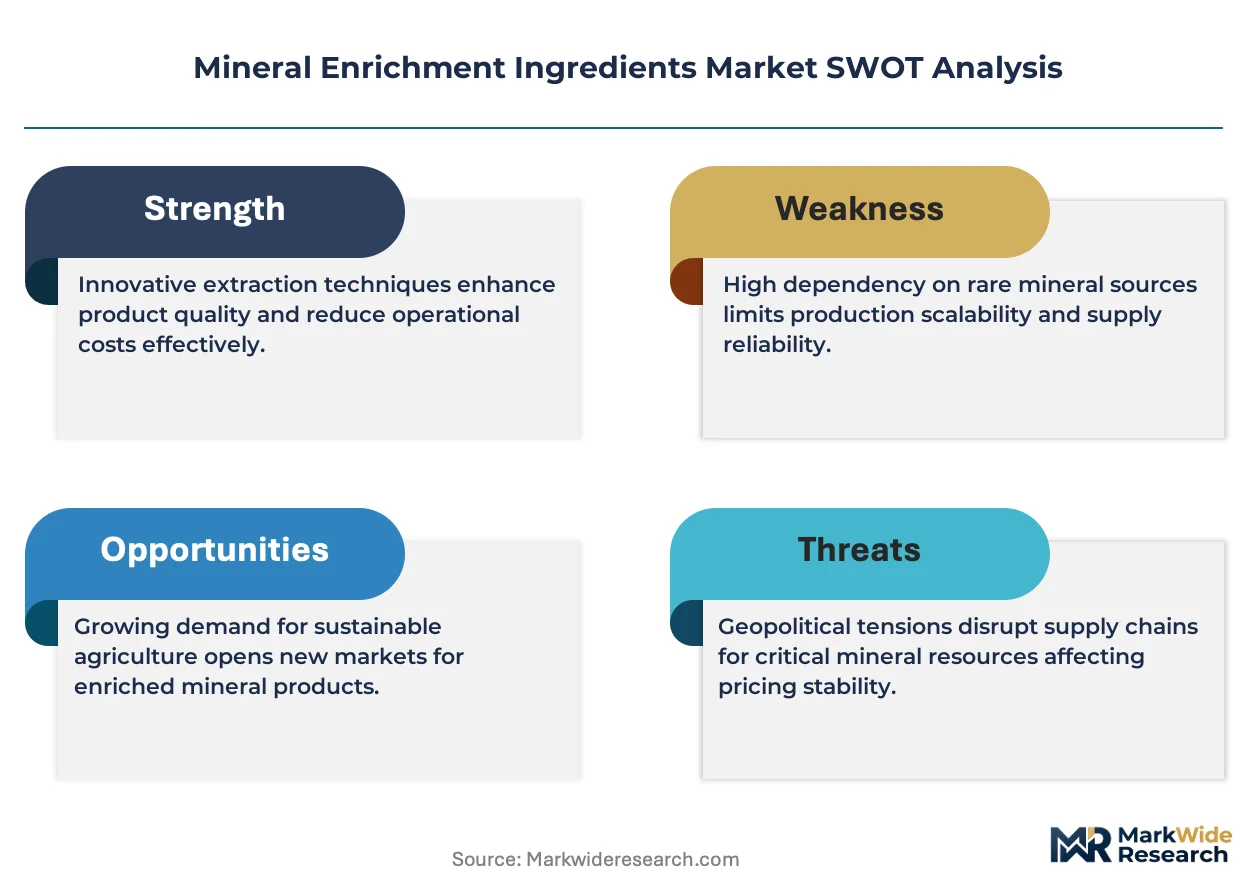
Pharmaceutical-grade purity specifications are compressing supplier margins while simultaneously erecting entry barriers against commodity-grade producers seeking to upgrade into nutraceutical channels.
Growth Catalysts
- EFSA Health Claim Authorization:Permissible marketing language for mineral-fortified products creates premium pricing headroom for compliant European suppliers across dietary supplement channels.
- Chelated Mineral Complexes:Bioavailability differentiation is accelerating uptake in functional beverage manufacturing corridors, particularly among Asia-Pacific formulators targeting absorption-optimized positioning.
- FSSAI Fortification Mandates:India's mandatory mineral levels in staple food categories are generating compliant-supplier bottlenecks that concentrate volume with certified domestic producers.
Market Restraints
- Input Cost Volatility:Bulk commodity sulfuric acid and hydrochloric acid prices oscillate with energy markets, compressing margins on inorganic mineral salt production.
- Supply Concentration Risk:Seaweed-derived iodine and selenium extraction concentrates in Chilean and Japanese coastal processing facilities, creating single-source vulnerability.
- Technical Limitation:Thermal stability thresholds for organic chelates restrict incorporation into ultra-high-temperature processed dairy and beverage matrices.
Strategic Opportunities
- Cell-Cultured Meat Nutrition:Precision fermentation-derived mineral premixes represent an emerging application vector as cultivated protein startups scale manufacturing.
- US FDA CGMP Enforcement Gaps:Identity testing and contaminant limit compliance creates acquisition targets among smaller suppliers lacking in-house analytical capabilities.
- Direct-to-Consumer Subscription Channels:Personalized mineral testing kits paired with bespoke supplement formulations are bypassing traditional pharmacy distribution in North American and European urban markets.
Industry Challenges
- Analytical Chemistry Talent Scarcity:ICP-MS and atomic absorption spectroscopy specialists command premium compensation, stretching quality control budgets at mid-tier suppliers.
- Multi-Jurisdiction Certification Timelines:Simultaneous FSSAI, FDA, and EFSA registration processes extend product launch windows by 18-24 months for novel mineral formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mineral Enrichment Ingredients Market |
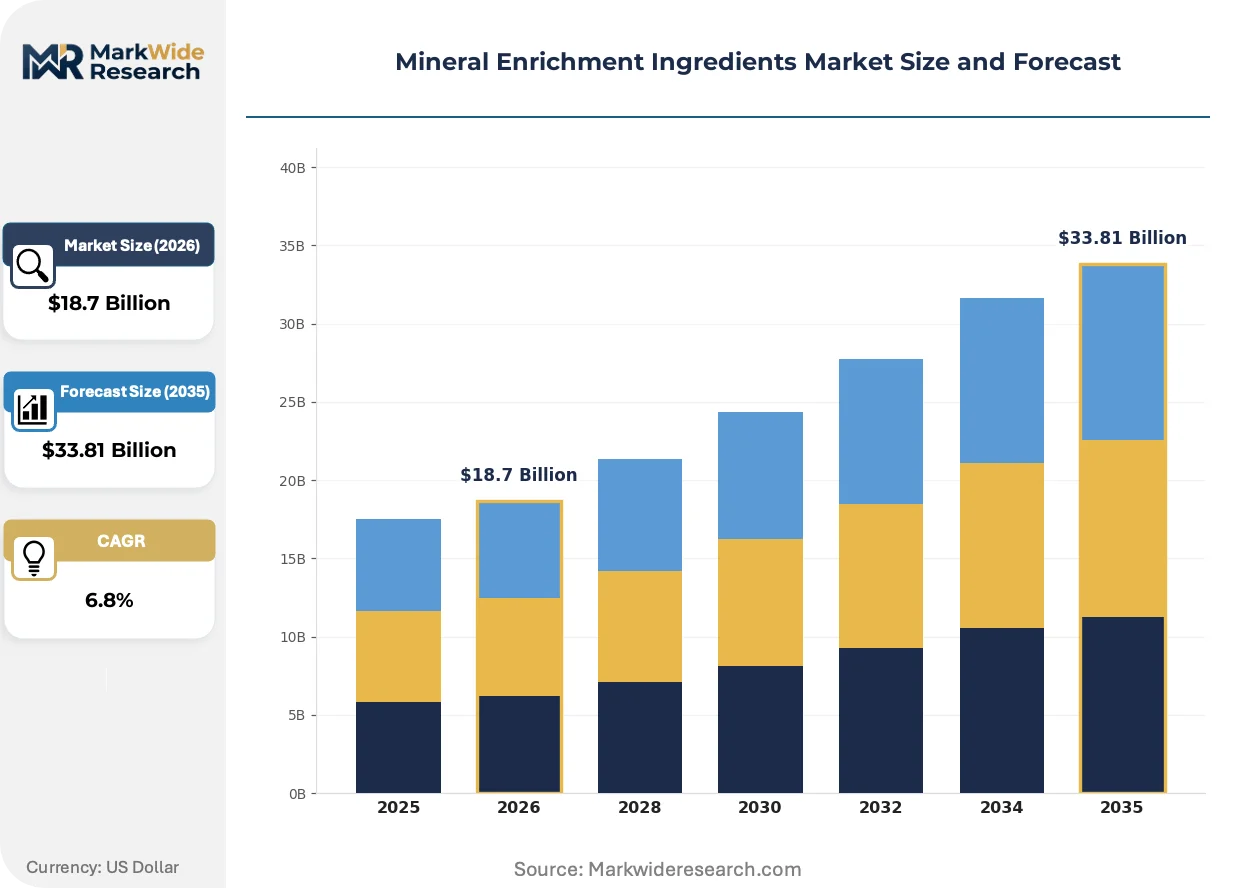
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Salts, Trace Minerals, Chelated Minerals, Mineral Blends Application: Food & Beverages, Nutraceuticals, Animal Feed, Dietary Supplements Form: Powder, Liquid, Granular, Tablets End User: Food Manufacturers, Pharmacies, Health Stores, Online Retailers |
| Companies Covered | Balchem Corporation, Cargill, Incorporated, Nestlé, Barry Callebaut, Kemin Industries, Corbion, ADM WILD Europe, Wilmar International Limited, Clover Hill Food Ingredients Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mineral Enrichment Ingredients Market Shifts & Advancements
Encapsulation technologies and bioavailability verification protocols are fragmenting the supplier base into technology-differentiated tiers while regulatory divergence between major economies complicates standardized product development.
Microencapsulation using lipid-shell and polymer-matrix technologies is bifurcating the ingredient market. Functional beverage manufacturers in South Korea and Australia are adopting these formats for taste-masking and controlled-release applications. The technology is compressing commodity mineral salt margins while enabling 40-60% price premiums for encapsulated grades in pediatric and geriatric supplement lines.
REACH authorization requirements for novel mineral-organic complexes are tightening purity documentation obligations across European manufacturing. ECHA's substance evaluation processes now demand extended toxicity datasets for chelated formats not on the 2013-2018 SVHC candidate list. German and Dutch premix blenders are responding by consolidating supplier relationships with REACH-registered producers possessing existing dossier libraries.
Buyer concentration among contract manufacturers is shortening qualification cycles and compressing switching costs. Large-scale beverage co-packers in Mexico and Thailand now demand 90-day supplier onboarding versus historical 180-day timelines. This pattern is most visible in tropical markets where seasonal demand spikes require rapid formulation pivots between mineral premix suppliers.
Mineral Enrichment Ingredients Market Segmentation
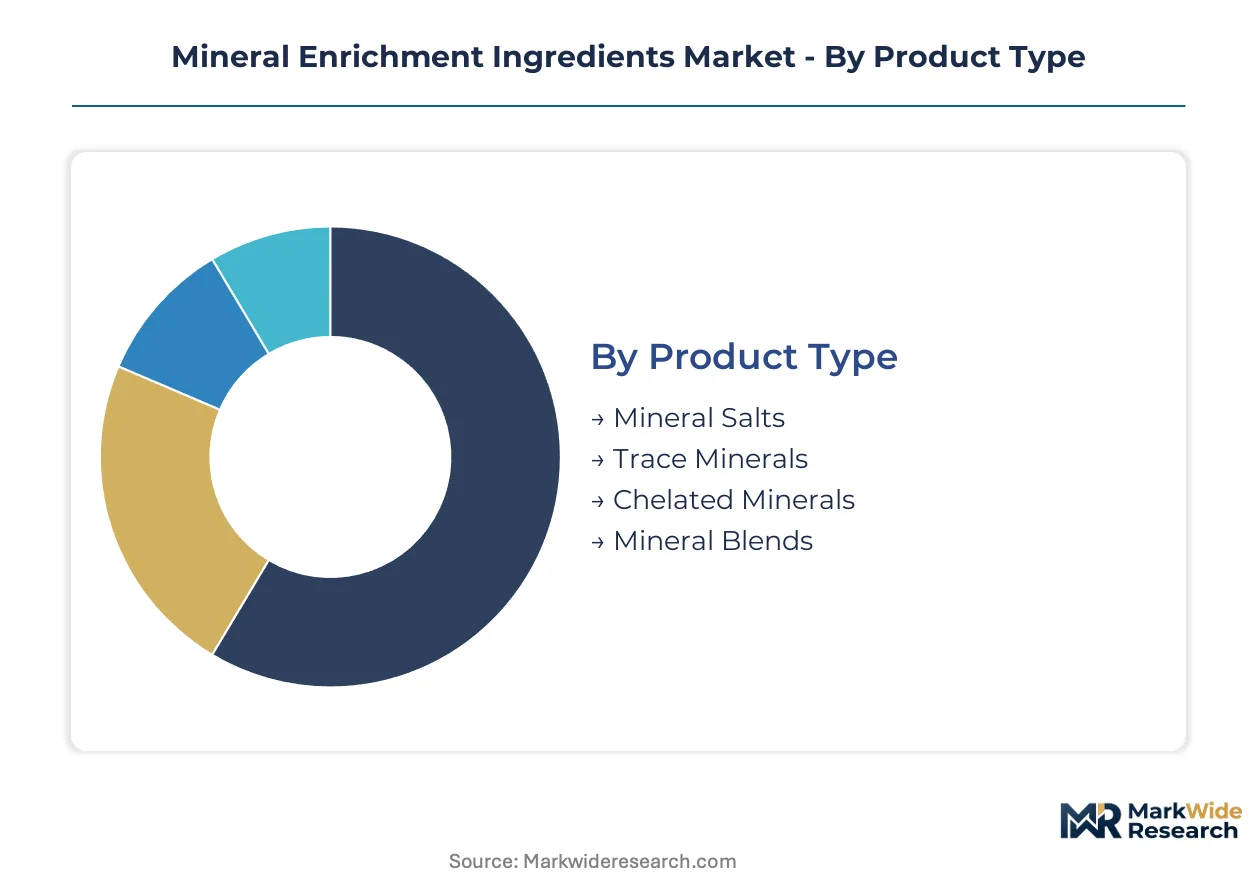
Segmentation in mineral enrichment ingredients reveals how purity grades and delivery formats map to distinct procurement channels. Pharmaceutical-grade specifications command laboratory-verified certification, while food-grade variants flow through commodity ingredient distributors with shorter qualification cycles.
Product Type:
Channel-mix patterns show mineral salts and chelated formats diverging sharply at the procurement stage, with salts flowing through bulk commodity distributors and chelates requiring direct technical sales engagement.
- Mineral Salts:Inorganic compounds—typically iron sulfate, zinc oxide, and calcium carbonate at 99.5%+ purity—serve as the cost-optimized backbone for mass-market food fortification. Demand concentrates in Indian and Chinese processed food manufacturing corridors where FSSAI and SAMR mandates enforce minimum fortification levels in edible oils and wheat flour.
- Chelated Minerals:Organic complexes bound to amino acids or organic acids deliver superior bioavailability for premium nutraceutical positioning. Asia-Pacific functional beverage formulators in South Korea and Thailand are accelerating uptake of glycinate and citrate formats for absorption-optimized marketing claims.
- Trace Minerals:Selenium, iodine, and chromium compounds at ppm-dosage precision address specific deficiency protocols in clinical nutrition.
- Mineral Blends:Pre-formulated premixes reduce compounding complexity for mid-tier supplement manufacturers lacking in-house analytical capabilities.
By volume, Mineral Salts leads. By growth pace, Chelated Minerals is expanding most quickly.
Application:
Cost-tier stratification separates pharmaceutical-grade nutraceutical applications from commodity food fortification, with margin spreads of 3-5x between adjacent tiers.
- Food & Beverages:Mandatory fortification programs in India, Nigeria, and Indonesia drive bulk mineral salt procurement for staple food categories. EFSA and FDA GRAS certifications gate European and North American market entry for novel mineral formats.
- Nutraceuticals:Bioavailability-verified chelates and encapsulated minerals command premium positioning in pharmacy and health store channels. German and Swiss premix blenders demand REACH-registered suppliers with existing toxicity dossiers for novel organic complexes.
- Animal Feed:Precision-formulated trace mineral premixes support livestock productivity optimization in Brazilian and Australian intensive farming operations.
- Dietary Supplements:Tablet and capsule formats sustain dose-standardization requirements through pharmacy distribution networks.
Food & Beverages dominates tonnage. Nutraceuticals shows the steepest margin expansion trajectory.
Form:
Manufacturing process compatibility dictates format selection, with thermal stability thresholds eliminating organic chelates from ultra-high-temperature dairy processing lines.
- Powder:Free-flowing mineral salts and spray-dried chelates integrate into dry-mix beverage and bakery applications. Mexican and Thai contract manufacturers demand 90-day supplier onboarding for powder premixes versus historical 180-day cycles.
- Liquid:Ionic mineral solutions enable homogeneous dispersion in ready-to-drink beverages and liquid dietary supplements.
- Granular:Agglomerated formats reduce dusting and improve handling characteristics for high-volume feed milling operations.
- Tablets:Direct-compression mineral excipients serve pharmacy and health store distribution through dose-standardization requirements.
Powder leads in shipment volume. Liquid formats are gaining share fastest in functional beverage channels.
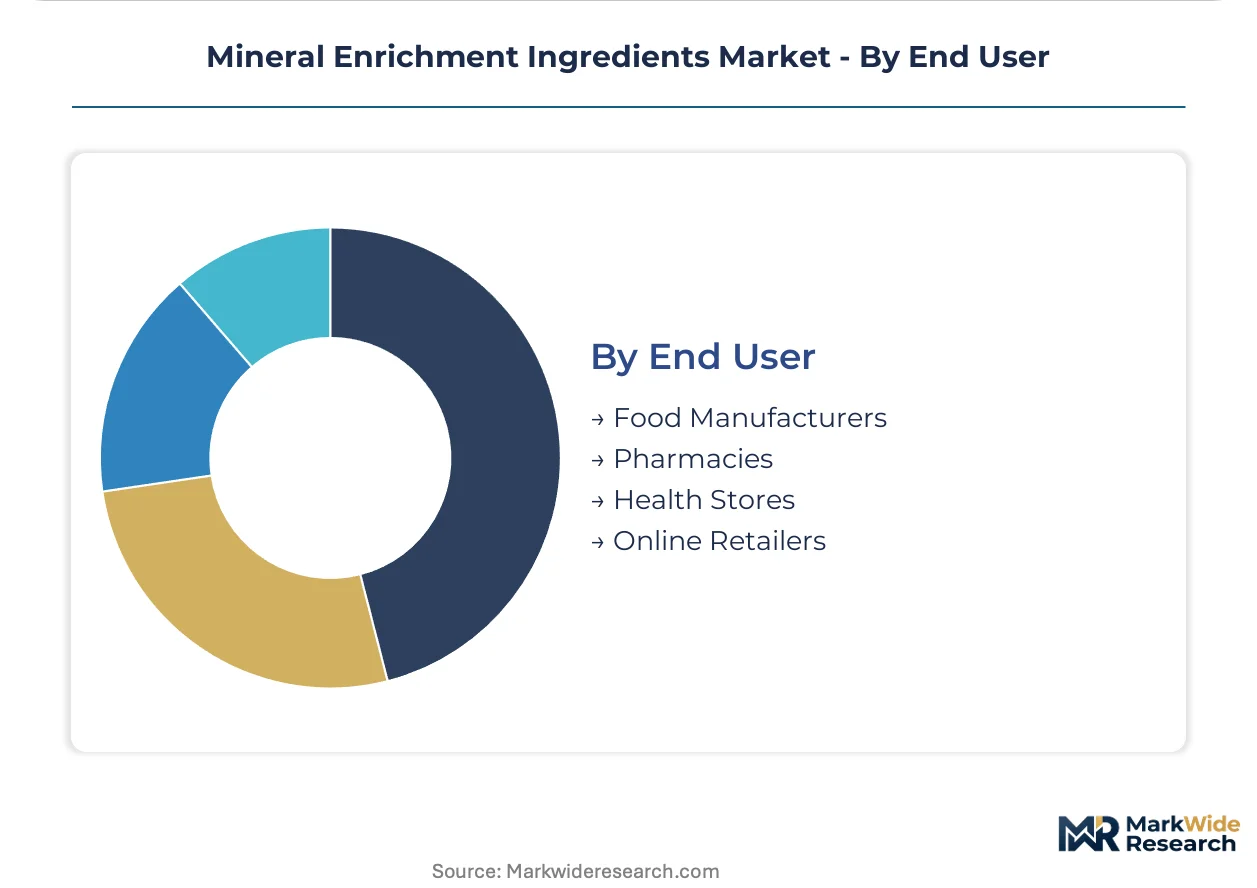
End User:
Customer-type concentration is shortening procurement cycles, with large-scale food manufacturers consolidating supplier relationships while direct-to-consumer channels fragment order patterns.
- Food Manufacturers:Multinational processors in India and Brazil enforce supplier certification against FSSAI and ANVISA fortification mandates. Backward integration into captive mineral premix production is emerging among top-tier cereal and dairy processors.
- Pharmacies:Dose-standardized tablet and capsule formats sustain prescription and OTC mineral supplement distribution.
- Health Stores:Specialty retail channels favor bioavailability-differentiated chelated formats with third-party verification seals.
- Online Retailers:Direct-to-consumer subscription models paired with personalized mineral testing kits are bypassing traditional pharmacy distribution in North American and European urban markets.
Food Manufacturers command the largest order volumes. Online Retailers exhibit the most rapid channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in mineral enrichment ingredients tilt toward net-importing manufacturing economies with limited domestic extraction capacity. Export-oriented producers in mineral-rich jurisdictions supply refined salts and chelated complexes to formulation hubs concentrated in pharmaceutical and nutraceutical manufacturing corridors.
United States
Functional beverage startups in Austin and Boulder are driving demand for bioavailability-verified chelated formats. The FDA's Current Good Manufacturing Practice regulations enforce identity testing and contaminant limits on suppliers entering US commerce. New Jersey and California host the densest clusters of dietary supplement contract manufacturers qualifying mineral premix vendors.
Germany
Premium nutraceutical brands in Munich and Hamburg require REACH-registered mineral-organic complexes with existing toxicity dossiers. ECHA substance evaluation processes demand extended datasets for novel chelated formats outside the 2013-2018 SVHC candidate list. The country's premix blenders are consolidating supplier relationships to dossier-compliant producers.
India
Pharmaceutical and nutraceutical manufacturing corridors around Hyderabad and Mumbai are concentrating demand for pharmaceutical-grade mineral specifications. FSSAI fortification standards mandate specific mineral levels in staple food categories, creating compliant-supplier bottlenecks. Gujarat and Maharashtra processed food manufacturers enforce supplier certification against domestic fortification mandates.
China
Mass-market food fortification programs drive bulk procurement of mineral salts for edible oils and wheat flour processing. SAMR mandates enforce minimum fortification levels in designated staple categories. Yangtze River Delta and Pearl River Delta manufacturing bases dominate domestic mineral salt compounding for regional food processors.
Brazil
Intensive livestock operations in São Paulo and Minas Gerais states sustain demand for precision-formulated trace mineral premixes. ANVISA fortification mandates govern mineral levels in processed food categories. The country's animal nutrition sector sources chelated complexes through direct technical sales engagement rather than commodity distributors.
Mineral Enrichment Ingredients Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and geographic coverage dimensions. The supplier base fragments into technology-differentiated tiers where encapsulation capabilities and bioavailability verification protocols erect margin premiums. Three archetypes dominate: bulk commodity salt producers, chelated mineral specialists, and integrated premix blenders with captive analytical capabilities. Competitive moves center on backward integration into bulk commodity sourcing and acquisition of REACH-registered producers possessing existing dossier libraries.
Within the chelated mineral specialist tier, Balchem Corporation and Kemin Industries exemplify technology-differentiated positioning. Cargill, Incorporated anchors the integrated commodity-processor archetype through scale advantages in bulk mineral salt sourcing. These three entities represent the dominant competitive anchors against which mid-tier suppliers benchmark certification investments and geographic expansion priorities.
| Leading Market Players |
|---|
| Balchem Corporation |
| Cargill, Incorporated |
| Nestlé |
| Barry Callebaut |
| Kemin Industries |
| Corbion |
| ADM WILD Europe |
| Wilmar International Limited |
| Clover Hill Food Ingredients Ltd |
| Others |
Supply & Pricing Matrix
Ninety-day supplier onboarding cycles at Mexican and Thai contract manufacturers compress inventory buffers while amplifying pricing leverage for qualified mineral premix vendors. This lead-time compression concentrates procurement power among REACH-registered producers and FSSAI-certified domestic suppliers, forcing commodity-grade mineral salt producers into margin-eroding spot-market transactions.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across mineral enrichment ingredients. Three-tier pricing stratification separates pharmaceutical-grade chelates from food-grade salts and feed-grade bulk compounds, with certification level and volume scale as primary differentiation drivers. Cost compression in commodity mineral salts intensifies as Indian and Chinese processed food manufacturers consolidate procurement around FSSAI and SAMR-compliant suppliers. Mid-tier supplement manufacturers exhibit highest price sensitivity, while German premix blenders absorbing REACH-registered organic complexes show lowest elasticity.
Supply Chain Analysis
Chile and Japan anchor seaweed-derived iodine and selenium extraction, while India and China dominate inorganic mineral salt compounding for mass-market fortification. The supply chain draws from sulfuric acid and hydrochloric acid feedstocks tethered to energy market oscillations, creating input cost volatility. Single-source vulnerability concentrates in Chilean coastal processing facilities for marine-derived trace minerals. Distribution runs through direct technical sales engagement for chelated formats and bulk commodity distributors for standard mineral salts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mineral enrichment ingredients function as a service-attach opportunity where bioavailability verification protocols and encapsulation technology licensing expand recurring revenue faster than commodity mineral salt production. After-sales analytical support and certification maintenance contracts deepen customer captivity beyond transactional ingredient supply.
For Market Incumbents: Consolidate supplier relationships with REACH-registered producers possessing existing toxicity dossiers to preempt German and Dutch premix blender procurement consolidation. Acquire mid-tier suppliers lacking in-house ICP-MS and atomic absorption spectroscopy capabilities before FDA CGMP enforcement gaps close. Backward integration into captive mineral premix production defends margin position against top-tier cereal and dairy processors pursuing vertical integration. For New Entrants and Emerging Players: Differentiate on bioavailability verification protocols for direct-to-consumer subscription channels in North American and European urban markets. Target cell-cultured meat nutrition applications where precision fermentation-derived mineral premixes remain underpenetrated. Partner with cultivated protein startups for co-development agreements rather than competing for established food manufacturer supply slots. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underoptimized mineral ingredient divisions lacking REACH registration depth. Long-term viability hinges on regulatory certification moats rather than commodity scale. Watch for FDA CGMP enforcement acceleration as the inflection signal compressing acquisition multiples for non-compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Acquisition | Secures European market access for novel chelated mineral formats under ECHA substance evaluation. |
| Backward Integration into Bulk Sourcing | Mitigates sulfuric acid price volatility through captive supply of inorganic mineral salt feedstocks. |
| Encapsulation Technology Licensing | Captures 40-60% price premiums in pediatric and geriatric supplement lines through lipid-shell delivery systems. |
| FSSAI Certification Investment | Unlocks mandatory fortification procurement in Indian staple food categories with compliant-supplier bottlenecks. |
| Cell-Cultured Meat Premix Development | Positions for emerging demand from cultivated protein startups scaling precision fermentation manufacturing. |
Research Methodology
Cross-validation between primary interviews with plant managers at mineral salt compounding facilities and secondary validation through customs/trade data anchors the qualitative findings. Procurement leads at downstream food manufacturers, distribution channel partners, technical R&D directors at premix blenders, and quality control officers at supplement contract manufacturers provided operational perspective. SEC 10-K filings, FSSAI fortification compliance records, ECHA REACH registration databases, and ACC/Cefic industry reports supplied quantitative grounding. Bottom-up volume builds triangulated against top-down market sizing across product type, application, form, and end user segments.
Sensitivity analysis tested forecast robustness across input cost volatility scenarios and regulatory enforcement intensity variations over the projection horizon. Segmentation dimensions modeled include purity grade tier, delivery format, end-use industry, and regional regulatory cluster. CAGRs derived from trend extrapolation of pharmaceutical-grade specification adoption rates and chelated mineral penetration in functional beverage channels. Cell-cultured meat nutrition application scaling and direct-to-consumer subscription channel expansion provided industry-specific demand inputs.
Material uncertainties — regulatory divergence between FDA, EFSA, and FSSAI purity benchmarks, energy market-driven sulfuric acid price spikes, and single-source vulnerability in Chilean seaweed extraction — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline standardization and bioavailability claim substantiation requirements. Recalibration cycles align with material shifts in CGMP enforcement intensity and REACH authorization requirement expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Fluorspar Market
Industrial Minerals
Calcined Anthracite Market
Industrial Minerals
Inorganic Salts Market
Industrial Minerals
Mediterranean Sea Salt Micro-Mineral Complexes Market
Industrial Minerals
Europe Frac Sand Market
Industrial Minerals
Mineral Adsorbent Market
Industrial Minerals
Industrial Diamond Market
Industrial Minerals
Bentonite Market
Industrial Minerals
Limestone Mill Market
Industrial Minerals
India Feed Minerals Market
Industrial Minerals
Europe Feed Minerals Market
Industrial Minerals
Barite Mining Market
Industrial Minerals
Dolomite Powder Market
Industrial Minerals
Middle East Feed Minerals Market
Industrial Minerals
Global Carbonate Minerals Market
Industrial Minerals
Mineral Sand Market