
 North America Feed Antioxidants Market | 2026-2036
North America Feed Antioxidants Market Size, Share, and Industry Trends Forecast 2026-2036
North America Feed Antioxidants Market Analytics
Pharmaceutical-grade antioxidant specifications for premium livestock nutrition is collapsing the gap between commodity feed additives and human-food-grade preservation chemistry. Cargill leverages its integrated oilseed processing network to secure captive tocopherol supplies for feed antioxidant formulations. ADM anchors its position through backward integration into vegetable oil refining, yielding cost-advantaged raw material streams for BHT and tocopherol production. Kemin Industries specializes in natural antioxidant extraction from botanical sources, competing on clean-label positioning against synthetic alternatives.
Feed antioxidants are chemical compounds or natural extracts added to animal feed to inhibit lipid oxidation, preserve vitamin potency, and maintain palatability, with synthetic variants typically exhibiting higher oxidative stability thresholds while natural tocopherols offer regulatory acceptance for antibiotic-free and organic production systems. BHT dominates volume consumption in ruminant and swine applications where cost sensitivity prevails, while tocopherols capture accelerating demand in poultry and aquaculture segments driven by export-market residue restrictions and premium meat positioning. The liquid form leads distribution through automated feed-mill integration, though powder formulations sustain relevance in smaller regional blending operations lacking liquid handling infrastructure.
The FDA's Generally Recognized as Safe determinations and CFIA's Feed Regulations shape product registration pathways and label claims across the United States and Canada, with state-level Department of Agriculture inspections in Iowa, North Carolina, and Texas adding compliance layers for interstate feed commerce. The EPA's oversight of chemical manufacturing emissions influences production siting decisions for synthetic antioxidant facilities, particularly BHT and BHA operations concentrated in the U.S. Gulf Coast petrochemical corridor. Stakeholders must monitor evolving state-level restrictions on synthetic antioxidant concentrations in organic livestock feeds and the pace of commercial validation for novel plant-derived alternatives with comparable shelf-life extension performance.
Market Dynamics
The FDA's tightening documentation requirements for antioxidant efficacy claims are compressing formulation cycles and forcing feed mills to validate oxidative stability through third-party testing protocols. This regulatory pressure intersects with poultry operations' pivot toward lipid-rich feed formulations, creating simultaneous demand pull and compliance friction.
Growth Catalysts
- Export-market residue restrictions:Tocopherol-based antioxidants satisfy EU and Japanese import standards for antibiotic-free poultry, accelerating substitution away from synthetic alternatives in U.S. Southeast processing corridors.
- CFIA Feed Regulations:Canadian documentation mandates for livestock feed safety drive formal adoption of antioxidant stability protocols among Ontario and Quebec integrated swine operations.
- Automated feed-mill infrastructure:Liquid antioxidant delivery systems reduce labor costs and dosing variance, penetrating the U.S. Midwest corn-soy belt where bulk procurement volumes justify capital deployment.
Market Restraints
- Vegetable oil feedstock volatility:Tocopherol production costs fluctuate with global soybean and sunflower oil refining margins, compressing natural antioxidant pricing power against synthetic BHT.
- Gulf Coast petrochemical concentration:BHT and BHA manufacturing clusters along the Texas-Louisiana corridor create hurricane-related supply disruption exposure and freight cost asymmetries for inland feed mills.
- Organic certification barriers:USDA National Organic Program restrictions on synthetic antioxidant concentrations limit formulation flexibility for producers serving premium retail channels.
Strategic Opportunities
- Botanical extraction scale-up:Rosemary and green tea-derived antioxidants with comparable shelf-life performance to BHT capture clean-label premiums in Pacific Northwest organic poultry operations.
- State-level organic feed incentives:Iowa and North Carolina Department of Agriculture cost-share programs accelerate antioxidant transition timelines for mid-scale producers entering antibiotic-free certification.
- Aquaculture formulation expansion:High-lipid salmon and shrimp feeds in British Columbia and Maine create demand for heat-stable antioxidant blends with minimal flavor transfer.
Industry Challenges
- Analytical chemistry skill scarcity:Feed mills struggle to hire technicians capable of operating peroxide value and thiobarbituric acid assay equipment for oxidative stability validation.
- Dual-registration compliance:Antioxidant suppliers must maintain separate FDA food additive and feed ingredient dossiers, duplicating toxicology study costs and timeline risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Feed Antioxidants Market |
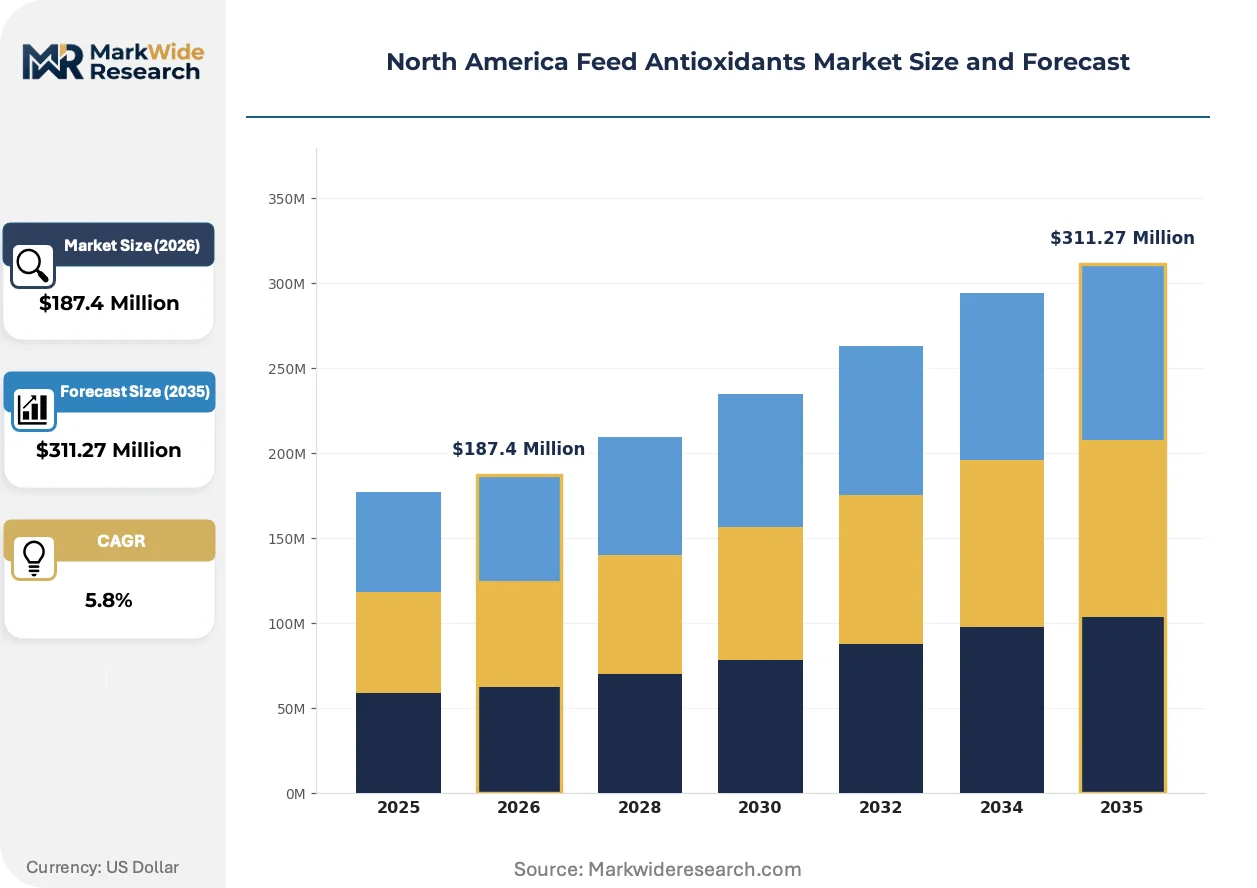
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BHA, BHT, Tocopherols, Citric Acid End User: Poultry, Swine, Ruminants, Aquaculture Form: Liquid, Powder, Granulated, Tablet Distribution Channel: Direct Sales, Distributors, E-commerce, Retail |
| Companies Covered | Cargill, ADM, Kemin Industries, Alltech, Adisseo, Novus International, Perstorp, dsm-firmenich, Nutreco, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Feed Antioxidants Market Evolving Landscape
Formulation science and regulatory documentation requirements are converging to reshape competitive positioning in feed antioxidants. Three developments are compressing product development cycles and redrawing procurement patterns across North America.
Microencapsulated tocopherol blends with enhanced heat stability during pelleting are displacing unprotected natural antioxidants in high-temperature poultry feed processing. U.S. Southeast integrators adopting these formulations report reduced vitamin degradation and extended feed storage windows. The technology is compressing price premiums between synthetic and natural alternatives.
EPA enforcement of chemical manufacturing emissions standards is forcing BHT producers to install scrubber systems and shift production toward lower-emission reactor designs. Gulf Coast facilities face capital allocation decisions between compliance upgrades and capacity expansion. Smaller synthetic antioxidant operations are consolidating rather than absorbing these environmental compliance costs.
Direct procurement contracts between integrated poultry operators and antioxidant compounders are bypassing traditional feed-additive distributors. Large Midwest and Southeast integrators negotiate volume commitments with dedicated technical service support, displacing spot-market purchasing through regional blending operations. This channel compression concentrates formulation expertise within fewer supplier relationships.
North America Feed Antioxidants Market Segmentation
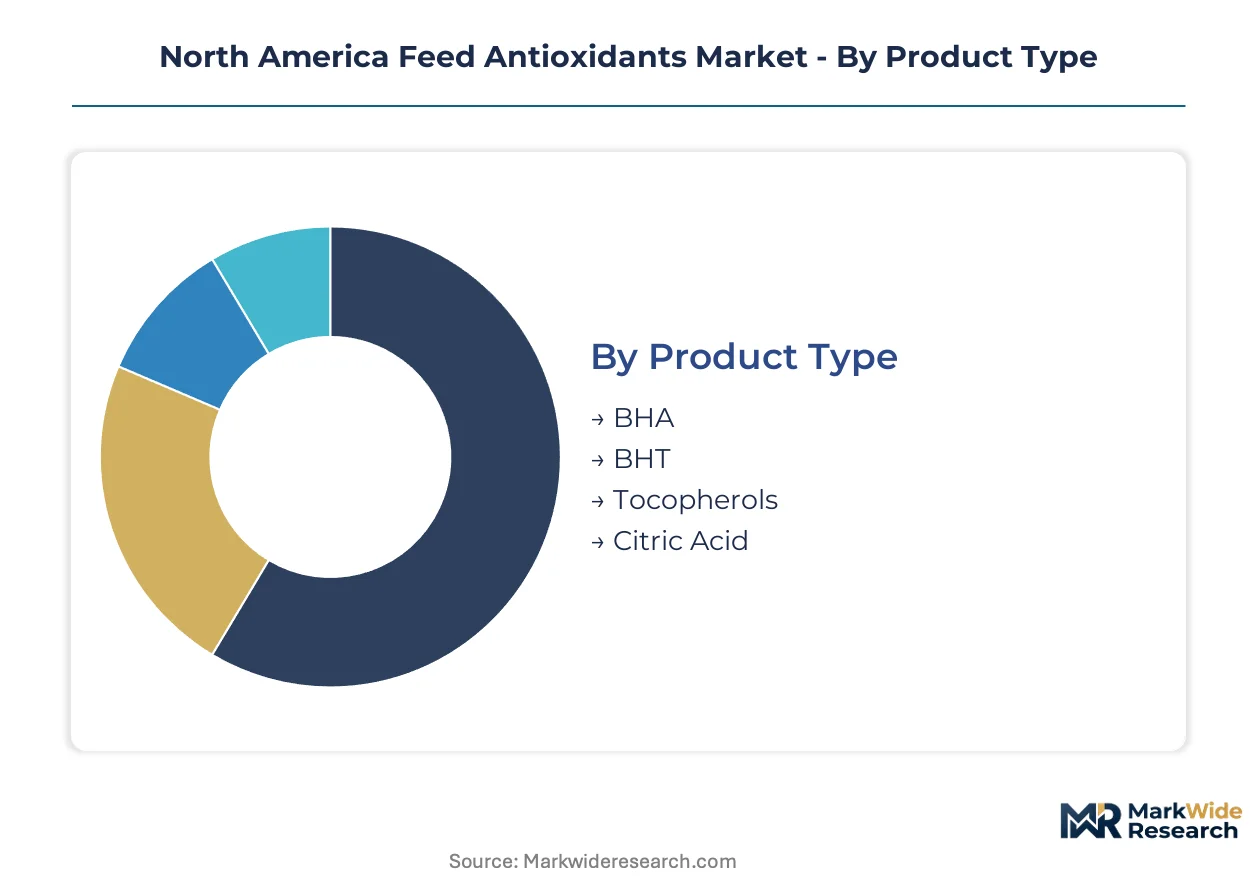
Feed antioxidant segmentation reveals divergent procurement patterns between commodity livestock operations and premium export-oriented producers. Product form and distribution channel choices directly correlate with operational scale and automation infrastructure across U.S. and Canadian feed milling networks.
Product Type:
Synthetic antioxidants dominate domestic ruminant and swine applications where cost minimization prevails, while natural variants capture export-facing poultry operations subject to EU and Japanese residue protocols.
- BHA:Butylated hydroxyanisole delivers potent oxidative inhibition for rendered fat stabilization in high-temperature pelleting environments. Demand concentrates in Texas and Louisiana integrated swine facilities where Gulf Coast petrochemical supply chains minimize delivered costs.
- BHT:Butylated hydroxytoluene anchors volume consumption across Midwest corn-soy belt operations, prized for thermal stability and extended shelf-life performance in bulk-stored feed grains. Iowa and Illinois procurement offices negotiate annual volume contracts with Gulf Coast manufacturers.
- Tocopherols:Vitamin E-derived antioxidants satisfy USDA National Organic Program specifications and antibiotic-free certification requirements, penetrating Pacific Northwest and New England premium poultry channels.
- Citric Acid:Organic acid synergist enhances metal chelation in complex antioxidant formulations, finding niche adoption in aquaculture feeds where flavor neutrality matters.
BHT commands the established base. The steepest expansion runs through Tocopherols.
End User:
Species-specific formulation requirements drive antioxidant selection, with lipid content in feed rations and processing temperature thresholds determining technical specifications.
- Poultry:High-energy corn-soy diets with elevated vegetable oil inclusion demand robust antioxidant protection against peroxidation during summer storage. U.S. Southeast integrators specify tocopherol-rich blends for export-compliant breast meat production.
- Swine:Grower-finisher rations with rendered fat additions rely on cost-optimized synthetic antioxidant packages. Ontario and Quebec operations adopt CFIA-mandated stability documentation protocols for nursery feed shipments.
- Ruminants:Protected fat supplements in dairy transition diets utilize antioxidant fortification to preserve fatty acid bioavailability. Wisconsin and California Central Valley cooperatives specify liquid delivery systems for TMR integration.
- Aquaculture:Marine and freshwater species feeds with fish oil and krill meal components require heat-stable antioxidant matrices. British Columbia salmon producers and Maine shrimp hatcheries drive specialized formulation demand.
Poultry anchors volume demand. Aquaculture posts the most rapid climb.
Form:
Physical presentation determines handling infrastructure requirements and dosing precision across automated versus manual feed mill operations.
- Liquid:Pump-dispersed antioxidant concentrates integrate with computerized batching systems at high-throughput facilities. Midwest corn-soy belt mills with 500,000+ ton annual capacity justify capital investment in bulk liquid storage and metering equipment.
- Powder:Dry-flowable antioxidant premixes sustain relevance in regional blending operations lacking liquid handling infrastructure. Carolina and Georgia independent feed mills serving contract growers rely on bagged powder formulations.
- Granulated:Dust-free pelletized antioxidants improve handling safety and reduce respiratory exposure in manual mixing environments. Alberta and Saskatchewan cattle feedlots specify granulated product for open-air commodity shed operations.
- Tablet:Slow-dissolving compressed antioxidant blocks target on-farm top-dressing applications in pasture-based systems. Texas Panhandle stocker operations utilize tablet formats for mineral supplement co-packaging.
Liquid formats dominate procurement value. Granulated alternatives gain share fastest among safety-conscious handlers.
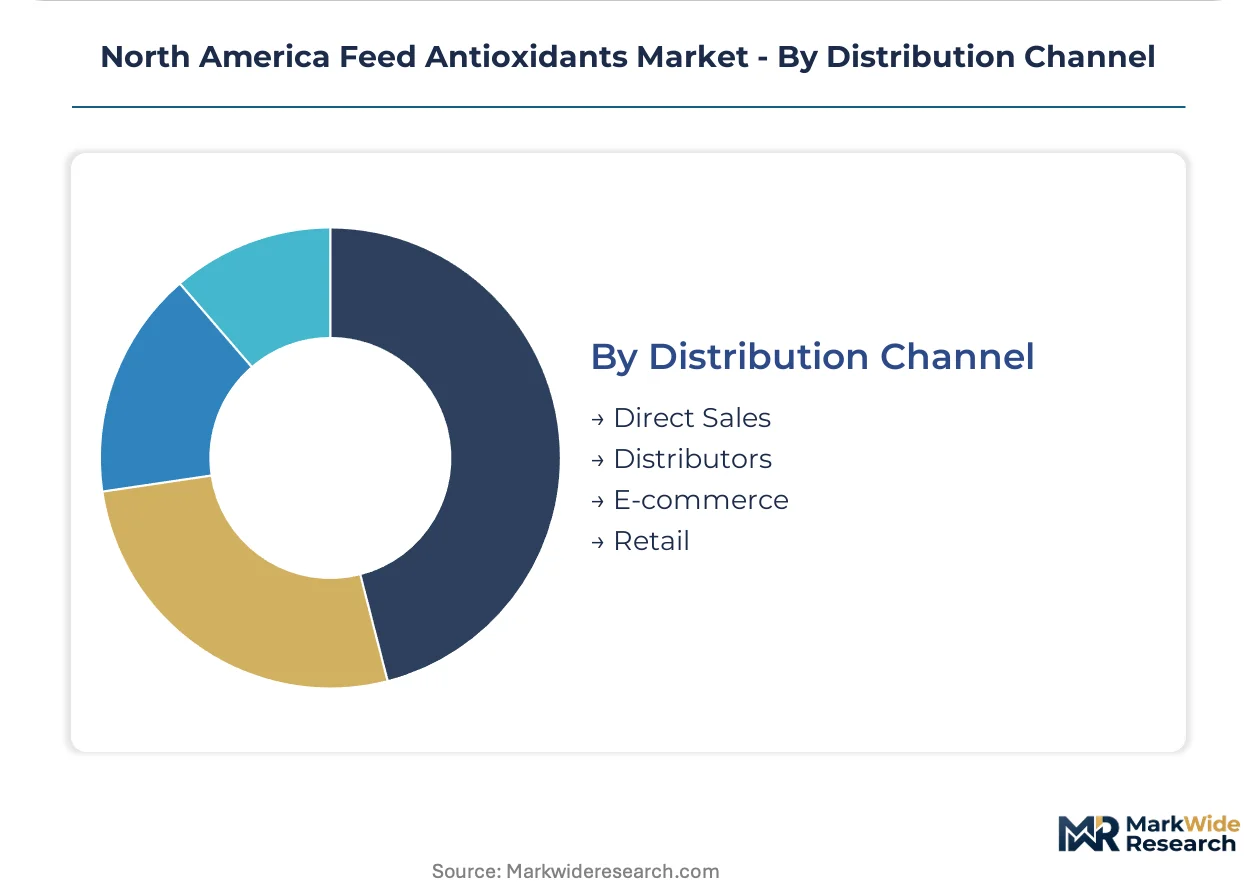
Distribution Channel:
Channel selection reflects operational scale and technical service requirements, with large integrators bypassing traditional distribution layers.
- Direct Sales:Volume commitments between antioxidant compounders and integrated protein producers eliminate distributor margins. Tyson Foods and Pilgrim's Pride procurement teams negotiate direct technical service agreements with Kemin and ADM specialty ingredients divisions.
- Distributors:Regional feed additive distributors sustain relevance in mid-scale independent mill networks. Wilbur-Ellis and Univar Solutions maintain antioxidant inventories across Great Plains and Mid-Atlantic warehousing footprints.
- E-commerce:Digital procurement platforms penetrate small-lot specialty feed producers and organic certification consultants. Amazon Business and specialty agricultural marketplaces list tocopherol and rosemary extract SKUs for pilot-scale operations.
- Retail:Farm supply cooperatives and feed stores serve hobby farm and 4-H show animal segments. Tractor Supply Company and local farm bureau outlets stock consumer-packaged antioxidant premixes for show pig and poultry enthusiasts.
Direct sales capture the largest contract value. E-commerce channels expand most quickly among niche organic producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antioxidant manufacturing clusters concentrate along the U.S. Gulf Coast petrochemical corridor and the Canadian Prairie provinces, with formulation facilities tracking feed mill density across the Midwest corn-soy belt.
United States
Poultry integrators in the Southeast specify tocopherol-rich blends for EU-compliant breast meat exports. FDA feed ingredient approval pathways tighten documentation requirements for oxidative stability claims. Iowa and Illinois procurement offices negotiate annual BHT volume contracts with Texas-Louisiana manufacturers.
Canada
Ontario and Quebec integrated swine operations adopt formal antioxidant stability protocols under CFIA Feed Regulations. Health Canada oversight of livestock feed safety mandates third-party peroxide value testing for cross-border shipments. Alberta cattle feedlots specify granulated antioxidants for open-air commodity shed handling.
Mexico
Sonora and Jalisco poultry producers source synthetic antioxidant packages for cost-sensitive domestic broiler operations. Mexico's national feed safety regulator aligns documentation standards with U.S. FDA frameworks for integrated North American supply chains. Yucatán Peninsula aquaculture hatcheries import heat-stable antioxidant blends for shrimp larval feeds.
North America Feed Antioxidants Market Competitive Landscape
Concentration sits with diversified agribusiness conglomerates controlling upstream oilseed processing and downstream formulation capabilities. Three archetypes dominate: integrated oilseed processors with captive tocopherol supplies, specialty chemical compounders with Gulf Coast petrochemical access, and botanical extraction specialists competing on clean-label positioning. Competitive moves center on backward integration into vegetable oil refining and direct procurement contracts bypassing traditional distribution layers.
Among integrated agribusiness operators, Cargill and ADM exemplify the oilseed-processor archetype with in-house antioxidant raw material streams. Kemin Industries occupies the botanical-specialist tier, extracting natural antioxidants from plant sources for antibiotic-free certification channels.
| Leading Market Players |
|---|
| Cargill |
| ADM |
| Kemin Industries |
| Alltech |
| Adisseo |
| Novus International |
| Perstorp |
| dsm-firmenich |
| Nutreco |
| Others |
Value Network & Pricing Analysis
Tocopherol substitution for synthetic BHT in antibiotic-free poultry feeds simultaneously redraws procurement geography toward vegetable oil refining corridors and compresses natural antioxidant price premiums against petrochemical alternatives. This feedstock-driven realignment concentrates supplier power among integrated oilseed processors while fragmenting spot-market pricing for regional feed mills lacking direct sourcing relationships.
Pricing Analysis
USDA National Organic Program certification dictates the pricing tier structure across the North American feed antioxidants market. Three-tier pricing stratifies across pharmaceutical-grade tocopherols, standard natural extracts, and commodity synthetic BHT, with FDA Generally Recognized as Safe documentation requirements adding compliance premiums to upper tiers. Price differentiation hinges on certification grade and volume scale, with annual contract volumes above ten thousand kilograms commanding fifteen to twenty percent discounts against spot purchases. Cost compression in synthetic BHT is intensifying because Gulf Coast petrochemical facilities face EPA emissions compliance capital demands, while mid-scale organic poultry integrators exhibit highest price sensitivity due to thin margin structures in antibiotic-free channels.
Supply Chain Analysis
Mississippi River barge terminals and Houston Ship Channel petrochemical complexes constitute the critical chokepoint infrastructure anchoring antioxidant feedstock flows to Midwest feed mill networks. Geographic supply concentration centers on the United States Gulf Coast for BHT and BHA manufacturing, Canadian Prairie provinces for canola-derived tocopherol extraction, and Argentina for supplemental soybean oil refining inputs. Raw material dependencies encompass crude petroleum derivatives for synthetic antioxidants, vegetable oil refining byproducts for natural tocopherols, and specialty botanical extracts for rosemary and green tea alternatives. Supply chain risk stems from hurricane-related disruption exposure concentrated in the Texas-Louisiana manufacturing corridor. Distribution runs through direct procurement contracts between integrated poultry operators and compounders, bypassing traditional regional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America feed antioxidants market is recovering from cyclical compression in livestock protein margins, with poultry inventory rebuilding and export demand normalization driving formulation volume restoration.
For Market Incumbents: Secure captive vegetable oil refining capacity in the Midwest corn-soy belt to defend tocopherol cost positions against Argentine import volatility. Lock in multi-year direct procurement contracts with top-ten integrated poultry operators before botanical extraction specialists achieve USDA organic certification scale. Prioritize EPA emissions compliance upgrades at Gulf Coast BHT facilities over capacity expansion given regulatory enforcement trajectory. For New Entrants and Emerging Players: CFIA Feed Regulations fast-track adoption among Ontario and Quebec swine integrators creates immediate white-space opportunity for stability documentation service providers. Pacific Northwest organic poultry operations remain underpenetrated by national compounders due to freight cost asymmetries from Midwest supply bases. Enter through technical service partnerships with regional feed mills lacking in-house peroxide value testing capability. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty chemical compounders lacking backward integration into oilseed processing. Five-to-ten year viability hinges on natural antioxidant cost parity achievement against synthetic alternatives. Monitor EPA enforcement actions against Gulf Coast BHT manufacturers as inflection indicator for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vegetable Oil Refining | Cargill and ADM secure captive tocopherol streams, insulating margin from global soybean price volatility. |
| CFIA Compliance Documentation Investment | Canadian feed mills formalize third-party peroxide value protocols, creating service revenue layers for analytical laboratories. |
| Botanical Extraction Scale-Up | Kemin Industries expands rosemary-derived antioxidant capacity to capture clean-label premiums in antibiotic-free channels. |
| Liquid Delivery System Deployment | Midwest integrators reduce dosing variance and labor costs through automated feed-mill infrastructure upgrades. |
| Direct Procurement Contract Negotiation | Tyson Foods and Pilgrim's Pride bypass distributor margins, concentrating formulation expertise within dedicated supplier relationships. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews across the value chain. Feed mill procurement managers, poultry integrator nutritionists, synthetic antioxidant plant engineers, and CFIA regulatory affairs specialists provided operational perspective. Secondary validation drew from FDA Generally Recognized as Safe determinations, CFIA Feed Regulations documentation, USDA National Organic Program standards, and SEC filings from publicly traded agribusiness conglomerates. Bottom-up volume modeling triangulated against top-down industry association aggregates.
Across the analysis window, forecasts incorporated product type segmentation by synthetic versus natural chemistry, end-user species requirements, physical form handling infrastructure, and distribution channel structure. Modeled dimensions included poultry versus ruminant versus aquaculture antioxidant intensity, liquid versus powder versus granulated adoption curves, and direct sales versus distributor penetration. CAGRs derived from regression analysis against livestock inventory cycles, export market residue protocol evolution, and feed mill automation capital expenditure patterns.
Decision-makers should treat outputs as directional under assumptions of stable FDA feed ingredient approval pathways and continued CFIA documentation harmonization; material deviation in regulatory enforcement intensity or hurricane disruption frequency would warrant model refresh. Practitioners should keep alternative scenarios live as EPA emissions standards and organic certification growth trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Feed Flavor Market
Agricultural Chemicals
Berry Greenhouse Premium Micronutrient Package Market
Agricultural Chemicals
Global Crop Oil Concentrates Market
Agricultural Chemicals
CBD Plant Nutrients Market
Agricultural Chemicals
Global Soil Wetting Agents Market
Agricultural Chemicals
North America Feed Minerals Market
Agricultural Chemicals
Asia-Pacific Feed Premix Market
Agricultural Chemicals
Organic Bromide Market
Agricultural Chemicals
Amino Acid for Agriculture Market
Agricultural Chemicals
South America Agricultural Disinfectants Market
Agricultural Chemicals
Indonesia Herbicide Market
Agricultural Chemicals
Pesticide Adjuvant Market
Agricultural Chemicals
South America Feed Acidifiers Market
Agricultural Chemicals
Europe Feed Pigments Market
Agricultural Chemicals
Asia Pacific Fungicide Market
Agricultural Chemicals
Fish Feed and Shrimp Feed and Additives Market