
 Agricultural Miticides Market | 2026-2036
Agricultural Miticides Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Miticides Market Outlook
Chinese active ingredient production is decoupling from European formulation capacity, reshaping supply geography for the Agricultural Miticides Market. BASF SE leverages integrated R&D pipelines across Ludwigshafen to sustain patent-protected acaricide families. Bayer AG anchors its position through biological-chemical hybrid portfolios that navigate regulatory complexity in multiple jurisdictions. Syngenta Group competes via broad distribution networks spanning emerging agricultural economies.
Agricultural miticides are crop protection agents specifically formulated to target and control spider mites, eriophyid mites, and other acarine pests through contact, translaminar, or systemic activity modes, with active ingredients typically concentrated between 100-480 grams per liter in commercial formulations. Their primary commercial purpose centers on preventing yield loss in high-value fruit, vegetable, and ornamental crops where mite infestations compromise photosynthetic capacity and marketable quality. Chemical miticides occupy the dominant revenue position due to established efficacy and farmer familiarity, though biological miticides represent the fastest-expanding category as residue-sensitive export markets tighten maximum residue limits. Application through crop protection channels generates the largest volume flow, while greenhouse deployment commands premium pricing due to enclosed-system precision requirements.
The EPA governs miticide registration under FIFRA, mandating ecological risk assessments that delay novel active ingredient commercialization by several growing seasons. REACH compliance in Europe restricts certain organophosphate and pyrethroid chemistries, redirecting formulation investment toward botanical extracts and microbial fermentation products. Brazil's national health surveillance agency, ANVISA, enforces residue monitoring protocols that shape export-oriented grower purchasing decisions. Stakeholders must monitor evolving biocide harmonization talks between EPA and European regulators, as alignment would accelerate cross-regulatory product registrations while divergence would fragment R&D investment priorities.
Market Dynamics
Regulatory pressure from residue tolerance tightening is compressing formulation cycles across the Agricultural Miticides Market, forcing manufacturers to accelerate biological-chemical hybrid development pipelines ahead of traditional commercialization timelines.
Growth Catalysts
- EPA Residue Tolerance Revisions:Lower-toxicity chemistry mandates in the United States are redirecting R&D investment toward botanical fermentation products and microbial acaricides that satisfy export market access requirements.
- Brazil Citrus Belt Intensification:Export-oriented orchards in São Paulo state require intensive pest management protocols that sustain multiple annual miticide applications against escalating spider mite pressure.
- Translaminar Formulation Advances:Novel delivery mechanisms enabling acaricide absorption through leaf tissue are expanding application windows and reducing weather-dependent efficacy losses.
Market Restraints
- Active Ingredient Supply Concentration:Chinese intermediate production dominates upstream chemical synthesis, creating vulnerability to trade policy disruptions and freight cost volatility.
- REACH Compliance Burden:European organophosphate and pyrethroid restrictions under ECHA frameworks eliminate established chemistries before replacement products achieve commercial scale.
- Resistance Development Velocity:Spider mite populations in intensive cropping systems develop acaricide resistance within 3-5 application seasons, compressing product lifecycle economics.
Strategic Opportunities
- Greenhouse Precision Deployment:Enclosed-system agriculture in the Netherlands and Spain commands premium pricing for miticides integrated with automated application infrastructure and sensor networks.
- India Specialty Crop Expansion:Pomegranate and grape cultivation in Maharashtra and Karnataka is creating demand for residue-compliant acaricides that satisfy European export certification requirements.
- Biological-Chemical Hybrid Portfolios:Formulation combinations leveraging microbial fermentation extracts with reduced-synthetic loading are converging with ANVISA monitoring protocols to secure Brazilian citrus market access.
Industry Challenges
- Ecotoxicology Assessment Talent Scarcity:FIFRA-mandated risk evaluation protocols require specialized toxicologists and field biologists whose training pipelines lag registration application volumes.
- Cross-Jurisdictional Registration Synchronization:Divergent EPA-European biocide harmonization timelines fragment R&D prioritization and delay commercial launch sequencing across key markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Miticides Market |
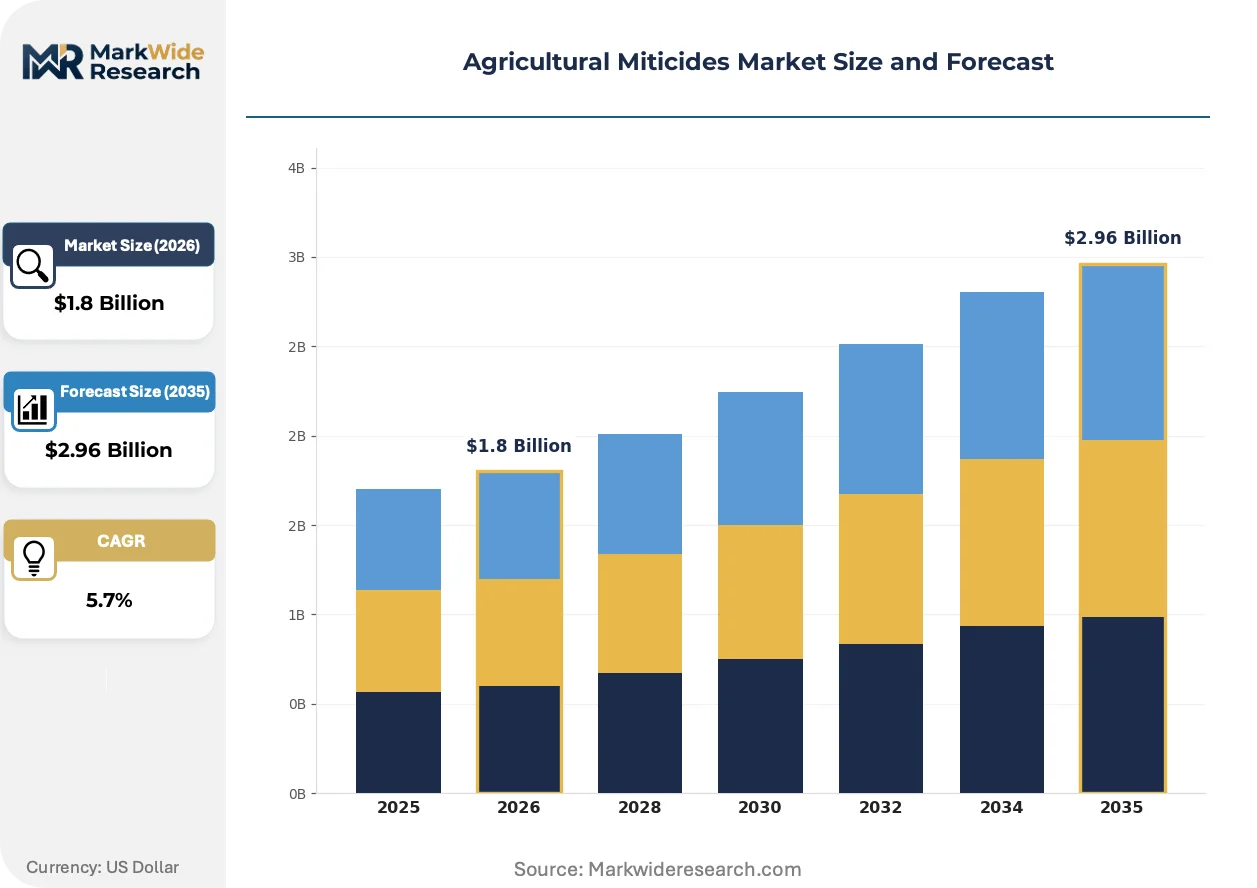
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acaricides, Insect Growth Regulators, Biological Miticides, Chemical Miticides Application: Crop Protection, Greenhouses, Turf & Ornamentals, Seed Treatment Formulation: Liquid, Granular, Emulsifiable Concentrate, WDG Distribution Channel: Online Retail, Agrochemical Stores, Direct Sales, Others |
| Companies Covered | BASF SE, Bayer AG, Syngenta Group, FMC Corporation, UPL Limited, Corteva Agriscience, ADAMA Agricultural Solutions, Sumitomo Chemical, Nufarm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Miticides Market Strategic Shifts
Biological fermentation technologies and precision application systems are converging to reshape how acaricide efficacy is measured and monetized across residue-sensitive export supply chains.
RNA interference-based acaricide development is converging with established microbial fermentation infrastructure to enable species-specific mite suppression without broad-spectrum ecological disruption. California almond and strawberry operations are piloting these formulations under restricted-use permits. The technology is converging with integrated pest management certification requirements to create premium market tiers for verified low-residue production systems.
REACH authorization procedures under ECHA are systematically eliminating organophosphate and pyrethroid chemistries from European formulation portfolios. Manufacturers are redirecting investment toward botanical extract standardization and microbial metabolite identification to maintain product registrations. Specialty vegetable exporters in Spain and Italy are accelerating adoption of these alternatives to preserve supermarket chain supply contracts.
Certification-driven procurement is restructuring distributor relationships as grower cooperatives consolidate purchasing through approved supplier lists tied to residue monitoring guarantees. Traditional independent retail channels in Brazil's citrus belt are losing volume to vertically integrated export consortiums that negotiate direct manufacturer contracts. This consolidation is most advanced in São Paulo state, where three cooperatives now control over half of acaricide procurement for fresh orange exports.
Agricultural Miticides Market Segmentation
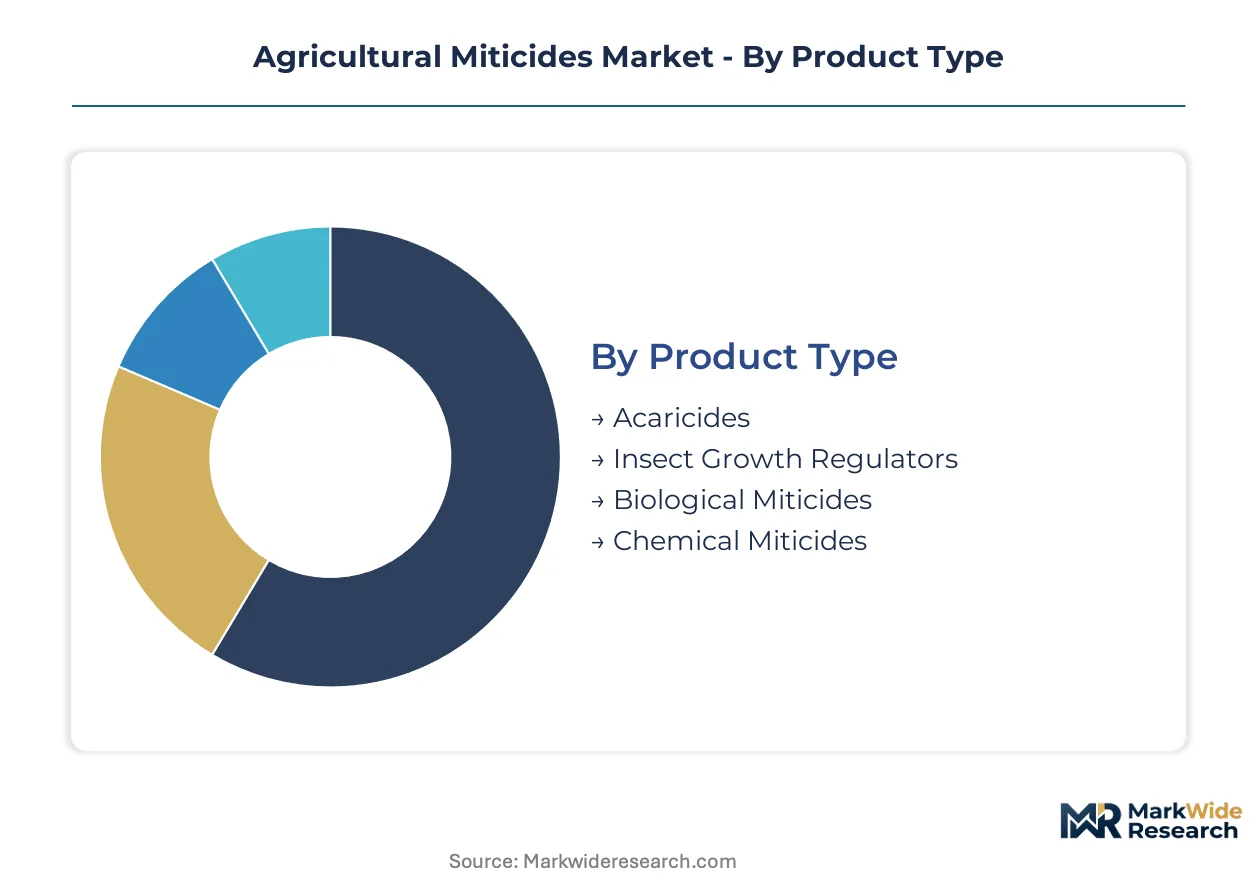
Segmentation in the Agricultural Miticides Market reveals how formulation chemistry, application setting, and channel structure determine pricing power and regulatory exposure. Each dimension carries distinct margin profiles and compliance burdens that reshape competitive positioning across residue-sensitive supply chains.
Product Type:
Supply concentration in active ingredient synthesis varies sharply across chemistry families, with fermentation-derived biologicals sourcing from distributed microbial facilities while synthetic acaricides cluster in specialized chemical corridors.
- Chemical Miticides:Synthetic formulations with active ingredient concentrations between 100-480 grams per liter dominate commercial volumes through established efficacy against spider mite populations. California almond and strawberry operations in the Central Valley sustain repeat purchase cycles despite resistance management protocols.
- Biological Miticides:Microbial fermentation products and botanical extracts satisfy tightening EPA residue tolerance frameworks and European export certification requirements. São Paulo citrus exporters are accelerating procurement of these alternatives to preserve EU supermarket supply contracts under ECHA-compliant protocols.
- Acaricides:Specialized mite-targeting chemistries with contact, translaminar, or systemic activity modes provide precision control in intensive cropping systems. These formulations face compressed lifecycle economics as resistance develops within 3-5 application seasons.
- Insect Growth Regulators:Hormone-disrupting compounds that interrupt mite molting cycles offer resistance management rotation options. Dutch greenhouse operations integrate these into automated application infrastructure for enclosed-system precision.
Chemical Miticides absorb the bulk of installed capacity; Biological Miticides are expanding most quickly.
Application:
Application setting determines equipment requirements, labor intensity, and residue monitoring rigor, with enclosed systems commanding premium pricing for precision delivery infrastructure.
- Crop Protection:Open-field deployment across fruit, vegetable, and commodity crops generates the largest volume flow through conventional ground and aerial application equipment. Brazil's citrus belt operations in São Paulo state require multiple annual applications against escalating spider mite pressure.
- Greenhouses:Enclosed-system agriculture in the Netherlands and Spain commands premium pricing for miticides integrated with sensor networks and automated dosing systems. These installations face stringent maximum residue limits for export-oriented production.
- Turf & Ornamentals:Golf course and nursery applications emphasize aesthetic quality preservation through preventive treatment protocols. This segment tolerates higher per-acre input costs than broad-acre agriculture.
- Seed Treatment:Prophylactic acaricide coating of planting material provides early-season protection in transplant operations. Maharashtra pomegranate growers utilize these treatments to satisfy European export certification requirements.
Crop Protection channels the greatest volume throughput; Greenhouses sustain the steepest expansion trajectory.
Formulation:
Physical form factor shapes freight economics, storage requirements, and compatibility with precision application equipment across divergent climatic conditions.
- Liquid:Ready-to-use and soluble concentrate formulations enable rapid field mixing and compatibility with drip irrigation systems. Karnataka grape vineyards favor these for residue-compliant export production.
- Emulsifiable Concentrate:Oil-based carriers enhance leaf surface penetration and rainfastness in tropical humidity. These formulations dominate Brazilian citrus applications.
- WDG:Water-dispersible granules reduce packaging weight and improve handler safety through reduced dust exposure. European formulators are redirecting investment toward these dry delivery systems under REACH compliance pressure.
- Granular:Slow-release matrix formulations provide extended protection in soil-applied systems. Turf management operations utilize these for season-long mite suppression with minimal labor input.
Liquid formulations absorb the bulk of installed capacity; WDG is expanding most quickly.
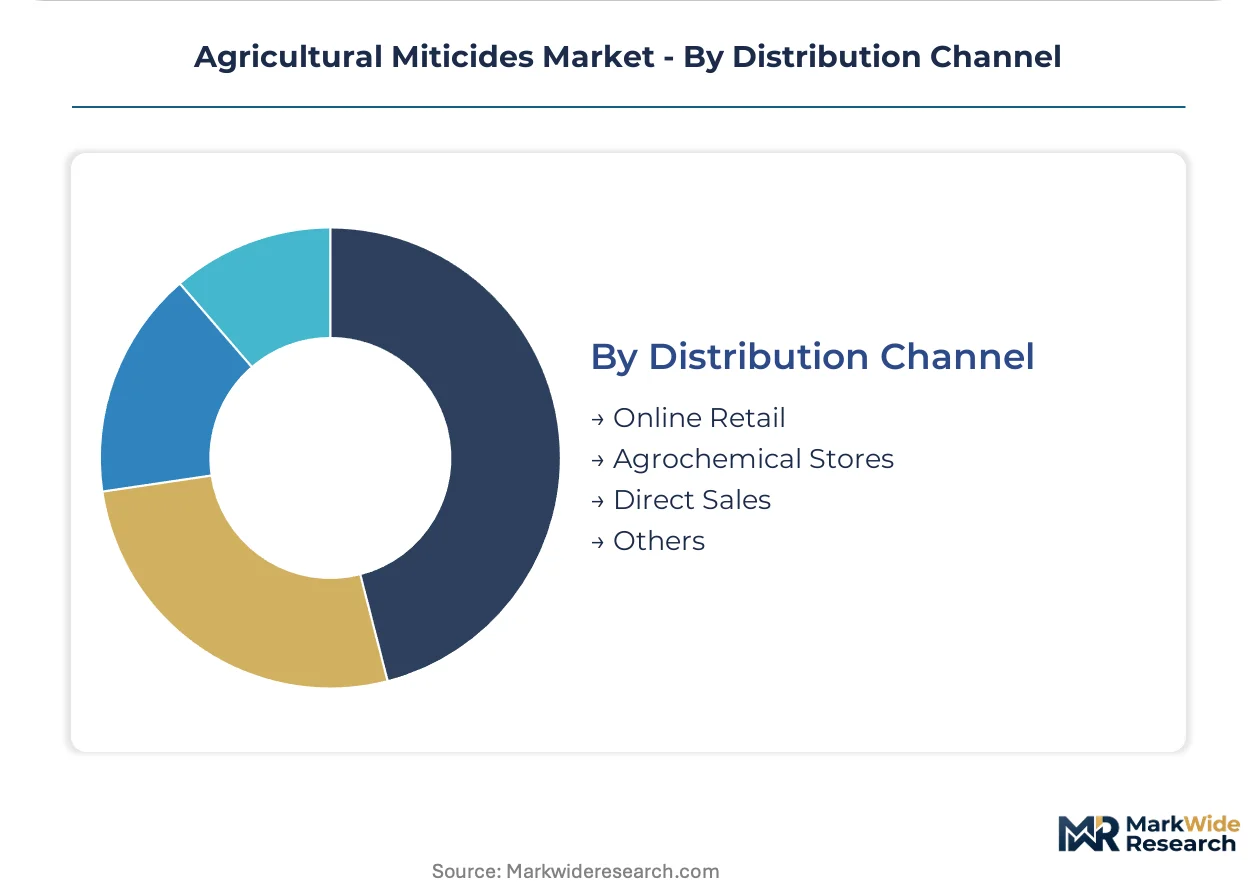
Distribution Channel:
Channel structure is consolidating as grower cooperatives displace independent retail through approved supplier lists tied to residue monitoring guarantees.
- Agrochemical Stores:Traditional independent retail networks in rural agricultural corridors maintain local technical advisory relationships. These outlets are losing volume to vertically integrated procurement consortiums in Brazil's citrus belt.
- Direct Sales:Manufacturer-to-grower contracts negotiated by export-oriented cooperatives capture premium pricing through volume commitments and technical service bundling. Three São Paulo cooperatives now control over half of acaricide procurement for fresh orange exports.
- Online Retail:Digital platforms enable price transparency and inventory access for smaller operations outside cooperative membership. These channels face regulatory constraints on restricted-use product delivery.
- Others:Government extension programs and development project procurement supply subsidized inputs to smallholder segments. These channels operate under separate tender and compliance frameworks.
Agrochemical Stores retain the greatest installed base; Direct Sales is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active ingredient synthesis clusters in eastern China supply intermediates to formulation plants across multiple continents, creating geographic interdependencies that reshape procurement security calculations for crop protection distributors.
United States
California almond and strawberry operations in the Central Valley sustain repeat miticide purchase cycles despite resistance management protocols. EPA residue tolerance revisions under FIFRA redirect R&D investment toward botanical fermentation products and microbial acaricides. Specialty vegetable producers in the Salinas Valley accelerate adoption of these alternatives to preserve export market access.
Brazil
Export-oriented citrus orchards in São Paulo state require intensive pest management protocols with multiple annual applications against escalating spider mite pressure. ANVISA enforces residue monitoring protocols that shape grower purchasing decisions toward ECHA-compliant formulations. Three cooperatives now control over half of acaricide procurement for fresh orange exports through direct manufacturer contracts.
China
Domestic pomegranate and grape cultivation in Xinjiang and Shandong provinces creates demand for residue-compliant acaricides. NMPA registration frameworks govern active ingredient commercialization timelines. Fermentation-derived biological production facilities in Jiangsu province expand capacity to serve European export certification requirements.
Netherlands
Enclosed-system greenhouse agriculture commands premium pricing for miticides integrated with automated application infrastructure and sensor networks. REACH authorization procedures under ECHA eliminate organophosphate chemistries from formulation portfolios. Wageningen-area research clusters pilot RNA interference-based acaricide formulations under restricted-use permits.
India
Pomegranate and grape cultivation in Maharashtra and Karnataka generates demand for residue-compliant acaricides satisfying European export certification. CDSCO regulates active ingredient registration through centralized pharmaceutical and agrochemical frameworks. Mumbai-Pune industrial corridors host formulation packaging operations serving domestic specialty crop segments.
Agricultural Miticides Market Competitive Environment
Global majors compete with regional champions across patent-protected acaricide families and biological-chemical hybrid portfolios. The vendor base separates into three tiers: integrated multinational conglomerates with captive R&D pipelines, mid-scale regional formulators with distribution depth in specific growing belts, and emerging biological specialists leveraging fermentation scale-up partnerships. Consolidation pressures concentrate around M&A activity targeting microbial metabolite identification capabilities and strategic partnerships bridging Chinese intermediate supply with European formulation capacity.
Within the integrated multinational tier, BASF SE, Bayer AG, and Syngenta Group exemplify divergent strategic postures. Ludwigshafen-based BASF SE anchors its position through patent-protected acaricide families sustained by integrated R&D pipelines. Leverkusen-headquartered Bayer AG occupies a position navigating regulatory complexity through biological-chemical hybrid portfolios. Syngenta Group sits within the broad distribution network archetype, spanning emerging agricultural economies with established crop protection channel relationships.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta Group |
| FMC Corporation |
| UPL Limited |
| Corteva Agriscience |
| ADAMA Agricultural Solutions |
| Sumitomo Chemical |
| Nufarm |
| Others |
Value Chain & Pricing Dynamics
Export-oriented citrus cooperatives in São Paulo state concentrate procurement through approved supplier lists, anchoring the market in contract-based long-term offtake agreements with residue monitoring guarantees. This buyer consolidation shifts pricing power toward volume-commitment structures that bundle technical advisory services with product supply.
Pricing Analysis
Technical service bundling separates premium manufacturer-direct contracts from unbundled agrochemical store transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in standard-tier formulations is intensifying because REACH compliance redirects R&D investment toward botanical alternatives before economies of scale mature. Smallholder operations outside cooperative membership exhibit highest price sensitivity; greenhouse precision deployments in the Netherlands tolerate premium positioning for sensor-integrated systems.
Supply Chain Analysis
Regional distribution centers in Rotterdam and São Paulo operate hub-and-spoke patterns feeding satellite agrochemical depots. Active ingredient synthesis draws from eastern China, with formulation capacity concentrated in Germany and Brazil. Specialty chemical intermediates for synthetic acaricides rest on pyrethroid and organophosphate feedstock availability. Single-source vulnerability in Chinese intermediate supply creates exposure to freight cost volatility and trade policy disruption. Distribution runs through manufacturer-direct channels for export consortiums, while independent retail networks serve fragmented smallholder demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Agricultural Miticides Market sits in a formulation chemistry transition, with biological fermentation technologies displacing legacy organophosphate and pyrethroid platforms under tightening EPA and ECHA frameworks.
For Market Incumbents: Acquire microbial metabolite identification capabilities to defend against biological-chemical hybrid entrants. Backward integration into Jiangsu province fermentation capacity secures supply continuity for botanical extract portfolios. Patent-protected acaricide families require accelerated lifecycle management as resistance compresses product economics to 3-5 application seasons. For New Entrants and Emerging Players: Maharashtra pomegranate cooperatives present an underserved buyer archetype seeking residue-compliant alternatives for European export certification. Karnataka grape vineyards offer secondary penetration opportunity through digital platform channels bypassing traditional agrochemical store networks. ANVISA-compliant formulation partnerships with Brazilian distributors provide fastest regulatory pathway to São Paulo citrus procurement. For Investors and Strategic Acquirers: The window for entry favors biological specialists with captive fermentation scale-up partnerships. Long-term viability centers on hybrid portfolio companies navigating divergent EPA-European harmonization timelines. Monitor biocide alignment negotiations between EPA and European regulators as inflection signal for cross-jurisdictional registration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Fermentation Scale-Up | Captive capacity in Jiangsu province serves ECHA-compliant export demand from European vegetable producers. |
| Residue Monitoring Partnership | ANVISA-aligned certification secures São Paulo citrus cooperative procurement against supermarket chain requirements. |
| Translaminar Formulation R&D | Novel delivery mechanisms expand application windows for California Central Valley almond operations. |
| Direct Sales Channel Expansion | Manufacturer-to-grower contracts capture premium pricing through volume commitments in Brazil's citrus belt. |
| RNA Interference Pipeline Development | Species-specific acaricide technology aligns with integrated pest management certification for premium market tiers. |
Study Parameters
Document review covered EPA registration databases, ANVISA residue monitoring protocols, and ECHA authorization procedures, complemented by interviews with crop protection R&D directors, Brazilian citrus cooperative procurement managers, and European specialty vegetable exporters. Secondary validation drew from customs trade data, SEC filings of listed agrochemical companies, and FAO agricultural input statistics. Bottom-up volume estimates triangulated against top-down value projections across formulation chemistry segments.
Historical volume trajectories cross-referenced against expert panel input on regulatory timeline acceleration. The analytical framework modeled product type, application setting, formulation format, and distribution channel dimensions across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic agricultural output assumptions. Resistance development velocity and biocide harmonization progress served as industry-specific forecast sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA-European regulatory divergence and Chinese intermediate supply disruption. Projections reflect assumptions regarding residue tolerance tightening velocity and biological fermentation cost curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
North America Agricultural Disinfectants Market
Agricultural Chemicals
South America Feed Acidifiers Market
Agricultural Chemicals
Europe Feed Acidifiers Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
Asia-Pacific Feed Minerals Market
Agricultural Chemicals
Turf and Ornamental Inputs Market
Agricultural Chemicals
Global Fertigation and Chemigation Market
Agricultural Chemicals
South America Feed Enzymes Market
Agricultural Chemicals
Europe Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Paclobutrazol Market
Agricultural Chemicals
Feed Flavor Market
Agricultural Chemicals
China Feed Amino Acids Market
Agricultural Chemicals
Asia-Pacific Feed Antioxidants Market
Agricultural Chemicals
Soil Treatment Market
Agricultural Chemicals
Feed Antibiotics Market
Agricultural Chemicals
Africa Feed Antioxidants Market