
 China Facility Management Market | 2026-2036
China Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
China Facility Management Market Analysis
Market Dynamics
The capital-intensity gap between multinational operators and domestic specialists is collapsing as local players scale technology platforms. CBRE leverages its global property management protocols to anchor premium commercial contracts in tier-one cities. Onewo Space-Tech Service competes through vertical control over smart building software and hardware integration. Sodexo China differentiates by sustaining long-term institutional relationships across healthcare and education sectors.
Segmentation Analysis
China facility management encompasses the coordinated delivery of hard and soft services—cleaning, security, HVAC, landscaping, and energy oversight—to maintain operational continuity of built assets. The discipline relies on IoT sensor networks, automation protocols, and energy management software to monitor equipment health, optimize consumption patterns, and reduce unplanned downtime across commercial, residential, and institutional properties. HVAC management and integrated solutions command the deepest margin pools as energy compliance costs rise under national efficiency mandates. IoT solutions and smart monitoring represent the fastest-expanding technology tier, while on-demand services remain fragmented with limited pricing power.
Regulatory Environment
MIIT's dual carbon goals and China's GB standards for intelligent buildings are forcing asset owners to retrofit legacy systems with monitored energy infrastructure. SAMR enforcement of service quality benchmarks and local fire safety bureaus shape procurement criteria for outsourced management contracts. Stakeholders must weigh capital deployment toward predictive maintenance platforms against the operational risk of delayed compliance upgrades.
Market Dynamics
MIIT's dual carbon mandates are compressing retrofit timelines for legacy commercial assets across Shanghai and Beijing, forcing facility operators to prioritize monitored energy infrastructure over reactive maintenance models.
Growth Catalysts
- GB standards for intelligent buildings:Compliance thresholds for HVAC automation and sensor integration are mandating monitored infrastructure upgrades across state-owned commercial portfolios.
- Healthcare and education sectors:Institutional buyers are consolidating vendor relationships under long-term integrated service contracts spanning soft and hard facility services.
- IoT-enabled predictive maintenance:Sensor networks for equipment health monitoring are reducing unplanned downtime in tier-one city commercial properties.
Market Restraints
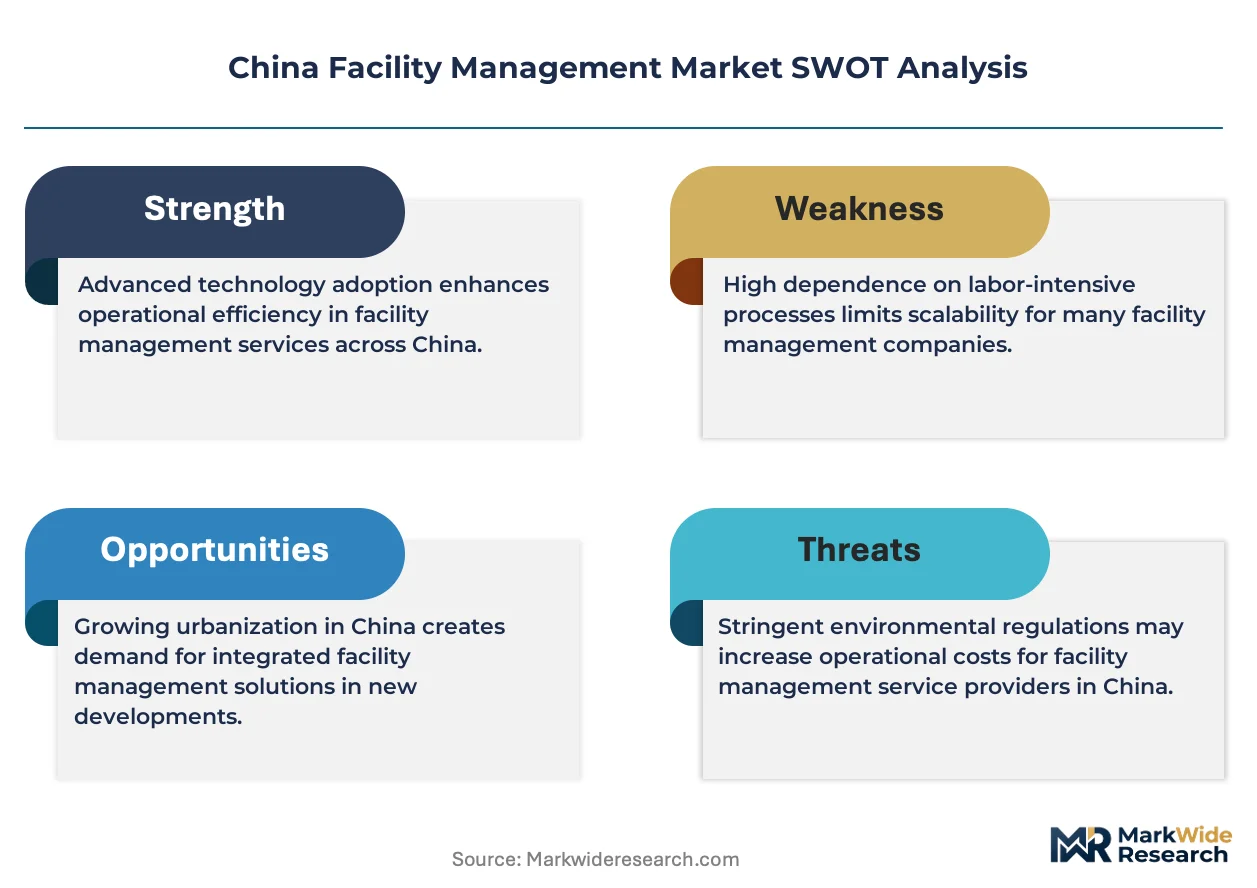
- Copper and semiconductor input costs:HVAC control systems and sensor hardware face margin pressure from volatile raw material pricing.
- Domestic software platform concentration:Smart building operating systems rely on a narrow base of local developers with limited interoperability standards.
- Legacy system technical debt:Pre-2015 building automation architectures lack API compatibility with modern IoT monitoring stacks.
Strategic Opportunities
- Greater Bay Area underpenetration:Shenzhen and Guangzhou commercial assets show lower outsourced facility management penetration than Shanghai or Beijing.
- Carbon accounting service bundling:MIIT dual carbon reporting requirements create white space for energy compliance as a subscription service layer.
- Edge computing and digital twin convergence:Real-time building simulation paired with localized data processing enables autonomous HVAC optimization.
Industry Challenges
- Certified building automation engineer scarcity:GB standards-compliant system integration requires specialized technicians in short supply across tier-two cities.
- Multi-vendor platform integration complexity:Disparate HVAC, security, and energy software stacks create data silos that degrade predictive analytics performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Facility Management Market |
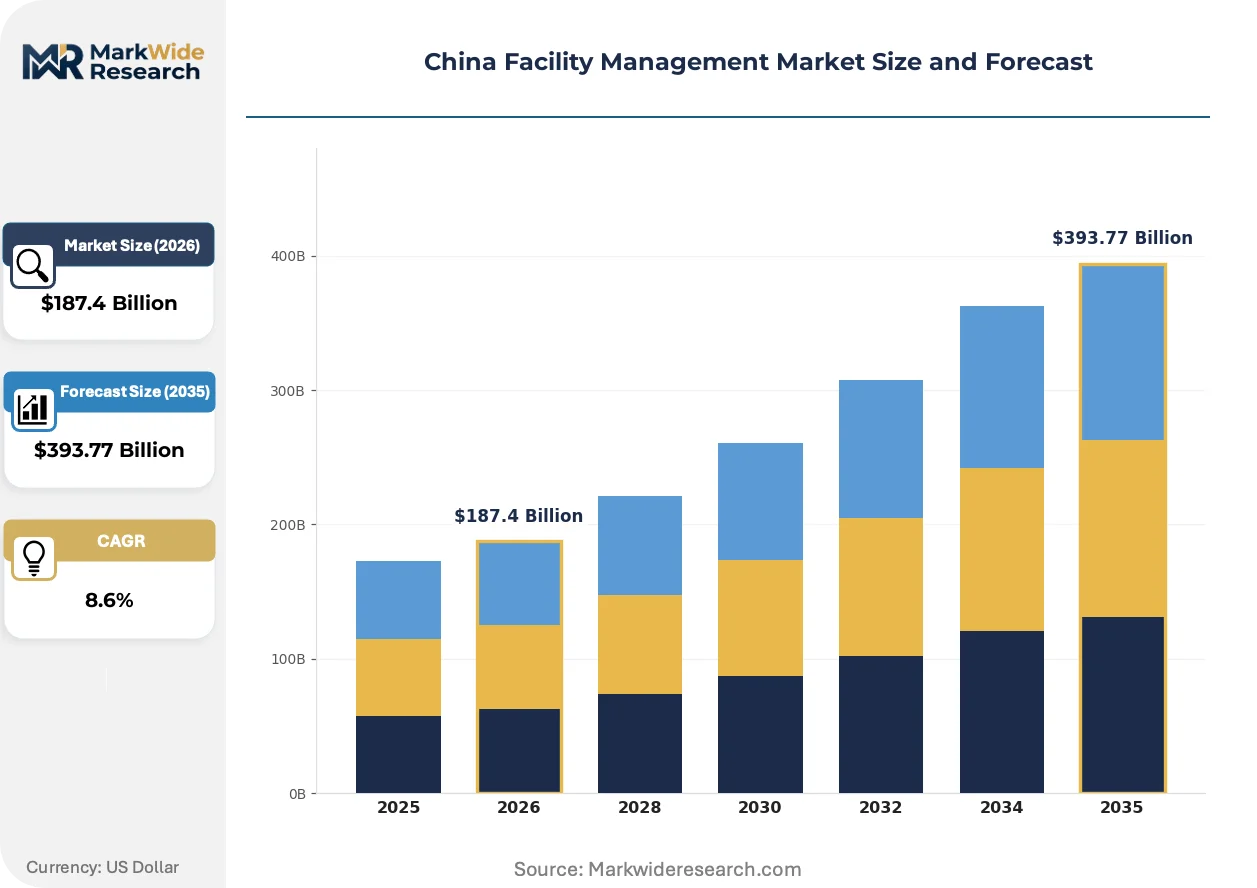
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $393.77 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning Services, Security Services, HVAC Management, Landscaping End User: Commercial Buildings, Residential Complexes, Hospitals, Educational Institutions Technology: IoT Solutions, Automation Systems, Energy Management Software, Smart Monitoring Contract Type: Annual Maintenance, On-Demand Services, Integrated Solutions, Outsourced Management |
| Companies Covered | Aeon Delight Co., Ltd., Onewo Space-Tech Service Co., Ltd, Leadec Industrial Services (Shanghai) Co., Ltd., ISS Group, China Shine, Sodexo China, CBRE, Aden Group, ESG Holdings Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Facility Management Market Emerging Trajectories
Facility management technology stacks are pivoting from centralized building management systems toward distributed sensor networks and autonomous control loops that compress response latency.
Wireless IoT sensor arrays for temperature, occupancy, and air quality monitoring are miniaturizing. Commercial property operators in Shanghai and Beijing are deploying these devices at density levels tenfold higher than legacy wired systems. The form factor reduction is miniaturizing installation costs and enabling retrofits in heritage buildings previously excluded from smart infrastructure.
MIIT's dual carbon goals and GB 50378 green building standards are tightening energy disclosure requirements for assets over 20,000 square meters. Asset owners must install monitored consumption infrastructure or face procurement disqualification from state-linked tenants. Premium commercial developments in Pudong and Chaoyang districts are responding by embedding sub-metering networks during pre-leasing phases.
Buyer procurement patterns are compressing vendor evaluation cycles from annual RFPs to continuous performance benchmarking. Institutional landlords in Shenzhen are unbundling long-term facility contracts into modular service tiers with quarterly reallocation rights. This shift is most visible in healthcare and education verticals where SAMR service quality benchmarks provide objective switching triggers.
China Facility Management Market Segmentation
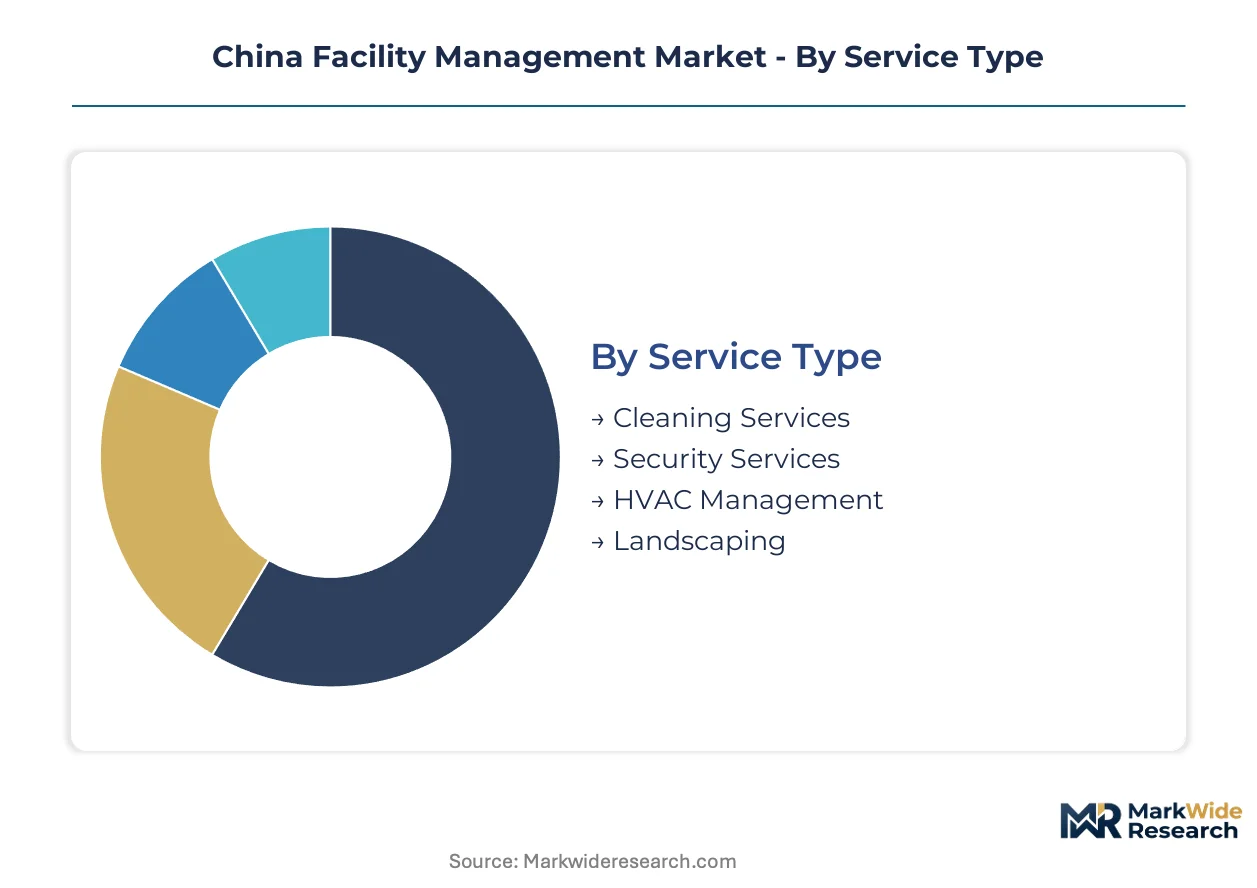
Facility management procurement in China fragments across service intensity, asset class, and technology sophistication. MIIT's dual carbon mandates and GB standards for intelligent buildings are compressing vendor selection criteria toward integrated, monitored solutions rather than discrete service bundles.
Service Type:
MIIT energy disclosure rules and SAMR service quality benchmarks differentiate procurement thresholds across hard versus soft service categories.
- HVAC Management:Climate control infrastructure combining chiller plants, air handling units, and zone-level temperature regulation. Shanghai and Beijing state-owned commercial portfolios are mandating sensor-enabled HVAC retrofits under GB standards compliance deadlines. This segment commands the deepest margin pools as energy efficiency penalties escalate.
- Security Services:Physical access control, surveillance systems, and manned guarding for asset protection. Demand concentrates in Pudong and Chaoyang premium commercial developments where institutional landlords bundle security with building automation under integrated contracts.
- Cleaning Services:Janitorial and hygiene maintenance for commercial and institutional properties.
- Landscaping:Exterior grounds maintenance and green space management for residential and commercial assets.
HVAC Management handles the majority of throughput; Smart Monitoring is gaining share fastest on technology convergence.
End User:
Asset ownership structure determines contract tenure and service bundling preferences across China's tier-one city clusters.
- Commercial Buildings:Office towers, retail centers, and mixed-use developments requiring 24/7 operational continuity. Shenzhen and Guangzhou commercial assets show lower outsourced penetration than Shanghai or Beijing, creating expansion headroom for integrated facility operators.
- Hospitals:Healthcare facilities with stringent infection control and equipment uptime requirements. SAMR enforcement of service quality benchmarks drives long-term vendor relationships with specialized healthcare facility managers.
- Residential Complexes:High-rise apartment developments and gated communities requiring property management services.
- Educational Institutions:Schools and universities with seasonal occupancy patterns and safety compliance needs.
Commercial Buildings anchor contract volume; Hospitals are climbing the fastest on regulatory intensity.
Technology:
Capital deployment patterns separate legacy building management system operators from sensor-native platform providers.
- Smart Monitoring:Real-time sensor networks for equipment health, occupancy, and environmental quality tracking. Wireless IoT sensor arrays are miniaturizing installation costs and enabling heritage building retrofits previously excluded from smart infrastructure.
- IoT Solutions:Connected device ecosystems for predictive maintenance and autonomous control loops. Tier-one city commercial properties are deploying these devices at density levels tenfold higher than legacy wired architectures.
- Energy Management Software:Consumption analytics platforms for carbon accounting and efficiency optimization.
- Automation Systems:Building control protocols for HVAC, lighting, and security integration.
Smart Monitoring captures the steepest expansion trajectory; Energy Management Software is the fastest mover on MIIT dual carbon reporting requirements.
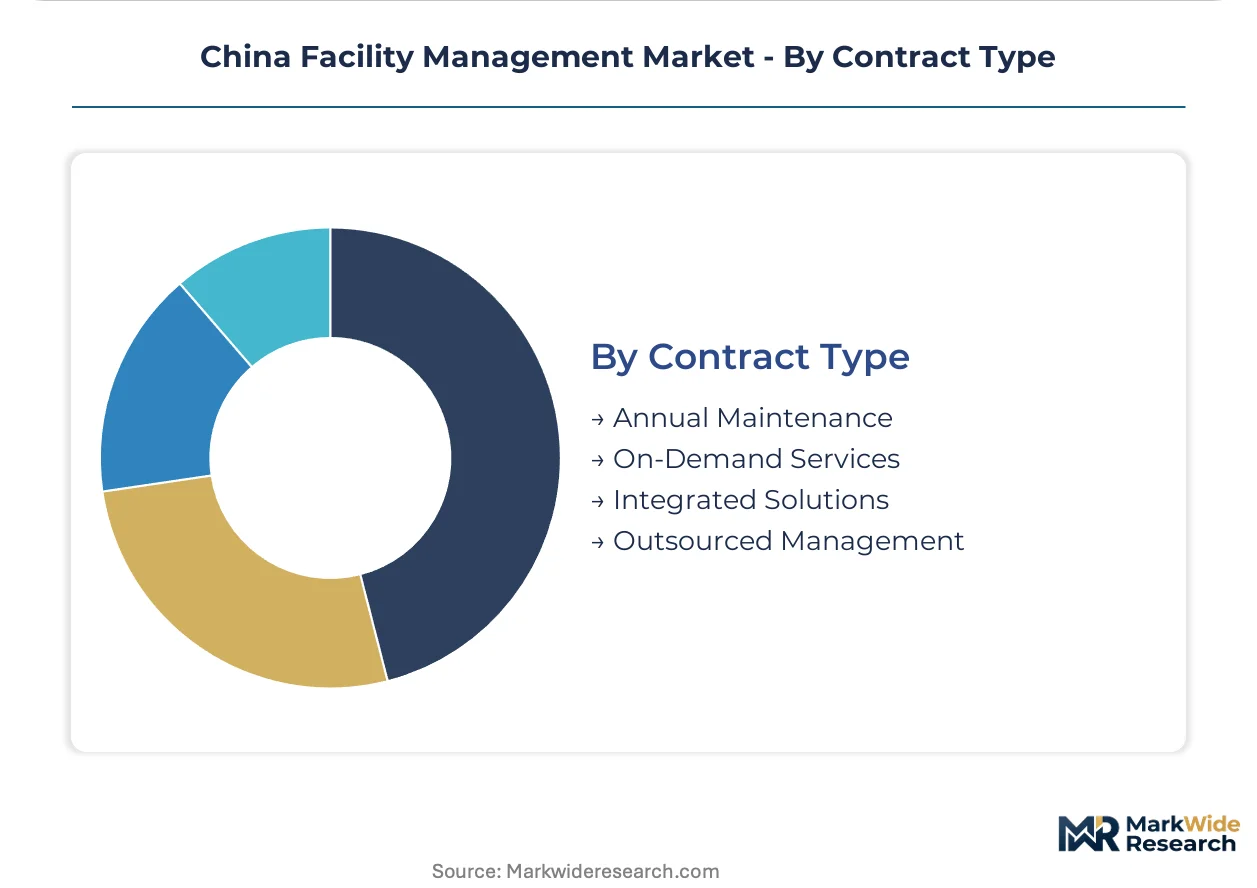
Contract Type:
Procurement modality determines vendor switching costs and performance accountability mechanisms.
- Integrated Solutions:Bundled hard and soft services under unified performance metrics and single-point accountability. Institutional buyers in healthcare and education are consolidating vendor relationships under these long-term structures.
- Outsourced Management:Third-party assumption of full facility operations for asset owners. State-owned commercial portfolios in Shanghai and Beijing are expanding these arrangements as internal technical capabilities lag GB standards compliance requirements.
- Annual Maintenance:Scheduled preventive service contracts for equipment upkeep.
- On-Demand Services:Reactive, transaction-based service requests with limited pricing power.
Integrated Solutions dominate value capture; Outsourced Management is expanding most quickly on state portfolio restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility management procurement intensity varies sharply across Chinese metropolitan clusters. Beijing and Shanghai prioritize integrated smart building compliance under MIIT mandates, while southern cities lag in outsourced penetration but accelerate faster on greenfield developments.
Beijing-Tianjin-Hebei
State-owned commercial portfolios in Chaoyang and Haidian districts are mandating sensor-enabled HVAC retrofits under GB standards compliance deadlines. SAMR enforcement of service quality benchmarks drives procurement consolidation toward integrated facility operators. The Beijing municipal government requires sub-metering networks in assets exceeding 20,000 square meters.
Yangtze River Delta
Shanghai's Pudong Lujiazui financial district anchors premium commercial contract volume with 24/7 operational continuity requirements. MIIT dual carbon disclosure rules compress vendor selection cycles toward monitored energy infrastructure providers. Suzhou and Hangzhou satellite cities are replicating Shanghai's integrated service bundling models for technology park developments.
Pearl River Delta
Shenzhen and Guangzhou commercial assets show lower outsourced facility management penetration than northern tier-one cities, creating expansion headroom. Guangdong provincial energy efficiency regulations are tightening disclosure thresholds for commercial buildings over 15,000 square meters. Qianhai Shenzhen-Hong Kong Cooperation Zone developments are embedding smart monitoring infrastructure during pre-leasing phases.
Sichuan-Chongqing
Western China's fastest-growing commercial hub concentrates healthcare and education facility contracts under long-term integrated structures. Chongqing municipal fire safety bureaus shape procurement criteria for outsourced management in hospital complexes. Chengdu's Tianfu New Area is deploying IoT-enabled predictive maintenance platforms in government-leased office towers.
Shandong Peninsula
Qingdao and Jinan manufacturing corridor demand blends industrial facility services with commercial property management. Shandong provincial GB standards implementation lags coastal tier-one cities by 18-24 months, extending retrofit windows for legacy system upgrades. Yantai port zone logistics facilities are piloting edge computing networks for autonomous HVAC optimization.
China Facility Management Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in China's facility management structure. Multinational property service protocols anchor premium commercial contracts in tier-one cities, while domestic technology platforms compete through vertical control over smart building software stacks. Three archetypes dominate: global real estate service conglomerates, state-linked integrated operators, and sensor-native technology specialists. Competitive positioning hardens around M&A-driven geographic expansion and proprietary IoT platform development.
Within the multinational tier, CBRE exemplifies global protocol adaptation for Chinese premium commercial assets. Sodexo China occupies a position anchoring long-term institutional relationships across healthcare and education verticals. Onewo Space-Tech Service represents the domestic technology-integrated archetype with captive smart building hardware and software capabilities. These three players illustrate the competitive tension between foreign expertise premiums and local technology sovereignty in contract procurement.
| Leading Market Players |
|---|
| Aeon Delight Co., Ltd. |
| Onewo Space-Tech Service Co., Ltd |
| Leadec Industrial Services (Shanghai) Co., Ltd. |
| ISS Group |
| China Shine |
| Sodexo China |
| CBRE |
| Aden Group |
| ESG Holdings Limited |
| Others |
Supply Flow & Price Mechanics
Scale economies in sensor hardware manufacturing compress unit costs for IoT-enabled HVAC monitoring systems, concentrating supply leverage among domestic platform operators while establishing price floors for integrated facility service bundles. MIIT dual carbon compliance deadlines force asset owners toward monitored infrastructure procurement, amplifying pricing power for vendors with captive smart building software stacks.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions generate lifetime value multiples exceeding hardware installation revenue. Three-tier pricing structure across premium, standard, and economy levels separates state-owned commercial portfolios with compliance mandates from fragmented residential complexes with limited procurement sophistication. Pricing pressure stems from volatile copper and semiconductor input costs eroding margins on HVAC control systems. Price-sensitive buyers cluster in on-demand service tiers with transactional procurement patterns, while integrated solution adopters in healthcare and education verticals prioritize performance accountability over unit cost.
Supply Chain Analysis
Strategic stockpiling of copper and semiconductor components dominates inventory strategy as volatile raw material pricing disrupts HVAC control system production schedules. Manufacturing concentration centers on China for sensor hardware assembly, South Korea for semiconductor components, and Germany for precision automation equipment. Raw material dependencies span copper for electrical infrastructure, semiconductors for IoT control boards, and rare earth elements for sensor magnetics. Single-source vulnerability in domestic software platform concentration creates interoperability risks across multi-vendor building automation deployments. Distribution runs through direct vendor relationships with state-owned commercial portfolios and tier-one city institutional landlords, bypassing fragmented channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China facility management represents a service-attach opportunity where recurring-revenue layers from predictive maintenance subscriptions and carbon accounting compliance services expand faster than discrete hardware installation contracts.
For Market Incumbents: Consolidate vendor relationships across state-owned commercial portfolios in Shanghai and Beijing by embedding proprietary IoT platforms during GB standards-mandated retrofits. Acquire certified building automation engineering capabilities in tier-two cities to preempt scarcity-driven margin compression. Defend against sensor-native technology specialists through backward integration into smart building hardware production. For New Entrants and Emerging Players: Anchor in Greater Bay Area commercial assets where outsourced facility management penetration trails northern tier-one cities. Target Shenzhen and Guangzhou greenfield developments with edge computing and digital twin capabilities for autonomous HVAC optimization. Pursue carbon accounting service bundling as a differentiated entry wedge under MIIT dual carbon reporting requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among domestic technology-integrated operators with captive smart building software and hardware capabilities. Long-term viability across the projection horizon hinges on proprietary platform development and M&A-driven geographic expansion. Acquisition targets should demonstrate vertical control over sensor-native technology stacks with established institutional relationships in healthcare or education verticals. The signal to watch is quarterly vendor reallocation rights adoption among Shenzhen institutional landlords as an indicator of procurement modality inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies HVAC, security, and energy software stacks under single data architecture for predictive analytics performance. |
| Geographic Expansion | Extends integrated service bundling models from Shanghai-Pudong into underpenetrated Shenzhen-Guangzhou commercial corridors. |
| Acquisition of Specialist Firm | Captures certified building automation engineering capabilities scarce across tier-two city labor markets. |
| Strategic Partnership | Aligns with state-owned portfolio managers under long-term outsourced management contracts with single-point accountability. |
| Product Launch | Deploys wireless IoT sensor arrays miniaturized for heritage building retrofits previously excluded from smart infrastructure. |
Methodological Framework
Cross-validation between facility management procurement directors and secondary regulatory filings anchors the qualitative findings on MIIT dual carbon compliance timelines. Primary interviews with building automation engineers, state-owned asset managers, healthcare facility directors, and smart building software developers combined with secondary validation from SAMR enforcement records, GB standards documentation, and municipal energy disclosure databases. Bottom-up service contract aggregation and top-down market sizing triangulation produced convergent estimates across the analysis window.
Sensitivity analysis on copper and semiconductor input cost volatility informs margin compression scenarios for HVAC control system providers. Segmentation dimensions modeled include service type intensity, asset ownership structure, technology deployment sophistication, and contract modality preferences. CAGRs derive from installed base expansion rates and technology substitution curves for legacy building management systems. Forecast inputs incorporate MIIT dual carbon mandate enforcement intensity and GB standards compliance deadline acceleration patterns.
Decision-makers should treat outputs as directional under assumptions of sustained MIIT dual carbon policy enforcement and stable state-owned portfolio restructuring momentum; material deviation would warrant model refresh. Revision becomes warranted when domestic software platform interoperability standards cross adoption thresholds enabling multi-vendor integration at scale.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Soft Facility Management Market
Facility Management
Central and Eastern Europe (CEE) Facility Management Market
Facility Management
Indonesia Facility Management Market
Facility Management
Hong Kong Facility Management Market
Facility Management
Brazil Facility Management Market
Facility Management
Bahrain Facility Management Market
Facility Management
Belgium Facility Management Market
Facility Management
Canada Facility Management Market
Facility Management
Italy Facility Management Services Market
Facility Management
Vietnam Facility Management Market
Facility Management
Slovenia Facility Management Market
Facility Management
Denmark Facility Management Market
Facility Management
United Kingdom (UK) Facility Management Market
Facility Management
Latin America Soft Facility Management Market
Facility Management
Panama Facility Management Market
Facility Management
Netherlands Facility Management Market