
 Belgium Facility Management Market | 2026-2036
Belgium Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Belgium Facility Management Market Analysis
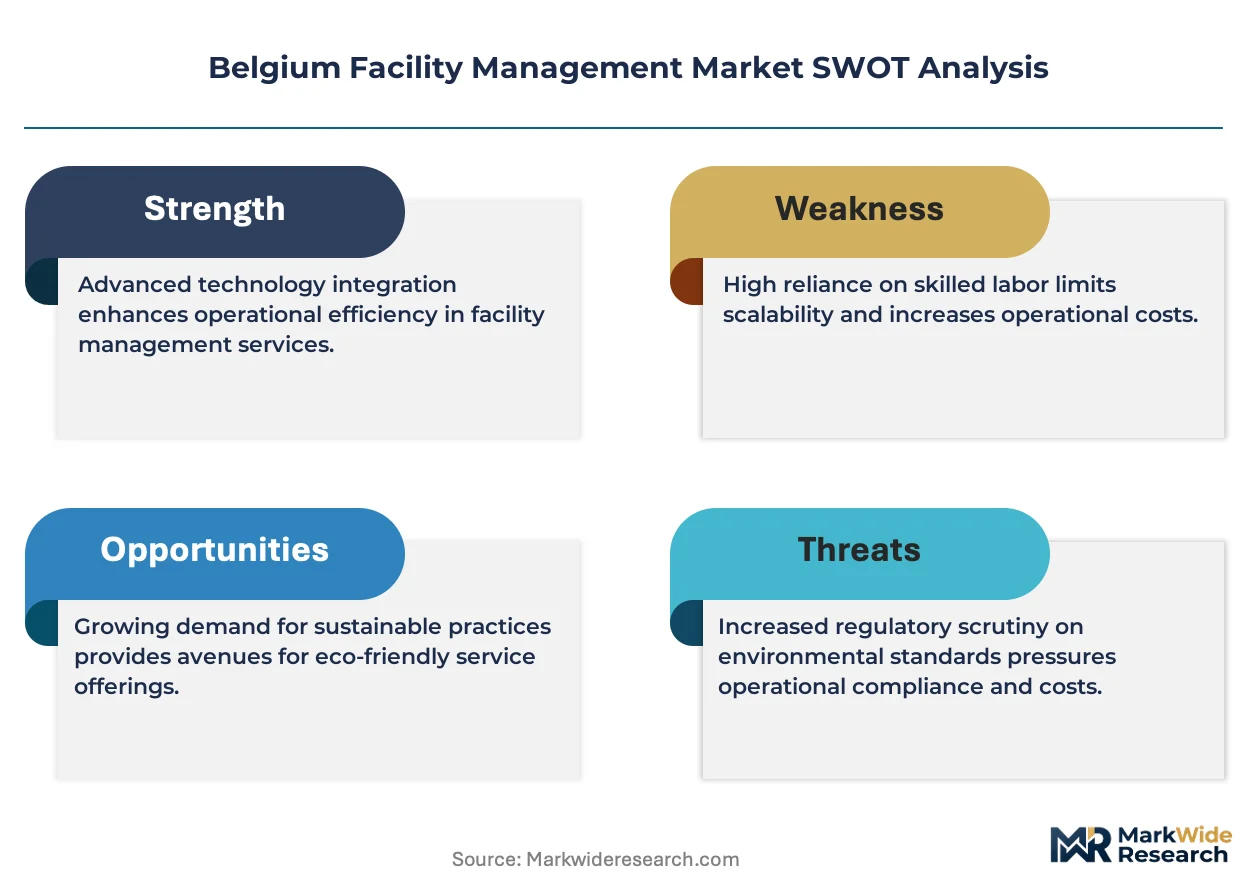
A widening capability gap between asset-heavy integrated providers and service-only contractors is reorganizing competitive dynamics across Belgium's facility management landscape. SPIE Belgium leverages its technical engineering heritage to anchor large infrastructure contracts in the public sector. Facilicom Solutions specializes in sustainable cleaning and maintenance protocols that differentiate its positioning with healthcare and educational clients. CBRE Belgium competes through property management technology platforms that extend its reach into workplace management advisory.
Facility management encompasses the coordination of physical workplace maintenance, operational support services, and asset lifecycle optimization across built environments, typically governed by service level agreements specifying response times, uptime thresholds, and energy performance benchmarks. Its primary purpose centers on reducing total cost of ownership for real estate portfolios while ensuring regulatory compliance and occupant productivity. Cleaning services and maintenance services constitute mature revenue pools with thin margins, while IoT solutions and energy management systems represent faster-growing segments where technology providers capture disproportionate value. Security services remain resilient across the Brussels-Capital Region due to elevated threat assessments for institutional clients.
Belgium's facility management sector operates under the EU Green Deal framework, the national transposition of the Energy Performance of Buildings Directive, and regional Flemish, Walloon, and Brussels environmental permitting regimes that mandate building renovation passports and operational carbon reporting. These regulations shape procurement criteria, forcing facility managers to certify energy performance and embed monitoring systems to retain public and commercial contracts. Stakeholders must decide whether to build in-house digital capabilities or partner with technology vendors as compliance complexity intensifies.
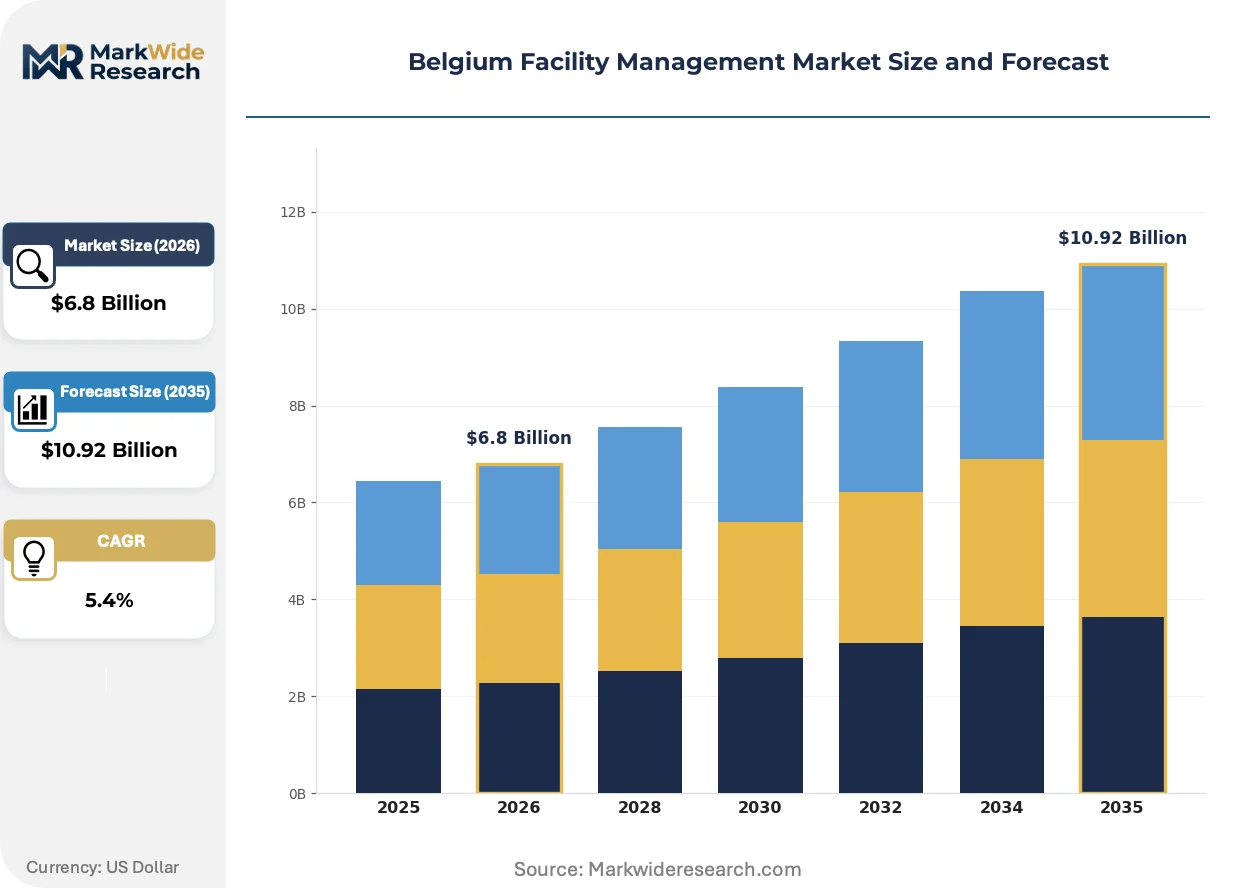
Market Dynamics
The EU Energy Performance of Buildings Directive transposition is forcing Belgian facility managers to embed integrated energy monitoring systems or forfeit public sector contracts. This regulatory compression is accelerating vendor consolidation as compliance complexity outstrips the capabilities of service-only contractors.
Growth Catalysts
- Healthcare infrastructure aging:Flanders hospitals require specialized maintenance protocols for obsolete HVAC and electrical systems, creating sustained demand for technical engineering services.
- EU Green Deal framework:Operational carbon reporting mandates under the national EPBD transposition require building renovation passports, expanding the addressable market for energy management system providers.
- Brussels-Capital density:Concentrated commercial real estate portfolios in the capital region generate economies of scale for centralized facility oversight platforms.
Market Restraints
- Skilled technician scarcity:Belgium's technical vocational pipeline produces insufficient certified building automation specialists to meet retrofit demand.
- Input cost volatility:Copper and semiconductor price fluctuations destabilize margins for IoT hardware deployment in energy monitoring infrastructure.
- Regulatory fragmentation:Divergent Flemish, Walloon, and Brussels environmental permitting regimes multiply compliance overhead for national contract bidders.
Strategic Opportunities
- Walloon industrial retrofits:Underpenetrated manufacturing facility stock in the southern region offers first-mover advantage for integrated energy-service companies.
- Security-technology convergence:Elevated threat assessments for Brussels institutional clients create cross-selling potential between physical security and building management systems.
- Workplace advisory extension:Property management platforms that incorporate occupancy analytics capture higher-margin advisory relationships beyond transactional maintenance.
Industry Challenges
- Digital competency gaps:Mid-sized contractors lack in-house data science capabilities to interpret sensor-generated building performance metrics.
- Legacy system integration:Proprietary protocols in existing building automation infrastructure obstruct seamless IoT platform deployment.
- Certification timeline compression:Accelerated EPBD compliance deadlines strain workforce training capacity for energy auditor credentials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belgium Facility Management Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning Services, Maintenance Services, Security Services, Landscaping Services End User: Commercial Buildings, Educational Institutions, Healthcare Facilities, Public Sector Technology: Computerized Maintenance Management Systems, IoT Solutions, Energy Management Systems, Security Monitoring Systems Application: Property Management, Asset Management, Space Management, Workplace Management |
| Companies Covered | SPIE Belgium, Facilicom Solutions, ISS World Belgium, ATALIAN Global Services Belgium, Vinci Facilities Limited Belgium, Sodexo Belgium, Equans, Serco Europe, CBRE Belgium, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belgium Facility Management Market Emerging Trajectories
Technology diffusion and regulatory tightening are compressing the traditional facility management value chain. Vendors must now deliver measurable energy outcomes rather than scheduled maintenance inputs.
IoT-enabled predictive maintenance is bifurcating the service market. Sensor networks monitoring HVAC vibration and electrical load patterns enable failure anticipation before downtime occurs. Large infrastructure operators in the public sector are adopting these systems rapidly, while smaller commercial portfolios lag. This capability gap is compressing margins for reactive maintenance providers and concentrating contract value with technology-integrated vendors.
Belgium's transposition of the EU Energy Performance of Buildings Directive mandates operational carbon reporting for commercial buildings above specified thresholds. The industrial consequence is procurement criteria that weight verified energy performance above unit cost in contractor selection. Healthcare and educational facilities face the steepest compliance curves, driving accelerated adoption of building renovation passports and continuous monitoring infrastructure.
Facility management purchasing is consolidating through framework agreements that bundle hard services, soft services, and energy advisory under single-provider accountability. This displaces fragmented multi-vendor arrangements common in older commercial leases. Brussels-Capital Region property portfolios exhibit the most advanced consolidation, with institutional investors demanding unified service level agreements spanning cleaning, maintenance, and carbon performance.
Belgium Facility Management Market Segmentation
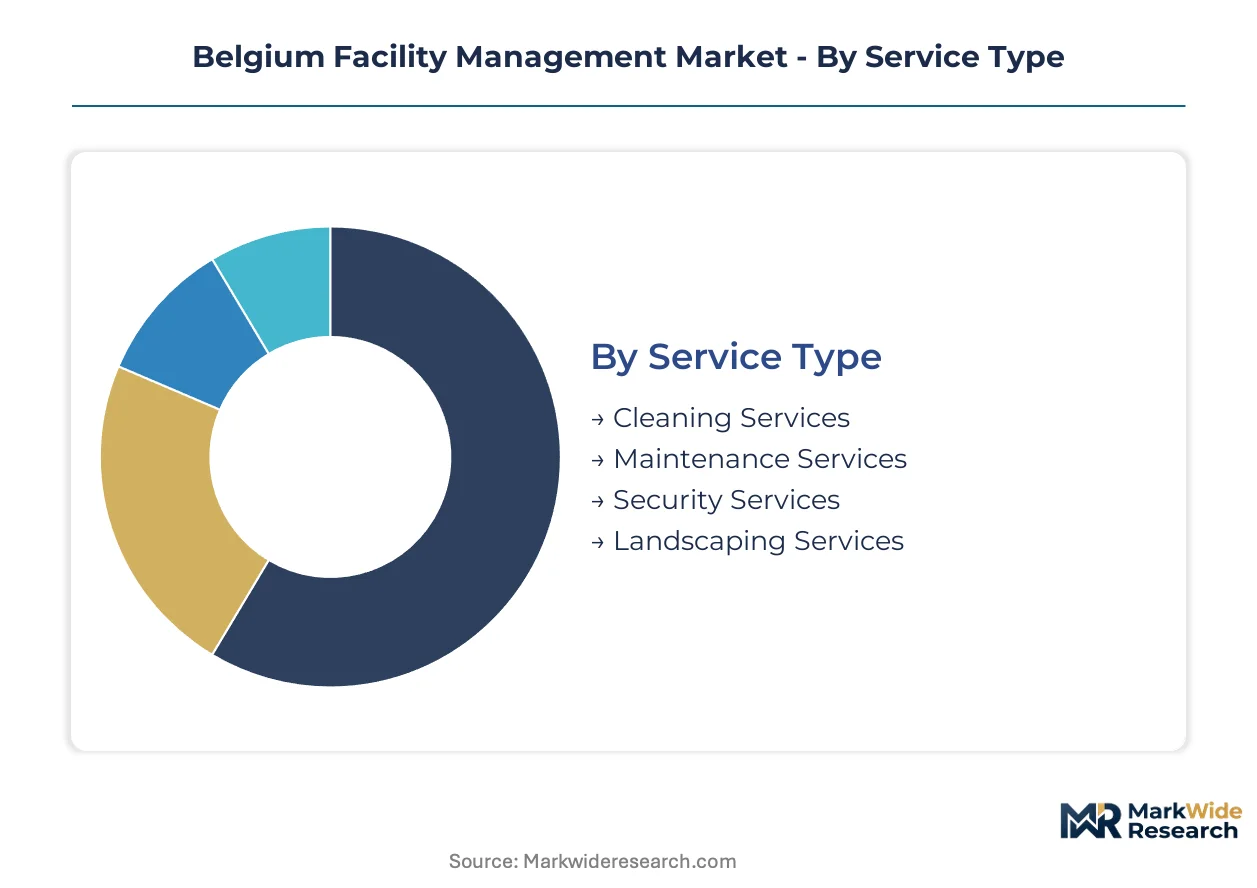
Segmentation reveals how regulatory pressure and technology diffusion redistribute value across Belgium's facility management landscape. Service providers must align portfolio composition with where compliance mandates concentrate demand and where digital capabilities unlock pricing power.
Service Type:
Margin pools concentrate in specialized technical services where certification barriers limit competition, while commoditized segments face procurement compression.
- Cleaning Services:Mature segment characterized by labor-intensive operations and thin margins. Demand concentrates in Brussels-Capital healthcare and educational facilities where infection control protocols and sustainability certifications drive contractor selection criteria.
- Maintenance Services:Technical engineering services spanning HVAC, electrical, and mechanical systems. Flanders hospitals generate sustained demand for specialized retrofit expertise as aging infrastructure requires obsolete system rehabilitation under EPBD compliance timelines.
- Security Services:Physical guarding and technology-enabled surveillance. Brussels institutional clients sustain premium pricing through elevated threat assessments and regulatory requirements for critical infrastructure protection.
- Landscaping Services:Grounds maintenance and exterior aesthetics management. Municipal contracts in Walloon industrial zones and Flemish commercial parks provide stable recurring revenue with lower technology integration requirements.
The dominant share belongs to Maintenance Services, while Security Services is closing the gap fastest.
End User:
Procurement sophistication varies sharply across end-user categories, with public sector frameworks demanding integrated service delivery that smaller contractors cannot satisfy.
- Commercial Buildings:Dense Brussels-Capital portfolios drive centralized facility oversight adoption. Institutional investors demand unified service level agreements spanning operational performance and carbon reporting metrics.
- Healthcare Facilities:Flanders hospitals require specialized maintenance protocols for obsolete HVAC and electrical infrastructure. EPBD transposition mandates building renovation passports and continuous energy monitoring, expanding addressable market for technical service providers.
- Educational Institutions:Schools and universities with distributed campus footprints. Budget constraints limit technology adoption, though EU Green Deal funding accelerates energy retrofit programs in publicly funded institutions.
- Public Sector:Government buildings and infrastructure under federal, regional, and municipal ownership. Framework agreements bundle hard services, soft services, and energy advisory under single-provider accountability, displacing fragmented multi-vendor arrangements.
Commercial Buildings command the largest contract value, though Healthcare Facilities is expanding most quickly under regulatory compliance pressure.
Technology:
Value capture concentrates in platforms that translate sensor data into measurable energy outcomes rather than hardware deployment alone.
- Computerized Maintenance Management Systems:Software platforms scheduling preventive maintenance and asset tracking. Mid-sized contractors face digital competency gaps interpreting performance metrics, creating partnership opportunities with specialized vendors.
- IoT Solutions:Sensor networks monitoring equipment vibration, electrical load, and environmental conditions. Predictive failure anticipation compresses margins for reactive maintenance providers while concentrating contract value with technology-integrated vendors.
- Energy Management Systems:Integrated platforms for operational carbon reporting and continuous performance optimization. EPBD compliance mandates expand addressable market as building renovation passports become procurement prerequisites.
- Security Monitoring Systems:Technology convergence between physical security and building management infrastructure. Brussels institutional demand creates cross-selling potential for integrated platform providers serving elevated threat assessment environments.
Energy Management Systems holds the dominant technology position, while IoT Solutions is gaining share fastest through predictive maintenance adoption.
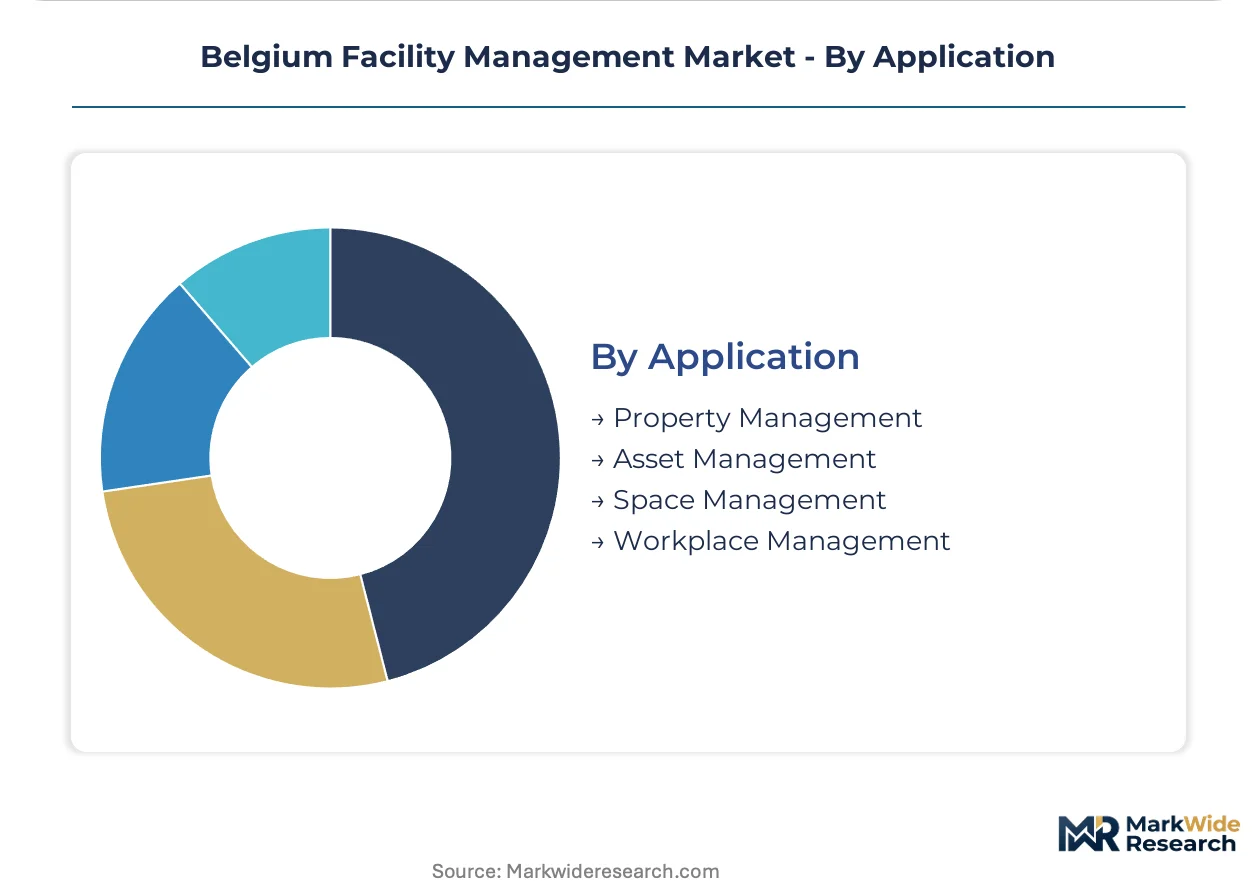
Application:
Service integration depth determines pricing power, with advisory relationships commanding premiums above transactional maintenance.
- Property Management:Comprehensive oversight of building operations, tenant services, and financial performance. Brussels-Capital commercial portfolios exhibit most advanced consolidation through unified service level agreements.
- Asset Management:Lifecycle optimization of physical infrastructure and capital planning. Public sector frameworks increasingly weight total cost of ownership against unit pricing in contractor evaluation.
- Space Management:Occupancy analytics and utilization optimization. Workplace advisory extension captures higher-margin relationships as hybrid work patterns demand flexible environment configuration.
- Workplace Management:End-user experience and productivity-focused service delivery. Technology platforms incorporating occupancy analytics differentiate positioning beyond traditional maintenance inputs.
Property Management retains the largest application share, while Workplace Management is climbing the fastest on advisory service expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brussels-Capital Region commands premium pricing for integrated facility oversight, while Wallonia's industrial zones trade at cost-plus benchmarks due to fragmented demand. This asymmetry shapes vendor investment priorities across Belgium's three linguistic regions.
Brussels-Capital Region
Dense commercial real estate portfolios generate economies of scale for centralized facility management platforms. The regional government mandates building renovation passports for structures exceeding specified energy thresholds. Institutional investors in the European Quarter demand unified service level agreements spanning carbon reporting and operational performance.
Flanders
Aging healthcare infrastructure in Antwerp and Ghent drives specialized maintenance demand for obsolete HVAC systems. The Flemish Energy and Climate Agency enforces operational carbon reporting timelines that accelerate technology adoption. Port of Antwerp-Bruges industrial complexes require integrated energy-service contracts for chemical and logistics facilities.
Wallonia
Underpenetrated manufacturing stock in Liège and Charleroi offers first-mover positioning for energy retrofit specialists. Walloon environmental permitting regimes diverge from Flemish standards, multiplying compliance overhead. Sambre-Meuse industrial corridor hosts automotive and steel facilities seeking building automation upgrades under EU Green Deal funding.
Belgium Facility Management Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across Belgium's facility management sector. Asset-heavy integrated providers capture large infrastructure contracts through engineering capabilities, while service-only contractors compete on unit pricing for commoditized cleaning and maintenance. Three archetypes dominate: technical engineering specialists, sustainable service protocol providers, and property management technology platforms. Vendor consolidation accelerates as compliance complexity outstrips smaller contractor capabilities, with framework agreements displacing fragmented multi-vendor arrangements.
Among Belgium-based technical service providers, SPIE Belgium anchors public sector infrastructure contracts through its engineering heritage. Facilicom Solutions occupies a position within the sustainable service tier, differentiating through cleaning and maintenance protocols for healthcare and educational clients. CBRE Belgium exemplifies the technology-platform archetype, extending property management systems into workplace advisory relationships. These three represent the strategic positioning vectors—engineering depth, sustainability certification, and digital platform integration—that define competitive differentiation in procurement decisions.
| Leading Market Players |
|---|
| SPIE Belgium |
| Facilicom Solutions |
| ISS World Belgium |
| ATALIAN Global Services Belgium |
| Vinci Facilities Limited Belgium |
| Sodexo Belgium |
| Equans |
| Serco Europe |
| CBRE Belgium |
| Others |
Supply Flow & Price Mechanics
Brussels-Capital Region economies of scale compress unit costs for centralized facility oversight platforms while elevating price floors for fragmented service-only contractors. The EU Green Deal compliance burden concentrates procurement power with integrated providers capable of certifying energy performance outcomes.
Pricing Analysis
Configured-to-order pricing for integrated energy management systems commands substantial premiums over standard maintenance service rates. Three-tier pricing structure across premium, standard, and economy levels stratifies the market: premium tiers bundle IoT-enabled predictive maintenance with carbon reporting compliance; standard tiers cover scheduled preventive maintenance; economy tiers address reactive break-fix services. Price differentiation rests on certification level under the EU Energy Performance of Buildings Directive and geographic delivery cost to Flanders healthcare clusters. Cost compression in economy-tier cleaning and maintenance intensifies because labor arbitrage limits and input cost volatility squeeze contractor margins. Public sector framework agreements exhibit lowest price sensitivity; small commercial property owners in Wallonia demonstrate highest sensitivity.
Supply Chain Analysis
Port congestion at Antwerp-Bruges and container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for IoT hardware components. Geographic supply concentration draws from China for sensor manufacturing, Germany for building automation controllers, and the Netherlands for integrated software platforms. Raw material dependencies center on copper for electrical infrastructure, semiconductors for edge computing devices, and lithium for backup power systems. Single-source vulnerability in specialized HVAC control modules poses structural risk for Flanders hospital retrofit timelines. Distribution runs through regional service hubs in Brussels, Ghent, and Liège with last-mile technician deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Belgium facility management sits in early-cycle expansion as EPBD transposition forces technology substitution across building stock with substandard energy performance. Regulatory compliance timelines compress adoption curves for integrated service providers.
For Market Incumbents: Fortify engineering capabilities in building automation integration to defend against technology-platform entrants capturing carbon reporting contracts. Secure backward integration into IoT sensor deployment to control hardware margins destabilized by semiconductor price volatility. Deepen certification pipelines for energy auditor credentials under Flemish, Walloon, and Brussels permitting regimes to maintain framework agreement eligibility.
For New Entrants and Emerging Players: Lead with specialized energy retrofit expertise targeting underpenetrated Walloon industrial manufacturing facilities in Liège and Charleroi. Capture first-mover positioning in Sambre-Meuse automotive and steel automation upgrades. Deploy workplace advisory services incorporating occupancy analytics to bypass entrenched maintenance relationships in Brussels commercial portfolios.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors asset-heavy integrated providers with captive engineering workforces over service-only contractors facing margin compression. Long-term viability centers on platforms translating sensor data into measurable energy outcomes rather than transactional maintenance inputs. Acquisition target archetype: regional technical specialists with EPBD certification infrastructure and established public sector relationships. Monitor EPBD compliance deadline acceleration as inflection indicator for vendor consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Energy Management System Integration | EPBD compliance mandates building renovation passports, expanding addressable market for certified providers. |
| Predictive Maintenance Platform Deployment | IoT sensor networks enable failure anticipation, concentrating contract value with technology-integrated vendors. |
| Workplace Advisory Service Extension | Occupancy analytics capture higher-margin relationships beyond transactional maintenance in Brussels portfolios. |
| Regional Certification Investment | Flemish, Walloon, and Brussels permitting regimes multiply compliance overhead, favoring multi-regional specialists. |
| Security-Technology Convergence | Elevated threat assessments for Brussels institutional clients create cross-selling between physical security and building management. |
Methodological Framework
Operator-level perspectives from facility directors, energy managers, procurement leads at institutional investors, and technical engineering heads anchored the qualitative base. Primary interviews combined with secondary validation from EU Energy Performance of Buildings Directive transposition documents, Flemish Energy and Climate Agency reports, Brussels-Capital environmental permitting records, and customs data on IoT hardware imports. Bottom-up service provider revenue aggregation triangulated against top-down building stock energy compliance modeling.
Sensitivity analysis tested forecast robustness across regulatory acceleration scenarios and input cost volatility assumptions. Segmentation dimensions modeled include service type, end-user category, technology platform, and application depth across the projection horizon. CAGRs derived from installed base expansion rates, replacement cycle compression, and technology substitution elasticities. Forecast inputs incorporated EPBD compliance timeline trajectories and healthcare infrastructure aging curves.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement or accelerated semiconductor supply normalization would require recalibration. Forecasts reflect documented assumptions regarding technology adoption rates and workforce training capacity. Specific risks that could revise projections include skilled technician scarcity deepening, copper price volatility exceeding historical bands, or divergent regional permitting timelines fragmenting national contract feasibility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Croatia Facility Management Market
Facility Management
Asia-Pacific Hard Facility Management Market
Facility Management
Japan Facility Management Market
Facility Management
United Kingdom (UK) Facility Management Market
Facility Management
Slovenia Facility Management Market
Facility Management
North America Soft Facility Management Market
Facility Management
Kuwait Facility Management Market
Facility Management
Global Unified Facility Management Market
Facility Management
Singapore Facility Management Market
Facility Management
United States Facility Management Market
Facility Management
Latvia Facility Management Market
Facility Management
Hungary Facility Management Market
Facility Management
Netherlands Facility Management Market
Facility Management
North America Hard Facility Management Market
Facility Management
Egypt Facility Management Market
Facility Management
Vietnam Facility Management Market