
 Netherlands Facility Management Market | 2026-2036
Netherlands Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Facility Management Market Outlook
The EU Green Deal is pivoting capital allocation across Dutch facility management as stricter building energy performance standards raise compliance costs for aging stock. CBRE Global Workplace Solutions leverages its integrated workplace platform to capture premium contracts in Amsterdam's financial district. Facilicom Group anchors its position through specialized healthcare cleaning protocols that exceed WIP standards. Vebego International BV differentiates via social enterprise labor models that align with Dutch municipal procurement criteria.
Facility management encompasses the coordinated oversight of physical building operations, maintenance, and support services through structured service delivery frameworks, typically governed by ISO 41011 standards for terminology and scope. Its primary commercial purpose is to optimize building lifecycle costs while ensuring occupant safety, comfort, and regulatory compliance across diverse property portfolios. Cleaning services dominate current revenue pools due to labor intensity and frequency requirements, while IoT Solutions represent the fastest-expanding technology segment as sensor networks enable predictive maintenance and real-time energy optimization. The outsourced delivery model leads transaction volume as Dutch corporations divest non-core real estate functions, though hybrid arrangements gain traction among mid-market tenants seeking flexibility.
CE marking requirements under the EU Construction Products Regulation shape material specifications for building retrofits, while Dutch Building Decree enforcement by the Ministry of the Interior and Kingdom Relations mandates energy label upgrades for commercial properties exceeding threshold sizes. The Netherlands Enterprise Agency (RVO) administers subsidy schemes that accelerate smart building technology adoption, directly influencing FM procurement priorities. Facility operators must monitor evolving CSRD disclosure obligations that will require granular reporting on building-level emissions and service supply chain impacts.
Market Dynamics
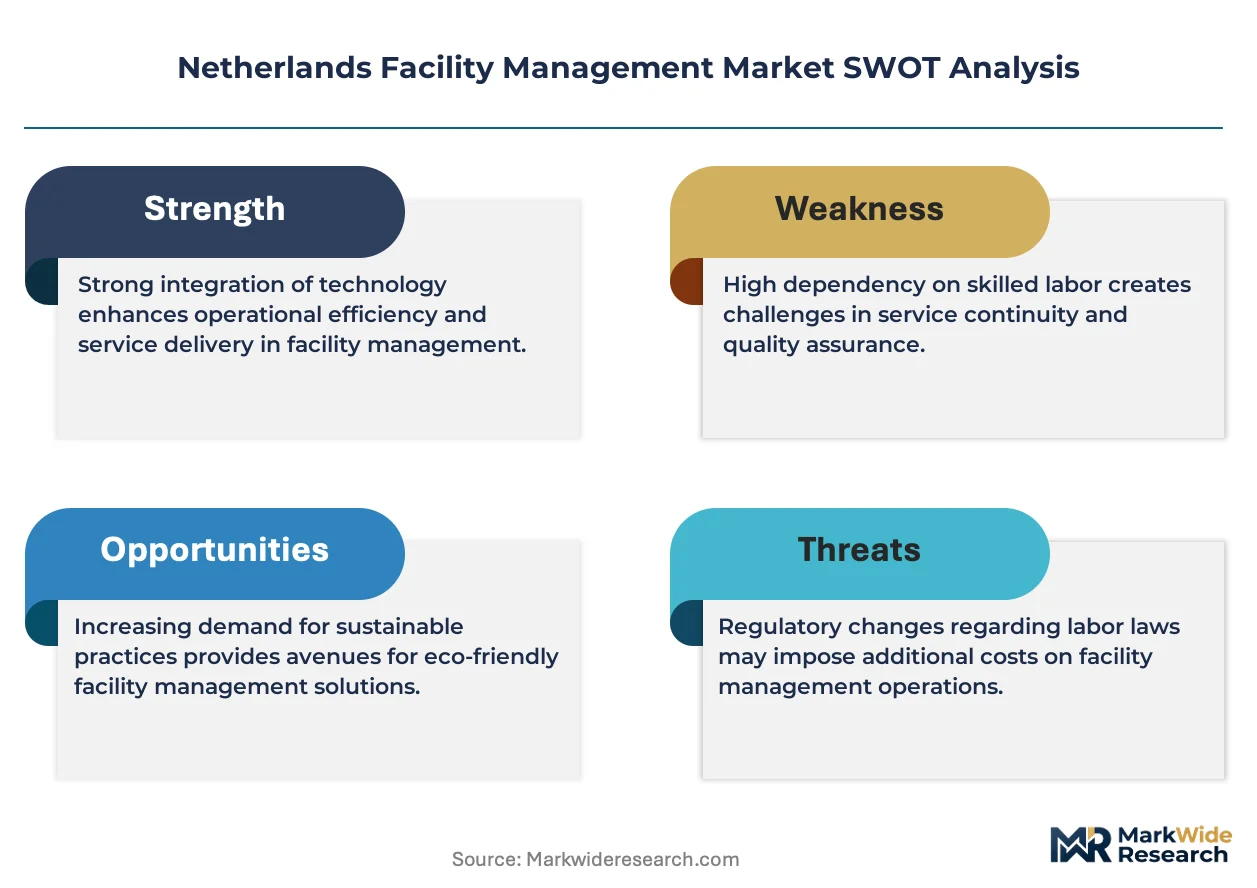
The EU Green Deal's escalating energy performance mandates are forcing Dutch commercial property owners into accelerated retrofit cycles, compressing FM contract renewal timelines and elevating technical capability requirements across the supplier base.
Growth Catalysts
- Healthcare outsourcing:Dutch hospitals are expanding integrated FM contracts to meet WIP hygiene protocols while offloading non-core asset management. Specialized cleaning and maintenance services capture premium pricing in this segment.
- Randstad commercial stock aging:Amsterdam, Rotterdam, The Hague and Utrecht contain substantial 1980s-1990s office inventory requiring simultaneous energy label upgrades and smart building retrofits.
- RVO subsidy schemes:The Netherlands Enterprise Agency accelerates sensor deployment and predictive maintenance adoption through direct procurement incentives for building technology.
Market Restraints
- Skilled technician scarcity:HVAC and building automation specialists command wage premiums that compress service provider margins, particularly for mid-market contracts.
- CE marking compliance costs:The EU Construction Products Regulation imposes material specification burdens on retrofit projects, extending procurement timelines for Dutch contractors.
- Energy price volatility:Natural gas and electricity input fluctuations destabilize energy performance contracting models that underpin long-term FM agreements.
Strategic Opportunities
- CSRD disclosure preparation:The Corporate Sustainability Reporting Directive creates advisory demand for granular building-level emissions tracking and supply chain impact assessment.
- Social enterprise labor models:Dutch municipal procurement criteria increasingly favor FM providers employing disadvantaged workers, opening public sector contract access.
- IoT-predictive maintenance convergence:Sensor networks and machine learning analytics integration enables outcome-based service pricing for critical infrastructure clients.
Industry Challenges
- ISO 41011 implementation gaps:Standardized facility management terminology adoption lags among smaller Dutch contractors, complicating multi-site portfolio oversight.
- Legacy BMS integration:Proprietary building management system architectures resist interoperability with modern cloud-based analytics platforms, fragmenting data visibility.
- Dutch Building Decree timeline pressure:Energy label upgrade deadlines compress project delivery windows while certification bottlenecks extend compliance verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Facility Management Market |
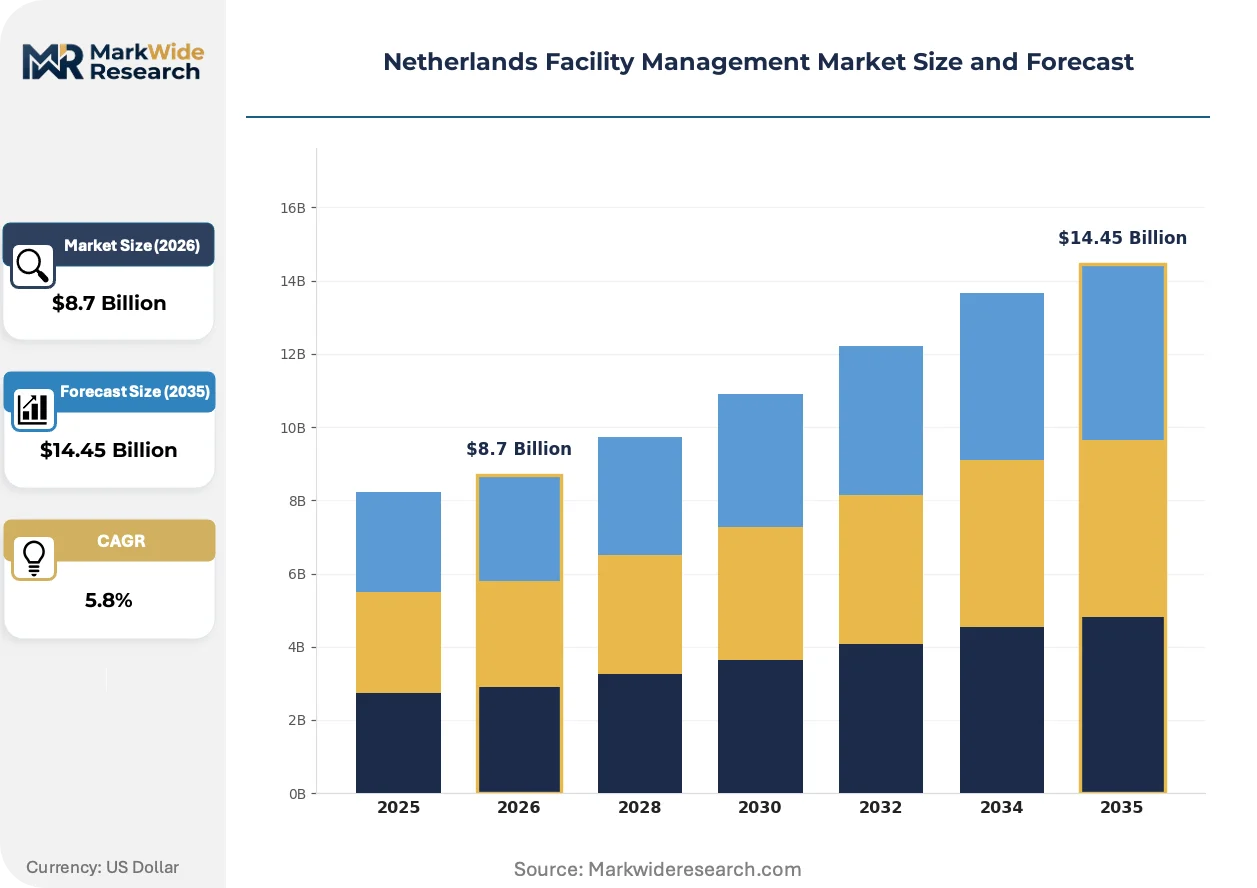
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Security, Maintenance, Space Management End User: Corporate Offices, Healthcare Facilities, Educational Institutions, Retail Stores Technology: IoT Solutions, Energy Management, Building Automation, Smart Security Delivery Model: Outsourced, In-House, Hybrid, Contractual |
| Companies Covered | CBRE Global Workplace Solutions (Netherlands), Facilicom Group, Vebego International BV, G4S Facilities Management Nederland, Hago Netherlands BV, ISS Facility Services Nederland, Apleona GmbH, DW Facility Group BV, Sodexo Nederland, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Facility Management Market Strategic Shifts
Digital infrastructure convergence and regulatory disclosure mandates are restructuring how Dutch facility operators capture, analyze and monetize building performance data across their portfolios.
Digital twin technology is unifying asset visualization, energy simulation and maintenance scheduling into single-platform environments. Dutch commercial landlords with multi-site Randstad holdings are piloting these systems at select properties. This unification compresses the vendor stack and elevates platform providers above point-solution competitors.
The EU Green Deal's building energy performance standards are tightening disclosure thresholds for commercial properties exceeding specific floor areas. Dutch enforcement by the Ministry of the Interior and Kingdom Relations mandates label upgrades before lease renewal. Healthcare facilities and financial district offices face the steepest compliance cost trajectories.
Buyer contracting preferences are pivoting toward integrated service bundles spanning maintenance, energy management and workspace experience. Corporate real estate departments in Amsterdam's Zuidas district are consolidating vendor relationships. This concentration favors operators with cross-functional capabilities over specialized cleaning or security providers.
Netherlands Facility Management Market Segmentation
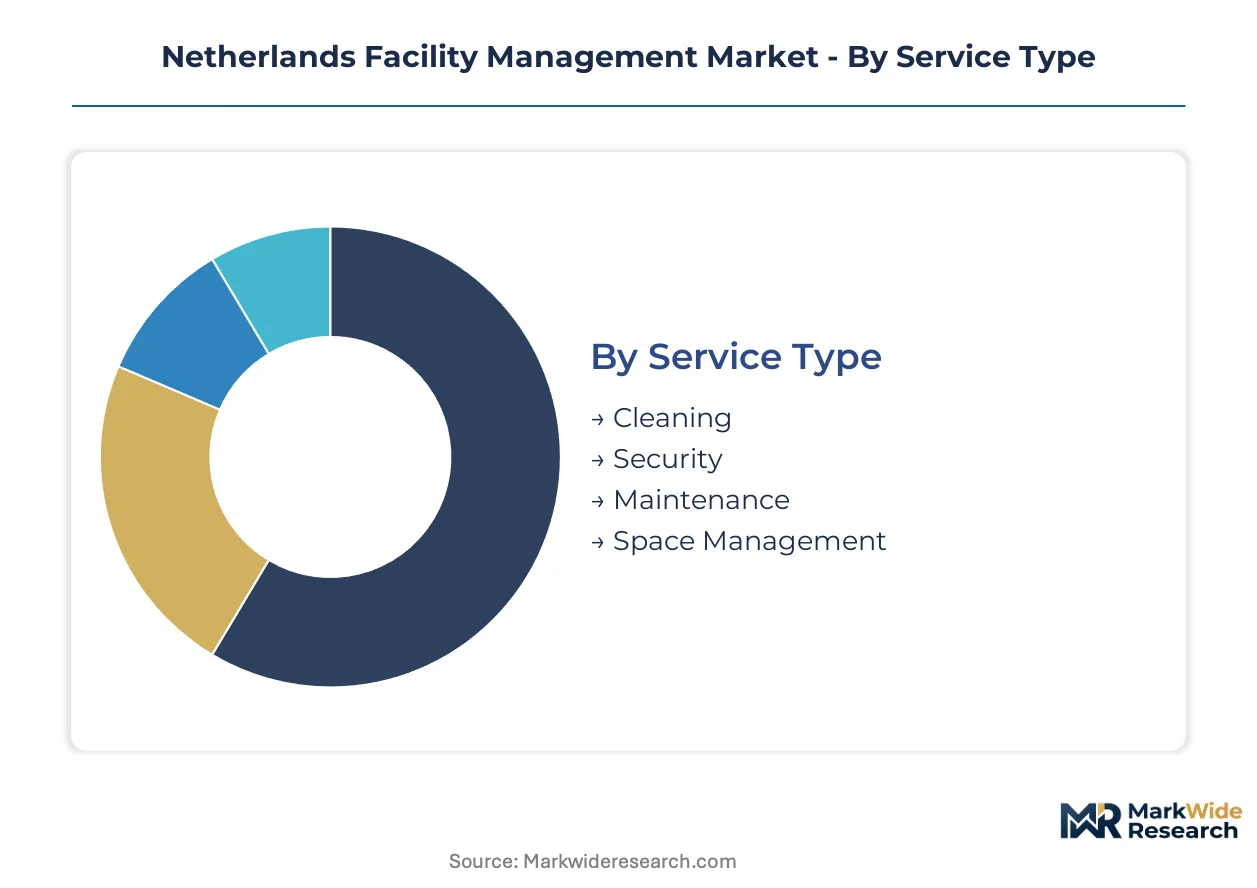
Segmentation reveals how Dutch facility operators align service portfolios with distinct regulatory burdens and client risk profiles. Understanding these divides clarifies where ISO 41011 compliance investments concentrate and which technology integrations command premium pricing.
Service Type:
CE marking under the EU Construction Products Regulation and WIP hygiene protocols create divergent certification pathways across service categories.
- Cleaning:Labor-intensive operations governed by WIP standards for healthcare environments and general hygiene mandates for commercial spaces. Dutch hospitals in the Randstad corridor drive specialized disinfection demand as EU Green Deal ventilation upgrades intersect with infection control protocols.
- Security:Physical and electronic guarding services requiring GDPR-compliant data handling for access control systems and camera networks. Amsterdam financial district tenants prioritize integrated threat detection alongside workplace experience management.
- Maintenance:HVAC and building system upkeep subject to Dutch Building Decree energy performance enforcement.
- Space Management:Workplace optimization and occupancy planning services.
Cleaning sits at the top of the volume ranking, with Maintenance climbing the fastest as energy label deadlines accelerate technical service demand.
End User:
Client sophistication tiers separate standardized procurement from complex integrated contracts requiring multi-stakeholder coordination.
- Corporate Offices:Amsterdam Zuidas and Rotterdam Maastoren district landlords pursue bundled FM contracts spanning maintenance, energy management, and workspace experience. CSRD disclosure preparation elevates demand for granular building-level emissions tracking across multi-site portfolios.
- Healthcare Facilities:Dutch hospitals and elderly care centers enforce WIP hygiene protocols exceeding standard commercial requirements. Specialized cleaning and critical infrastructure maintenance capture premium pricing as institutions offload non-core asset management.
- Educational Institutions:Universities and municipal schools with decentralized procurement.
- Retail Stores:High-frequency, low-margin service requirements with standardized specifications.
Corporate Offices dominate contract value concentration, with Healthcare Facilities expanding most quickly through integrated outsourcing mandates.
Technology:
Integration complexity and data sovereignty requirements stratify adoption timelines across the technology stack.
- IoT Solutions:Sensor networks for predictive maintenance and real-time monitoring. RVO subsidy schemes accelerate deployment in Randstad commercial retrofits where aging BMS architectures resist cloud interoperability.
- Energy Management:Performance contracting and optimization platforms tied to EU Green Deal compliance. Dutch Building Decree enforcement tightens disclosure thresholds for properties exceeding floor area limits, forcing landlord investment in granular consumption analytics.
- Building Automation:Integrated control systems for HVAC and lighting.
- Smart Security:AI-enabled surveillance and access management with GDPR constraints.
Energy Management holds the largest installed base, with IoT Solutions gaining share fastest as digital twin pilots expand across multi-site portfolios.
Delivery Model:
Contractual risk allocation and labor model flexibility distinguish procurement approaches across client segments.
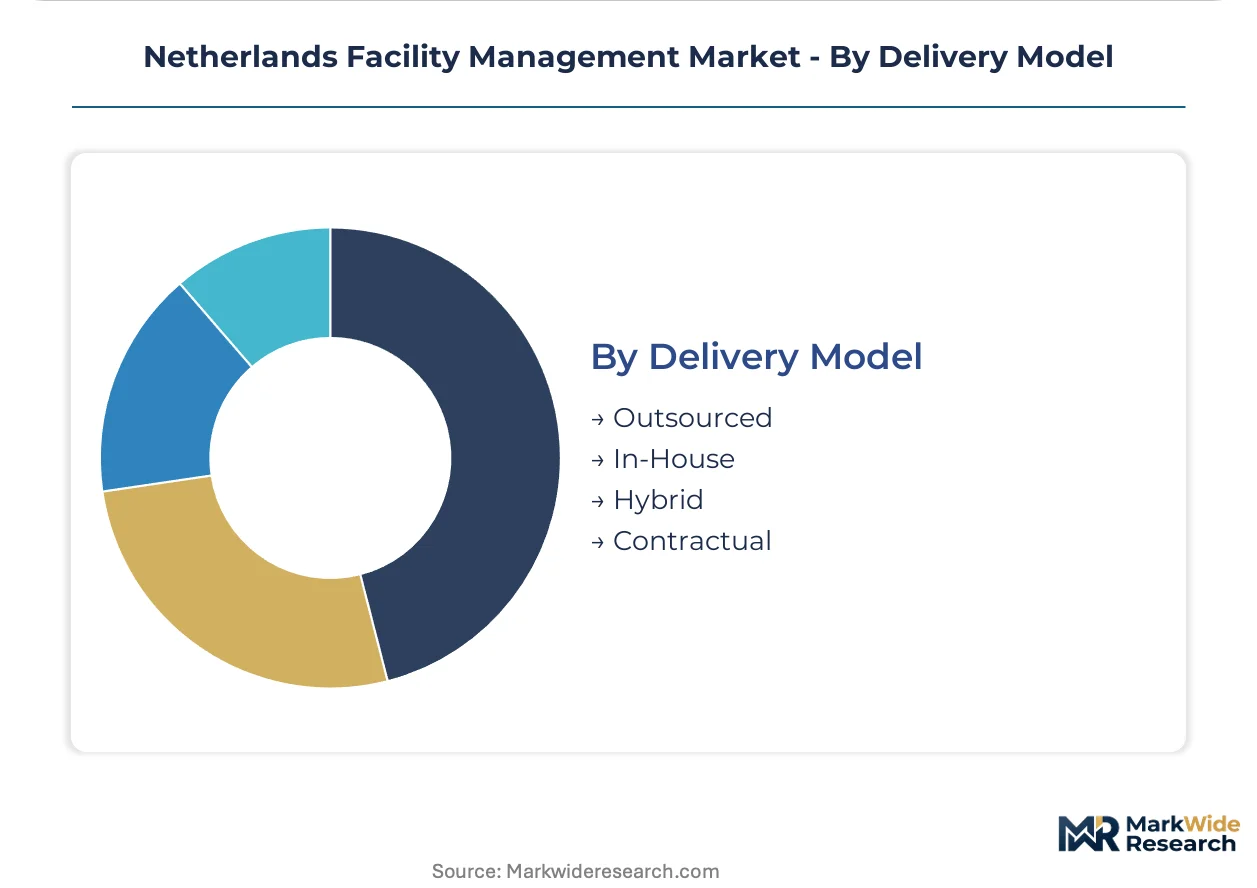
- Outsourced:Full-service delegation to specialized FM operators. Dutch corporations divest non-core real estate functions, concentrating transaction volume with providers offering cross-functional capabilities over point-solution specialists.
- In-House:Captive service delivery retaining direct workforce control.
- Hybrid:Blended arrangements where strategic functions stay internal and transactional services shift external. Mid-market tenants in Utrecht and The Hague seek flexibility without full outsourcing complexity.
- Contractual:Outcome-based agreements with performance guarantees.
Outsourced delivery commands the greatest transaction volume, with Hybrid arrangements expanding most quickly among cost-conscious mid-market tenants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled FM technicians cluster disproportionately in Randstad metropolitan corridors, where aging commercial stock and healthcare expansion generate concentrated service demand. This workforce distribution shapes contract accessibility and response-time capabilities across Dutch sub-regions.
Randstad
Amsterdam Zuidas and Rotterdam Maastoren district landlords pursue bundled FM contracts spanning maintenance, energy management, and workspace experience. Dutch Building Decree enforcement by the Ministry of the Interior and Kingdom Relations mandates energy label upgrades before lease renewal. Healthcare facilities in Utrecht and The Hague expand integrated outsourcing to meet WIP hygiene protocols.
Brabant
Eindhoven's high-tech manufacturing campuses require specialized cleanroom maintenance and critical infrastructure uptime guarantees. RVO subsidy schemes accelerate smart building sensor deployment across industrial facilities. The Brainport Eindhoven corridor concentrates predictive maintenance demand among semiconductor and automotive suppliers.
Eindhoven Region
ASML and Philips supply chain facilities enforce stringent contamination control and HVAC reliability standards exceeding typical commercial specifications. CE marking under the EU Construction Products Regulation governs material specifications for retrofit projects. FM providers serving this cluster invest in technician certification programs to capture premium contracts.
Northern Netherlands
Groningen and Leeuwarden healthcare institutions drive specialized cleaning demand as provincial hospitals consolidate asset management functions. Municipal procurement criteria favor social enterprise labor models aligning with Dutch public sector values. Energy transition projects in former gas extraction zones create facility infrastructure upgrade requirements.
Netherlands Facility Management Market Competitive Environment
The competitive structure tilts toward integrated service platforms over point-solution specialists. Dutch corporations divesting non-core real estate functions concentrate contract volume with providers offering cross-functional capabilities. Three archetypes dominate: global workplace consultancies with technology platforms, specialized healthcare cleaning operators with WIP certification depth, and social enterprise labor models aligned with municipal procurement. M&A activity targets regional maintenance specialists to fill capability gaps, while strategic partnerships with sensor vendors accelerate predictive maintenance offerings.
Among Netherlands-based operators, Facilicom Group and Vebego International BV exemplify contrasting positioning strategies. Facilicom anchors the healthcare-specialist archetype through WIP-exceeding cleaning protocols. Vebego occupies the social enterprise tier, leveraging labor models that satisfy Dutch municipal procurement criteria. CBRE Global Workplace Solutions represents the integrated platform approach, capturing premium contracts in Amsterdam's financial district through workplace technology convergence.
| Leading Market Players |
|---|
| CBRE Global Workplace Solutions (Netherlands) |
| Facilicom Group |
| Vebego International BV |
| G4S Facilities Management Nederland |
| Hago Netherlands BV |
| ISS Facility Services Nederland |
| Apleona GmbH |
| DW Facility Group BV |
| Sodexo Nederland |
| Others |
Value Chain & Pricing Dynamics
Horizontal integration across cleaning, maintenance, and energy management services anchors pricing power for Dutch facility operators serving Randstad corporate portfolios, while EU Green Deal compliance costs compress margins for point-solution specialists lacking cross-functional scale.
Pricing Analysis
The bundled-versus-unbundled service split separates Amsterdam Zuidas landlords pursuing integrated workplace contracts from mid-market tenants in Utrecht selecting hybrid arrangements. Three-tier pricing structure across premium, standard, and economy levels reflects WIP certification depth, energy performance guarantees, and social enterprise labor model compliance. Pricing pressure stems from skilled technician scarcity elevating wage costs for HVAC and building automation specialists. Mid-market corporate tenants exhibit highest price sensitivity, while healthcare facilities accept premium positioning for infection control protocols exceeding baseline standards.
Supply Chain Analysis
Dutch municipal procurement criteria and social enterprise mandates reshape sourcing toward domestic labor pools and certified training programs rather than lowest-cost international alternatives. Equipment and sensor hardware draws from Germany, Belgium, and domestic Dutch manufacturers serving building automation retrofits. CE marking compliance under the EU Construction Products Regulation governs material specifications for energy label upgrade projects. Single-source vulnerability concentrates in proprietary BMS architectures resisting cloud interoperability. Distribution runs through direct FM operator procurement teams coordinating with property management divisions of institutional landlords.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Netherlands facility management market functions as a geographic-arbitrage play where EU Green Deal compliance costs in neighboring Germany and Belgium exceed Dutch RVO subsidy-offset levels, attracting cross-border contract migration toward Randstad operators.
For Market Incumbents: Lock in healthcare facility relationships through WIP-exceeding protocol investments before Dutch hospital consolidation accelerates. Capture Amsterdam financial district contracts via digital twin platform integration that proprietary BMS architectures cannot replicate. Vertical integration into technician certification programs defends against wage premium compression from HVAC specialist scarcity.
For New Entrants and Emerging Players: Enter via municipal procurement channels where social enterprise labor models satisfy Dutch public sector criteria unavailable to scaled international competitors. Target Northern Netherlands healthcare institutions in Groningen and Leeuwarden where incumbent coverage remains thin. Lead with CSRD disclosure advisory services as landlords face granular building-level emissions reporting mandates.
For Investors and Strategic Acquirers: Roll-up economics work for regional maintenance specialists because ISO 41011 standardization gaps fragment multi-site portfolio oversight and create capability arbitrage opportunities. The five-to-ten year viability window favors platforms integrating IoT predictive maintenance with outcome-based contracting. Acquisition targets should demonstrate RVO subsidy navigation expertise and WIP certification depth. Watch for Dutch Building Decree enforcement acceleration as the inflection signal compressing compliance timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Digital twin unification compresses vendor stacks for Randstad multi-site landlords. |
| Certification Investment | WIP-exceeding protocols capture premium pricing in Dutch hospital outsourcing. |
| Backward Integration | In-house technician training programs offset HVAC specialist wage premiums. |
| Strategic Partnership | Sensor vendor alliances accelerate predictive maintenance offerings for critical infrastructure. |
| Geographic Expansion | Brainport Eindhoven corridor penetration targets ASML supply chain cleanroom requirements. |
Study Parameters
Bottom-up end-user modeling reconciled against top-down service provider tracking forms the analytical core of this study. Primary interviews with facility management executives, healthcare asset directors, corporate real estate procurement leads, and municipal contracting officers combined with secondary validation from RVO subsidy disclosures, Dutch Building Decree enforcement records, and EU Green Deal implementation timelines. Trade data from Netherlands Enterprise Agency publications and sector association filings provided supply-side triangulation against demand estimates.
Input-output matrices mapped service type, end-user segment, technology adoption, and delivery model dimensions across the projection horizon. Segmentation modeling incorporated healthcare outsourcing intensity, energy label upgrade velocity, and IoT deployment patterns. CAGRs derived from fitted growth curves adjusted for regulatory deadline clustering and subsidy scheme phase-outs. Forecast inputs included skilled technician pipeline data and BMS interoperability adoption rates.
Inputs from Dutch hospital procurement databases and municipal contract registries were available through the study window; gaps in mid-market tenant hybrid arrangement penetration introduce uncertainty bands around delivery model splits. Forecasts reflect documented assumptions regarding EU Green Deal enforcement pacing and RVO scheme continuity. Energy price volatility and CE marking compliance timeline extensions represent specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Latin America Facility Management Market
Facility Management
Egypt Facility Management Market
Facility Management
Asia-Pacific Hard Facility Management Market
Facility Management
Saudi Arabia Facility Management Market
Facility Management
France Facility Management Market
Facility Management
Europe Hard Facility Management Market
Facility Management
Saudi Arabia Soft Facility Management Market
Facility Management
Chile Facility Management Market
Facility Management
Middle East and Africa Soft Facility Management Market
Facility Management
Hungary Facility Management Market
Facility Management
Warehouse Management Service Market
Facility Management
GCC Facility Management Market
Facility Management
New Zealand Facility Management Market
Facility Management
Global Unified Facility Management Market
Facility Management
UK Facility Management Market
Facility Management
India Integrated Facility Management Market