
 Denmark Facility Management Market | 2026-2036
Denmark Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Facility Management Market Analysis
Consolidation among Danish healthcare institutions and pharmaceutical campuses is repositioning procurement toward bundled facility management contracts. ISS A/S leverages its nationwide service network to anchor large integrated accounts across hospital systems and research parks. Coor Service Management A/S specializes in Nordic energy optimization protocols, while Sodexo Facilities Management Denmark A/S competes through foodservice-facility hybrids tied to corporate and educational sites.
Facility management encompasses the coordinated delivery of hard services (mechanical, electrical, and building fabric maintenance) and soft services (cleaning, security, catering, and groundskeeping) to ensure operational continuity, occupant safety, and asset lifecycle optimization of commercial and institutional properties. Cleaning Services and Maintenance Services dominate current contract value due to mandatory hygiene protocols and aging building stock renovation cycles, while IoT Solutions and Energy Management represent the fastest-expanding technology segments as Danish landlords deploy sensor networks to comply with tightening heating efficiency benchmarks. Outsourced and Hybrid management models capture growing share as in-house teams shrink and integrated service providers assume capital planning responsibilities.
Denmark's Building Regulations (Bygningsreglementet), administered by the Danish Transport, Construction and Housing Authority, mandate energy performance certificates and CO2 reduction pathways that directly shape retrofit demand and service specifications. The Danish Working Environment Authority (Arbejdstilsynet) enforces indoor climate and cleaning chemical exposure limits that filter vendor eligibility. Stakeholders must monitor how proposed EU Energy Performance of Buildings Directive amendments tighten Denmark's renovation rate obligations and whether hybrid management models absorb or cede technology investment burdens to specialized energy service companies.
Market Dynamics
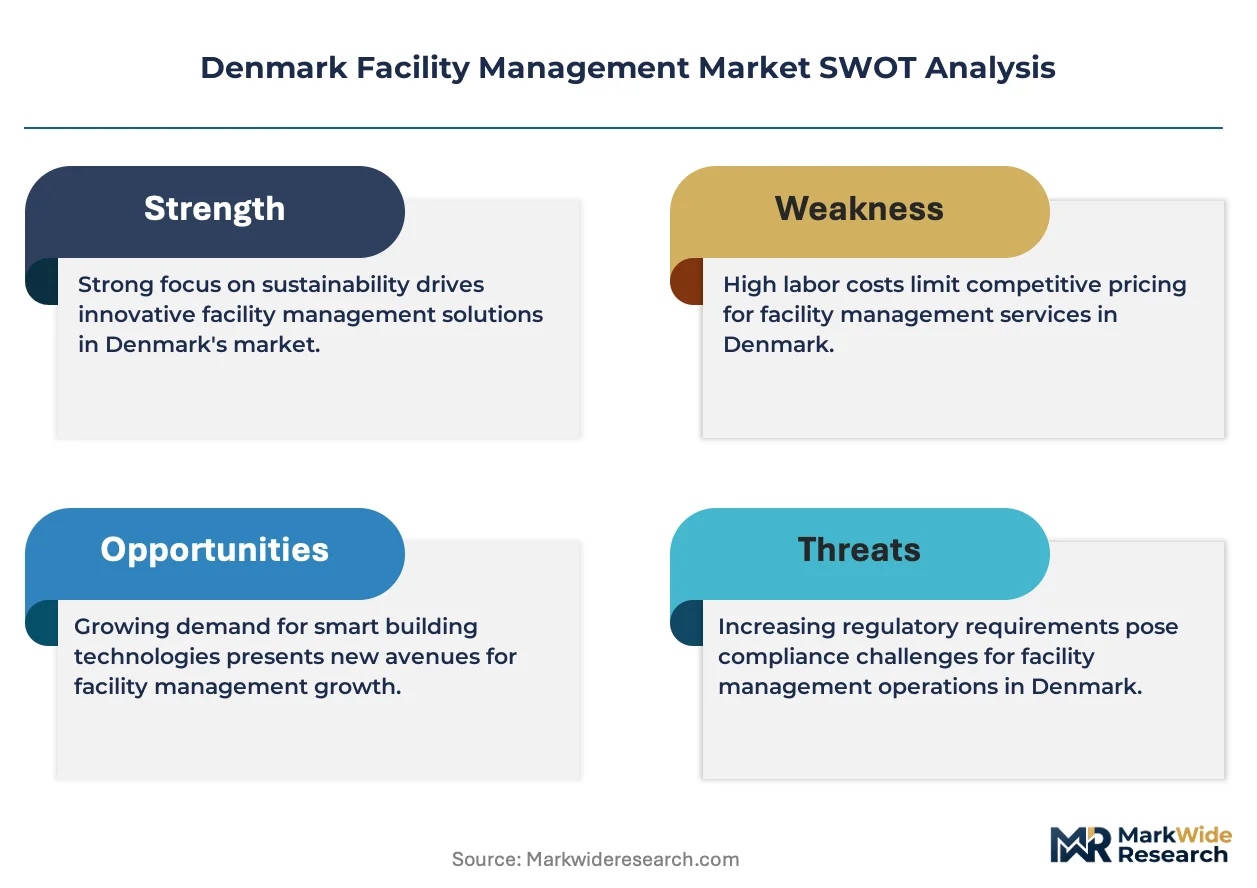
Denmark's facility management sector is compressing around energy retrofit mandates, with the Building Regulation's CO2 reduction pathways forcing landlords to outsource capital-intensive building system upgrades to integrated service providers rather than maintain fragmented in-house operations.
Growth Catalysts
- Bygningsreglementet energy performance standards:Mandatory renovation rates for commercial stock over 1,000 square meters are accelerating hard service outsourcing as owners seek bundled retrofit-project delivery.
- Healthcare consolidation:Merged hospital systems and pharmaceutical campuses are consolidating vendor rosters toward single-source facility management contracts covering clinical hygiene, HVAC, and grounds.
- IoT sensor networks:Danish landlords are deploying connected building systems to automate heating efficiency compliance, creating recurring software-integrated service revenue streams.
Market Restraints
- Specialized technician scarcity:Denmark's tight labor market limits availability of certified BMS engineers and energy auditors, constraining service expansion.
- Arbejdstilsynet compliance costs:Indoor climate and chemical exposure mandates add certification overhead that smaller regional vendors struggle to absorb.
- Technology vendor concentration:Nordic building automation hardware relies heavily on a narrow supplier base, exposing integrated providers to component lead time volatility.
Strategic Opportunities
- Zealand secondary cities:Ringsted and Køge logistics corridors show underpenetrated demand for industrial facility management as warehousing expands beyond Copenhagen's cost base.
- EU Energy Performance of Buildings Directive amendments:Proposed renovation rate tightening would deepen Danish landlord reliance on outsourced energy service companies for compliance execution.
- Foodservice-facility hybrids:Corporate and educational sites are unbundling catering from pure cleaning contracts, creating integrated soft service packages.
Industry Challenges
- Legacy BMS integration:Copenhagen's aging commercial stock runs incompatible building management protocols, forcing costly middleware development for IoT retrofits.
- Green skills pipeline:Denmark's vocational training system produces insufficient energy optimization specialists to match retrofit demand acceleration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Facility Management Market |
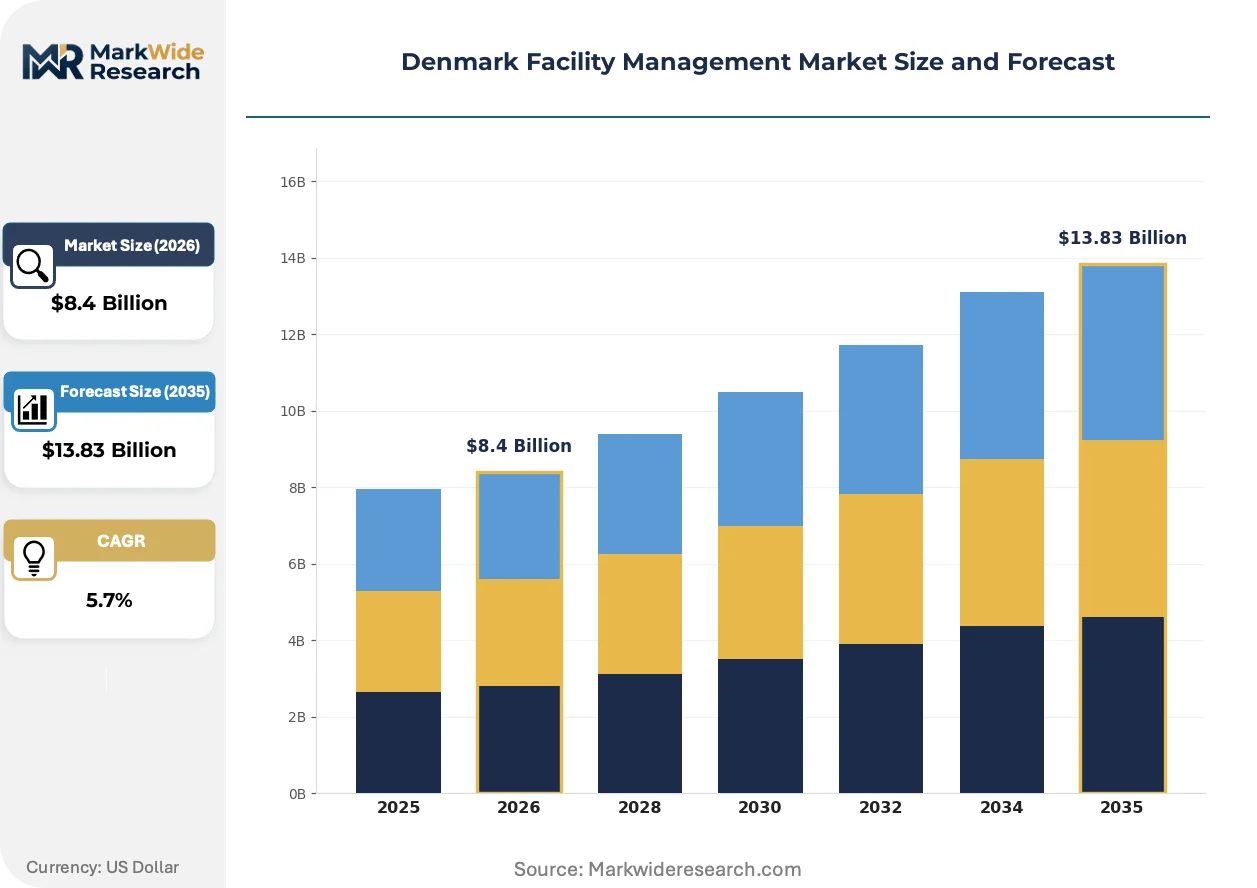
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning Services, Security Services, Maintenance Services, Landscaping Services End User: Corporate Offices, Industrial Facilities, Healthcare Institutions, Educational Establishments Management Model: In-House, Outsourced, Hybrid, Integrated Technology: IoT Solutions, Building Management Systems, Energy Management, Automation Tools |
| Companies Covered | Sodexo Facilities Management Denmark A/S, Apleona GmbH, ISS A/S, CBRE Group, Aramark Facilities Services Nordics, Coor Service Management A/S, G4S Facilities Management Denmark A/S, JLL Limited, Compass Group Denmark A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Facility Management Market Emerging Trajectories
Digital infrastructure is rewiring competitive advantage across Danish facility management, with sensor networks and predictive platforms compressing service delivery models while regulatory pressure forces technology adoption timelines.
Cloud-based building management platforms are modularizing how Danish landlords consume facility services. Copenhagen commercial property owners are adopting subscription-based HVAC and lighting control systems that unbundle capital expenditure into operational contracts. This architecture is modularizing vendor relationships, allowing owners to swap individual service modules without terminating entire integrated agreements.
The EU Energy Performance of Buildings Directive is tightening Denmark's renovation obligations through proposed amendments to accelerate commercial stock retrofit rates. Danish Transport, Construction and Housing Authority enforcement will expand energy audit frequency and penalty structures for non-compliance. Copenhagen's Class A office segment is responding fastest, embedding continuous commissioning clauses into long-term facility management contracts.
Corporate buyers are consolidating vendor relationships from multi-contract fragmentation toward single-accountability integrated service agreements. Danish pharmaceutical and financial services campuses are replacing siloed cleaning, security, and maintenance procurement with unified performance-based contracts. This concentration is most visible in Greater Copenhagen's Ørestad business district, where landlords now prioritize providers offering combined hard and soft service capabilities with guaranteed energy outcomes.
Denmark Facility Management Market Segmentation
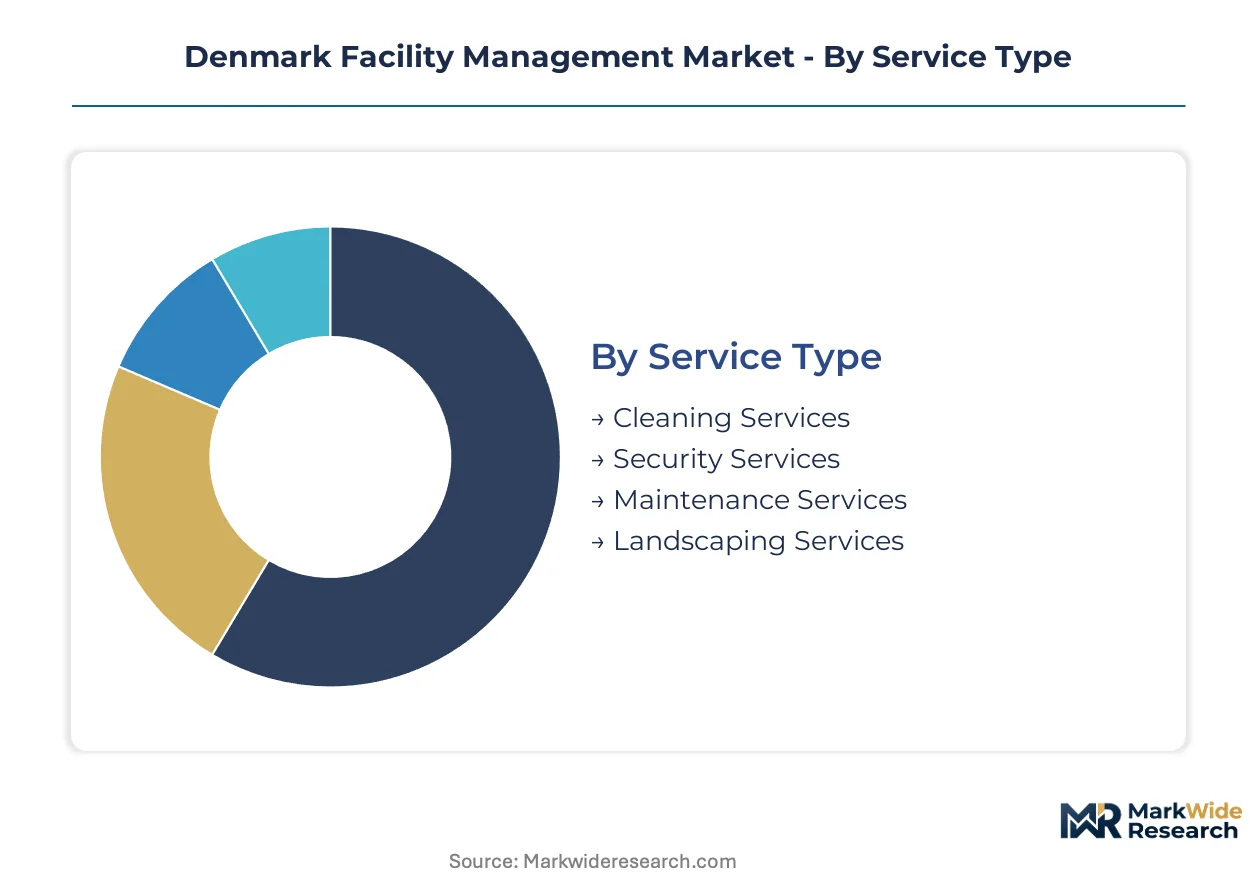
Segmentation in Danish facility management reveals how regulatory pressure and building stock characteristics reshape procurement patterns. Service bundling decisions, technology adoption thresholds, and compliance burdens vary sharply across customer types and operational models.
Service Type:
Arbejdstilsynet chemical exposure limits and hygiene protocols create tiered certification requirements across service categories, with clinical-facing segments bearing the heaviest audit burdens.
- Cleaning Services:Clinical-grade disinfection protocols dominate healthcare procurement specifications, with mandatory chemical handling certifications under Arbejdstilsynet exposure thresholds. Copenhagen hospital systems and pharmaceutical campuses concentrate demand for specialized biohazard cleaning crews as consolidation reduces vendor counts.
- Maintenance Services:Hard service contracts encompass HVAC, electrical, and building fabric upkeep with CO2 reduction pathway compliance embedded in scope. Aging commercial stock in Copenhagen's central business district drives retrofit-project bundling as landlords outsource capital-intensive system upgrades.
- Security Services:Perimeter and access control operations requiring background clearance protocols under Danish Private Security Services Act provisions.
- Landscaping Services:Grounds maintenance and seasonal vegetation management tied to municipal green space contracts and corporate campus aesthetics.
Leading the category by volume: Cleaning Services. Growing fastest: Maintenance Services.
End User:
Customer procurement sophistication varies by asset ownership structure, with public-sector buyers imposing stricter energy performance clauses than private landlords.
- Healthcare Institutions:Merged hospital systems and research campuses drive single-source integrated contracts spanning clinical hygiene, HVAC, and grounds. Zealand Region's consolidated healthcare procurement now mandates continuous energy commissioning clauses in multi-year agreements.
- Corporate Offices:Class A office landlords in Ørestad and central Copenhagen prioritize providers combining hard and soft services with guaranteed heating efficiency outcomes. Subscription-based building management platforms are modularizing how these buyers consume facility services.
- Industrial Facilities:Manufacturing and logistics sites in Ringsted and Køge corridors seeking bundled maintenance for production-critical equipment.
- Educational Establishments:Universities and municipal schools unbundling catering from pure cleaning contracts toward integrated soft service packages.
Dominant by contract value: Healthcare Institutions. Expanding most quickly: Corporate Offices.
Management Model:
Capital planning responsibility allocation determines which model captures share as Danish landlords confront renovation rate obligations.
- Outsourced:Full operational transfer to specialized providers with performance-based KPIs and energy outcome guarantees. Copenhagen commercial property owners increasingly adopt this structure to access bundled retrofit-project delivery without maintaining fragmented in-house teams.
- Integrated:Unified hard and soft service delivery under single accountability with continuous commissioning embedded. Pharmaceutical and financial services campuses in Greater Copenhagen are consolidating from siloed procurement toward this model.
- Hybrid:Split responsibility with in-house teams retaining strategic oversight while vendors execute tactical operations.
- In-House:Direct employment of maintenance and cleaning staff, shrinking as specialized technician scarcity constrains expansion.
Capturing largest share: Outsourced. Steepest expansion trajectory: Integrated.
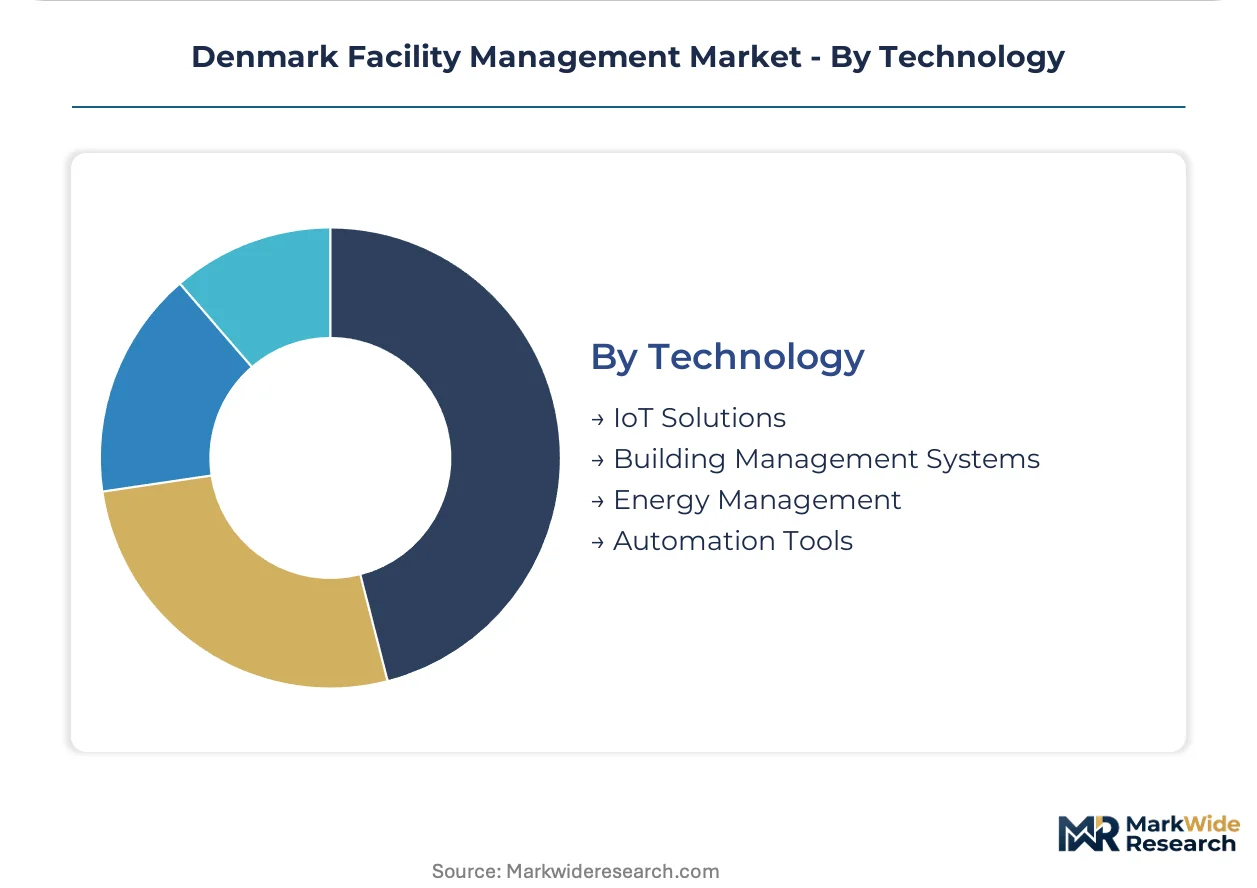
Technology:
Compliance automation requirements and sensor deployment economics differentiate adoption patterns across building vintages.
- IoT Solutions:Connected sensor networks automating heating efficiency monitoring and predictive maintenance alerts. Copenhagen landlords deploy these systems to satisfy tightening Bygningsreglementet benchmarks while creating recurring software-integrated service revenue.
- Energy Management:Continuous commissioning platforms and audit automation tools tied to CO2 reduction pathway documentation. Class A office segment leads adoption as enforcement expands penalty structures for non-compliance.
- Building Management Systems:Centralized control platforms for HVAC, lighting, and access systems requiring middleware development for legacy protocol integration.
- Automation Tools:Robotic cleaning and security patrol systems with deployment concentrated in high-traffic transportation and logistics facilities.
Widest installed base: IoT Solutions. Gaining share fastest: Energy Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark's facility management demand concentrates in Copenhagen's commercial core, Zealand's healthcare corridor, and emerging logistics zones. Geographic fragmentation between capital-intensive retrofit zones and secondary growth corridors shapes procurement patterns.
Greater Copenhagen
Class A office landlords in Ørestad and the central business district drive integrated service adoption. Bygningsreglementet enforcement through the Danish Transport, Construction and Housing Authority mandates continuous energy commissioning in multi-year contracts. Copenhagen's aging commercial stock forces costly middleware development for legacy BMS-IoT integration.
Zealand Region
Consolidated hospital systems and pharmaceutical campuses anchor single-source facility management procurement. Zealand Region's healthcare procurement now embeds energy performance guarantees into clinical hygiene contracts. Ringsted and Køge logistics corridors generate underpenetrated industrial facility management demand as warehousing expands.
North Denmark Region
Aalborg's manufacturing base sustains hard service contracts for production-critical equipment maintenance. Arbejdstilsynet indoor climate mandates filter vendor eligibility for industrial cleaning and HVAC operations. The region's vocational training institutions struggle to supply sufficient energy optimization specialists for retrofit acceleration.
Central Denmark Region
Aarhus educational establishments unbundle catering from pure cleaning contracts toward integrated soft service packages. Municipal school procurement under the Danish Working Environment Authority chemical exposure limits favors certified regional vendors. The city's university research parks generate bundled facility management demand spanning laboratory hygiene and building systems.
Southern Denmark Region
Odense's robotics and automation industrial cluster creates specialized maintenance requirements for cleanroom and precision manufacturing environments. EU Energy Performance of Buildings Directive amendments would deepen landlord reliance on outsourced energy service companies across the region's commercial stock. Smaller regional vendors face absorption challenges from Arbejdstilsynet certification overhead.
Denmark Facility Management Market Vendor Landscape
Danish integrated service providers anchor one tier; international facility management conglomerates hold scale-driven positions through Nordic subsidiaries. The market compresses around energy retrofit mandates and healthcare consolidation, favoring vendors with bundled hard-soft service capabilities and continuous commissioning expertise. Two strategic archetypes dominate: nationwide integrated platforms and specialized energy optimization operators. Competitive moves center on healthcare contract consolidation and IoT-enabled service modularization.
Within the integrated service tier, ISS A/S and Coor Service Management A/S occupy anchor positions exemplifying Nordic-scale operational networks. Sodexo Facilities Management Denmark A/S represents the foodservice-facility hybrid archetype serving corporate and educational sites. These Danish and Danish-registered entities sit alongside international operators including CBRE Group and JLL Limited, whose Nordic subsidiaries compete through global account relationships and cross-border service standardization.
| Leading Market Players |
|---|
| Sodexo Facilities Management Denmark A/S |
| Apleona GmbH |
| ISS A/S |
| CBRE Group |
| Aramark Facilities Services Nordics |
| Coor Service Management A/S |
| G4S Facilities Management Denmark A/S |
| JLL Limited |
| Compass Group Denmark A/S |
| Others |
Supply Flow & Price Mechanics
Horizontal integration across hard and soft service capabilities anchors both supply positioning and pricing power for Danish facility management providers, with bundled retrofit-project delivery commanding premium contract terms under Bygningsreglementet compliance mandates while fragmented regional vendors absorb certification overhead without scale leverage.
Pricing Analysis
Volume-margin splits in Danish facility management favor integrated providers capturing recurring software-embedded service revenue against transactional project-based competitors. Contract-based long-term offtake structures dominate, with price differentiation driven by Arbejdstynet certification tier and continuous commissioning capability. Cost compression in standard maintenance tiers is intensifying because certified technician scarcity constrains service expansion. Healthcare institutions show least price sensitivity due to mandatory clinical hygiene protocols, while municipal educational buyers exhibit highest sensitivity to soft service bundling.
Supply Chain Analysis
Arbejdstilsynet certification gating filters vendor eligibility through indoor climate and chemical exposure mandates that smaller regional operators struggle to absorb. Building automation hardware draws from Denmark, Germany, and Sweden, with HVAC components and IoT sensor networks resting on Nordic supplier concentration. Single-source vulnerability in BMS engineering talent creates bottleneck risk for integrated service expansion. Distribution runs through direct national account relationships with hospital systems and pharmaceutical campuses, supplemented by municipal procurement frameworks for educational and government facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Danish facility management is becoming a vertical-integration race, with control over energy optimization talent and IoT platform development emerging as the decisive downstream lever for contract retention and margin defense.
For Market Incumbents: Acquire certified energy auditor and BMS engineering capabilities to anchor bundled retrofit-project delivery against specialized energy service companies. Consolidate vendor relationships across Zealand Region's merged hospital systems before regulatory tightening deepens landlord reliance on outsourced compliance execution. Arbejdstilsynet certification overhead filters smaller competitors, creating acquisition opportunities for scale players to absorb regional service networks. For New Entrants and Emerging Players: Capture underpenetrated industrial facility management demand in Ringsted and Køge logistics corridors as warehousing expansion outpaces established provider coverage. Foodservice-facility hybrid unbundling at corporate and educational sites offers the most penetrable entry vector, with catering integration providing differentiation against pure-play cleaning competitors. Partner with Nordic building automation hardware distributors to shortcut technology vendor concentration barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by international facility management conglomerates seeking Nordic-scale operational networks and energy optimization expertise. Long-term viability hinges on continuous commissioning capability and guaranteed heating efficiency outcomes rather than transactional service delivery. Watch proposed EU Energy Performance of Buildings Directive amendments as the inflection signal that would accelerate Danish landlord reliance on outsourced energy service companies and deepen contract value pools.| Strategic Initiative | Industry Significance |
|---|---|
| Energy Auditor Talent Acquisition | Addresses certified BMS engineer scarcity constraining service expansion across Zealand healthcare corridors. |
| IoT Platform Development | Enables subscription-based HVAC and lighting control systems that unbundle capital into operational contracts. |
| Healthcare Contract Consolidation | Positions providers for single-source integrated agreements spanning clinical hygiene, HVAC, and grounds. |
| Foodservice-Facility Hybrid Integration | Captures corporate and educational site procurement shifting from siloed cleaning toward bundled soft services. |
| Zealand Logistics Corridor Expansion | Accesses underpenetrated industrial facility management demand as warehousing expands beyond Copenhagen's cost base. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across facility management executives, hospital procurement directors, commercial property landlords, Arbejdstilsynet compliance officers, and energy auditor specialists. Secondary sources encompassed Danish Transport, Construction and Housing Authority enforcement records, EU Energy Performance of Buildings Directive amendment tracking, and municipal procurement databases. Bottom-up contract value aggregation and top-down market sizing triangulated segment-level estimates.
Granularity-level modeling deployed service type, end user, management model, and technology adoption dimensions at the regional level across Greater Copenhagen, Zealand, North Denmark, Central Denmark, and Southern Denmark regions. CAGRs derived from regulatory mandate acceleration curves and building stock renovation rate obligations. Forecast inputs incorporated Bygningsreglementet compliance timeline enforcement and IoT sensor network deployment economics across building vintages.
The model holds under steady regulatory enforcement and technician training pipeline continuity; deviation in EU directive amendment timing or vocational education output would shift retrofit demand acceleration. Forecasts reflect assumptions on energy performance certificate penetration and outsourced management model adoption. A model refresh is warranted upon material change in Arbejdstilsynet indoor climate mandate stringency or Nordic building automation hardware supply availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Cold Storage Warehouse Market
Facility Management
Soft Facility Management Market
Facility Management
Croatia Facility Management Market
Facility Management
Bahrain Facility Management Market
Facility Management
United Arab Emirates Facility Management Market
Facility Management
UK Facility Management Market
Facility Management
Portugal Facility Management Market
Facility Management
Australia Facility Management Market
Facility Management
Qatar Facility Management Market
Facility Management
Panama Facility Management Market
Facility Management
Asia-Pacific Hard Facility Management Market
Facility Management
Germany Facility Management Market
Facility Management
United States Facility Management Market
Facility Management
Norway Facility Management Market
Facility Management
Greece Facility Management Market
Facility Management
North America Soft Facility Management Market