
 United Kingdom (UK) Facility Management Market | 2026-2036
United Kingdom (UK) Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom (UK) Facility Management Market Insights
The direct procurement channel between NHS trusts and integrated FM providers is narrowing as framework agreements consolidate vendor lists. Mitie Group PLC leverages its healthcare specialization to anchor large hospital estate contracts across England. Serco Group PLC competes through its government outsourcing heritage, while CBRE Group Inc. differentiates via technology-led asset management platforms for commercial landlords.
United Kingdom facility management encompasses the coordinated delivery of hard services (mechanical, electrical, and building fabric maintenance) and soft services (cleaning, security, and catering) to ensure operational continuity of built assets. The discipline applies computerized maintenance management systems (CMMS) and Internet of Things (IoT) sensor networks to optimize asset lifecycle performance and energy efficiency. Corporate client contracts dominate value pools, though healthcare demand accelerates fastest as NHS estates modernize aging infrastructure. Integrated contract models are displacing fragmented single-service arrangements, concentrating margin capture with full-service providers.
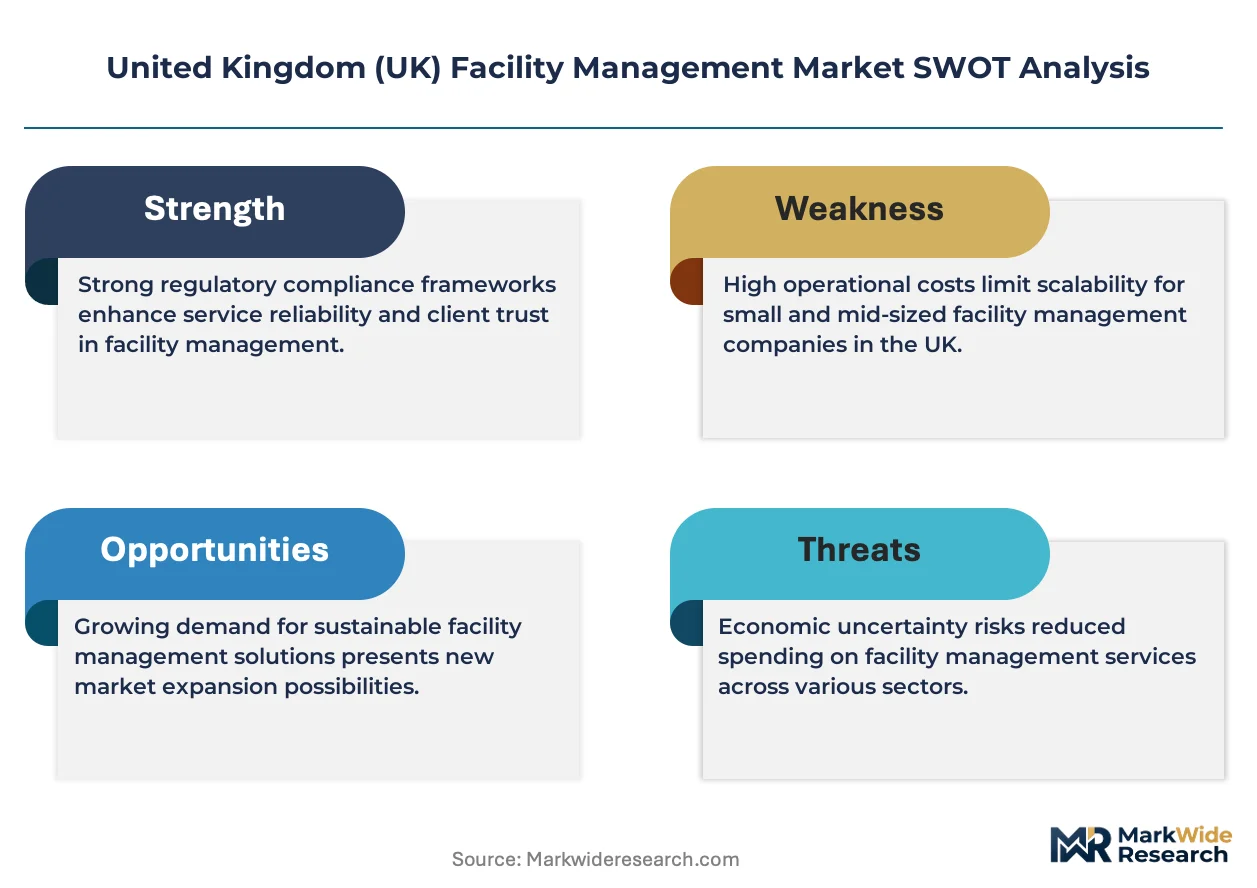
The Health and Safety Executive enforces workplace safety standards that elevate risk management obligations across FM operations, while the UK Green Building Council frameworks push carbon reduction targets into service-level agreements. Building Regulations Part L and the Future Buildings Standard reshape energy performance requirements for maintenance and retrofit scopes. Stakeholders must weigh compliance cost trajectories against the competitive advantage of early certification in carbon-accounting service lines.
Market Dynamics
The UK Net Zero Strategy and Building Safety Act are compressing operational margins while simultaneously creating premium service tiers for carbon-accounting FM providers who certify compliance ahead of enforcement deadlines.
Growth Catalysts
- NHS Estate Modernization:Aging hospital infrastructure across England is accelerating hard services outsourcing as trusts consolidate vendor relationships under framework agreements.
- Building Regulations Part L:Tightened energy performance standards for maintenance and retrofit scopes are mandating technology upgrades that favor integrated service providers.
- IoT Sensor Deployment:Predictive maintenance platforms are reducing unplanned downtime for commercial landlords in London's core office stock.
Market Restraints
- Skilled Technician Scarcity:Brexit-related labor mobility restrictions have tightened supply of certified mechanical and electrical engineers across England's FM workforce.
- Energy Price Volatility:Gas and electricity input cost swings are compressing fixed-price contract margins for heating, ventilation, and air conditioning maintenance providers.
- Framework Consolidation:NHS procurement centralization is reducing direct access routes for mid-tier FM vendors outside approved supplier lists.
Strategic Opportunities
- Northern Powerhouse Corridor:Manchester and Leeds commercial development is creating greenfield demand for integrated FM contracts outside saturated London markets.
- Carbon Accounting Services:The UK Green Building Council frameworks are enabling premium pricing for FM providers who embed Scope 1 and 2 emissions tracking into service-level agreements.
- CMMS-AI Convergence:Computerized maintenance management systems fused with machine learning analytics are opening predictive asset lifecycle contracts for industrial estates.
Industry Challenges
- Competence Certification Bottlenecks:The Health and Safety Executive's evolving competency requirements for high-risk building maintenance are extending contractor onboarding timelines.
- Legacy System Integration:NHS trusts' fragmented estate data architectures are complicating unified dashboard deployment for multi-site FM providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom (UK) Facility Management Market |
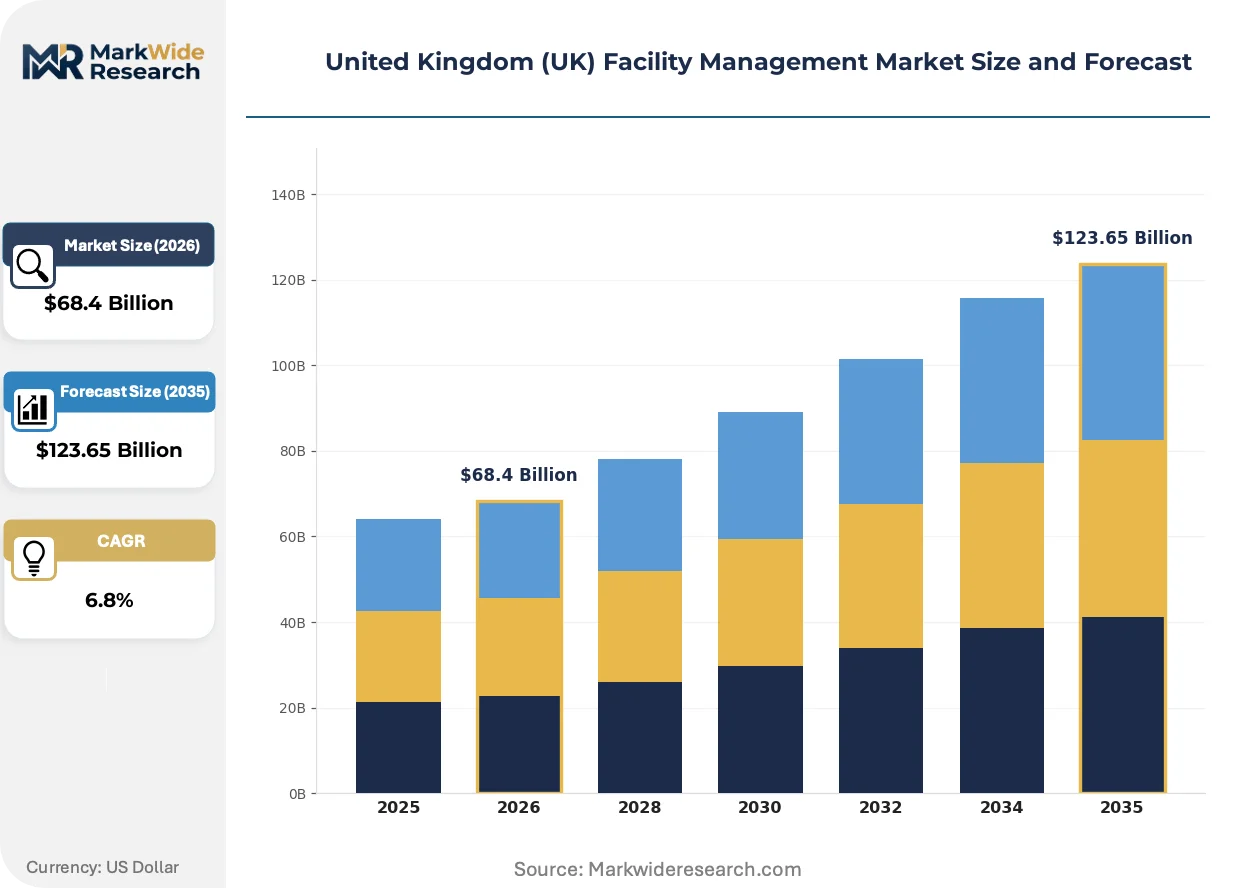
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Maintenance, Security, Landscaping Client Type: Corporate, Government, Educational, Healthcare Contract Model: Outsourced, In-house, Integrated, Hybrid Facility Type: Commercial, Industrial, Residential, Retail |
| Companies Covered | Mitie Group PLC, ISS UK, Serco Group PLC, OCS Group UK Ltd., CBRE Group Inc., Compass Group PLC, EMCOR Group Inc., Kier Group PLC, G4S Facilities Management UK, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom (UK) Facility Management Market Trends and Innovations
Digital infrastructure is penetrating asset-heavy operations faster than organizational readiness permits, creating capability gaps that favor technology-forward FM vendors.
Internet of Things sensor networks embedded in building management systems is digitizing mechanical and electrical asset monitoring across London's Grade A office stock. Commercial landlords with portfolios exceeding 500,000 square feet are deploying these platforms at scale to satisfy insurer risk assessments. The technology is digitizing reactive maintenance schedules into predictive workflows that compress capital replacement cycles.
The UK Future Buildings Standard is mandating operational energy performance targets that cascade into FM service specifications for heating and cooling systems. Building operators must now document retrofit compliance pathways within maintenance contracts or face enforcement action from local authorities. Healthcare estates in England are responding fastest, embedding carbon reduction milestones into ten-year NHS trust agreements.
Integrated service contracts are displacing fragmented single-service arrangements as procurement teams seek consolidated accountability for hard and soft services. Corporate real estate directors in London and Birmingham are consolidating vendor panels to reduce administrative overhead and improve cross-service coordination. This concentration is most visible in financial services and technology sector occupiers with multi-site footprints.
United Kingdom (UK) Facility Management Market Segmentation
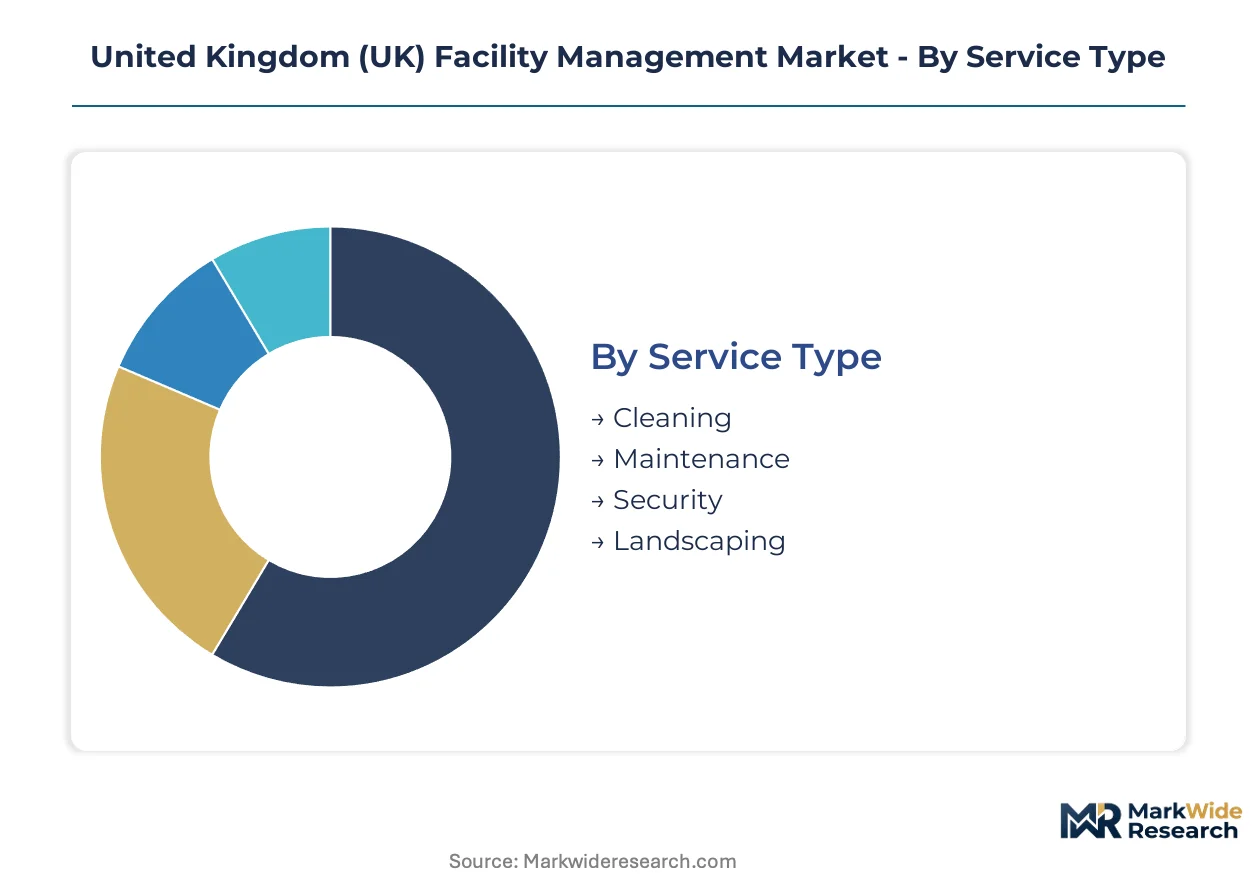
Service configuration and contract architecture determine margin capture and client retention in UK facility management. Procurement patterns across NHS trusts and commercial landlords favor integrated delivery models that compress vendor panels and extend contract tenures.
Service Type:
Mature maintenance and cleaning services anchor revenue pools, while technology-enabled security and specialized landscaping carve faster expansion paths.
- Maintenance:Hard services encompassing mechanical, electrical, and building fabric preservation dominate contract value. NHS estate modernization across England concentrates demand for predictive maintenance platforms that reduce unplanned downtime in aging hospital infrastructure.
- Cleaning:Soft services range from routine janitorial to specialized infection control protocols. Healthcare trusts in London and the Northern Powerhouse corridor are embedding clinical-grade cleaning specifications into framework agreements as Building Safety Act compliance tightens.
- Security:Technology-integrated guarding and access control systems serve commercial landlords. Demand accelerates in London's Grade A office stock where insurer risk assessments mandate IoT-enabled surveillance platforms.
- Landscaping:Grounds maintenance and biodiversity management support corporate estates and public sector campuses. Scope 3 carbon accounting requirements under UK Green Building Council frameworks are elevating sustainable horticulture specifications.
Maintenance retains volume leadership; security holds the steepest expansion curve.
Client Type:
Contract value concentrates with institutional clients bearing compliance-heavy estates, while healthcare modernization outpaces other verticals.
- Healthcare:NHS trusts represent the most dynamic demand pool as estate modernization accelerates hard services outsourcing. Framework agreement consolidation across England is narrowing vendor access to large hospital contracts with ten-year carbon reduction milestones embedded.
- Corporate:Financial services and technology sector occupiers with multi-site footprints drive integrated service adoption. London commercial landlords exceeding 500,000 square feet deploy CMMS-AI platforms to optimize asset lifecycle performance.
- Government:Central and local government estates prioritize cost certainty through outcome-based contracts. Building Regulations Part L compliance cascades into maintenance specifications for heating and cooling system retrofits.
- Educational:University campuses and school trusts balance budget constraints against sustainability targets. Energy performance contracting models are gaining traction across higher education estates in Manchester and Leeds.
Corporate commands the largest contract value pool; healthcare climbs the fastest.
Contract Model:
Procurement sophistication separates fragmented single-service arrangements from consolidated accountability structures.
- Integrated:Full-service contracts combining hard and soft services under single-vendor accountability displace fragmented arrangements. Corporate real estate directors in Birmingham and London consolidate vendor panels to reduce administrative overhead and improve cross-service coordination.
- Outsourced:Third-party provision of discrete service lines persists in mid-market commercial estates. Margin compression from energy price volatility challenges fixed-price heating, ventilation, and air conditioning maintenance providers.
- Hybrid:Blended models retain strategic functions in-house while outsourcing specialized technical services. NHS trusts deploy this architecture to preserve estate management expertise while accessing external mechanical and electrical engineering capacity.
- In-house:Direct employment of facilities staff concentrates in security-sensitive government buildings and heritage estates. Brexit-related skilled technician scarcity constrains expansion of captive engineering teams.
Integrated models capture margin premiums; hybrid structures gain share fastest among NHS trusts.
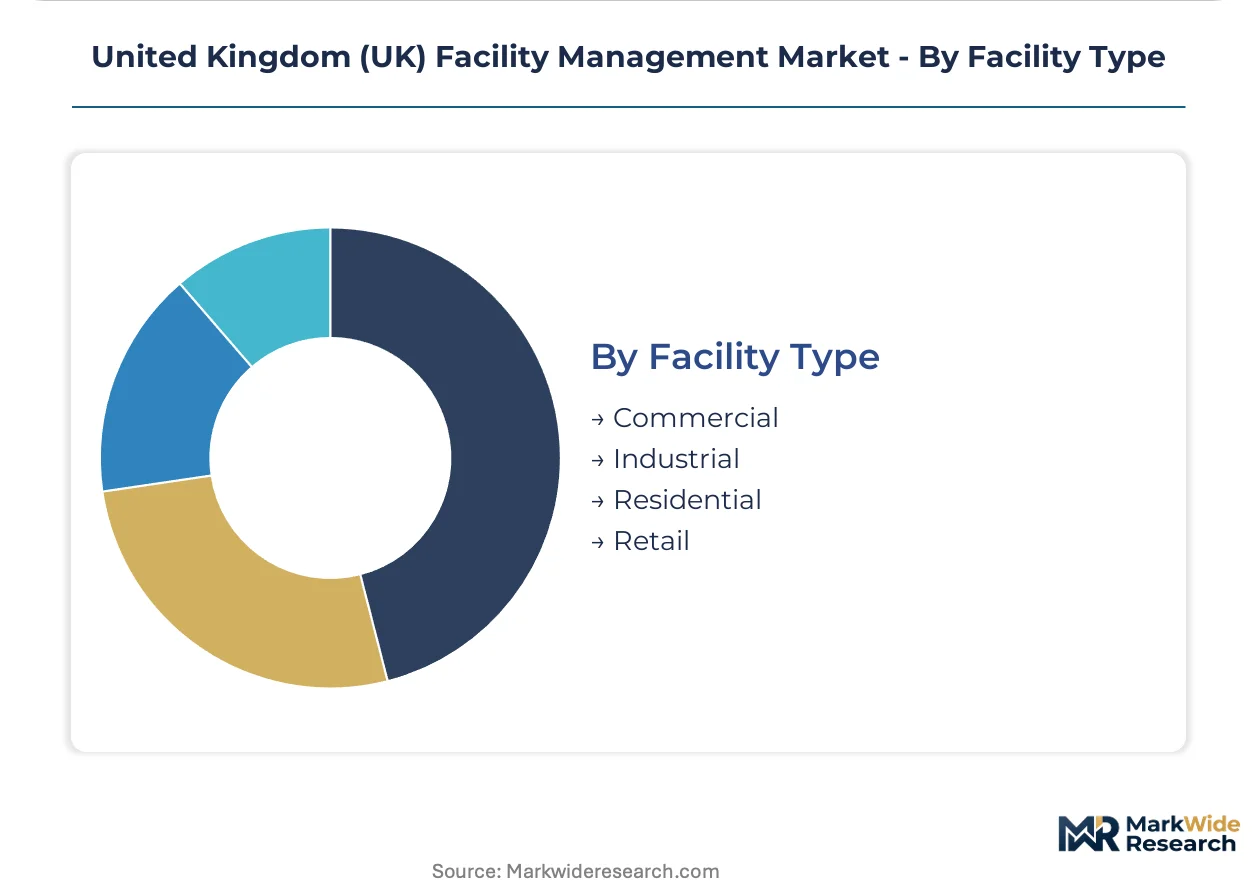
Facility Type:
Asset class characteristics dictate service intensity and technology deployment patterns.
- Commercial:Office buildings and business parks generate the deepest CMMS-AI platform penetration. London's core Grade A stock leads sensor network deployment for predictive maintenance workflows that satisfy insurer risk assessments.
- Industrial:Manufacturing estates and logistics facilities demand specialized mechanical maintenance and compliance documentation. The Northern Powerhouse corridor's warehouse expansion creates greenfield demand for integrated FM contracts outside saturated London markets.
- Retail:Shopping centers and high-street portfolios prioritize cleaning and security visibility. Footfall recovery patterns post-pandemic are reshaping service frequency specifications across regional mall operators.
- Residential:Build-to-rent and social housing estates require responsive maintenance and communal area management. Building Safety Act enforcement is elevating competency certification requirements for high-risk building maintenance contractors.
Commercial dominates technology investment; industrial posts the steepest contract growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The HS2 rail corridor underwrites the Midlands' emergence as a logistics and commercial hub, redistributing FM demand northward from London's saturated core. This infrastructure spine reshapes service provider deployment patterns across England.
London and the Southeast
Grade A office stock exceeding 500,000 square feet drives CMMS-AI platform penetration for predictive maintenance workflows. The Building Safety Act enforces competency certification for high-risk building maintenance contractors. Canary Wharf and the City of London concentrate demand for integrated security and access control systems.
Midlands
Birmingham's commercial expansion and the HS2 interchange at Curzon Street generate greenfield integrated FM contracts. Building Regulations Part L compliance cascades into heating and cooling system retrofit specifications across West Midlands estates. The East Midlands logistics corridor attracts warehouse-focused maintenance providers serving distribution networks.
North England
Manchester and Leeds anchor the Northern Powerhouse corridor's fastest-growing contract pool outside London. NHS trust framework agreements consolidate vendor relationships for hospital estate modernization across Greater Manchester. Liverpool's port infrastructure supports industrial FM demand for maritime logistics facilities.
Scotland
Edinburgh and Glasgow public sector estates prioritize outcome-based contracts for cost certainty. The Scottish Government's net zero targets embed carbon reduction milestones into ten-year FM agreements. Aberdeen's energy transition shifts maintenance demand from offshore platforms to renewable infrastructure.
Wales
Cardiff's government and educational estates balance budget constraints against sustainability procurement rules. NHS Wales framework centralization narrows direct access for mid-tier FM vendors. The M4 corridor links industrial zones in Newport and Swansea to Bristol supply chains.
United Kingdom (UK) Facility Management Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in discrete service lines. The vendor base organizes around three tiers: full-service nationals capturing integrated contracts, regional specialists defending single-service niches, and technology-forward disruptors embedding IoT analytics. Consolidation accelerates through NHS procurement centralization and corporate real estate panel reduction. Vertical integration into in-house engineering teams and strategic technology licensing dominate competitive moves.
Within the full-service national tier, Mitie Group PLC and Serco Group PLC exemplify divergent heritage strategies—Mitie anchoring healthcare specialization, Serco leveraging government outsourcing lineage. CBRE Group Inc. occupies the technology-led commercial landlord segment. These three represent the archetype spectrum: healthcare-focused, public-sector-rooted, and asset-management-platform-driven respectively.
| Leading Market Players |
|---|
| Mitie Group PLC |
| ISS UK |
| Serco Group PLC |
| OCS Group UK Ltd. |
| CBRE Group Inc. |
| Compass Group PLC |
| EMCOR Group Inc. |
| Kier Group PLC |
| G4S Facilities Management UK |
| Others |
Pricing and Supply Chain Analysis
Engineering labor pools in Poland and Romania anchor cost-competitive service delivery for UK FM providers, concentrating margin capture with vendors who maintain captive technical recruitment channels rather than spot-market hiring.
Pricing Analysis
Volume-discount tiering separates NHS framework contracts above £50 million annual value from mid-tier commercial estates and small-site retail portfolios. Price differentiation rests on Building Safety Act certification status and IoT platform integration depth. Cost compression in standard-tier maintenance contracts is intensifying because energy price volatility erodes fixed-price HVAC margins. NHS procurement teams exhibit lowest price sensitivity due to compliance-driven specification rigidity, while retail landlords remain most sensitive to per-square-foot service costs.
Supply Chain Analysis
Export-control regimes limiting dual-use sensor technology flows from the United States complicate IoT platform deployment for predictive maintenance vendors. Component sourcing draws from China for sensor hardware, Germany for building automation controllers, and the Netherlands for HVAC equipment. Single-source vulnerability concentrates in CMMS software licensing from dominant SaaS providers. Distribution runs through framework-approved supplier lists maintained by NHS Shared Business Services and major corporate real estate advisors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK FM market operates as a defensive-moat sector where regulatory entrenchment via Building Safety Act competency requirements creates substantial switching costs for institutional clients.
For Market Incumbents: Insulate core NHS relationships by embedding carbon-accounting capabilities ahead of Future Buildings Standard enforcement deadlines. Pursue backward integration into specialist engineering training academies to offset Brexit-constrained technician supply. The emerging threat of technology-forward disruptors with AI-native CMMS platforms demands preemptive platform licensing or acquisition. For New Entrants and Emerging Players: Establish a beachhead in the Northern Powerhouse corridor's industrial logistics estates, where greenfield warehouse construction outpaces incumbent vendor coverage. Target mid-tier university estates in Manchester and Leeds with energy performance contracting models that transfer retrofit risk from capital-constrained clients. A direct-sales engineering team with local competency certification accelerates trust-building faster than subcontractor-dependent models. For Investors and Strategic Acquirers: Capital is best deployed toward integrated service providers with demonstrated NHS framework tenure and proprietary IoT analytics platforms rather than single-service specialists facing margin compression. The five-to-ten-year viability window favors vendors who consolidated during procurement centralization. Watch for inflection signals in HS2 construction milestones that would accelerate Midlands commercial development beyond current capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Competency Certification Investment | Building Safety Act contractor licensing creates regulatory moats against unqualified competitors. |
| CMMS-AI Platform Integration | Predictive maintenance contracts with London Grade A landlords command premium pricing tiers. |
| NHS Framework Consolidation | Approved supplier list inclusion determines access to ten-year hospital estate modernization programs. |
| Energy Performance Contracting | Retrofit risk transfer models unlock capital-constrained university and public sector estates. |
| Technical Training Academy Buildout | Captive engineering pipelines offset Brexit-constrained skilled technician availability. |
Research Methodology
A spread of perspectives from NHS estate directors, corporate real estate procurement leads, FM operations managers, and building automation engineers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against NHS procurement databases, Health and Safety Executive enforcement notices, UK Green Building Council framework documentation, and corporate tender records. Bottom-up contract value aggregation triangulated against top-down sector spending estimates.
Demand-supply-balance framing anchored the analytical approach across the analysis window. Segmentation dimensions modeled encompass service type, client vertical, contract architecture, and facility asset class. CAGRs derived from trend extrapolation of NHS outsourcing penetration rates, commercial office stock modernization cycles, and regulatory compliance cost trajectories. Forecast inputs incorporated IoT sensor deployment curves and skilled technician supply elasticity assumptions.
Sensitivities concentrate around NHS budget allocation shifts, HS2 construction timeline revisions, and Building Safety Act enforcement intensity variations. Forecasts reflect documented assumptions regarding framework consolidation velocity and carbon-accounting service adoption curves. Material shifts in post-Brexit labor mobility policy or energy price volatility regimes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Italy Facility Management Services Market
Facility Management
Facility Management Services Market
Facility Management
Singapore Facility Management Market
Facility Management
Netherlands Facility Management Market
Facility Management
North America Soft Facility Management Market
Facility Management
Latvia Facility Management Market
Facility Management
Croatia Facility Management Market
Facility Management
Middle East and Africa Soft Facility Management Market
Facility Management
Global Facility Management Software Market
Facility Management
India Integrated Facility Management Market
Facility Management
Refrigerated Warehousing Market
Facility Management
Saudi Arabia Soft Facility Management Market
Facility Management
Egypt Facility Management Market
Facility Management
Iceland Facility Management Market
Facility Management
Poland Facility Management Market
Facility Management
Romania Facility Management Market