
 Centrifugation-Free Sperm Separation Systems Market | 2026-2036
Centrifugation-Free Sperm Separation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Centrifugation-Free Sperm Separation Systems Market Analysis
German and Swiss precision manufacturing clusters is hardening the supply base for microfluidic separation chips. DxNow leverages its MEMS fabrication partnerships to sustain cost advantages in disposable chip production. Thermo Fisher Scientific anchors the high-throughput research segment with integrated workflow platforms. Hamilton Thorne competes through specialized imaging-compatible separation systems for time-lapse IVF laboratories.
Centrifugation-free sperm separation systems employ microfluidic channels, density gradient media, or membrane filtration to isolate motile spermatozoa without subjecting cells to damaging centrifugal forces exceeding 400g. These systems preserve DNA integrity and mitochondrial function, serving primarily to improve fertilization outcomes in assisted reproductive technology and reduce oxidative stress artifacts in research settings. Microfluidics product types command the deepest margin pools due to patent-protected channel geometries and consumable recurring revenue. Magnetic separation technology leads in clinical translation speed, while dielectrophoresis occupies an emerging niche for label-free selection based on electrical membrane properties.
FDA 510(k) clearance pathways and EU MDR Class IIa requirements shape product development timelines and clinical evidence burdens for manufacturers entering commercial distribution. ISO 13485 quality management standards and WHO laboratory guidelines for semen analysis further constrain design specifications and performance claims. Stakeholders must monitor evolving reimbursement codes for advanced sperm preparation in major IVF markets and calibrate R&D portfolios against regulatory divergence between North American and European conformity assessment routes.
Market Dynamics
Microfluidic chip fabrication concentration in German and Swiss precision manufacturing clusters is compressing procurement timelines for disposable separation consumables while elevating quality benchmarks for clinical-grade sperm preparation workflows.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for Class II reproductive devices are reducing commercialization barriers for microfluidic platform developers seeking US market entry.
- IVF laboratory automation:Time-lapse imaging integration demands from fertility clinics in the United States, Germany, and Japan are pulling compatible separation systems into standard procurement bundles.
- WHO semen analysis guideline updates:Revised laboratory standards for DNA fragmentation assessment are elevating centrifugation-free methods as reference procedures in andrology laboratories.
Market Restraints
- Polydimethylsiloxane (PDMS) supply volatility:Microfluidic chip substrate costs fluctuate with specialty silicone precursor availability from German chemical suppliers.
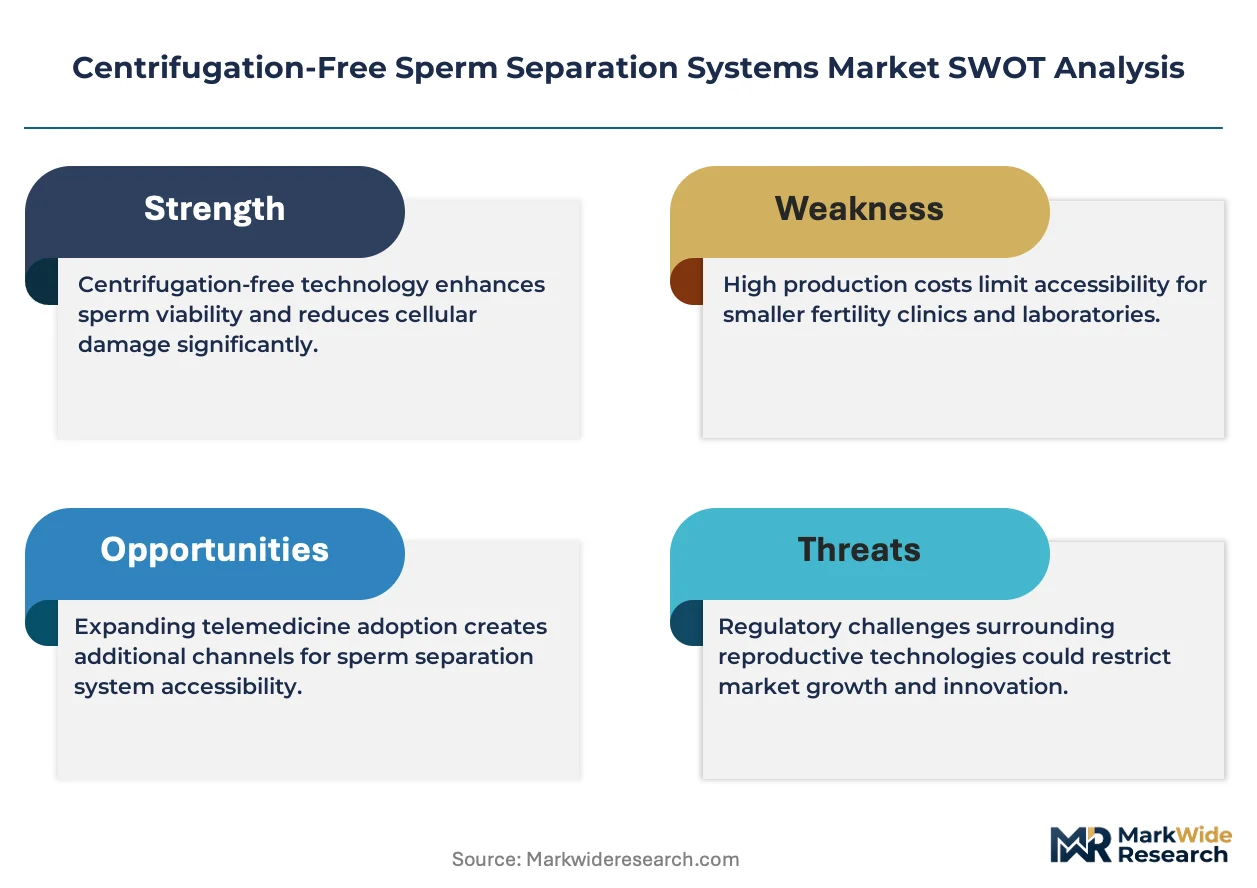
- EU MDR clinical evidence requirements:Stricter conformity assessment for Class IIa reproductive devices extends validation timelines and elevates documentation burdens for manufacturers.
- Limited substitute differentiation:Density gradient media remain entrenched in cost-sensitive fertility markets due to established reimbursement codes and lower per-procedure consumable expense.
Strategic Opportunities
- Japan's aging fertility patient demographic:Expanding government subsidization for advanced reproductive technology creates procurement pull for premium sperm preparation platforms.
- Dielectrophoresis-membrane hybrid systems:Convergence of label-free electrical selection with passive filtration opens functional selection based on membrane capacitance properties.
- Research cryobank segment:Unbundled sperm preparation services for biobanking applications represent underpenetrated demand outside clinical IVF workflows.
Industry Challenges
- MEMS fabrication talent scarcity:Cleanroom process engineering expertise concentrates in Swiss and German academic clusters, constraining rapid scale-up for disposable chip production.
- ISO 13485 certification timelines:Quality management system implementation for microfluidic device manufacturing extends operational readiness by twelve to eighteen months.
- Legacy centrifuge workflow integration:Fertility clinic capital equipment refresh cycles delay full platform replacement despite demonstrated clinical benefits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Centrifugation-Free Sperm Separation Systems Market |
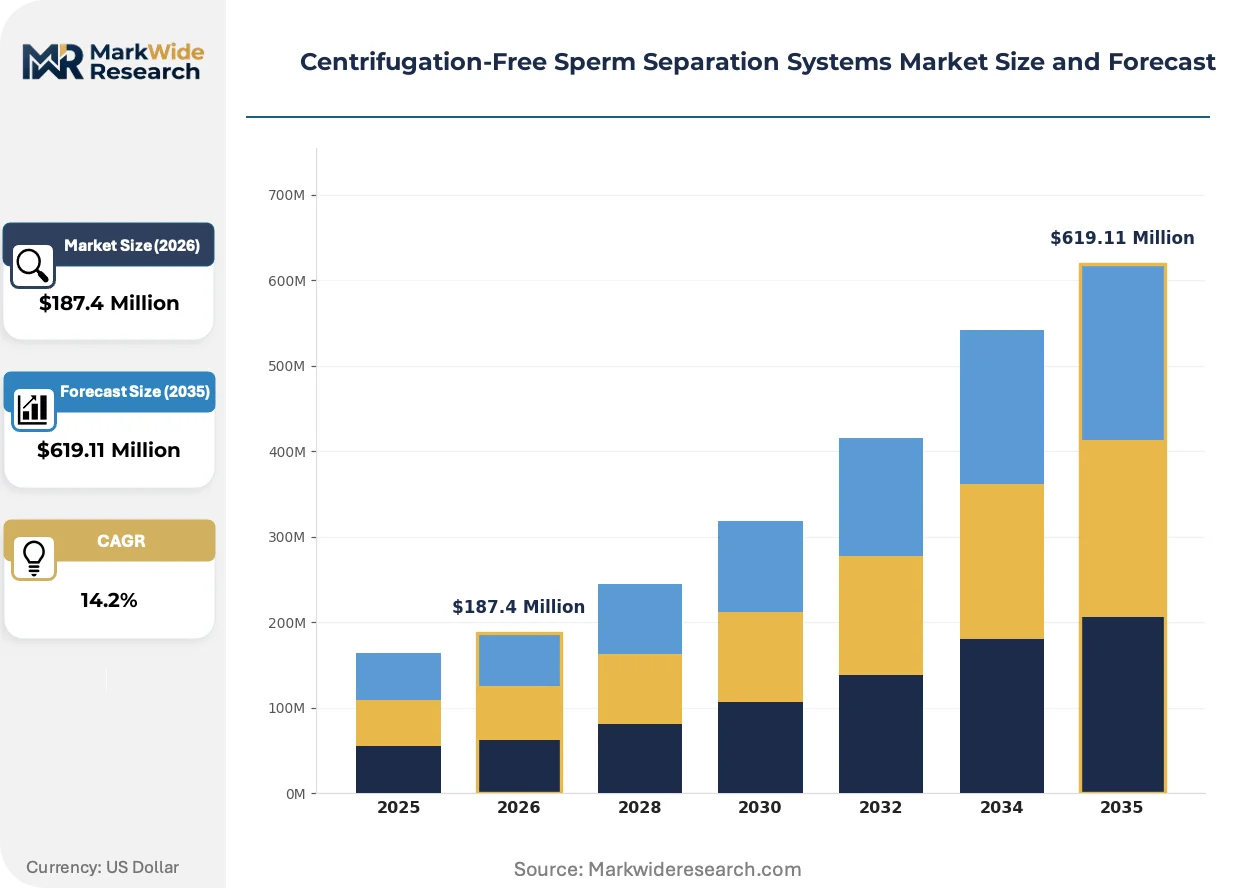
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfluidics, Density Gradient, Filtration, Separation Chips End User: Fertility Clinics, Research Laboratories, Hospitals, IVF Centers Technology: Magnetic Separation, Acoustic Separation, Dielectrophoresis, Membrane Technology Application: IVF, Sperm Banking, Genetic Screening, Assisted Reproductive Technology |
| Companies Covered | DxNow, Thermo Fisher Scientific, Hamilton Thorne, Cook Medical, Koek Biotechnology, CooperSurgical, Irvine Scientific, SAR Healthline Pvt. Ltd., Memphasys Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Centrifugation-Free Sperm Separation Systems Market Emerging Trajectories
Active materials science breakthroughs and regulatory harmonization efforts are compressing product development cycles while fragmenting competitive positioning across research and clinical application segments.
Acoustic radiation force microfluidics is converging with standard IVF laboratory workflows. Fertility clinics in Japan and Germany are piloting label-free sperm enrichment using surface acoustic wave chambers that separate motile cells without physical filtration. This convergence is compressing the performance gap between research-grade selection precision and clinical throughput requirements.
EU MDR Annex XIV clinical evaluation requirements are reshaping evidence generation strategies for microfluidic separation devices. Manufacturers must now demonstrate clinical performance equivalence through prospective studies rather than predicate device comparisons. High-throughput research platform developers face the steepest compliance burden as they pivot toward therapeutic device classifications.
Service unbundling is fragmenting traditional equipment-consumable bundling in fertility clinic procurement. Standalone sperm preparation service contracts are displacing capital purchase models in German university hospital networks. This pattern is most visible in Baden-Württemberg and Bavaria, where centralized laboratory services consolidate multiple clinic volumes under single technical operation agreements.
Centrifugation-Free Sperm Separation Systems Market Segmentation
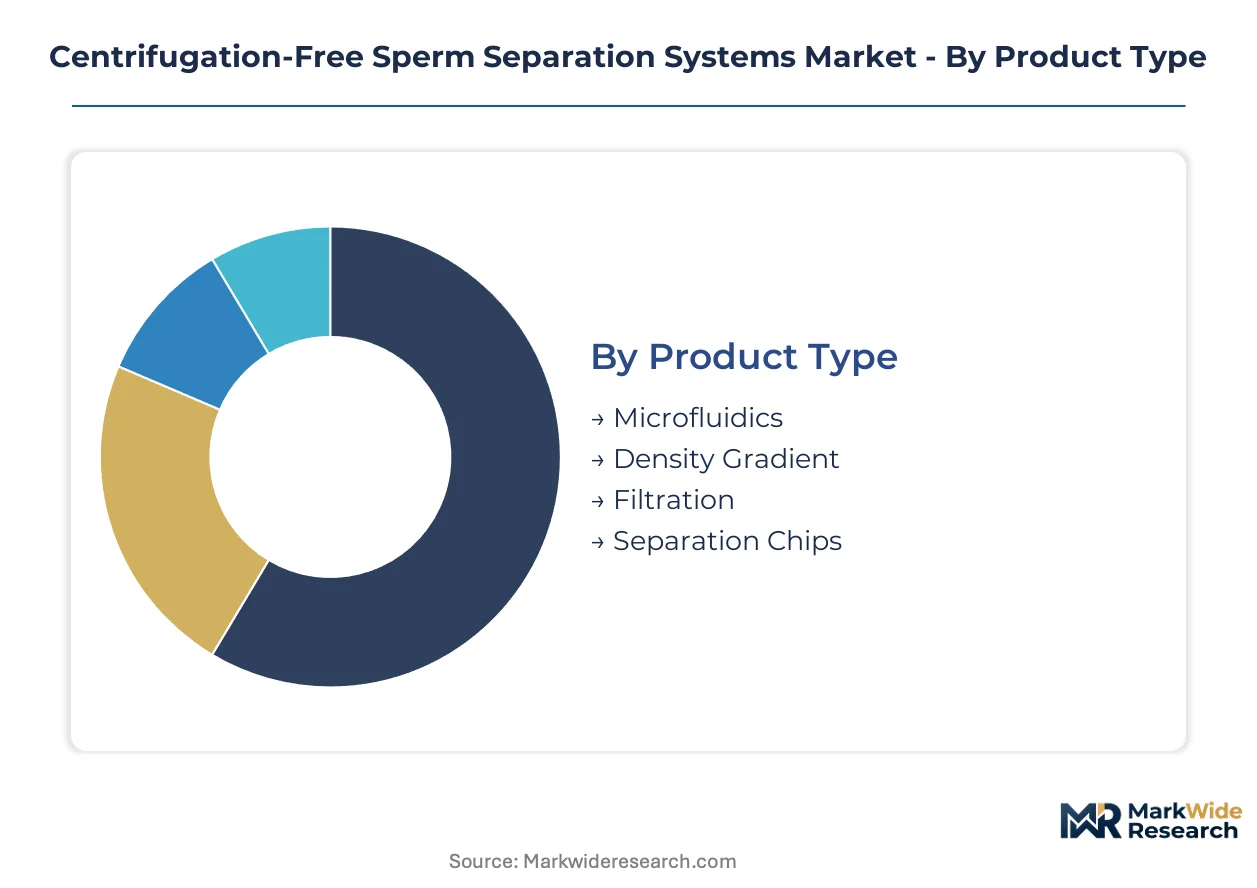
Segmentation in centrifugation-free sperm separation systems reveals how technical specifications, clinical settings, and regulatory pathways intersect to shape procurement patterns. Each dimension carries distinct margin profiles, evidence requirements, and integration complexity that determine competitive positioning across the value chain.
Product Type:
Channel geometry and substrate material choices define performance ceilings and manufacturing scalability for each platform architecture.
- Microfluidics:Polydimethylsiloxane and thermoplastic substrates form labyrinthine channel networks that exploit sperm motility differentials. Demand clusters in German university hospital networks where time-lapse IVF integration justifies premium consumable pricing.
- Density Gradient:Silica-coated colloidal suspensions create buoyant separation columns without mechanical force. Established reimbursement codes in United States fertility markets sustain volume despite inferior DNA integrity outcomes compared to microfluidic alternatives.
- Filtration:Membrane pore-size selection isolates motile populations through passive sieving. Cost-sensitive clinics in Japan favor this modality for government-subsidized ART cycles.
- Separation Chips:Disposable cartridge formats integrate pre-loaded media with standardized fluidic interfaces. Swiss precision manufacturing clusters dominate substrate supply for clinical-grade chip production.
Mature deployment sits with Density Gradient. Newer deployment is concentrated in Microfluidics.
End User:
Procurement authority and reimbursement access determine which customer types drive premium platform adoption versus commodity consumable volume.
- Fertility Clinics:Private practice networks in Bavaria and Baden-Württemberg consolidate sperm preparation services under centralized laboratory contracts. These arrangements favor integrated microfluidic platforms with automated quality documentation.
- Research Laboratories:Academic andrology departments require flexible protocols for experimental sperm selection methods. Cryobank applications for donor specimen processing represent expanding demand outside clinical IVF workflows.
- Hospitals:Public health system procurement in Japan emphasizes capital efficiency and multi-purpose equipment utilization. Government subsidization frameworks limit per-procedure consumable expenditure.
- IVF Centers:Dedicated reproductive medicine facilities in the United States pursue laboratory accreditation through CAP and WHO semen analysis guideline compliance. Time-lapse imaging compatibility shapes separation system selection.
Volume concentration rests with Fertility Clinics. Margin expansion is strongest in Research Laboratories.
Technology:
Physical separation mechanisms differ in label requirements, throughput capacity, and regulatory validation burden for clinical translation.
- Magnetic Separation:Antibody-conjugated paramagnetic beads isolate subpopulations based on surface antigen expression. FDA 510(k) predicate device pathways accelerate clearance for platforms targeting specific sperm maturity markers.
- Acoustic Separation:Surface acoustic wave chambers exert radiation forces that concentrate motile cells in pressure nodes. Pilot deployments in Tokyo fertility clinics demonstrate label-free enrichment without physical filtration barriers.
- Dielectrophoresis:Non-uniform electric fields exploit membrane capacitance differences between morphologically normal and abnormal spermatozoa. Emerging niche for DNA fragmentation-based selection in research settings.
- Membrane Technology:Track-etched or phase-inversion membranes provide deterministic size exclusion. Integration with microfluidic manifolds enables multi-stage purification in compact disposable formats.
Clinical translation speed favors Magnetic Separation. Steepest expansion trajectory belongs to Acoustic Separation.
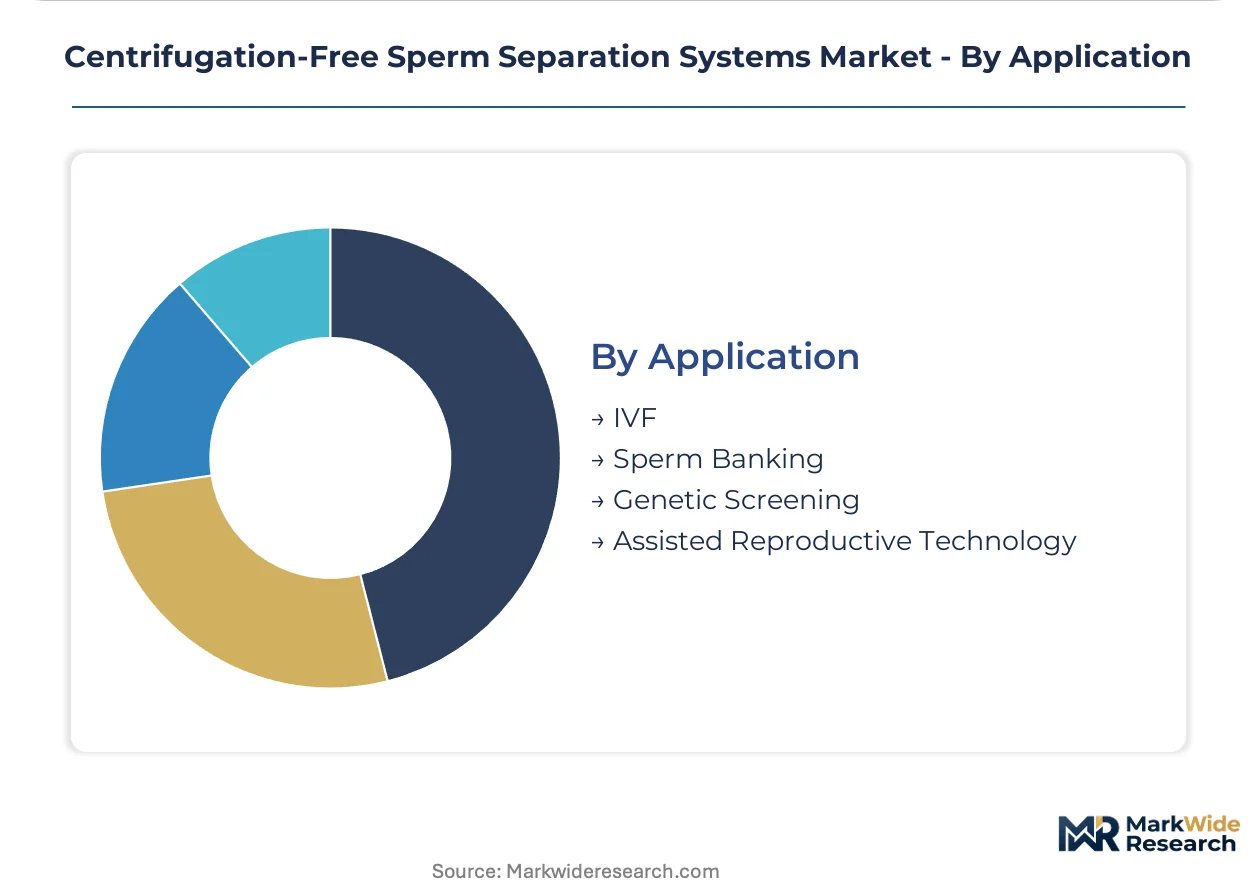
Application:
Clinical outcome requirements and specimen handling protocols create divergent performance specifications across use cases.
- IVF:Standard in vitro fertilization workflows demand motile sperm recovery rates exceeding 80% with minimal DNA fragmentation induction. EU MDR Class IIa conformity assessment governs device marketing for therapeutic use.
- Sperm Banking:Cryopreservation preparation prioritizes post-thaw motility retention over immediate fertilization capacity. Biobanking service contracts in German university networks consolidate demand for high-throughput separation platforms.
- Genetic Screening:Preimplantation genetic testing workflows require sperm isolation without contaminating maternal DNA or cellular debris. Dielectrophoresis enables label-free selection based on nuclear maturity indicators.
- Assisted Reproductive Technology:Broad category encompassing ICSI, IUI, and emerging gamete manipulation techniques. WHO laboratory guideline updates elevate centrifugation-free methods as reference procedures across ART modalities.
Revenue concentration aligns with IVF. Regulatory scrutiny intensity peaks in Genetic Screening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Swiss polydimethylsiloxane precursor supply chains anchor microfluidic chip fabrication for centrifugation-free sperm separation platforms across major IVF markets.
United States
Fertility clinic consolidation in California and Massachusetts drives procurement of time-lapse-compatible separation systems. FDA 510(k) pathway streamlining for Class II reproductive devices accelerates commercialization timelines for microfluidic platform developers. Greater Boston laboratory networks pilot acoustic separation technology for label-free sperm enrichment.
Germany
Baden-Württemberg and Bavaria university hospitals consolidate sperm preparation services under centralized technical operation agreements. EU MDR Class IIa conformity assessment requirements elevate clinical evidence burdens for manufacturers entering commercial distribution. Freiburg precision manufacturing clusters supply clinical-grade thermoplastic substrates for disposable separation chips.
Japan
Tokyo fertility clinics pilot surface acoustic wave chambers for motile cell enrichment without physical filtration barriers. METI-subsidized advanced reproductive technology programs expand procurement pull for premium sperm preparation platforms. Kansai region government-subsidized ART cycles favor membrane filtration modalities for cost-sensitive applications.
Switzerland
Swiss precision manufacturing clusters dominate substrate supply for clinical-grade microfluidic chip production. Swissmedic regulatory frameworks align with EU MDR requirements for reproductive device marketing authorization. Basel-area MEMS fabrication partnerships sustain cost advantages in disposable chip manufacturing.
United Kingdom
London and Southeast IVF centers pursue CAP laboratory accreditation through WHO semen analysis guideline compliance. MHRA post-Brexit regulatory divergence from EU MDR creates separate conformity assessment routes for device manufacturers. Cambridge research laboratories expand cryobank applications for donor specimen processing outside clinical workflows.
Centrifugation-Free Sperm Separation Systems Market Vendor Landscape
Global majors compete with regional champions across microfluidic fabrication capabilities and IVF laboratory integration depth. Market structure fragments across three tiers: integrated life science conglomerates with workflow platforms, specialized reproductive device manufacturers with imaging-compatible systems, and emerging MEMS fabrication specialists with disposable chip cost advantages. Dominant competitive moves include strategic partnerships with German and Swiss precision manufacturing clusters and technology licensing for acoustic separation modalities.
Within the specialized reproductive device tier, DxNow exemplifies MEMS fabrication partnership strategies for disposable chip production. Thermo Fisher Scientific occupies a position among integrated workflow platform providers serving high-throughput research segments. Hamilton Thorne anchors the imaging-compatible separation systems niche for time-lapse IVF laboratories. These three companies represent distinct archetypes competing across clinical translation speed, manufacturing scalability, and laboratory automation integration vectors.
| Leading Market Players |
|---|
| DxNow |
| Thermo Fisher Scientific |
| Hamilton Thorne |
| Cook Medical |
| Koek Biotechnology |
| CooperSurgical |
| Irvine Scientific |
| SAR Healthline Pvt. Ltd. |
| Memphasys Ltd. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up fertility device specialists have consolidated procurement leverage across German and Swiss microfluidic substrate networks, compressing supplier margins while sustaining premium pricing for clinical-grade separation chips through ISO 13485 certification scarcity.
Pricing Analysis
Service-bundling configurations separate capital equipment purchase from consumable supply agreements, with three-tier pricing structure across premium, standard, and economy levels. Premium tiers bundle time-lapse imaging compatibility with automated quality documentation for Bavaria university hospital networks, while economy tiers strip after-sales support for cost-sensitive Japanese government-subsidized ART cycles. Pricing pressure stems from PDMS precursor cost volatility emanating from German chemical suppliers. Research laboratories exhibit lowest price sensitivity due to grant-funded procurement autonomy.
Supply Chain Analysis
Dual-sourcing qualification requirements from FDA-cleared manufacturers mandate redundant PDMS substrate suppliers across German and Swiss precision manufacturing clusters. Clinical-grade chip fabrication draws from Freiburg thermoplastic substrate specialists and Basel-area MEMS foundries. Raw material dependencies center on polydimethylsiloxane precursors, silica-coated colloidal density gradient media, and track-etched membrane substrates. Single-source vulnerability concentrates in Swiss cleanroom process engineering talent pools. Distribution runs through centralized laboratory service contracts consolidating multiple clinic volumes under single technical operation agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS fabrication cleanroom capacity scarcity across Swiss and German academic clusters props pricing discipline for clinical-grade microfluidic chips, constraining rapid scale-up despite expanding IVF automation demand.
For Market Incumbents: Extend MEMS fabrication partnerships into captive supply arrangements for PDMS substrate precursors, insulating margin structures from German chemical supplier volatility. Acquire acoustic separation technology licenses from Tokyo pilot programs before regulatory clearance accelerates competitive diffusion. Priority defensive positioning targets time-lapse IVF laboratory integration depth as substitute magnetic separation platforms gain FDA 510(k) predicate pathway traction.
For New Entrants and Emerging Players: German university hospital cryobank service contracts offer the most penetrable white-space target, with unbundled sperm preparation services displacing capital purchase models across Baden-Württemberg and Bavaria. Dielectrophoresis-membrane hybrid systems for DNA fragmentation-based selection represent underexploited research laboratory demand outside clinical IVF workflows. Go-to-market execution should prioritize GPO contracts managers at consolidating fertility clinic networks over direct capital equipment sales.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized reproductive device manufacturers with EU MDR Class IIa technical documentation packages already assembled, particularly those anchored in Freiburg precision manufacturing clusters. Long-term viability hinges on reimbursement code expansion for advanced sperm preparation across United States fertility markets. Signal to monitor: FDA 510(k) clearance volume acceleration for microfluidic platform developers, indicating regulatory pathway maturation and competitive entry threshold elevation.
| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Fabrication Partnership Expansion | Captive PDMS substrate supply from German chemical networks insulates margin compression from precursor volatility. |
| Acoustic Separation Technology Licensing | Surface acoustic wave chamber patents from Tokyo pilot programs secure label-free enrichment positioning before FDA clearance acceleration. |
| EU MDR Class IIa Technical Documentation Assembly | Prospective clinical study completion satisfies Annex XIV equivalence requirements ahead of predicate device pathway restrictions. |
| Cryobank Service Contract Penetration | Baden-Württemberg university hospital network consolidation creates recurring revenue outside capital equipment refresh cycles. |
| Time-Lapse Imaging Compatibility Certification | CAP laboratory accreditation alignment with WHO semen analysis guidelines locks in fertility clinic procurement bundles. |
Methodological Framework
FDA 510(k) device filings, EU MDR technical documentation databases, and WHO laboratory guideline archives formed the secondary backbone for market sizing and competitive positioning validation. Primary interviews with biomedical engineers at German university hospital networks, GPO contracts managers at consolidating United States fertility clinic chains, and cleanroom process engineering directors at Swiss MEMS fabrication facilities triangulated demand forecasts against secondary data. Bottom-up procedure volume estimates across IVF, sperm banking, and genetic screening applications converged with top-down expenditure analysis from national ART reimbursement databases.
Historical trendline analysis of microfluidic chip procurement patterns across German precision manufacturing clusters established baseline growth trajectories. The analytical framework segmented demand across product type, end user, technology, and application dimensions, with regional regulatory cluster variations modeled separately. CAGRs were derived from fitted growth curves applied to procedure volume projections and per-procedure consumable pricing trends. Industry-specific forecast inputs incorporated EU MDR implementation timeline assumptions and METI subsidy expansion scenarios for Japanese advanced reproductive technology.
Caveats apply where FDA 510(k) pathway streamlining reverses or EU MDR clinical evidence requirements intensify beyond current Annex XIV interpretations, materially shifting commercialization timelines and competitive entry economics. Deviation in Swiss cleanroom engineering talent availability or German PDMS precursor supply continuity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Surgical Visualization Products Market
Medical Devices
Global Electrotherapy System Market
Medical Devices
Pressotherapy Systems Market
Medical Devices
Enteral Stents Market
Medical Devices
Nephrostomy Devices Market
Medical Devices
Balloon Inflation Devices Market
Medical Devices
Global Pacemakers Market
Medical Devices
Brazil Minimally Invasive Surgery Devices Market
Medical Devices
Global Blood Ketone Meter Market
Medical Devices
Global Brachytherapy Devices Market
Medical Devices
Germany Spinal Surgery Devices Market
Medical Devices
North America Laser Hair Removal Market
Medical Devices
North America Wearable Medical Devices Market
Medical Devices
Global Nasal Cannula Market
Medical Devices
Knee Reconstruction Devices Market
Medical Devices
Brazil Artificial Organs and Bionic Implants Market