
 Asia-Pacific Digital X-Ray Devices Market | 2026-2036
Asia-Pacific Digital X-Ray Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Digital X-Ray Devices Market Outlook
A-Si flat-panel detectors are pivoting away from legacy amorphous selenium substrates across the Asia-Pacific digital x-ray landscape, cutting unit costs while preserving diagnostic resolution. GE Healthcare leverages captive manufacturing of scintillator materials to sustain margin control across Southeast Asian tenders. Siemens Healthineers anchors its regional position through R&D partnerships with Japanese university hospitals. Fujifilm Holdings Corporation differentiates via proprietary ISS technology that reduces radiation exposure in pediatric screening protocols.
Digital x-ray devices convert ionizing radiation into electronic images through solid-state detectors, typically employing cesium iodide or gadolinium oxysulfide scintillators layered on thin-film transistor arrays, with spatial resolution commonly ranging from 2.5 to 5 line pairs per millimeter for clinical diagnosis. The technology's primary purpose is to replace film-based radiography with immediate image acquisition, transmission, and storage integrated into hospital information systems. Direct Radiography systems now dominate new hospital procurement in Australia and South Korea due to faster workflow throughput and lower total cost of ownership compared to Computed Radiography. Portable digital systems represent the fastest-expanding product configuration, driven by emergency department retrofit cycles and point-of-care screening programs in India's public health infrastructure.
Japan's PMDA enforces stringent detector calibration standards that shape product certification timelines for manufacturers seeking market entry, while Australia's TGA aligns with IEC 60601-1-3 radiation safety benchmarks that dictate dose optimization requirements across all imported equipment. China's NMPA has tightened registration pathways for wireless digital radiography systems, compelling vendors to demonstrate electromagnetic compatibility in dense hospital network environments. Stakeholders must monitor how India's CDSCO adapts its medical device rules to harmonize with ASEAN regulatory frameworks, as this alignment will determine which certification strategies unlock the largest addressable patient populations.
Market Dynamics
Hospital procurement committees across Southeast Asia are consolidating vendor relationships around single-source digital radiography contracts, compressing supplier margins while accelerating replacement cycles for aging analog equipment.
Growth Catalysts
- India's PLI Scheme:Domestic manufacturing incentives for medical electronics are expanding local production capacity for flat-panel detectors and reducing import dependency for public hospital tenders.
- Emergency department retrofit programs:Portable digital x-ray systems are displacing fixed installations in India's tier-one city hospitals as throughput demands intensify.
- Wireless DR certification pathways:China's NMPA streamlined electromagnetic compatibility testing requirements, accelerating product registration timelines for networked radiography equipment.
Market Restraints
- Cesium iodide crystal supply concentration:Scintillator material production clusters in Japanese and South Korean chemical processing facilities, exposing detector manufacturers to single-source risk.
- Japan's PMDA calibration mandates:Extended detector validation protocols for imported equipment create six-to-nine month certification delays that favor incumbent domestic suppliers.
- Computed Radiography residual installed base:Australia's regional healthcare networks maintain CR cassette systems to defer capital expenditure, slowing full digital conversion.
Strategic Opportunities
- Indonesia's healthcare infrastructure expansion:Provincial hospital construction programs in Java and Sumatra are specifying digital radiography in greenfield procurement packages.
- Pediatric screening protocol differentiation:Low-dose imaging configurations for neonatal intensive care units represent an underserved application segment with premium pricing potential.
- Telemedicine integration:Cloud-based image transmission capabilities are enabling remote radiologist interpretation for rural clinics in Thailand's public health system.
Industry Challenges
- Detector calibration technician scarcity:Australia's regional hospitals struggle to recruit personnel qualified for A-Si flat-panel maintenance under TGA-mandated service intervals.
- Legacy PACS integration complexity:South Korean hospital information systems require custom middleware development to interface with new wireless DR acquisition workstations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Digital X-Ray Devices Market |
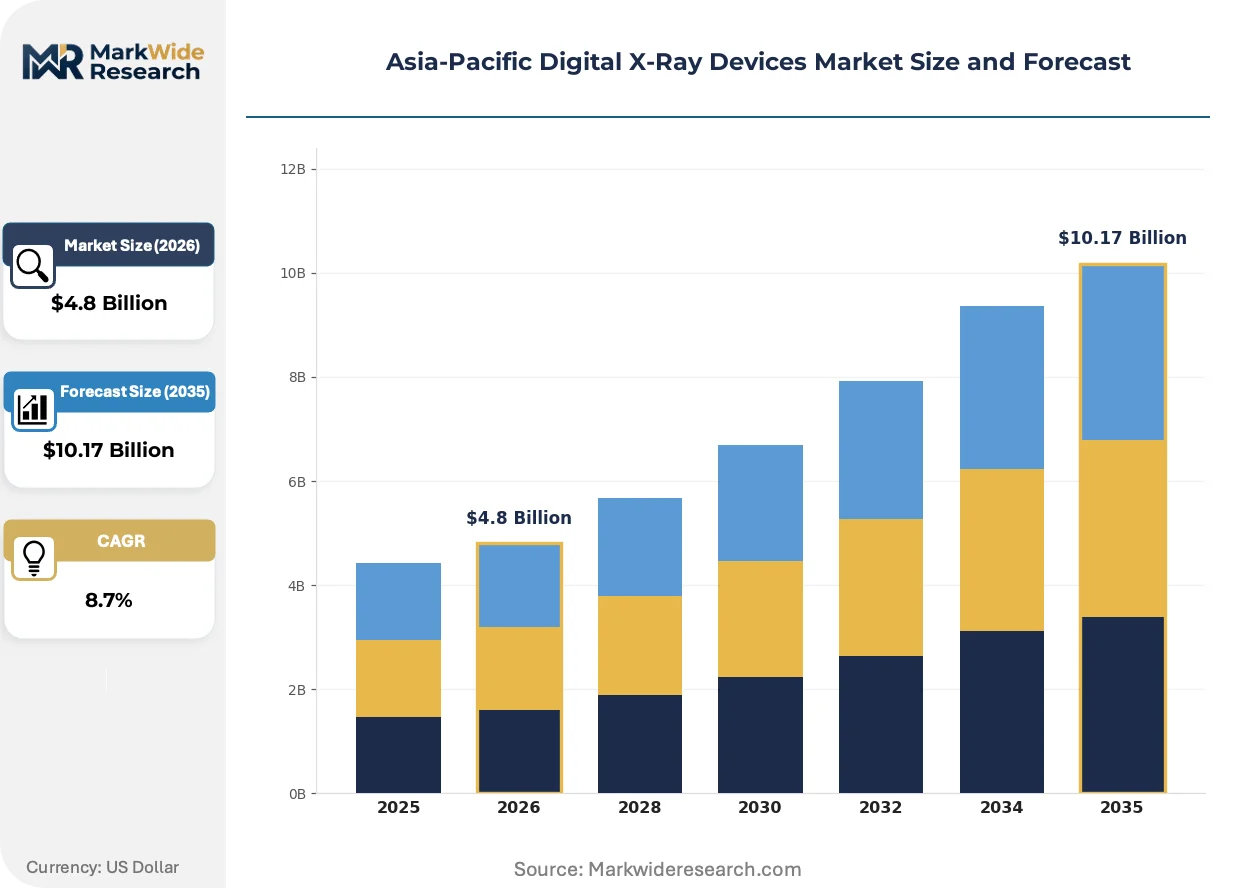
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Portable, Fixed Technology: Computed Radiography, Direct Radiography, Hybrid Systems, Wireless Systems End User: Hospitals, Imaging Centers, Dental Clinics, Veterinary Clinics Application: Orthopedics, Dentistry, Mammography, Cardiovascular |
| Companies Covered | GE Healthcare, Siemens Healthineers, Fujifilm Holdings Corporation, Koninklijke Philips, Canon Medical Systems Corporation, Shimadzu Corporation, Hologic, Carestream Health, Hitachi Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Digital X-Ray Devices Market Strategic Shifts
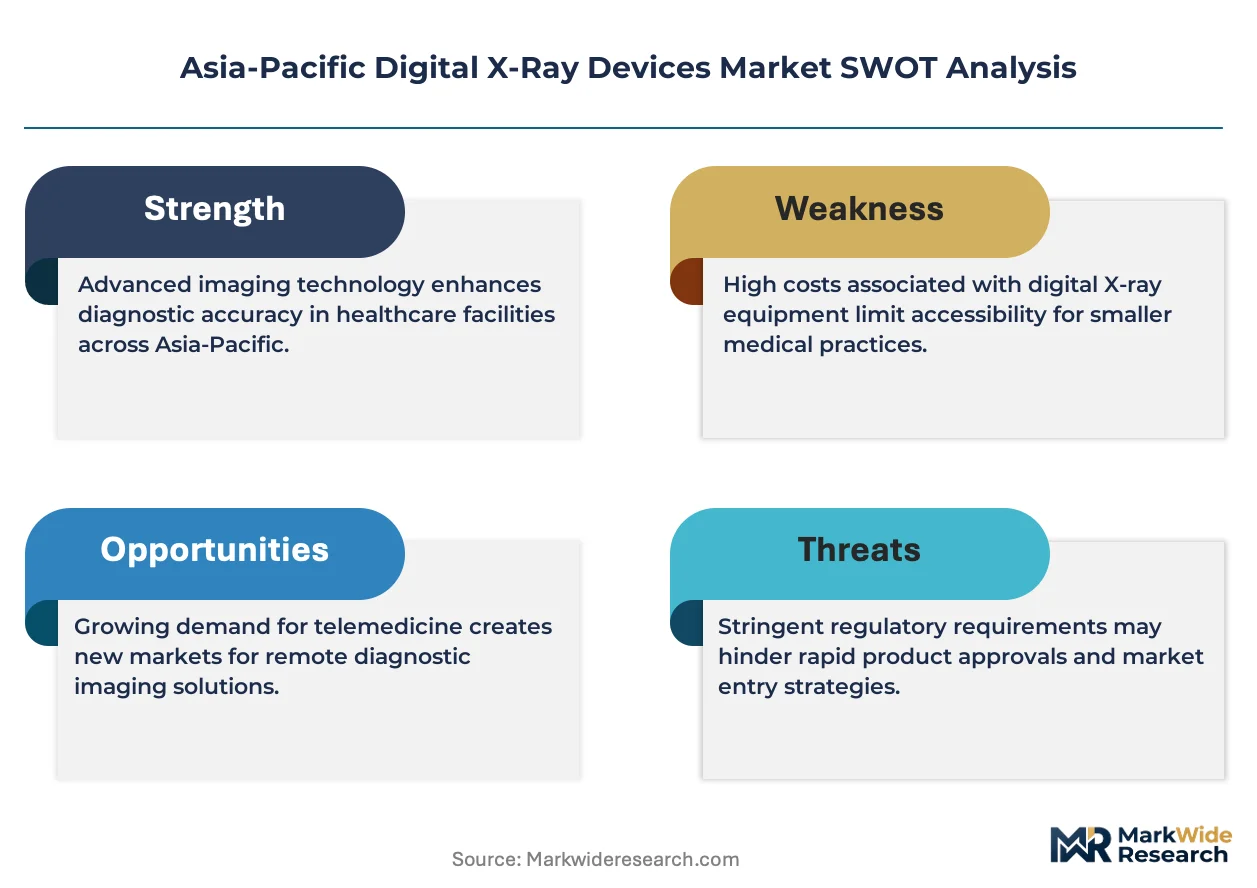
Detector architecture convergence and regulatory harmonization pressures are compressing product differentiation timelines across the Asia-Pacific digital radiography supply base.
Artificial intelligence-based image enhancement algorithms are unifying diagnostic workflow efficiency across high-volume screening programs. Public hospital networks in South Korea are deploying these tools for tuberculosis detection in mobile health units. The technology is unifying radiologist productivity metrics with automated measurement protocols that reduce interpretation time per study.
China's NMPA tightened electromagnetic compatibility standards for wireless digital radiography systems operating in dense hospital network environments. Equipment vendors must now demonstrate interference resilience across 2.4 GHz and 5 GHz spectrum bands before market authorization. South Korean manufacturers are responding by integrating proprietary frequency-hopping protocols that exceed baseline IEC 60601-1-2 requirements.
Service contract unbundling is fragmenting traditional equipment procurement relationships across Australia's private hospital sector. Buyers are separating hardware acquisition from maintenance agreements and software subscription fees. This restructuring is most visible in Queensland's regional health districts, where procurement committees negotiate detector replacement schedules independently from original installation vendors.
Asia-Pacific Digital X-Ray Devices Market Segmentation
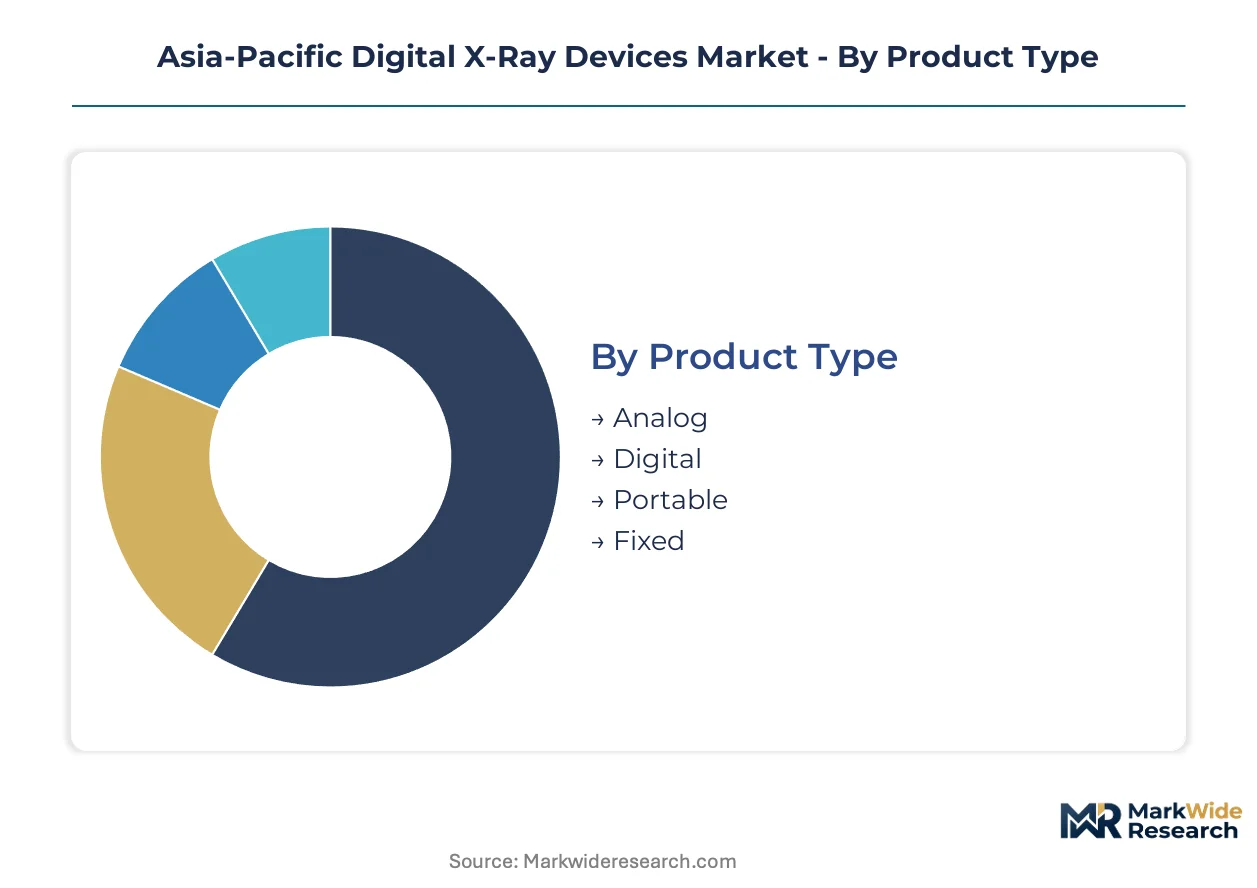
Segmentation in the Asia-Pacific digital x-ray market reveals how procurement priorities diverge across public hospital networks, private imaging chains, and specialized clinics. Each dimension—product configuration, detector technology, clinical setting, and anatomical application—carries distinct margin profiles and regulatory compliance burdens that reshape vendor go-to-market strategies.
Product Type:
Standardization dominates analog and fixed installations, while portable configurations demand customization for battery capacity, wireless range, and ruggedized chassis design.
- Analog:Legacy screen-film systems persist in India's rural primary health centers and Indonesia's provincial hospitals where capital budgets constrain digital conversion. Replacement demand concentrates in Vietnam's district-level facilities as Ministry of Health modernization grants expand.
- Digital:Direct-capture flat-panel systems anchor new hospital construction across China's tier-two cities and Australia's metropolitan networks. PACS integration requirements drive specification complexity, with South Korean buyers mandating HL7 FHIR compatibility for enterprise imaging archives.
- Portable:Battery-powered mobile units serve emergency departments and intensive care units in Thailand's public hospital system. Compact form factors and extended wireless range differentiate procurement winners in Japan's space-constrained urban facilities.
- Fixed:Ceiling-suspended and floor-mounted installations dominate high-throughput radiology departments in Australia's private hospital chains. Tube-detector positioning automation reduces technician workload in Malaysia's understaffed public imaging centers.
Most installed capacity flows through Digital systems. Expansion is steepest in Portable configurations.
Technology:
Cost tiers separate legacy cassette-based workflows from premium wireless architectures, with hybrid systems occupying a narrowing middle band.
- Computed Radiography:Photostimulable phosphor plate systems retain installed base in Australia's regional health networks deferring full digital conversion. Cassette compatibility with existing bucky stands reduces retrofit capital for Queensland's rural hospitals.
- Direct Radiography:Solid-state flat-panel detectors with integrated readout electronics command premium pricing in Japan's university hospitals and South Korea's cancer screening centers. Immediate image availability accelerates emergency department throughput in Singapore's public health system.
- Hybrid Systems:CR-to-DR upgrade pathways allow phased migration for India's mid-tier private hospitals balancing capital constraints against workflow efficiency targets. Detector sharing across multiple tube stands optimizes equipment utilization in Indonesia's resource-limited provincial facilities.
- Wireless Systems:Battery-integrated flat panels eliminate tethering constraints for surgical suite and neonatal unit deployments in China's tier-one city hospitals. China's NMPA electromagnetic compatibility mandates shape product development priorities for domestic and imported equipment alike.
Direct Radiography captures the dominant revenue share. Wireless Systems are gaining share fastest as hospital network density intensifies.
End User:
Volume concentration varies sharply across customer types, with hospitals driving procurement scale and dental clinics fragmenting vendor relationships.
- Hospitals:Acute care networks in Australia and South Korea consolidate radiography procurement through multi-year enterprise agreements. India's AIIMS-affiliated institutions anchor tender volumes for high-specification fluoroscopy-capable systems.
- Imaging Centers:Independent diagnostic chains in China's urban clusters prioritize throughput-optimized configurations with automated patient positioning. Australia's primary care co-located imaging services demand compact footprints for retail clinic integration.
- Dental Clinics:Intraoral and panoramic systems serve Thailand's expanding private dental practice base. Sensor size standardization and software compatibility with practice management systems determine purchase decisions.
- Veterinary Clinics:Specialized positioning tables and extended detector formats accommodate equine and small animal imaging in Australia's veterinary specialist networks. Price sensitivity limits premium feature adoption in India's emerging pet care market.
Hospitals account for the largest installed base. Imaging Centers show the steepest expansion trajectory as outpatient diagnostic volumes rise.
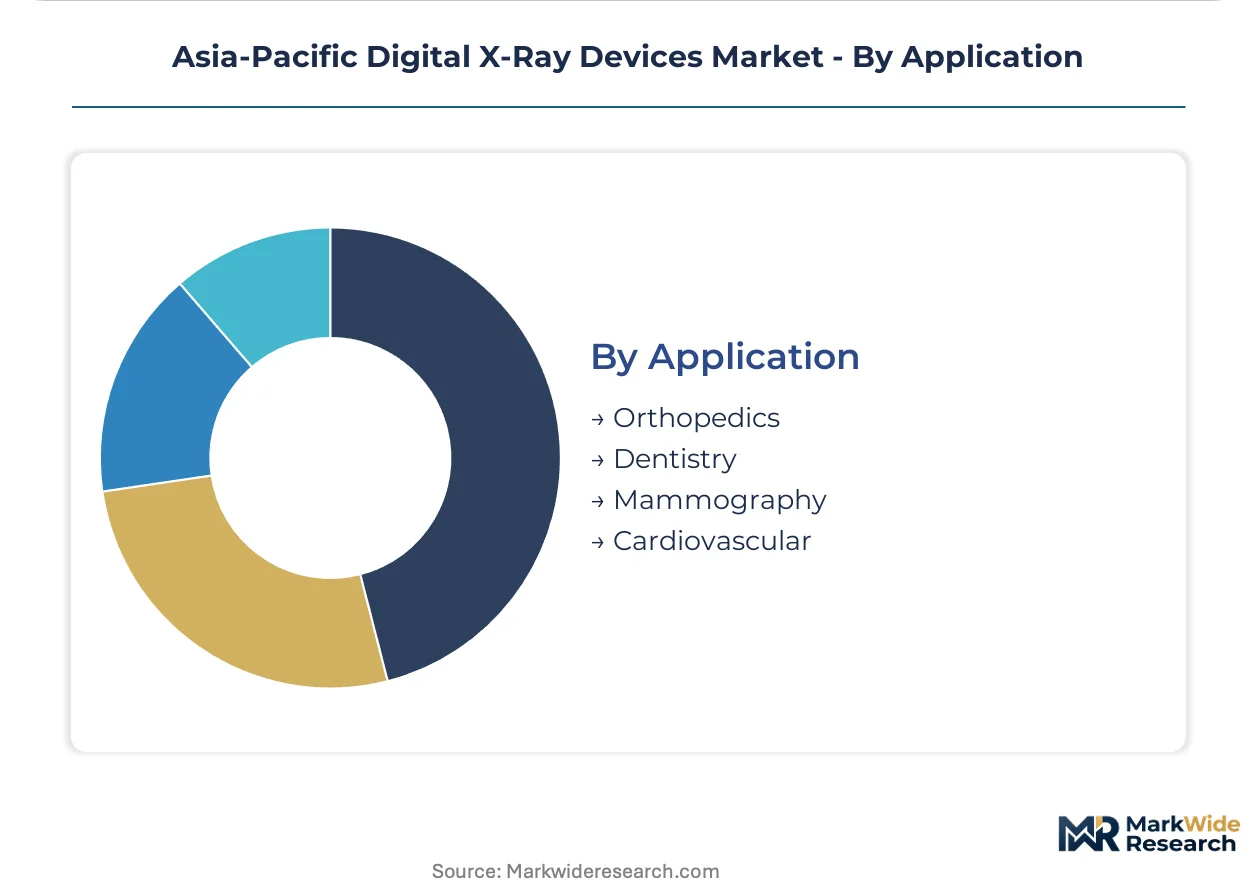
Application:
Maturity gradients separate established orthopedics and dentistry segments from emerging cardiovascular applications requiring specialized detector timing and contrast protocols.
- Orthopedics:Weight-bearing extremity imaging and full-spine acquisition drive demand for long-length detector configurations in Japan's rehabilitation-focused hospital networks. Australia's sports medicine clinics specify high-resolution modes for stress fracture detection.
- Dentistry:Cephalometric and cone-beam integration requirements shape product roadmaps for panoramic system vendors serving South Korea's orthodontic market. India's dental college expansion programs anchor tender volumes for teaching-compatible equipment.
- Mammography:Tomosynthesis-capable systems command premium positioning in China's breast cancer screening pilot programs. Australia's BreastScreen network mandates specific dose-performance benchmarks that filter eligible suppliers.
- Cardiovascular:Electrocardiogram-synchronized acquisition and high-frame-rate fluoroscopy support interventional procedures in Singapore's cardiac centers. Detector heat dissipation limits and iodinated contrast compatibility constrain product design for this application.
Orthopedics retains the deepest installed penetration. Cardiovascular represents the most technically demanding expansion frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-two and tier-three cities anchor procurement volume for digital radiography systems as healthcare infrastructure expansion accelerates across provincial hospital networks.
China
Provincial hospital construction in Sichuan and Hunan provinces drives tender volumes for fixed digital radiography installations. The NMPA tightened electromagnetic compatibility standards for wireless systems operating in dense network environments. Chengdu's medical device industrial cluster hosts domestic flat-panel detector assembly operations serving western China distribution.
India
Public health infrastructure expansion and emergency department retrofit programs concentrate demand in tier-one city hospitals. The CDSCO medical device rules adaptation toward ASEAN harmonization shapes certification strategies for imported equipment. Tamil Nadu's medical electronics manufacturing zone under the PLI scheme expands local production capacity for detector components.
Japan
University hospital R&D partnerships and stringent detector calibration requirements sustain premium equipment demand. The PMDA enforces extended validation protocols that create six-to-nine month certification timelines for imported systems. Osaka's Kansai region hosts concentrated medical imaging R&D facilities developing pediatric low-dose protocols.
Australia
Regional healthcare networks maintain computed radiography systems while metropolitan hospitals consolidate procurement around single-source contracts. The TGA aligns with IEC 60601-1-3 radiation safety benchmarks dictating dose optimization requirements. Queensland's regional health districts negotiate detector replacement schedules independently from installation vendors.
South Korea
Cancer screening centers and tuberculosis detection programs in mobile health units drive high-throughput system requirements. The MFDS regulates software as medical device classifications for AI-enhanced image interpretation tools. Seoul's Digital Healthcare Cluster anchors development of frequency-hopping protocols exceeding baseline electromagnetic compatibility requirements.
Asia-Pacific Digital X-Ray Devices Market Competitive Environment
Global majors compete with regional champions across detector technology and service contract structures, producing a tiered market where scale-driven portfolios face pressure from specialized configurations. The vendor base organizes around three strategic archetypes: diversified conglomerates with captive component supply, mid-tier specialists emphasizing pediatric or portable applications, and domestic champions leveraging regulatory familiarity. Consolidation pressure manifests through multi-year enterprise agreements and unbundled service contracts separating hardware from maintenance obligations.
Among diversified healthcare conglomerates, GE Healthcare, Siemens Healthineers, and Fujifilm Holdings Corporation exemplify contrasting geographic anchoring and technology positioning. GE Healthcare represents North American-headquartered supply chain integration, Siemens Healthineers occupies German-engineered premium-tier positioning, and Fujifilm Holdings Corporation exemplifies Japanese-origin specialization in radiation dose reduction. Each anchors distinct procurement committee relationships across hospital networks, imaging centers, and public health tenders.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Fujifilm Holdings Corporation |
| Koninklijke Philips |
| Canon Medical Systems Corporation |
| Shimadzu Corporation |
| Hologic |
| Carestream Health |
| Hitachi Ltd. |
| Others |
Value Chain & Pricing Dynamics
Cesium iodide crystal costs cascade from Japanese and South Korean chemical processing facilities through detector manufacturing tiers, compressing margins at mid-market suppliers while premium vendors absorb volatility through captive scintillator production. Hospital procurement committees across Southeast Asia exploit this concentration to extract volume discounts from non-integrated vendors.
Pricing Analysis
Input-cost pass-through from scintillator materials to finished detectors operates on 90-120 day lags, with Japanese suppliers maintaining firmer pricing than Korean competitors. Pricing stratifies across premium, standard, and economy tiers based on detector resolution grade and PMDA certification status. Cost compression in the standard tier is intensifying because Chinese domestic manufacturers are qualifying for NMPA wireless DR registrations. Public hospital networks in India and Indonesia exhibit highest price sensitivity, while Japan's university hospitals accept premium positioning for calibration-validated systems.
Supply Chain Analysis
Dual-sourcing requirements from Australia's TGA and China's NMPA compel detector manufacturers to qualify scintillator suppliers in both Japan and South Korea, despite production clustering in those markets. Flat-panel detector assembly draws from Taiwanese TFT array foundries, Japanese cesium iodide crystal growers, and Korean gadolinium oxysulfide processors. Single-source vulnerability concentrates in photodiode wafer supply from Japanese semiconductor fabricators. Distribution runs through regional medical device distributors with hospital GPO contracts in Australia, direct government tender channels in India, and provincial procurement platforms in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific digital x-ray market functions as a geographic-arbitrage play where manufacturing in Tamil Nadu's PLI zone undercuts landed costs from Japanese or German imports by 15-25 percent before duty differentials.
For Market Incumbents: Extend service contract unbundling into Australia's regional health districts before domestic competitors replicate the Queensland procurement model. Anchor detector replacement schedules through multi-year calibration service agreements that lock out third-party maintenance providers. Threat from Chinese wireless DR vendors with NMPA fast-track approval demands accelerated R&D partnerships with Japanese university hospitals to preserve premium positioning. For New Entrants and Emerging Players: Capture Indonesia's provincial hospital construction programs in Java and Sumatra where greenfield procurement packages lack incumbent vendor relationships. Pediatric low-dose imaging configurations for neonatal intensive care units represent the most penetrable application segment with premium pricing tolerance unavailable in commoditized orthopedics. Go-to-market through telemedicine-integrated cloud platforms enables remote radiologist interpretation partnerships with Thailand's rural clinic networks. For Investors and Strategic Acquirers: Consolidation pressure builds where hospital procurement committees compress supplier margins through single-source contracting and unbundled service negotiations. Long-term viability favors vendors with captive scintillator supply or proprietary detector calibration protocols that create switching costs. Acquisition target archetype: mid-tier specialists with NMPA wireless DR certification and established provincial distribution in China's tier-two cities. Signal to watch: CDSCO harmonization with ASEAN medical device rules that would unlock cross-border tender eligibility for certified manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Accelerates entry into Australia's TGA-aligned procurement systems requiring IEC 60601-1-3 compliance. |
| Hospital System Partnership | Locks in multi-year enterprise agreements with South Korea's cancer screening centers and mobile health units. |
| Software Companion Development | Enables AI-enhanced tuberculosis detection algorithms for MFDS-regulated mobile screening deployments. |
| Reimbursement Strategy | Aligns product positioning with India's Ayushman Bharat coverage expansion for district hospital digitalization. |
| Backward Integration into Scintillators | Secures margin control against cesium iodide supply concentration in Japanese chemical processing facilities. |
Study Parameters
Coverage spans China, India, Japan, Australia, and South Korea, with primary inputs from each market's hospital procurement committees, biomedical engineering directors, and medical device regulatory consultants. Secondary validation drew from NMPA registration databases, CDSCO medical device rules filings, TGA therapeutic goods registers, and MFDS software-as-medical-device classifications. Bottom-up triangulation across installed base estimates and top-down cross-check against public hospital capital expenditure budgets anchored volume projections.
Rate-of-change decomposition separated replacement demand from expansion demand across the projection horizon, with segmentation modeling across product configuration, detector technology, end-user type, and clinical application dimensions. CAGRs were derived from logistic diffusion curves fitted to analog-to-digital conversion rates in India's tier-one cities and China's provincial hospital networks. Industry-specific forecast inputs incorporated PLI scheme capacity expansion timelines and NMPA electromagnetic compatibility testing backlog estimates.
Regulatory approval delays, scintillator supply disruptions, and hospital budget freeze triggers are the dominant revision risks to the installed base and revenue projections. Deviation in CDSCO-ASEAN harmonization timing would shift the outlook materially for import-dependent market segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Super Resolution Microscopes Market
Medical Imaging
Global Magnetic Resonance Imaging System Market
Medical Imaging
Whole-Body Imaging Market
Medical Imaging
Automated Contouring Radiotherapy Software Market
Medical Imaging
Netherlands Diagnostic Imaging Equipment Market
Medical Imaging
North America Digital Pathology Market
Medical Imaging
North America Nuclear Imaging Market
Medical Imaging
South Africa Computed Tomography Market
Medical Imaging
Portable MRI Market
Medical Imaging
Cephalometric X-Ray System Market
Medical Imaging
Imaging Agents Market
Medical Imaging
Global Confocal Microscope Market
Medical Imaging
Smart X-Ray Detectors Market
Medical Imaging
PSMA-PET Imaging Market
Medical Imaging
Global Colposcopy Market
Medical Imaging
Breast Imaging Equipment Market